
 Asia-Pacific Tumor Ablation Market | 2026-2036
Asia-Pacific Tumor Ablation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Tumor Ablation Market Insights
Aftermarket service revenue is fragmenting across the Asia-Pacific Tumor Ablation Market as device manufacturers compete for recurring revenue from probe replacements and maintenance contracts. Medtronic PLC leverages its extensive service network across Japan and Australia to sustain long-term customer relationships. Boston Scientific Corporation anchors its regional position through specialized training programs for interventional radiologists in tertiary hospitals.
Asia-Pacific tumor ablation encompasses percutaneous and intraoperative techniques that apply thermal or electrical energy to destroy malignant tissue, typically operating at radiofrequencies between 460 and 480 kHz or cryogenic temperatures below minus 40 degrees Celsius to achieve irreversible cellular damage while preserving surrounding structures. Radiofrequency ablation occupies the largest installed base across hepatic tumor applications, while microwave ablation systems demonstrate the fastest expansion in lung tumor protocols due to reduced procedural time and larger ablation zones. Image-guided techniques dominate technology selection as hospitals integrate real-time CT and ultrasound navigation to improve targeting precision and reduce complication rates.
Japan's PMDA and Australia's TGA enforce stringent biocompatibility and electromagnetic safety standards that shape product registration timelines and clinical evidence requirements for ablation device manufacturers. China's NMPA accelerates review pathways for innovative thermal therapy systems through its priority review channels, though domestic firms like Chongqing Haifu Technology face additional scrutiny for export-bound devices. Stakeholders must monitor evolving reimbursement classifications for outpatient ablation procedures across South Korea's HIRA and India's CDSCO jurisdictions.
Market Dynamics
Japan's PMDA priority review pathway and China's NMPA accelerated approval channels are compressing device registration timelines, forcing manufacturers to front-load clinical evidence generation and localize manufacturing partnerships ahead of commercial launch.
Growth Catalysts
- Hepatocellular carcinoma prevalence:China's tier-one cities report sustained incidence rates that drive radiofrequency ablation system procurement in tertiary hospitals.
- India's PLI scheme for medical devices:Domestic manufacturing incentives reduce import dependency for ablation generators and disposable probes.
- Microwave ablation protocols:Reduced procedural time and larger thermal zones accelerate adoption across lung tumor interventions in South Korean university hospitals.
Market Restraints
- Biocompatibility testing costs:Australia's TGA and Japan's PMDA require extended cytotoxicity and electromagnetic compatibility studies that extend pre-market expenditure cycles.
- Probe supply concentration:Single-source dependencies for specialized RF electrodes create vulnerability in procurement planning across Southeast Asian private hospital chains.
- Cryoablation system footprint:Bulk and infrastructure requirements limit deployment to major metropolitan medical centers, excluding secondary-tier facilities.
Strategic Opportunities
- Vietnam and Indonesia expansion:Underpenetrated interventional oncology infrastructure creates first-mover positioning for ablation system distributors.
- AI-guided navigation convergence:Real-time CT-ultrasound fusion software integration with thermal mapping enables procedural standardization.
- Outpatient reimbursement expansion:South Korea's HIRA recategorization of same-day ablation procedures shifts volume from inpatient settings.
Industry Challenges
- Interventional radiologist training pipelines:Specialized fellowship programs in image-guided thermal therapy remain concentrated in Japan and Australia, constraining procedural capacity elsewhere.
- Legacy imaging system integration:PACS connectivity and DICOM compliance requirements complicate retrofitting ablation workstations into existing hospital IT architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Tumor Ablation Market |
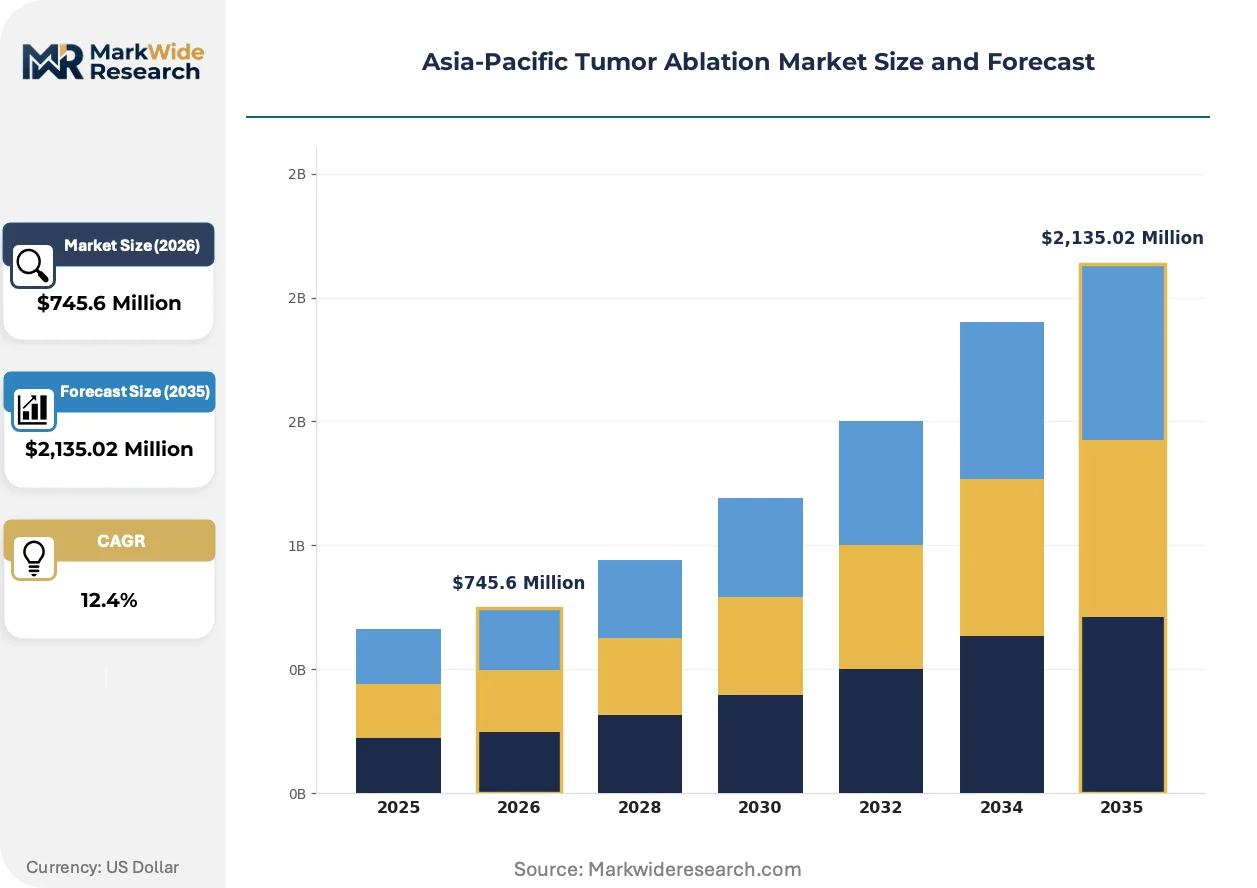
| Market Size in 2026 | $745.6 Million |
| Market Size in 2035 | $2,135.02 Million |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiofrequency Ablation, Microwave Ablation, Cryoablation, Laser Ablation End User: Hospitals, Ambulatory Surgical Centers, Cancer Treatment Centers, Diagnostic Laboratories Application: Hepatic Tumors, Lung Tumors, Kidney Tumors, Bone Tumors Technology: Image-Guided Techniques, Surgical Navigation, Electrosurgery, Thermal Therapy |
| Companies Covered | Medtronic PLC, Boston Scientific Corporation, Johnson & Johnson, AngioDynamics Inc, EDAP TMS, Mermaid Medical, Chongqing Haifu Technology, HealthTronics, Terumo Medical Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Tumor Ablation Market Trends and Innovations
Digital workflow integration and real-time procedural analytics are compressing the gap between diagnosis and intervention, reshaping how hospitals evaluate ablation platform investments beyond hardware specifications.
Electromagnetic navigation systems with integrated impedance monitoring are virtualizing the traditional reliance on repeated CT confirmation scans during hepatic ablation procedures. Tertiary hospitals in Shanghai and Tokyo deploy these platforms to reduce radiation exposure and shorten anesthesia duration. The technology is virtualizing conventional stepwise imaging protocols into continuous feedback loops that enable single-session multi-lesion treatment.
Japan's PMDA introduced a conditional early approval framework for breakthrough thermal therapy devices that permits limited commercialization during confirmatory trials. Manufacturers now structure clinical programs to satisfy both Japanese and Australian TGA evidentiary requirements through coordinated study designs. Microwave ablation systems with adaptive power algorithms receive expedited review under this pathway, compressing time-to-revenue for next-generation platforms.
Hospital procurement committees increasingly unbundle capital equipment purchases from multi-year service and probe supply agreements. Australian private health networks and Indian corporate hospital chains negotiate probe pricing separately from generator acquisitions, treating consumables as distinct spend categories. This pattern concentrates in markets where third-party probe compatibility expands sourcing alternatives beyond original equipment manufacturers.
Asia-Pacific Tumor Ablation Market Segmentation
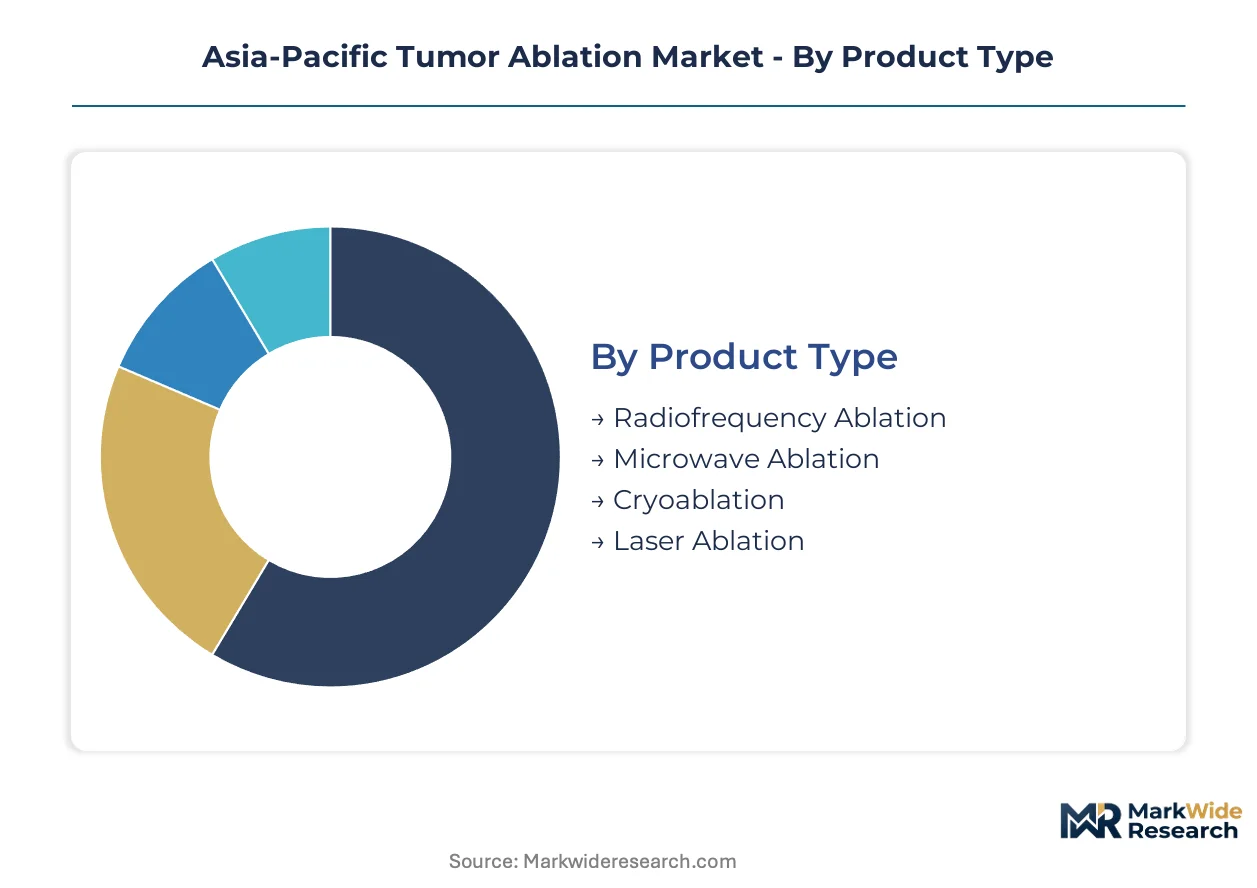
Ablation system procurement patterns diverge sharply across clinical settings and tumor indications. Procurement committees weigh capital intensity against consumable throughput when segmenting vendor evaluations. Technology selection tracks directly to reimbursement classifications and interventional radiologist training availability.
Product Type:
Radiofrequency systems turn over slowest with decade-long generator lifecycles, while microwave platforms refresh fastest as power algorithm upgrades accelerate obsolescence. Cryoablation occupies the middle with compressor maintenance driving mid-cycle replacements.
- Radiofrequency Ablation:Systems operate at 460-480 kHz through impedance-controlled electrodes. China's tertiary hospitals in Beijing and Shanghai concentrate procurement for hepatocellular carcinoma protocols, constrained by interventional radiologist training bottlenecks in secondary cities.
- Microwave Ablation:Electromagnetic energy at 915 MHz or 2.45 GHz generates larger thermal zones with shorter procedural times. South Korean university hospitals drive adoption for lung tumor interventions where reduced anesthesia duration shifts case volume from surgical resection.
- Cryoablation:Argon-helium systems achieve sub-minus-40°C temperatures for renal and prostate applications. Japan's PMDA streamlines approval for next-generation platforms with integrated temperature monitoring.
- Laser Ablation:Nd:YAG and diode systems target small-volume brain and spinal lesions. Australian private networks deploy these for outpatient neuro-oncology procedures.
Radiofrequency Ablation dominates installed base. Microwave Ablation is where expansion concentrates.
End User:
Cost tiering separates high-volume tertiary hospitals from price-sensitive ambulatory settings. Cancer treatment centers occupy the premium tier with bundled service contracts.
- Hospitals:Tertiary institutions in China and India anchor capital equipment procurement with dedicated interventional oncology departments. India's PLI scheme for medical devices reduces import dependency for generator sourcing.
- Ambulatory Surgical Centers:Same-day discharge protocols in South Korea and Australia concentrate demand for compact microwave systems. HIRA reimbursement recategorization accelerates volume shift from inpatient settings.
- Cancer Treatment Centers:Specialized facilities in Japan and Singapore deploy multimodal thermal therapy platforms. PMDA conditional early approval frameworks compress technology refresh cycles.
- Diagnostic Laboratories:Limited ablation service lines in India and Indonesia focus on biopsy-integrated thermal sampling. CDSCO registration requirements constrain multi-site expansion.
Hospitals capture the highest equipment revenue per site. Ambulatory Surgical Centers are climbing the fastest in unit volume.
Application:
Geographic incidence patterns concentrate demand by tumor type. Hepatic applications align with hepatitis B prevalence corridors; lung applications track smoking rate demographics.
- Hepatic Tumors:Hepatocellular carcinoma protocols consume the largest probe volumes. China's tier-one cities sustain radiofrequency system density with incidence rates driving repeat intervention demand.
- Lung Tumors:Microwave systems displace surgical resection in South Korean and Japanese centers. Reduced procedural time enables high-volume screening program integration.
- Kidney Tumors:Cryoablation preserves renal function in solitary kidney patients. Australian TGA biocompatibility requirements shape probe material selection.
- Bone Tumors:Palliative ablation for metastatic disease concentrates in Japan's cancer centers. METI reimbursement frameworks cover outpatient palliative protocols.
Hepatic Tumors command the deepest installed base. Lung Tumors show the steepest expansion trajectory.
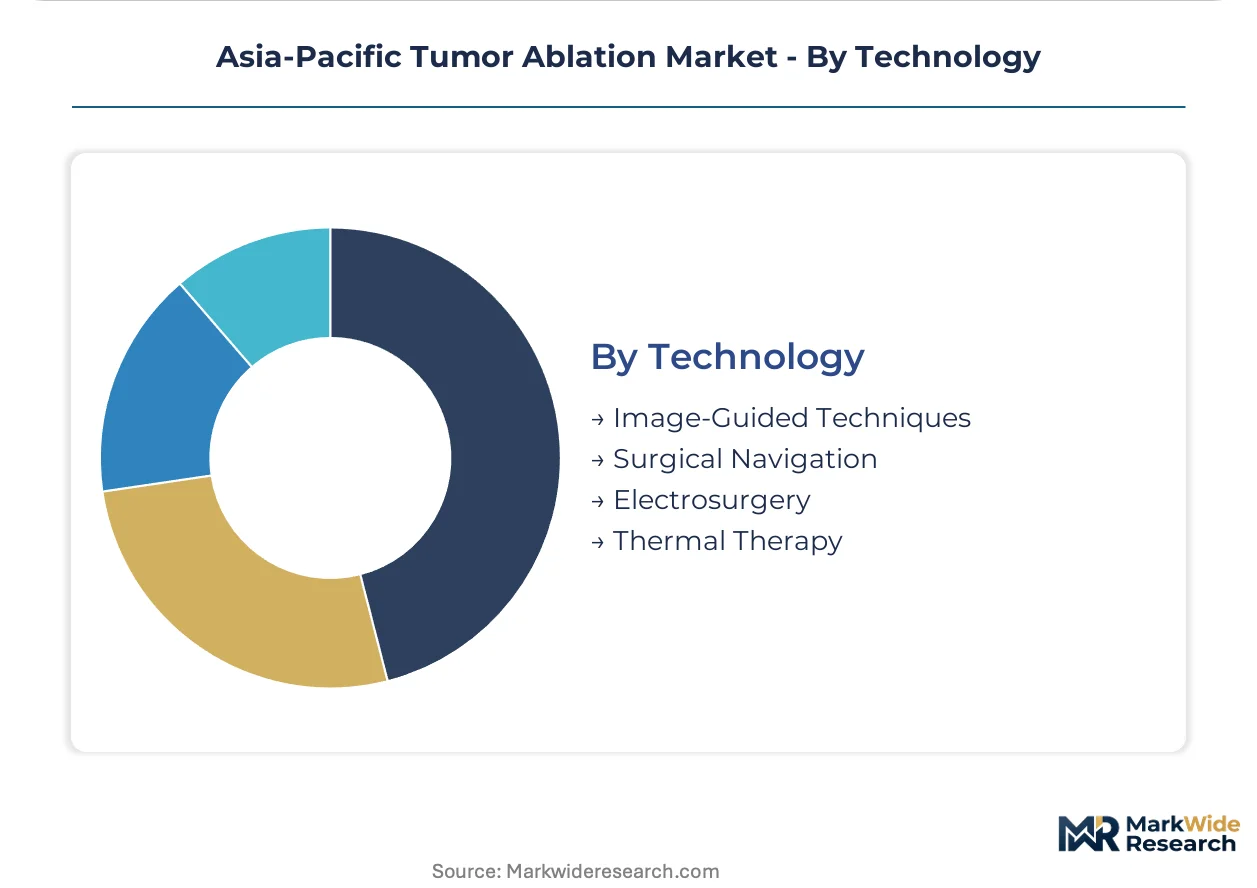
Technology:
Customer sophistication tiers separate image-guided adoption leaders from basic electrosurgery users. Navigation integration marks the premium boundary.
- Image-Guided Techniques:Real-time CT-ultrasound fusion dominates Shanghai and Tokyo tertiary deployments. Electromagnetic navigation with impedance monitoring virtualizes repeated confirmation scans.
- Surgical Navigation:Integrated tracking systems enable single-session multi-lesion treatment. PMDA breakthrough device pathways accelerate platform registration.
- Electrosurgery:Basic radiofrequency generators serve cost-constrained Indian and Indonesian facilities. CDSCO and national pharmaceutical regulator scrutiny limits import channel diversity.
- Thermal Therapy:Adaptive power algorithms and thermal mapping software differentiate next-generation platforms. NMPA priority review channels compress domestic manufacturer time-to-market.
Image-Guided Techniques anchor current procurement standards. Surgical Navigation is gaining share fastest as precision requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in Southeast Asian private hospital chains contrasts sharply with premium procurement tolerance in Japanese cancer centers, creating a bifurcated demand elasticity landscape across the Asia-Pacific region.
China
Hepatocellular carcinoma incidence in Beijing and Shanghai sustains radiofrequency ablation system density, with tertiary hospitals expanding interventional oncology departments. NMPA priority review channels compress registration timelines for domestic manufacturers like Chongqing Haifu Technology. Yangtze River Delta medical clusters concentrate microwave ablation adoption for lung tumor protocols.
Japan
Kanto region cancer centers deploy multimodal thermal therapy platforms with integrated navigation systems. PMDA conditional early approval frameworks permit limited commercialization during confirmatory trials, accelerating next-generation platform registration. Tokyo metropolitan hospitals lead electromagnetic navigation adoption to reduce radiation exposure during hepatic procedures.
India
Corporate hospital chains in Delhi-NCR and Maharashtra negotiate probe pricing separately from generator acquisitions, treating consumables as distinct spend categories. PLI scheme incentives for medical devices reduce import dependency for ablation generators. Tier-one city tertiary institutions anchor capital equipment procurement while secondary cities face interventional radiologist training bottlenecks.
South Korea
University hospitals in Seoul drive microwave ablation adoption for lung tumor interventions where reduced procedural time shifts case volume from surgical resection. HIRA reimbursement recategorization of same-day ablation procedures accelerates volume migration from inpatient to ambulatory settings. Busan-Ulsan medical clusters concentrate outpatient palliative ablation for metastatic bone disease.
Australia
Private health networks in New South Wales and Victoria unbundle capital equipment purchases from multi-year service agreements, treating probe supply as separately negotiable. TGA biocompatibility and electromagnetic safety standards shape probe material selection and extend pre-market expenditure cycles. Sydney and Melbourne tertiary centers deploy cryoablation systems for renal applications with integrated temperature monitoring.
Asia-Pacific Tumor Ablation Market Competitive Landscape
Capability concentration sits with diversified medical technology conglomerates; scale advantage sits with specialized interventional oncology device manufacturers. The competitive structure stratifies across three tiers: multinational platform vendors with integrated service networks, regional specialists with localized regulatory expertise, and domestic challengers leveraging manufacturing incentives. Dominant competitive moves include strategic partnerships with tertiary hospital networks and portfolio diversification into navigation software and consumable probe lines.
Within the multinational platform tier, Medtronic PLC and Boston Scientific Corporation exemplify divergent regional anchoring strategies. Medtronic leverages extensive service infrastructure across Japan and Australia to sustain recurring revenue from probe replacements and maintenance contracts. Boston Scientific anchors positioning through specialized training programs for interventional radiologists in tertiary hospitals across China and India. Johnson & Johnson occupies a position spanning surgical and interventional oncology portfolios. Among Asia-Pacific-based specialists, Chongqing Haifu Technology represents domestic manufacturing capability aligned with NMPA regulatory pathways, while Terumo Medical Corporation exemplifies Japanese precision device fabrication with PMDA compliance integration.
| Leading Market Players |
|---|
| Medtronic PLC |
| Boston Scientific Corporation |
| Johnson & Johnson |
| AngioDynamics Inc |
| EDAP TMS |
| Mermaid Medical |
| Chongqing Haifu Technology |
| HealthTronics |
| Terumo Medical Corporation |
| Others |
Pricing and Supply Chain Analysis
Generator undercapacity in China's Yangtze River Delta medical manufacturing clusters compresses supplier margins while amplifying pricing power for probe and electrode producers serving Japan and Australia's premium hospital networks. This utilization asymmetry forces tier-two Chinese manufacturers toward aggressive consumables bundling, whereas Japanese precision fabricators extract premiums through extended service contracts and NMPA-compliant export certification.
Pricing Analysis
Probe replacement and maintenance contract revenue drives lifetime value capture across Asia-Pacific installed bases. Three-tier pricing structure across premium, standard, and economy levels separates PMDA-validated Japanese systems from NMPA-accelerated domestic Chinese platforms and CDSCO-registered Indian imports. Pricing pressure stems from hospital procurement committees unbundling capital equipment from consumables agreements. Ambulatory surgical centers in South Korea exhibit highest price sensitivity; Japanese cancer centers demonstrate lowest.
Supply Chain Analysis
Extended payment terms from Australian private health networks and supply-chain finance facilities from Singapore distributors shape working capital dynamics for probe manufacturers. Component sourcing concentrates in Japan, China, and South Korea for RF electrodes, microwave antennas, and cryogenic gas systems. Raw material dependencies include medical-grade stainless steel, specialized ceramics, and argon-helium gas mixtures. Single-source vulnerability persists for impedance-monitoring sensors. Distribution runs through regional medical device distributors with NMPA, PMDA, and TGA compliance certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
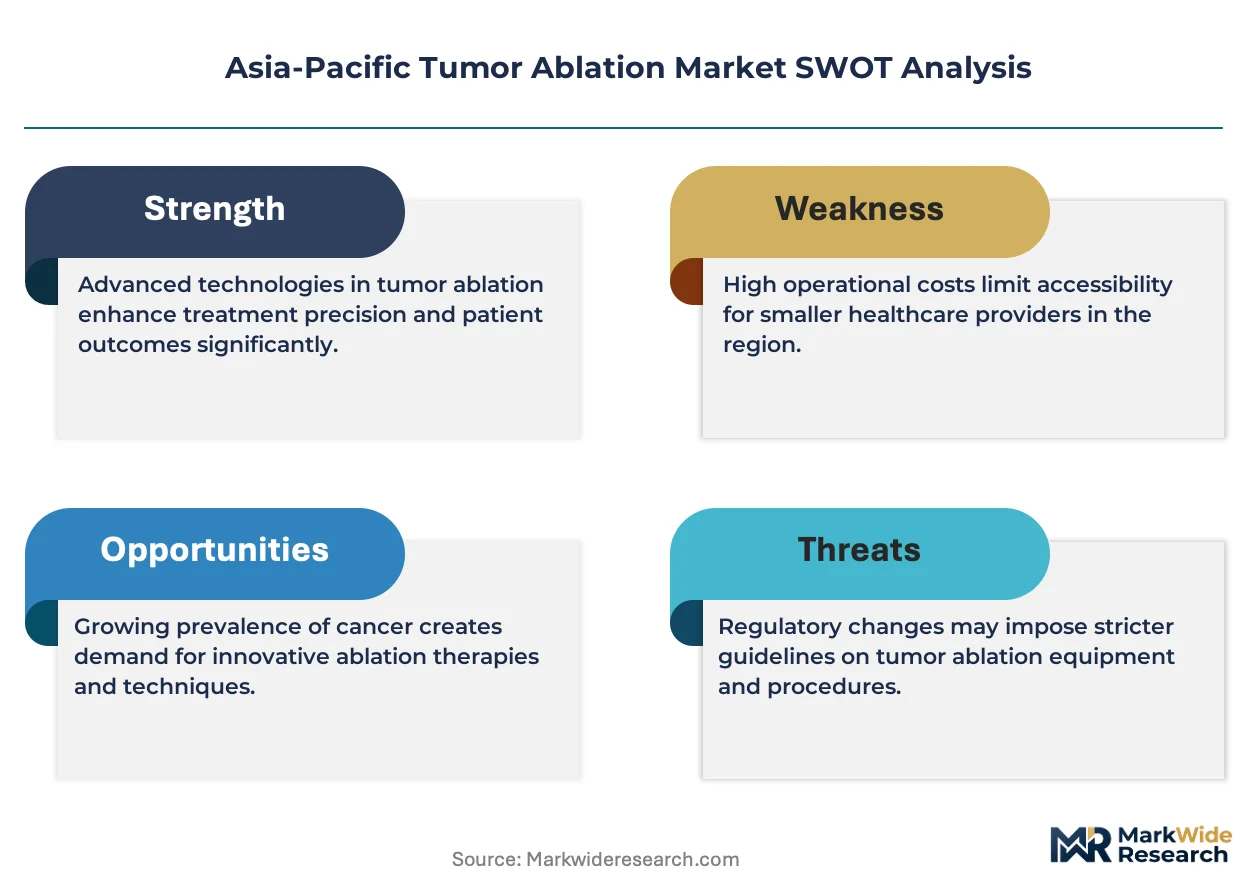
Fragmentation opportunity concentrates in microwave ablation platform supply where HIRA reimbursement recategorization and NMPA priority review channels create parallel demand niches for navigation-integrated and bare-generator configurations.
For Market Incumbents: Entrench service infrastructure depth across Japan and Australia to capture recurring probe revenue from installed RF generator bases. Consolidate training program partnerships with tertiary hospitals in China and India before domestic manufacturers achieve interventional radiologist certification scale. Vertical integration into thermal mapping software offsets hardware margin compression from unbundled procurement trends. For New Entrants and Emerging Players: Establish a beachhead in Vietnam and Indonesia interventional oncology infrastructure where tertiary hospital expansion outpaces trained specialist supply. Target microwave ablation for lung tumor protocols in South Korean university hospitals where reduced procedural time commands premium positioning. Pursue distributor partnerships with established imaging equipment vendors to leverage installed CT-ultrasound fusion navigation bases. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AI-guided navigation software sub-segments where algorithm development displaces hardware fabrication. Long-term viability favors platform vendors with integrated consumables ecosystems over pure-play generator manufacturers. Acquisition target archetype: regional specialists with localized PMDA or NMPA regulatory expertise and established tertiary hospital training relationships. Signal to watch: HIRA and NMPA reimbursement recategorization velocity for outpatient ablation procedures.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Boston Scientific's radiologist training programs in Delhi-NCR tertiary hospitals lock in multi-year probe commitments. |
| Software Companion Development | Real-time CT-ultrasound fusion integration with thermal mapping enables PMDA breakthrough device pathway qualification. |
| Reimbursement Strategy | HIRA same-day procedure recategorization shifts volume toward ambulatory-compatible microwave platforms in Seoul. |
| CE Marking Pathway | TGA biocompatibility alignment with EU MDR streamlines Australian private network procurement for cryoablation systems. |
| Manufacturing Scale-Up | India's PLI scheme incentives reduce import dependency for ablation generators in Maharashtra corporate hospital chains. |
Research Methodology
Operator-level perspectives from interventional radiologists, hospital procurement committee chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against NMPA registration databases, PMDA approval filings, HIRA reimbursement classifications, and hospital procurement records. Top-down macroeconomic triangulation against bottom-up equipment installation tracking ensured segment-level consistency.
Scenario-bracketing framed demand projections across the analysis window, with sensitivity testing for regulatory approval velocity and reimbursement recategorization timing. Segmentation dimensions modeled include ablation modality, tumor indication, end-user facility tier, navigation technology integration, and regional regulatory cluster. CAGRs derived from equipment replacement cycles, probe throughput assumptions, and procedure volume elasticities to reimbursement policy shifts.
Stress conditions across PMDA review timeline compression, NMPA domestic preference enforcement, and HIRA outpatient coverage expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding interventional radiologist training pipeline expansion and imaging system integration complexity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Tumor Infiltrating Lymphocytes Market
Oncology
North America Veterinary Oncology Market
Oncology
Ovarian Cancer Market
Oncology
Single-Room Proton Therapy Systems Market
Oncology
Global Metastatic Cancer Treatment Market
Oncology
Global Metastatic Melanoma Drugs Market
Oncology
Radiation Therapy Software Market
Oncology
BRCA Mutation-Positive Ovarian Cancer Market
Oncology
Outpatient Oncology Infusion Market
Oncology
North America Kidney Cancer Therapeutics and Diagnostics Market
Oncology
Tumor Ablation Market
Oncology
Tumor Embolization Market
Oncology
Breast Cancer Brachytherapy Market
Oncology
Metastatic Melanoma Market
Oncology
North America Bone Metastasis Market
Oncology
Triple-Negative Breast Cancer Market