
 Middle East and Africa Ovarian Cancer Diagnostics and Therapeutics Market | 2026-2036
Middle East and Africa Ovarian Cancer Diagnostics and Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Ovarian Cancer Diagnostics and Therapeutics Market Foresight
A shortage of board-certified gynecologic oncologists is redrawing competitive dynamics across the Middle East and Africa. F. Hoffmann-La Roche Ltd anchors its position through sustained investment in companion diagnostic platforms tied to targeted therapies. Bristol Myers Squibb Company differentiates via immuno-oncology portfolios that compete directly with chemotherapy standards in markets where reimbursement for novel biologics remains uneven. AstraZeneca plc leverages partnerships with regional distributors to extend access where cold-chain infrastructure limits biologic delivery.
Middle East and Africa Ovarian Cancer Diagnostics and Therapeutics encompasses detection modalities and treatment interventions for malignant neoplasms of the ovaries, including CA-125 biomarker quantification, transvaginal ultrasound imaging, PARP inhibitor pharmacotherapy, and platinum-based chemotherapy regimens administered across intravenous and intraperitoneal delivery modes. The primary purpose is early-stage detection to improve five-year survival rates and progression-free intervals in patient populations where hereditary BRCA mutation prevalence drives screening urgency. Biomarker segments currently dominate value capture given their role in monitoring treatment response and recurrence, while next-generation sequencing technology represents the fastest-expanding diagnostic category as laboratories in the United Arab Emirates and Israel adopt comprehensive genomic profiling panels. Therapeutics segments split between cytotoxic agents with established reimbursement and targeted biologics where access depends on private insurance or government exceptional-use programs.
South Africa's SAHPRA, Saudi Arabia's SFDA, and Israel's Ministry of Health each enforce distinct clinical trial requirements and import licensing frameworks that shape product registration timelines and market entry sequencing for multinational manufacturers. EMA-aligned standards in Israel contrast with Gulf state regulatory harmonization efforts through the GCC Central Drug Registration system, creating compliance complexity for companies pursuing multi-country launches. Stakeholders must monitor how national cancer control strategies in Egypt, Nigeria, and Kenya prioritize ovarian cancer within broader non-communicable disease agendas, as these policy signals determine public procurement budgets and screening program expansion.
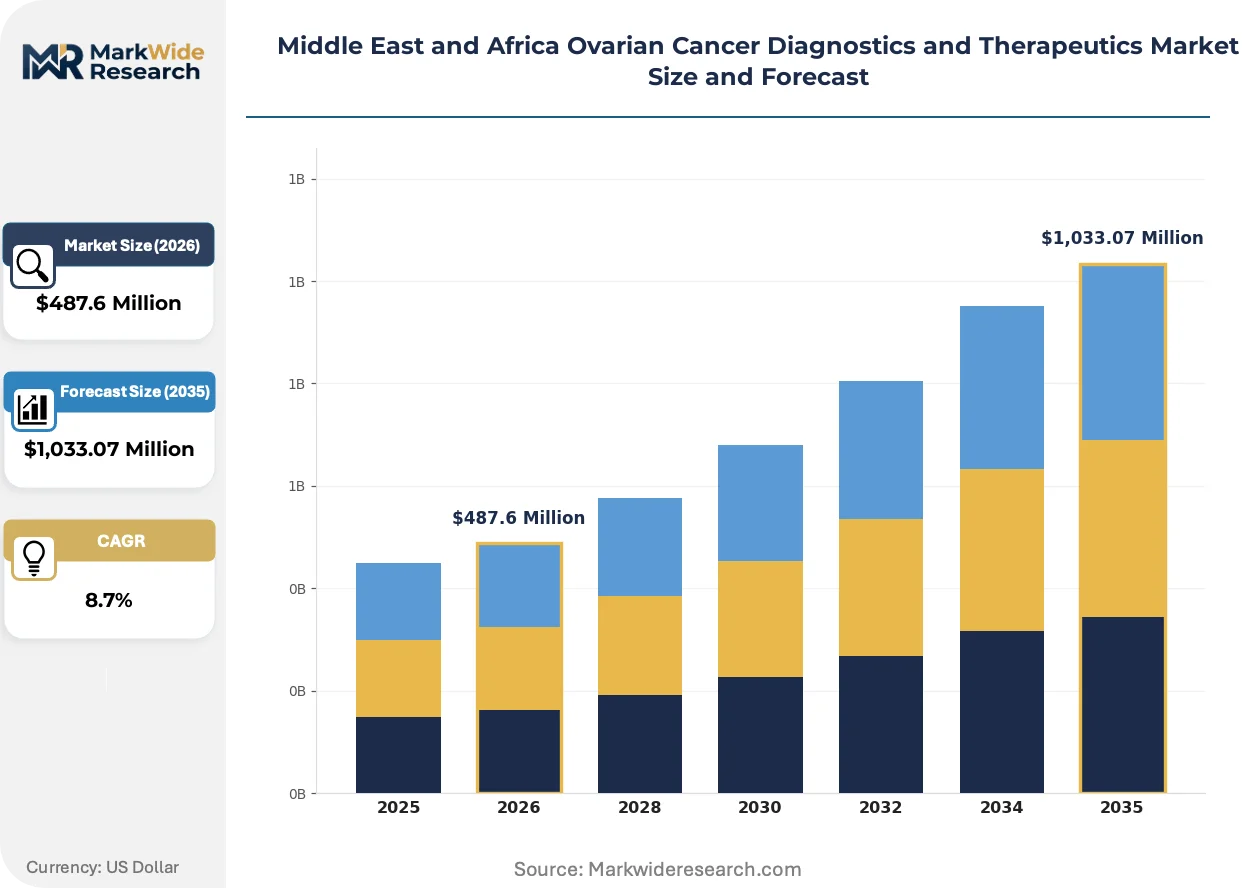
Market Dynamics
Companion diagnostic platforms are reconfiguring competitive boundaries across the Middle East and Africa ovarian cancer market, as biomarker-driven patient stratification becomes the prerequisite for accessing targeted PARP inhibitor therapies in tertiary oncology centers.
Growth Catalysts
- Saudi SFDA Streamlined Pathways:The Saudi Food and Drug Authority has compressed biomarker assay registration timelines, accelerating commercial deployment of BRCA mutation testing kits across Gulf state oncology networks.
- Private Hospital Procurement:South Africa's private hospital groups are expanding molecular pathology capabilities, creating dedicated revenue streams for genomic profiling services within Netcare and Life Healthcare facilities.
- NGS Platform Adoption:Next-generation sequencing technology is penetrating diagnostic laboratories in the United Arab Emirates and Israel, enabling comprehensive tumor profiling that matches patients to targeted therapeutic protocols.
Market Restraints
- Cold-Chain Infrastructure Deficits:Biologic therapeutics requiring continuous cold storage face distribution failures across Nigeria, Kenya, and Egypt where last-mile temperature monitoring remains inconsistent.
- Reimbursement Fragmentation:Gulf state government exceptional-use programs and South African medical aid schemes apply divergent prior-authorization criteria, creating unpredictable access barriers for novel immuno-oncology agents.
- Gynecologic Oncologist Scarcity:The region's shortage of board-certified specialists limits surgical staging quality and clinical trial enrollment capacity in Egypt, Morocco, and sub-Saharan African markets.
Strategic Opportunities
- Kenya National Cancer Control Strategy:Policy prioritization of ovarian cancer within Kenya's non-communicable disease agenda signals forthcoming public procurement budget allocations for screening program infrastructure.
- Telepathology Networks:Digital pathology platforms connecting regional laboratories to Israeli and South African specialist hubs are emerging as distribution innovations that bypass physical infrastructure constraints.
- Platinum Sensitivity Testing:Functional assay integration with chemotherapy selection protocols represents an underpenetrated application segment where pharmacogenomic guidance could displace empirical regimen selection.
Industry Challenges
- Multi-Jurisdictional Registration Complexity:EMA-aligned Israeli Ministry of Health standards contrast with GCC Central Drug Registration harmonization efforts, forcing manufacturers to maintain parallel compliance documentation for multi-country launches.
- Sample Logistics Integration:Tumor tissue acquisition, processing, and transport for central laboratory testing requires coordination with surgical schedules that vary across public and private hospital workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Ovarian Cancer Diagnostics and Therapeutics Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioassays, Imaging Systems, Biomarkers, Therapeutics Delivery Mode: Intravenous, Oral, Intraperitoneal, Topical End User: Hospitals, Diagnostic Centers, Research Institutes, Homecare Settings Technology: Molecular Diagnostics, Immunoassays, Next-Generation Sequencing, PCR |
| Companies Covered | AstraZeneca plc, Bristol Myers Squibb Company, F. Hoffmann-La Roche Ltd, Johnson & Johnson, Siemens Healthineers AG, GlaxoSmithKline plc, Eli Lilly and Company, Pfizer Inc., Abbott, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Ovarian Cancer Diagnostics and Therapeutics Market Shifts & Advancements
Liquid biopsy technology is penetrating diagnostic workflows ahead of tissue-based sequencing, compressing turnaround times for treatment-naive patient stratification and enabling serial monitoring without repeat surgical intervention.
Cell-free DNA analysis is supplanting archival tissue testing in initial molecular characterization, particularly where primary debulking surgery occurs at facilities lacking on-site pathology infrastructure. Oncology departments in Saudi Arabia and the UAE are adopting plasma-based BRCA testing within six-month validation windows. This shift is compressing the interval between diagnosis and targeted therapy initiation while reducing dependency on surgical specimen quality.
South Africa's SAHPRA has implemented risk-based classification for in-vitro diagnostic devices, differentiating registration pathways by clinical impact tier and compressing timelines for companion diagnostic co-submissions. This regulatory architecture is accelerating parallel approvals for targeted therapies and their required biomarker tests. Multinational manufacturers are prioritizing South Africa as a launch sequencing anchor for subsequent GCC market entry.
Academic medical centers are consolidating molecular testing procurement through centralized laboratory partnerships, displacing hospital-based pathology departments that previously maintained fragmented vendor relationships. This concentration is most visible in Israel's tertiary hospital network and South Africa's private oncology chains, where volume commitments secure preferential pricing and priority technical support from platform providers.
Middle East and Africa Ovarian Cancer Diagnostics and Therapeutics Market Segmentation
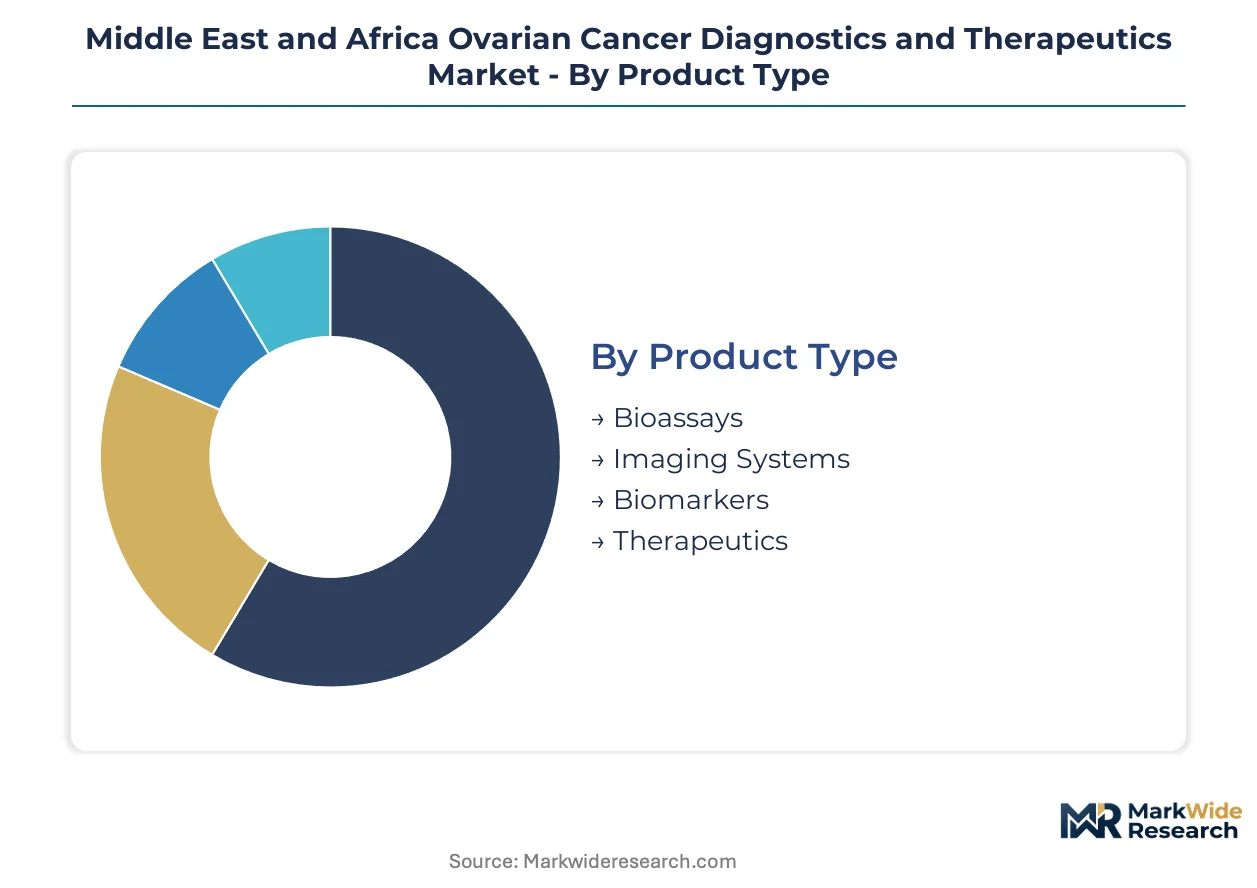
Segmentation in the Middle East and Africa ovarian cancer market reveals how diagnostic and therapeutic value flows through distinct procurement channels. Hospital procurement committees, private laboratory networks, and government screening programs each favor different product configurations and technology platforms.
Product Type:
Bioassays and imaging systems move primarily through hospital tenders and diagnostic center supply contracts, while biomarkers and therapeutics follow separate reimbursement pathways tied to oncology department formularies.
- Biomarkers:CA-125 quantification assays and HE4 testing kits dominate laboratory procurement budgets across Saudi Arabia's SFDA-regulated networks and South Africa's private hospital chains. Demand concentrates in tertiary oncology centers where treatment monitoring protocols require serial biomarker tracking.
- Therapeutics:PARP inhibitors and platinum-based chemotherapy agents command premium pricing through Gulf state exceptional-use programs and South African medical aid schemes. Distribution depends on cold-chain integrity that fragments between private hospital networks and public sector procurement.
- Bioassays:Functional assays for platinum sensitivity testing remain underdeployed across Egypt and Morocco where pathology infrastructure limits adoption.
- Imaging Systems:Transvaginal ultrasound platforms and CT/MRI staging equipment flow through radiology department capital expenditure cycles in Israel and UAE tertiary centers.
By volume, therapeutics leads. By growth pace, biomarkers are expanding most quickly.
Delivery Mode:
Route of administration determines site-of-care economics and nursing resource allocation across the region's divergent healthcare infrastructure.
- Intravenous:Platinum-based regimens and bevacizumab infusions anchor chemotherapy day units in South Africa's Netcare facilities and Saudi Arabia's National Guard hospitals. Administration requires dedicated oncology nursing staff that concentrates in urban tertiary centers.
- Oral:PARP inhibitor tablets enable outpatient maintenance therapy, reducing dependency on infusion chair capacity in markets where gynecologic oncologist scarcity limits surgical throughput.
- Intraperitoneal:Hyperthermic intraperitoneal chemotherapy delivery remains restricted to Israeli and South African academic medical centers with specialized surgical oncology programs.
- Topical:Palliative topical agents address symptom management in homecare settings across Kenya and Nigeria where hospice infrastructure is nascent.
Intravenous administration captures the largest patient volume. Oral delivery is climbing the fastest as maintenance protocols expand.
End User:
Customer type segmentation maps directly to procurement authority and budget source, from government health ministries to private insurance reimbursement.
- Hospitals:Tertiary oncology departments in Israel's Sheba Medical Center and Saudi Arabia's King Faisal Specialist Hospital drive adoption of comprehensive genomic profiling. Capital budgets here support integrated diagnostic-therapeutic platforms.
- Diagnostic Centers:Independent laboratories in South Africa's Lancet and Ampath networks compete on BRCA testing turnaround times for private medical aid patients.
- Research Institutes:Academic medical centers in the UAE and Israel conduct biomarker discovery studies that feed into companion diagnostic development pipelines.
- Homecare Settings:Oral therapy administration and patient-monitoring devices extend into home settings where Gulf state nursing services and South African community health programs diverge in coverage.
Hospitals dominate absolute spending. Diagnostic centers are gaining share fastest as decentralized testing reduces referral bottlenecks.
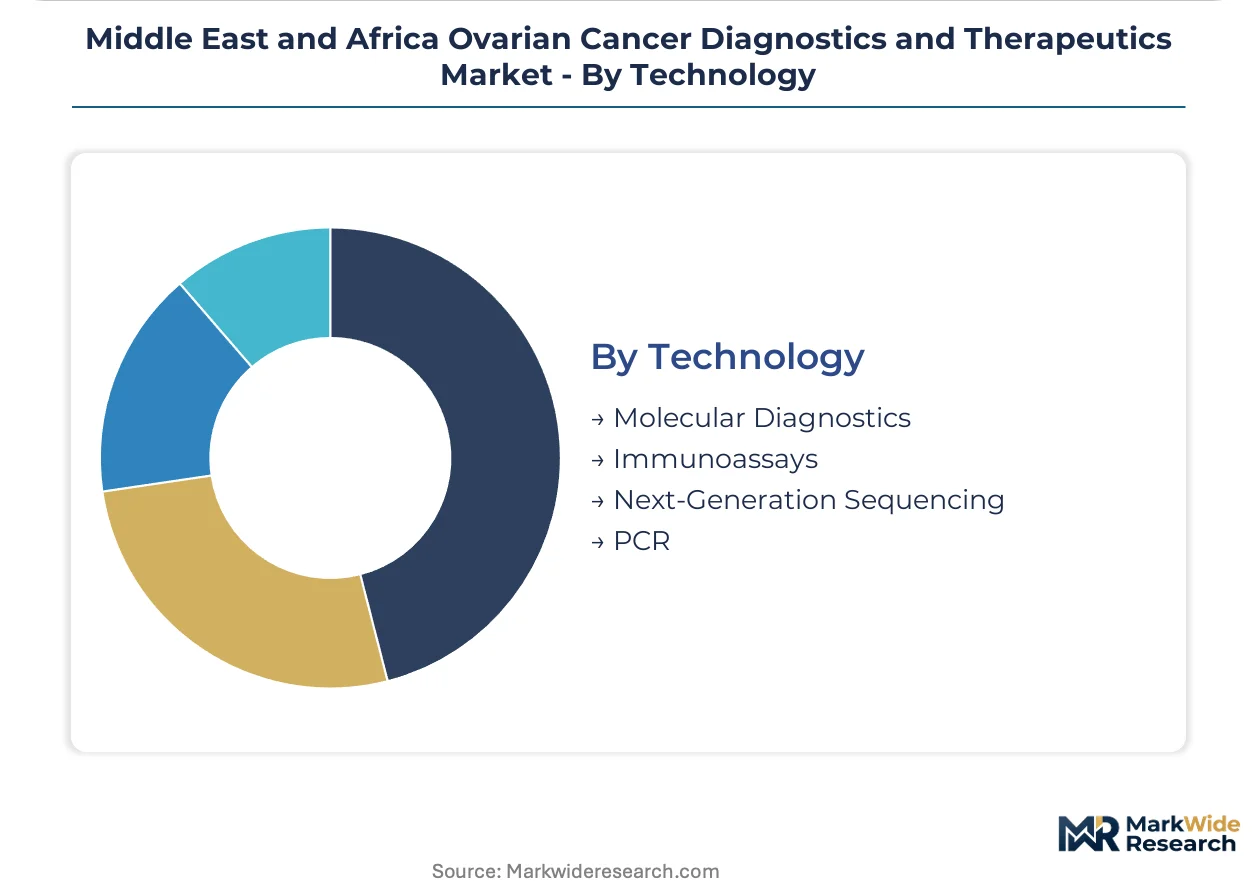
Technology:
Technology platform selection reflects laboratory capital investment cycles and pathologist training availability across the region's fragmented diagnostic infrastructure.
- Next-Generation Sequencing:Comprehensive genomic profiling panels are penetrating UAE and Israeli reference laboratories, enabling tumor-agnostic biomarker detection that matches patients to targeted trials. Platform economics favor high-throughput centralized labs over hospital-based pathology departments.
- Molecular Diagnostics:BRCA1/2 mutation testing and HRD assay deployment concentrates in Saudi Arabia's SFDA-registered central laboratories and South Africa's academic medical center networks.
- Immunoassays:CA-125 and HE4 ELISA platforms remain the workhorse technology across Egypt and Morocco where equipment costs and technical training requirements are lower.
- PCR:Targeted mutation detection supports liquid biopsy validation studies in Israeli and South African research programs.
Immunoassays lead by installed base. Next-generation sequencing shows the steepest expansion trajectory as laboratory consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA regulatory modernization in Saudi Arabia anchors pharmaceutical and diagnostic access across the Gulf Cooperation Council. The authority's compressed biomarker assay registration timelines are accelerating commercial deployment of companion diagnostic platforms. Regional harmonization through the GCC Central Drug Registration system is reducing multi-country launch complexity for multinational manufacturers.
Saudi Arabia
King Faisal Specialist Hospital and National Guard Hospital oncology departments are expanding comprehensive genomic profiling capabilities. SFDA streamlined pathways for BRCA mutation testing kits have compressed validation windows to under six months. Riyadh and Jeddah tertiary centers are consolidating molecular testing procurement through centralized laboratory partnerships.
United Arab Emirates
Dubai Health Authority and Abu Dhabi Department of Health are licensing next-generation sequencing platforms for tumor-agnostic biomarker detection. MOHAP regulatory frameworks align with international standards for in-vitro diagnostic device registration. Cleveland Clinic Abu Dhabi and Sheikh Khalifa Medical City are establishing reference laboratory partnerships with Israeli and European genomic profiling providers.
South Africa
Netcare and Life Healthcare private hospital networks are expanding molecular pathology capabilities for medical aid scheme patients. SAHPRA risk-based classification for companion diagnostic co-submissions is accelerating parallel therapy and test approvals. Johannesburg and Cape Town academic medical centers are consolidating procurement through centralized laboratory partnerships.
Israel
Sheba Medical Center and Tel Aviv Sourasky Medical Center are deploying liquid biopsy workflows for treatment-naive patient stratification. Ministry of Health EMA-aligned standards enable rapid adoption of European-approved genomic profiling panels. Tel Aviv and Haifa metropolitan laboratory networks are integrating cell-free DNA analysis into standard ovarian cancer diagnostic protocols.
Egypt
National Cancer Institute Cairo is expanding surgical oncology capacity for primary debulking procedures. The country's national pharmaceutical regulator maintains import licensing frameworks that extend registration timelines for novel biologic therapeutics. Cairo and Alexandria public hospital networks face cold-chain infrastructure deficits that fragment biologic distribution outside private oncology centers.
Middle East and Africa Ovarian Cancer Diagnostics and Therapeutics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle East and Africa ovarian cancer market. Swiss and UK-based pharmaceutical multinationals anchor the targeted therapy segment through companion diagnostic platform investments, while US-based diversified health conglomerates compete on scale and distribution reach. The market structure splits between premium-tier biologic manufacturers and established cytotoxic chemotherapy suppliers. Dominant competitive moves include strategic partnerships with regional distributors to overcome cold-chain constraints and portfolio diversification into oral maintenance therapies that reduce infusion chair dependency.
Within the pharmaceutical archetype, AstraZeneca plc and Bristol Myers Squibb Company occupy positions shaped by immuno-oncology and targeted therapy portfolios. F. Hoffmann-La Roche Ltd represents the integrated diagnostic-therapeutic model through sustained investment in companion diagnostic platforms. Among diversified health conglomerates, Johnson & Johnson exemplifies scale-driven market presence spanning surgical oncology devices through pharmaceutical therapeutics. Siemens Healthineers AG and Abbott sit within the diagnostic technology tier, supplying imaging systems and biomarker quantification platforms to hospital procurement committees across Gulf state oncology networks.
| Leading Market Players |
|---|
| AstraZeneca plc |
| Bristol Myers Squibb Company |
| F. Hoffmann-La Roche Ltd |
| Johnson & Johnson |
| Siemens Healthineers AG |
| GlaxoSmithKline plc |
| Eli Lilly and Company |
| Pfizer Inc. |
| Abbott |
| Others |
Supply & Pricing Matrix
Take-or-pay contracts for cold-chain logistics capacity lock in biologic distribution access across Gulf state oncology networks while anchoring price visibility for PARP inhibitor therapies over multi-year procurement cycles. South African medical aid schemes and Saudi exceptional-use programs negotiate these arrangements to mitigate supply interruption risks that would destabilize patient maintenance protocols.
Pricing Analysis
Price spreads between Israeli tertiary centers and Egyptian public hospitals exceed threefold for identical BRCA testing kits, reflecting divergent reimbursement frameworks and import duty structures. Three-tier pricing structure across premium, standard, and economy levels stratifies by laboratory accreditation tier and turnaround time guarantees. Cost compression in economy-tier immunoassay segments is intensifying because Egyptian and Moroccan public procurement favors lowest-bidder selection criteria. Private hospital networks in South Africa and the UAE exhibit lowest price sensitivity, while Kenya's nascent screening programs demonstrate highest sensitivity to per-test costs.
Supply Chain Analysis
Cold-chain infrastructure gaps at Lagos and Nairobi air freight terminals fragment biologic distribution into sub-Saharan African markets beyond South Africa's Netcare network. Manufacturing concentration in Switzerland, the United States, and India for active pharmaceutical ingredients and diagnostic reagents creates single-source vulnerability for BRCA testing kits and PARP inhibitor tablets. Distribution runs through authorized distributor networks with temperature-validated last-mile protocols in Gulf states, contrasting with ambient-temperature degradation risks in Egyptian public sector channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid biopsy technology is compressing diagnostic timelines from weeks to days, creating a regulatory and reimbursement inflection that rewards first-movers in plasma-based BRCA testing workflows. Saudi SFDA's six-month validation windows and South Africa's SAHPRA risk-based classification together accelerate market entry for companion diagnostic platforms.
For Market Incumbents: Fortify companion diagnostic platform positions through exclusive laboratory partnerships in Israel's Sheba Medical Center and UAE's Cleveland Clinic Abu Dhabi, locking out rival biomarker assay vendors. Deepen backward integration into cell-free DNA analysis reagent manufacturing to offset margin pressure from emerging liquid biopsy entrants. Prioritize certification investment for GCC Central Drug Registration harmonization to compress multi-country launch timelines. For New Entrants and Emerging Players: Anchor in platinum sensitivity functional assay segments across Egypt and Morocco, where pathology infrastructure gaps have delayed incumbent penetration. Kenya's National Cancer Control Strategy expansion and Nigeria's diagnostic center privatization waves represent the most penetrable geographies. Pursue telepathology network partnerships as the primary go-to-market angle, bypassing physical infrastructure constraints through Israeli and South African specialist hub connectivity. For Investors and Strategic Acquirers: Regional distributors with validated cold-chain capabilities and SFDA registration expertise command premium positioning as acquisition targets. Long-term viability hinges on portfolio exposure to oral maintenance therapies that reduce infusion chair dependency and expand addressable patient populations beyond tertiary center catchments. Watch SAHPRA companion diagnostic co-submission volumes as the inflection signal for parallel therapy-test approval velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Submission | SAHPRA's risk-based classification compresses parallel therapy and test approval timelines for South African launches. |
| Liquid Biopsy Platform Validation | Six-month SFDA validation windows for plasma-based BRCA testing accelerate treatment-naive patient stratification in Gulf states. |
| Cold-Chain Distribution Partnership | Temperature-validated last-mile protocols unlock biologic access beyond South Africa's private hospital networks. |
| Telepathology Network Integration | Digital pathology platforms connecting regional labs to Israeli specialist hubs bypass Egypt's pathologist scarcity constraints. |
| Oral Maintenance Therapy Expansion | PARP inhibitor tablets reduce dependency on infusion chair capacity where gynecologic oncologist shortages limit surgical throughput. |
Research Methodology
The analysis maps biomarker assay, imaging system, and therapeutic modality segments, each validated through regulatory affairs leads at Saudi SFDA and South Africa's SAHPRA, oncology department procurement managers at Netcare and Life Healthcare facilities, and formulary directors at Israeli medical centers. Primary interviews with gynecologic oncologists and laboratory directors across tertiary hospitals in the UAE, Israel, and South Africa combined with secondary validation against EMA submission databases, ClinicalTrials.gov protocol records, and GCC Central Drug Registration harmonization documents. Bottom-up patient volume modeling and top-down healthcare expenditure triangulation anchored market sizing across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs, with projections tested against historical adoption curves for NGS platform penetration in comparable emerging markets. Segmentation dimensions modeled include technology platform, delivery mode, end-user facility type, and regional regulatory cluster. CAGRs derived from weighted average of procedure volume growth and price evolution assumptions, with inputs from biomarker test reimbursement rate trajectories and pharmaceutical pricing negotiation patterns in Gulf state exceptional-use programs.
Underlying assumptions cover sustained SFDA regulatory modernization, GCC harmonization progress, and private hospital procurement expansion, with deviation risk concentrated in cold-chain infrastructure investment delays and public sector budget constraints in Egypt and Nigeria. Practitioners should keep alternative scenarios live as Kenya's National Cancer Control Strategy implementation pace and liquid biopsy reimbursement determinations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Colorectal Cancer Market
Oncology
Ovarian Cancer Market
Oncology
Testicular Cancer Treatment Market
Oncology
Europe Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Europe Tumor Ablation Market
Oncology
Global Metastatic Cancer Treatment Market
Oncology
North America Veterinary Oncology Market
Oncology
Europe Radiotherapy Market
Oncology
Small Cell Lung Cancer (SCLC) Therapeutics Market
Oncology
North America Bone Metastasis Market
Oncology
Global Skin Cancer Diagnostics and Therapeutics Market
Oncology
Precision Oncology Market
Oncology
Oncology Market
Oncology
Pancreatic Cancer Treatment Market
Oncology
Global Oncology Clinical Trials Market
Oncology
Hadron Therapy Market