
 Spinal Cord Trauma Treatment Market | 2026-2036
Spinal Cord Trauma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Cord Trauma Treatment Market Analysis
Neurostimulation platform miniaturization is reshaping how spinal cord trauma interventions are designed, manufactured, and deployed across acute and chronic care settings. Medtronic leverages decades of implantable device expertise to sustain leadership in closed-loop stimulation architectures. Stryker anchors its position through integrated surgical navigation systems that bridge operative precision with post-operative monitoring. Pfizer Inc competes via pharmacologic portfolios targeting secondary injury cascades, differentiating its pipeline through blood-spinal cord barrier permeability enhancements.
Spinal cord trauma treatment encompasses surgical decompression, neural protection, functional restoration, and long-term rehabilitation protocols delivered through implantable hardware, biologics, and targeted drug delivery systems, with neurostimulation devices typically operating at 2–120 Hz frequency ranges to modulate pain and motor pathways. Medication segments command substantial margin pools where biologics and neuroprotective agents address inflammation and glial scarring, while rehabilitation devices represent the fastest-growing structural category as payors shift toward outcome-based recovery metrics. Surgical procedures remain the mature revenue backbone, though biological treatments within technology segments are gaining traction through stem cell and gene therapy vectors.
FDA breakthrough device pathways and CMS inpatient rehabilitation facility criteria shape product development timelines and reimbursement access across the United States, while EMA's Medical Device Regulation and EU AI Act impose conformity and algorithmic transparency requirements on AI-assisted diagnostic and neurostimulation systems in Europe. Japan's PMDA accelerates market entry through Sakigake designation for regenerative therapies targeting spinal cord injury. Stakeholders must monitor evolving evidentiary standards for neurostimulation durability claims and prepare for indication expansions that could redraw competitive boundaries between device and pharmaceutical modalities.
Market Dynamics
Neurostimulation platform miniaturization is compressing development cycles and forcing surgical hardware manufacturers to integrate software competencies or cede positioning to neuromodulation specialists with closed-loop architectures.
Growth Catalysts
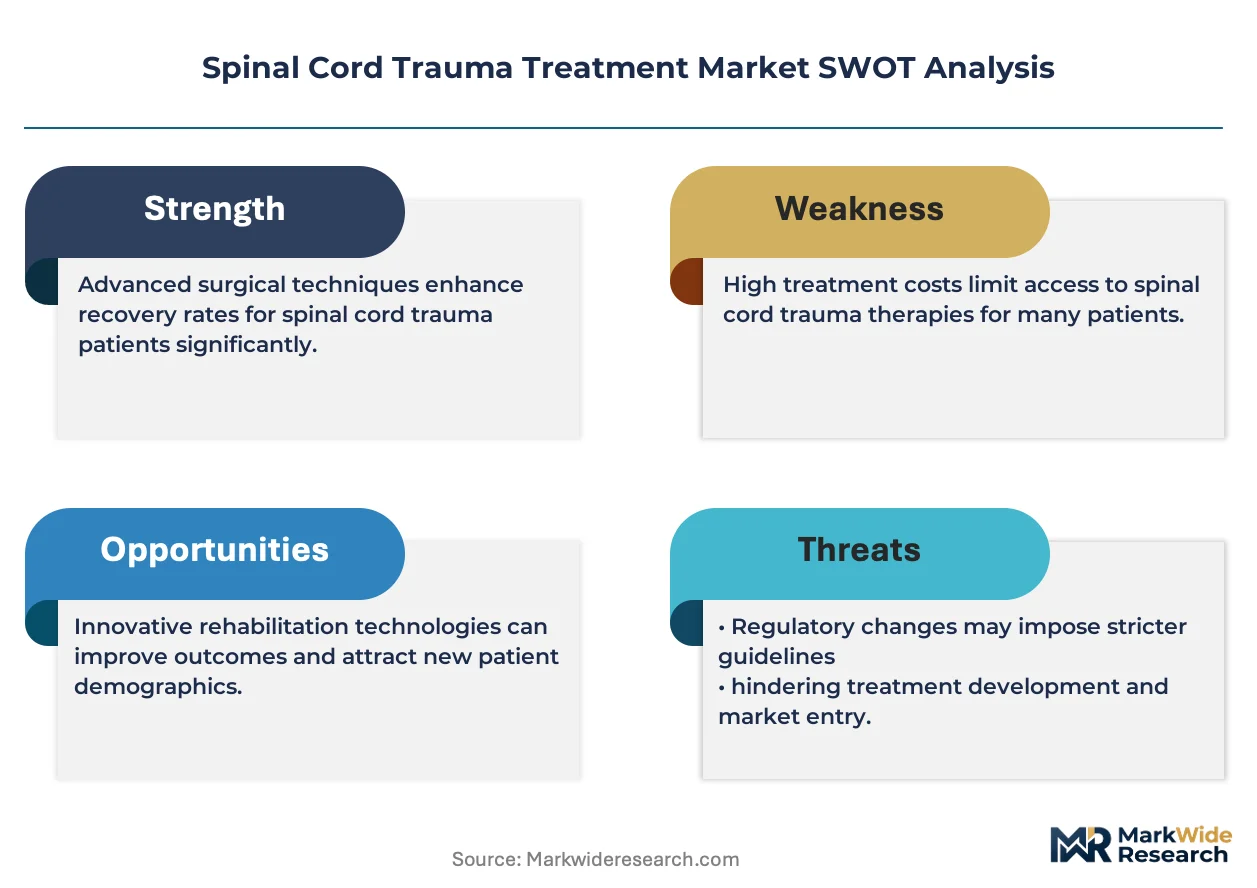
- FDA Breakthrough Device Pathway:The FDA's accelerated review mechanism for spinal cord injury devices compresses time-to-market for neurostimulation implants and regenerative biologics, incentivizing venture investment in preclinical pipelines.
- Trauma Center Capability Upgrades:Level I trauma centers across the United States are acquiring intraoperative neurophysiological monitoring systems, expanding addressable surgical volumes for real-time spinal cord function preservation.
- Stem Cell Vector Advances:Pluripotent stem cell-derived oligodendrocyte progenitor cells are demonstrating remyelination efficacy in early-phase trials, pulling pharmaceutical investment toward biological restoration modalities.
Market Restraints
- Platinum-Iridium Electrode Cost Volatility:Neurostimulation device margins face pressure from precious metal price swings in electrode fabrication, concentrating supply risk with three primary metallurgical suppliers.
- Long-Term Implant Durability Uncertainty:Ten-year reliability data for epidural stimulation arrays remains sparse, creating reimbursement hesitation among private payors and CMS regional contractors.
- Neuroprotective Agent Substitution:High-dose methylprednisolone protocols, despite efficacy controversies, persist as low-cost acute alternatives to proprietary biologics in resource-constrained settings.
Strategic Opportunities
- Home-Based Rehabilitation Devices:Wearable functional electrical stimulation systems for chronic-phase patients bypass facility-based reimbursement caps, opening direct-to-consumer and durable medical equipment channels.
- PMDA Sakigake Designation:Japan's regenerative medicine fast-track is accelerating iPSC-derived neural stem cell therapies toward conditional approval, creating first-mover positioning for entrants with manufacturing scale.
- AI-Assisted Surgical Navigation:Machine learning integration with intraoperative imaging is collapsing operative time variability, enabling high-volume surgeons to expand case throughput without proportional staffing increases.
Industry Challenges
- Neurostimulation Programmer Certification Complexity:Device manufacturers must maintain specialized field clinical engineer networks capable of parameter optimization, constraining geographic expansion speed.
- Biologics Cold Chain Integrity:Cell therapy products require continuous cryogenic logistics from manufacturing through implantation, with temperature excursion risks amplifying liability exposure.
- Legacy Electronic Health Record Integration:Surgical navigation and post-operative monitoring systems face interoperability friction with hospital IT infrastructure, extending sales cycles and implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Cord Trauma Treatment Market |
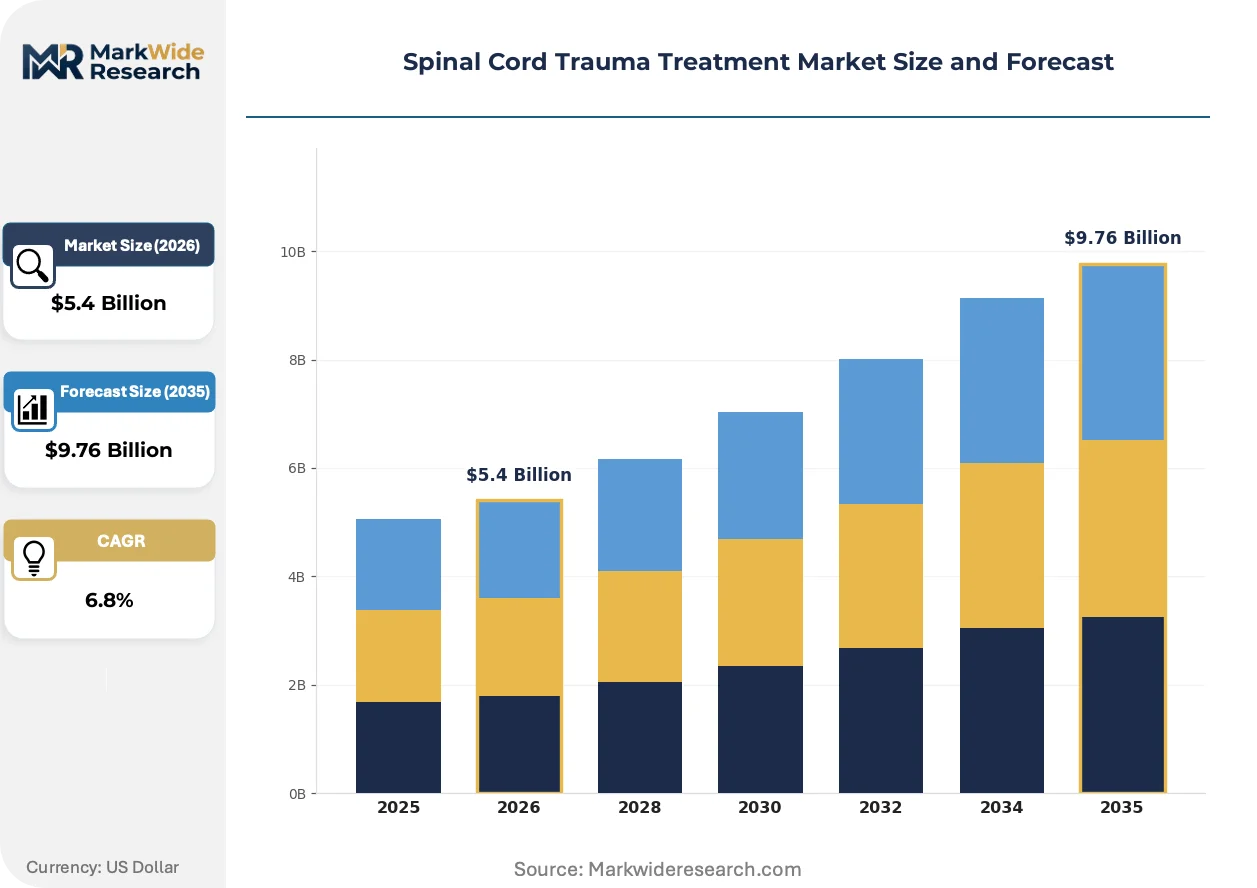
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Procedures, Rehabilitation Devices, Medication, Diagnostic Tools End User: Hospitals, Rehabilitation Centers, Home Care Settings, Specialty Clinics Application: Acute Treatment, Long-term Management, Post-operative Care, Research Studies Technology: Neurostimulation, Biological Treatments, Pharmacologic Interventions, Assistive Technologies |
| Companies Covered | Pfizer Inc, AbbVie Inc, Biogen Inc, Medtronic, Stryker, Globus Medical Inc, Acorda Therapeutics Inc, Kringle Pharma Inc, Pharmazz Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Cord Trauma Treatment Market Emerging Trajectories
Convergence of implantable hardware with closed-loop algorithms and biological payloads is dissolving traditional boundaries between device and pharmaceutical modalities in spinal cord trauma intervention.
Closed-loop neurostimulation architectures with adaptive feedback algorithms are collapsing the distinction between fixed-parameter and patient-responsive therapy delivery. Academic medical centers and specialized spinal cord injury units are adopting these systems at accelerating cadence for both acute neuroprotection and chronic motor restoration. The technology is collapsing pricing power for conventional open-loop stimulators while forcing manufacturers to build software-as-service revenue streams around algorithm updates.
EMA's Medical Device Regulation and the EU AI Act are imposing conformity assessment and algorithmic transparency requirements on AI-assisted diagnostic and neurostimulation systems marketed in Europe. Device manufacturers must now submit technical documentation demonstrating clinical validation of machine learning components, extending regulatory timelines by twelve to eighteen months for new product introductions. Neurostimulation platforms with embedded diagnostic algorithms face the steepest compliance burden, with notified body backlog concentrating submission risk in Germany and the Netherlands.
Hospital procurement committees are unbundling after-sales service from device capital purchases, compressing vendor margins on implementation and training. This pattern is displacing traditional bundled contracts with multi-year service agreements in favor of spot-market technical support and third-party maintenance alternatives. The shift is most visible in United States academic medical centers where GPO-negotiated hardware pricing now excludes proprietary software licenses and parameter optimization services.
Spinal Cord Trauma Treatment Market Segmentation
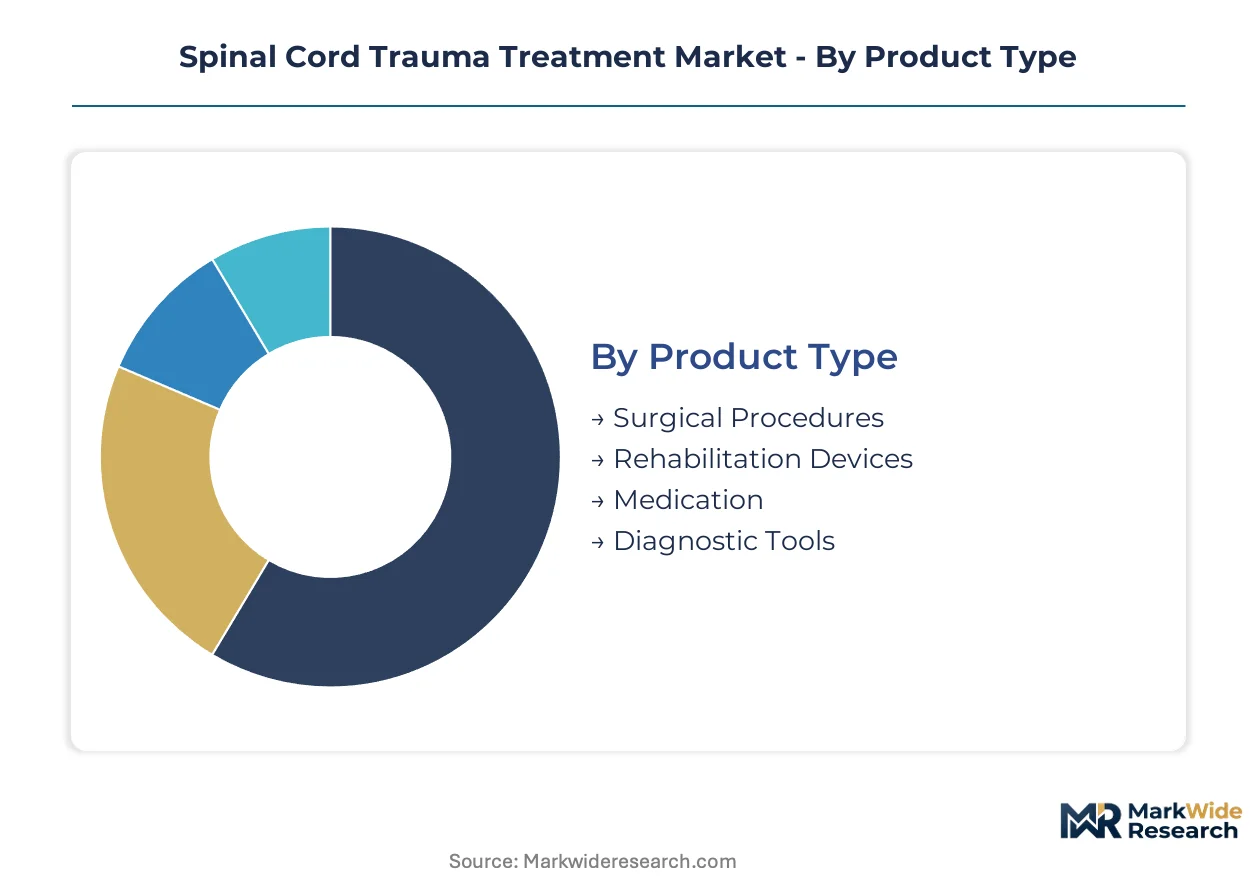
Spinal cord trauma treatment segments reflect divergent reimbursement pathways, technology maturity curves, and care setting economics that reshape vendor go-to-market strategies. Understanding how acute surgical intervention, chronic rehabilitation, and biological restoration modalities split across institutional and ambulatory channels determines portfolio prioritization for device and pharmaceutical stakeholders.
Product Type:
Product type segmentation spans the full care continuum from emergency decompression through lifetime functional maintenance, with each modality carrying distinct margin profiles and regulatory burdens.
- Surgical Procedures:Decompression laminectomies, vertebral stabilization, and intradural interventions command premium reimbursement under DRG-based acute care payment systems. Demand concentrates in Level I trauma centers across the United States, Germany, and Japan where intraoperative neuromonitoring capabilities justify case complexity premiums.
- Medication:Neuroprotective agents, corticosteroid protocols, and analgesic regimens address secondary injury cascades and chronic pain management. Formulary placement in hospital emergency departments and inpatient rehabilitation facilities drives volume, with blood-spinal cord barrier permeability enhancements differentiating next-generation candidates from generic alternatives.
- Rehabilitation Devices:Functional electrical stimulation systems and exoskeleton platforms enable motor recovery in chronic-phase patients.
- Diagnostic Tools:Intraoperative imaging and electrophysiological monitoring systems guide surgical decision-making and post-operative assessment.
Established volume favors surgical procedures; emerging adoption favors rehabilitation devices.
End User:
End user segmentation tracks the decentralization of spinal cord trauma care from centralized surgical hubs toward distributed rehabilitation and home-based management.
- Hospitals:Academic medical centers and designated trauma centers anchor acute surgical volume, with neurosurgical ICU capacity and intraoperative imaging infrastructure determining referral catchment areas. CMS inpatient prospective payment systems and comparable DRG mechanisms in Germany and Japan shape profitability for complex spinal stabilization procedures.
- Rehabilitation Centers:Inpatient rehabilitation facilities and specialized spinal cord injury units deliver intensive functional recovery protocols. Outcome-based reimbursement contracts from private payors and national health systems in Europe are accelerating capital deployment for robotic-assisted therapy platforms.
- Home Care Settings:Wearable neurostimulation and telehealth-monitored exercise programs bypass facility-based reimbursement caps.
- Specialty Clinics:Ambulatory surgical centers and pain management practices handle selective decompression and neurostimulator programming.
Revenue concentration sits with hospitals; expansion opportunity concentrates in home care settings.
Application:
Application segmentation distinguishes time-sensitive acute intervention from longitudinal management protocols with divergent evidence requirements and pricing power.
- Acute Treatment:Emergency decompression, spinal stabilization, and neuroprotective drug administration within the first 72 hours post-injury aim to limit secondary neuronal damage. Trauma center network density in the United States and specialized spinal cord injury units in Japan determine geographic access to guideline-concordant acute care.
- Long-term Management:Chronic pain control, spasticity management, and functional restoration span decades of patient engagement. Payer willingness to cover implantable neurostimulation and biological therapies for chronic indications remains variable across CMS regional contractors and European national health technology assessment bodies.
- Post-operative Care:Wound management, infection surveillance, and early mobilization protocols bridge surgical intervention and rehabilitation entry.
- Research Studies:Clinical trial infrastructure supports investigational stem cell, gene therapy, and closed-loop neurostimulation platforms.
Clinical urgency dominates acute treatment; sustained engagement characterizes long-term management.
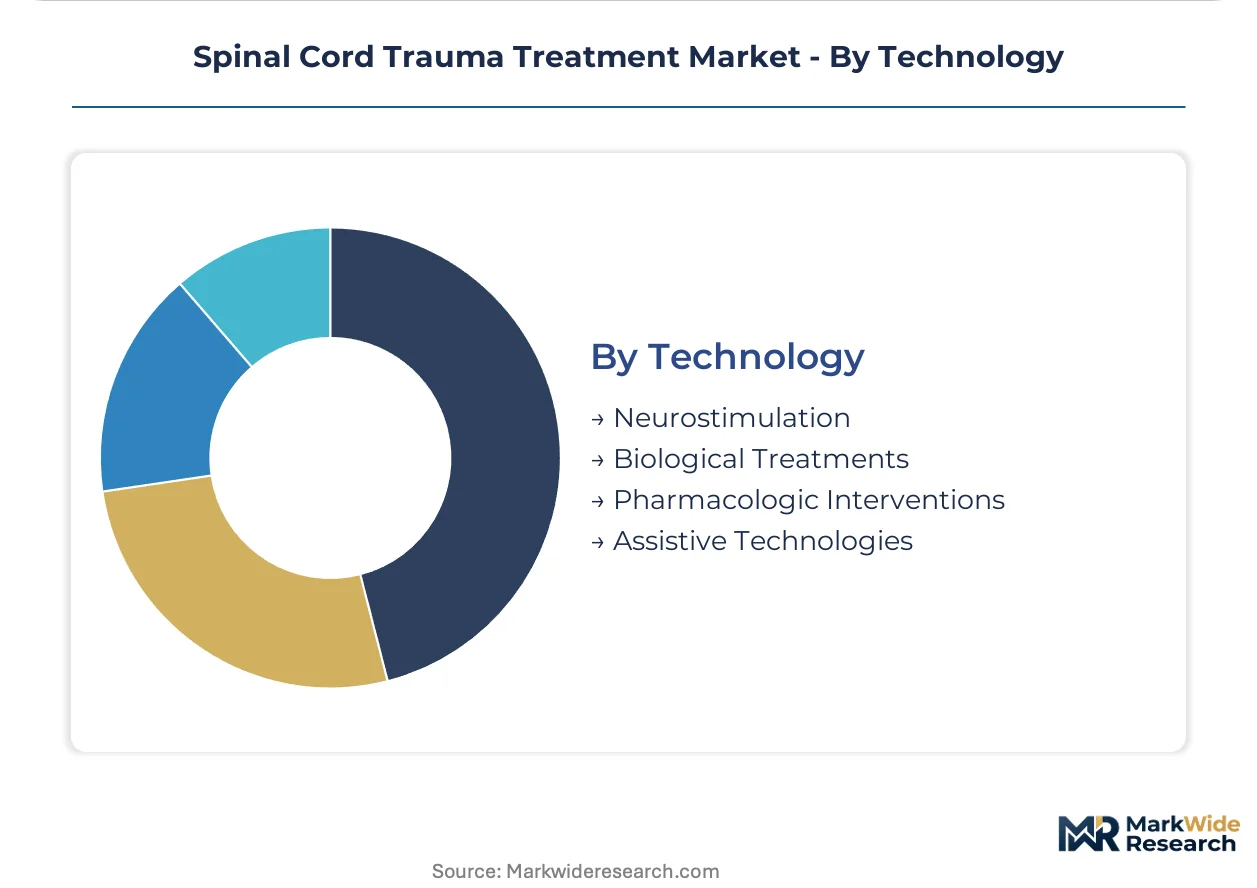
Technology:
Technology segmentation captures the convergence of electrical neuromodulation, biological restoration, and pharmacologic intervention into multimodal treatment paradigms.
- Neurostimulation:Epidural and transcutaneous electrical stimulation systems modulate pain and motor pathways through programmable frequency delivery. Closed-loop architectures with adaptive feedback algorithms are displacing fixed-parameter devices in academic medical centers, with software-as-service revenue models emerging around algorithm optimization.
- Biological Treatments:Stem cell-derived oligodendrocyte progenitor cells, gene therapy vectors, and tissue engineering scaffolds target remyelination and axonal regeneration. Japan's PMDA Sakigake designation is accelerating iPSC-derived neural stem cell candidates toward conditional approval ahead of comparable pathways in the United States and Europe.
- Pharmacologic Interventions:Small-molecule neuroprotectants and anti-inflammatory agents address secondary injury mechanisms.
- Assistive Technologies:Exoskeletons, brain-computer interfaces, and environmental control systems augment residual function.
Commercial maturity anchors neurostimulation; pipeline momentum favors biological treatments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German neurostimulation device exports flow into United States trauma centers and Japanese rehabilitation networks, establishing a transatlantic-Pacific trade corridor that concentrates high-value surgical hardware procurement in three national markets.
United States
Level I trauma center density in Baltimore, Houston, and Los Angeles drives demand for intraoperative neuromonitoring systems. FDA breakthrough device designations compress regulatory timelines for epidural stimulation implants. The Cleveland Clinic and Johns Hopkins anchor clinical trial networks for closed-loop neurostimulation protocols.
Germany
Specialized spinal surgery clusters in Berlin, Munich, and Heidelberg generate concentrated demand for precision navigation systems. EMA Medical Device Regulation and EU AI Act impose algorithmic transparency requirements on AI-assisted surgical tools. The Rhine-Ruhr medical technology corridor hosts manufacturing operations for electrode arrays and stimulation programmers.
Japan
Aging demographics and traffic injury patterns sustain demand for regenerative interventions in Tokyo, Osaka, and Nagoya. PMDA Sakigake designation accelerates conditional approval pathways for iPSC-derived neural stem cell therapies. The Kanto region concentrates biologics cold chain infrastructure for cell therapy distribution.
Switzerland
Swissmedic regulatory frameworks attract pharmaceutical development for blood-spinal cord barrier permeability enhancements. Basel and Zurich anchor neuroprotective drug formulation clusters serving European hospital networks. Precision manufacturing capabilities in the Swiss Mittelland support microelectrode fabrication for implantable devices.
United Kingdom
NHS England specialized spinal cord injury centers in London, Sheffield, and Glasgow drive adoption of rehabilitation robotics. MHRA post-Brexit regulatory autonomy enables accelerated assessment of novel neurostimulation indications. The Oxford-Cambridge arc hosts academic partnerships bridging surgical navigation with machine learning diagnostics.
Spinal Cord Trauma Treatment Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where integrated surgical system vendors hold acute-care procurement leverage while neuromodulation specialists capture chronic-phase recurring revenue. The market stratifies into three archetypes: implantable hardware manufacturers with closed-loop software competencies, biologics developers targeting remyelination endpoints, and integrated surgical navigation providers bridging operative and post-operative care. Dominant competitive moves include strategic partnerships between device manufacturers and academic medical centers for clinical validation, plus backward integration into precious metal electrode supply chains to mitigate cost volatility.
Within the implantable hardware tier, Medtronic and Stryker occupy positions exemplifying divergent strategic orientations toward software-centric versus surgical-navigation-centric value capture. Among pharmaceutical developers, Pfizer Inc represents the archetype of neuroprotective drug portfolios targeting secondary injury cascades. These three entities anchor competitive dynamics across the acute-to-chronic care continuum without exclusive territorial claims.
| Leading Market Players |
|---|
| Pfizer Inc |
| AbbVie Inc |
| Biogen Inc |
| Medtronic |
| Stryker |
| Globus Medical Inc |
| Acorda Therapeutics Inc |
| Kringle Pharma Inc |
| Pharmazz Inc |
| Others |
Supply Flow & Price Mechanics
Platinum-iridium electrode fabrication concentrates in three German and Swiss metallurgical suppliers, anchoring margin pools in neurostimulation device tiers where precious metal pass-through clauses protect upstream suppliers from downstream pricing pressure. This concentration forces device manufacturers to absorb volatility or renegotiate GPO contracts, reshaping procurement strategies across implantable hardware portfolios.
Pricing Analysis
Closed-loop neurostimulation platforms command 40-60% premiums over fixed-parameter predecessors, while next-generation biological-device hybrids are pre-negotiating value-based contracts with CMS regional contractors. Three-tier pricing structure across premium algorithm-optimized, standard programmable, and economy fixed-output tiers stratifies the market, with premium tiers bundling software-as-service updates. Pricing pressure stems from hospital procurement committees unbundling after-sales service from capital purchases, compressing vendor margins on implementation. Academic medical centers exhibit lowest price sensitivity due to NIH-funded research budgets, while community hospitals in the United States face acute budget constraints.
Supply Chain Analysis
Platinum-group metals feed from South African and Russian mining operations, with iridium refining concentrated in Belgium and the United Kingdom. Device assembly draws from German precision manufacturing clusters, while biologics cold chain logistics rest on Dutch and Singaporean distribution hubs. Single-source vulnerability in electrode metallurgy amplifies exposure to commodity price swings and geopolitical disruption. Distribution runs through specialized medical device distributors with field clinical engineer networks, bypassing generalist hospital supply chains for parameter optimization services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA breakthrough device designations and CMS reimbursement expansions are accelerating commercial validation for spinal cord trauma interventions, positioning the market for early-cycle penetration gains as trauma centers upgrade intraoperative capabilities.
For Market Incumbents: Pre-empt neuromodulation specialist encroachment by acquiring closed-loop algorithm competencies or licensing adaptive feedback platforms from academic medical centers. Backward integration into platinum-iridium electrode supply chains mitigates cost volatility exposure from German and Swiss metallurgical suppliers. Hospital procurement committee unbundling of after-sales service threatens traditional bundled contract margins, requiring pivot to software-as-service revenue streams around algorithm optimization. For New Entrants and Emerging Players: Home-based rehabilitation devices for chronic-phase patients represent the most penetrable entry point, bypassing facility-based reimbursement caps and opening direct-to-consumer channels. Japan's PMDA Sakigake designation for iPSC-derived neural stem cell therapies offers regulatory fast-track positioning ahead of FDA and EMA pathways. Go-to-market execution should prioritize durable medical equipment distributor partnerships with existing Medicare billing relationships over direct hospital capital sales cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed surgical navigation platform developers lacking closed-loop neuromodulation integration. Long-term viability over the next decade hinges on convergence of implantable hardware with biological payloads, favoring platforms with dual-modality development pipelines. Watch for FDA indication expansion decisions for epidural stimulation in motor restoration as the inflection signal for competitive boundary redraw between device and pharmaceutical modalities.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated review compresses time-to-market for neurostimulation implants and regenerative biologics. |
| CE Marking Pathway under EU AI Act | Algorithmic transparency requirements extend regulatory timelines for AI-assisted diagnostic systems in Europe. |
| Hospital System Partnership | Level I trauma center alliances secure intraoperative neuromonitoring placement and referral volume capture. |
| Software Companion Development | Closed-loop algorithm updates generate recurring revenue streams as hardware margins compress. |
| Reimbursement Strategy | CMS inpatient rehabilitation facility criteria alignment determines commercial access across United States markets. |
Methodological Framework
Desk research of FDA 510(k) and PMA filings, EMA Medical Device Regulation submissions, and CMS Medicare reimbursement databases preceded structured interviews with neurosurgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from ClinicalTrials.gov protocols, hospital procurement databases, and SEC 10-K filings of publicly traded device manufacturers. Bottom-up procedure volume estimates and top-down market sizing triangulated demand figures across the analysis window.
Assumptions held fixed include current FDA breakthrough device pathway timelines, CMS reimbursement criteria stability, and trauma center capability upgrade trajectories; variables tested included EMA MDR compliance timeline extensions, platinum-group metal price volatility scenarios, and PMDA Sakigake designation acceleration effects. Segmentation modeling spanned product type, end user, application, and technology dimensions with regional regulatory cluster overlays. CAGRs derived from procedure volume growth rates, pricing trajectory assumptions, and technology adoption curve positioning, with neurostimulation device replacement cycles and biologics cold chain infrastructure buildout as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, NIH research funding levels, or European medical device reimbursement austerity would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and trauma center network expansion. Cross-checking against CMS Medicare claims data and hospital discharge databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Neurodegenerative Disease Treatment Market
Neurology
Olivopontocerebellar Atrophy Treatment Market
Neurology
Labyrinthitis Market
Neurology
Neurology Software Market
Neurology
Chordoma Disease Market
Neurology
Bell Palsy Treatment Market
Neurology
Moyamoya Disease Market
Neurology
Chile Neurology Devices Market
Neurology
Spasticity Treatment Market
Neurology
Chronic Brain Damage Management Market
Neurology
Transverse Myelitis Treatment Market
Neurology
Amnestic Disorders Therapeutics Market
Neurology
Hepatic Encephalopathy Market
Neurology
Optic Neuritis Treatment Market
Neurology
Asia-Pacific Neurology Monitoring Market
Neurology
Occipital Nerve Block Treatment Market