
 Malignant Lymphoma Market | 2026-2036
Malignant Lymphoma Market Size, Share, and Industry Trends Forecast 2026-2036
Malignant Lymphoma Market Outlook
Multi-source biologics sourcing is realigning procurement strategies across oncology supply chains. Bristol-Myers Squibb anchors its position through integrated immuno-oncology manufacturing networks. F. Hoffmann-La Roche leverages extensive diagnostic-therapeutic pairing to sustain channel control in lymphoma care. BeiGene competes aggressively on biosimilar and novel antibody development, extending its geographic footprint beyond established markets.
Malignant lymphoma comprises a heterogeneous group of hematologic neoplasms originating from lymphoid tissue, characterized by clonal proliferation of B-cells, T-cells, or natural killer cells with distinct immunophenotypic markers and cytogenetic profiles; these conditions disrupt normal immune function and require systemic therapeutic intervention. The primary commercial purpose centers on interrupting oncogenic signaling pathways while preserving hematopoietic reserve. Monoclonal antibodies occupy the dominant revenue position given entrenched CD20-targeted protocols, while immunotherapies represent the fastest-expanding margin pool as CAR-T and bispecific antibody platforms gain regulatory traction. Targeted therapies concentrate investment around PI3K and BTK inhibitor classes where resistance profiling creates specialist segmentation.
FDA breakthrough therapy designation and EMA's PRIME scheme compress development timelines for lymphoma drug candidates, directly shaping competitive market access conditions. The EPA governs biologics manufacturing waste streams, while HIPAA frameworks constrain real-world evidence collection strategies that manufacturers depend on for post-market differentiation. Stakeholders must monitor how CMS coverage determination processes for cellular therapies evolve against background pricing scrutiny from congressional oversight committees.
Market Dynamics
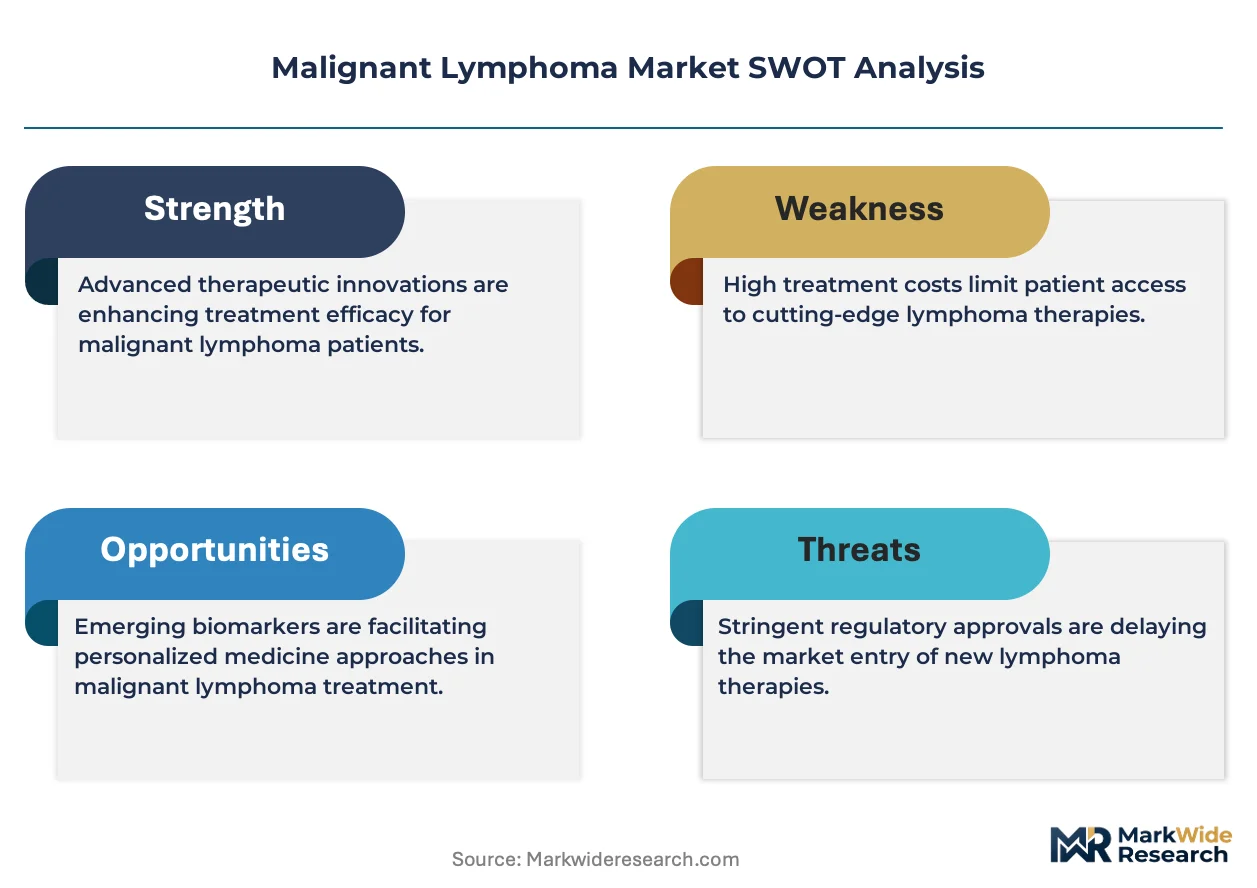
CAR-T cell therapy manufacturing bottlenecks are concentrating competitive advantage among firms with captive viral vector production, compressing margins for contract-dependent developers and reshaping partnership terms across the value chain.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Accelerated review timelines for lymphoma drug candidates compress development cycles and reduce capital-at-risk duration for novel immunotherapy platforms.
- Academic Medical Center Expansion:Major cancer treatment centers in the United States anchor patient recruitment networks that sustain clinical trial velocity for cellular therapy protocols.
- CD20-Targeted Protocol Entrenchment:Established monoclonal antibody treatment pathways create predictable reimbursement codes that reduce commercial friction for next-generation combination regimens.
Market Restraints
- Viral Vector Supply Concentration:Lentiviral and retroviral vector manufacturing concentrates among a limited supplier base, creating single-source vulnerability for CAR-T developers.
- CMS Coverage Determination Uncertainty:Reimbursement pathways for inpatient cellular therapy administration remain contested, pressuring provider adoption timelines.
- Autologous Manufacturing Complexity:Patient-specific cell processing requires distributed cleanroom infrastructure that scales linearly with volume, constraining cost reduction curves.
Strategic Opportunities
- Allogeneic Off-the-Shelf Platforms:Universal donor cell therapies promise manufacturing scale economies that autologous processes cannot achieve, attracting venture allocation toward gene-editing enablement.
- Real-World Evidence Infrastructure:HIPAA-compliant data collection networks offer post-market differentiation pathways for therapies demonstrating durable response in community oncology settings.
- Bispecific Antibody Convergence:Dual-targeting modalities bridge chemotherapy and cellular therapy treatment sequences, capturing patients ineligible for CAR-T enrollment.
Industry Challenges
- Cell Processing Technician Scarcity:Specialized cleanroom operators and vector production scientists command premium compensation, constraining manufacturing expansion timelines.
- Multi-Site Quality Harmonization:Decentralized cell therapy manufacturing requires consistent potency assay performance across geographically dispersed facilities, complicating regulatory inspection readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malignant Lymphoma Market |
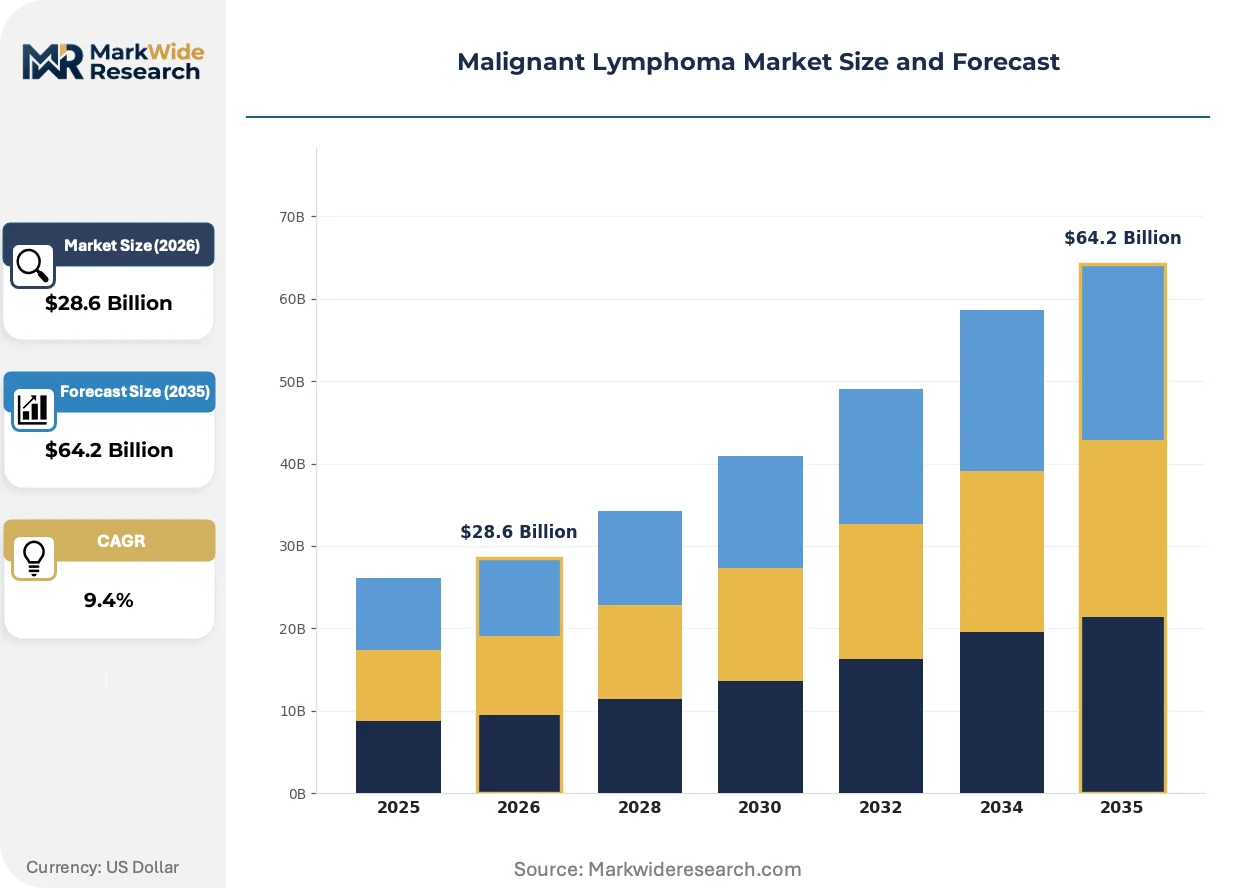
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Chemotherapy Agents, Targeted Therapies, Immunotherapies Therapy Area: Non-Hodgkin Lymphoma, Hodgkin Lymphoma, Burkitt Lymphoma, Follicular Lymphoma End User: Hospitals, Clinics, Research Institutions, Cancer Treatment Centers Delivery Mode: Oral, Intravenous, Subcutaneous, Intramuscular |
| Companies Covered | AstraZeneca, Johnson & Johnson, Bristol-Myers Squibb, Gilead Sciences, Merck & Co., F. Hoffmann-La Roche, Novartis, BeiGene, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malignant Lymphoma Market Strategic Shifts
Immunotherapy platform evolution is compressing treatment paradigms from months-long chemotherapy cycles toward single-infusion cellular interventions, forcing infrastructure reinvestment across infusion center networks and cold-chain logistics.
Bispecific T-cell engagers are overtaking salvage chemotherapy regimens in relapsed/refractory diffuse large B-cell lymphoma. Community oncology practices accelerate adoption as outpatient administration protocols mature. The technology is overtaking traditional step-up dosing requirements through improved cytokine release syndrome management, compressing hospitalization duration and total cost of care.
EMA's PRIME scheme eligibility expansion for hematologic malignancies accelerates European market access timelines for lymphoma therapies. Manufacturers file parallel scientific advice requests to align FDA and EMA development strategies. The policy shift most affects mid-cap developers lacking legacy regulatory affairs infrastructure, forcing external partnership or capability acquisition.
Site-of-care migration accelerates as hospital outpatient departments consolidate infusion capacity and private payers narrow in-network site preferences. Independent oncology practices face displacement unless they achieve accreditation for cellular therapy administration. This concentration is most visible in United States metropolitan markets where academic medical center affiliation determines referral pattern capture.
Malignant Lymphoma Market Segmentation
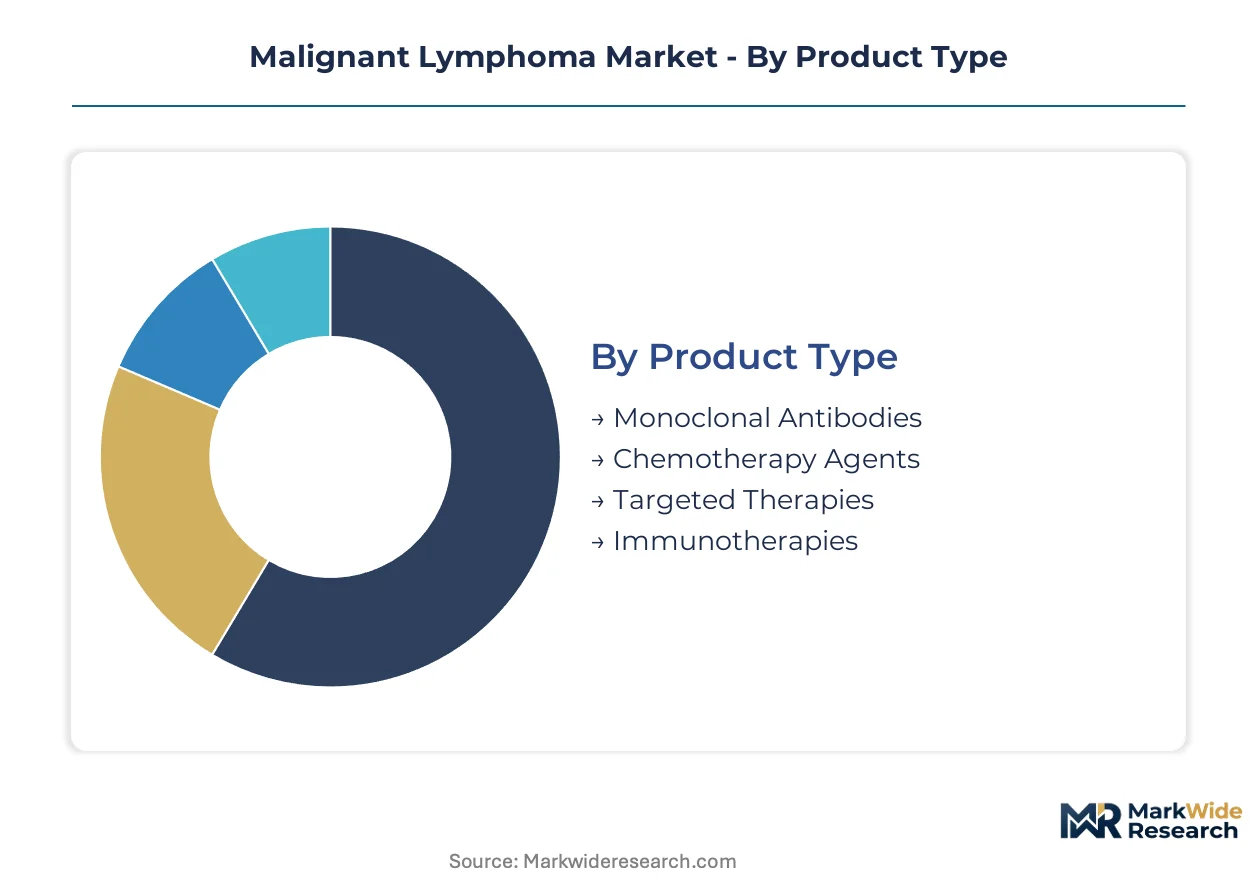
Treatment modality selection in malignant lymphoma hinges on immunophenotypic profiling and prior therapy exposure, creating distinct procurement patterns across academic and community settings. Segmentation reveals how CD20-targeted protocols anchor volume while cellular therapies concentrate margin capture among specialized centers.
Product Type:
Procurement teams differentiate these categories by manufacturing complexity and cold-chain requirements, with biologics commanding premium logistics investment.
- Monoclonal Antibodies:CD20-targeted agents dominate infusion center throughput with established reimbursement codes and predictable supply scheduling. United States academic medical centers anchor procurement volumes through entrenched rituximab-based protocols, though biosimilar substitution is compressing net pricing.
- Immunotherapies:CAR-T cell therapies and bispecific antibodies require patient-specific manufacturing or complex protein engineering with distributed cleanroom dependency. Demand concentrates at NCI-designated cancer centers in the United States where FDA-approved manufacturing partnerships enable treatment access.
- Targeted Therapies:Small-molecule BTK and PI3K inhibitors offer oral administration with pharmacy benefit management exposure.
- Chemotherapy Agents:Genericized cytotoxic regimens face commoditization with consolidated purchasing through group purchasing organizations.
Monoclonal antibodies lead volumes today; immunotherapies are gaining share fastest.
Therapy Area:
Clinical trial density and biomarker availability determine commercial prioritization across these indications.
- Non-Hodgkin Lymphoma:Diffuse large B-cell and follicular subtypes drive the majority of novel therapy development with well-defined CD19 and CD20 target expression. United States community oncology practices generate substantial volume for maintenance rituximab following chemoimmunotherapy induction.
- Hodgkin Lymphoma:Checkpoint inhibitor consolidation in early-stage and relapsed settings is displacing salvage chemotherapy and autologous stem cell transplant referral patterns. European treatment centers under EMA guidance are accelerating PD-1 adoption in first-line combined modality protocols.
- Follicular Lymphoma:Indolent disease biology enables prolonged treatment sequences with multiple line-of-therapy opportunities.
- Burkitt Lymphoma:Aggressive disease course requires intensive chemotherapy with limited targeted therapy penetration.
Non-Hodgkin lymphoma commands the largest patient population; Hodgkin lymphoma shows the steepest expansion trajectory for novel immunotherapy uptake.
End User:
Site-of-care economics and cellular therapy accreditation requirements fragment purchasing authority across provider types.
- Cancer Treatment Centers:NCI-designated comprehensive cancer centers control CAR-T patient funneling with captive apheresis and infusion infrastructure. These United States facilities negotiate direct manufacturer contracts bypassing traditional distribution for autologous cell therapies.
- Hospitals:Hospital outpatient departments consolidate infusion capacity with 340B pricing exposure for targeted therapies, though CMS reimbursement uncertainty for cellular therapies constrains capital deployment.
- Clinics:Community oncology practices face site-of-care displacement without cellular therapy accreditation.
- Research Institutions:Academic medical centers anchor clinical trial recruitment with early-access protocols for investigational agents.
Cancer treatment centers capture the highest-value cellular therapy cases; hospitals retain volume leadership for conventional infusion regimens.
Delivery Mode:
Administration setting requirements and pharmacist oversight intensity shape distribution channel selection.
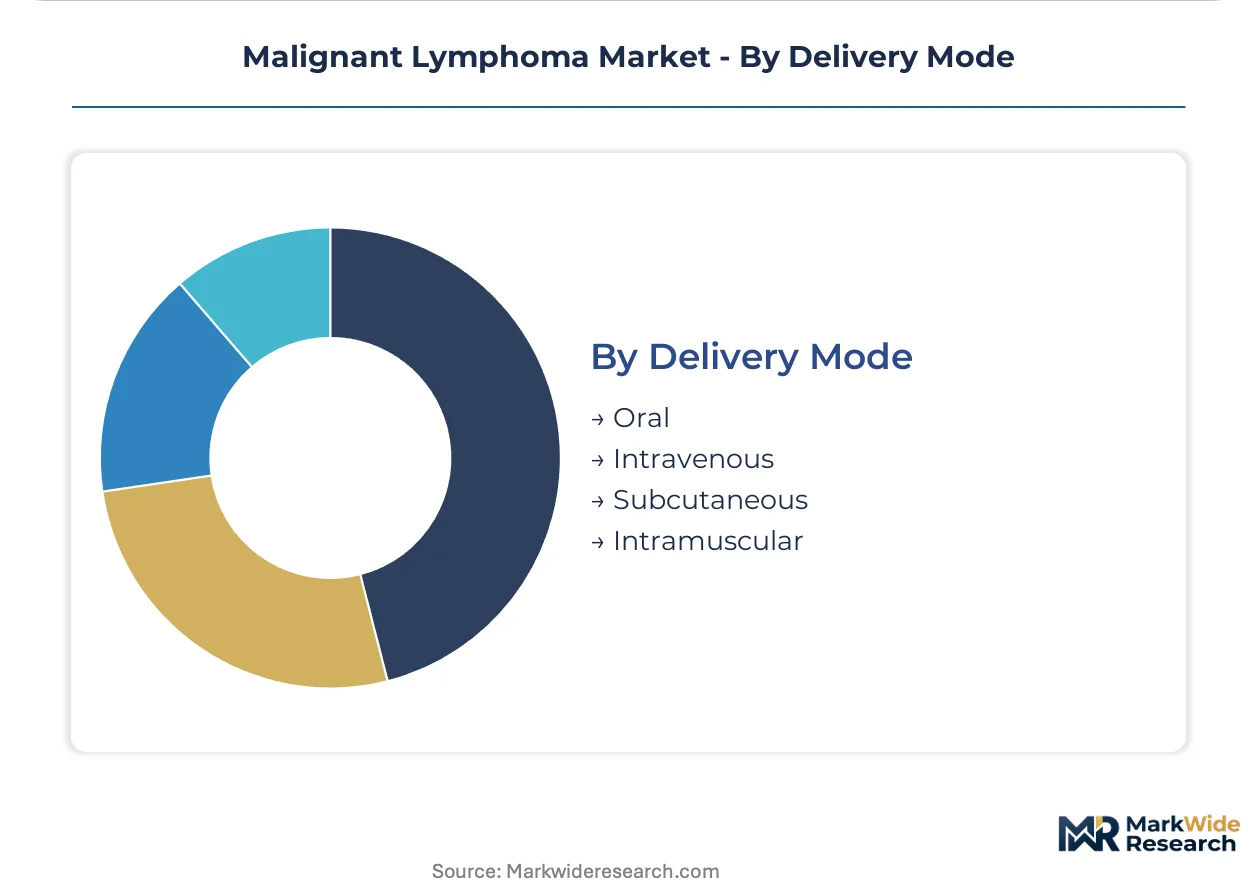
- Intravenous:Infusion center scheduling and nursing supervision requirements concentrate this mode at hospital-affiliated sites with established monoclonal antibody protocols. United States metropolitan markets show site-of-care consolidation toward academic medical center outpatient departments.
- Oral:Targeted small molecules enable community pharmacy dispensing with pharmacy benefit management formulary positioning driving access constraints.
- Subcutaneous:Fixed-dose biologics reduce infusion chair time and enable community practice administration.
- Intramuscular:Limited application for supportive care agents with minimal lymphoma-specific utilization.
Intravenous administration dominates current revenue; oral targeted therapies are expanding most quickly as fixed-duration regimens mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors commercial activity for malignant lymphoma therapeutics through NCI-designated cancer centers in Boston, Houston, and New York that control patient funneling for cellular therapy access. Academic medical centers in these metropolitan clusters negotiate direct manufacturer contracts for autologous CAR-T products. FDA breakthrough therapy designation and CMS coverage determination processes shape reimbursement timelines for novel immunotherapies.
United States
Demand concentrates at Memorial Sloan Kettering, MD Anderson, and Dana-Farber where apheresis infrastructure enables CAR-T patient throughput. FDA accelerated approval pathways compress commercialization timelines for bispecific antibody platforms. The Boston-Cambridge biotech corridor anchors viral vector manufacturing partnerships that supply autologous cell therapy production networks.
Germany
EMA's PRIME scheme eligibility accelerates market access for hematologic malignancy developers filing through Frankfurt regulatory channels. The country's statutory health insurance system negotiates outcome-based reimbursement for checkpoint inhibitor consolidation in Hodgkin lymphoma. Heidelberg and Munich academic hospitals anchor European clinical trial recruitment for novel antibody-drug conjugates.
Japan
PMDA's sakigake designation system prioritizes lymphoma drug reviews for companies with domestic manufacturing presence. Tokyo and Osaka cancer centers concentrate demand for rituximab biosimilars following patent expiry of reference products. METI's pharmaceutical industry revitalization program subsidizes cell therapy manufacturing facility investments in the Kanto region.
China
NMPA's breakthrough therapy designation for hematologic malignancies attracts domestic biotech investment toward CD19-targeted modalities. Shanghai and Beijing hospitals participate in global Phase III trials for novel BTK inhibitors. The country's dual carbon goals pressure biologics manufacturers to retrofit cleanroom energy consumption profiles in the Yangtze River Delta production cluster.
United Kingdom
NICE technology appraisals determine NHS funding for CAR-T therapies through specialized commissioning arrangements. London's Royal Marsden and University College Hospital anchor early-access programs for bispecific T-cell engagers. The MHRA's post-Brexit regulatory autonomy enables accelerated assessment pathways for lymphoma therapies with substantial equivalence to EMA-approved products.
Malignant Lymphoma Market Competitive Environment
Global majors compete with regional champions across manufacturing scale and regulatory access dimensions. The vendor base stratifies into three tiers: integrated pharmaceutical conglomerates with captive viral vector production, mid-cap biotech specialists dependent on contract manufacturing organizations, and emerging biosimilar developers competing on rituximab reference product substitution. Consolidation pressures intensify as CAR-T manufacturing bottlenecks favor firms with backward integration into lentiviral supply. Strategic moves center on geographic licensing partnerships and site-of-care accreditation networks.
Within the integrated conglomerate tier, Bristol-Myers Squibb and F. Hoffmann-La Roche exemplify archetypes combining diagnostic-therapeutic pairing with entrenched CD20 protocol control. BeiGene occupies a position representing aggressive biosimilar and novel antibody development with footprint extension beyond established Western markets. These three anchors illustrate how manufacturing self-sufficiency and regulatory affairs infrastructure determine competitive positioning in cellular therapy commercialization.
| Leading Market Players |
|---|
| AstraZeneca |
| Johnson & Johnson |
| Bristol-Myers Squibb |
| Gilead Sciences |
| Merck & Co. |
| F. Hoffmann-La Roche |
| Novartis |
| BeiGene |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
Viral vector production costs cascade through autologous CAR-T manufacturing, concentrating pricing power among developers with captive lentiviral supply while contract-dependent firms absorb margin compression from third-party vector markups. This input-cost architecture stratifies the market across premium cellular therapies, standard monoclonal antibody protocols, and commoditized chemotherapy regimens with divergent reimbursement exposure.
Pricing Analysis
Input-cost pass-through from viral vector manufacturing dominates pricing structures for cellular therapies, with lentiviral supplier concentration enabling premium tier capture by integrated developers. Pricing stratifies across premium CAR-T products, standard monoclonal antibody maintenance protocols, and economy chemotherapy generics with volume-scale and site-of-care accreditation as primary differentiation drivers. Cost compression in the biosimilar monoclonal antibody tier is intensifying due to rituximab reference product substitution, while academic medical centers show least price sensitivity given captive reimbursement pathways. Community oncology practices face greatest pricing pressure from pharmacy benefit management formulary positioning on oral targeted agents.
Supply Chain Analysis
Direct-to-academic medical center channels handle autologous cell therapy distribution, bypassing traditional wholesale networks through patient-specific manufacturing partnerships. Manufacturing gravity centers on the United States, Germany, and China where NCI-designated cancer centers, Heidelberg-Munich academic hospital clusters, and Shanghai-Beijing biotech corridors anchor production. Raw material dependencies include lentiviral vectors, patient-derived apheresis collections, and cryopreservation media with single-source vulnerability concentrated among limited viral vector suppliers. Distribution runs through cold-chain logistics networks with site-of-care accreditation requirements fragmenting downstream access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The malignant lymphoma market compounds steadily through immunotherapy platform maturation, with FDA breakthrough therapy designation and EMA PRIME scheme acceleration sustaining novel therapy velocity against background pricing scrutiny.
For Market Incumbents: To counter biosimilar erosion in CD20-targeted protocols, Bristol-Myers Squibb and Roche-class developers should deepen backward integration into viral vector manufacturing and secure site-of-care accreditation networks across NCI-designated cancer centers. Channel control through diagnostic-therapeutic pairing remains the priority lever for preserving margin in lymphoma care. For New Entrants and Emerging Players: Begin with allogeneic off-the-shelf platform development targeting the bispecific T-cell engager segment where outpatient administration protocols are displacing salvage chemotherapy in relapsed diffuse large B-cell lymphoma. Community oncology practice accreditation offers the most penetrable go-to-market angle against academic medical center concentration. For Investors and Strategic Acquirers: Consolidation pressure builds where CAR-T manufacturing bottlenecks favor firms with captive lentiviral supply over contract-dependent mid-cap developers. Long-term viability hinges on regulatory affairs infrastructure depth and manufacturing self-sufficiency across the 5-10 year window. Watch for CMS coverage determination finalization for inpatient cellular therapy administration as the inflection signal for provider adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Viral Vector Manufacturing | Backward integration into lentiviral production secures supply certainty for autologous CAR-T programs against contract manufacturing bottlenecks. |
| Site-of-Care Accreditation Network | Community oncology practice certification for bispecific antibody administration captures patients ineligible for academic medical center referral. |
| Parallel Regulatory Filing Strategy | FDA breakthrough therapy designation paired with EMA PRIME scheme eligibility compresses commercialization timelines for novel immunotherapy platforms. |
| Real-World Evidence Infrastructure | HIPAA-compliant data collection networks enable post-market differentiation for therapies demonstrating durable response in community settings. |
| Allogeneic Platform Development | Universal donor cell therapies promise manufacturing scale economies that patient-specific autologous processes cannot achieve. |
Study Parameters
Direct dialogue with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers grounded the qualitative assessment, cross-referenced against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS coverage determination documents. Secondary validation drew from SEC 10-K disclosures, formulary databases, and academic medical center procurement records. Bottom-up patient-flow modeling and top-down revenue triangulation converged on segment-level estimates.
Market size and growth trajectory outputs emerged from integrated epidemiological, pricing, and penetration assumptions across the projection horizon, with segmentation modeling across treatment modality, lymphoma subtype, line of therapy, administration route, and regional regulatory cluster. CAGRs derived from therapy-specific adoption curves, patent expiry impacts, and biosimilar substitution rates. Forecast inputs incorporated clinical trial pipeline progression, manufacturing capacity expansion timelines, and payer coverage evolution.
Several conditions sit outside the modeled scope, including unforeseen regulatory withdrawals, manufacturing facility contamination events, and abrupt shifts in congressional pricing oversight intensity. Forecasts reflect documented assumptions about immunotherapy platform maturation and reimbursement pathway stabilization. Periodic stress-testing of base assumptions is recommended against emerging real-world evidence on bispecific antibody durability and allogeneic platform safety profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Burkitt Lymphoma Treatment Market
Hematology
Apheresis Market
Hematology
Anemia Drugs Market
Hematology
Thalassemia Treatment Market
Hematology
Polycythemia Vera Treatment Market
Hematology
Bleeding Disorders Therapeutics Market
Hematology
Haematocrit Centrifuge Market
Hematology
Sickle-Cell Anemia Therapeutics Market
Hematology
Hemoglobinopathies Treatment Market
Hematology
Venous Blood Collection Market
Hematology
Sickle Cell Anemia Market
Hematology
At-Home Hematology Testing Market
Hematology
Acute Myeloid Leukemia Treatment Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Radiation-Induced Myelosuppression Treatment Market
Hematology
Global Hematologic Malignancies Treatment Market