
 Ecoa, Esource & Clinical Trials Market | 2026-2036
Ecoa, Esource & Clinical Trials Market Size, Share, and Industry Trends Forecast 2026-2036
Ecoa, Esource & Clinical Trials Market Analytics
Shift from sponsor-built systems to vendor-managed platforms is consolidating procurement patterns across large pharmaceutical sponsors. IQVIA leverages its integrated data science backbone to anchor full-service trial execution for top-20 drug developers. Medidata Solutions competes through cloud-native architecture that extends across protocol design, data capture, and regulatory submission workflows. Signant Health specializes in patient-reported outcomes technology, occupying a differentiated position in decentralized trial instrumentation.
Electronic clinical outcome assessment, electronic source documentation, and digitally orchestrated trials collectively describe technology-mediated capture of patient data, trial metrics, and safety signals through validated software platforms operating under 21 CFR Part 11 audit-trail requirements. These systems replace paper case report forms and source worksheets with timestamped, role-permissioned digital records to accelerate database lock and reduce transcription error. Patient-Reported Outcomes leads product-type revenue as oncology and CNS sponsors prioritize symptom-tracking endpoints for regulatory filings. Cloud Computing anchors technology deployment, though Wearable Devices represents the fastest-expanding segment as continuous glucose monitors, accelerometers, and digital biomarkers penetrate cardiovascular and metabolic protocols.
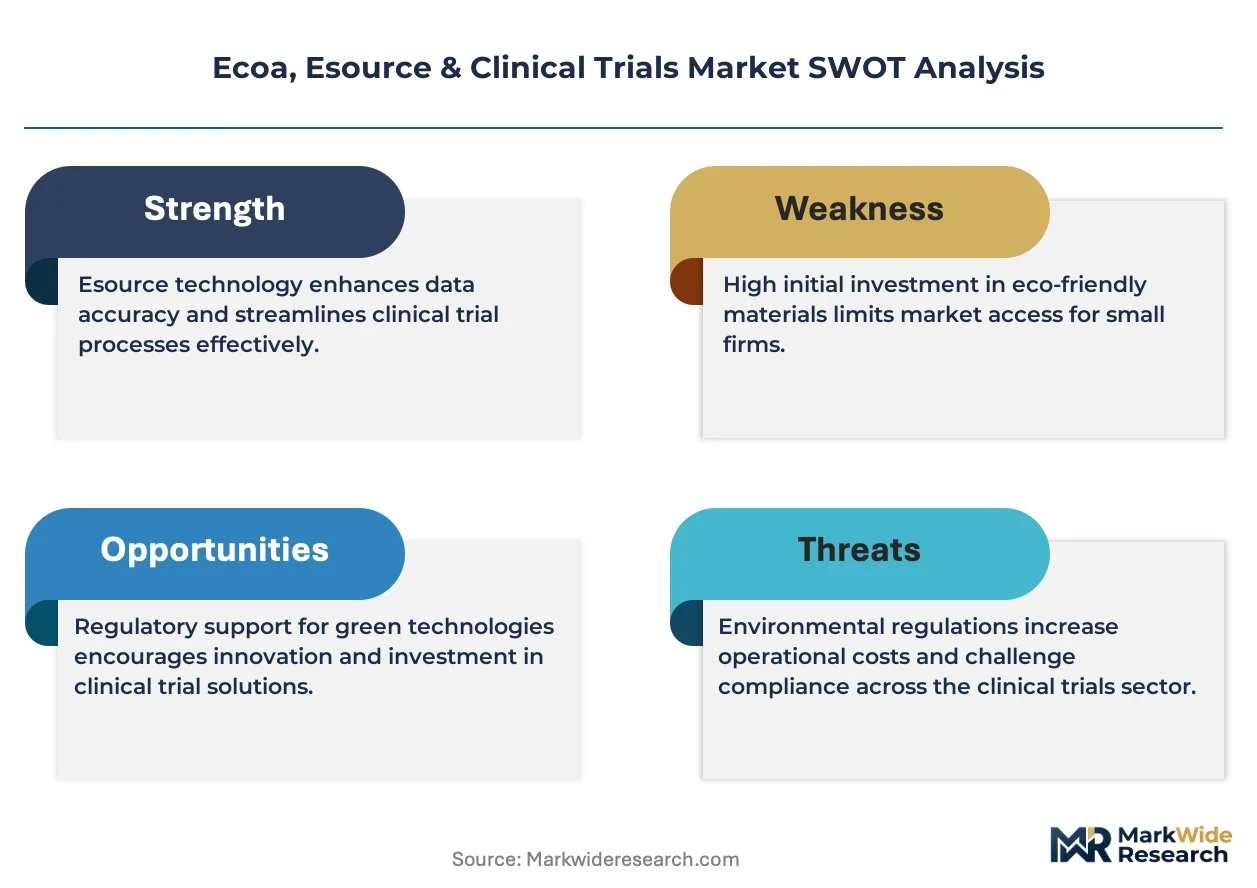
FDA enforces 21 CFR Part 11 for electronic records and signatures, while EMA's reflection paper on expectations for eSource data governs European submission acceptability. Japan's PMDA has issued comparable guidance on electronic data integrity, creating a triad of regulatory benchmarks that vendors must satisfy for multi-regional trial access. Sponsors and contract research organizations should monitor divergence between FDA's risk-based monitoring framework and EMA's evolving data-traceability standards when selecting platform partners for international protocols.
Market Dynamics
Pharmaceutical sponsors are consolidating procurement around vendor-managed eCOA platforms rather than sponsor-built systems, compressing vendor selection cycles and elevating validation requirements under 21 CFR Part 11 and EMA computerized systems guidance.
Growth Catalysts
- FDA 21 CFR Part 11 enforcement:Regulatory clarity on electronic records and signatures accelerates site-level deployment of digital trial infrastructure across Phase II-IV oncology studies.
- Patient-reported outcomes prioritization:CNS and oncology sponsors demand symptom-tracking endpoints for regulatory filings, elevating ePRO module adoption within integrated platforms.
- Wearable device penetration:Continuous glucose monitors and accelerometers penetrate cardiovascular and metabolic protocols, expanding data capture beyond clinic visits.
Market Restraints
- Validation cost concentration:Multi-regional trial access requires simultaneous FDA, EMA, and PMDA compliance, inflating platform certification expenditures for mid-tier vendors.
- Site infrastructure heterogeneity:Rural and community oncology centers lack broadband reliability and device standardization, creating deployment friction for decentralized protocols.
- Transcription error substitution risk:Direct data entry from wearables threatens traditional eCOA capture models, compressing revenue for questionnaire-focused platform modules.
Strategic Opportunities
- Japan PMDA alignment:Comparable electronic data integrity guidance to FDA and EMA creates a regulatory triad for multi-regional trial access, opening vendor expansion paths.
- Cloud-native architecture convergence:Integration of protocol design, data capture, and regulatory submission workflows on single platforms displaces fragmented point solutions.
- Decentralized trial instrumentation:Home-based eSource data collection via patient-owned devices addresses site capacity constraints in Germany and United States metropolitan clusters.
Industry Challenges
- 21 CFR Part 11 audit trail engineering:Timestamped, role-permissioned record systems require specialized software validation talent scarce in contract research organizations.
- Legacy EDC integration complexity:Electronic data capture systems from prior trial eras resist API connectivity with modern eCOA platforms, forcing costly middleware development.
- Database lock acceleration pressure:Compressed regulatory submission timelines demand real-time data quality monitoring that outpaces existing site monitoring workforce capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ecoa, Esource & Clinical Trials Market |
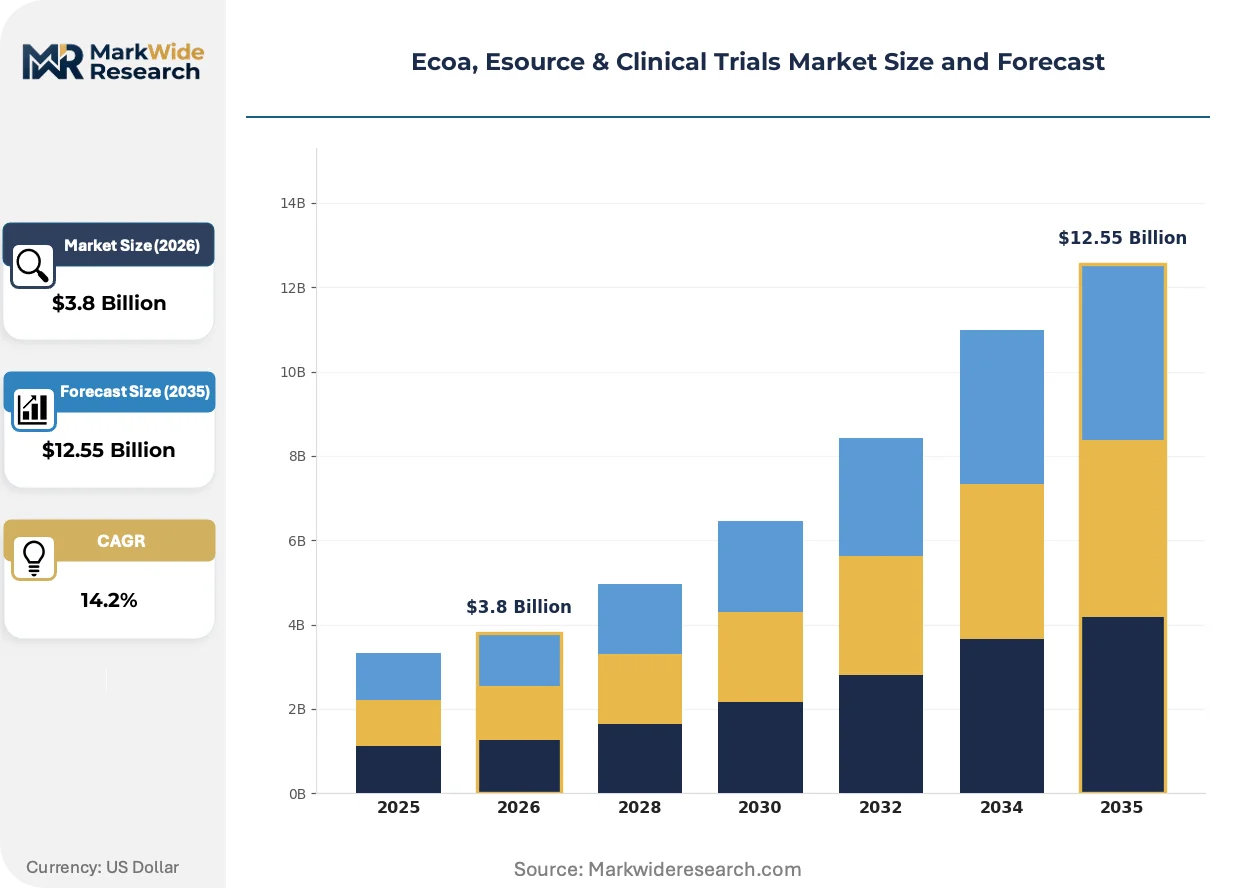
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patient-Reported Outcomes, Remote Monitoring Devices, Data Collection Software, Clinical Trial Management Systems End User: Pharmaceutical Companies, Research Organizations, Hospitals, Academic Institutions Technology: Mobile Applications, Cloud Computing, Wearable Devices, Artificial Intelligence Functionality: Data Analytics, Compliance Tracking, Patient Engagement, Risk Mitigation |
| Companies Covered | Medidata Solutions, Signant Health, IQVIA, Clario, ICON Plc, Medable, Parexel International Corporation, ArisGlobal, OpenClinica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ecoa, Esource & Clinical Trials Market Evolving Landscape
Electronic clinical trial infrastructure is fragmenting into interoperable microservices, with sponsors assembling best-of-breed components rather than accepting monolithic platform constraints. This architectural shift compresses vendor switching costs and elevates API standardization as a competitive battleground.
Platform architecture is modularizing around discrete eCOA, eSource, and eConsent modules that sponsors license separately. Large pharmaceutical developers now demand API-first connectivity between patient-reported outcome capture and safety signal detection systems. This modularity is compressing procurement cycles as sponsors swap underperforming modules without platform-wide replacement.
EMA's reflection paper on expectations for eSource data is reshaping European submission acceptability standards for timestamped digital records. The guidance elevates data traceability requirements above FDA's risk-based monitoring framework, forcing multi-regional sponsors to maintain dual validation protocols. Oncology and CNS trial sponsors face the steepest compliance adjustments as symptom-tracking endpoints dominate their regulatory filings.
Site-level procurement authority is migrating toward centralized sponsor technology governance, with procurement teams mandating pre-approved vendor lists across therapeutic areas. Contract research organizations lose negotiating leverage as sponsors dictate platform selection to ensure data harmonization across portfolios. This concentration is most visible in United States and Germany, where top-20 drug developers enforce standardized eCOA instrumentation across competing CRO partnerships.
Ecoa, Esource & Clinical Trials Market Segmentation
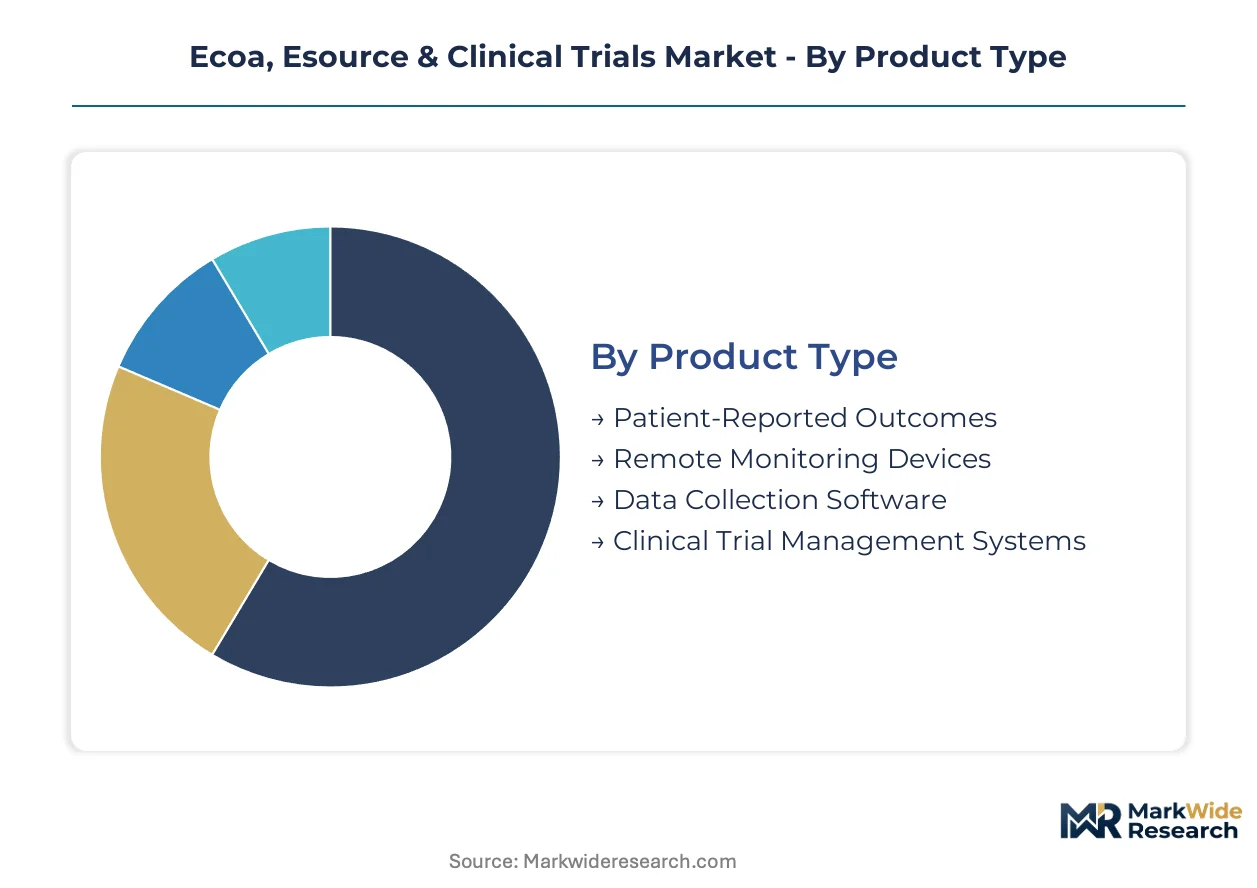
Segmentation in the eCOA, eSource and clinical trials market reveals how procurement patterns concentrate around validated platforms versus modular components. Pharmaceutical sponsors select technology configurations based on therapeutic area complexity, regulatory submission geography, and site infrastructure maturity.
Product Type:
Customization versus standardization tension dominates platform selection, with sponsors balancing configurable questionnaire libraries against pre-validated instrument packages.
- Patient-Reported Outcomes:Symptom-tracking questionnaires capture oncology and CNS endpoints directly from trial participants. FDA 21 CFR Part 11 validation requirements elevate procurement toward pre-certified ePRO modules in United States Phase II-IV studies.
- Remote Monitoring Devices:Home-based biometric sensors transmit continuous vital signs and activity metrics outside clinic settings. Cardiovascular and metabolic protocols in Germany and Japan drive demand for glucose monitors and accelerometers with PMDA-aligned data integrity standards.
- Data Collection Software:Electronic source documentation platforms replace paper worksheets with timestamped digital records.
- Clinical Trial Management Systems:Integrated protocol design and regulatory submission workflows consolidate fragmented point solutions.
Most installed capacity flows through Patient-Reported Outcomes modules. Expansion is steepest in Remote Monitoring Devices.
End User:
Cost tier stratification separates enterprise-grade deployments from constrained academic budgets, reshaping vendor pricing architectures.
- Pharmaceutical Companies:Top-20 drug developers mandate standardized eCOA instrumentation across competing CRO partnerships. Centralized technology governance in United States and Germany compresses vendor selection cycles while elevating validation requirements.
- Research Organizations:Contract research organizations lose negotiating leverage as sponsors dictate platform selection to ensure data harmonization across portfolios. Mid-tier CROs face certification expenditure inflation for simultaneous FDA, EMA, and PMDA compliance.
- Hospitals:Academic medical centers anchor site-level deployment for oncology and CNS protocols with established digital infrastructure.
- Academic Institutions:University-affiliated research programs prioritize open-source interoperability over proprietary platform depth.
Pharmaceutical Companies concentrate procurement authority. Academic Institutions are gaining share fastest as decentralized trial models democratize access.
Technology:
Application maturity varies sharply, with cloud-native architectures displacing on-premise legacy systems while AI remains experimental.
- Mobile Applications:Patient-facing smartphone interfaces deliver ePRO instruments and medication adherence prompts. Deployment friction persists at rural United States oncology centers lacking device standardization and broadband reliability.
- Cloud Computing:Scalable infrastructure anchors multi-regional trial data hosting with automated backup and disaster recovery. EMA's data traceability requirements exceed FDA's risk-based monitoring framework, forcing dual validation protocols for European submission acceptability.
- Wearable Devices:Continuous biosensors generate real-world evidence streams beyond scheduled clinic visits.
- Artificial Intelligence:Machine learning models flag safety signals and predict enrollment bottlenecks from integrated trial datasets.
Cloud Computing carries the dominant installed base. Wearable Devices show the steepest expansion trajectory as digital biomarkers penetrate cardiovascular protocols.
Functionality:
Customer type differentiation separates enterprise platforms with full-stack capabilities from point solutions addressing single workflow stages.
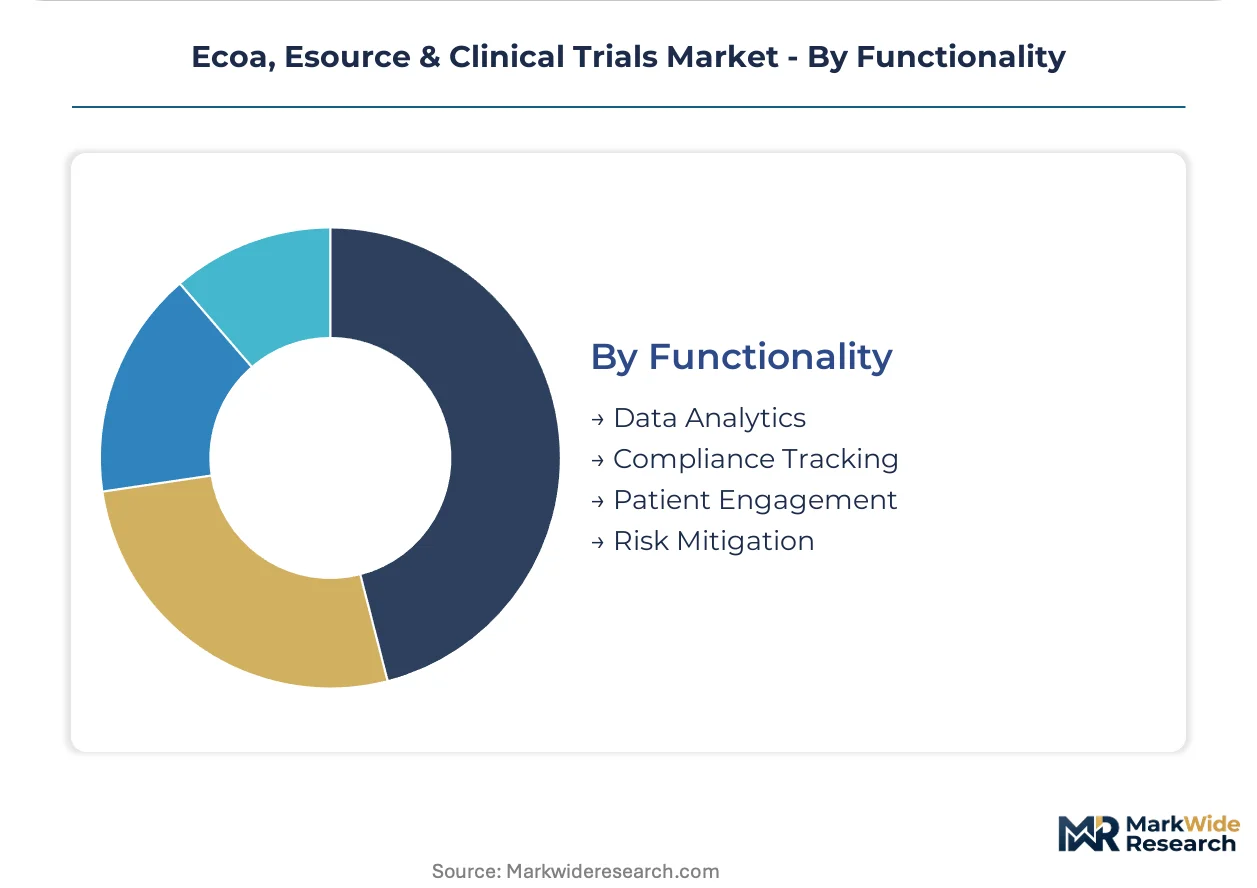
- Data Analytics:Real-time quality monitoring and predictive enrollment modeling compress database lock timelines. Compressed regulatory submission timelines in United States and Japan outpace existing site monitoring workforce capacity.
- Compliance Tracking:Automated audit trails and role-permissioned access satisfy 21 CFR Part 11 and EMA computerized systems guidance. Specialized software validation talent scarcity constrains mid-tier vendor engineering capacity.
- Patient Engagement:Gamified adherence prompts and telemedicine integration improve retention in decentralized protocols.
- Risk Mitigation:Centralized statistical monitoring algorithms trigger targeted site visits based on data anomaly detection.
Data Analytics commands the largest functional spend. Patient Engagement is climbing the fastest as sponsors address retention gaps in home-based trials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting eCOA platform development toward jurisdictions with harmonized electronic data integrity standards, as vendors seek to minimize multi-jurisdictional validation burdens while maintaining access to high-value pharmaceutical sponsor contracts.
United States
FDA 21 CFR Part 11 enforcement drives Phase II-IV oncology sponsors toward pre-certified ePRO modules. The agency's risk-based monitoring framework accelerates site-level digital deployment. Greater Boston and San Francisco Bay Area biotech clusters concentrate vendor R&D partnerships for decentralized trial instrumentation.
Germany
EMA computerized systems guidance elevates data traceability requirements above FDA benchmarks, forcing dual validation protocols for European submission acceptability. The country's federal data protection framework adds compliance layering for cross-border trial hosting. Munich and Heidelberg anchor pharmaceutical sponsor technology governance centers mandating standardized eCOA instrumentation.
Japan
PMDA electronic data integrity guidance creates regulatory parity with FDA and EMA standards, opening multi-regional trial access for compliant vendors. Domestic sponsors prioritize wearable device integration for cardiovascular and metabolic protocols. Tokyo and Osaka metropolitan clusters concentrate site infrastructure investment for home-based eSource collection.
United Kingdom
MHRA post-Brexit alignment with EMA eSource expectations maintains European submission pathways for UK-based trials. NHS digital transformation programs accelerate site-level broadband and device standardization. London and Cambridge biotech corridors concentrate contract research organization partnerships for international protocol execution.
India
CDSCO's evolving stance on electronic records creates compliance uncertainty for sponsor-built systems, favoring vendor-managed platforms with established FDA-EMA validation. Cost-competitive clinical trial execution attracts decentralized protocol outsourcing. Hyderabad and Bangalore technology parks concentrate data analytics workforce for real-time quality monitoring services.
Ecoa, Esource & Clinical Trials Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular microservices and API-first connectivity. The vendor base stratifies between full-service platform consolidators and point-solution specialists. Three archetypes dominate: integrated data science backbones, cloud-native workflow orchestrators, and patient-reported outcome instrumentation specialists. Competitive moves concentrate on strategic partnerships with top-20 pharmaceutical sponsors and vertical integration into site monitoring workforce capacity.
Within the integrated platform tier, IQVIA, Medidata Solutions, and Signant Health exemplify contrasting strategic positions. IQVIA anchors full-service trial execution through its data science infrastructure. Medidata Solutions occupies the cloud-native architecture vector extending across protocol-to-submission workflows. Signant Health represents the differentiated patient-reported outcomes specialization for decentralized trial instrumentation.
| Leading Market Players |
|---|
| Medidata Solutions |
| Signant Health |
| IQVIA |
| Clario |
| ICON Plc |
| Medable |
| Parexel International Corporation |
| ArisGlobal |
| OpenClinica |
| Others |
Value Network & Pricing Analysis
Software validation engineers concentrated in the Greater Boston and San Francisco Bay Area biotech clusters command compensation premiums that compress pricing-tier spreads between premium and standard eCOA platform tiers. Labor-cost differentials between these talent hubs and emerging delivery centers in Hyderabad and Bangalore create arbitrage opportunities for mid-tier vendors seeking to undercut incumbent pricing.
Pricing Analysis
Direct-to-pharma-sponsor subscription tiers dominate, with pricing stratifying across premium, standard, and economy levels based on 21 CFR Part 11 certification depth and multi-regional validation coverage. Price differentiation rests on FDA-EMA-PMDA simultaneous compliance versus single-jurisdiction certification and after-sales implementation support intensity. Pricing pressure stems from cloud-native entrants offering modular microservices that bypass full-platform licensing. Academic institutions and mid-tier contract research organizations exhibit highest price sensitivity, while top-20 pharmaceutical developers prioritize validation assurance over cost minimization.
Supply Chain Analysis
FDA 21 CFR Part 11 and EMA computerized systems guidance certification gating concentrates qualified platform engineering in the United States, Germany, and Japan. Component dependencies include AWS and Azure cloud infrastructure, biometric sensor hardware from East Asian manufacturers, and specialized audit-trail software modules. Single-source vulnerability runs through concentrated hyperscaler cloud regions for multi-regional trial hosting. Distribution runs through direct enterprise sales teams supplemented by contract research organization channel partnerships for site-level deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 21 CFR Part 11 enforcement acceleration compounds platform demand as sponsors abandon sponsor-built systems for vendor-managed alternatives. This regulatory milestone elevates validation-certified vendors above uncertified competitors.
For Market Incumbents: Deepen backward integration into specialized software validation talent pools in Greater Boston and the San Francisco Bay Area to defend against cloud-native entrants modularizing around API-first connectivity. Expand certification maintenance infrastructure for simultaneous FDA, EMA, and PMDA compliance to exploit mid-tier vendor dropout from validation cost inflation.
For New Entrants and Emerging Players: Launch via modular microservices and API-first connectivity targeting academic institutions and decentralized trial instrumentation in Japan's metropolitan clusters. White-space concentration sits in wearable device-integrated eSource platforms for cardiovascular protocols where PMDA guidance creates regulatory parity with established markets.
For Investors and Strategic Acquirers: Pharmaceutical technology consolidators represent the most active acquirer category in this space, seeking patient-reported outcomes specialization and cloud-native architecture assets. Long-term viability favors vendors with established 21 CFR Part 11 validation moats and multi-regional regulatory triad coverage. Watch for FDA enforcement discretion shifts on risk-based monitoring frameworks as inflection indicators for platform consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | Simultaneous FDA-EMA-PMDA compliance unlocks multi-regional trial access for oncology sponsors. |
| Cloud-Native Architecture Migration | API-first connectivity displaces fragmented point solutions across protocol-to-submission workflows. |
| Patient-Reported Outcomes Specialization | Symptom-tracking endpoint expertise captures CNS and oncology regulatory filing demand. |
| Wearable Device Integration | Continuous glucose monitors and accelerometers expand data capture beyond clinic visits. |
| Decentralized Trial Instrumentation | Home-based eSource collection addresses site capacity constraints in Germany and United States clusters. |
Research Methodology
Bottom-up pharmaceutical sponsor deployment modeling reconciled against top-down eCOA platform vendor capacity tracking forms the analytical core. Primary interviews with drug development executives, regulatory affairs leads, clinical operations directors, and site-level technology coordinators combined with secondary validation against FDA 21 CFR Part 11 guidance documents, EMA reflection papers on eSource expectations, PMDA electronic data integrity circulars, and ClinicalTrials.gov protocol registries. Triangulation across sponsor-reported procurement timelines and vendor-reported implementation cycles anchored volume estimates.
Historical trendline analysis of Phase II-IV digital trial adoption rates informed projection frameworks across the modeling period. Segmentation dimensions modeled include product type, end user archetype, deployment technology, and functional capability, with therapeutic area complexity and regional regulatory cluster as cross-cutting variables. CAGRs derived from sponsor budget allocation trajectories for electronic clinical outcome assessment platforms and wearable device penetration curves in cardiovascular protocols.
Several conditions sit outside the modeled scope, including potential divergence between FDA risk-based monitoring frameworks and EMA data-traceability standards, and unanticipated site infrastructure investment in rural oncology centers. Forecasts reflect assumptions regarding sustained regulatory enforcement clarity and cloud infrastructure reliability. A model refresh is warranted upon material change in FDA 21 CFR Part 11 audit trail interpretation or PMDA guidance alignment with international standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Global in Vivo Toxicology Market
Clinical Research
Edema Clinical Trials Market
Clinical Research
Global Clinical Trial Supply Market
Clinical Research
Real World Evidence Linkage Services Market
Clinical Research
Clinical Trials Site Management Organizations Market
Clinical Research
India CRO Market
Clinical Research
Pharmacovigilance Outsourcing Market
Clinical Research
Real-World Evidence Analytics Market
Clinical Research
Non-Alcoholic Steatohepatitis Clinical Trials Market
Clinical Research
Global Virtual Clinical Trials Market
Clinical Research
Early Phase Clinical Trial Outsourcing Market
Clinical Research
Clinical Trial Management Services Market
Clinical Research
Clinical Trial Biorepository and Archiving Solutions Market
Clinical Research
Biomarker Discovery Outsourcing Services Market
Clinical Research
Healthcare Europe Clinical Data Analytics Market
Clinical Research
North America Clinical Trials Market