
 India CRO Market | 2026-2036
India CRO Market Size, Share, and Industry Trends Forecast 2026-2036
India CRO Market Outlook
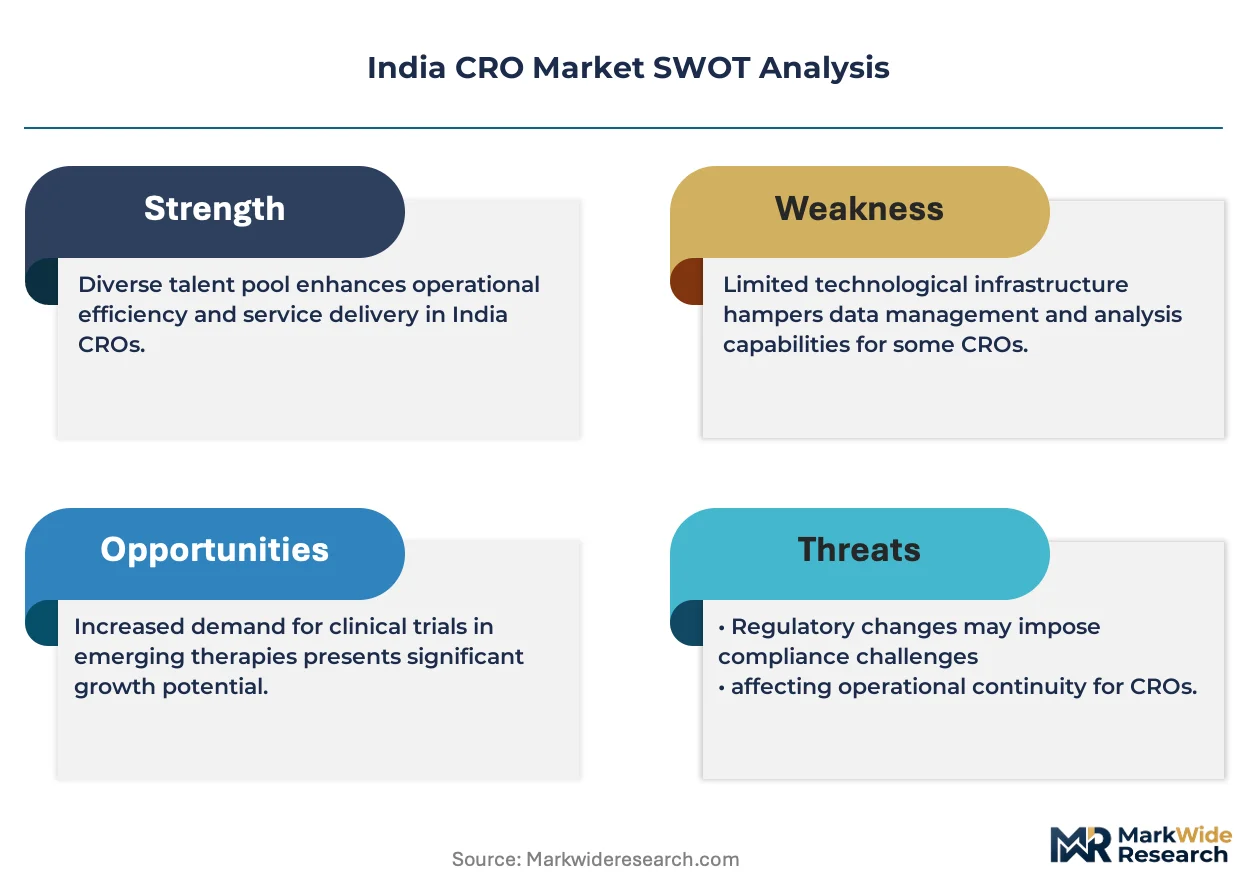
Good Clinical Practice certification from the Indian Council of Medical Research is redrawing vendor eligibility for multinational sponsor trials. Syngene International leverages its integrated discovery-to-commercialization campus in Bangalore to anchor large-molecule bioanalytical work for global pharma clients. Jubilant Biosys sustains chemistry-heavy early-phase operations through captive medicinal chemistry teams and specialized DMPK infrastructure. Eurofins Advinus competes on regulatory toxicology breadth, operating GLP-compliant facilities that support IND-enabling study packages for US and European submissions.
A Contract Research Organization delivers outsourced pharmaceutical development services spanning preclinical discovery, clinical trial execution, regulatory documentation, and post-market surveillance under formal service agreements with sponsor firms. Clinical trial services dominate value capture within the India CRO landscape, driven by Phase II-III oncology and diabetes studies where patient recruitment costs run below Western benchmarks by substantial margins. Pharmacovigilance segments exhibit accelerating structural growth as EMA and FDA mandate periodic safety update reporting for generic drug portfolios manufactured in Indian facilities. Full-service delivery models concentrate margin pools through long-term strategic partnerships, while fee-for-service arrangements dominate transactional early-phase bioanalytical testing.
CDSCO's New Drugs and Clinical Trials Rules compress approval timelines for bioequivalence studies, reshaping how CROs structure protocol submission workflows for domestic generic sponsors. The PLI scheme for active pharmaceutical ingredients indirectly stimulates CRO demand by expanding local formulation development requiring companion clinical validation. India's adoption of ICH-GCP E6 R2 guidelines aligns site qualification standards with FDA and EMA inspectorate expectations, reducing duplicate audit burdens for export-oriented studies. Stakeholders must monitor CDSCO's impending digital platform integration for trial protocol submissions, as this will redistribute competitive advantage toward CROs with validated electronic document management infrastructure.
Market Dynamics
CDSCO's digital submission mandates and ICH-GCP E6 R2 alignment are compressing study startup timelines while redrawing vendor eligibility criteria for multinational sponsor trials across India's clinical research infrastructure.
Growth Catalysts
- Regulatory Streamlining:CDSCO's New Drugs and Clinical Trials Rules compress bioequivalence study approval timelines, accelerating protocol submission workflows for domestic generic sponsors.
- Oncology Pipeline Expansion:Biopharmaceutical sponsors now expand outsourced clinical development across oncology pipelines, with patient recruitment costs running substantially below Western benchmarks.
- PLI Scheme Stimulus:The Production Linked Incentive scheme for active pharmaceutical ingredients indirectly stimulates CRO demand by expanding local formulation development requiring companion clinical validation.
Market Restraints
- Investigator Site Concentration:Demand concentrates heavily in Maharashtra and Telangana, creating geographic dependency risk for sponsors requiring distributed trial networks.
- Qualification Cost Burden:Good Clinical Practice certification from the Indian Council of Medical Research imposes upfront compliance costs that filter out smaller regional operators.
- Generic Portfolio Pressure:Pharmacovigilance mandates from EMA and FDA for generic drug portfolios manufactured in Indian facilities strain safety reporting infrastructure without proportional revenue uplift.
Strategic Opportunities
- Digital Platform Integration:CDSCO's impending electronic protocol submission platform will redistribute competitive advantage toward CROs with validated electronic document management infrastructure.
- Metabolic Disorder Expansion:Biopharmaceutical sponsors are expanding outsourced clinical development into metabolic disorder pipelines, opening new therapeutic verticals beyond oncology dominance.
- Full-Service Partnership Models:Long-term strategic partnerships concentrate margin pools and create defensive revenue streams distinct from transactional fee-for-service arrangements.
Industry Challenges
- GLP Certification Timelines:Regulatory toxicology breadth requiring GLP-compliant facilities for IND-enabling study packages demands extended facility qualification periods.
- Electronic System Integration:CDSCO's digital mandates force reconfiguration of legacy paper-based protocol management systems.
- Specialized Talent Scarcity:Large-molecule bioanalytical work requires captive medicinal chemistry teams and specialized DMPK infrastructure that outpaces available trained personnel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India CRO Market |
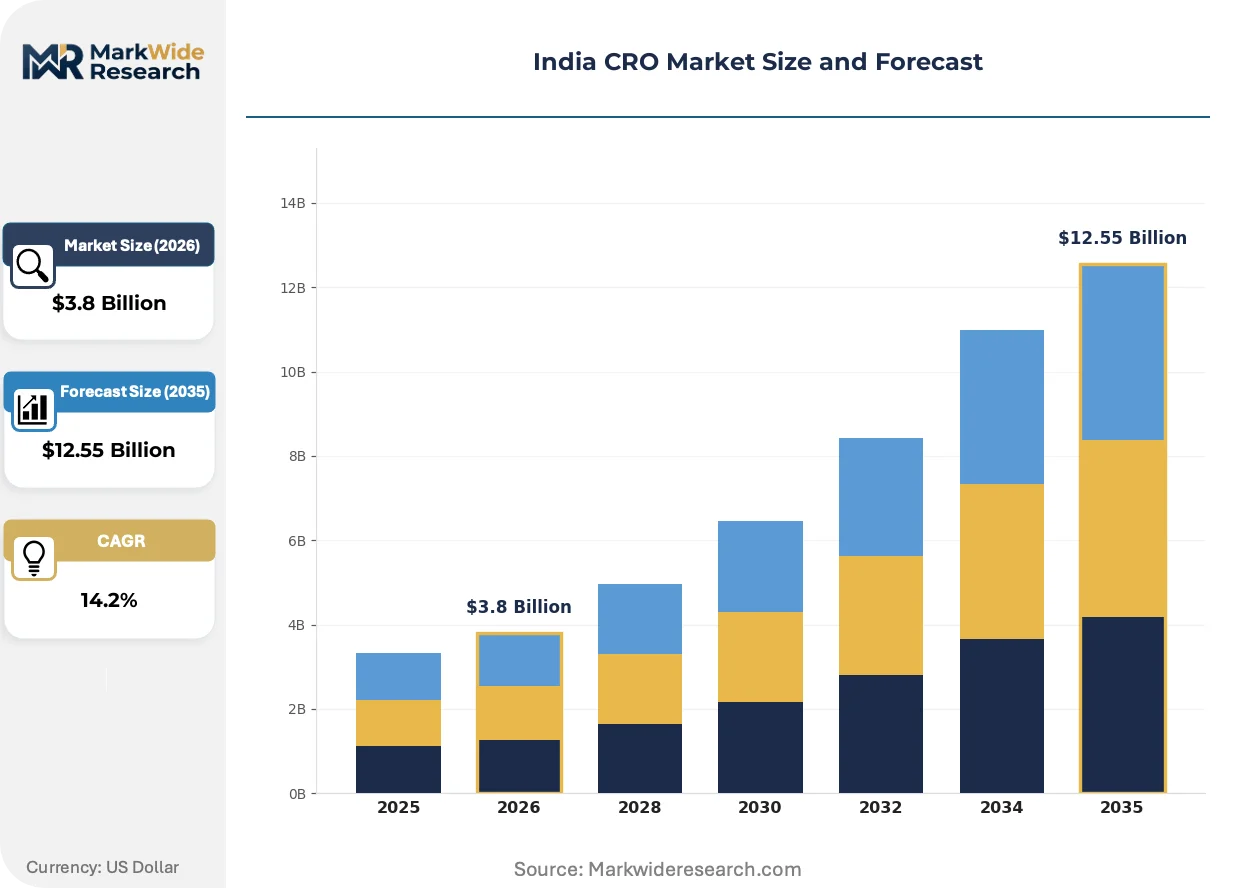
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Clinical Trials, Regulatory Affairs, Data Management, Pharmacovigilance End User: Pharmaceutical Companies, Biotechnology Firms, Medical Device Manufacturers, Academic Institutions Technology: Electronic Data Capture, Randomization Software, Clinical Trial Management Systems, Biostatistics Delivery Model: On-Demand Services, Full-Service Solutions, Fee-For-Service, Dedicated Team |
| Companies Covered | Syngene International Ltd, Jubilant Biosys, Eurofins Advinus, Veeda Clinical Research, IQVIA, TheraIndx Lifesciences, Dabur Research, Cliantha Research, Axis Clinicals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India CRO Market Strategic Shifts
Technology convergence between electronic document management and regulatory submission platforms is actively compressing study startup timelines while redrawing competitive positioning across India's contract research infrastructure.
Electronic document management systems with integrated regulatory submission capabilities are displacing fragmented paper-based protocol workflows across mid-size and large CRO operations. Multinational pharmaceutical sponsors now mandate these platforms as a vendor qualification prerequisite for Phase II-III study awards. The structural consequence is a widening capability gap between digitized full-service providers and regional operators dependent on manual documentation processes.
CDSCO's alignment with ICH-GCP E6 R2 guidelines is compressing site qualification standards toward FDA and EMA inspectorate expectations. This regulatory harmonization eliminates duplicate audit burdens for export-oriented studies but imposes new training and documentation infrastructure requirements on investigator sites. Hyderabad's Genome Valley and Mumbai's pharmaceutical corridors are responding fastest due to concentrated prior exposure to multinational sponsor protocols.
Sponsor procurement patterns now favor integrated discovery-to-commercialization service agreements over transactional bioanalytical testing contracts. Large pharmaceutical clients are consolidating vendor rosters and demanding end-to-end accountability spanning preclinical through post-market surveillance. This behavioral shift is most visible among US and European sponsors with established India-based clinical operations, where relationship depth now outweighs unit cost in vendor selection criteria.
India CRO Market Segmentation
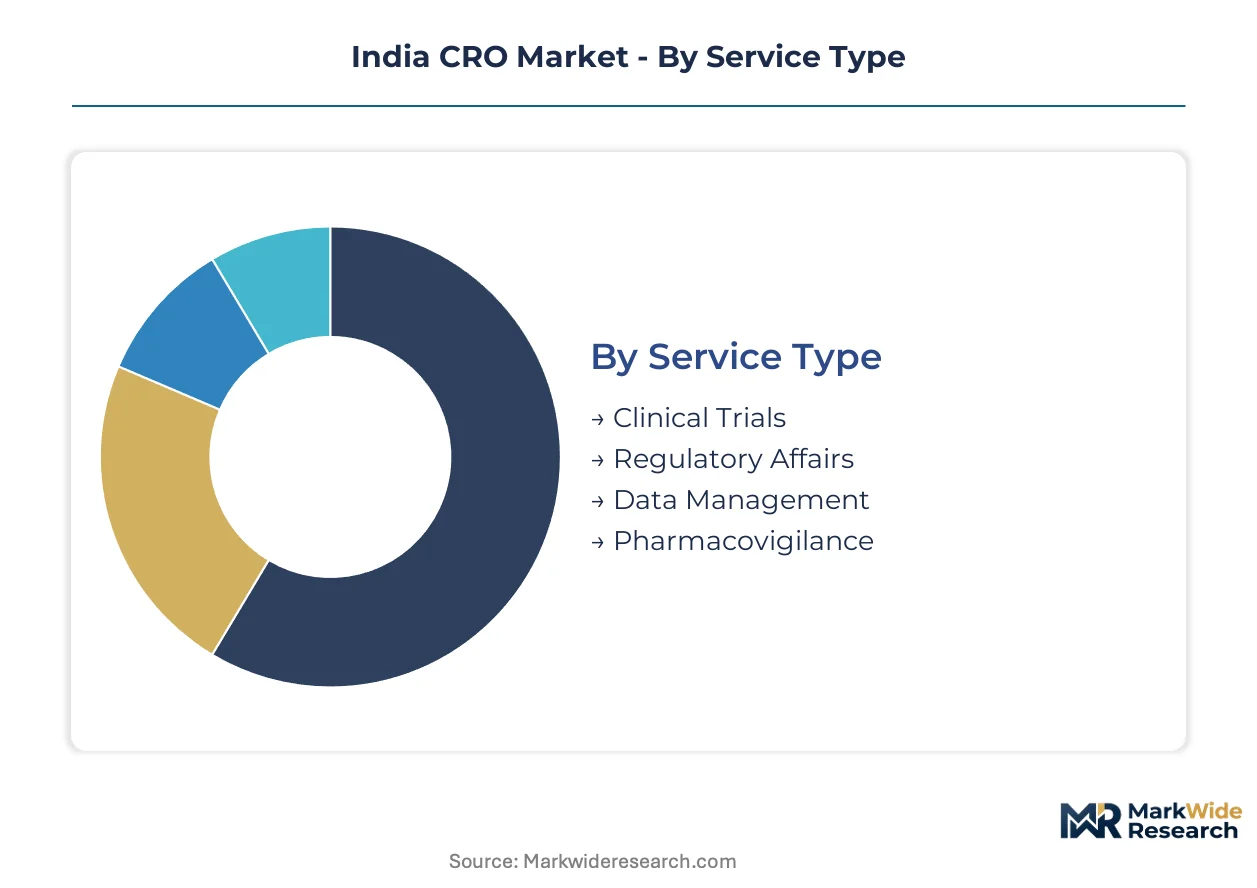
Segmentation of the India CRO Market reveals how service delivery, client procurement patterns, and technology adoption intersect to determine competitive positioning. Understanding these divisions exposes where margin pools concentrate and which capability investments yield sustainable differentiation.
Service Type:
Channel-mix dynamics show clinical trial execution flowing through full-service partnerships while regulatory and safety services fragment across transactional arrangements.
- Clinical Trials:Phase II-III oncology and metabolic disorder studies dominate revenue capture, with Maharashtra and Telangana investigator sites handling the bulk of multinational sponsor volumes. Patient recruitment costs running below Western benchmarks sustain this segment's commercial centrality.
- Regulatory Affairs:CDSCO submission preparation and IND-enabling documentation packages constitute the core offering, with demand accelerating from domestic generic manufacturers seeking export market access. Digital submission mandates are compressing turnaround timelines and favoring CROs with validated electronic systems.
- Data Management:Electronic Data Capture integration and statistical programming support clinical operations.
- Pharmacovigilance:EMA and FDA periodic safety update reporting mandates for Indian-manufactured generics are expanding service scope.
Clinical Trials dominates installed base. Pharmacovigilance is where expansion concentrates.
End User:
Customer-type stratification shows pharmaceutical sponsors consolidating vendor rosters while biotechnology and device clients pursue specialized niche partnerships.
- Pharmaceutical Companies:Multinational sponsors with established India operations drive full-service contract values, demanding end-to-end accountability from discovery through post-market surveillance. Relationship depth now outweighs unit cost in procurement decisions.
- Biotechnology Firms:Emerging biotech clients concentrate early-phase bioanalytical and DMPK work with CROs possessing captive medicinal chemistry capabilities. Bangalore's integrated discovery campuses capture disproportionate share.
- Medical Device Manufacturers:CDSCO medical device rules compliance and clinical evaluation report preparation form the service core.
- Academic Institutions:Investigator-initiated studies and government-funded research projects generate episodic demand.
Pharmaceutical Companies anchor revenue concentration. Biotechnology Firms are climbing the fastest.
Technology:
Technology maturity curves separate validated platform adopters from legacy-dependent operators facing qualification barriers.
- Electronic Data Capture:Cloud-based systems with real-time monitoring capabilities are now mandatory for Phase II-III study awards from US and European sponsors. CDSCO's impending digital platform integration will further entrench this requirement.
- Clinical Trial Management Systems:Integrated protocol workflow and site communication platforms compress study startup timelines. Hyderabad's Genome Valley and Mumbai's pharmaceutical corridors are responding fastest due to concentrated prior exposure.
- Randomization Software:IWRS and IRT systems support adaptive trial designs.
- Biostatistics:Specialized statistical programming for complex oncology endpoints commands premium pricing.
Electronic Data Capture dominates installed base. Clinical Trial Management Systems is where expansion concentrates.
Delivery Model:
Margin structure varies sharply between long-term strategic partnerships and transactional fee arrangements.
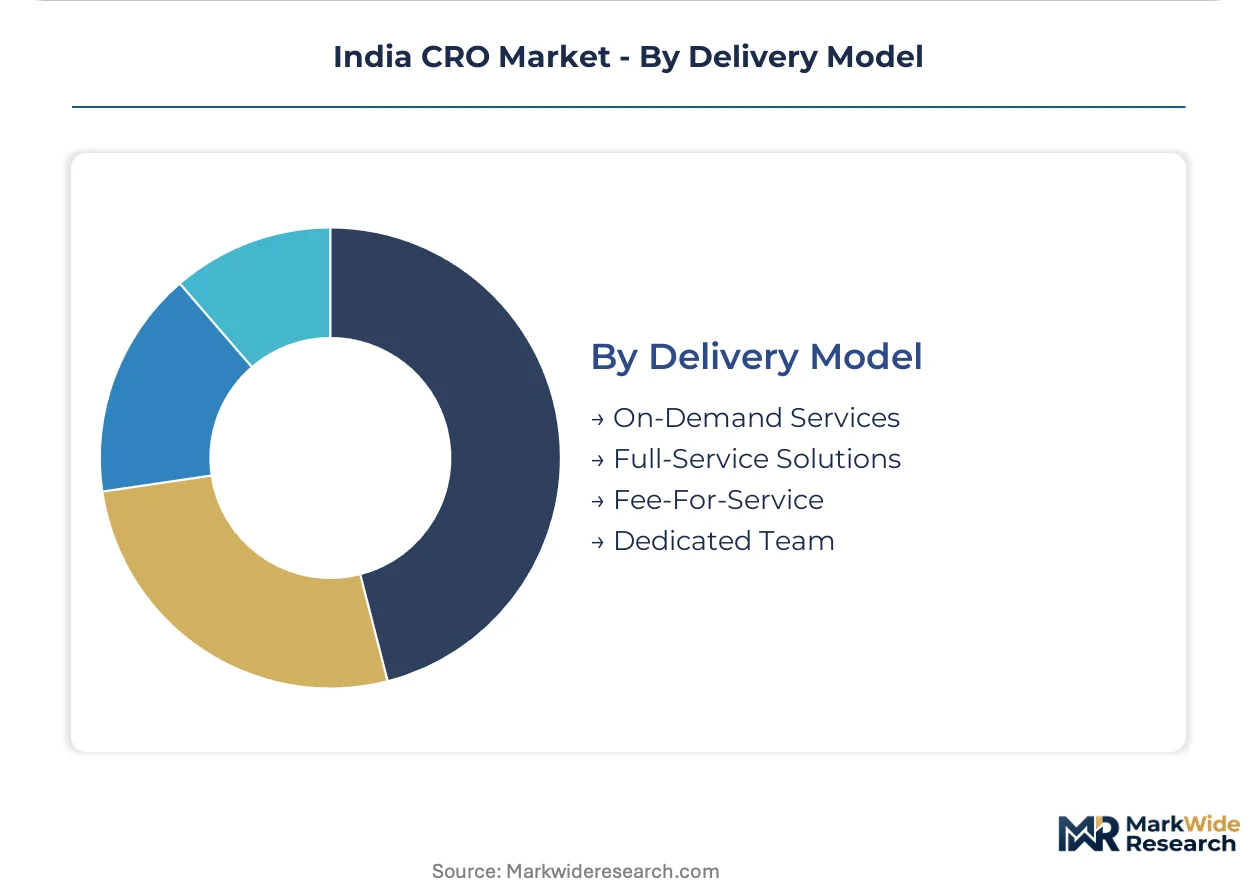
- Full-Service Solutions:Integrated discovery-to-commercialization agreements concentrate margin pools and create defensive revenue streams. Syngene International's Bangalore campus exemplifies this model's execution.
- Fee-For-Service:Transactional bioanalytical testing and early-phase chemistry work dominate this tier, with pricing pressure from regional competitors. Eurofins Advinus competes on regulatory toxicology breadth within this structure.
- On-Demand Services:Flexible capacity augmentation for sponsor surge requirements.
- Dedicated Team:Embedded personnel arrangements for large pharmaceutical clients with sustained India-based pipelines.
Fee-For-Service dominates installed base. Full-Service Solutions is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CDSCO's New Drugs and Clinical Trials Rules and the PLI scheme for active pharmaceutical ingredients are redirecting clinical trial investment toward states with established investigator networks and bioanalytical infrastructure.
Maharashtra
Mumbai's pharmaceutical corridors host concentrated Phase II-III oncology studies driven by multinational sponsor demand. CDSCO's streamlined approval mechanisms compress study startup timelines for domestic generic manufacturers seeking export market access. The state's investigator sites handle substantial volumes of diabetes and metabolic disorder trials where patient recruitment costs sustain competitive positioning.
Telangana
Hyderabad's Genome Valley anchors large-molecule bioanalytical work and regulatory toxicology operations for global pharma clients. The cluster's prior exposure to multinational sponsor protocols accelerates adoption of ICH-GCP E6 R2 guidelines. CDSCO's impending digital platform integration favors CROs in this corridor with validated electronic document management infrastructure.
Karnataka
Bangalore's integrated discovery-to-commercialization campuses capture emerging biotechnology firm demand for early-phase DMPK and medicinal chemistry services. The state's concentration of captive research infrastructure supports full-service partnership models that multinational sponsors now favor over transactional arrangements. Good Clinical Practice certification requirements from the Indian Council of Medical Research filter regional operator eligibility.
Gujarat
Ahmedabad-Vadodara pharmaceutical manufacturing clusters generate companion clinical validation demand from PLI scheme beneficiaries expanding local formulation development. CDSCO's compressed bioequivalence study approval timelines reshape how CROs structure protocol submission workflows for domestic generic sponsors. The region's formulation-focused industrial base creates specialized pharmacovigilance service requirements.
Andhra Pradesh
Visakhapatnam's emerging life sciences corridor attracts early-phase chemistry-heavy operations requiring extended facility qualification periods. The state's regulatory toxicology capacity supports IND-enabling study packages for US and European submissions. Investigator site concentration remains lighter than western and southern counterparts, creating geographic diversification opportunities for distributed trial networks.
India CRO Market Competitive Environment
Player mix skews toward integrated full-service providers with captive discovery infrastructure and specialized early-phase operators with chemistry-heavy capabilities. The market structure concentrates margin pools through long-term strategic partnerships while transactional fee-for-service arrangements dominate bioanalytical testing. Two strategic archetypes dominate: campus-based integrated providers spanning discovery-to-commercialization, and regulatory toxicology specialists operating GLP-compliant facilities. Competitive moves center on electronic document management infrastructure investment and CDSCO digital platform readiness.
Within the integrated full-service tier, Syngene International exemplifies the campus-based archetype with its Bangalore discovery-to-commercialization infrastructure. Jubilant Biosys occupies a position among chemistry-focused early-phase specialists with captive medicinal chemistry teams. Eurofins Advinus anchors the regulatory toxicology segment, operating GLP-compliant facilities that support IND-enabling study packages. These three represent the structural divergence between end-to-end accountability models and specialized functional service provision.
| Leading Market Players |
|---|
| Syngene International Ltd |
| Jubilant Biosys |
| Eurofins Advinus |
| Veeda Clinical Research |
| IQVIA |
| TheraIndx Lifesciences |
| Dabur Research |
| Cliantha Research |
| Axis Clinicals |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at GLP-compliant facilities in Hyderabad and Mumbai establishes price floors across clinical trial services, concentrating margin capture among operators with validated electronic document management systems while compressing returns for paper-dependent regional competitors.
Pricing Analysis
Certification level creates the primary spread between full-service providers and transactional operators, with CDSCO GCP compliance and ICH-GCP E6 R2 alignment commanding substantial premiums over uncertified regional labs. Project-based pricing dominates clinical trial execution, while fee-for-service arrangements govern early-phase bioanalytical testing where pricing pressure stems from chemistry-heavy regional competitors. Domestic generic sponsors exhibit highest price sensitivity due to compressed bioequivalence study margins, whereas multinational pharmaceutical clients prioritize relationship depth and regulatory track record over unit cost.
Supply Chain Analysis
Extended facility qualification timelines for GLP certification create inventory-like lead-time constraints, stretching 18-24 months for IND-enabling toxicology capacity. Supply concentrates in India for clinical investigator sites and bioanalytical laboratories, with critical dependencies on imported reference standards and specialized reagents from USA and Europe. Single-source vulnerability runs through CDSCO's centralized approval mechanisms for trial protocols, which can bottleneck study startup across all operator tiers. Distribution runs through direct sponsor-CRO contractual relationships, with limited intermediary presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India CRO market is entering a cyclical recovery phase driven by CDSCO's digital platform integration, which will redistribute competitive advantage toward infrastructure-ready operators after a period of regulatory consolidation.
For Market Incumbents: Shield margin pools by accelerating electronic document management infrastructure investment ahead of CDSCO's mandatory digital submission rollout. Consolidate position through captive DMPK and medicinal chemistry capacity in Bangalore, defending against emerging biotech clients defecting to integrated discovery campuses. Prioritize long-term strategic partnerships over transactional fee-for-service arrangements to lock in sponsor relationships. For New Entrants and Emerging Players: Anchor in Visakhapatnam's emerging life sciences corridor, where lighter investigator site concentration creates geographic diversification opportunities for distributed trial networks. Target early-phase regulatory toxicology services for domestic generic sponsors seeking export market access, leveraging extended GLP qualification timelines as a competitive moat against established operators. Pursue CDSCO certification as the primary go-to-market credential. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among full-service providers with integrated discovery-to-commercialization infrastructure, positioning these archetypes for sustained cash flow quality across the projection horizon. Acquisition targets should demonstrate validated electronic systems and established CDSCO relationships. Watch CDSCO's digital platform launch timing as the critical inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Electronic Document Management Investment | CDSCO's digital submission mandates will disqualify paper-dependent operators from Phase II-III study awards. |
| GLP Certification Pathway | FDA and EMA inspectorate alignment through ICH-GCP E6 R2 eliminates duplicate audit burdens for export-oriented studies. |
| Full-Service Partnership Conversion | Multinational sponsors now consolidate vendor rosters, favoring end-to-end accountability over transactional arrangements. |
| Metabolic Disorder Pipeline Expansion | Oncology-dominant CROs can diversify revenue streams into diabetes and obesity trials with similar recruitment economics. |
| Genome Valley Capacity Buildout | Hyderabad's concentrated bioanalytical infrastructure accelerates adoption of CDSCO's streamlined approval mechanisms. |
Study Parameters
The analysis maps clinical trial services, regulatory affairs, pharmacovigilance, and data management segments, each validated through primary interviews with drug development executives, regulatory affairs leads at domestic generic manufacturers, CDSCO officials, and hospital procurement managers. Secondary sources include FDA filings, EMA submissions, ClinicalTrials.gov records, and CDSCO public approval databases. Bottom-up service-line sizing and top-down market triangulation were cross-referenced for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation by service type, end user category, technology adoption tier, and delivery model structure, with therapeutic area concentration and regional regulatory cluster as additional dimensions. CAGRs were derived from sponsor pipeline tracking and capacity expansion announcements, incorporating PLI scheme stimulus effects and CDSCO digital mandate implementation timelines.
Decision-makers should treat outputs as directional under assumptions of sustained CDSCO regulatory streamlining and continued biopharmaceutical outsourcing trends; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
AI-Based Clinical Trial Solutions for Patient Matching Market
Clinical Research
Real World Evidence Linkage Services Market
Clinical Research
Omics-Based Clinical Trials Market
Clinical Research
Clinical Data Analytics Market
Clinical Research
North America Contract Research Organization Market
Clinical Research
Clinical Trial Patient Recruitment Services Market
Clinical Research
Healthcare Contract Research Organization Market
Clinical Research
Global Clinical Trials Matching Software Market
Clinical Research
Clinical Trial Logistics Market
Clinical Research
AI-Based Clinical Trials Solution Provider Market
Clinical Research
Clinical Trials Site Management Organizations Market
Clinical Research
Clinical Trial Investigative Site Network Market
Clinical Research
Humanized Mice Model Market
Clinical Research
Non-Alcoholic Steatohepatitis Clinical Trials Market
Clinical Research
Global Clinical Trial Supply Management Market
Clinical Research
Atopic Dermatitis Clinical Trials Market