
 Clinical Trial Investigative Site Network Market | 2026-2036
Clinical Trial Investigative Site Network Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Trial Investigative Site Network Market Intelligence
Electronic data capture is decoupling site networks from paper-based monitoring economics. IQVIA leverages its informatics infrastructure to anchor multi-country trial execution. ICON plc sustains competitive density through therapeutic specialization in oncology and rare disease networks. Meridian Clinical Research operates one of the largest integrated site footprints across North American metropolitan corridors.
A clinical trial investigative site network constitutes an organized consortium of healthcare facilities, principal investigators, and support staff executing protocol-driven research under Good Clinical Practice standards, typically requiring 21 CFR Part 11 compliant electronic systems and institutional review board oversight. These networks aggregate patient access, standardize enrollment workflows, and distribute regulatory risk across multiple geographic nodes. Academic institutions retain dominance in early-phase oncology studies where principal investigator prestige drives sponsor selection, while private clinics represent the fastest-expanding site type as community-based recruitment shortens enrollment timelines. Phase III studies generate the largest service revenue pools within site networks due to extended duration and higher patient volumes per protocol.
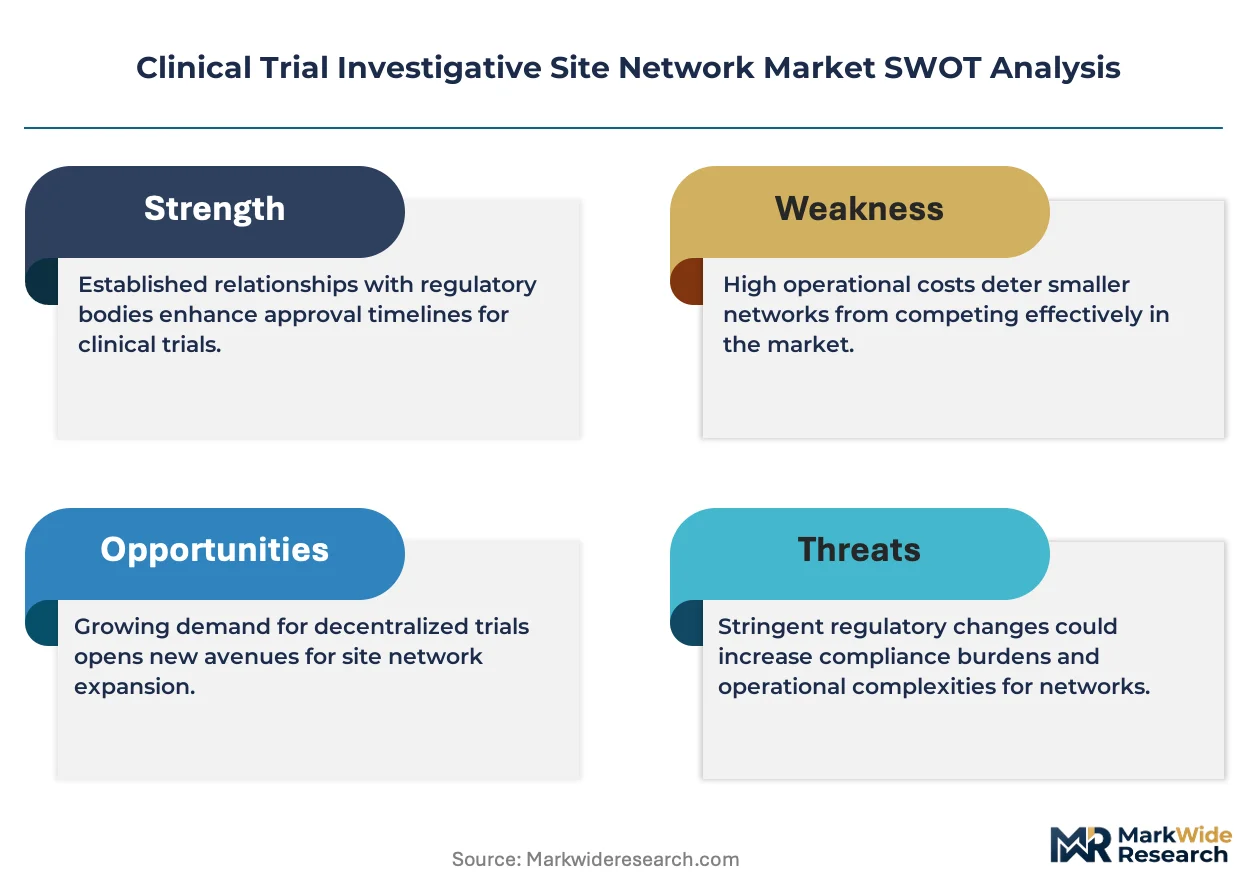
FDA oversight through 21 CFR Part 312 and ICH E6(R2) guidelines mandates source data verification and risk-based monitoring, directly elevating demand for centralized data monitoring services within network offerings. EMA's Clinical Trials Regulation and EU MDR requirements reshape site qualification protocols across European member states, compelling networks to maintain dual compliance architectures. China's NMPA alignment with ICH standards accelerates multinational sponsor entry into domestic site partnerships. Stakeholders must weigh regulatory divergence against operational scale when configuring network footprints for upcoming therapeutic programs.
Market Dynamics
Decentralized trial infrastructure is fragmenting the traditional site-network value chain, forcing incumbents to rebuild around direct-to-patient logistics and home-health nursing capabilities rather than brick-and-mortary enrollment density.
Growth Catalysts
- FDA Digital Health Guidance:The agency's 2023 enforcement discretion framework for decentralized clinical trial technologies removes premarket barriers for software-enabled recruitment platforms, accelerating sponsor adoption of virtual-first protocols.
- Community-based oncology pipelines:Biopharmaceutical developers are shifting Phase II-III immuno-oncology studies into suburban and rural treatment centers to access treatment-naive patient populations outside academic medical center catchments.
- Electronic source data verification:Cloud-native EDC systems with real-time monitoring dashboards compress database lock timelines by eliminating transcription lag between site entry and sponsor review.
Market Restraints
- Principal investigator scarcity:The finite pool of FDA 1572-qualified investigators with active IND experience concentrates trial access in metropolitan corridors, inflating site activation fees in secondary markets.
- EU MDR site qualification burden:The European Medical Device Regulation's expanded clinical evidence requirements force networks to duplicate quality management systems across notified body jurisdictions, elevating compliance overhead.
- Patient retention platform substitution:Third-party virtual visit vendors and wearable data streams displace traditional site-based monitoring touchpoints, compressing per-patient service revenue for physical infrastructure-dependent networks.
Strategic Opportunities
- China's ICH convergence:NMPA alignment with international harmonization standards enables multinational sponsors to run concurrent global protocols through domestic Chinese site partnerships, unlocking access to the world's second-largest pharmaceutical market.
- Decentralized-hybrid protocol design:The convergence of telemedicine platforms with direct-to-patient drug distribution creates white-space service models combining virtual enrollment with localized biosample collection.
- Rare disease natural history studies:Orphan drug incentives under FDA's Breakthrough Therapy designation generate sustained demand for global patient registry infrastructure that networks can repurpose across multiple sponsor engagements.
Industry Challenges
- Clinical research coordinator turnover:Burnout-driven attrition in site-level study coordination roles disrupts enrollment continuity and elevates training costs for complex therapeutic protocols.
- Legacy CTMS integration friction:Sponsor-mandated migration from on-premise clinical trial management systems to API-first cloud architectures requires expensive middleware development for multi-site data harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Trial Investigative Site Network Market |
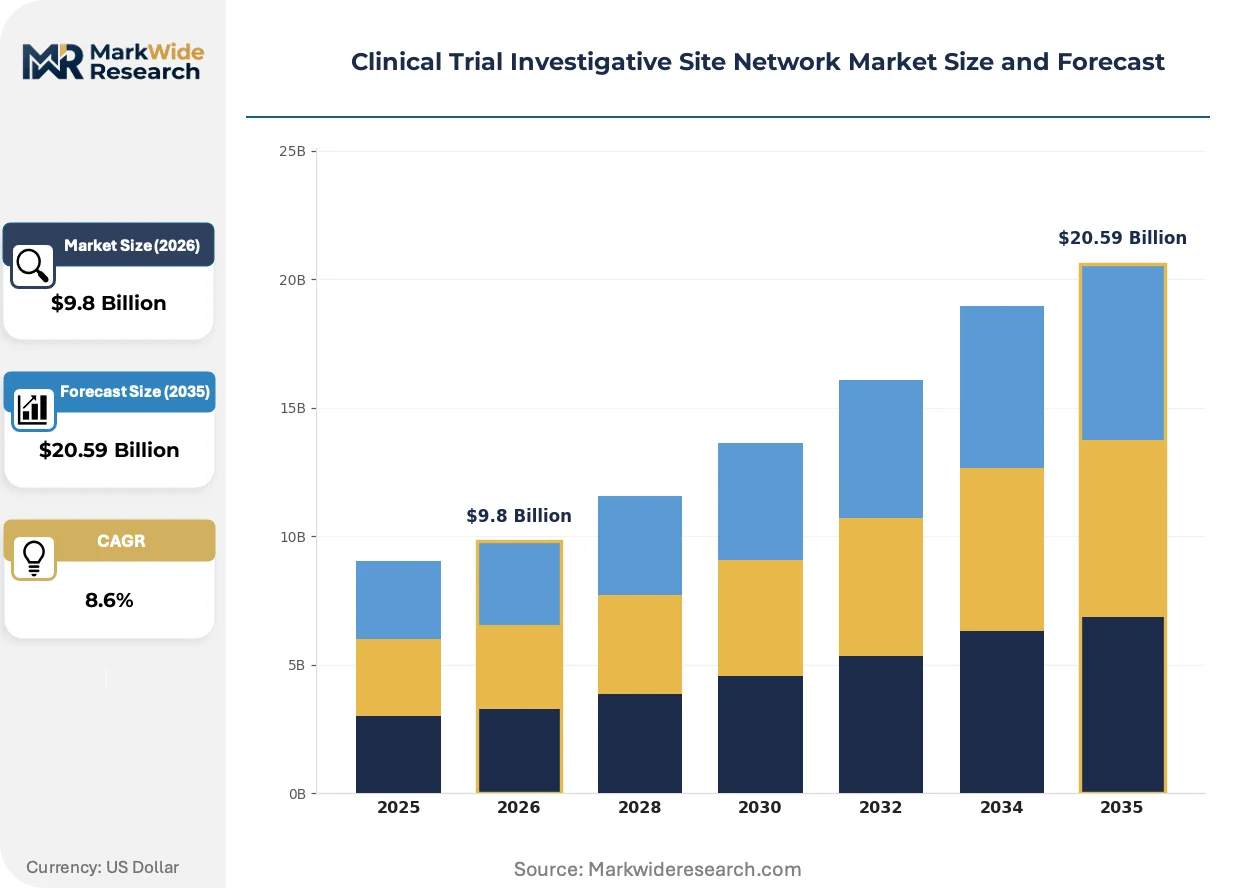
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.59 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Site Type: Academic Institutions, Private Clinics, Research Organizations, Specialized Facilities Study Phase: Phase I, Phase II, Phase III, Phase IV Therapy Area: Oncology, Neurology, Cardiology, Infectious Diseases Service Offering: Patient Recruitment, Site Management, Data Monitoring, Regulatory Affairs |
| Companies Covered | Elligo Health Research, ClinChoice, ICON plc, FOMAT Medical Research Inc., Access Clinical Trials Inc., Velocity Clinical Research, WCG, Meridian Clinical Research, IQVIA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Trial Investigative Site Network Market Strategic Shifts & Innovations
Electronic data infrastructure and patient-facing digital tools are collapsing the spatial constraints that historically defined site network competitiveness, redistributing value toward platforms that orchestrate distributed care delivery.
Remote patient monitoring technology is modularizing the traditional site visit into discrete data collection events. Wearable biosensors and smartphone-reported outcomes now capture continuous safety signals outside clinical settings. Large CROs are embedding these tools into standard protocol templates, compressing the physical site footprint required for regulatory-grade evidence generation.
EMA's Clinical Trials Information System is mandating unified trial registration and results disclosure across all European Economic Area member states. The regulation eliminates fragmented national submission pathways, compelling networks to consolidate regulatory affairs functions into centralized European hubs. German and French site operators are absorbing compliance costs through sponsor-facing transparency fees.
Sponsor procurement teams are unbundling full-service site management into component contracts for recruitment, data capture, and regulatory submission. Biotechnology companies with lean operational structures now directly contract patient advocacy groups for enrollment while outsourcing monitoring to specialized quality assurance vendors. This disaggregation is most pronounced in North American early-phase oncology studies where speed-to-first-patient dominates vendor selection criteria.
Clinical Trial Investigative Site Network Market Segmentation
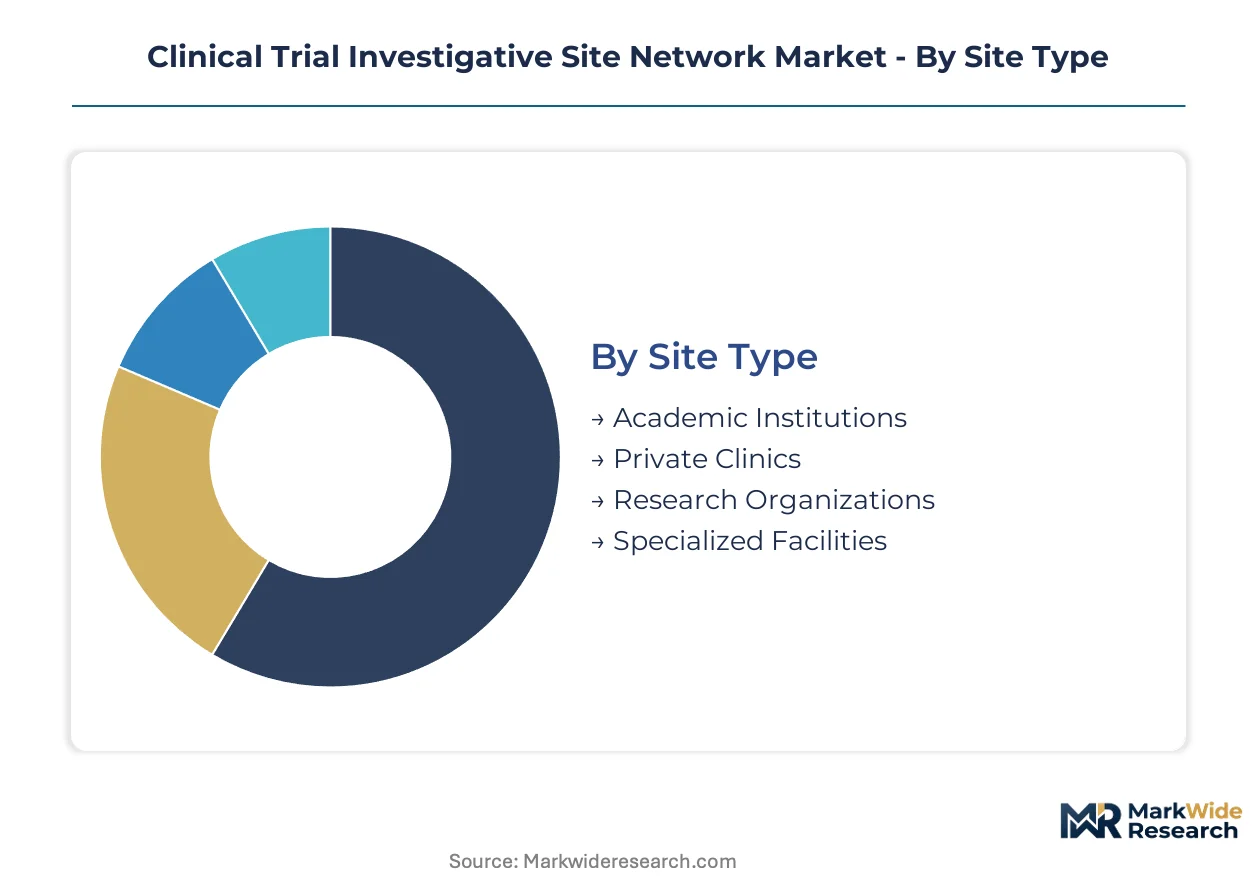
Site networks compete on access density, therapeutic credibility, and regulatory execution speed. Segmentation reveals where sponsor procurement teams concentrate contract value and which service lines command premium pricing.
Site Type:
Upgrade cycles in site infrastructure favor organizations that can absorb EDC migration costs and maintain dual FDA-EMA compliance architectures without sponsor subsidies.
- Academic Institutions:University-affiliated medical centers with tenured principal investigators and NIH-funded research infrastructure. Principal investigator prestige drives sponsor selection in early-phase oncology, though activation timelines stretch longer than private alternatives.
- Private Clinics:Community-based outpatient facilities with streamlined IRB relationships and suburban patient access. Biopharmaceutical sponsors prioritize these for Phase II-III immuno-oncology recruitment outside academic catchments.
- Research Organizations:Dedicated clinical research facilities without teaching obligations. These concentrate in Texas, Florida, and North Carolina metropolitan corridors where patient mobility and coordinator availability exceed national averages.
- Specialized Facilities:Disease-specific centers with captive patient registries and natural history databases. Rare disease networks leverage these for orphan drug protocol execution.
Volume placements concentrate in Academic Institutions; the faster expansion belongs to Private Clinics.
Study Phase:
Cost tier separation in sponsor procurement creates distinct vendor pools by phase complexity and patient volume requirements.
- Phase I:First-in-human safety and tolerability studies requiring intensive pharmacokinetic sampling. Demand clusters in academic medical centers with dedicated clinical pharmacology units and experienced investigative staff.
- Phase II:Efficacy signal detection in targeted patient populations. Sponsor preference for hybrid decentralized designs compresses physical site requirements while expanding geographic reach.
- Phase III:Large-scale confirmatory trials generating the largest service revenue pools. Extended duration and higher patient volumes per protocol justify dedicated project management infrastructure.
- Phase IV:Post-marketing surveillance and real-world evidence collection. These studies expand fastest in community-based networks with existing electronic health record integration.
Revenue concentration sits with Phase III; the steepest expansion trajectory belongs to Phase IV.
Therapy Area:
Application-specific site capabilities determine competitive positioning, with oncology commanding specialized infrastructure investments that other therapeutic areas cannot amortize.
- Oncology:Immuno-oncology and cell therapy protocols requiring specialized infusion centers and cryogenic sample handling. Academic institutions retain dominance where principal investigator reputation influences regulatory submission credibility.
- Neurology:Central nervous system trials with complex cognitive assessment batteries and longitudinal imaging requirements. Site networks with dedicated neuropsychology coordinators capture disproportionate sponsor attention.
- Cardiology:Cardiovascular outcome studies with event adjudication infrastructure and echocardiography core lab relationships. Community-based recruitment shortens enrollment timelines for hypertension and heart failure indications.
- Infectious Diseases:Vaccine and antimicrobial development with pandemic preparedness implications. Government funding flows concentrate in sites with biosafety level containment and rapid activation protocols.
Sponsor contract value peaks in Oncology; Infectious Diseases is climbing the fastest on pandemic infrastructure investment.
Service Offering:
Customer type unbundling in biotechnology procurement separates full-service contracts into component specialties, rewarding vendors with modular capabilities.
- Patient Recruitment:Direct-to-patient marketing, prescreening databases, and community outreach. Virtual recruitment platforms and patient advocacy partnerships displace traditional site-based enrollment.
- Site Management:Coordinator training, supply chain logistics, and visit scheduling across multi-site protocols. Centralized project management offices in Research Triangle Park and San Diego metro areas serve national sponsor bases.
- Data Monitoring:Source data verification, query resolution, and database lock preparation. Cloud-native EDC systems with real-time dashboards compress timelines between site entry and sponsor review.
- Regulatory Affairs:IND maintenance, IRB submission, and FDA correspondence. Dual US-EU compliance capabilities command premium pricing as EMA Clinical Trials Regulation harmonization proceeds.
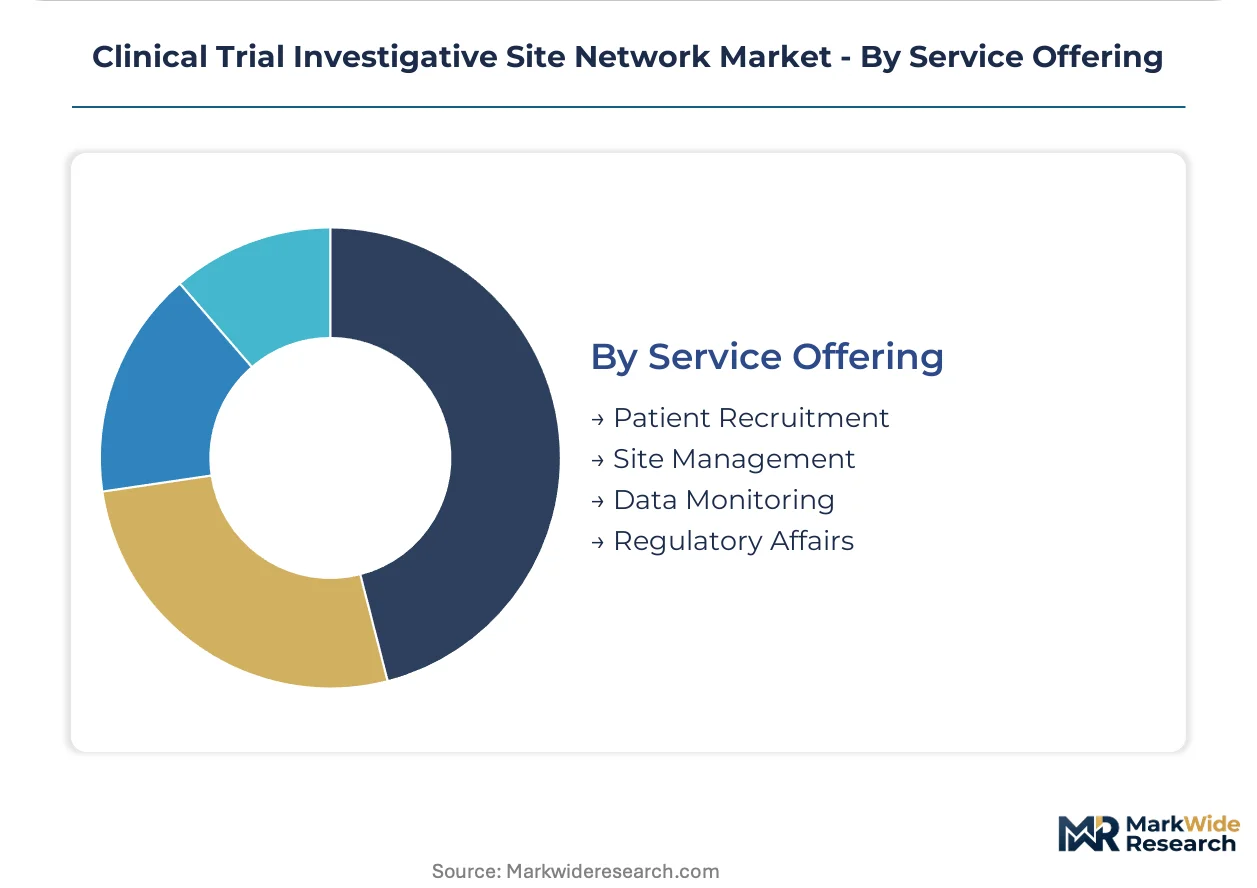
Contract volume concentrates in Site Management; Data Monitoring is gaining share fastest on real-time infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sponsor procurement teams concentrate contract awards in jurisdictions with aligned regulatory pathways and dense patient access corridors. Site network valuations track directly to the volume of active IND filings and the speed of ethics committee turnaround.
United States
FDA's 2023 enforcement discretion framework for decentralized trial technologies accelerates virtual-first protocol adoption across suburban and rural treatment centers. The 21 CFR Part 312 requirements for source data verification sustain demand for centralized monitoring infrastructure. The Research Triangle Park corridor in North Carolina anchors multi-site project management offices serving national sponsor bases.
Germany
EMA's Clinical Trials Information System mandates unified trial registration across all European Economic Area member states, compelling networks to consolidate regulatory affairs into centralized European hubs. The EU MDR expanded clinical evidence requirements elevate compliance overhead for site qualification protocols. Berlin and Munich metropolitan clusters absorb these costs through sponsor-facing transparency fees.
China
NMPA alignment with ICH standards enables multinational sponsors to run concurrent global protocols through domestic site partnerships, unlocking access to the world's second-largest pharmaceutical market. Government funding flows concentrate in sites with rapid activation protocols and biosafety containment capabilities. Shanghai and Beijing anchor the largest integrated site footprints for multinational trial execution.
United Kingdom
MHRA post-Brexit regulatory autonomy creates parallel submission pathways that networks must navigate alongside EMA procedures. The NHS Long Term Plan drives community-based recruitment into suburban treatment centers outside academic medical center catchments. The London-Oxford-Cambridge corridor retains dominance in early-phase oncology where principal investigator prestige influences sponsor selection.
India
CDSCO harmonization with ICH-GCP standards accelerates multinational sponsor entry into domestic site partnerships for cost-efficient Phase III execution. The country's central pharmaceutical regulator mandates local ethics committee oversight that networks navigate through established institutional relationships. Hyderabad and Mumbai metropolitan clusters concentrate dedicated clinical research facilities with streamlined IRB relationships.
Clinical Trial Investigative Site Network Market Key Industry Players
Strategic partnerships dominate the current landscape as incumbents rebuild capabilities around decentralized trial infrastructure and direct-to-patient logistics. The vendor base separates into three distinct tiers: global CRO-integrated networks with informatics infrastructure, mid-scale therapeutic specialists with oncology and rare disease concentration, and regional community-based operators with streamlined activation timelines. Two competitive moves define positioning: technology licensing agreements for cloud-native EDC integration, and geographic expansion through acquisition of suburban private clinic networks.
Within the global CRO-integrated tier, IQVIA leverages informatics infrastructure to anchor multi-country trial execution, while ICON plc exemplifies therapeutic specialization through concentrated oncology and rare disease network investments. Meridian Clinical Research occupies a position among North American metropolitan corridor operators with one of the largest integrated site footprints across community-based facilities. These three represent the strategic archetypes that procurement teams evaluate against protocol-specific requirements for speed, scale, and therapeutic credibility.
| Leading Market Players |
|---|
| Elligo Health Research |
| ClinChoice |
| ICON plc |
| FOMAT Medical Research Inc. |
| Access Clinical Trials Inc. |
| Velocity Clinical Research |
| WCG |
| Meridian Clinical Research |
| IQVIA |
| Others |
Cost & Logistics Intelligence
Cloud-native electronic data capture platforms are displacing legacy on-premise systems, compressing per-patient monitoring costs while concentrating procurement power among sponsors with centralized informatics infrastructure. This technology transition simultaneously flattens tiered service pricing and rewards networks with API-first architectures capable of real-time data streaming.
Pricing Analysis
Volume placements concentrate in academic medical centers with established principal investigator relationships, while margins compress fastest among community-based private clinics competing on activation speed. Three-tier pricing structure across premium, standard, and economy levels reflects therapeutic specialization depth, regulatory dual-compliance capability, and geographic patient access density. Cost compression in standard-tier site management is intensifying because third-party virtual visit vendors displace physical monitoring touchpoints. Biotechnology sponsors with lean procurement functions exhibit highest price sensitivity; large pharmaceutical developers prioritize speed-to-first-patient over per-patient economics.
Supply Chain Analysis
Freight and logistics costs for temperature-controlled investigational product distribution represent a growing cost center as decentralized trials fragment delivery endpoints across suburban and rural patient residences. Supply concentrates in the United States, Germany, and China, where regulatory alignment with ICH standards enables concurrent global protocol execution. Raw material dependencies include cryogenic sample handling equipment, direct-to-patient drug distribution infrastructure, and wearable biosensor hardware. Single-source vulnerability sits with specialized courier networks qualified for Good Distribution Practice compliance. Distribution runs through sponsor-contracted central depots with regional hub-and-spoke configurations for patient-direct shipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The clinical trial investigative site network market is executing a technology-transition phase as decentralized trial infrastructure replaces brick-and-mortary enrollment density. Cloud-native electronic data capture and direct-to-patient logistics platforms are displacing legacy paper-based monitoring economics.
For Market Incumbents: Deepen therapeutic specialization in oncology and rare disease networks where principal investigator prestige sustains pricing power against virtual-first competitors. Invest in backward integration into direct-to-patient logistics capabilities to capture service revenue displaced from physical site footprints. Defensive consolidation around informatics infrastructure anchors multi-country trial execution against mid-scale specialists.
For New Entrants and Emerging Players: Patient advocacy group partnerships offer the most penetrable channel for enrollment outsourcing contracts as biotechnology sponsors unbundle full-service site management. Target suburban private clinic networks in the Research Triangle Park and San Diego metropolitan corridors where streamlined IRB relationships accelerate activation timelines. White-space opportunity sits in hybrid decentralized protocol design combining telemedicine platforms with localized biosample collection.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale therapeutic specialists given NMPA alignment with ICH standards unlocking concurrent global protocol access to China. Long-term viability across the analysis window favors networks with dual FDA-EMA compliance architectures and cloud-native EDC integration. Acquisition target archetype: community-based operators with established patient registries in immuno-oncology. Signal to watch: sponsor procurement team unbundling velocity in early-phase oncology studies.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native EDC Integration | Real-time data streaming compresses database lock timelines and displaces legacy transcription economics. |
| Direct-to-Patient Logistics Buildout | Home-health nursing capabilities capture service revenue fragmented from traditional site-based monitoring. |
| Therapeutic Specialization Concentration | Oncology and rare disease networks command premium pricing where principal investigator reputation influences regulatory credibility. |
| Dual Compliance Architecture Investment | Simultaneous FDA-EMA qualification enables multinational sponsor contracts without redundant quality systems. |
| Patient Advocacy Partnership Formation | Direct enrollment outsourcing contracts displace traditional site-based recruitment in lean biotechnology procurement. |
Research Approach
Document review covered FDA 1572 investigator filings, ClinicalTrials.gov protocol registries, and EMA Clinical Trials Information System submissions, complemented by interviews with drug development executives, regulatory affairs leads, site network operations directors, and sponsor procurement managers. Secondary validation drew from IQVIA Institute reports, ICON plc investor disclosures, and CDSCO harmonization notifications. Bottom-up site capacity modeling and top-down sponsor spend analysis provided triangulation across independent estimation approaches.
Market size outputs reflect patient enrollment velocity projections, per-protocol service revenue assumptions, and technology adoption curves across the modeling period. Segmentation dimensions modeled include site type, study phase, therapy area, and service offering with regional regulatory cluster overlays. CAGRs were derived from sponsor pipeline analysis, site activation trend data, and informatics infrastructure investment trajectories. Forecast inputs incorporated decentralized trial penetration rates and principal investigator supply constraints.
Caveats apply where FDA enforcement discretion revisions, EU MDR implementation delays, or NMPA regulatory shifts could materially shift the outlook. Forecasts reflect assumptions about technology adoption timelines and sponsor procurement unbundling velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Global Clinical Trial Management Systems Market
Clinical Research
Atopic Dermatitis Clinical Trials Market
Clinical Research
US Clinical Trials Market
Clinical Research
Omics-Based Clinical Trials Market
Clinical Research
Europe Clinical Trials Market
Clinical Research
Ecoa, Esource & Clinical Trials Market
Clinical Research
Clinical Data Analytics Market
Clinical Research
Clinical Trials Site Management Organizations Market
Clinical Research
Clinical Trial Management Services Market
Clinical Research
AI-Based Clinical Trials Solution Provider Market
Clinical Research
Clinical Trial Biorepository and Archiving Solutions Market
Clinical Research
Healthcare Contract Research Organization Market
Clinical Research
Clinical Trial Patient Recruitment Services Market
Clinical Research
Global Clinical Trial Support Services Market
Clinical Research
Clinical Trial Logistics and Direct-to-Patient Delivery Platforms Market
Clinical Research
Pharmacovigilance Outsourcing Market