
 Clinical Trial Patient Recruitment Services Market | 2026-2036
Clinical Trial Patient Recruitment Services Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Trial Patient Recruitment Services Market Intelligence
The FDA's risk-based monitoring framework is recalibrating the cost-of-entry calculus for recruitment vendors by mandating auditable digital workflows and real-time patient tracking. IQVIA Holdings Inc. leverages its integrated data ecosystem to anchor large-scale oncology trial pipelines across North America and Europe. Syneos Health, Inc. competes through therapeutic-area specialization, particularly in complex neurology and infectious disease protocols where site access remains constrained. ICON plc sustains geographic dominance in Asia-Pacific through localized investigator networks and regulatory consulting bundled with recruitment execution.
Clinical trial patient recruitment services encompass the systematic identification, screening, enrollment, and retention of qualified participants for investigational studies, typically executed through centralized databases, site feasibility assessments, targeted outreach campaigns, and compliance monitoring against protocol inclusion criteria. The primary commercial purpose is to accelerate trial timelines and reduce sponsor costs by replacing fragmented site-dependent enrollment with structured, metrics-driven patient access programs. Digital platforms and predictive modeling now capture the fastest-growing margin pools as sponsors prioritize algorithmic prescreening and dropout-risk forecasting over traditional advertising-heavy recruitment marketing. Oncology trials remain the largest application segment, though infectious disease trials expanded rapidly following pandemic-era infrastructure investments and sustained vaccine platform development.
The FDA, EMA, and MHRA collectively enforce Good Clinical Practice standards that dictate informed consent documentation, adverse event reporting timelines, and data integrity requirements directly shaping vendor operational design and technology procurement. Japan's PMDA and China's NMPA impose additional localization mandates for patient-facing materials and electronic data capture systems, fragmenting platform architecture and raising compliance costs for cross-border trials. Stakeholders must monitor evolving AI governance frameworks in the EU and US to determine whether automated patient matching algorithms will require explicit regulatory validation before deployment in protocol-driven enrollment workflows.
Market Dynamics
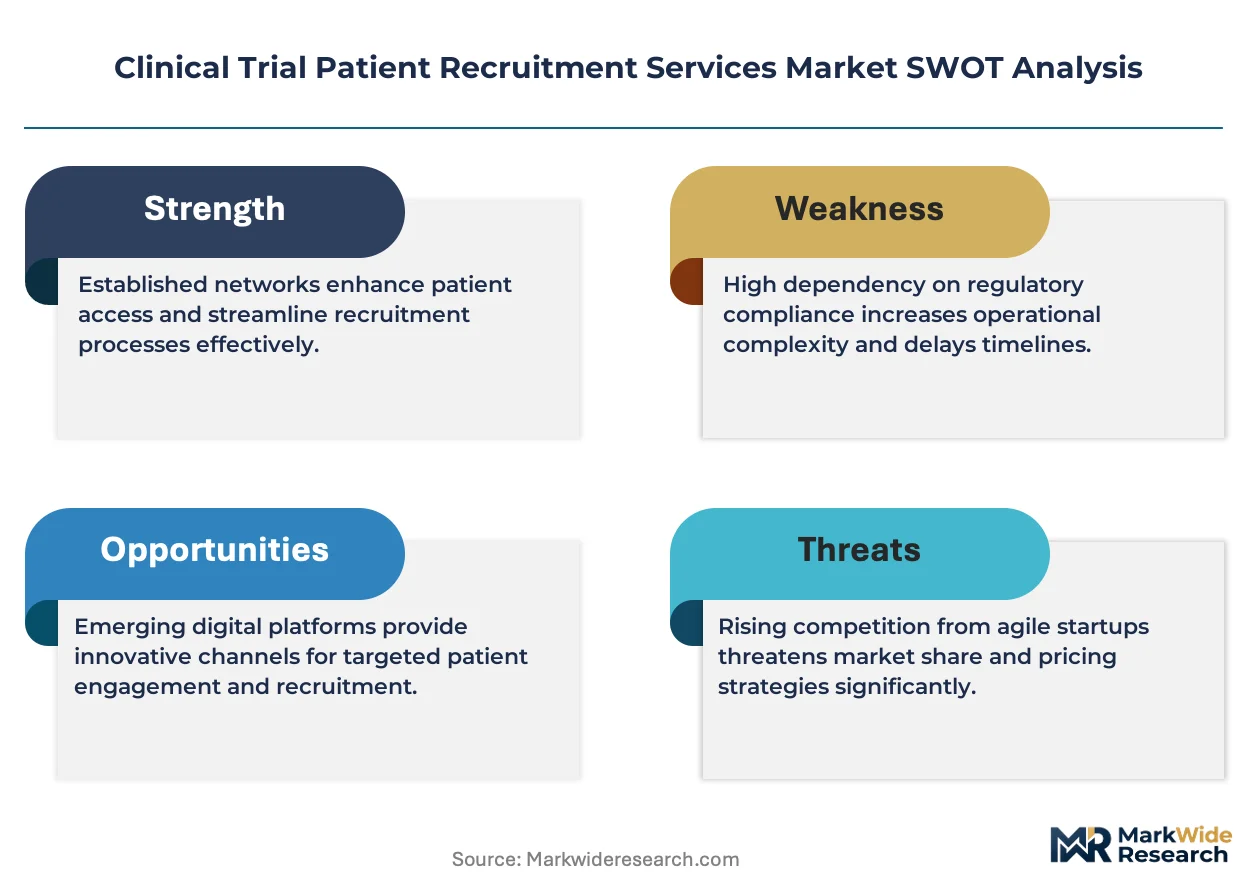
The FDA's risk-based monitoring framework is compressing vendor qualification timelines by mandating auditable digital workflows and real-time patient tracking capabilities. Pharmaceutical sponsors now prioritize integrated data ecosystems over fragmented site-dependent enrollment, restructuring procurement criteria and technology procurement budgets across North America and Europe.
Growth Catalysts
- Decentralized trial infrastructure:Remote monitoring technologies and direct-to-patient shipping protocols are expanding addressable patient pools beyond traditional site catchment areas. Sponsors in oncology and rare disease segments now access geographically dispersed populations previously excluded from protocol participation.
- EMA's clinical trial information system:The transparency mandate is accelerating vendor investments in interoperable data architectures. European sponsors demand standardized electronic data capture systems that streamline cross-border trial execution and regulatory submission workflows.
- Algorithmic prescreening:Machine learning models applied to electronic health records are reducing screen-failure rates and accelerating enrollment velocity. CROs deploying predictive analytics capture disproportionate share of large-scale infectious disease and vaccine platform trials.
Market Restraints
- Regulatory fragmentation:Japan's PMDA and China's NMPA impose divergent localization mandates for patient-facing materials and electronic consent systems. Cross-border trial sponsors absorb duplicated compliance costs and extended platform development cycles.
- Specialized talent scarcity:Clinical data scientists with dual expertise in regulatory science and predictive modeling command premium compensation. Recruitment vendors face margin compression or service quality trade-offs when competing for limited qualified personnel.
- Site concentration risk:Oncology trial enrollment concentrates among high-volume academic medical centers in the United States and Germany. Capacity constraints at these institutions create enrollment bottlenecks that centralized recruitment services cannot fully circumvent.
Strategic Opportunities
- LATAM expansion:Brazil's ANVISA and Mexico's COFEPRIS are harmonizing Good Clinical Practice standards with FDA and EMA frameworks. Sponsors seeking cost-efficient trial execution are establishing investigator networks in São Paulo and Mexico City metro corridors.
- Real-world evidence integration:Convergence of patient recruitment platforms with longitudinal health record systems is enabling protocol feasibility assessments prior to site activation. Vendors offering combined recruitment-RWE analytics capture expanded scope in protocol design consulting.
- EU AI Act compliance services:Automated patient matching algorithms will require explicit validation documentation under emerging European artificial intelligence governance. Early-mover vendors developing auditable AI decision-trail systems position for regulatory-driven demand inflection.
Industry Challenges
- Legacy system integration:Pharmaceutical sponsors operate entrenched clinical trial management systems with limited API connectivity. Recruitment platform vendors absorb substantial implementation costs and timeline risk when interfacing with heterogeneous sponsor technology stacks.
- Retention protocol complexity:Dropout-risk forecasting models require continuous retraining as patient behavior patterns shift across therapeutic areas. Vendors struggle to maintain predictive accuracy without sustained investment in labeled outcome datasets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Trial Patient Recruitment Services Market |
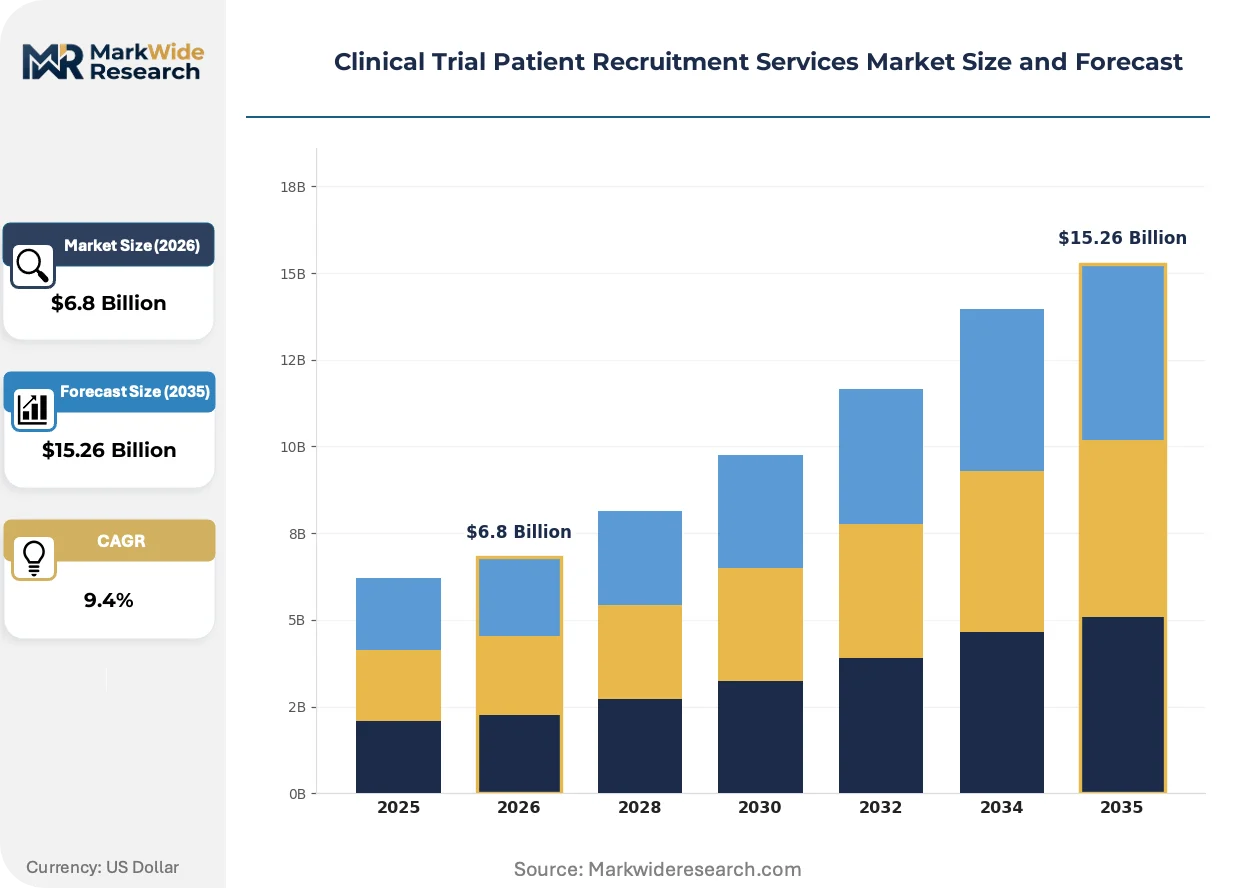
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Patient Identification, Site Selection, Recruitment Marketing, Retention Strategies Technology: Digital Platforms, EHR Integration, Data Analytics, Predictive Modeling Application: Oncology Trials, Cardiovascular Studies, Neurology Research, Infectious Disease Trials End User: Pharmaceutical Companies, CROs, Academic Institutions, Biotech Firms |
| Companies Covered | ICON plc, Syneos Health, Inc., IQVIA Holdings Inc., Wuxi AppTec Co., Ltd., Medpace Holdings, Inc., Laboratory Corporation of America Holdings, Parexel International Corporation, PPD, Inc., Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Trial Patient Recruitment Services Market Strategic Shifts & Innovations
Digital platforms are displacing traditional advertising-heavy recruitment marketing as sponsors prioritize algorithmic prescreening and predictive retention analytics. Three interconnected developments are restructuring competitive positioning and technology procurement criteria across the vendor landscape.
Artificial intelligence applied to electronic health record parsing is rewriting patient identification economics. Mid-cap pharmaceutical sponsors are adopting natural language processing tools at accelerated pace, compressing the timeline between protocol finalization and first-patient-in. The technology is rewriting vendor competitive dynamics by privileging data-access partnerships over traditional site-network scale.
REACH regulatory requirements for chemical substance documentation are extending into clinical supply chain traceability mandates. European sponsors must now demonstrate full material disclosure for investigational product packaging and patient-facing devices. The pharmaceutical packaging segment is responding by consolidating vendor relationships with certified documentation specialists capable of integrated regulatory submission support.
Subscription-based platform licensing is displacing per-patient recruitment fees among large-cap sponsors. The procurement model change concentrates vendor revenue into annual contracts with performance guarantees, compressing cash conversion cycles and elevating working capital requirements. This shift is most visible in United States-based oncology trials where sponsor procurement functions have centralized technology vendor selection authority.
Clinical Trial Patient Recruitment Services Market Segmentation
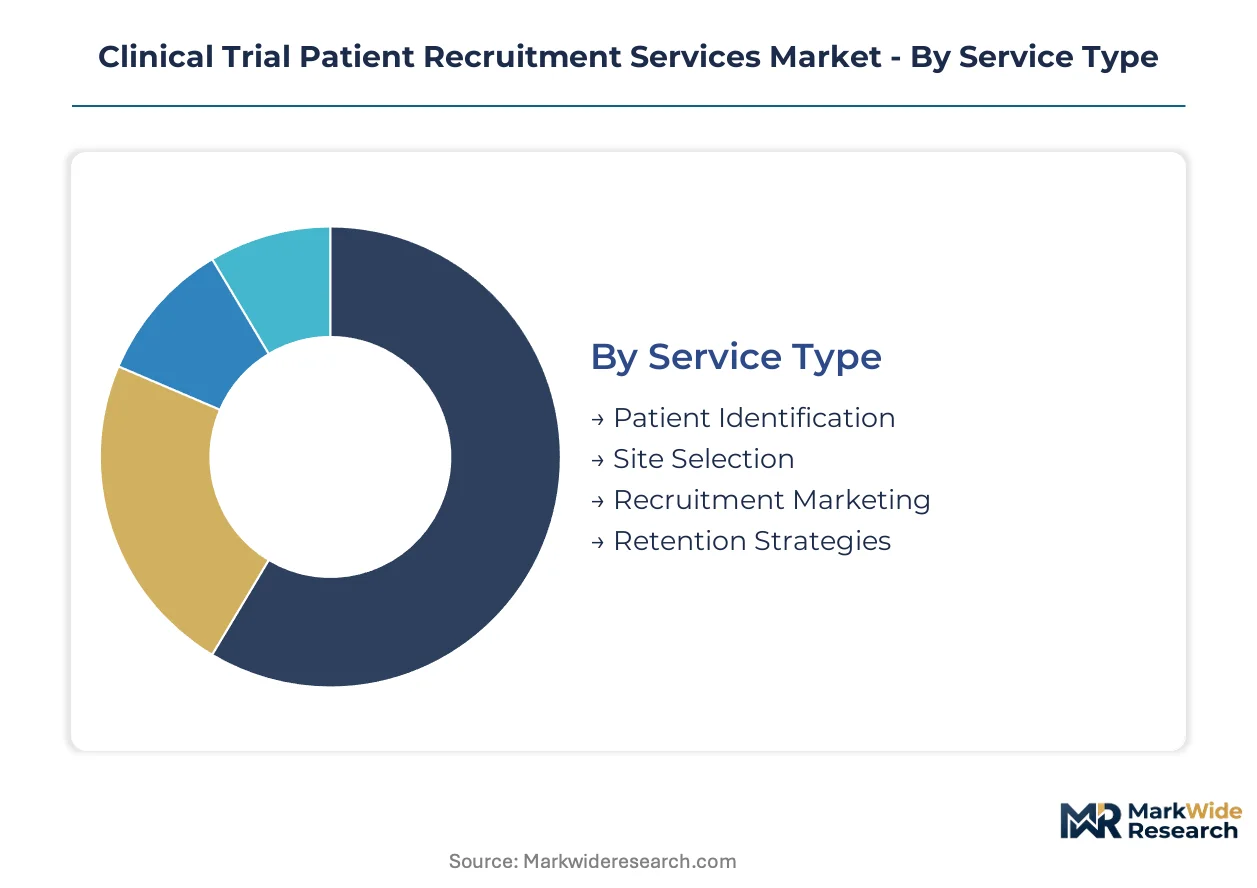
Patient recruitment services fragment across service delivery models, technology stacks, therapeutic applications, and sponsor organizational types. Each segmentation axis reveals distinct margin structures and vendor capability requirements that reshape competitive positioning.
Service Type:
Standardized modules dominate low-complexity trials while bespoke protocol engineering commands premium pricing in rare disease and oncology indications.
- Patient Identification:Systematic screening of electronic health records and claims databases against protocol inclusion criteria. Demand concentrates in the United States where HIPAA-compliant data partnerships enable large-scale prescreening, though FDA audit trail requirements raise vendor compliance costs.
- Site Selection:Feasibility assessments evaluating investigator experience, patient population density, and regulatory history. Academic medical centers in Germany absorb disproportionate site selection investment due to EMA transparency mandates and investigator qualification standards.
- Recruitment Marketing:Targeted outreach campaigns spanning digital advertising, community engagement, and physician referral networks.
- Retention Strategies:Patient engagement protocols, travel reimbursement programs, and adherence monitoring designed to minimize dropout rates.
Most installed capacity flows through Patient Identification. Expansion is steepest in Retention Strategies.
Technology:
Proprietary platform architectures differentiate vendor offerings while interoperability requirements drive API standardization investments.
- Digital Platforms:Cloud-based patient portals, eConsent systems, and remote monitoring interfaces. Pharmaceutical sponsors in Japan prioritize PMDA-validated electronic data capture systems that fragment platform architecture for cross-border trials.
- EHR Integration:Direct connectivity with hospital information systems for automated eligibility screening. Academic institutions in the United States leverage Epic and Cerner integrations to accelerate oncology trial enrollment velocity.
- Data Analytics:Descriptive reporting on enrollment metrics, screen-failure patterns, and site performance benchmarks.
- Predictive Modeling:Machine learning algorithms forecasting enrollment timelines and dropout risk.
Platform investments concentrate in Digital Platforms. Predictive Modeling is gaining share fastest among large-cap sponsors.
Application:
Therapeutic area specialization determines vendor expertise requirements and pricing power, with complex protocols commanding sustained premium margins.
- Oncology Trials:Precision medicine protocols requiring biomarker stratification and companion diagnostic coordination. Site access constraints at high-volume academic centers in the United States and Germany create enrollment bottlenecks that centralized services cannot fully resolve.
- Infectious Disease Trials:Rapid enrollment protocols for outbreak response and vaccine platform development. Pandemic-era infrastructure investments sustain elevated demand for decentralized trial capabilities across multiple geographies.
- Cardiovascular Studies:Large-scale outcomes trials with long follow-up periods and broad inclusion criteria.
- Neurology Research:Complex protocols involving cognitive assessments and caregiver-reported outcomes.
Oncology Trials anchor current vendor revenue. Infectious Disease Trials show the steepest expansion trajectory post-pandemic.
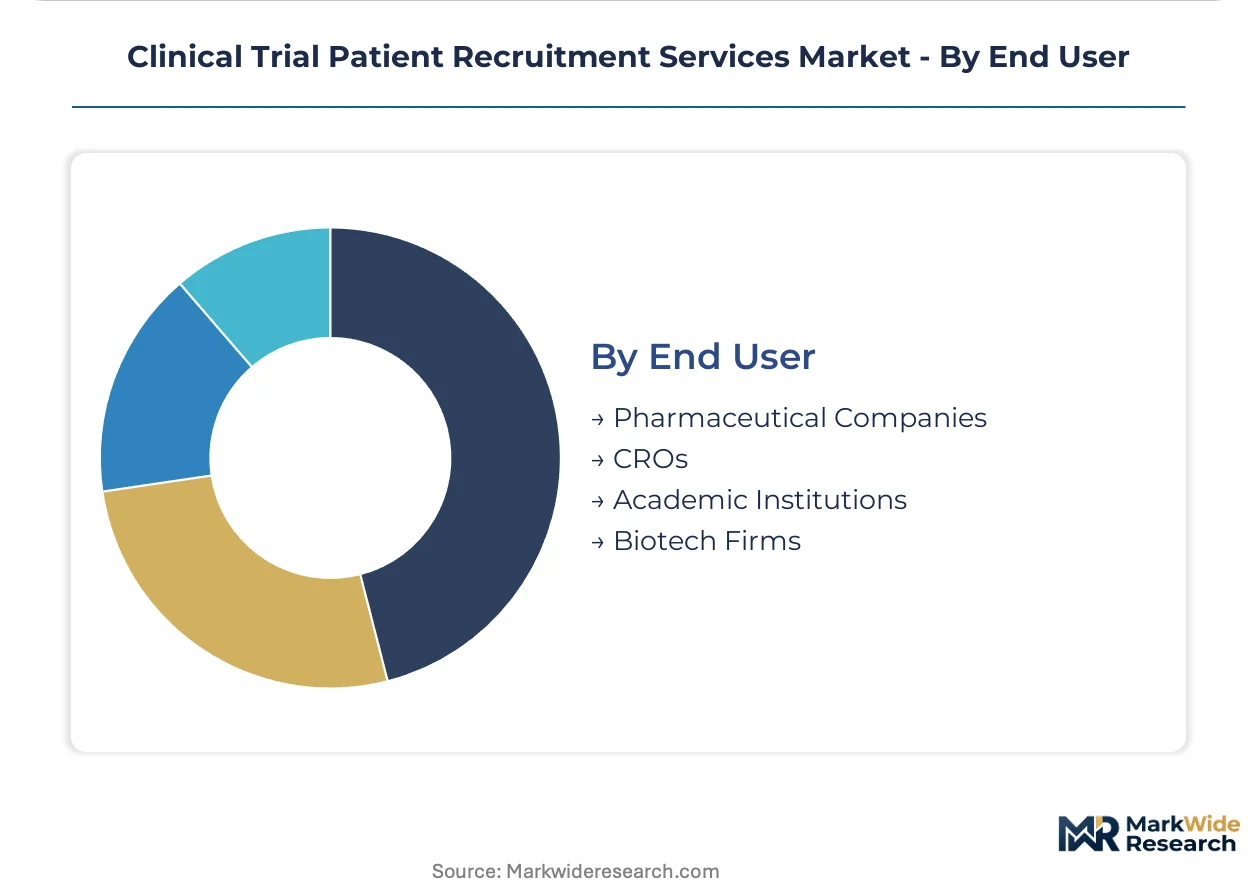
End User:
Procurement sophistication varies dramatically across sponsor types, with large pharmaceutical companies consolidating vendor relationships while biotech firms prioritize flexibility.
- Pharmaceutical Companies:Global sponsors with centralized procurement functions and multi-year master service agreements. Subscription-based platform licensing is displacing per-patient fees among United States-based oncology sponsors with centralized technology selection authority.
- CROs:Full-service contract research organizations bundling recruitment with site management and regulatory consulting. IQVIA and Syneos Health compete through integrated data ecosystems and therapeutic-area specialization respectively.
- Academic Institutions:University medical centers and teaching hospitals conducting investigator-initiated trials.
- Biotech Firms:Venture-backed developers with limited internal infrastructure and rapid timeline pressures.
Pharmaceutical Companies represent the largest addressable spend. Biotech Firms are expanding most quickly as venture financing sustains pipeline development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized clinical data scientists cluster in the United States, Germany, and Japan, anchoring vendor capability development and algorithmic recruitment platform deployment across major trial corridors.
United States
FDA risk-based monitoring mandates compress vendor qualification timelines while driving auditable digital workflow adoption. HIPAA-compliant data partnerships enable large-scale electronic health record prescreening, though audit trail requirements elevate compliance costs for recruitment platforms. Academic medical centers in Boston and the Research Triangle absorb disproportionate oncology trial enrollment investment.
Germany
EMA transparency requirements and investigator qualification standards concentrate site selection investment at high-volume academic institutions. The country's pharmaceutical regulator enforces stringent Good Clinical Practice documentation protocols that reshape vendor operational design. Frankfurt and Munich metro corridors host centralized European trial coordination functions for multinational sponsors.
Japan
PMDA localization mandates for patient-facing materials and electronic consent systems fragment platform architecture for cross-border trials. The national pharmaceutical regulator imposes additional validation requirements for electronic data capture systems. Tokyo and Osaka academic medical centers maintain concentrated investigator networks for neurology and infectious disease protocols.
China
NMPA divergence from FDA and EMA frameworks creates duplicated compliance costs for multinational sponsors executing cross-border trials. The national pharmaceutical regulator mandates localized electronic consent systems and patient-facing documentation. Shanghai and Beijing biotech clusters drive demand for integrated recruitment and regulatory consulting services.
Brazil
ANVISA harmonization with FDA and EMA Good Clinical Practice standards attracts sponsors seeking cost-efficient trial execution. The national health surveillance agency streamlines investigator qualification pathways for international protocols. São Paulo metro corridors anchor expanding investigator networks serving infectious disease and vaccine platform development.
Clinical Trial Patient Recruitment Services Market Key Industry Players
The competitive structure tilts toward integrated data ecosystem providers with therapeutic-area specialization capabilities. Large-cap sponsors consolidate vendor relationships through multi-year master service agreements with performance guarantees. Three archetypes dominate: full-service CROs bundling recruitment with regulatory consulting, specialized patient identification platforms with predictive analytics, and laboratory services companies extending into trial execution. Dominant competitive moves include strategic partnerships with electronic health record systems and geographic expansion through localized investigator network development.
Within the full-service CRO tier, IQVIA Holdings Inc., Syneos Health, Inc., and ICON plc exemplify divergent specialization strategies. IQVIA occupies a position anchored by integrated data ecosystem scale across North American and European oncology pipelines. Syneos Health sits within the therapeutic-area specialization vector, particularly in complex neurology protocols where site access constraints persist. ICON represents geographic expansion archetype execution, sustaining Asia-Pacific presence through localized investigator networks and bundled regulatory consulting. Wuxi AppTec Co., Ltd. and Parexel International Corporation occupy positions between these vectors, reflecting the market's structural pressure toward either data integration depth or geographic coverage breadth.
| Leading Market Players |
|---|
| ICON plc |
| Syneos Health, Inc. |
| IQVIA Holdings Inc. |
| Wuxi AppTec Co., Ltd. |
| Medpace Holdings, Inc. |
| Laboratory Corporation of America Holdings |
| Parexel International Corporation |
| PPD, Inc. |
| Thermo Fisher Scientific Inc. |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up specialists now dominate mid-tier patient recruitment vendors, compressing pricing discipline through standardized service modules while concentrating procurement leverage against fragmented site networks in the United States and Germany. This ownership pattern tightens margin capture at the platform level and feeds backward into supplier payment terms, reshaping how EHR data partnerships and investigator network contracts are negotiated.
Pricing Analysis
Bundled full-service contracts are displacing unbundled per-patient fees as pharmaceutical sponsors consolidate vendor relationships under multi-year master service agreements. Three-tier pricing structure across premium, standard, and economy levels reflects therapeutic complexity and protocol risk, with oncology biomarker-stratified trials commanding sustained premiums. Cost compression in standardized infectious disease protocols is intensifying because algorithmic prescreening commodifies basic patient identification. Biotech firms exhibit highest price sensitivity due to venture-financed runway constraints, while large-cap pharmaceutical companies prioritize performance guarantees over unit cost.
Supply Chain Analysis
Freight and logistics costs for direct-to-patient investigational product shipping are reshaping site network economics as decentralized trial models expand. Supply concentrates in the United States, Germany, and Japan where regulatory-validated electronic data capture systems and HIPAA-compliant EHR integrations anchor vendor capability. The supply chain draws from specialized clinical data scientists, localized investigator networks, and cloud infrastructure providers. Single-source vulnerability in AI-enabled patient matching algorithms creates concentration risk as vendors rely on limited qualified personnel pools. Distribution runs through centralized platform licensing to large sponsors and project-based contracting for biotech clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA risk-based monitoring mandates and EMA transparency requirements continuously elevate compliance spend and vendor qualification barriers. The FDA's 2023 finalized guidance on decentralized clinical trials marks the most significant demand inflection, forcing sponsor procurement toward auditable digital workflows.
For Market Incumbents: Deepen therapeutic-area specialization in neurology and rare disease protocols where site access constraints persist and algorithmic prescreening delivers limited penetration. Consolidate EHR data partnerships with Epic and Cerner installations at high-volume academic medical centers to defend against specialized platform entrants. Invest in PMDA-validated system architectures to capture Japan's localized trial expansion.
For New Entrants and Emerging Players: Enter via LATAM investigator network development in São Paulo and Mexico City corridors where ANVISA and COFEPRIS harmonization creates cost-efficient execution opportunities. Target infectious disease and vaccine platform trials as the most penetrable segment given pandemic-era infrastructure investments and sustained platform development demand. Pursue regulatory consulting bundling as the primary go-to-market angle against pure-play recruitment vendors.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap specialized platforms with predictive analytics capabilities but limited geographic coverage. Long-term viability hinges on AI governance compliance positioning as EU and US frameworks mature. Target acquisition archetype: EHR-integrated patient identification platforms with validated algorithmic decision trails. Monitor FDA enforcement patterns on audit trail requirements as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Consulting Bundling | Captures expanded scope in protocol design and EMA submission support. |
| Predictive Analytics Platform Development | Secures disproportionate share of large-scale infectious disease trials. |
| EHR Data Partnership Expansion | Accelerates enrollment velocity through Epic and Cerner system integrations. |
| LATAM Investigator Network Buildout | Exploits ANVISA harmonization for cost-efficient cross-border trial execution. |
| EU AI Act Compliance Services | Positions early-mover vendors for regulatory-driven demand inflection. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing demand calibration and regulatory impact assessment. The study combines structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and site feasibility specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up enrollment velocity modeling and top-down sponsor spend analysis were triangulated to anchor market sizing.
Granularity-level modeling proceeded at service-type, technology-stack, therapeutic-application, and sponsor-archetype dimensions across the analysis window. CAGRs were derived from enrollment timeline compression rates and sponsor procurement budget shifts. Treatment line stratification and regional regulatory cluster differentiation informed segment-level projections. Forecast inputs incorporated decentralized trial adoption curves and AI governance framework implementation timelines.
Inputs from regulatory filing databases and sponsor procurement disclosures were available through the study window; gaps in real-time enrollment performance metrics introduce uncertainty bands around vendor market share estimates. Forecasts reflect documented assumptions regarding FDA enforcement continuity and EMA transparency mandate adherence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Clinical Trials Market
Clinical Research
Real-World Evidence Analytics Market
Clinical Research
Preclinical CRO Market
Clinical Research
Global Clinical Trial Support Services Market
Clinical Research
Clinical Trial Biorepository and Archiving Solutions Market
Clinical Research
North America Contract Research Organization Market
Clinical Research
Patient-Reported Outcome Data Monetization Market
Clinical Research
Clinical Trial Management Services Market
Clinical Research
Pharmacovigilance Outsourcing Market
Clinical Research
Ecoa, Esource & Clinical Trials Market
Clinical Research
Global Clinical Trial Supply Market
Clinical Research
Global in Vivo Toxicology Market
Clinical Research
AI-Based Clinical Trials Solution Provider Market
Clinical Research
Generative AI in Clinical Trials Market
Clinical Research
Biomarker Discovery Outsourcing Services Market
Clinical Research
Europe Clinical Trials Market