
 Early Phase Clinical Trial Outsourcing Market | 2026-2036
Early Phase Clinical Trial Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Early Phase Clinical Trial Outsourcing Market Foresight
Decentralized clinical trial platforms is reconfiguring how early-phase studies recruit, monitor, and collect patient data. IQVIA Inc. leverages its global site network and real-world data infrastructure to compress study timelines. Charles River Laboratories anchors its competitive position through integrated non-clinical and early clinical capabilities. Medpace Holdings, Inc. differentiates via a full-service model that controls protocol design through final study report delivery.
Early phase clinical trial outsourcing encompasses the delegation of Phase I, Phase II, Phase I/II, and early feasibility study execution to specialized service providers, encompassing patient recruitment, site monitoring, data management, and regulatory submission preparation under Good Clinical Practice standards. The primary purpose is to reduce sponsor fixed costs while accessing therapeutic expertise and accelerated enrollment capabilities that internal teams rarely match. Patient recruitment services command premium pricing due to persistent enrollment bottlenecks that delay timelines across oncology and rare disease indications. Phase I dose-escalation studies remain the largest revenue pool, though Phase I/II adaptive designs represent the fastest-expanding segment as sponsors pursue accelerated approval pathways. Fee-for-service and hybrid delivery models now dominate contracting structures, displacing pure fixed-price arrangements that proved unsustainable for complex adaptive protocols.
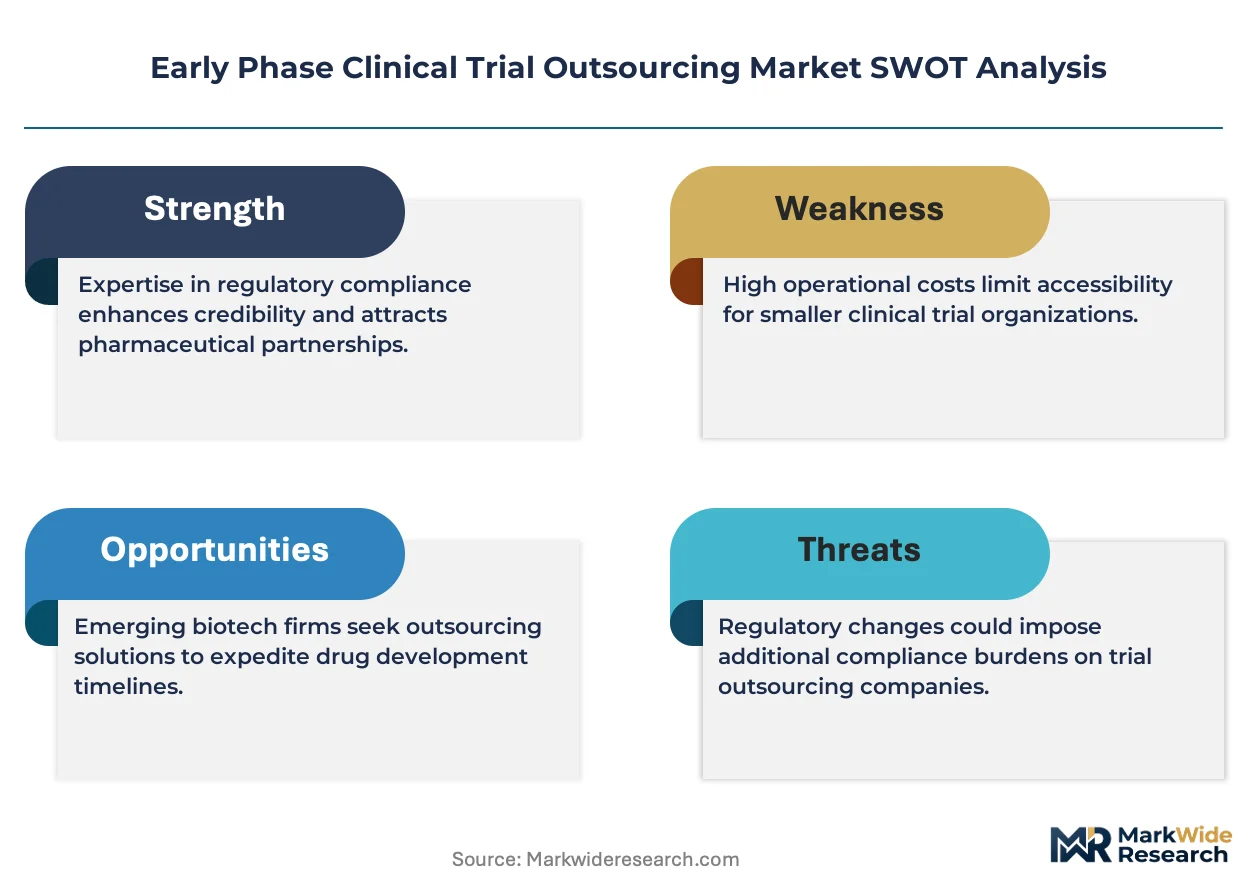
FDA's Investigational New Drug application requirements and EMA's Clinical Trials Regulation reshape protocol design standards and safety reporting cadences for all outsourced early-phase work. The FDA, EMA, and ICH-GCP frameworks collectively elevate data quality expectations, forcing contract research organizations to invest in centralized monitoring technology and risk-based quality management systems. Sponsors must evaluate vendor inspection readiness and regulatory intelligence capabilities before committing to multi-study partnerships.
Market Dynamics
Adaptive protocol complexity is forcing sponsors to abandon fixed-price contracts in favor of hybrid risk-sharing arrangements that transfer enrollment and timeline risk to contract research organizations.
Growth Catalysts
- EMA Clinical Trials Regulation:The harmonized EU submission portal reduces redundant national filings, accelerating study startup timelines across member states.
- Oncology pipeline expansion:Biopharmaceutical sponsors require specialized Phase I dose-escalation expertise for bispecific antibodies and cell therapies.
- Decentralized trial technology:Remote patient monitoring and direct-to-patient drug delivery compress enrollment cycles for rare disease indications.
Market Restraints
- Principal investigator scarcity:Qualified investigators concentrate in Boston, Basel, and Singapore, creating site access bottlenecks for competitive therapeutic areas.
- Specialized labor costs:Clinical pharmacologists and adaptive trial statisticians command compensation premiums that inflate service provider operating margins.
- FDA safety reporting burden:Expedited IND safety update requirements extend data management timelines and require redundant pharmacovigilance staffing.
Strategic Opportunities
- Japan's PMDA regulatory pathway:The Sakigake designation system creates first-mover advantages for sponsors outsourcing early feasibility studies to local Japanese sites.
- Real-world evidence integration:Convergence of electronic health record networks with trial data capture enables synthetic control arms for rare disease studies.
- Latin American site expansion:Brazil's ANVISA and Mexico's COFEPRIS offer accelerated review timelines for infectious disease and vaccine protocols.
Industry Challenges
- Legacy data system interoperability:Sponsor electronic data capture platforms require custom API development to interface with CRO risk-based monitoring dashboards.
- Quality assurance talent gaps:Experienced clinical research associates with centralized monitoring certification remain scarce relative to demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Early Phase Clinical Trial Outsourcing Market |
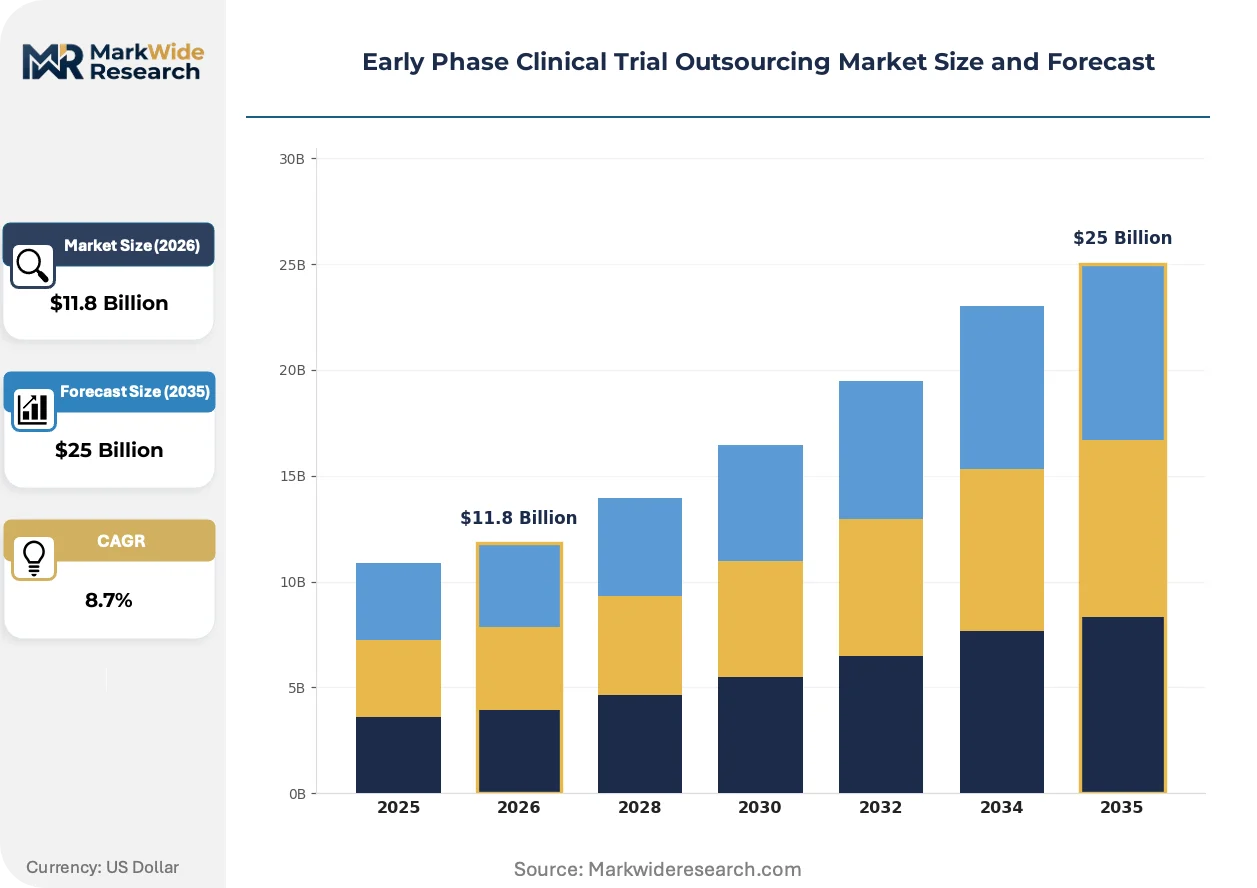
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $25 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Monitoring, Data Management, Regulatory Affairs, Patient Recruitment End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Contract Research Organizations Study Phase: Phase I, Phase II, Phase I/II, Early Feasibility Delivery Model: Fixed-Price, Time and Materials, Fee-for-Service, Hybrid |
| Companies Covered | IQVIA Inc., Charles River Laboratories, Covance Inc., Syneos Health, ICON plc, Parexel International, Laboratory Corporation of America Holdings, Medpace Holdings, Inc., Wuxi Apptec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Early Phase Clinical Trial Outsourcing Market Shifts & Advancements
Digital infrastructure is compressing study timelines while regulatory convergence across FDA and EMA frameworks elevates data integrity standards for outsourced execution.
Distributed clinical trial platforms is virtualizing patient touchpoints through telemedicine visits, wearable biosensors, and direct-to-home investigational product distribution. Mid-sized biotech sponsors are adopting these capabilities fastest to access geographically dispersed patient populations. The technology is virtualizing site selection criteria, enabling sponsors to recruit from primary care networks rather than academic medical centers alone.
FDA's Project Optimus initiative is reshaping dose-finding methodology by requiring randomized comparisons across multiple dose levels rather than traditional 3+3 escalation designs. Oncology sponsors must now incorporate expansion cohorts and biomarker stratification into Phase I protocols. This shift most affects dose-escalation studies for targeted therapies, where CROs are retraining biostatisticians in model-informed drug development approaches.
Sponsor procurement teams are unbundling full-service contracts into functional service provider arrangements that separate patient recruitment from data management and biostatistics. Large pharmaceutical companies are driving this fragmentation to benchmark unit costs across specialized vendors. The unbundling is most advanced in the United States, where sponsor procurement organizations have matured their vendor oversight capabilities.
Early Phase Clinical Trial Outsourcing Market Segmentation
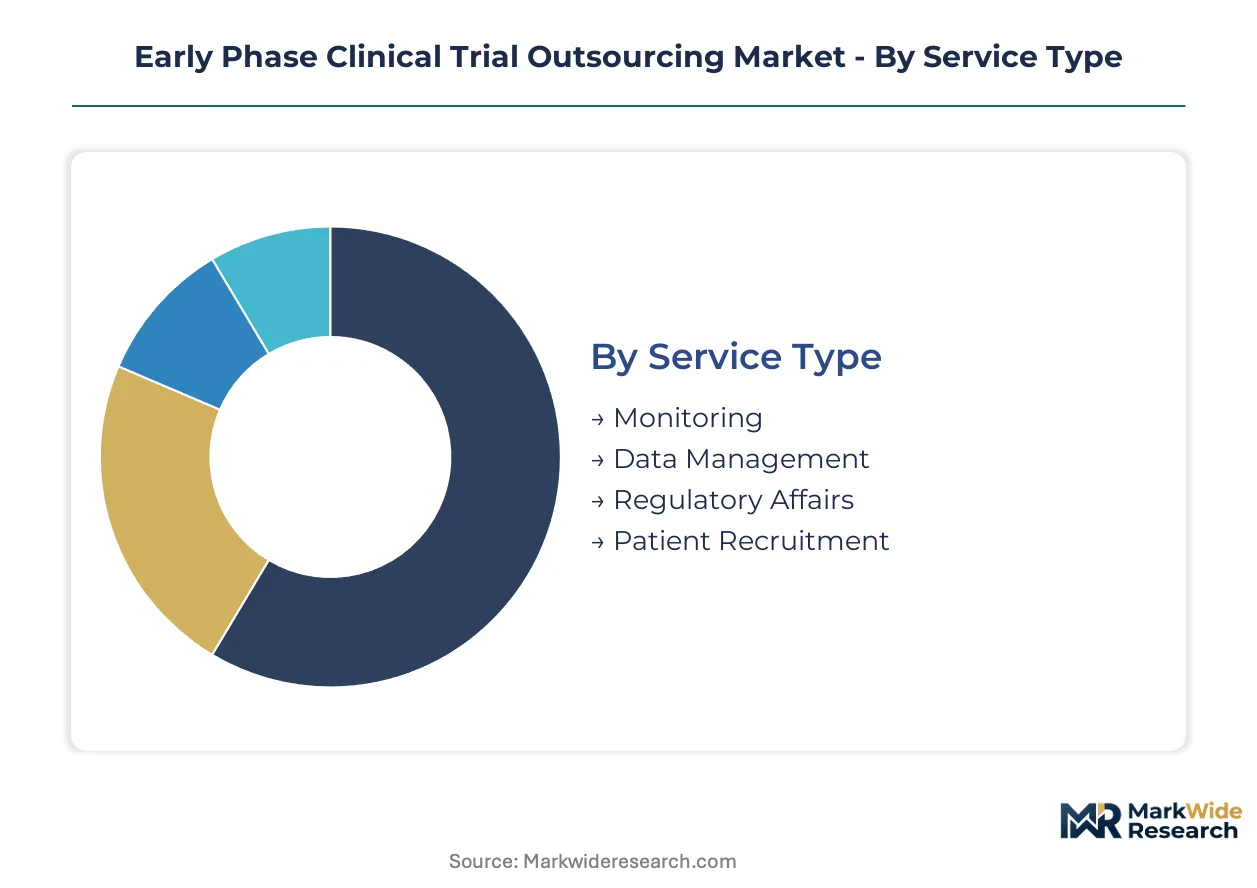
Service complexity and regulatory intensity vary sharply across early-phase trial activities. Sponsors select outsourcing partners based on therapeutic specialization, enrollment velocity requirements, and risk-sharing appetite for adaptive protocol designs.
Service Type:
After-sales service intensity peaks in monitoring and patient recruitment, where CROs maintain continuous site relationships throughout study execution and beyond database lock.
- Monitoring:On-site and remote oversight of investigator compliance, source data verification, and protocol deviation management. Demand concentrates among oncology sponsors running multi-cohort dose-escalation studies across Boston, Basel, and Singapore investigator clusters, where FDA inspection readiness requirements elevate quality assurance staffing ratios.
- Patient Recruitment:Site identification, pre-screening, and enrollment acceleration through direct-to-patient campaigns and physician network activation. Biotechnology sponsors in rare disease indications drive fastest adoption, as decentralized trial platforms compress geographic barriers to participant access.
- Data Management:Electronic data capture configuration, database lock, and CDISC-compliant dataset preparation.
- Regulatory Affairs:IND/CTA compilation, safety report submission, and agency correspondence management.
By volume, monitoring leads. By growth pace, patient recruitment is ahead.
End User:
Cost tier segmentation separates capital-constrained emerging biotech from resource-dense pharmaceutical procurement organizations.
- Pharmaceutical Companies:Large sponsors with established vendor qualification programs and multi-study master service agreements. These organizations unbundle contracts into functional service provider arrangements to benchmark unit costs across specialized vendors, particularly in the United States where procurement maturity is highest.
- Biotechnology Firms:Mid-cap and emerging sponsors lacking internal clinical operations infrastructure. Cell therapy and bispecific antibody developers in Cambridge, Massachusetts and South San Francisco represent the fastest-expanding demand pool, as accelerated approval pathways compress development timelines.
- Academic Institutions:University medical centers conducting investigator-initiated trials with limited commercial sponsorship.
- Contract Research Organizations:Subcontracting arrangements where full-service providers delegate specialized functions to niche vendors.
Pharmaceutical companies dominate contract value. Biotechnology firms are climbing the fastest.
Study Phase:
Application-driven segmentation aligns with regulatory milestone requirements and safety database complexity.
- Phase I:First-in-human and dose-escalation studies establishing safety and pharmacokinetic profiles. Traditional 3+3 designs persist for small molecules, though FDA Project Optimus is forcing randomized multi-dose comparisons for oncology targeted therapies, expanding biostatistician demand.
- Phase I/II:Seamless adaptive designs incorporating efficacy signals and biomarker stratification. Sponsors pursuing accelerated approval pathways in immuno-oncology and gene therapy drive steepest expansion, as these protocols require specialized statistical modeling and expansion cohort management.
- Phase II:Proof-of-concept studies with defined patient populations and preliminary efficacy endpoints.
- Early Feasibility:Initial device or combination product evaluations in limited patient cohorts.
Phase I commands the largest revenue base. Phase I/II adaptive designs are gaining share fastest.
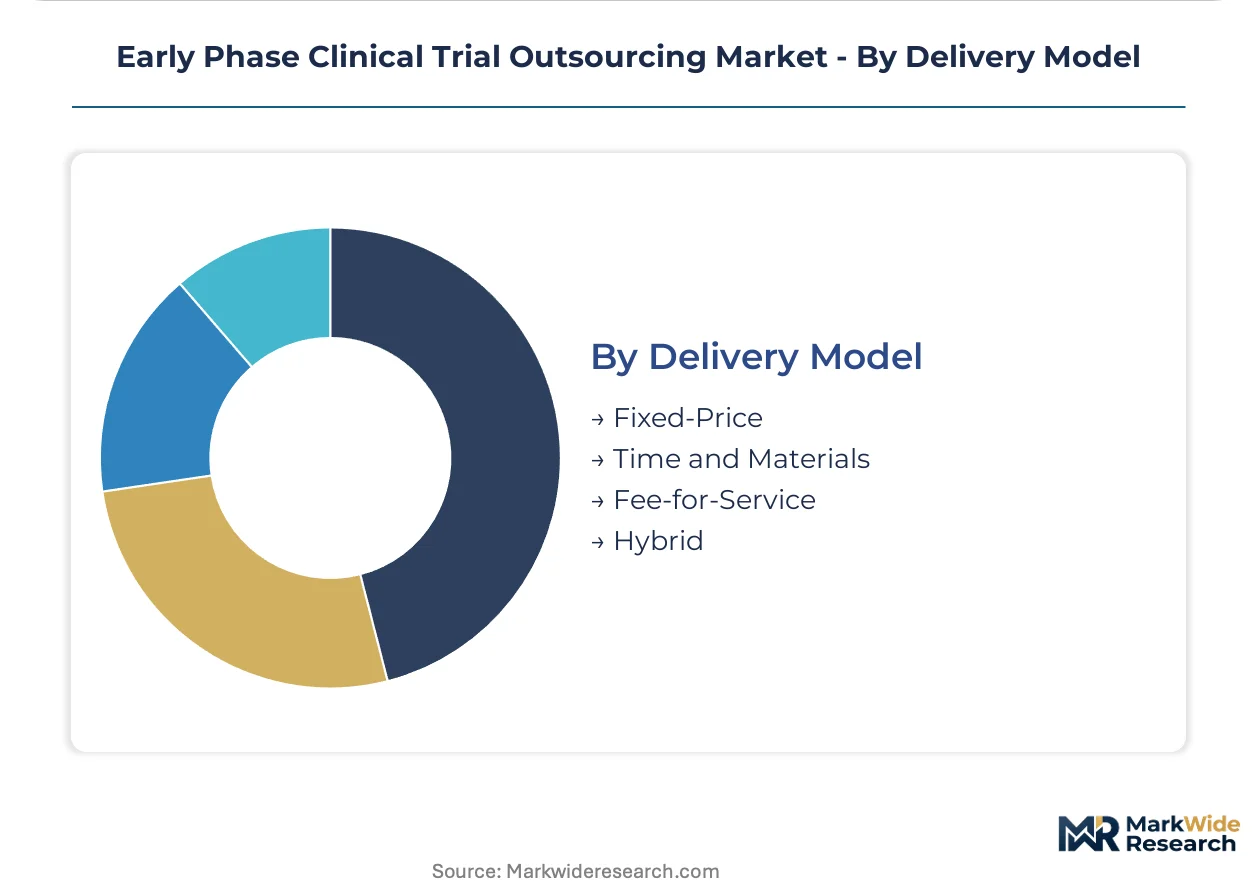
Delivery Model:
Customer type and risk tolerance determine contracting structure selection across sponsor portfolios.
- Hybrid:Blended arrangements combining fixed milestones with variable enrollment-based fees. Large pharmaceutical sponsors favor this structure for complex adaptive protocols, transferring timeline risk to CROs while retaining cost predictability for standard activities.
- Fee-for-Service:Unit-based pricing for discrete activities such as monitoring visits or data queries. Emerging biotech sponsors prefer this model for early feasibility studies with undefined scope, preserving cash flow flexibility.
- Fixed-Price:Comprehensive lump-sum contracts for well-defined protocol scopes with limited adaptation.
- Time and Materials:Hourly or daily rates for advisory and consulting engagements.
Hybrid models lead by contract value. Fee-for-service arrangements are expanding most quickly among capital-constrained sponsors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based contract research organizations export early-phase clinical trial services to biopharmaceutical sponsors across Western Europe and Japan, with cross-border regulatory harmonization accelerating contract flows through standardized ICH-GCP frameworks.
United States
Biotechnology clusters in Cambridge and South San Francisco drive concentrated demand for Phase I/II adaptive designs. FDA's Project Optimus initiative mandates randomized multi-dose comparisons for oncology targeted therapies, elevating biostatistician requirements. Greater Boston anchors the investigator site network, with Massachusetts General Hospital and Dana-Farber Cancer Institute hosting dose-escalation studies for bispecific antibodies.
Germany
EMA's Clinical Trials Regulation harmonizes submission procedures across member states, reducing redundant national filings for sponsors. The Paul-Ehrlich-Institute enforces stringent pharmacovigilance standards for first-in-human studies. Heidelberg and Berlin concentrate Phase I units within university hospital networks, with Charité Universitätsmedizin Berlin operating dedicated early-phase facilities for immuno-oncology protocols.
Switzerland
Basel's pharmaceutical hub generates sustained outsourcing demand from Roche and Novartis development pipelines. Swissmedic maintains accelerated review pathways for innovative therapies through its Marketing Authorization with Rapid Access scheme. The Basel-Stadt canton clusters specialized clinical pharmacology units, with Basel University Hospital conducting integrated non-clinical and early clinical programs for cell therapies.
United Kingdom
Medicines and Healthcare products Regulatory Agency's Innovative Licensing and Access Pathway compresses timelines for breakthrough therapies. The MHRA's standalone status post-Brexit requires sponsors to maintain separate UK regulatory submissions. London and Cambridge concentrate adaptive trial expertise, with the Francis Crick Institute supporting biomarker-stratified protocol designs.
Japan
PMDA's Sakigake designation system creates first-mover advantages for sponsors conducting early feasibility studies. The Pharmaceuticals and Medical Devices Agency prioritizes review resources for regenerative medicine and gene therapy candidates. Tokyo and Osaka metropolitan areas host specialized Phase I facilities, with the National Cancer Center Hospital East operating dedicated units for oncology dose-escalation studies.
Early Phase Clinical Trial Outsourcing Market Competitive Landscape
On the supply side, the industry is consolidating around full-service providers with integrated non-clinical and clinical capabilities. Tiered competition separates global platform operators from specialized regional boutiques and therapeutic-focused niche players. Strategic archetypes include integrated laboratory-to-clinic conglomerates, decentralized trial technology enablers, and adaptive design statistical specialists. Dominant competitive moves encompass geographic site network expansion and risk-based monitoring technology licensing.
Among publicly traded full-service providers, IQVIA Inc., Charles River Laboratories, and Medpace Holdings, Inc. exemplify distinct strategic positioning within the competitive hierarchy. IQVIA represents the data-integrated platform archetype, leveraging real-world evidence infrastructure alongside clinical execution. Charles River Laboratories anchors the laboratory-to-clinic integrated model, spanning non-clinical toxicology through early human studies. Medpace Holdings occupies the full-service control position, maintaining protocol design through final study report delivery under unified management.
| Leading Market Players |
|---|
| IQVIA Inc. |
| Charles River Laboratories |
| Covance Inc. |
| Syneos Health |
| ICON plc |
| Parexel International |
| Laboratory Corporation of America Holdings |
| Medpace Holdings, Inc. |
| Wuxi Apptec |
| Others |
Supply & Pricing Matrix
Principal investigator scarcity in Boston, Basel, and Singapore creates site access bottlenecks that compress pricing tiers while forcing sponsors toward hybrid risk-sharing contracts. This single-source dependency on specialized clinical pharmacologists and adaptive trial statisticians simultaneously widens premium-standard spreads and reshapes CRO network investments toward decentralized trial infrastructure.
Pricing Analysis
Legacy electronic data capture platforms versus centralized monitoring dashboards versus AI-enabled risk-based quality management systems stratify service pricing across three tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with FDA inspection readiness certification and therapeutic specialization (oncology dose-escalation expertise) driving differentiation. Cost compression in standard-tier monitoring services is intensifying because sponsor procurement teams unbundle full-service contracts to benchmark unit costs. Emerging biotechnology firms exhibit highest price sensitivity due to cash flow constraints, while large pharmaceutical procurement organizations prioritize timeline certainty over unit cost.
Supply Chain Analysis
Extended payment terms from sponsor procurement teams now reach 90-120 days, forcing mid-sized CROs to rely on supply-chain finance facilities to maintain site network liquidity. Geographic supply concentration centers on the United States, Germany, and Switzerland, where specialized Phase I units cluster within academic medical centers and university hospital networks. Raw material dependencies include clinical pharmacologist labor pools, adaptive trial biostatisticians, and centralized monitoring technology licenses. Single-source vulnerability runs through qualified investigator sites in Greater Boston and Basel-Stadt canton. Distribution runs through master service agreements with tiered subcontracting to regional site networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adaptive protocol complexity fragments the vendor landscape, creating specialized niches for statistical modeling boutiques and decentralized trial technology enablers alongside integrated full-service platforms.
For Market Incumbents: Build therapeutic expertise moats in immuno-oncology dose-escalation and cell therapy early feasibility studies. Acquire adaptive design biostatistics boutiques in Cambridge and South San Francisco to preempt sponsor unbundling. Expand centralized monitoring certification programs to defend against sponsor procurement benchmarking initiatives. For New Entrants and Emerging Players: Build out Latin American site networks in Brazil and Mexico, where ANVISA and COFEPRIS offer accelerated review timelines for infectious disease protocols. Target rare disease patient recruitment through direct-to-patient campaigns and wearable biosensor integration, the most penetrable segment for virtualized trial platforms. Pursue functional service provider arrangements with mid-cap biotech sponsors seeking cash flow flexibility. For Investors and Strategic Acquirers: FDA's Project Optimus dose-finding requirements reshape the acquisition landscape toward biostatistics capabilities and model-informed drug development expertise. Five-to-ten-year viability favors CROs with integrated real-world evidence infrastructure and regulatory intelligence across FDA, EMA, and PMDA frameworks. Target acquisition archetype: decentralized trial technology platforms with existing site network relationships. Monitor sponsor procurement team maturity as the signal indicating unbundling velocity and contract fragmentation depth.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Design Capability Buildout | FDA Project Optimus mandates randomized multi-dose comparisons, elevating biostatistician demand. |
| Decentralized Trial Technology Licensing | Remote patient monitoring compresses enrollment cycles for rare disease indications. |
| Site Network Expansion in Japan | PMDA Sakigake designation creates first-mover advantages for early feasibility studies. |
| Real-World Evidence Infrastructure Integration | Electronic health record convergence enables synthetic control arms. |
| Hybrid Risk-Sharing Contract Structuring | Transfers enrollment and timeline risk to CROs for complex adaptive protocols. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across drug development executives at biotechnology and pharmaceutical sponsors, regulatory affairs leads managing IND and CTA submissions, clinical operations directors overseeing site selection, and procurement officers negotiating master service agreements. Secondary validation drew from FDA Investigational New Drug filings, EMA Clinical Trials Regulation implementation guidance, ClinicalTrials.gov protocol registrations, and ICH-GCP framework updates. Bottom-up service revenue modeling and top-down sponsor outsourcing spend analysis were triangulated to cross-validate market sizing.
Calibration against historical contract values and announced study awards anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type (monitoring, patient recruitment, data management, regulatory affairs), end user (pharmaceutical, biotechnology, academic), study phase (Phase I, Phase I/II adaptive, Phase II), and delivery model (hybrid, fee-for-service, fixed-price). CAGRs were derived from sponsor pipeline analysis and CRO capacity expansion announcements, with specific inputs including oncology pipeline expansion rates and decentralized trial technology adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by technology-enabled new entrants or sponsor vertical integration into clinical operations would shift outcomes. Forecasts reflect assumptions regarding regulatory harmonization pace and investigator site capacity constraints. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Preclinical CRO Market
Clinical Research
Real World Evidence Linkage Services Market
Clinical Research
US Clinical Trials Market
Clinical Research
Clinical Trials Outsourcing Market
Clinical Research
Esource and Clinical Trials Market
Clinical Research
Clinical Trial Biorepository and Archiving Solutions Market
Clinical Research
Healthcare Europe Clinical Data Analytics Market
Clinical Research
Biomarker Discovery Outsourcing Services Market
Clinical Research
North America Clinical Trials Market
Clinical Research
Clinical Trial Logistics and Direct-to-Patient Delivery Platforms Market
Clinical Research
Synthetic Clinical Trial Data Market
Clinical Research
Global Clinical Trial Management Systems Market
Clinical Research
Global Clinical Trial Support Services Market
Clinical Research
Global Clinical Trial Supply Market
Clinical Research
Global Virtual Clinical Trials Market
Clinical Research
Patient-Reported Outcome Data Monetization Market