
 Agrochemicals Testing and Inspection Service Market | 2026-2036
Agrochemicals Testing and Inspection Service Market Size, Share, and Industry Trends Forecast 2026-2036
Agrochemicals Testing and Inspection Service Market Intelligence
Buyer concentration among large-scale agricultural operators is broadening the addressable market for bundled testing services. SGS SA leverages its Latin American laboratory network to anchor multi-site contracts with grain traders. Bureau Veritas competes through integrated supply-chain audits that span manufacturing through field application. Eurofins Scientific specializes in chromatography-based residue panels that meet divergent import-country standards.
Agrochemicals testing and inspection services encompass analytical verification of pesticide formulations, residue quantification in food matrices, and soil-chemical profiling against regulatory thresholds, typically employing gas chromatography-mass spectrometry with detection limits at parts-per-billion. These services enable crop-protection manufacturers, distributors, and end-users to demonstrate compliance with maximum residue limits and environmental safety criteria before product registration or shipment. Regulatory compliance services command premium pricing due to jurisdiction-specific documentation burdens, while residue testing volumes expand fastest as import nations tighten enforcement. Laboratory testing dominates value capture given capital intensity, though rapid testing gains traction in field-side pre-harvest screening where turnaround time determines market access.
EPA certification requirements in the United States, REACH and EU Green Deal mandates in Europe, and GB standards administered by SAMR in China collectively elevate testing depth and frequency across export-oriented supply chains. Regulators in Brazil and India are aligning domestic maximum residue limits with Codex Alimentarius benchmarks, multiplying the certificate burden per active ingredient. Stakeholders must monitor divergence between major import jurisdictions, as misaligned residue thresholds threaten to fragment testing protocols and inflate compliance costs for multi-market product portfolios.
Market Dynamics
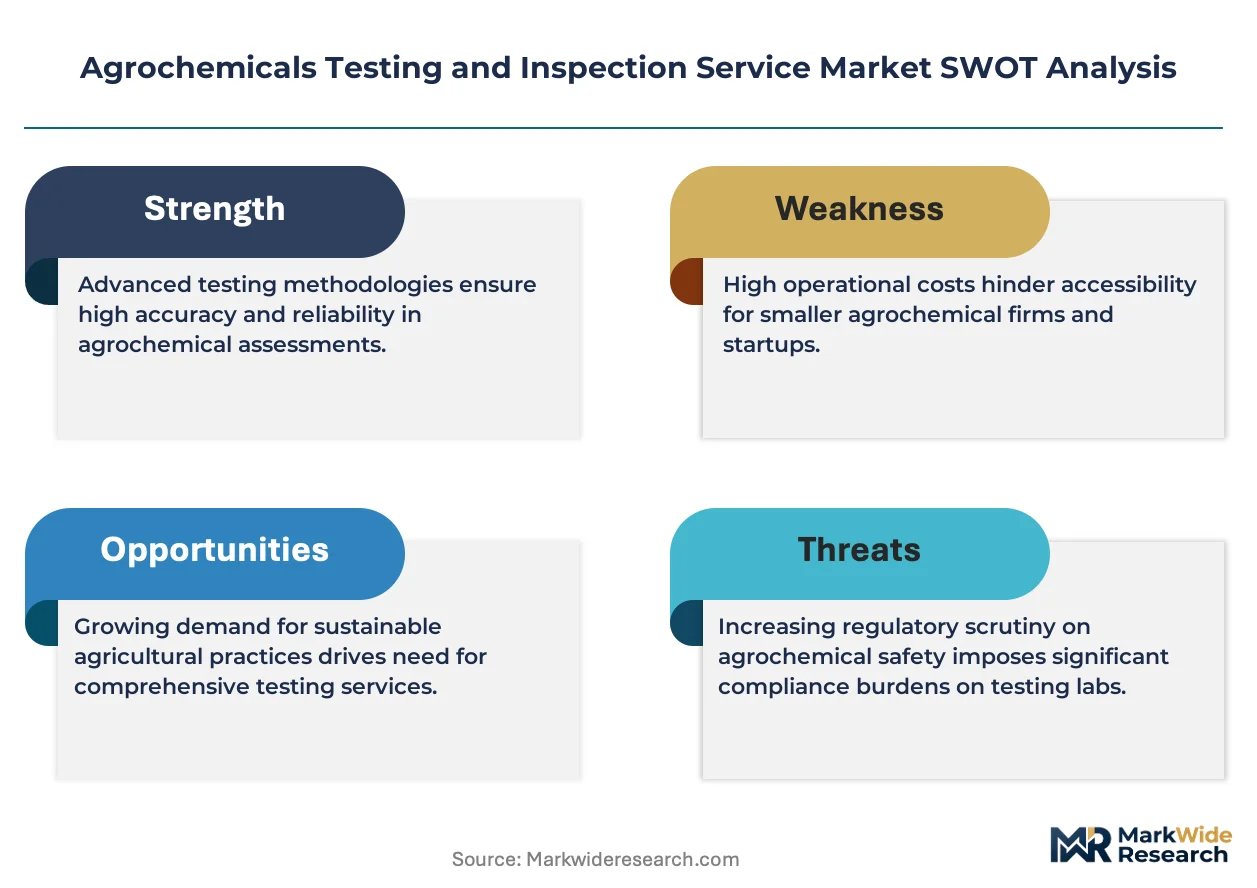
Regulatory divergence between import jurisdictions is fragmenting testing protocols and forcing multi-certification strategies across the agrochemical value chain. Laboratories must now maintain parallel analytical capabilities to serve export markets with non-aligned maximum residue limits.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:The tightened maximum residue limits under this framework are compelling reformulation investments across active ingredient portfolios, expanding contract volumes for residue panel verification.
- Brazilian soybean belt concentration:Large-scale operators in Mato Grosso require integrated soil analysis and regulatory compliance bundles to preserve EU and Chinese market access for their export shipments.
- Gas chromatography-mass spectrometry advancement:Detection thresholds reaching parts-per-billion enable laboratories to certify compliance with the most stringent Codex Alimentarius benchmarks.
Market Restraints
- Capital intensity of chromatography infrastructure:High-performance liquid chromatography and mass spectrometry equipment requires substantial upfront investment, limiting laboratory expansion in secondary agricultural regions.
- Specialty crop seasonality:California residue testing demand spikes unpredictably around export deadlines, creating utilization volatility for fixed-capacity facilities.
- Regulatory misalignment friction:Divergent maximum residue limits between EPA, EFSA, and SAMR standards multiply certificate burdens per active ingredient without harmonization mechanisms.
Strategic Opportunities
- Field-side rapid testing deployment:Portable immunoassay and biosensor technologies enable pre-harvest screening at farm gate, compressing turnaround time for time-sensitive export windows.
- India regulatory alignment:Domestic maximum residue limit convergence with Codex Alimentarius benchmarks is expanding certificate demand for export-oriented crop protection formulations.
- Integrated supply-chain audit bundling:Manufacturers seek single-provider contracts spanning manufacturing quality control through field application verification.
Industry Challenges
- Analytical chemist talent scarcity:Specialized expertise in chromatography method development and regulatory interpretation commands premium compensation, constraining laboratory scaling.
- Multi-jurisdiction certification timelines:Parallel EPA, REACH, and GB standard approvals extend product registration cycles, delaying revenue recognition for testing service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agrochemicals Testing and Inspection Service Market |
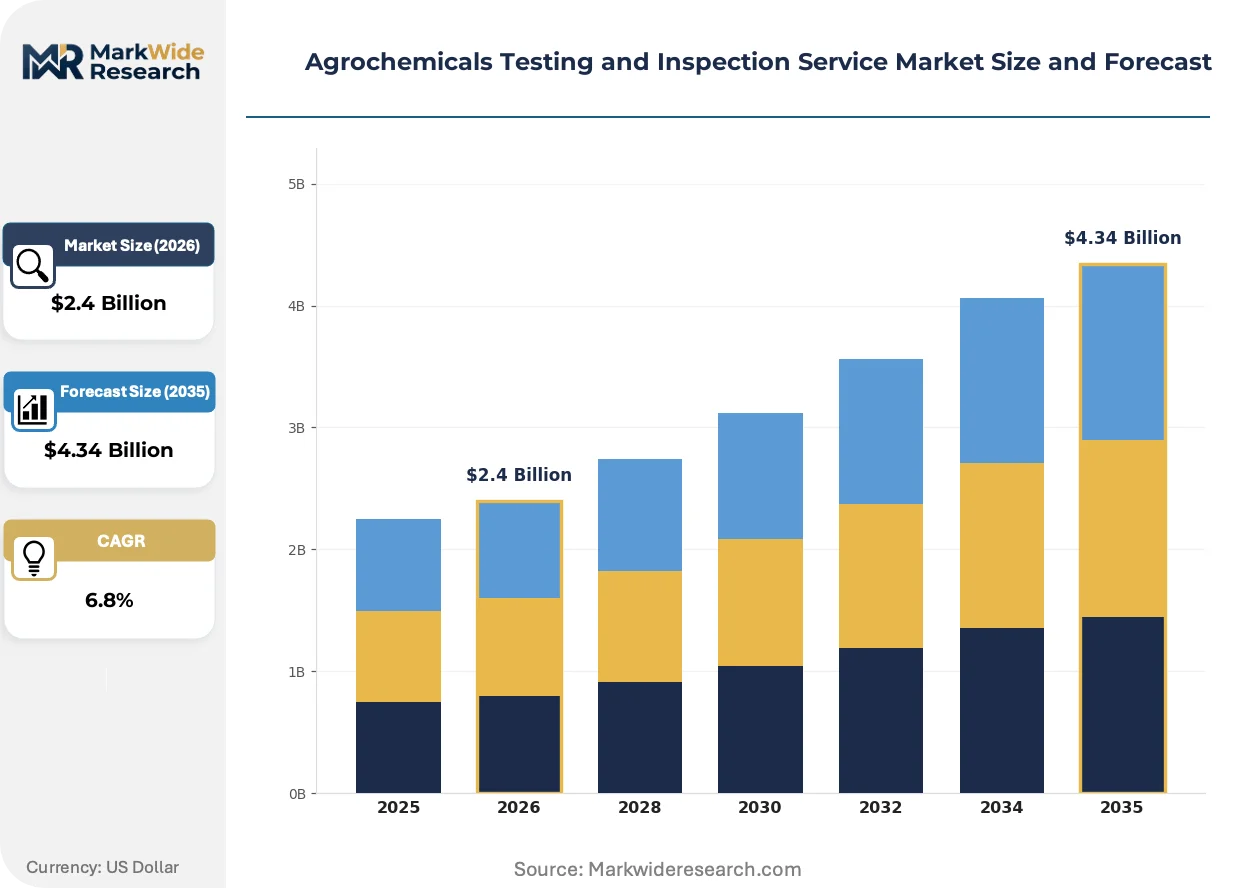
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residue Testing, Quality Testing, Regulatory Compliance, Soil Analysis End Use Industry: Agriculture, Horticulture, Forestry, Turf Management Testing Method: Laboratory Testing, Field Testing, Rapid Testing, Chromatography Certification Type: ISO Certification, EPA Certification, GMP Certification, CQA Certification |
| Companies Covered | Bureau Veritas, TÜV SÜD, SGS SA, HQTS Group, Charles River Laboratories, Eurofins Scientific, ALS Limited, RJ Hill Laboratories Ltd., Intertek Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agrochemicals Testing and Inspection Service Market Strategic Shifts & Innovations
Digital integration of field data with laboratory information management systems is compressing sample-to-certificate timelines and enabling predictive compliance monitoring across growing seasons.
Portable rapid testing equipment is modularizing residue screening workflows by enabling on-site preliminary analysis before laboratory confirmation. Specialty crop producers in California deploy these units for pre-harvest self-monitoring. The technology is modularizing the traditional centralized laboratory model into distributed screening networks.
REACH authorization requirements and EU Green Deal sustainability criteria are extending testing obligations beyond residue quantification to include environmental fate and ecotoxicology endpoints. Formulation manufacturers must now submit expanded dossiers covering degradation pathways and non-target organism effects. European export-oriented suppliers are restructuring product development cycles to accommodate these deeper analytical requirements.
Grain traders and large-scale cooperatives are consolidating testing procurement under multi-site contracts with preferred laboratory networks. This concentration displaces fragmented local testing relationships in Brazil's Mato Grosso and Iowa's corn belt. The shift is most visible among export-dependent operators seeking standardized certificate formats across multiple origin points.
Agrochemicals Testing and Inspection Service Market Segmentation
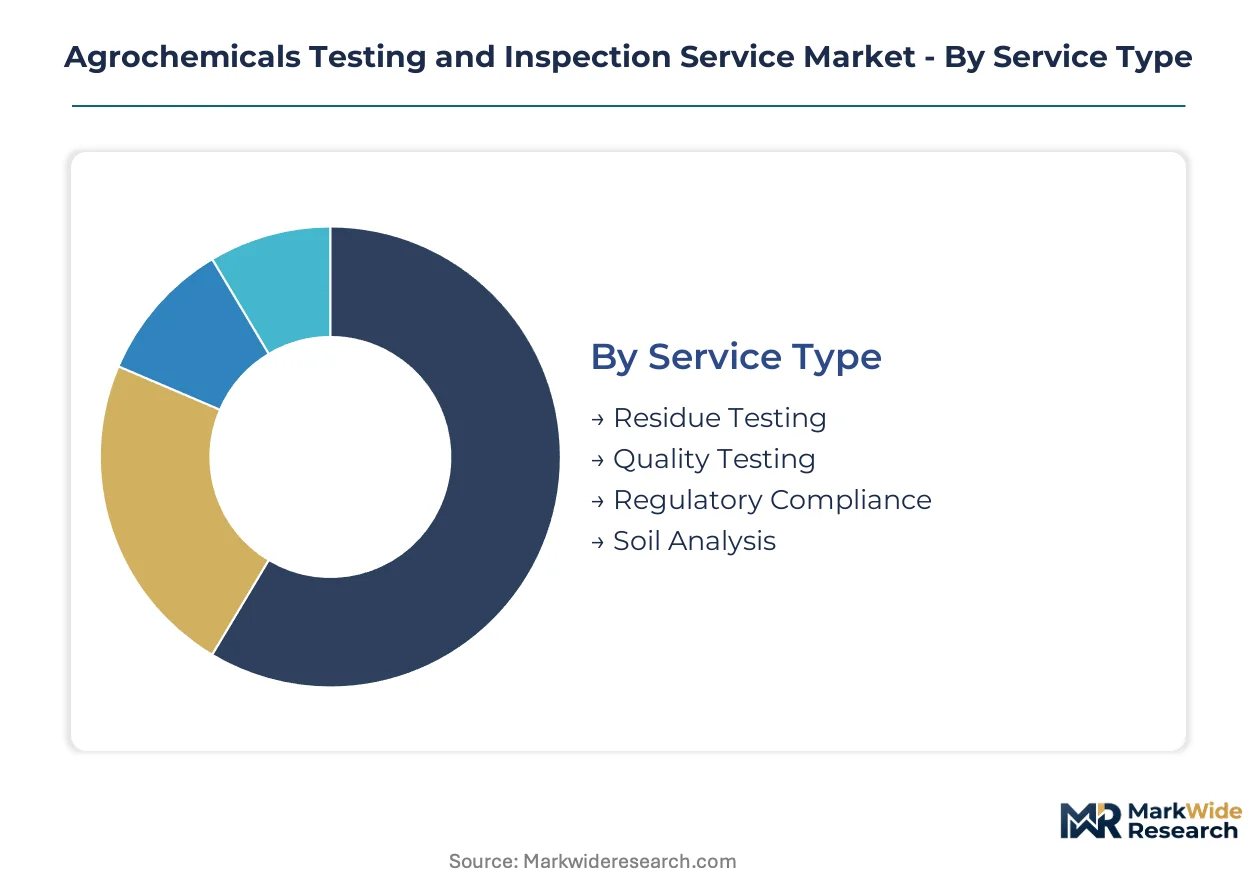
Testing service providers configure analytical portfolios around regulatory jurisdiction, sample throughput requirements, and detection threshold specifications. Segmentation reveals where capital-intensive laboratory infrastructure commands premium pricing versus commoditized field-screening alternatives.
Service Type:
Standardized protocols dominate high-volume residue panels, while bespoke method development serves specialty crop exporters with non-aligned import-country thresholds.
- Residue Testing:Chromatography-based quantification of pesticide metabolites in food matrices at parts-per-billion detection limits. California specialty crop producers and Brazil's Mato Grosso soybean operators drive contract volumes ahead of EU and Chinese export deadlines.
- Quality Testing:Verification of active ingredient concentration, formulation stability, and physical-chemical properties against manufacturer specifications. Agrochemical distributors in India require batch certification under tightening BIS alignment with Codex Alimentarius benchmarks.
- Regulatory Compliance:Documentation preparation for EPA, ECHA, and SAMR registration dossiers including toxicology and environmental fate studies.
- Soil Analysis:Chemical profiling of nutrient status, heavy metal contamination, and pesticide persistence to inform application protocols.
Most installed capacity flows through Residue Testing. Expansion is steepest in Regulatory Compliance.
End Use Industry:
Volume concentration tracks export-oriented crop systems where market access depends on certificate documentation, while domestic-serving segments tolerate longer turnaround times.
- Agriculture:Large-scale grain and oilseed operations requiring integrated testing bundles spanning soil through final shipment. Brazilian cooperatives consolidate procurement under multi-site contracts with preferred laboratory networks to standardize certificate formats across origin points.
- Horticulture:Specialty fruit and vegetable producers facing compressed pre-harvest windows and divergent EU, US, and Chinese maximum residue limits. California's Central Valley operators deploy rapid field-screening before laboratory confirmation.
- Forestry:Plantation timber and pulpwood operations monitoring herbicide drift and soil accumulation.
- Turf Management:Golf course and sports field maintenance programs verifying glyphosate and phenoxy herbicide applications against local runoff regulations.
Agriculture captures the majority of contract value. Horticulture is climbing the fastest as import thresholds tighten.
Testing Method:
Capital requirements and detection precision separate centralized laboratory infrastructure from distributed field deployment.
- Laboratory Testing:Gas chromatography-mass spectrometry and high-performance liquid chromatography delivering definitive quantitative results for regulatory submission. Eurozone exporters depend on EFSA-compliant methods with full method validation documentation.
- Chromatography:Advanced separation techniques enabling simultaneous multi-residue panels covering hundreds of active ingredients. The technology commands premium pricing for complex matrices like tea and spices with high co-extractable interference.
- Rapid Testing:Portable immunoassay and biosensor technologies for preliminary screening at farm gate or import checkpoint.
- Field Testing:On-site spectroscopic and electrochemical methods for immediate qualitative assessment before laboratory referral.
Laboratory Testing anchors revenue capture. Rapid Testing is gaining share fastest as pre-harvest self-monitoring expands.
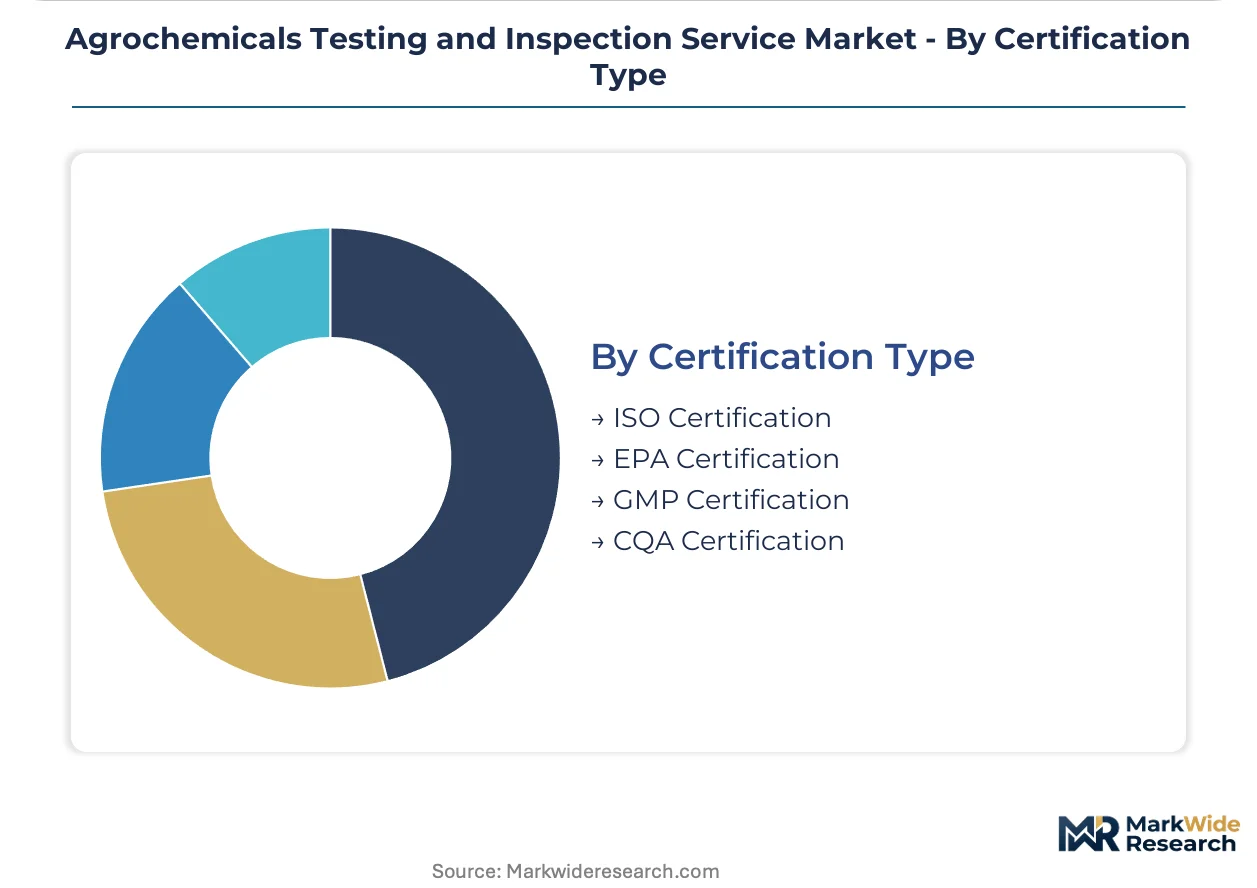
Certification Type:
Jurisdiction-specific documentation burdens determine pricing tiers, with multi-market portfolios requiring parallel certification tracks.
- EPA Certification:United States registration requirements covering toxicology, environmental fate, and residue chemistry studies. Formulation manufacturers seeking US market access face extended review timelines that delay testing service revenue recognition.
- ISO Certification:Laboratory quality management accreditation enabling mutual recognition across export destinations. ISO 17025 underpins contract eligibility for EU grain traders requiring standardized analytical competence.
- GMP Certification:Good Manufacturing Practice verification for production facility audits and batch release documentation.
- CQA Certification:Certified Quality Auditor credentials for supply-chain inspection and manufacturing compliance verification.
ISO Certification supports the broadest cross-border recognition. EPA Certification shows steepest volume growth as US import enforcement intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil generates larger contract volumes for integrated soil-residue bundles than Germany, where EU Green Deal compliance drives premium analytical services. India and China are expanding certificate demand through regulatory alignment with Codex Alimentarius benchmarks. California specialty crop producers face compressed pre-harvest testing windows distinct from Midwest grain operations.
United States
EPA certification requirements for pesticide registration sustain demand for toxicology and environmental fate studies. The Farm Bill's conservation compliance provisions link soil testing to federal crop insurance eligibility. California's Central Valley operators deploy rapid field-screening before laboratory confirmation ahead of EU and Chinese export deadlines.
Brazil
Large-scale soybean operators in Mato Grosso require bundled soil analysis and regulatory compliance services to preserve EU and Chinese market access. ANVISA is aligning domestic maximum residue limits with Codex Alimentarius benchmarks, multiplying certificate burdens per active ingredient. São Paulo-based grain traders consolidate procurement under multi-site contracts with preferred laboratory networks.
Germany
REACH authorization requirements and EU Green Deal sustainability criteria extend testing obligations to environmental fate and ecotoxicology endpoints. EFSA-compliant chromatography methods with full validation documentation command premium pricing. Bavarian formulation manufacturers restructure product development cycles to accommodate deeper analytical requirements.
China
GB standards administered by SAMR elevate testing depth for export-oriented crop protection formulations. The country's dual carbon goals intensify scrutiny of pesticide degradation pathways and non-target organism effects. Yangtze River Delta agrochemical manufacturers expand residue panel verification to maintain EU and US market access.
India
BIS alignment with Codex Alimentarius benchmarks expands certificate demand for export-oriented crop protection formulations. Domestic maximum residue limit convergence multiplies testing volumes for active ingredient portfolios. Maharashtra-based agrochemical distributors require batch certification under tightening quality standards.
Agrochemicals Testing and Inspection Service Market Key Industry Players
European laboratory networks anchor one tier; Latin American specialists hold regional compliance expertise. The market structures around three tiers: integrated multinational networks, regional testing specialists, and rapid field-screening technology providers. Swiss and French-originated entities exemplify the bundled audit archetype. German and UK-based laboratories represent chromatography-intensive residue panels. Competitive moves concentrate on multi-site contract consolidation and portable technology licensing.
Within the integrated network tier, SGS SA and Bureau Veritas occupy positions spanning manufacturing quality control through field application verification. Eurofins Scientific exemplifies the chromatography-specialist archetype with residue panels meeting divergent import-country standards. These three entities represent contrasting geographic origins and service configurations across the value chain.
| Leading Market Players |
|---|
| Bureau Veritas |
| TÜV SÜD |
| SGS SA |
| HQTS Group |
| Charles River Laboratories |
| Eurofins Scientific |
| ALS Limited |
| RJ Hill Laboratories Ltd. |
| Intertek Group plc |
| Others |
Cost & Logistics Intelligence
Large-scale grain traders and cooperatives in Brazil's Mato Grosso and Iowa's corn belt are consolidating procurement under multi-site contracts, forcing laboratories to compete on bundled pricing for integrated soil-residue-compliance packages rather than standalone test rates.
Pricing Analysis
Capacity additions in Germany and Switzerland are reshaping price floors for chromatography-intensive residue panels. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-compliant validated methods from rapid field-screening alternatives. Cost compression in rapid testing is intensifying because portable immunoassay manufacturers are licensing technology to agricultural cooperatives for pre-harvest self-monitoring. Small-scale horticulture operators in California's Central Valley show highest price sensitivity, while export-oriented soybean conglomerates in Brazil accept premium rates for guaranteed turnaround times ahead of Chinese customs deadlines.
Supply Chain Analysis
ISO 17025 accreditation and EPA certification requirements gate laboratory network eligibility for multi-site contracts with grain traders. Chromatography equipment manufacturing concentrates in Germany, the United States, and Japan. High-purity analytical reagents and certified reference standards for pesticide metabolites draw from specialized chemical suppliers in Switzerland and the United Kingdom. Single-source vulnerability exists for gas chromatography-mass spectrometry consumables from German original equipment manufacturers. Distribution runs through regional laboratory hubs that batch samples for centralized chromatography confirmation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The agrochemicals testing market functions as a regulatory compounder where EU Green Deal Farm to Fork maximum residue limit tightening generates recurring contract volume expansion across reformulation cycles.
For Market Incumbents: Cement multi-site contract renewal rates by embedding field-side rapid testing units directly into large-scale cooperative operations. Lock in analytical chemist talent through specialized chromatography method development training programs before emerging portable biosensor providers erode laboratory confirmation volumes. Prioritize backward integration into certified reference standard production to secure margin control over consumables.
For New Entrants and Emerging Players: The price-point gap between premium EFSA-validated chromatography panels and economy-tier rapid field-screening creates white-space for mid-tier laboratories offering expedited turnaround with documented method equivalency. Target India's Maharashtra and Gujarat agricultural belts where BIS alignment with Codex Alimentarius benchmarks is expanding certificate demand faster than established laboratory capacity. Deploy partnership-based go-to-market models with regional grain trader associations rather than direct field sales.
For Investors and Strategic Acquirers: Integrated multinational testing networks are the most active acquirer in this space, seeking chromatography-specialist laboratories to fill geographic gaps in Latin American coverage. Long-term viability rests on regulatory divergence persistence between EPA, EFSA, and SAMR standards that sustains multi-certification demand. Acquisition target archetype: regional laboratories with established ANVISA relationships in Brazil's Mato Grosso corridor. The signal to watch is Codex Alimentarius harmonization progress that could collapse parallel certification requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Network Expansion | Multi-site contracts with Brazilian grain traders require geographic coverage across Mato Grosso and São Paulo corridors. |
| Portable Technology Licensing | Immunoassay and biosensor partnerships enable pre-harvest screening penetration into California specialty crop operations. |
| Regulatory Compliance Bundling | Integrated soil-residue-documentation packages command premium pricing from export-dependent agricultural cooperatives. |
| Analytical Talent Acquisition | Chromatography method development expertise scarcity constrains laboratory scaling in secondary agricultural regions. |
| Certification Investment | ISO 17025 and EPA accreditation enable contract eligibility for EU grain traders requiring standardized competence. |
Research Approach
Coverage spans Brazil, the United States, Germany, China, and India, with primary inputs from each region combining structured interviews with laboratory operations directors, regulatory affairs managers at agrochemical manufacturers, grain trader procurement leads, and chromatography equipment technical specialists. Secondary validation draws from EPA registration databases, EFSA scientific opinions, ANVISA maximum residue limit notifications, SAMR GB standard publications, and customs trade flow records. Bottom-up testing volume estimates triangulate against top-down market value reconstructions.
Rate-of-change decomposition separates volume expansion from pricing dynamics across the analysis window. Segmentation dimensions modeled include service type, end-use industry, testing method, and certification jurisdiction. CAGRs derive from regression analysis of historical contract volumes against regulatory milestone timing. Industry-specific forecast inputs incorporate EU Green Deal implementation schedules and Codex Alimentarius alignment progress in Brazil and India.
Caveats apply where regulatory harmonization between EPA, EFSA, and SAMR standards could materially shift the outlook by collapsing multi-certification requirements. Forecasts reflect assumptions about continued divergence in maximum residue limits and sustained enforcement intensity at import checkpoints. A model refresh is warranted upon material change in EU Green Deal Farm to Fork strategy implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Testing Services
Seed Testing Services Market
Agricultural Testing Services
Soil Testing Kit Market
Agricultural Testing Services
Europe Feed Testing Market
Agricultural Testing Services
Pesticide Residue Testing Market
Agricultural Testing Services
Pesticide Detection Market
Agricultural Testing Services
Poultry Diagnostic Testing Market
Agricultural Testing Services
Impact Soil Tester Market
Agricultural Testing Services
Soil Sampling Services Market
Agricultural Testing Services
Feed Testing Market
Agricultural Testing Services
Soil Field Testing Equipment Market
Agricultural Testing Services
Plant Nutrient Testing Equipment Market
Agricultural Testing Services
Plant Disease Diagnostic Market
Agricultural Testing Services
Nematode Testing Services Market
Agricultural Testing Services
Agricultural Testing Services Market
Agricultural Testing Services
Rapid Mycotoxin Detection Systems for Grain Handling Facilities Market
Agricultural Testing Services
Soil Erosion Testing Market