
 Pesticide Residue Testing Market | 2026-2036
Pesticide Residue Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Pesticide Residue Testing Market Analysis
Multi-residue panel expansion is reshaping margin distribution across the Pesticide Residue Testing landscape, pulling profitability from single-analyte contracts toward broader screening portfolios. Eurofins Scientific SE leverages its pan-European laboratory network to anchor high-throughput food safety contracts across multiple jurisdictions. Bureau Veritas S.A. competes through integrated supply-chain auditing that bundles residue testing with certification services. SGS S.A. dominates agricultural export corridors by positioning mobile sampling units near major port and processing clusters.
Pesticide residue testing encompasses the analytical detection and quantification of agrochemical remnants in food commodities, environmental matrices, and biological samples using chromatographic separation coupled with mass-selective detection at parts-per-billion sensitivity thresholds. Its primary commercial purpose is to verify compliance with maximum residue limits that govern market access and consumer safety across regulated supply chains. LC-MS and GC-MS instrument segments command the deepest margin pools due to their regulatory acceptance for confirmatory analysis in dispute resolution and border enforcement. Multi-residue testing methods are expanding fastest as laboratories seek operational leverage through single-extraction protocols that replace sequential single-compound workflows.
The European Food Safety Authority, the U.S. Environmental Protection Agency, and the Food and Drug Administration collectively enforce tightening maximum residue limits that directly determine which testing technologies laboratories must deploy to maintain accreditation and commercial viability. REACH and the EU Green Deal's Farm to Fork targets are forcing method upgrades toward broader analyte coverage and lower detection thresholds that legacy immunoassay platforms cannot satisfy. Stakeholders must decide whether to absorb capital costs for LC-MS/MS system upgrades or outsource to consolidated multi-national laboratories that have already deployed next-generation instrumentation.
Market Dynamics
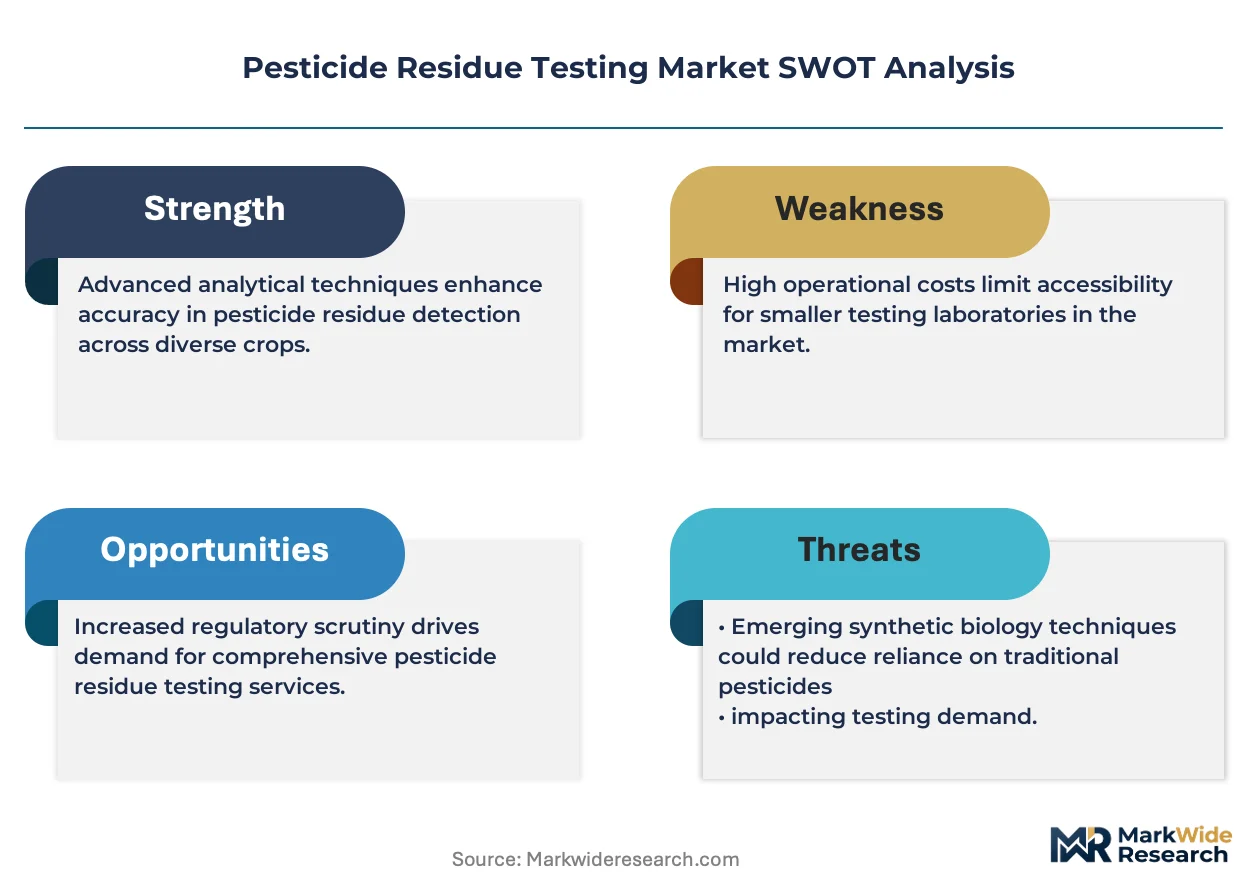
Multi-residue method expansion is compressing the economics of single-analyte testing contracts while concentrating demand among laboratories with high-throughput LC-MS/MS capacity. This structural shift is forcing smaller regional players to either consolidate or exit confirmatory testing entirely.
Growth Catalysts
- EFSA guideline tightening:Lower maximum residue limits across the EU are mandating detection thresholds that only advanced mass spectrometry platforms can reliably achieve, driving instrument replacement cycles.
- Export corridor compliance:Agricultural commodity exporters in Brazil and Argentina require pre-shipment certification to EU and US standards, creating captive demand for accredited third-party testing.
- High-resolution mass spectrometry:Orbitrap and Q-TOF systems enable non-targeted screening that identifies unknown metabolites, expanding contract scope beyond regulated analyte lists.
Market Restraints
- Helium supply volatility:GC-MS operations depend on helium carrier gas sourced primarily from Qatar and the US, where export constraints and price spikes disrupt laboratory operating budgets.
- Reference material scarcity:Certified reference standards for emerging pesticide metabolites face 12-18 month production lead times from European suppliers, delaying method validation.
- Immunoassay platform obsolescence:ELISA and lateral flow devices lack the sensitivity for updated EU MRL compliance, stranding capital in legacy equipment that cannot be repurposed.
Strategic Opportunities
- India food safety modernization:FSSAI implementation of Codex-aligned MRLs for domestic and export markets creates first-mover advantage for laboratories establishing ISO 17025-accredited facilities in Mumbai and Delhi.
- Blockchain-integrated certification:Distributed ledger technology enables real-time traceability from field sampling to laboratory report, commanding premium pricing from organic and specialty crop distributors.
- Biological sample expansion:Human biomonitoring for occupational exposure and dietary intake assessment opens adjacent revenue streams beyond commodity testing for environmental health agencies.
Industry Challenges
- Mass spectrometry specialist scarcity:Method development and troubleshooting require PhD-level analytical chemists, with European and North American laboratories competing for talent against pharmaceutical and clinical diagnostics sectors.
- Cross-border accreditation friction:Mutual recognition agreements between national accreditation bodies remain incomplete, forcing redundant audits for laboratories serving multiple export markets.
- Legacy LIMS integration:Older laboratory information management systems lack API connectivity to modern chromatography data systems, requiring expensive middleware development or full platform replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pesticide Residue Testing Market |
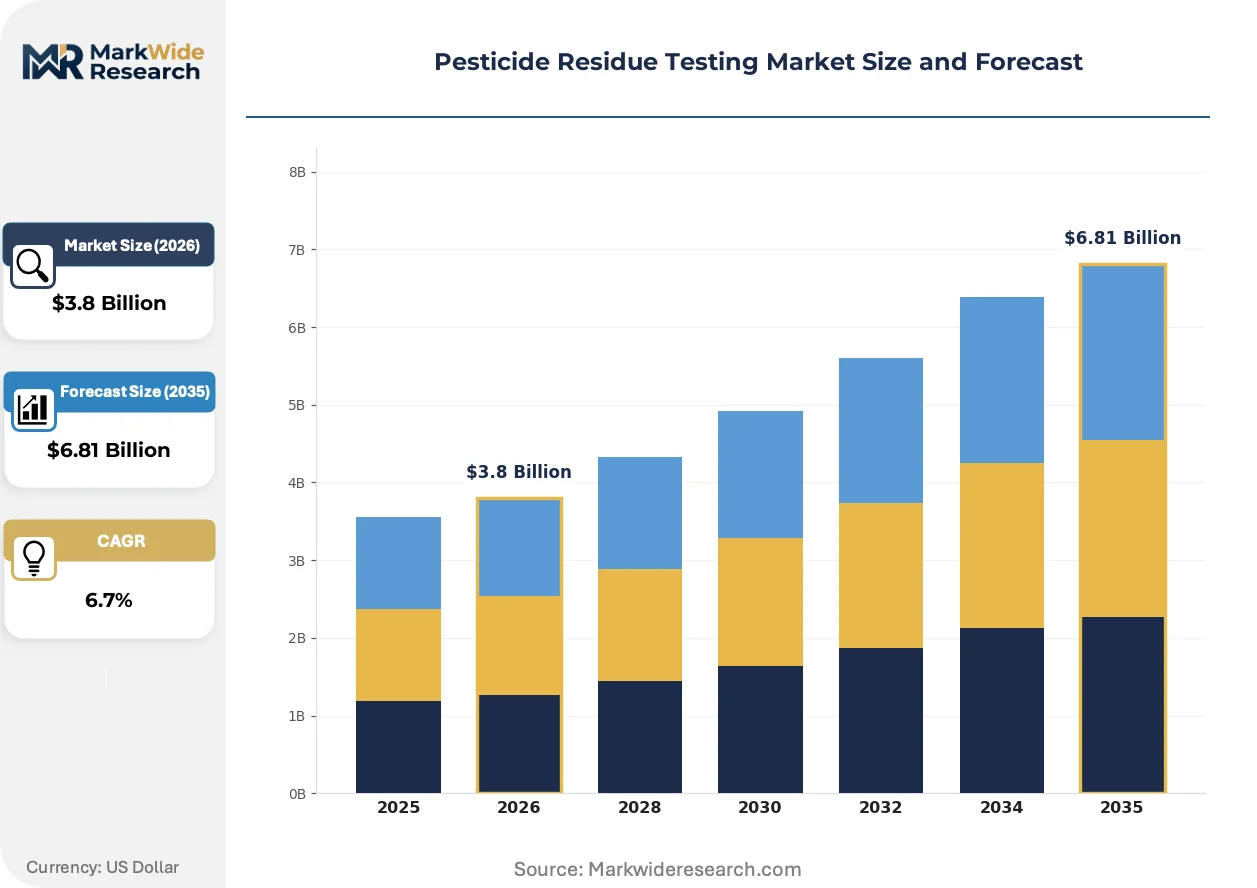
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GC-MS, HPLC, LC-MS, ELISA End User: Agriculture, Food Processing, Laboratories, Environmental Agencies Technology: Chromatography, Mass Spectrometry, Immunoassays, Bioassays Testing Method: Screening, Quantitative Analysis, Qualitative Analysis, Multi-Residue Testing |
| Companies Covered | Eurofins Scientific SE, Bureau Veritas S.A., SGS S.A., Intertek Group plc, ALS Limited, Mérieux NutriSciences, AsureQuality, Silliker, Inc., Microbac Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pesticide Residue Testing Market Emerging Trajectories
Cloud-based data architecture is restructuring how laboratories manage multi-site operations and regulatory submissions. This infrastructure shift enables centralized method development while distributing sample processing to regional hubs.
Artificial intelligence-driven peak integration software is virtualizing the manual review bottleneck that constrains high-throughput screening capacity. Contract laboratories in Germany and the Netherlands are deploying machine learning classifiers to flag suspect chromatograms for analyst confirmation. This automation compresses turnaround times from 72 hours to 24 hours for routine multi-residue panels without sacrificing false negative rates.
REACH authorization requirements for persistent organic pollutants are extending residue testing obligations to environmental matrices and processing equipment surfaces. Food manufacturers in Belgium and the Netherlands must now demonstrate absence of legacy organochlorine compounds in facility swabs and wastewater discharge. This regulatory expansion is pulling industrial hygiene laboratories into food safety accreditation scopes.
Consolidated procurement by retail grocery chains is bundling residue testing with microbiological and allergen screening into single-source contracts. German discount retailers and French hypermarket operators are mandating quarterly panel testing across entire produce categories rather than supplier-specific spot checks. This buyer concentration is squeezing regional laboratories unable to offer integrated food safety service portfolios.
Pesticide Residue Testing Market Segmentation
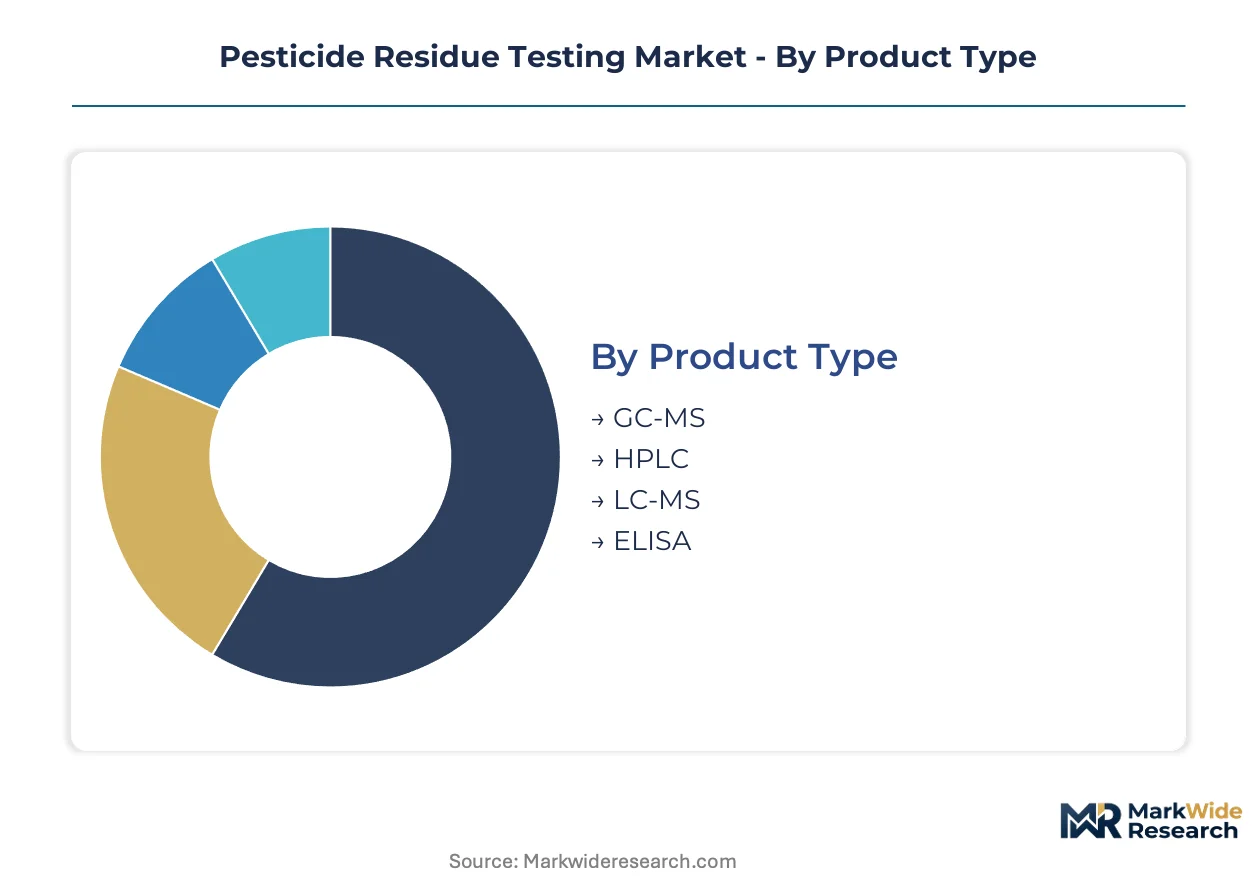
Technology and method selection in pesticide residue testing directly determines regulatory acceptance, detection sensitivity, and operational economics across food safety workflows. Laboratories segment their procurement decisions across instrument platforms, end-use applications, and analytical methodologies to balance capital efficiency against evolving compliance mandates.
Product Type:
Mature chromatographic platforms anchor routine screening workflows while emerging mass spectrometry configurations capture method-upgrade budgets.
- LC-MS:Liquid chromatography-tandem mass spectrometry delivers parts-per-billion sensitivity for polar and thermally labile compounds across multi-residue panels. German food safety laboratories in Berlin and Hamburg are prioritizing LC-MS/MS acquisitions to meet EFSA guideline revisions for lower maximum residue limits.
- GC-MS:Gas chromatography-mass spectrometry remains essential for volatile and semi-volatile organochlorine, organophosphorus, and pyrethroid detection. Helium supply constraints from Qatar and US export bottlenecks are compressing operating margins for laboratories dependent on GC-MS carrier gas.
- HPLC:High-performance liquid chromatography with UV or fluorescence detection serves cost-sensitive screening applications where mass spectrometry confirmatory analysis follows positive findings.
- ELISA:Enzyme-linked immunosorbent assay platforms face obsolescence as EU MRL tightening exceeds ELISA sensitivity thresholds, stranding capital in legacy equipment.
LC-MS retains volume leadership; GC-MS holds the steepest expansion curve in emerging market accreditation programs.
End User:
Procurement authority concentrates differently across customer types, with regulatory compliance intensity varying by supply chain position and export exposure.
- Food Processing:Large-scale processors in North America and Europe are expanding in-house testing protocols to pre-empt regulatory rejection and protect brand equity. These operators demand high-throughput multi-residue panels with 24-hour turnaround commitments.
- Laboratories:Independent and government-affiliated testing facilities compete for accreditation contracts based on ISO 17025 scope breadth and geographic coverage of sampling networks.
- Agriculture:Commercial farming operations and agricultural cooperatives require pre-harvest testing to optimize spray intervals and harvest timing against MRL thresholds.
- Environmental Agencies:Regulatory bodies monitor surface water, soil, and non-target organism exposure, extending residue testing beyond food matrices into ecological risk assessment.
Food Processing commands the largest contract values; Laboratories are climbing the fastest as third-party accreditation consolidates.
Technology:
Platform selection tracks the regulatory acceptance hierarchy, with confirmatory methods commanding premium pricing over screening alternatives.
- Mass Spectrometry:Triple quadrupole and high-resolution Orbitrap systems enable quantitative confirmation with definitive compound identification for dispute resolution and border enforcement.
- Chromatography:Separation science foundations underpin all regulatory methods, with method development expertise concentrated among PhD-level analytical chemists in European and North American laboratory clusters.
- Immunoassays:Antibody-based detection faces displacement as sensitivity requirements tighten, though lateral flow devices persist in field screening applications.
- Bioassays:Whole-organism toxicity testing complements chemical analysis for mechanism-of-action assessment in environmental monitoring programs.
Mass Spectrometry dominates confirmatory revenue; Chromatography maintains the broadest installed base across routine laboratories.
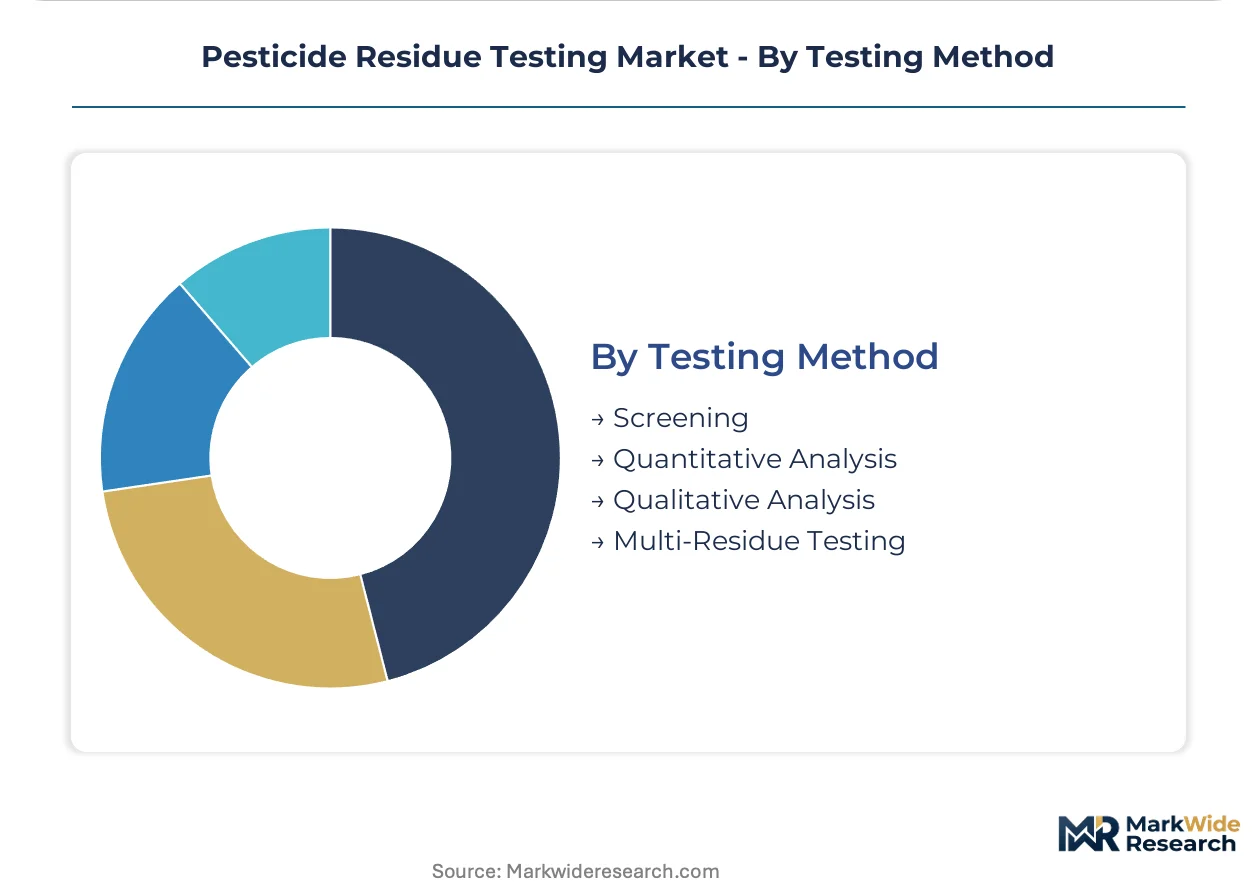
Testing Method:
Method scope determines laboratory throughput economics, with extraction protocol efficiency becoming the critical operational variable.
- Multi-Residue Testing:Single-extraction protocols detecting hundreds of compounds simultaneously are displacing sequential single-analyte workflows. The EU Farm to Fork Strategy accelerates adoption as laboratories seek operational leverage.
- Quantitative Analysis:Definitive concentration measurement against certified reference standards supports regulatory enforcement and trade dispute resolution with legally defensible documentation.
- Screening:Rapid preliminary detection triages samples for confirmatory analysis, reducing mass spectrometry instrument time spent on negative specimens.
- Qualitative Analysis:Presence-absence determination serves investigative and surveillance applications where exact concentration is secondary to detection.
Multi-Residue Testing is gaining share fastest; Quantitative Analysis retains the highest per-sample pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys pesticide residue testing primarily for multi-residue panel verification across European food trade corridors, while Brazil and Argentina concentrate pre-shipment certification for agricultural export compliance, and India channels investment toward domestic food safety modernization for both local consumption and export markets.
Germany
EFSA guideline revisions and the EU Farm to Fork Strategy drive laboratory capacity expansion for lower maximum residue limit detection. The country's central position in European food distribution mandates ISO 17025-accredited multi-residue testing for transshipment verification. Berlin and Hamburg host the densest concentration of high-throughput LC-MS/MS facilities serving cross-border trade.
United States
Food processing companies expand in-house testing protocols to pre-empt FDA enforcement actions and protect brand equity. EPA registration requirements for new active ingredients create demand for metabolite detection methods. California's agricultural export corridors and Midwest grain processing clusters anchor the highest laboratory instrument density.
Brazil
Soybean and coffee exporters require pre-shipment certification to EU and US maximum residue limits before port release. ANVISA alignment with Codex standards accelerates third-party laboratory accreditation demand. São Paulo state and the Matopiba region concentrate mobile sampling units near major export terminals.
India
FSSAI implementation of Codex-aligned maximum residue limits creates first-mover opportunity for ISO 17025-accredited facility establishment. Domestic food safety modernization and spice export compliance drive parallel investment tracks. Mumbai and Delhi-NCR emerge as the primary laboratory hub locations for multi-residue panel deployment.
China
SAMR enforcement of GB standards for domestic food safety and agricultural export certification sustains dual-track testing demand. NMPA coordination with customs authorities tightens border inspection protocols for imported food commodities. Yangtze River Delta processing clusters and Pearl River Delta export corridors concentrate chromatography service providers.
Pesticide Residue Testing Market Vendor Landscape
Capability concentration sits with pan-European laboratory networks possessing EFSA-recognized accreditation scopes; scale advantage sits with integrated testing and certification conglomerates operating across multiple jurisdictions. The market structures around three tiers: multinational consolidators with cross-border accreditation, regional specialists with crop-specific method expertise, and commodity-focused auditors bundling residue testing with supply chain verification. M&A activity targets ISO 17025-accredited facilities in high-volume agricultural export zones, while technology licensing agreements transfer multi-residue method protocols between laboratory networks.
Within the multinational consolidator tier, Eurofins Scientific SE and SGS S.A. exemplify scale-driven positioning through distributed laboratory networks and mobile sampling infrastructure. Bureau Veritas S.A. occupies a distinct position integrating residue testing with broader supply chain certification services. These three entities anchor competitive dynamics as laboratories compete for retail grocery chain procurement contracts bundling multi-residue panels with microbiological and allergen screening.
| Leading Market Players |
|---|
| Eurofins Scientific SE |
| Bureau Veritas S.A. |
| SGS S.A. |
| Intertek Group plc |
| ALS Limited |
| Mérieux NutriSciences |
| AsureQuality |
| Silliker, Inc. |
| Microbac Laboratories, Inc. |
| Others |
Supply Flow & Price Mechanics
Helium extraction from Qatar and the US concentrates carrier gas supply for GC-MS laboratories, anchoring margin pools with chromatography service providers in Germany and the Netherlands who can secure long-term offtake agreements. This upstream concentration forces downstream laboratories to absorb cost volatility or migrate toward LC-MS platforms that eliminate helium dependency entirely.
Pricing Analysis
Contract structures in pesticide residue testing gravitate toward multi-year accreditation agreements with food processing conglomerates, though spot pricing persists for pre-shipment export certification in Brazil and Argentina. Three-tier pricing structure across premium, standard, and economy levels separates high-resolution Orbitrap confirmatory analysis from routine triple-quadrupole screening and basic HPLC triage. Cost compression in standard-tier multi-residue panels is intensifying because retail grocery chains consolidate procurement into bundled food safety contracts. Agricultural cooperatives exhibit highest price sensitivity due to seasonal cash flow constraints, while multinational food manufacturers prioritize turnaround reliability over per-sample economics.
Supply Chain Analysis
Export-control regimes on high-resolution mass spectrometry components from the US and Germany limit instrument availability for laboratories in India and China seeking ISO 17025 accreditation upgrades. Manufacturing concentration for LC-MS systems rests on Massachusetts and Singapore production facilities, while certified reference standards draw exclusively from European suppliers facing 12-18 month production lead times. Single-source vulnerability pervades the reference material tier, where emerging pesticide metabolite standards lack secondary sourcing. Distribution runs through manufacturer-authorized service networks that bundle installation, method validation, and maintenance into multi-year captive contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of PhD-level mass spectrometry method developers concentrates capability within incumbent laboratory networks, creating defensive moats that new entrants must breach through specialized accreditation or geographic whitespace.
For Market Incumbents: Harden accreditation scopes against EFSA guideline revisions by pre-emptively validating expanded multi-residue panels before mandatory adoption deadlines. Deepen vertical integration into mobile sampling infrastructure to capture pre-shipment certification demand in Brazil's Matopiba region, defending against regional specialists bundling logistics with testing. Lock in helium supply contracts or accelerate LC-MS platform migration to neutralize carrier gas price volatility threatening GC-MS operating margins. For New Entrants and Emerging Players: Build out ISO 17025-accredited facilities in Mumbai and Delhi-NCR ahead of FSSAI's full Codex alignment, seizing first-mover advantage before Eurofins and SGS consolidate Indian laboratory networks. Target biological sample testing for occupational exposure assessment, an adjacent segment where incumbent food safety laboratories lack established method expertise. Pursue blockchain-integrated certification partnerships with organic distributors commanding premium pricing for real-time traceability documentation. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap European laboratories possessing EFSA-recognized multi-residue method portfolios but lacking pan-European geographic coverage to compete for retail chain procurement contracts. Over the projection horizon, consolidation economics favor targets with existing high-throughput LC-MS/MS capacity that can absorb volume from smaller competitors exiting confirmatory testing. Monitor FSSAI enforcement intensity against import rejections as the signal indicating when Indian laboratory acquisition premiums justify deployment.| Strategic Initiative | Industry Significance |
|---|---|
| LC-MS/MS Platform Migration | Eliminates helium dependency while meeting EFSA's tightened maximum residue limit detection thresholds. |
| Multi-Residue Method Validation | Single-extraction protocols replace sequential workflows, compressing turnaround times from 72 hours to 24 hours. |
| Mobile Sampling Unit Deployment | Positions pre-shipment certification capacity adjacent to Brazil's soybean export terminals in São Paulo state. |
| Blockchain-Integrated Certification | Enables real-time traceability from field sampling to laboratory report for organic and specialty crop distributors. |
| Biological Sample Testing Expansion | Opens human biomonitoring revenue streams for environmental health agencies beyond commodity food matrices. |
Methodological Framework
Desk research of EFSA scientific opinions, EPA registration documents, FDA pesticide residue monitoring reports, and ISO 17025 accreditation databases preceded structured interviews with laboratory technical directors, food safety compliance officers at processing conglomerates, agricultural export logistics managers, and chromatography instrument manufacturer sales engineers. Primary fieldwork across Berlin, Hamburg, São Paulo, and Mumbai validated secondary estimates of laboratory capacity expansion and instrument procurement timelines. Bottom-up triangulation aggregated individual facility throughput estimates; top-down verification cross-checked against customs data on chromatography system imports and EFSA proficiency testing participation records.
Assumptions held fixed across the modeling period include EFSA's Farm to Fork Strategy implementation trajectory and FSSAI's Codex alignment schedule, while helium supply volatility and reference material production bottlenecks were modeled as variable stress conditions. Segmentation dimensions encompassed instrument platform, end-user procurement authority, testing method scope, and geographic regulatory cluster. CAGRs were derived from instrument shipment forecasts, laboratory accreditation expansion plans, and export commodity volume projections. Industry-specific inputs included EFSA guideline revision timelines and ANVISA's convergence with international maximum residue limit standards.
Stress conditions across helium export constraints, reference material production delays, and mass spectrometry specialist wage inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about regulatory enforcement intensity and technology substitution rates that could shift materially with policy acceleration or instrument breakthroughs. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Testing Services
Agricultural Testing Services Market
Agricultural Testing Services
Europe Feed Testing Market
Agricultural Testing Services
Asia Pacific Feed Testing Market
Agricultural Testing Services
Nematode Testing Services Market
Agricultural Testing Services
Irrigation Testing Kit Market
Agricultural Testing Services
Impact Soil Tester Market
Agricultural Testing Services
Soil Erosion Testing Market
Agricultural Testing Services
Global Agriculture Testing Services Market
Agricultural Testing Services
Plant Disease Diagnostic Market
Agricultural Testing Services
Pesticide Detection Market
Agricultural Testing Services
Soil Testing Kit Market
Agricultural Testing Services
Rapid Mycotoxin Detection Systems for Grain Handling Facilities Market
Agricultural Testing Services
Agrochemicals Testing and Inspection Service Market
Agricultural Testing Services
Testing, Inspection, and Certification for Agriculture & Food Market
Agricultural Testing Services
Plant Nutrient Testing Equipment Market
Agricultural Testing Services
Animal Feed Testing Market