
 Plant Disease Diagnostic Market | 2026-2036
Plant Disease Diagnostic Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Disease Diagnostic Market Insights
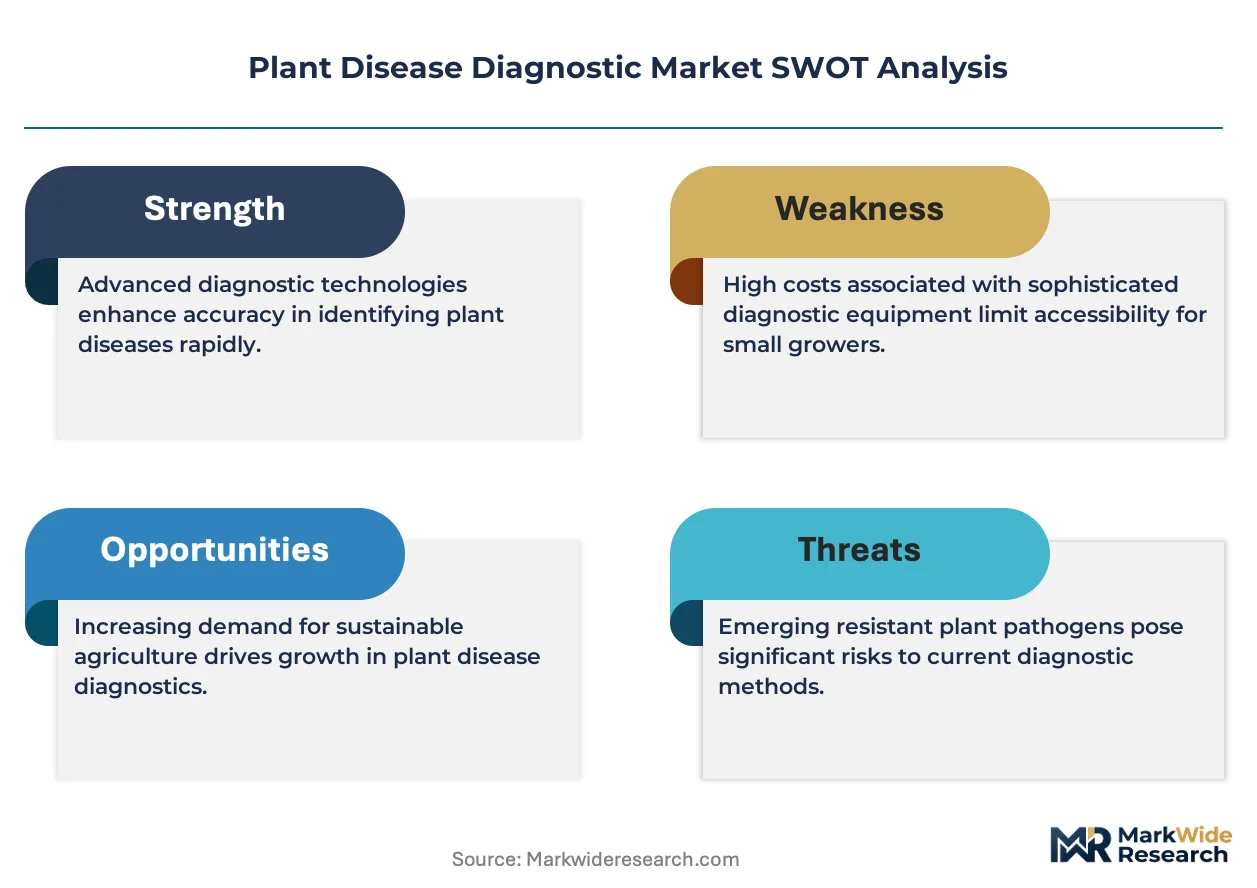
The gap between premium molecular platforms and commodity immunodiagnostic strips is pivoting into a full market bifurcation. Thermo Fisher Scientific leverages its sequencing infrastructure to dominate laboratory-grade NGS workflows for pathogen identification. Agdia sustains channel control through specialized ELISA and lateral flow kits calibrated for field agronomists. LOEWE Biochemica anchors the European market with region-specific pathogen panels that navigate divergent national certification standards.
Plant disease diagnostic systems encompass laboratory and field-deployable technologies that detect bacterial, viral, fungal, and oomycete pathogens through serological, nucleic acid, or protein-based assays, typically achieving sensitivity thresholds of picogram-level antigen detection or single-copy pathogen DNA resolution. These systems serve commercial agriculture, seed certification programs, and phytosanitary border controls by enabling containment decisions before disease establishment. Molecular diagnostic kits capture the fastest-expanding margin pool as PCR and NGS displace slower culture methods in seed health testing, while immunodiagnostic kits retain volume leadership in agricultural research settings where cost-per-sample constraints persist. Bioinformatics solutions represent the emerging structural layer, with demand concentrating where sequencing data volumes exceed manual interpretation capacity.
EPA and USDA APHIS shape US market access through quarantine pathogen lists and interstate movement certification requirements, while the EU Green Deal and REACH frameworks drive substitution toward reduced-chemical crop protection that elevates early detection value. EFSA's evolving guidance on novel genomic techniques in plants indirectly tightens diagnostic stringency for gene-edited resistance traits. Stakeholders must monitor how national plant health agencies synchronize digital reporting mandates with field diagnostic tool capabilities.
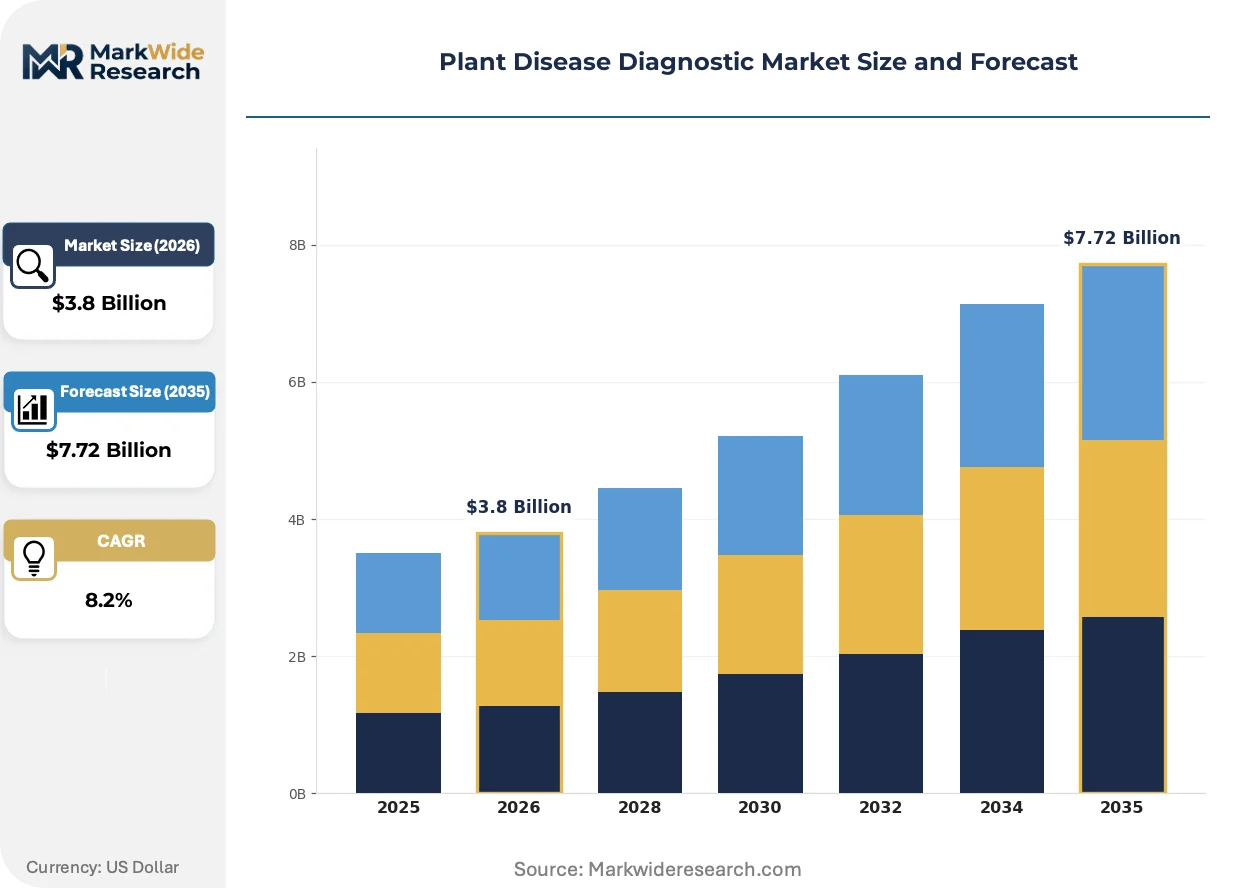
Market Dynamics
Precision agriculture platforms are compressing diagnostic decision windows from weeks to hours, forcing vendors to recalibrate field-deployable sensitivity thresholds against laboratory-grade validation standards.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Mandatory phytosanitary compliance timelines across member states are accelerating procurement of rapid molecular detection systems for seed certification programs.
- Large-scale commercial farms:Centralized agronomic operations in Germany and the Netherlands are consolidating purchasing power for multiplex PCR platforms that replace single-pathogen ELISA workflows.
- NGS infrastructure:Declining per-sample sequencing costs are automating pathogen identification in border control laboratories previously dependent on culture-based methods.
Market Restraints
- Reagent supply concentration:Taq polymerase and fluorescent probe manufacturing clusters in specific Asian supply zones create vulnerability to customs delays and cold-chain interruptions.
- Technical specificity limits:Cross-reactivity between closely related oomycete species in lateral flow assays generates false-negative risks in field conditions with mixed pathogen pressure.
- REACH chemical substitution mandates:Reformulation of preservative buffers in sample collection kits requires re-validation cycles that extend product launch timelines by 8-14 months.
Strategic Opportunities
- Digital reporting mandates:National plant health agencies in France and Spain are requiring real-time pathogen data upload, creating demand for cloud-integrated diagnostic instruments with API connectivity.
- CRISPR-Cas detection convergence:SHERLOCK and DETECTR platforms are merging with smartphone-based readout hardware to enable non-laboratory confirmation of resistance gene edits.
- Seed export corridors:Ukrainian and Romanian grain terminals are investing in in-house qPCR capacity to preempt phytosanitary holds in destination markets.
Industry Challenges
- Bioinformatics talent scarcity:Interpretation of NGS output for novel pathogen variants requires computational phylogenetics expertise that agronomic laboratories rarely maintain in-house.
- Multi-jurisdiction certification:Divergent national approval pathways for genetically modified diagnostic organisms create parallel validation burdens for kit manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Disease Diagnostic Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.72 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunodiagnostic Kits, Molecular Diagnostic Kits, Diagnostic Equipment, Bioinformatics Solutions Application: Agricultural Research, Field Testing, Laboratory Testing, Seed Health Testing Technology: PCR, ELISA, Next-Generation Sequencing, Microarray Technology End User: Research Institutes, Agricultural Farms, Biotechnology Companies, Government Agencies |
| Companies Covered | Thermo Fisher Scientific, Agdia, Merck KGaA, Abingdon Health, TwistDx, Qualiplante SAS, ClearDetections, LOEWE Biochemica, BIORBA AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Disease Diagnostic Market Trends and Innovations
Loop-mediated isothermal amplification (LAMP) hardware is penetrating field agronomy at the expense of central laboratory throughput, while regulatory data interoperability mandates are redefining instrument purchasing criteria.
Portable LAMP devices with battery-powered thermal cyclers are automating sample-to-answer workflows for viral pathogens in vineyard and orchard settings. German cooperative extension services are deploying these units for immediate downy mildew confirmation during humid growing periods. The technology is automating decision support that previously required 72-hour courier transit to regional laboratories.
EFSA guidance on novel genomic techniques is tightening diagnostic stringency for gene-edited disease resistance traits in commercial cultivars. Seed companies must now demonstrate pathogen-free status through validated molecular methods before variety registration. Vegetable breeding programs in the Netherlands are responding by integrating in-house diagnostics into phenotyping pipelines.
Consolidated purchasing by agronomic service providers is displacing individual farmer kit acquisitions across commercial row-crop regions. Multi-farm cooperatives in France's cereal belt are centralizing diagnostic capacity through shared equipment leases with technical support contracts. This concentration is most visible in wheat-producing departments where fusarium monitoring is mandatory under cooperative quality agreements.
Plant Disease Diagnostic Market Segmentation
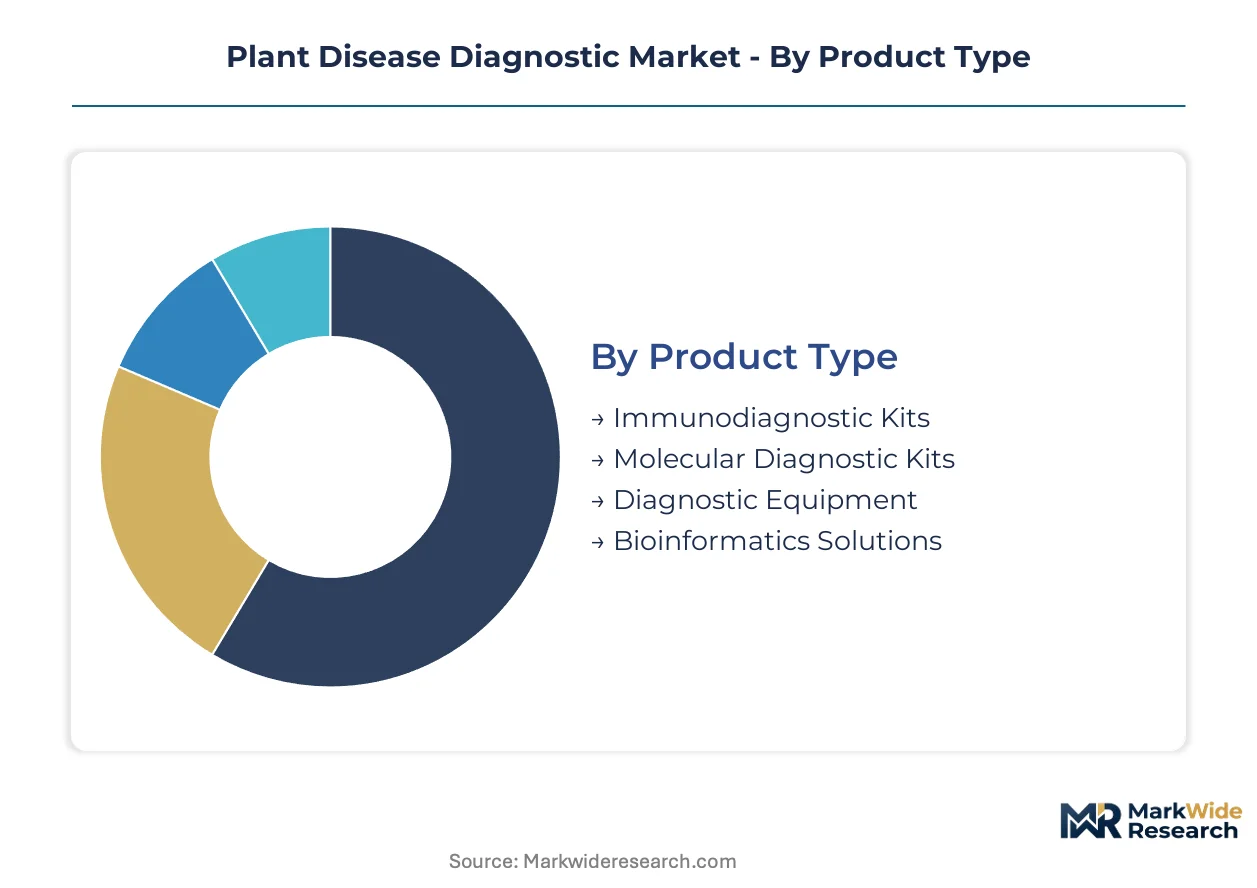
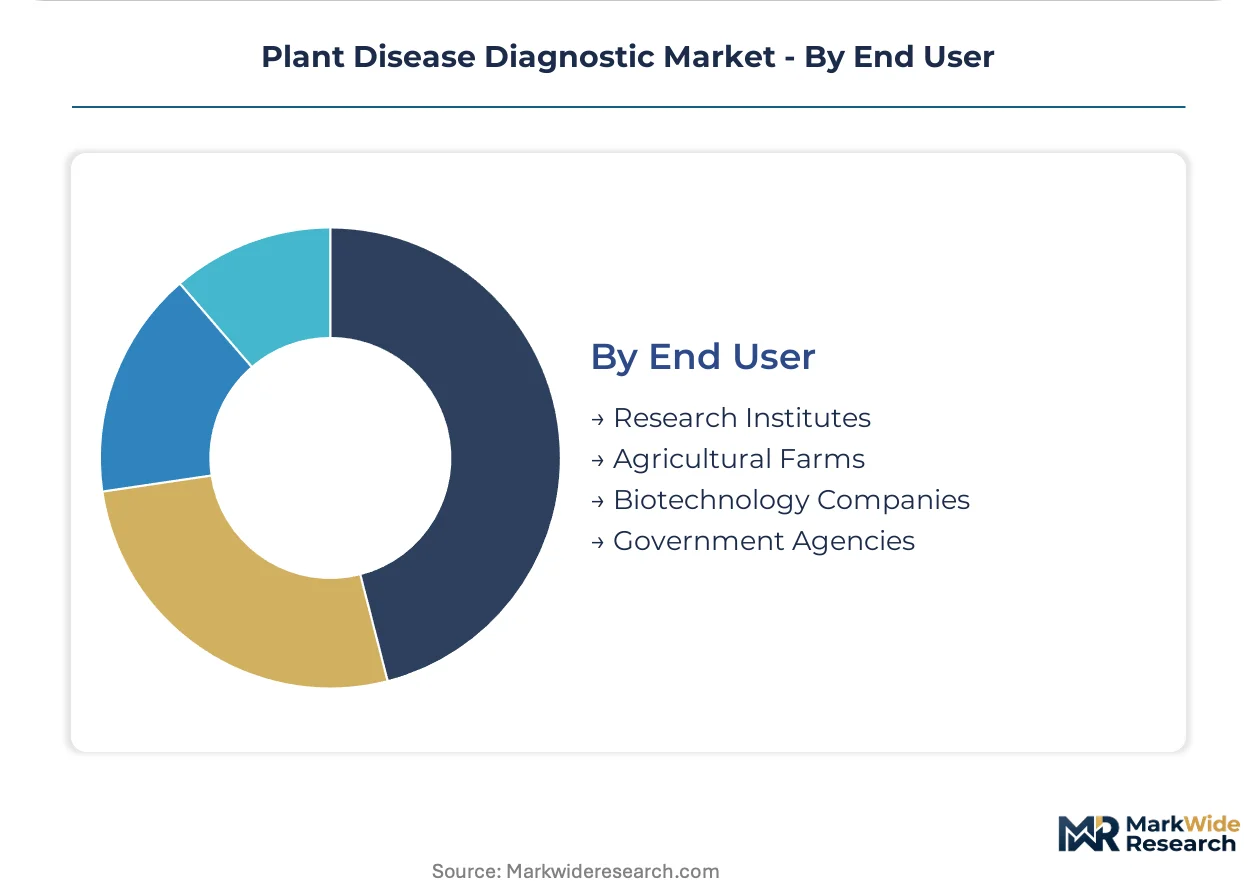
Diagnostic procurement patterns diverge sharply between centralized laboratories requiring validated throughput and decentralized field operations prioritizing speed over sensitivity. Understanding these structural splits reveals where margin pools concentrate and which technology transitions will reshape vendor positioning.
Product Type:
Standalone diagnostic consumables dominate agricultural procurement budgets, while embedded bioinformatics layers are penetrating where sequencing volumes exceed manual interpretation capacity.
- Molecular Diagnostic Kits:PCR and NGS reagent chemistries achieve single-copy pathogen DNA resolution for seed certification and phytosanitary border controls. Demand concentrates in Germany and the Netherlands where centralized research institutes drive consolidated purchasing of multiplex platforms.
- Immunodiagnostic Kits:ELISA and lateral flow strips detect picogram-level antigens through antibody binding assays calibrated for field agronomists. Cost-per-sample constraints in French and Spanish cooperative extension services sustain volume leadership despite slower turnaround times.
- Diagnostic Equipment:Thermal cyclers, imaging systems, and automated sample prep stations anchor laboratory infrastructure investments.
- Bioinformatics Solutions:Cloud-based phylogenetic analysis pipelines interpret NGS output for novel pathogen variants.
Immunodiagnostic kits lead volumes today; bioinformatics solutions are gaining share fastest.
Application:
Cost tier stratification separates premium laboratory validation from commodity field screening, with seed health testing commanding the steepest price premiums per sample.
- Seed Health Testing:Regulatory mandates under EU Green Deal phytosanitary compliance require validated molecular confirmation before interstate movement. Dutch vegetable breeding programs integrate in-house diagnostics into phenotyping pipelines to preempt variety registration delays.
- Laboratory Testing:Centralized regional facilities perform species-level pathogen identification using culture-based and molecular methods for official certification.
- Field Testing:Battery-powered LAMP devices with smartphone readout automate immediate downy mildew confirmation in German vineyard cooperatives during humid growing periods.
- Agricultural Research:University and institute laboratories maintain diverse assay portfolios for pathogen characterization and resistance screening.
Field testing climbs the fastest as precision agriculture platforms compress decision windows from weeks to hours.
Technology:
Technology maturity curves separate established serological methods from emerging nucleic acid platforms, with NGS infrastructure investments concentrated in border control laboratories.
- PCR:Quantitative real-time amplification remains the reference standard for seed certification and regulatory submission, with multiplex panels displacing single-pathogen workflows in large-scale commercial farm operations.
- Next-Generation Sequencing:Metagenomic pathogen detection automates identification of novel variants previously requiring sequential culturing, with Ukrainian and Romanian grain terminals investing in in-house capacity to preempt phytosanitary holds.
- ELISA:Enzyme-linked immunosorbent assays provide cost-effective bulk screening where regulatory stringency permits serological confirmation.
- Microarray Technology:High-density probe arrays enable parallel detection of hundreds of pathogen targets in centralized reference laboratories.
PCR anchors installed base today; next-generation sequencing shows the steepest expansion trajectory.
End User:
Customer type determines purchasing modality, with research institutes favoring capital-intensive platforms and agricultural farms migrating toward service-based diagnostic access.
- Research Institutes:Max Planck and INRAE facilities drive centralized procurement of laboratory-grade molecular platforms for pathogen characterization and resistance gene validation.
- Agricultural Farms:French cereal belt cooperatives centralize diagnostic capacity through shared equipment leases with technical support contracts, displacing individual farmer kit acquisitions.
- Biotechnology Companies:Seed developers integrate in-house diagnostics to demonstrate pathogen-free status before variety registration under tightening EFSA guidance.
- Government Agencies:National plant health agencies in France and Spain mandate real-time pathogen data upload, creating demand for cloud-integrated instruments with API connectivity.
Agricultural farms represent the largest volume pool today; government agencies are expanding procurement most quickly through digital reporting mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phytosanitary compliance specialists cluster in Germany's centralized agricultural research institutes, anchoring European demand for molecular diagnostic platforms while precision agriculture adoption accelerates field-deployable testing across commercial farm belts.
Germany
Max Planck Institute and Julius Kühn-Institute scientists drive consolidated procurement of multiplex PCR systems for seed certification. EU Green Deal Farm to Fork phytosanitary mandates tighten compliance timelines for interstate seed movement. Bavarian cooperative extension services deploy battery-powered LAMP devices for immediate downy mildew confirmation in vineyard corridors during humid growing periods.
United States
USDA APHIS quarantine pathogen lists and interstate movement certification requirements shape market access for diagnostic kit manufacturers. EPA regulatory frameworks on reduced-chemical crop protection elevate early detection value in commercial row-crop regions. California's Central Valley agronomic service providers consolidate purchasing power for field-deployable molecular platforms serving almond and grape producers.
France
INRAE research facilities anchor laboratory-grade platform demand for pathogen characterization and resistance gene validation. National plant health agency mandates require real-time pathogen data upload through cloud-integrated instruments with API connectivity. Cereal belt cooperatives in Hauts-de-France centralize diagnostic capacity through shared equipment leases with technical support contracts for mandatory fusarium monitoring.
Netherlands
Dutch vegetable breeding programs integrate in-house diagnostics into phenotyping pipelines to preempt variety registration delays under tightening EFSA guidance. REACH chemical substitution mandates drive reformulation cycles for preservative buffers in sample collection kits. Wageningen University research clusters anchor demand for next-generation sequencing infrastructure in plant pathology laboratories.
Ukraine
Black Sea grain terminal operators invest in in-house qPCR capacity to preempt phytosanitary holds in destination markets for wheat and corn exports. National agricultural ministry programs accelerate adoption of rapid field-based diagnostics among large-scale commercial farm operations. Odessa port logistics clusters drive centralized procurement of molecular detection systems for export corridor compliance.
Plant Disease Diagnostic Market Competitive Landscape
Top-tier vendors anchor laboratory-grade molecular platforms, while mid-tier specialists control field-deployable immunodiagnostic channels. Thermo Fisher Scientific leverages sequencing infrastructure dominance in centralized reference laboratories. Agdia sustains agronomist relationships through specialized ELISA and lateral flow kit distribution. LOEWE Biochemica navigates divergent national certification standards with region-specific pathogen panels. Consolidation pressures intensify as precision agriculture platforms compress diagnostic decision windows from weeks to hours.
Within the sequencing infrastructure tier, Thermo Fisher Scientific occupies a position exemplifying laboratory-grade NGS workflow dominance for pathogen identification. Agdia and LOEWE Biochemica represent contrasting archetypes: the former anchors field agronomist channel control through specialized immunoassay calibration, while the latter exemplifies European market anchoring through region-specific panel navigation. Merck KGaA and TwistDx sit within the reagent chemistry tier, their positions reflecting supply concentration in Taq polymerase and isothermal amplification chemistries respectively. Qualiplante SAS and ClearDetections exemplify national-specialist positioning, their structures suggesting focused geographic or application-specific market penetration rather than broad platform competition.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agdia |
| Merck KGaA |
| Abingdon Health |
| TwistDx |
| Qualiplante SAS |
| ClearDetections |
| LOEWE Biochemica |
| BIORBA AG |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap reagent specialists in Germany and the Netherlands anchor European supply networks for molecular diagnostic platforms, their concentrated ownership structures enabling pricing discipline through direct agronomist relationships rather than distributor markups. This ownership pattern tightens margin control across PCR consumables and LAMP device procurement, with centralized cooperative purchasing in France and Spain forcing volume-tiered contract structures that compress field-kit premiums.
Pricing Analysis
The bundled-vs-unbundled service split separates laboratory-grade platform vendors from field-deployable kit suppliers. Equipment-leasing contracts with embedded technical support command premium positioning in German research institutes, while per-unit transactional pricing dominates French cooperative extension services where cost-per-sample constraints persist. Price differentiation hinges on certification grade under EU Green Deal phytosanitary mandates and volume scale in multi-farm cereal belt consolidations. Pricing pressure stems from REACH chemical substitution mandates extending reagent reformulation cycles. Agricultural farms exhibit highest price sensitivity; government border control laboratories show lowest.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive reagents and refurbishment of thermal cycler modules create secondary value recovery channels in centralized European laboratories. Manufacturing concentrates in Germany, the Netherlands, and China for Taq polymerase, fluorescent probes, and battery-powered LAMP hardware. Raw material dependencies include optical-grade plastics for imaging systems, semiconductor components for thermal control, and preservative chemistries for sample collection buffers. Single-source vulnerability in Asian supply zones for probe synthesis creates customs delay exposure. Distribution runs through agronomic service providers consolidating multi-farm cooperative leases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Plant Disease Diagnostic Market functions as a stable compounder anchored by EU Green Deal phytosanitary compliance mandates that institutionalize recurring procurement cycles across member state seed certification programs.
For Market Incumbents: Hedge against isothermal amplification displacement by embedding cloud-integrated reporting capabilities into installed PCR platforms before French and Spanish digital mandates harden. Secure backward integration into Taq polymerase production to neutralize Asian supply zone vulnerability. Channel control through cooperative extension service contracts remains the priority defensive lever.
For New Entrants and Emerging Players: Launch via smartphone-based CRISPR-Cas detection hardware targeting Ukrainian and Romanian grain terminal operators seeking preemptive phytosanitary compliance capacity. The seed export corridor segment offers lowest incumbent saturation. White-space exists in bioinformatics-as-a-service for NGS interpretation where agronomic laboratories lack computational phylogenetics expertise.
For Investors and Strategic Acquirers: Valuations sit cheapest among field-deployable LAMP specialists with established vineyard and orchard cooperative relationships but limited multiplex PCR coverage. The five-to-ten year viability window favors platforms with API connectivity infrastructure. Target acquisition archetype: regional pathogen panel developers navigating divergent national certification standards. Monitor EFSA guidance evolution on novel genomic techniques as inflection signal for gene-edited resistance trait diagnostic demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Integrated Instrument Launch | French and Spanish digital reporting mandates require API-connected diagnostic hardware for real-time pathogen data upload compliance. |
| Backward Integration into Reagent Chemistry | In-house Taq polymerase production neutralizes Asian supply zone concentration risk for PCR consumable margins. |
| Regional Pathogen Panel Expansion | LOEWE Biochemica's certification-navigation model enables faster market entry under divergent EU member state approval pathways. |
| Cooperative Service Contract Consolidation | French cereal belt equipment leases demonstrate scalable revenue capture displacing individual farmer kit acquisitions. |
| Bioinformatics Pipeline Development | NGS data volumes exceeding manual interpretation capacity in Dutch vegetable breeding programs create software subscription demand. |
Research Methodology
Multiple input streams — primary interviews with molecular platform procurement officers at Max Planck and Julius Kühn-Institute facilities, field agronomists in Bavarian vineyard cooperatives, and seed certification program managers — were reconciled against secondary validation from EU Green Deal implementation documents, EFSA guidance releases, and REACH chemical substitution regulatory filings. Bottom-up triangulation across product-type demand curves and top-down cross-checks against national agricultural ministry expenditure disclosures anchored volume estimates.
Historical adoption curves for PCR, LAMP, and NGS platforms were cross-referenced against expert panel assessments of precision agriculture platform penetration rates across the projection horizon. Segmentation dimensions modeled include product type, application tier, technology maturity curve, and end-user purchasing modality. CAGRs were derived from slope analysis of equipment procurement cycles and consumable replenishment patterns. Industry-specific forecast inputs incorporated phytosanitary compliance timeline tightening under Farm to Fork strategy implementation and declining per-sample sequencing cost trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained customs disruption in Asian reagent supply zones or accelerated EFSA guidance revision on gene-edited resistance trait validation. Practitioners should monitor national plant health agency digital reporting mandate rollouts and CRISPR-Cas detection platform regulatory classification decisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Testing Services
Poultry Diagnostic Testing Market
Agricultural Testing Services
Soil Field Testing Equipment Market
Agricultural Testing Services
Pesticide Residue Testing Market
Agricultural Testing Services
Europe Feed Testing Market
Agricultural Testing Services
Feed Testing Market
Agricultural Testing Services
Testing, Inspection, and Certification for Agriculture & Food Market
Agricultural Testing Services
Animal Feed Testing Market
Agricultural Testing Services
Soil Testing Kit Market
Agricultural Testing Services
Soil Erosion Testing Market
Agricultural Testing Services
Seed Testing Services Market
Agricultural Testing Services
Irrigation Testing Kit Market
Agricultural Testing Services
Rapid Mycotoxin Detection Systems for Grain Handling Facilities Market
Agricultural Testing Services
Agrochemicals Testing and Inspection Service Market
Agricultural Testing Services
Asia Pacific Feed Testing Market
Agricultural Testing Services
Impact Soil Tester Market
Agricultural Testing Services
Global Agriculture Testing Services Market