
 Poultry Diagnostic Testing Market | 2026-2036
Poultry Diagnostic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Poultry Diagnostic Testing Market Analytics
EU F-Gas Regulation is hardening cold-chain requirements for avian vaccine transport, forcing diagnostic labs to validate temperature-stable reagent kits. IDEXX Laboratories sustains technology leadership through integrated veterinary software platforms that link farm-level sampling to centralized analytics. BioChek anchors European demand with species-specific ELISA portfolios calibrated to EFSA pathogen thresholds. Neogen Corporation competes on manufacturing scale, operating high-throughput production lines that supply rapid test cassettes to North American integrators.
Poultry diagnostic testing encompasses laboratory and field-based methods for detecting avian pathogens including Newcastle disease virus, avian influenza subtypes, and Salmonella enterica serovars, typically employing immunoassay, nucleic acid amplification, or chromatographic techniques with sensitivity thresholds reaching picogram-level antigen detection. The primary purpose is to enable flock-level health management, trade certification, and zoonotic risk containment before birds enter processing facilities. Molecular tests command premium positioning due to multiplexing capacity and same-day turnaround, while rapid tests occupy high-volume screening roles at farm gate checkpoints. Serological tests retain structural importance for export sero-surveillance programs despite longer incubation cycles.
USDA APHIS, EFSA, and OIE standards collectively shape product registration pathways, with divergent strain notification timelines forcing manufacturers to maintain parallel validation dossiers for transatlantic market access. FDA oversight of veterinary diagnostic devices under VFD guidelines adds compliance layers for kits deployed in antibiotic stewardship programs. Stakeholders must monitor emerging avian metapneumovirus strains and corresponding reference material availability to avoid assay obsolescence during outbreak surge events.
Market Dynamics
Multiplex PCR platforms are compressing detection timelines from days to hours, forcing laboratories to retire legacy serological workflows and retrain technical staff across three continents simultaneously.
Growth Catalysts
- USDA Biosecurity Mandates:Commercial integrators in the United States must maintain continuous pathogen surveillance, creating recurring demand for high-throughput molecular screening infrastructure.
- EU Sanitary Export Standards:Brazilian producers deploy molecular diagnostics to preserve market access, converting diagnostic spending from discretionary to operational necessity.
- Loop-Mediated Isothermal Amplification:Field-deployable LAMP kits eliminate cold-chain dependencies, enabling same-day testing at remote farm locations without laboratory infrastructure.
Market Restraints
- Reference Material Scarcity:Emerging avian metapneumovirus strains lack certified control panels, forcing manufacturers to suspend assay validation during outbreak windows.
- Reagent Cost Volatility:Enzyme and oligonucleotide supply concentrates in German and Japanese chemical clusters, exposing test producers to input price shocks.
- Parallel Validation Burden:Divergent strain notification timelines between USDA APHIS and EFSA require manufacturers to maintain separate dossiers, inflating registration costs.
Strategic Opportunities
- Sub-Saharan Africa Expansion:Underpenetrated veterinary infrastructure in Nigeria and Kenya creates first-mover advantage for portable nucleic acid platforms.
- Antibiotic Stewardship Integration:FDA Veterinary Feed Directive guidelines position diagnostic kits as mandatory gatekeepers for therapeutic decision workflows.
- Blockchain Traceability Convergence:Diagnostic result immobilization on distributed ledgers enables immutable export certification, differentiating premium test providers.
Industry Challenges
- Molecular Biology Skill Deficits:Rural veterinary stations lack personnel trained in nucleic acid extraction protocols, creating deployment bottlenecks for advanced platforms.
- Legacy System Interoperability:Farm management software from the 2010s cannot ingest real-time PCR data streams, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poultry Diagnostic Testing Market |
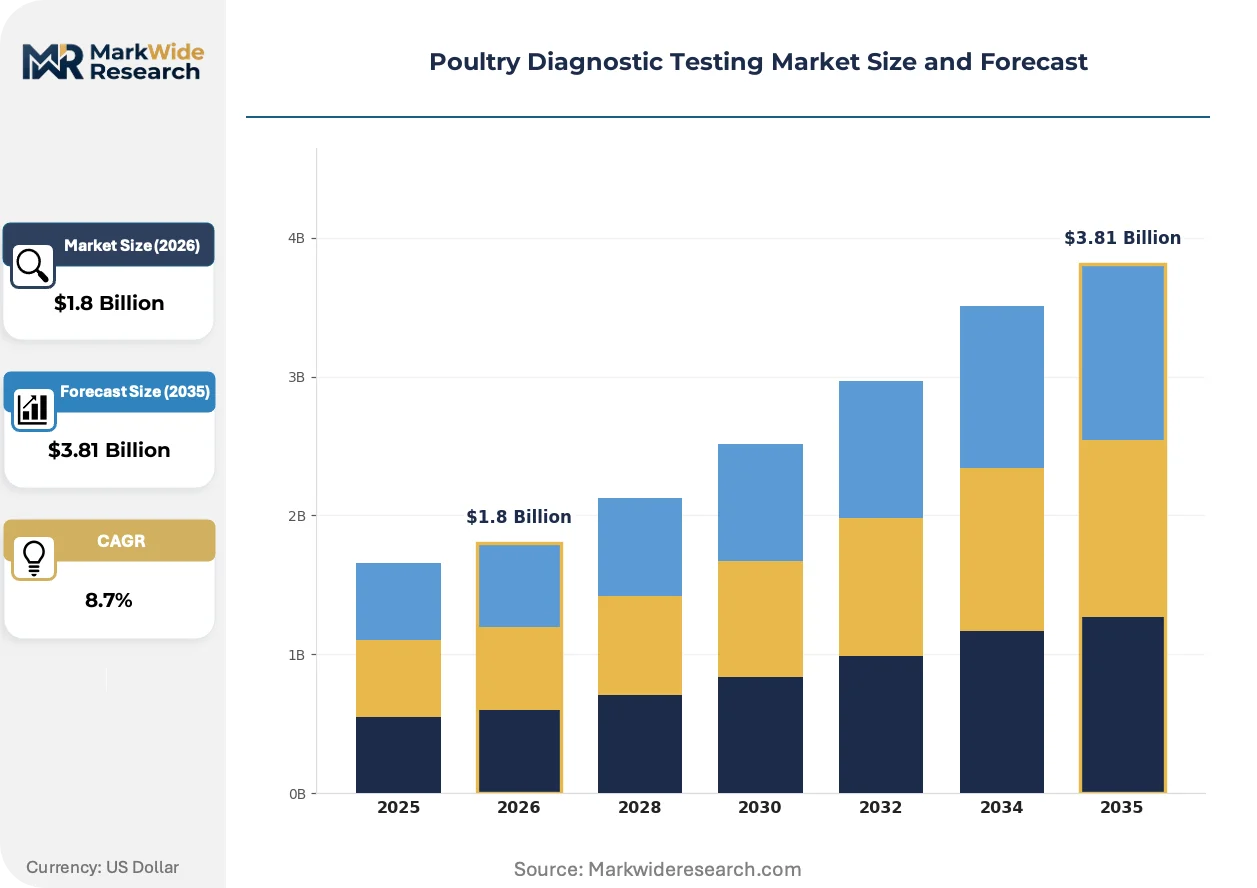
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Serological Tests, Molecular Tests, Rapid Tests, Antigen Tests End User: Commercial Poultry Farms, Veterinary Clinics, Research Institutions, Government Agencies Species: Broilers, Layers, Turkeys, Ducks Delivery Mode: Laboratory Testing, Point-of-Care Testing, Home Testing, Mobile Testing Units |
| Companies Covered | BioChek, BioNote, Inc., IDEXX Laboratories, Inc., Neogen Corporation, bioMérieux, Thermo Fisher Scientific Inc., GD Animal Health, IDvet, Zoetis Services LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poultry Diagnostic Testing Market Evolving Landscape
Diagnostic workflows are fragmenting into point-of-care and centralized laboratory poles, with each pole demanding incompatible performance specifications and business models from suppliers.
CRISPR-based diagnostic platforms are converging with smartphone readout systems. Poultry integrators in Southeast Asia pilot these combinations for Newcastle disease screening at farm gate checkpoints. The technology is converging with cloud-based epidemiological mapping, compressing outbreak response timelines from weeks to 48 hours.
EU F-Gas Regulation is hardening cold-chain requirements for temperature-sensitive reagents. Diagnostic laboratories must now validate lyophilized kit stability under ambient transport conditions. European manufacturers are responding by reformulating PCR master mixes with thermostable polymerase variants.
Integrated producers now bundle diagnostic subscriptions with veterinary service contracts. The traditional transactional test-kit purchase is yielding to multi-year monitoring agreements. This shift is most visible in Brazil, where exporters require continuous serological documentation to maintain EU market eligibility.
Poultry Diagnostic Testing Market Segmentation
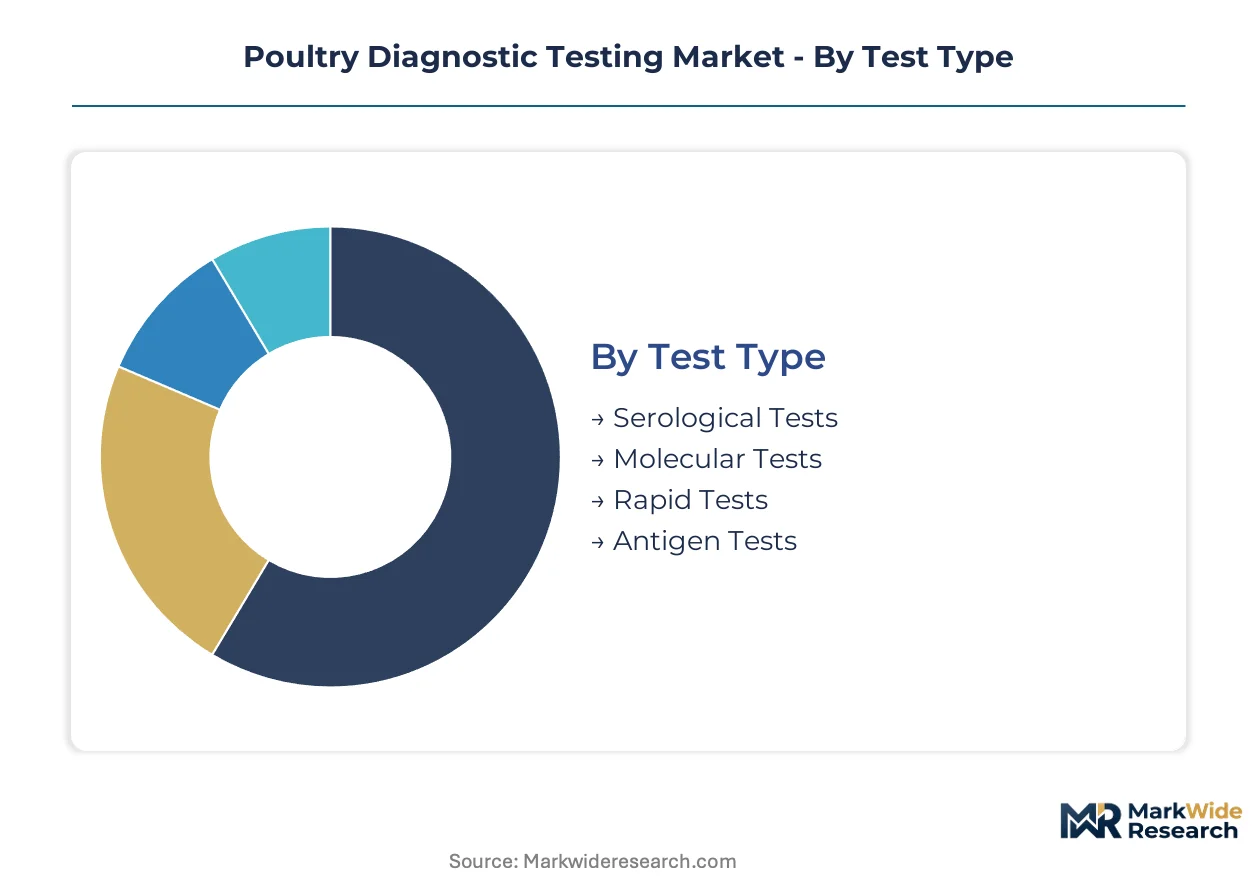
Poultry diagnostic testing segments fragment sharply between centralized laboratory infrastructure and distributed field deployment. Each category demands incompatible performance specifications, pricing models, and regulatory validation pathways from suppliers.
Test Type:
Customization intensity varies from commodity rapid strips to engineered multiplex PCR panels requiring strain-specific primer design.
- Molecular Tests:Multiplex PCR and LAMP platforms detect avian influenza subtypes and Newcastle disease virus with same-day turnaround. Brazilian integrators deploy these for EU export certification, converting diagnostic spending from discretionary to operational necessity.
- Rapid Tests:Lateral flow cassettes deliver qualitative results at farm gate checkpoints without laboratory infrastructure. USDA APHIS mandates drive recurring procurement from commercial farms seeking biosecurity compliance.
- Serological Tests:ELISA-based antibody detection supports export sero-surveillance programs despite longer incubation cycles.
- Antigen Tests:Chromatographic methods target surface protein detection for Salmonella enterica screening at processing facility entry points.
Leading the category by volume: Rapid Tests. Growing fastest: Molecular Tests.
End User:
Procurement authority concentrates in vertically integrated producers while fragmented veterinary stations struggle with molecular biology skill requirements.
- Commercial Poultry Farms:Large integrators in the United States and Brazil maintain continuous pathogen surveillance through multi-year diagnostic subscriptions bundled with veterinary service contracts.
- Veterinary Clinics:Rural stations lack personnel trained in nucleic acid extraction protocols, creating deployment bottlenecks for advanced platforms.
- Research Institutions:Academic centers validate emerging avian metapneumovirus strains and develop reference materials for assay calibration.
- Government Agencies:USDA APHIS and state agricultural departments operate centralized laboratories for regulatory confirmation testing.
Dominant procurement volume: Commercial Poultry Farms. Steepest expansion trajectory: Government Agencies under strengthened biosecurity mandates.
Species:
Disease pressure and export market access requirements create divergent diagnostic intensity across avian categories.
- Broilers:High-throughput screening for Salmonella enterica serovars dominates processing facility protocols. Rapid test cassettes supply North American integrators operating under FDA Veterinary Feed Directive guidelines.
- Layers:Sustained production cycles demand continuous monitoring for avian influenza and Newcastle disease virus. Molecular screening preserves flock value across extended laying periods.
- Turkeys:Seasonal production concentrates testing demand during autumn processing windows.
- Ducks:Reservoir status for influenza subtypes drives surveillance intensity in Southeast Asian production clusters.
Highest test frequency: Broilers. Gaining share fastest: Layers under extended-cycle health management protocols.
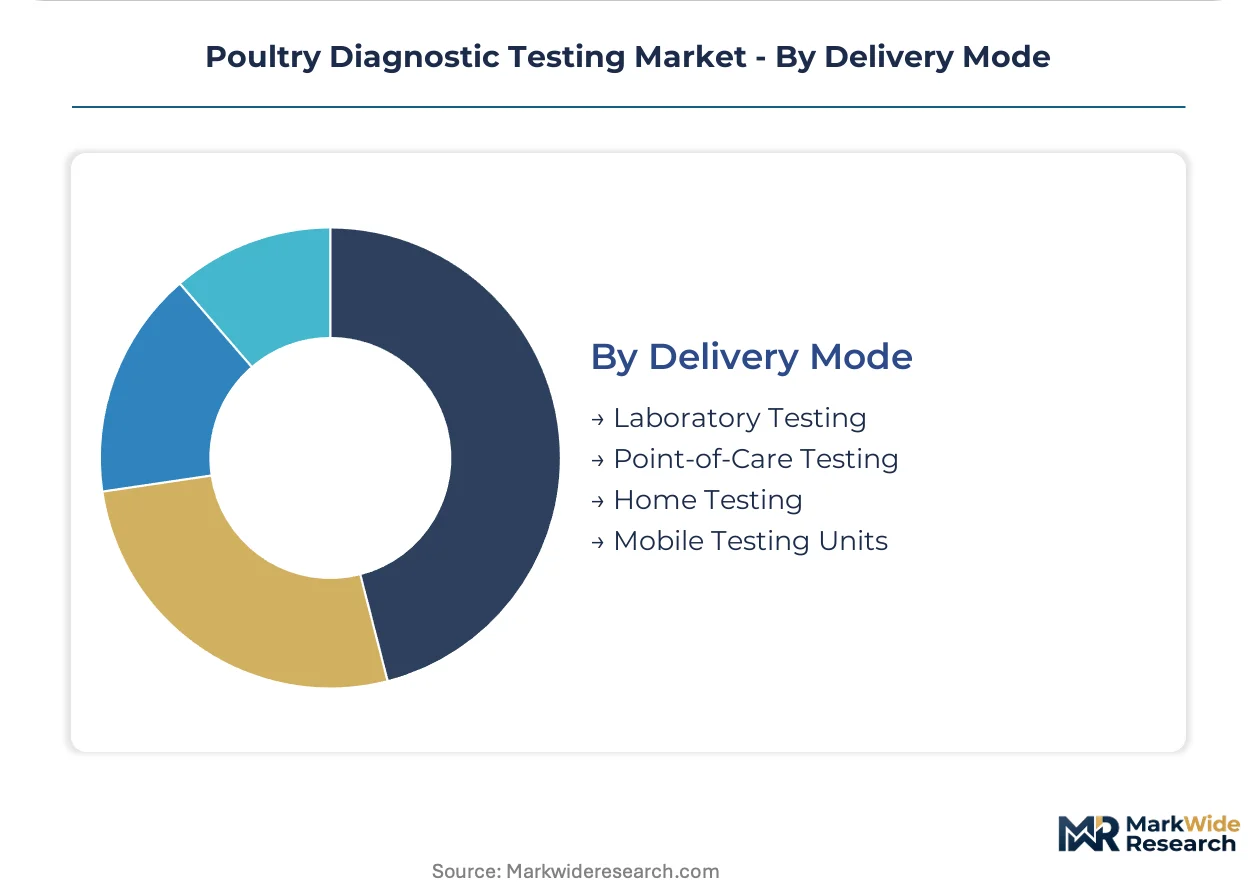
Delivery Mode:
Cold-chain dependencies and technical skill requirements fragment workflows between centralized and distributed poles.
- Laboratory Testing:Centralized facilities process multiplex PCR panels with reference-grade sensitivity. EU F-Gas Regulation forces validation of lyophilized reagent stability under ambient transport conditions.
- Point-of-Care Testing:Field-deployable LAMP kits eliminate infrastructure requirements. Southeast Asian integrators pilot CRISPR-smartphone combinations for Newcastle disease screening at farm gate checkpoints.
- Mobile Testing Units:Veterinary service vehicles extend molecular capability to remote production regions lacking fixed laboratory infrastructure.
- Home Testing:Limited penetration due to regulatory restrictions on unsupervised pathogen detection and result reporting.
Installed base leader: Laboratory Testing. Expanding most quickly: Point-of-Care Testing through thermostable polymerase formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors diagnostic procurement intensity across Brazil's integrated poultry belt, where exporters maintain continuous molecular screening to preserve EU market eligibility under sanitary certification protocols.
United States
Commercial integrators in the Southeast and Midwest maintain high-throughput PCR infrastructure to satisfy USDA APHIS biosecurity mandates. The FDA Veterinary Feed Directive positions diagnostic kits as mandatory gatekeepers for antibiotic stewardship decisions. Georgia and Arkansas production clusters deploy rapid test cassettes at farm gate checkpoints under state-level surveillance programs.
Brazil
Integrated producers in São Paulo and Paraná convert diagnostic spending from discretionary to operational necessity to safeguard export eligibility. ANVISA coordinates with EFSA on strain notification timelines, forcing parallel validation protocols. The southern production belt concentrates molecular screening capacity for continuous serological documentation.
Germany
Laboratories in Lower Saxony and Bavaria reformulate PCR master mixes with thermostable polymerase variants to satisfy EU F-Gas Regulation cold-chain requirements. The country's national pharmaceutical regulator enforces reference-grade sensitivity standards for centralized testing facilities. Leipzig and Munich clusters specialize in lyophilized reagent stability validation under ambient transport conditions.
China
Yangtze River Delta producers deploy LAMP platforms for avian influenza surveillance in reservoir duck populations. NMPA oversight of veterinary diagnostic devices accelerates registration pathways for field-deployable nucleic acid kits. Shandong Peninsula integrators pilot CRISPR-smartphone combinations for Newcastle disease screening at processing facility entry points.
Netherlands
Randstad diagnostic laboratories validate temperature-stable reagent kits to comply with hardened EU cold-chain requirements for vaccine transport. EFSA pathogen thresholds drive species-specific ELISA portfolio calibration across Utrecht and Rotterdam testing hubs. The Eindhoven Region anchors thermostable polymerase research for ambient-condition master mix formulations.
Poultry Diagnostic Testing Market Competitive Landscape
The competitive structure tilts toward integrated technology-platform providers with captive software ecosystems. Three to five multinational conglomerates dominate high-throughput molecular infrastructure, while mid-sized specialists occupy species-specific immunoassay niches. Strategic archetypes include vertically integrated diagnostic-platform vendors, regional reagent manufacturers with chemical supply advantages, and point-of-care specialists with field-deployment expertise. Competitive intensity concentrates on M&A activity targeting nucleic acid amplification technology portfolios and strategic partnerships bundling diagnostic subscriptions with veterinary service contracts.
Within the integrated-platform tier, IDEXX Laboratories and Thermo Fisher Scientific exemplify archetypes linking farm-level sampling to centralized analytics. Neogen Corporation anchors the manufacturing-scale segment with high-throughput production lines supplying North American integrators. BioChek occupies the European specialist position with portfolios calibrated to EFSA thresholds. These three entities collectively represent the divergence between software-integrated ecosystems, manufacturing-scale commodity supply, and regulatory-calibrated regional specialization.
| Leading Market Players |
|---|
| BioChek |
| BioNote, Inc. |
| IDEXX Laboratories, Inc. |
| Neogen Corporation |
| bioMérieux |
| Thermo Fisher Scientific Inc. |
| GD Animal Health |
| IDvet |
| Zoetis Services LLC |
| Others |
Value Network & Pricing Analysis
Taq polymerase and oligonucleotide reagent costs originating in German and Japanese chemical clusters cascade through three distinct pricing tiers before reaching poultry integrators in São Paulo and Georgia. Cold-chain logistics for temperature-sensitive master mixes absorb margin at each handoff, forcing reformulation investments that stratify final kit pricing by stability certification grade.
Pricing Analysis
Throughput-based subscription pricing anchors the molecular diagnostics segment, with Brazilian exporters paying premium rates for same-day turnaround guarantees tied to EU sanitary certification. Price differentiation separates reference-grade multiplex PCR panels from rapid lateral flow cassettes by sensitivity threshold and regulatory validation depth. Pricing pressure stems from enzyme cost volatility in concentrated chemical supply hubs. Commercial poultry farms exhibit highest price sensitivity, while government reference laboratories prioritize accuracy over unit economics.
Supply Chain Analysis
Freight costs for lyophilized reagent stabilization have reshaped procurement geography, with ambient-stable formulations now commanding logistics savings that offset higher polymerase input costs. Manufacturing concentrates in Germany, Japan, and the United States for thermostable enzyme production. Raw material dependencies center on fluorophore dyes, synthetic primers, and diagnostic-grade plastics. Single-source vulnerability in oligonucleotide synthesis exposes producers to regional production disruptions. Distribution runs through veterinary service distributors with cold-chain capability or direct-to-integrator subscription fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race, with captive control over thermostable polymerase supply emerging as the decisive margin lever. Players securing upstream enzyme production or downstream veterinary service networks will capture pricing power across the forecast horizon.
For Market Incumbents: Hedge against CRISPR-based platform displacement by acquiring point-of-care specialists with field-deployment expertise. Consolidate position through backward integration into thermostable polymerase manufacturing, reducing exposure to German and Japanese chemical cluster price shocks. Lock in multi-year diagnostic subscriptions with Brazilian exporters before ambient-stable LAMP kits commoditize same-day molecular screening. For New Entrants and Emerging Players: Fragmented veterinary stations in Nigeria and Kenya represent the most penetrable buyer archetype, lacking nucleic acid extraction personnel but facing intensifying avian influenza surveillance mandates. Deploy smartphone-readout LAMP platforms with cloud-based epidemiological mapping to bypass laboratory infrastructure requirements. Partner with mobile veterinary service networks for distribution reach rather than building direct sales capacity. For Investors and Strategic Acquirers: ANVISA-EFSA strain notification timeline convergence is the leading indicator that parallel validation burden will consolidate toward harmonized standards, favoring manufacturers with existing dual-dossier capabilities. Target acquisition candidates with lyophilized reagent stability validation and ambient transport certification. Monitor blockchain-immobilized diagnostic result pilots as the signal for premium export certification differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Thermostable Polymerase Backward Integration | Captive enzyme supply insulates margin from German and Japanese chemical cluster volatility. |
| Multi-Year Diagnostic Subscription Bundling | Brazilian integrators convert transactional kit purchases to recurring revenue under EU export compliance pressure. |
| Lyophilized Reagent Ambient Stability Validation | EU F-Gas Regulation compliance enables cold-chain elimination and logistics cost compression. |
| CRISPR-Smartphone Platform Development | Southeast Asian Newcastle disease pilots demonstrate farm gate point-of-care viability without laboratory infrastructure. |
| Blockchain Export Certification Integration | Immutable diagnostic result ledgers differentiate premium providers under EFSA pathogen threshold documentation requirements. |
Research Methodology
Independent corroboration across veterinary diagnostic laboratory directors, poultry integrator procurement officers, and regulatory affairs specialists at ANVISA and EFSA underwrites the qualitative findings. Primary interviews with thermostable polymerase manufacturing leads and veterinary service contract managers supplied operational detail. Secondary validation drew from USDA APHIS surveillance program disclosures, EFSA pathogen threshold documentation, and OIE strain notification databases. Bottom-up test volume modeling triangulated against top-down molecular infrastructure capacity estimates across the analysis window.
Rate-of-change decomposition structured the analytical framework, segmenting growth by test type, delivery mode, species category, and end-user procurement authority across the projection horizon. Multiplex PCR and LAMP platform adoption curves, EU export certification compliance intensity, and antibiotic stewardship diagnostic gatekeeping penetration served as industry-specific forecast inputs. CAGRs were derived from installed base expansion rates and replacement cycle dynamics rather than extrapolated trend fitting.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to avian metapneumovirus strain emergence and corresponding reference material availability disruptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Testing Services
Animal Feed Testing Market
Agricultural Testing Services
Irrigation Testing Kit Market
Agricultural Testing Services
Soil Testing Kit Market
Agricultural Testing Services
Agrochemicals Testing and Inspection Service Market
Agricultural Testing Services
Soil Sampling Services Market
Agricultural Testing Services
Europe Feed Testing Market
Agricultural Testing Services
Soil Field Testing Equipment Market
Agricultural Testing Services
Seed Testing Services Market
Agricultural Testing Services
Pesticide Detection Market
Agricultural Testing Services
Nematode Testing Services Market
Agricultural Testing Services
Feed Testing Market
Agricultural Testing Services
Asia Pacific Feed Testing Market
Agricultural Testing Services
Soil Erosion Testing Market
Agricultural Testing Services
Plant Disease Diagnostic Market
Agricultural Testing Services
Plant Nutrient Testing Equipment Market
Agricultural Testing Services
Rapid Mycotoxin Detection Systems for Grain Handling Facilities Market