
 Rapid Mycotoxin Detection Systems for Grain Handling Facilities Market | 2026-2036
Rapid Mycotoxin Detection Systems for Grain Handling Facilities Market Size, Share, and Industry Trends Forecast 2026-2036
Rapid Mycotoxin Detection Systems for Grain Handling Facilities Market Insights
Large commercial grain elevators are rotating procurement priority toward in-house testing capabilities, displacing reliance on third-party laboratory turnaround. Neogen leverages its diagnostic reagent manufacturing scale to supply high-throughput ELISA platforms direct to cooperative buyers. Eurofins Scientific anchors its competitive position through integrated laboratory-to-on-site service bundling across North American grain corridors. Charm Sciences differentiates via lateral flow device portfolios calibrated for aflatoxin and fumonisin dual detection at elevator intake bays.
Rapid mycotoxin detection systems comprise portable analytical instruments and consumable test kits engineered to identify fungal metabolites in cereal grains within minutes of sampling. These systems typically achieve detection thresholds at parts-per-billion sensitivity using antibody-based recognition or spectroscopic fingerprinting, enabling grain handlers to segregate contaminated lots before commingling into storage silos. Lateral flow devices currently dominate transaction volume due to minimal operator training requirements and field-deployable form factors, though biosensor architectures are capturing R&D investment for multiplexed toxin panels. Fluorescence-based detection methods sustain premium pricing positions where regulatory audits mandate documented chain-of-custody compliance.
The FDA enforces aflatoxin action levels under the Food Safety Modernization Act, compelling grain handlers to maintain verifiable testing records at receiving points. EPA coordination on mycotoxin environmental fate supports state-level grain inspection protocols, while ISO 17025 accreditation requirements shape vendor qualification criteria for detection system suppliers. Stakeholders must monitor evolving harmonization between FDA guidance and Codex Alimentarius international standards as export-bound grain faces dual compliance verification.
Market Dynamics
Commercial grain elevators are displacing third-party laboratory dependencies with in-house rapid testing infrastructure, compressing intake-to-storage decision cycles from days to minutes at harvest peaks.
Growth Catalysts
- FSMA Enforcement Intensification:The FDA's updated aflatoxin surveillance mandates at grain intake points create binding compliance requirements that only on-site detection systems can satisfy operationally.
- Corn Belt Moisture Conditions:Harvest-season humidity patterns across Iowa, Illinois, and Nebraska elevate fungal contamination risk, concentrating equipment procurement among elevator cooperatives in these states.
- Biosensor Multiplexing:Emerging antibody-array architectures enable simultaneous aflatoxin-fumonisin detection in single assays, reducing per-test consumable costs for high-volume handlers.
Market Restraints
- Consumables Cost Volatility:Monoclonal antibody production concentrates among a limited supplier base, exposing test kit pricing to bioreactor input fluctuations.
- ISO 17025 Accreditation Barriers:Third-party laboratory incumbents leverage existing certification infrastructure to delay on-site system validation timelines for elevator operators.
- Spectroscopic System Substitutes:Near-infrared screening platforms for protein and moisture content threaten to absorb capital budgets that might otherwise fund dedicated mycotoxin detection.
Strategic Opportunities
- Underpenetrated Export Terminals:Gulf Coast grain export facilities in Louisiana and Texas maintain minimal on-site mycotoxin verification, creating white space for rapid system deployment ahead of vessel loading.
- Organic Grain Premium Channels:Certified organic handlers face stricter fungal metabolite thresholds than conventional operations, opening premium pricing for validated detection workflows.
- Blockchain Traceability Convergence:Integration of detection system outputs with distributed ledger documentation creates auditable chain-of-custody records that satisfy EU importer due diligence requirements.
Industry Challenges
- Operator Training Deficits:Rural elevator workforces lack sufficient analytical chemistry literacy to execute ELISA protocols without repeated manufacturer field support.
- Legacy Silo Management System Integration:Proprietary data formats from 1990s-era grain handling software resist API connectivity with modern detection instrument outputs.
- Cross-Contamination Protocol Complexity:Elevators handling both corn and wheat must maintain separate sampling equipment calibrations, multiplying maintenance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rapid Mycotoxin Detection Systems for Grain Handling Facilities Market |
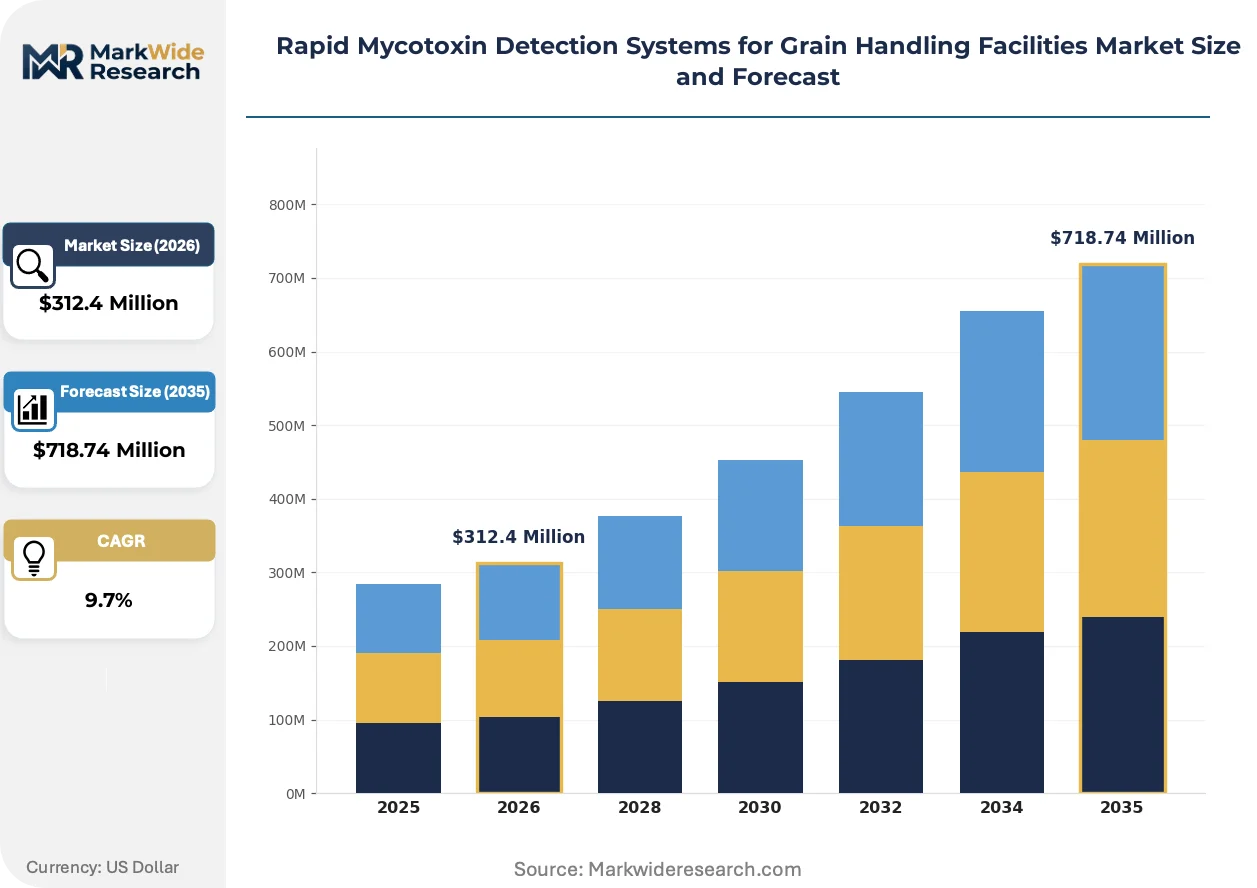
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $718.74 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassay Kits, Lateral Flow Devices, Chromatographic Test Strips, Biosensors, ELISA Kits Technology: Fluorescence, Enzyme-Linked Immunosorbent Assay, Near-Infrared Spectroscopy, Electrochemical Sensing, Polymerase Chain Reaction, Microfluidics Detection Application: Corn, Wheat, Barley, Rice, Oats, Sorghum End User: Grain Inspectors, Storage Managers, Logistics Operators, Quality Assurance Teams |
| Companies Covered | Charm Sciences, Neogen, Envirologix, Vicam, Romer Labs, Eurofins Scientific, SGS, Intertek, Bureau Veritas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rapid Mycotoxin Detection Systems for Grain Handling Facilities Market Trends and Innovations
Detection hardware is miniaturizing while sensitivity thresholds tighten, compressing the form-factor-to-performance tradeoff that previously favored laboratory-scale equipment.
Surface plasmon resonance biosensors are miniaturizing into handheld units capable of parts-per-billion aflatoxin quantification without chromatographic separation. Large cooperative elevators in Kansas and Minnesota are piloting these devices during 2024 harvest intake. The technology is miniaturizing what previously required benchtop fluorescence readers into battery-operated field units, collapsing capital cost barriers for mid-scale grain handlers.
EPA coordination with state agriculture departments on mycotoxin environmental fate is tightening documentation requirements for grain destined for animal feed channels. This interagency alignment is extending testing obligations beyond human food safety into livestock supply chains. Corn-soybean operations in Indiana and Ohio are responding by installing dual-use detection systems that satisfy both FDA food safety and emerging EPA feed-grade protocols.
Elevator procurement committees are unbundling after-sales service contracts from initial equipment purchases, treating calibration support and reagent supply as separately negotiated recurring spend categories. This purchasing behavior shift is pressuring detection system vendors to disclose consumable pricing transparency they previously obscured within bundled proposals. The unbundling trend is most visible among multi-facility cooperative networks in the Dakotas, where centralized procurement offices apply standardized RFP templates across geographically dispersed elevators.
Rapid Mycotoxin Detection Systems for Grain Handling Facilities Market Segmentation
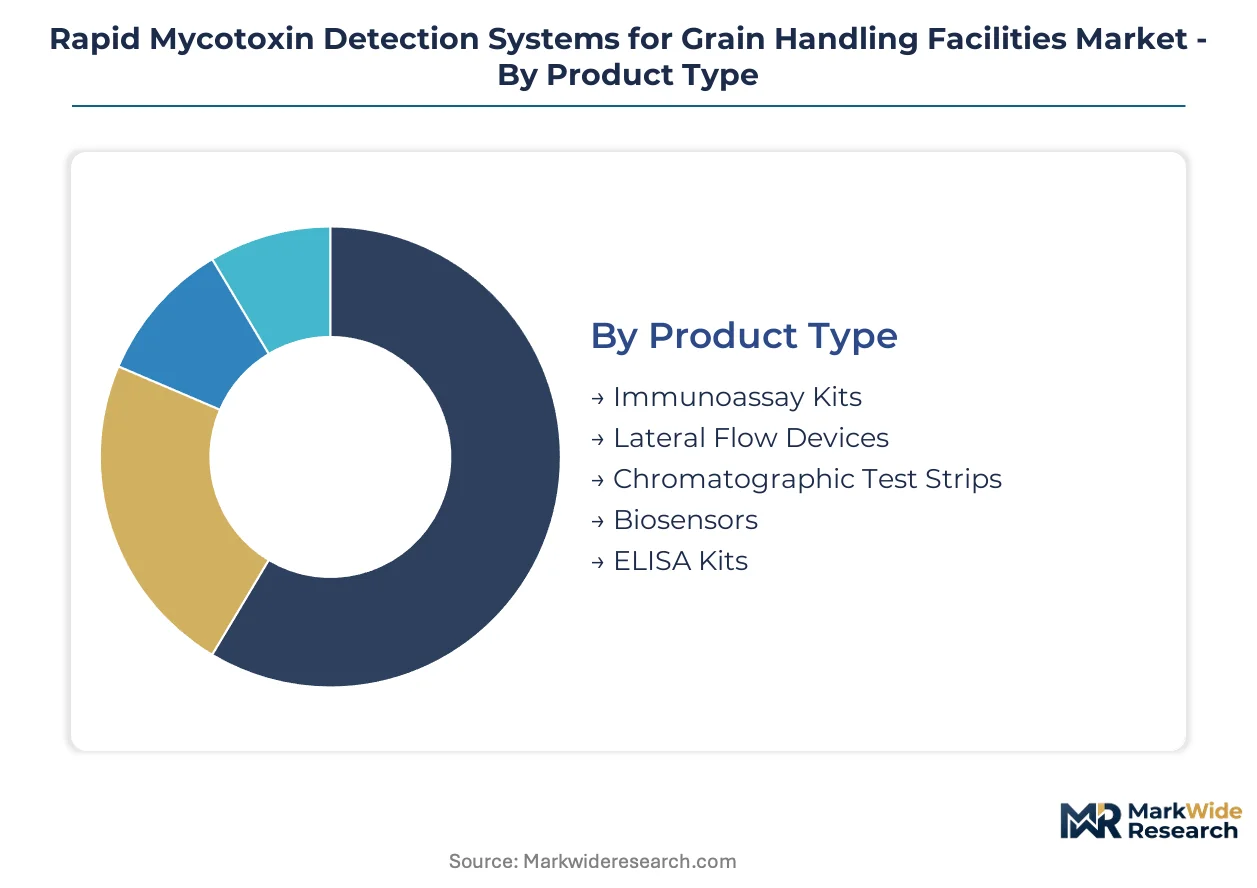
Segmentation in rapid mycotoxin detection systems reveals divergent margin structures across hardware platforms, consumable formats, and operational workflows. Equipment vendors optimize pricing strategies around detection sensitivity thresholds, while grain handlers prioritize throughput economics at harvest intake points.
Product Type:
Premium margins concentrate in proprietary reagent formats and integrated instrument-consumable bundles that lock in recurring revenue streams.
- Lateral Flow Devices:Antibody-impregnated membrane strips deliver visual or reader-based results within 5-15 minutes without laboratory infrastructure. Elevator cooperatives in Iowa and Illinois deploy these at truck intake bays during peak harvest windows when sample volume overwhelms laboratory capacity.
- Biosensors:Miniaturized transducer platforms achieve parts-per-billion sensitivity through surface plasmon resonance or electrochemical signal amplification. Pilot installations at Kansas and Minnesota cooperatives are validating handheld units for simultaneous aflatoxin-fumonisin quantification.
- Immunoassay Kits:Reagent-based formats requiring external readers or incubation steps.
- Chromatographic Test Strips:Thin-layer separation methods for confirmatory testing.
- ELISA Kits:Plate-based enzyme immunoassay formats with laboratory workflow requirements.
Lateral flow devices hold installed capacity. Biosensors are rotating up the share rankings.
Technology:
Capital intensity varies dramatically across optical, biological, and electrochemical detection principles.
- Fluorescence:Excitation-emission spectroscopy achieves regulatory-grade quantification with documented chain-of-custody compliance. Large commercial elevators serving export markets invest in benchtop fluorometers to satisfy EU importer due diligence requirements.
- Enzyme-Linked Immunosorbent Assay:Colorimetric or chemiluminescent readout from antibody-antigen binding reactions. Cooperative quality assurance teams across Nebraska and South Dakota favor ELISA platforms for their established ISO 17025 validation pathways.
- Near-Infrared Spectroscopy:Non-destructive screening using chemometric models for protein and moisture content.
- Electrochemical Sensing:Amperometric or potentiometric transduction for portable field deployment.
- Polymerase Chain Reaction:DNA-based fungal species identification preceding toxin quantification.
- Microfluidics:Lab-on-chip architectures integrating sample preparation with detection.
Fluorescence maintains premium positioning. Microfluidics is climbing the fastest in R&D allocation.
Detection Application:
Commodity-specific contamination risk profiles drive equipment specification requirements.
- Corn:Aflatoxin and fumonisin screening dominates procurement budgets due to FDA action levels and moisture susceptibility during storage. Iowa and Illinois elevators allocate capital disproportionately toward corn-dedicated testing infrastructure.
- Wheat:Deoxynivalenol and zearalenone detection requirements for bread and durum grades. Elevators in the northern Plains states handling spring wheat invest in DON-calibrated assay formats.
- Barley:Malt-grade specifications requiring DON thresholds below feed-grade limits.
- Rice:Aflatoxin surveillance for domestic and export food safety compliance.
- Oats:T-2 and HT-2 toxin screening for specialty grain channels.
- Sorghum:Emerging detection protocols for bird-resistant hybrid varieties.
Corn commands testing volume leadership. Wheat is gaining share fastest among diversified grain handlers.
End User:
Workflow integration requirements fragment purchasing authority across operational roles.
- Grain Inspectors:Field-deployable devices with minimal calibration drift for official grade determination. USDA-licensed inspectors at country elevators in Indiana and Ohio require documented accuracy traceability.
- Quality Assurance Teams:Laboratory-grade instrumentation with LIMS connectivity for regulatory audit preparation. Multi-facility cooperatives centralize QA oversight across geographically dispersed elevators.
- Storage Managers:Bin intake decisions prioritizing speed over analytical precision.
- Logistics Operators:Load-out verification for contract specification compliance.
Grain inspectors hold procedural authority. Quality assurance teams are rotating up the influence rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grain elevator cooperatives and commercial storage operators concentrate procurement authority across four distinct national markets, each shaped by harvest logistics, regulatory enforcement intensity, and export corridor positioning.
United States
Iowa and Illinois elevators deploy lateral flow devices at truck intake bays during peak harvest windows when sample volume overwhelms laboratory capacity. The FDA enforces aflatoxin action levels under the Food Safety Modernization Act, compelling handlers to maintain verifiable testing records at receiving points. Kansas and Minnesota cooperatives pilot handheld biosensor units for simultaneous aflatoxin-fumonisin quantification during 2024 harvest intake.
Brazil
Mato Grosso and Paraná grain terminals invest in rapid detection infrastructure to satisfy EU importer due diligence requirements for export-bound corn and soybeans. The country's national agricultural regulator tightens surveillance protocols for mycotoxin contamination in animal feed channels. Santos port corridor facilities accelerate procurement of fluorescence-based systems to document chain-of-custody compliance ahead of vessel loading.
Argentina
Buenos Aires province exporters face heightened aflatoxin scrutiny from Chinese and European buyers, driving adoption of ISO 17025-validated detection workflows. The central grain inspection service mandates documented testing records for all export-bound shipments. Rosario grain hub operators consolidate procurement decisions through cooperative networks to standardize reagent supply contracts across multiple elevator facilities.
Canada
Prairie province wheat handlers in Saskatchewan and Manitoba invest in deoxynivalenol-calibrated assay formats to satisfy malt-grade specifications below feed-grade limits. Health Canada coordination with the Canadian Grain Commission tightens documentation requirements for mycotoxin surveillance in food and feed channels. Vancouver export terminal operators lag in on-site verification capacity, creating deployment opportunities ahead of vessel loading.
Rapid Mycotoxin Detection Systems for Grain Handling Facilities Market Competitive Landscape
Player mix skews toward diagnostic reagent manufacturers with captive antibody production capacity and third-party testing laboratories extending into on-site service bundling. The market structures around three strategic archetypes: integrated laboratory-to-field service providers, specialized rapid test kit manufacturers, and diversified analytical instrumentation conglomerates. Competitive moves concentrate on geographic expansion through cooperative procurement networks and technology licensing agreements for multiplexed biosensor architectures.
Within the specialized rapid test kit tier, Charm Sciences exemplifies lateral flow device portfolios calibrated for dual-toxin detection at elevator intake bays. Neogen anchors the diagnostic reagent manufacturing archetype through direct supply relationships with cooperative buyers. Eurofins Scientific occupies a position among integrated service providers bundling laboratory validation with on-site deployment support across North American grain corridors.
| Leading Market Players |
|---|
| Charm Sciences |
| Neogen |
| Envirologix |
| Vicam |
| Romer Labs |
| Eurofins Scientific |
| SGS |
| Intertek |
| Bureau Veritas |
| Others |
Pricing and Supply Chain Analysis
ISO 17025 accreditation gates both supplier qualification and price differentiation simultaneously, as elevator cooperatives refuse uncertified detection systems regardless of cost advantage while paying premiums for validated chain-of-custody documentation. This certification barrier fragments pricing power across antibody manufacturers, instrument assemblers, and service bundlers.
Pricing Analysis
Next-generation biosensor platforms command 40-60% premiums over incumbent lateral flow devices, while legacy ELISA systems face accelerating price erosion at the economy tier. Three-tier pricing structure across premium fluorescence-based systems, standard ELISA platforms, and economy lateral flow strips dominates procurement negotiations. Pricing pressure stems from cooperative procurement offices unbundling service contracts and demanding consumable transparency. Small country elevators exhibit highest price sensitivity, while export-facing commercial elevators prioritize compliance-grade systems regardless of cost.
Supply Chain Analysis
Monoclonal antibody production concentrates in the United States, Germany, and China, creating single-source vulnerability for detection kit manufacturers dependent on bioreactor capacity. Supply chains draw from recombinant protein expression systems, specialized membrane substrates, and precision optical components. Tariff exposure on Chinese-sourced lateral flow membranes threatens margin stability for mid-tier kit assemblers. Distribution runs through cooperative procurement networks that centralize reagent purchasing across geographically dispersed elevator facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of analytical chemistry literacy among rural elevator workforces constrains technology diffusion, creating competitive advantage for vendors who embed training protocols into hardware design rather than treating education as aftermarket service.
For Market Incumbents: Consolidate antibody production capacity through captive bioreactor investment or exclusive supply agreements, insulating test kit margins from input volatility. Lock in cooperative procurement networks with multi-year reagent supply contracts that penalize switching costs. Defend against emerging biosensor substitutes by accelerating fluorescence platform miniaturization to match field-deployable form factors. For New Entrants and Emerging Players: Lead with handheld multiplex biosensor architectures targeting Gulf Coast export terminals in Louisiana and Texas, where on-site verification capacity remains minimal ahead of vessel loading. Penetrate organic grain certification channels with premium-priced detection workflows satisfying stricter fungal metabolite thresholds than conventional operations. Deploy blockchain-integrated documentation as differentiated go-to-market positioning for EU-bound export handlers. For Investors and Strategic Acquirers: FSMA enforcement intensification reshapes the acquisition landscape toward diagnostic reagent manufacturers with captive antibody production and established ISO 17025 validation pathways. Long-term viability favors integrated laboratory-to-field service providers over pure hardware vendors exposed to commoditization. Target acquisition archetypes include regional testing laboratories with grain corridor relationships and biosensor startups with surface plasmon resonance miniaturization patents. Watch EPA coordination with state agriculture departments on feed-grade mycotoxin documentation as signal for regulatory scope expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Antibody Production Backward Integration | Captive bioreactor capacity insulates test kit margins from supplier concentration risk. |
| Handheld Biosensor Platform Launch | Surface plasmon resonance miniaturization collapses capital barriers for mid-scale grain handlers. |
| Blockchain Traceability Integration | Distributed ledger documentation satisfies EU importer due diligence for export-bound shipments. |
| Cooperative Procurement Network Lock-in | Multi-year reagent contracts with Dakota-based centralized purchasing offices secure recurring revenue. |
| Dual-Use Detection System Certification | Simultaneous FDA food safety and EPA feed-grade validation expands addressable market for corn-soybean operations. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in verifiable enforcement patterns. Grain elevator quality assurance managers, USDA-licensed inspectors, cooperative procurement directors, and diagnostic reagent manufacturing executives provided operational perspective. FDA guidance documents, EPA coordination memoranda, ISO 17025 accreditation records, and state-level grain inspection protocols supplied secondary validation. Bottom-up equipment procurement tallies triangulate against top-down market sizing from reagent consumption patterns.
Sensitivity analysis on harvest moisture variability and regulatory enforcement intensity brackets the projection range across the analysis window. Segmentation modeling incorporates product type, detection technology, commodity application, and end-user workflow integration. CAGRs derive from equipment replacement cycles, cooperative expansion capex, and export terminal infrastructure buildout assumptions. Biosensor pilot program outcomes at Kansas and Minnesota cooperatives inform technology transition timelines.
Underlying assumptions cover sustained FSMA enforcement intensity and antibody production capacity expansion, with deviation risk concentrated in monoclonal supplier consolidation and spectroscopic screening platform substitution. Practitioners should keep alternative scenarios live as EPA feed-grade documentation requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Testing Services
Impact Soil Tester Market
Agricultural Testing Services
Global Agriculture Testing Services Market
Agricultural Testing Services
Testing, Inspection, and Certification for Agriculture & Food Market
Agricultural Testing Services
Soil Field Testing Equipment Market
Agricultural Testing Services
Seed Testing Services Market
Agricultural Testing Services
Soil Testing Kit Market
Agricultural Testing Services
Agricultural Testing Services Market
Agricultural Testing Services
Agrochemicals Testing and Inspection Service Market
Agricultural Testing Services
Irrigation Testing Kit Market
Agricultural Testing Services
Pesticide Detection Market
Agricultural Testing Services
Plant Disease Diagnostic Market
Agricultural Testing Services
Feed Testing Market
Agricultural Testing Services
Soil Sampling Services Market
Agricultural Testing Services
Soil Erosion Testing Market
Agricultural Testing Services
Nematode Testing Services Market
Agricultural Testing Services
Pesticide Residue Testing Market