
 Agrochemical Active Ingredients Market | 2026-2036
Agrochemical Active Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Agrochemical Active Ingredients Market Analysis
Specialty crop growers is redrawing procurement priorities across the agrochemical active ingredients sector, shifting volume toward precision-formulated solutions that minimize off-target effects. BASF SE leverages its R&D intensity to anchor positions in fungicide chemistry, while Syngenta Crop Protection AG competes through integrated seed-and-crop-protection platforms that extend channel control. Corteva Agriscience specializes in novel herbicide modes of action that differentiate its portfolio in glyphosate-tolerant systems.
Agrochemical active ingredients comprise the biologically active chemical entities in crop protection formulations, typically synthesized through multi-step organic processes involving chlorination, nitration, or phosphorus chemistry, and dosed at grams to kilograms per hectare to control pests, diseases, or weeds. Herbicides occupy the largest share of the product-type landscape due to their essential role in broad-acre row-crop systems, while fungicides represent the fastest-growing category as climate volatility elevates disease pressure in humid growing regions. On the application dimension, agricultural use dominates absolute volume, though horticultural applications command premium pricing because of stricter residue standards and shorter pre-harvest intervals.
The EPA in the United States and the EU's EFSA jointly shape market access through divergent toxicity assessment protocols, with REACH and the EU Green Deal tightening hazard classifications that restrict certain active chemistries. India's CDSCO and the country's Central Insecticides Board impose parallel registration requirements that govern import and domestic manufacture of technical-grade materials. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and portfolio rationalization timelines.
Market Dynamics
Precision-formulated active chemistry is compressing commodity generic volumes as residue limits tighten under the EU Green Deal and Brazil's soybean expansion concentrates procurement power among integrated crop protection platforms.
Growth Catalysts
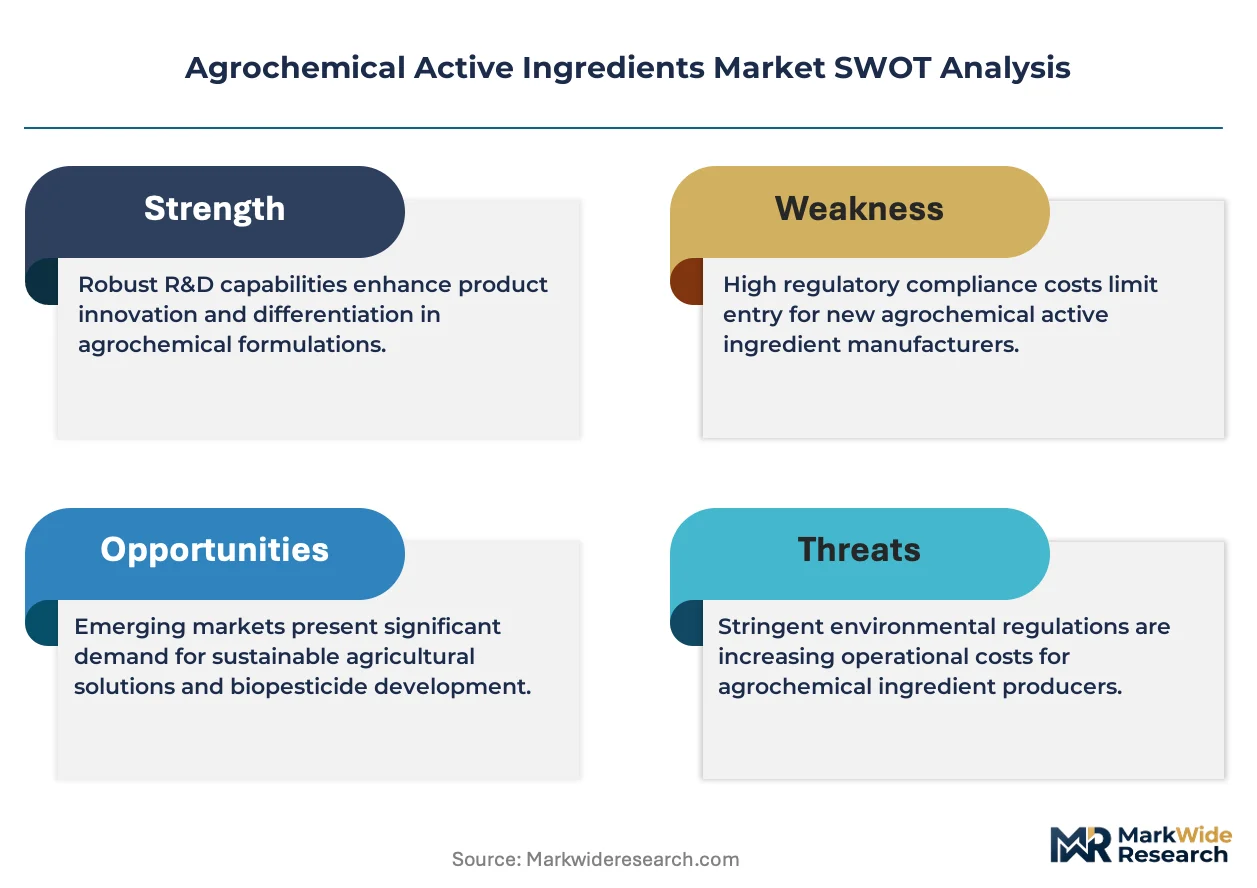
- EU Green Deal residue mandates:The Farm to Fork strategy is accelerating bio-based active ingredient registrations as synthetic chemistry faces hazard reclassification.
- Climate-driven disease pressure:Humid growing regions in Southeast Asia are elevating fungicide application frequency and precision-dosing adoption.
- Brazilian soybean intensification:Double-cropping systems are expanding herbicide and fungicide active volumes through extended growing windows.
Market Restraints
- Phosphorus and chlorinated intermediate volatility:Technical-grade precursor costs fluctuate with energy and feedstock markets, squeezing formulation margins.
- China technical manufacturing concentration:Over half of global active ingredient synthesis capacity sits in coastal chemical clusters, exposing supply to environmental enforcement disruptions.
- Glyphosate resistance proliferation:Weed biotypes resistant to broad-spectrum herbicides are forcing costly mode-of-action rotation without guaranteed efficacy.
Strategic Opportunities
- Biological actives convergence:Microbial fermentation extracts paired with synthetic chemistry are opening premium positioning in organic-transition acres.
- India domestic manufacturing incentives:PLI scheme benefits and CDSCO registration streamlining are attracting technical-grade production investment.
- Drone application compatibility:Low-volume, high-concentration formulations designed for unmanned aerial systems are capturing horticultural premium segments.
Industry Challenges
- Regulatory dossier compilation timelines:EFSA and EPA toxicity endpoint studies require multi-year mammalian and ecotoxicology datasets that delay commercialization.
- Formulation chemist scarcity:Expertise in multi-step organic synthesis and adjuvant compatibility testing is concentrating at legacy agrochemical specialists.
- Legacy equipment incompatibility:Precision-actives require closed-transfer systems and direct-injection sprayers that smallholder operations cannot retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agrochemical Active Ingredients Market |
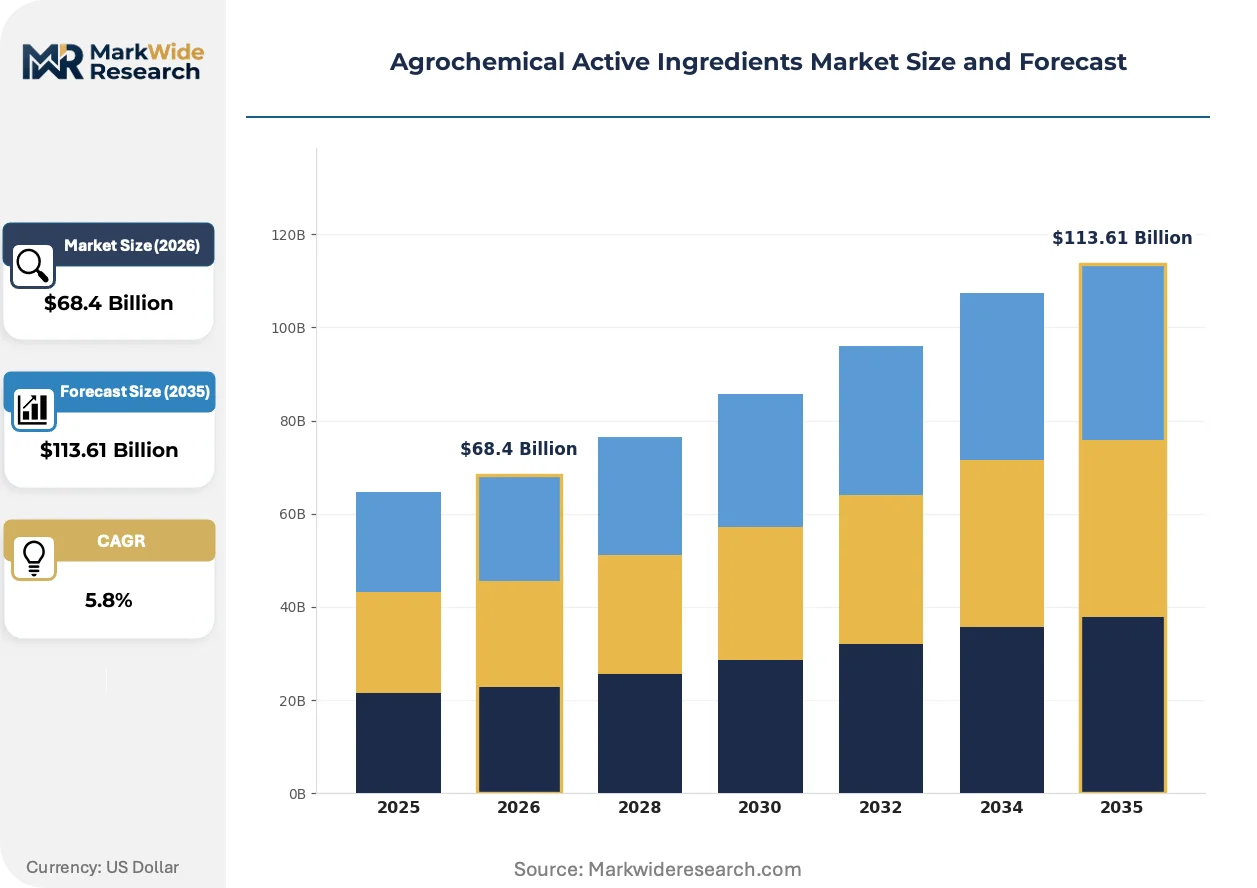
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Plant Growth Regulators Application: Agricultural, Horticultural, Forestry, Turf Management Formulation: Granules, Liquids, Tablets, Powders End User: Farmers, Agricultural Cooperatives, Distributors, Retailers |
| Companies Covered | Corteva Agriscience, Sumitomo Chemical Co., Ltd., BASF SE, Nufarm Limited, UPL Limited, Bayer CropScience AG, FMC Corporation, China National Chemical Corporation, Syngenta Crop Protection AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agrochemical Active Ingredients Market Emerging Trajectories
RNA interference and peptide-based biocontrols are advancing from experimental to pilot-scale production, while digital residue monitoring and blockchain traceability reshape how actives are validated and procured across fragmented supply chains.
RNAi-based biopesticides targeting lepidopteran pests are supplanting broad-spectrum synthetic insecticides in specialty vegetable and fruit systems. Large-scale greenhouse operators in the Netherlands and Spain are piloting foliar-applied dsRNA formulations at commercial scale. This technology is compressing the regulatory approval advantage of incumbents with legacy chemical portfolios as novel-mode-of-action timelines shorten.
REACH authorization and the EU Green Deal hazard classification overhaul are restricting neonicotinoid and certain organophosphate chemistries from renewal. Formulators are accelerating reformulation toward bio-based alternatives and low-toxicity synthetics ahead of sunset dates. Horticultural exporters to EU markets face the steepest compliance costs as maximum residue limits tighten for import certification.
Integrated pest management service contracts are displacing standalone product transactions among cooperative buying groups in Brazil and Argentina. Agronomists bundled with precision-scouting and variable-rate application recommendations now control active ingredient selection at the farm gate. This consolidation of procurement decision-making is most visible in Mato Grosso and Buenos Aires provinces where soybean acreage concentrates among 500-hectare-plus operations.
Agrochemical Active Ingredients Market Segmentation
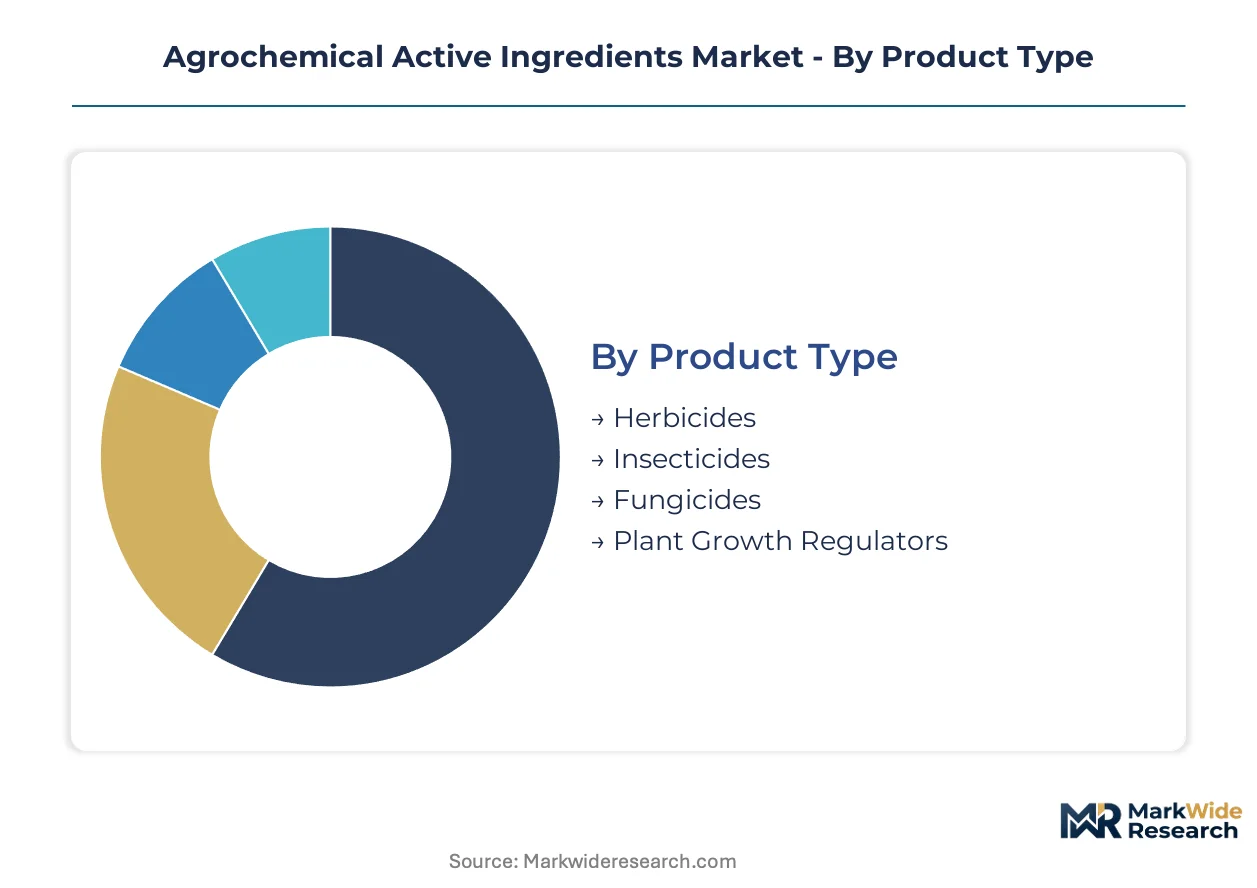
Segmentation in agrochemical active ingredients reveals divergent margin structures across product chemistry and application intensity. Formulation technology and procurement channel control determine pricing power more than volume scale alone.
Product Type:
Herbicides command the deepest margin pools due to proprietary mode-of-action patents and resistance-management bundling.
- Herbicides:These molecules disrupt photosynthesis, amino acid synthesis, or lipid metabolism in target weed species. Brazilian soybean and corn operations in Mato Grosso drive procurement concentration as double-cropping extends application windows and glyphosate-tolerant trait penetration deepens.
- Fungicides:Systemic and contact fungicides inhibit ergosterol biosynthesis or mitochondrial respiration in fungal pathogens. Southeast Asian humid growing regions are elevating application frequency as climate volatility intensifies disease pressure in rice and palm oil systems.
- Insecticides:Neurotoxic chemistries targeting acetylcholinesterase or sodium channels face neonicotinoid restrictions under EFSA hazard reclassifications.
- Plant Growth Regulators:Synthetic auxins and gibberellin inhibitors modulate crop architecture and harvest timing for high-value fruit and vegetable exporters to EU markets.
Herbicides hold installed capacity. Fungicides is rotating up the share rankings.
Application:
Agricultural use absorbs absolute volume while horticultural commands steepest price premiums per hectare.
- Agricultural:Broad-acre row-crop systems in Brazil, Argentina, and the US Midwest consume synthetic actives at kilogram-per-hectare rates. Integrated crop protection platforms are consolidating procurement decision-making among 500-hectare-plus operations.
- Horticultural:Protected cultivation in Spain's Almería and the Netherlands' Westland region requires precision-dosed actives with shortened pre-harvest intervals. EU Green Deal residue limits are forcing reformulation toward bio-based alternatives ahead of synthetic sunset dates.
- Forestry:Long-rotation timber plantations in Scandinavia and the Pacific Northwest deploy herbaceous weed control with extended residual activity requirements.
- Turf Management:Golf course and sports field maintenance in the US Sun Belt and Gulf states drives selective herbicide demand for warm-season grass species.
Agricultural use anchors volume throughput. Horticultural is expanding most quickly on value terms.
Formulation:
Liquid concentrates concentrate formulation chemist expertise and adjuvant compatibility testing capabilities.
- Liquids:Emulsifiable concentrates and suspension concentrates enable uniform droplet distribution through precision application equipment. Drone-compatible low-volume formulations are capturing horticultural premium segments in China and Japan.
- Granules:Controlled-release matrices reduce leaching risk in paddy rice systems across Southeast Asia. CDSCO registration pathways in India favor granular formulations for smallholder equipment compatibility.
- Powders:Wettable powders persist in generic procurement channels where water dispersibility meets cost minimization priorities.
- Tablets:Pre-measured dosing units serve cooperative buying groups in Brazil seeking to eliminate mixing errors and operator exposure.
Liquids hold formulation R&D concentration. Granules is climbing the fastest on volume growth.
End User:
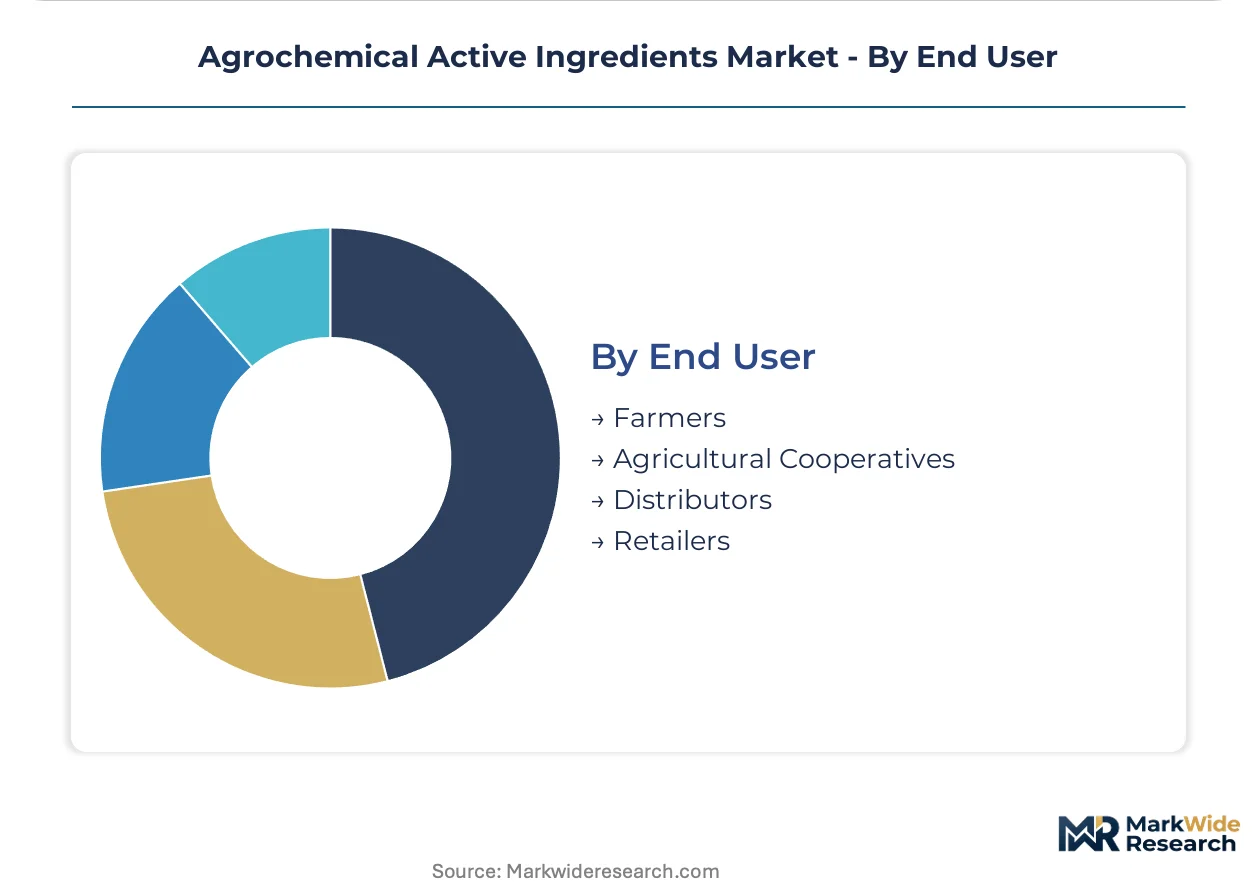
Channel structure fragments procurement influence between direct farm relationships and cooperative aggregation.
- Farmers:Large-scale operators in Brazil's Cerrado and US Corn Belt negotiate directly with integrated seed-and-crop-protection platforms. Variable-rate application technology adoption correlates with active ingredient selection autonomy.
- Agricultural Cooperatives:Buying groups in Argentina's Buenos Aires province and India's Maharashtra state aggregate volume for formulation procurement leverage. Bundled agronomic advisory services now control product selection at the farm gate.
- Distributors:Regional inventory holders manage working capital exposure to phosphorus and chlorinated intermediate price volatility.
- Retailers:Point-of-sale networks in fragmented smallholder markets face legacy equipment incompatibility with closed-transfer precision-actives.
Cooperatives hold procurement aggregation scale. Farmers is gaining share fastest on direct platform relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports technical-grade actives to formulation hubs in Brazil, India, and the European Union. Coastal chemical clusters in Jiangsu and Zhejiang provinces synthesize over half of global herbicide and fungicide intermediates. Containerized shipments move through Shanghai and Ningbo to Rotterdam, Santos, and Mumbai.
Brazil
Soybean and corn double-cropping in Mato Grosso and Goiás extends herbicide and fungicide application windows. ANVISA enforces residue limits that align with EU import standards for agricultural commodities. The Rondonópolis logistics corridor concentrates bulk formulation packaging for distribution to the Cerrado frontier.
United States
Corn and soybean operations across Iowa, Illinois, and Indiana drive glyphosate-tolerant system demand. The EPA regulates active ingredient registration through multi-year toxicity endpoint studies. The Mississippi River chemical corridor links technical synthesis in Louisiana to Midwest formulation plants.
India
Cotton and rice cultivation in Maharashtra and Gujarat sustains insecticide and fungicide procurement volumes. CDSCO and the Central Insecticides Board govern technical-grade import and domestic manufacture registration. The Gujarat Industrial Development Corporation zone near Ankleshwar attracts PLI scheme investment for captive synthesis capacity.
Germany
Sugar beet and rapeseed production in Lower Saxony and Bavaria requires precision-formulated herbicide actives. ECHA and EFSA hazard reclassifications under REACH restrict neonicotinoid and organophosphate chemistries. The BASF Ludwigshafen complex anchors European fungicide active R&D and multi-step organic synthesis.
Netherlands
Greenhouse vegetable cultivation in Westland and North Brabant demands low-residue actives with shortened pre-harvest intervals. The EU Green Deal Farm to Fork strategy accelerates bio-based alternative registrations ahead of synthetic sunset dates. Wageningen University partnerships pilot RNAi-based biocontrol field applications at commercial scale.
Agrochemical Active Ingredients Market Vendor Landscape
Listed leaders compete with private specialists across R&D intensity and channel control dimensions. The vendor base concentrates around integrated seed-and-crop-protection platforms, standalone agrochemical formulators, and state-affiliated technical manufacturers. Three archetypes dominate: chemistry-led innovators with proprietary mode-of-action pipelines, generics specialists with cost-optimized synthesis, and biological convergence players blending microbial fermentation with synthetic actives. Competitive moves center on portfolio diversification into bio-based alternatives and backward integration into technical-grade precursor supply.
Within the chemistry-led tier, BASF SE and Syngenta Crop Protection AG exemplify integrated platform operators. Corteva Agriscience occupies a position among innovators prioritizing novel herbicide modes of action. Sumitomo Chemical Co., Ltd. represents the Asia-Pacific synthesis specialist archetype with technical manufacturing scale.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Sumitomo Chemical Co., Ltd. |
| BASF SE |
| Nufarm Limited |
| UPL Limited |
| Bayer CropScience AG |
| FMC Corporation |
| China National Chemical Corporation |
| Syngenta Crop Protection AG |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Brazilian soybean cooperatives and Chinese technical-grade manufacturers lock in supply access while capping price visibility against phosphorus and chlorinated intermediate volatility. These arrangements concentrate procurement power among integrated crop protection platforms in Mato Grosso while exposing formulators to margin compression when energy feedstocks spike.
Pricing Analysis
Next-generation precision-formulated actives command 40-60% premiums over legacy generic chemistries, while prior-generation organophosphates face price erosion under EFSA hazard reclassifications. The dominant pricing structure runs through contract-based long-term offtake with volume-scale and certification-grade differentiation. Price differentiation stems from REACH compliance tier and adjuvant compatibility testing depth. Cost compression in commodity generics is intensifying because Chinese environmental enforcement disrupts technical synthesis capacity. Smallholder retailers in fragmented markets exhibit highest price sensitivity; greenhouse operators in the Netherlands show least sensitivity due to residue-limit compliance premiums.
Supply Chain Analysis
Container availability constraints on the Shanghai-to-Santos trade lane are elevating inbound logistics costs for Brazilian formulation hubs. Supply concentrates in China, India, and Germany, with coastal chemical clusters in Jiangsu and Zhejiang synthesizing over half of global herbicide and fungicide intermediates. Raw material dependencies rest on phosphorus trichloride, chlorinated aromatics, and microbial fermentation feedstocks. Single-source vulnerability from China's technical manufacturing concentration exposes the chain to environmental enforcement disruptions. Distribution runs through regional inventory holders managing working capital exposure to precursor price volatility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Multi-year EFSA and EPA toxicity dossier timelines create switching costs that protect incumbent positions against rapid displacement.
For Market Incumbents: Compound regulatory entrenchment by accelerating bio-based active registrations ahead of EU Green Deal sunset dates. Deepen backward integration into technical-grade precursor supply to offset phosphorus intermediate volatility. Channel control through integrated seed-and-crop-protection platforms defends against biological convergence entrants. For New Entrants and Emerging Players: Lead with drone-compatible low-volume formulations targeting horticultural premium segments in Japan and China where legacy equipment incompatibility blocks incumbent penetration. White-space opportunity concentrates in organic-transition acres seeking microbial-synthetic hybrid actives. Pursue CDSCO registration streamlining under India's PLI scheme to capture technical manufacturing migration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated pest management service contractors in Brazil and Argentina where agronomist bundling locks in multi-season active selection. Long-term viability favors biological convergence players with microbial fermentation capabilities paired with synthetic chemistry pipelines. Signal to watch: ANVISA residue limit alignment with EU standards accelerating bio-based procurement mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical Synthesis | Captive supply of phosphorus intermediates insulates margins from Jiangsu environmental enforcement volatility. |
| Bio-Based Active Registration Acceleration | EFSA hazard reclassifications under REACH are forcing reformulation ahead of neonicotinoid sunset dates. |
| Drone-Compatible Formulation Development | Low-volume high-concentration actives capture horticultural premiums in Japan's precision agriculture sector. |
| Integrated Pest Management Service Contracts | Agronomist bundling in Mato Grosso consolidates procurement decision-making at the farm gate. |
| CDSCO Registration Streamlining Investment | PLI scheme benefits in Gujarat attract technical-grade production away from coastal Chinese clusters. |
Methodological Framework
Initial hypotheses were tested against primary input from agrochemical R&D directors, formulation chemists, Brazilian cooperative procurement managers, and EFSA regulatory affairs specialists and refined through secondary validation. Bottom-up triangulation combined trade data from CDSCO registration filings, customs records of technical-grade imports, SEC 10-K disclosures from listed agrochemical firms, and EU pesticide residue monitoring reports with top-down macroeconomic anchoring.
Variance decomposition across the analysis window isolates volume drivers from price-mix effects in herbicide, fungicide, and insecticide segments. The framework models product chemistry, application intensity, formulation technology, and procurement channel control dimensions. CAGRs were derived from segment-level growth rate reconciliation against macro agricultural commodity price assumptions and climate-driven disease pressure indices.
Forecasts assume regulatory continuity in EU REACH authorization, EPA registration protocols, and ANVISA residue limit alignment; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agrochemicals
India Agrochemicals Market
Agrochemicals
Egypt Agrochemicals Market
Agrochemicals
Potassium Humate Market
Agrochemicals
Australia Agrochemicals Market
Agrochemicals
Superphosphates Market
Agrochemicals
South Africa Agrochemicals Market
Agrochemicals
Malaysia Agrochemicals Market
Agrochemicals
Indonesia Agrochemicals Market
Agrochemicals
North America Agrochemicals Market
Agrochemicals
South America Agrochemicals Market
Agrochemicals
Mexico Agrochemicals Market
Agrochemicals
Global Buprofezin Market
Agrochemicals
Agrochemical Market
Agrochemicals
Africa Agrochemicals Market
Agrochemicals
Global Glufosinate Market
Agrochemicals
L-Glufosinate Ammonium Market