
 UAE Agriculture Market | 2026-2036
UAE Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Agriculture Market Insights
UAE's National Food Security Strategy 2051 is repositioning the cost-of-entry calculus for commercial agriculture, conditioning subsidy access and land allocation on technology-intensive production methods. Al Dahra Holding Company leverages its integrated feed-to-food supply chain across multiple Emirates to sustain volume leadership in fodder and grains. Madar Farms specializes in vertical farming operations, occupying a premium niche in leafy greens and herbs for UAE retailers. Agthia Group anchors downstream value through its controlled distribution network, extending shelf-life logistics that complement domestic sourcing mandates.
UAE agriculture encompasses crop cultivation, livestock husbandry, and input supply within an arid-climate context where production depends on desalinated water, hydroponic substrates, and climate-controlled greenhouses to overcome sub-100mm annual rainfall. The sector serves domestic food security priorities, hospitality procurement, and re-export positioning across the Gulf. Crops and precision farming together attract the majority of new capital deployment, as hydroponics and controlled-environment systems deliver measurable water savings against conventional field methods. Livestock retains structural importance through dairy and poultry verticals, though margin pools increasingly favor technology-enabled segments over commodity protein production.
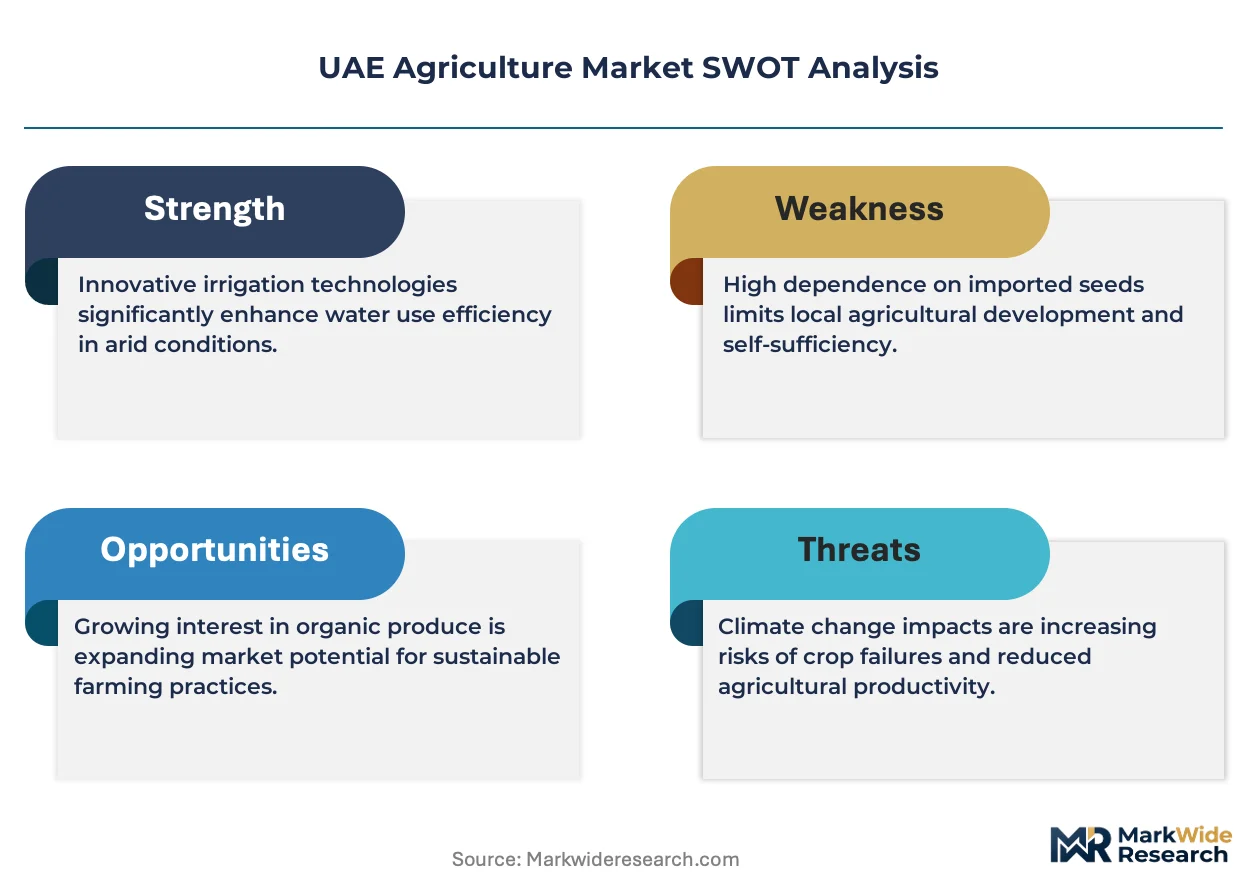
MOHAP and the Emirates Authority for Standardization and Metrology (ESMA) set product safety and labeling requirements that shape market access for seeds, fertilizers, and imported biological inputs. The UAE's dual carbon goals and green building regulations are tightening energy-use standards for greenhouse operations, favoring solar-integrated designs. Stakeholders must monitor how Abu Dhabi's AgriTech Park and Dubai's Food Tech Valley compete for project pipelines, as zone-specific incentive structures will determine where capacity localizes and which technology platforms achieve commercial scale first.
Market Dynamics
Capital allocation in UAE agriculture is pivoting decisively toward controlled-environment systems as the National Food Security Strategy 2051 conditions subsidy eligibility on technology-intensive production methods, fundamentally reshaping the cost-of-entry calculus for new entrants.
Growth Catalysts
- Abu Dhabi AgriTech Park:This government-backed zone clusters infrastructure and talent, accelerating commercialization timelines for hydroponic and vertical farming ventures seeking scale.
- Hospitality procurement mandates:UAE hotels and foodservice operators are expanding local sourcing quotas, creating guaranteed offtake channels for domestic producers of leafy greens and herbs.
- Solar-integrated greenhouse designs:Falling photovoltaic installation costs paired with green building regulations are making energy-intensive controlled-environment agriculture economically viable in desert conditions.
Market Restraints
- Desalinated water dependency:Production costs remain tethered to energy-intensive seawater desalination, with water input costs consuming disproportionate operating budgets versus rainfall-dependent agriculture elsewhere.
- Biological input concentration:Seeds, fertilizers, and beneficial microbes flow through a narrow import channel governed by MOHAP and ESMA clearance protocols, creating supply bottlenecks during regulatory review cycles.
- Substrate sourcing limitations:Hydroponic and aquaponic operations rely on imported coconut coir, rockwool, and perlite, exposing margins to shipping cost volatility and currency fluctuation.
Strategic Opportunities
- Dubai Food Tech Valley:This competing agri-tech zone offers alternative incentive structures to Abu Dhabi's park, creating location choice for ventures optimizing between tax treatment, land tenure, and proximity to export logistics.
- Controlled-environment livestock integration:Dairy and poultry verticals present underexploited terrain for precision climate control, automated feeding, and waste-to-energy systems that closed-loop operations can exploit.
- Re-export positioning:UAE's port infrastructure and Gulf trade agreements enable domestic production to serve Saudi Arabia, Kuwait, and Bahrain markets with shorter lead times than European or Asian competitors.
Industry Challenges
- Agronomic talent scarcity:Commercial-scale hydroponics and vertical farming require specialized expertise in plant physiology, nutrient solution management, and climate control engineering that local education pipelines have not yet scaled to produce.
- ESMA certification timelines:Novel biological inputs and precision equipment face extended safety and labeling review periods that delay revenue generation for product innovators.
- Legacy supply chain reconfiguration:Traditional trading relationships for imported produce resist displacement by domestic sourcing mandates, requiring sustained buyer education and quality consistency demonstration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Agriculture Market |
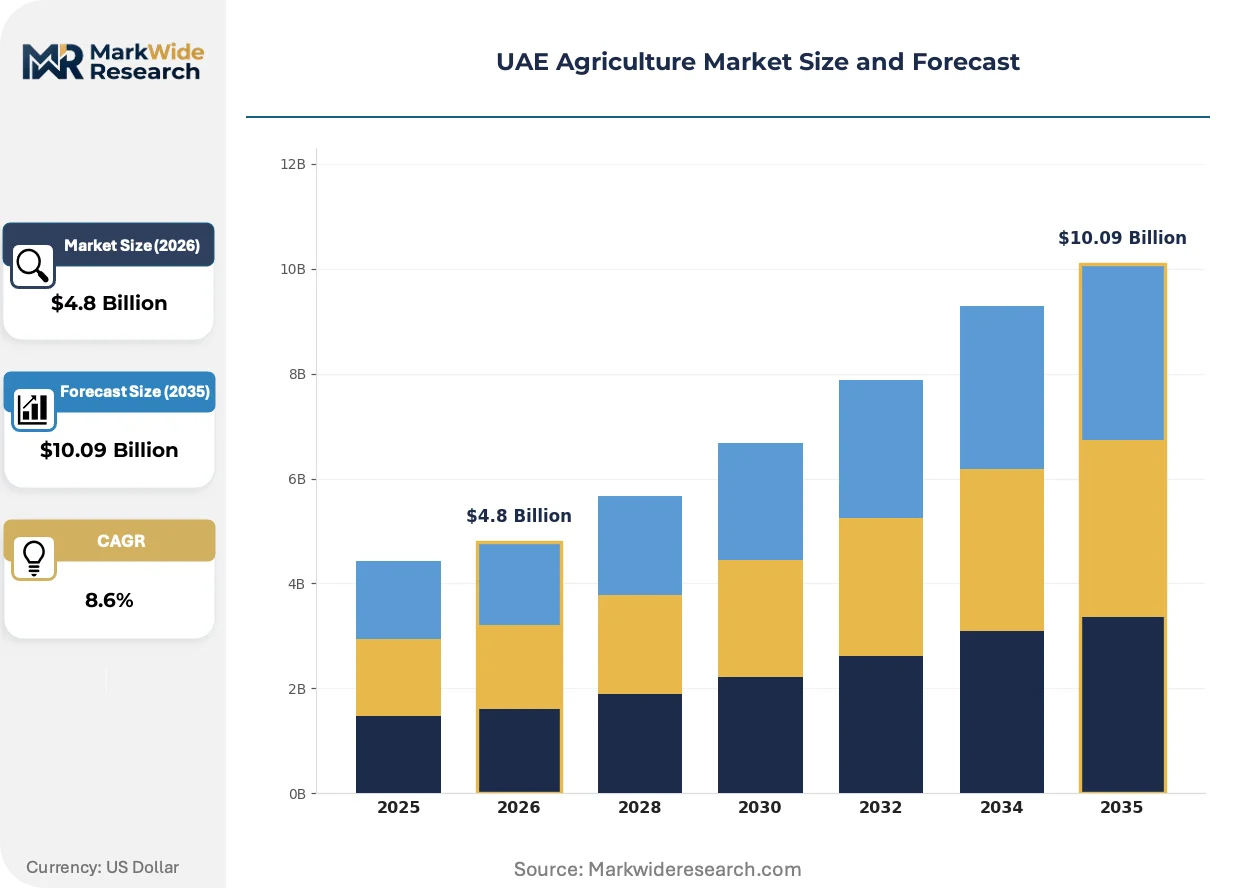
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crops, Livestock, Seeds, Fertilizers End Use Industry: Farming, Horticulture, Aquaculture, Landscape Technology: Precision Farming, Hydroponics, Aquaponics, Organic Practices Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Al Dahra Holding Company, Agthia Group, Arabian Agricultural Services Company (ARASCO), Silal, Madar Farms, iFarm Corporation, Dayma, ARDI (Agriculture Research and Development Initiative), Jenaan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Agriculture Market Trends and Innovations
Technology deployment in UAE agriculture is accelerating around three vectors: hardware modularization that reduces capital risk, regulatory tightening around carbon and energy use, and buyer-side restructuring of procurement relationships toward direct contracting with producers.
Containerized vertical farming units are modularizing entry into controlled-environment agriculture, allowing operators to deploy production capacity in 40-foot increments rather than committing to permanent greenhouse construction. UAE retailers and hospitality groups are piloting these systems on-site for hyperlocal herb supply. This modularization is compressing payback periods and enabling iterative technology upgrades without stranded asset risk.
MOHAP and ESMA are tightening energy-use disclosure requirements for agricultural facilities above defined output thresholds, paralleling broader UAE green building code evolution. Operators must now document photovoltaic integration and cooling efficiency metrics to maintain licensing. Greenhouse developers in Dubai are responding with solar-thermal hybrid designs that pre-empt enforcement risk while securing preferential grid interconnection terms.
Large UAE hospitality chains are consolidating vendor relationships through direct multi-year contracts with domestic producers, bypassing traditional produce wholesalers. This channel compression is visible in Dubai and Abu Dhabi hotel procurement, where sustainability reporting requirements favor traceable local supply. Smaller Emirates-based farms face exclusion pressure unless they achieve scale sufficient for direct contracting qualification.
UAE Agriculture Market Segmentation
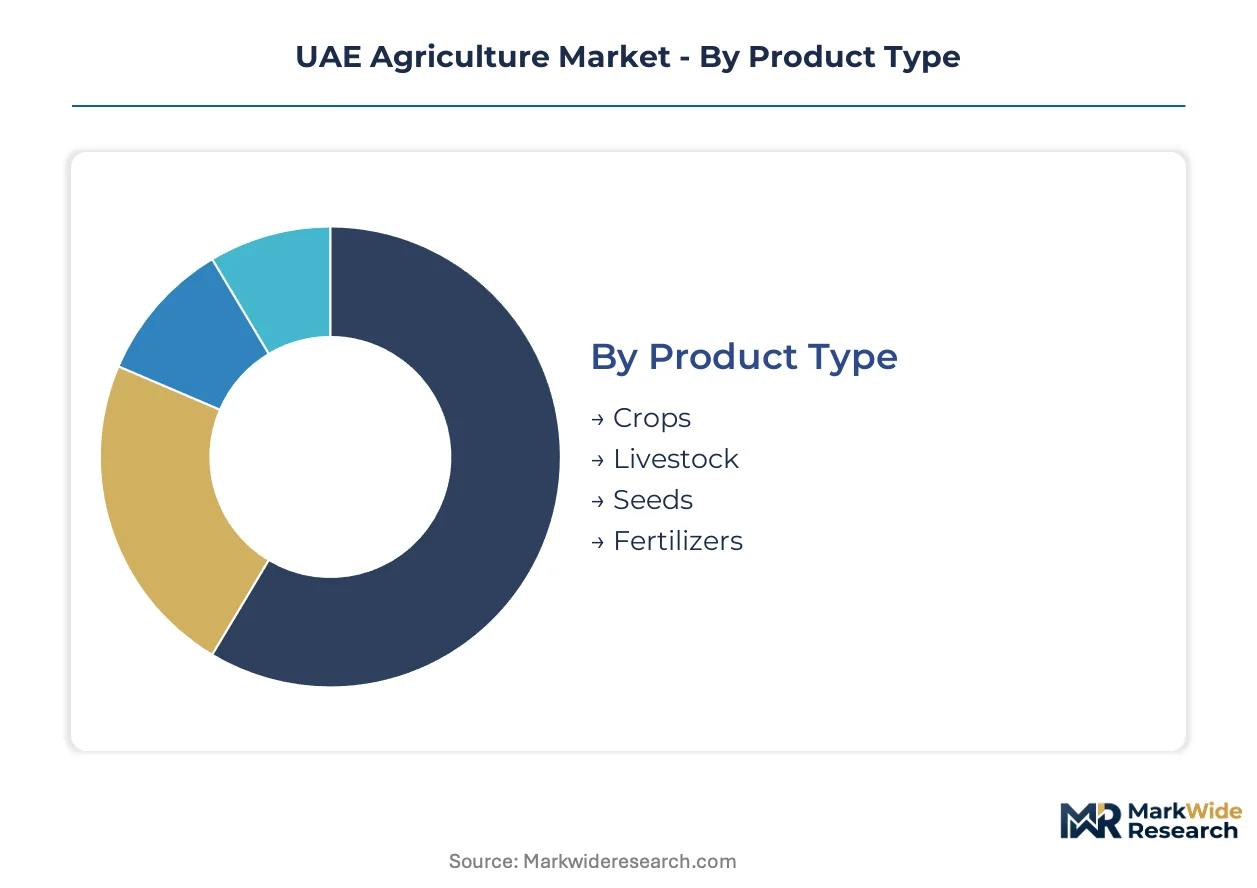
UAE agriculture segmentation reveals how technology intensity and buyer procurement power reshape competitive boundaries across product, channel, and application dimensions. Distinct margin profiles separate commodity livestock from controlled-environment crops, while distribution channel choice determines access to hospitality procurement mandates and retail shelf placement.
Product Type:
Buyers differentiate by water intensity and subsidy eligibility under National Food Security Strategy 2051 criteria, with technology-intensive categories commanding premium positioning.
- Crops:Controlled-environment production of tomatoes, cucumbers, and leafy greens dominates capital deployment, with Abu Dhabi AgriTech Park operators securing preferential land tenure and MOHAP fast-track licensing for hydroponic facilities serving Dubai hotel procurement mandates.
- Livestock:Dairy and poultry verticals retain structural importance through Al Ain Dairy and Emirates Poultry vertical integration, though margin compression from imported feed costs limits expansion relative to crop alternatives.
- Seeds:Heat-tolerant and saline-resistant varieties flow through ESMA-regulated import channels, with germination standards tightening for commercial-scale hydroponic operations.
- Fertilizers:Specialized nutrient solutions for closed-loop systems attract domestic blending investments to reduce shipping cost exposure from European and Asian suppliers.
Volume sits with Livestock; growth tilts toward Crops.
End Use Industry:
Application-specific water and energy requirements create divergent technology adoption curves across production environments.
- Farming:Arable operations concentrate in Al Ain and Ras Al Khaimah where groundwater access, however depleted, sustains date palm and fodder cultivation with partial desalination supplementation.
- Horticulture:Ornamental and edible flower production serves UAE's landscaping and hospitality sectors, with Dubai's luxury hotel procurement driving demand for pesticide-free certification and traceable supply chains.
- Aquaculture:Hamour and seabream farming in Fujairah and Umm Al Quwain leverages coastal infrastructure, though expansion faces MOHAP biosecurity protocols for imported broodstock.
- Landscape:Municipal and private landscaping consumes drought-resistant species, with Abu Dhabi Municipality mandates accelerating substitution of water-intensive lawns with native xeriscaping.
Revenue concentrates in Farming; Horticulture climbs the fastest on hospitality procurement expansion.
Technology:
Capital efficiency and water productivity metrics determine which platforms secure National Food Security Strategy 2051 subsidy qualification.
- Precision Farming:Sensor networks and automated irrigation in Al Dahra's fodder operations demonstrate measurable water savings, establishing the reference case for subsidy eligibility benchmarks applied to new entrants.
- Hydroponics:Nutrient film and deep water culture systems dominate vertical farming deployments, with Madar Farms and similar operators achieving 90% water reduction versus field agriculture to meet ESMA sustainability disclosure requirements.
- Aquaponics:Fish-vegetable integrated systems remain pilot-scale, constrained by biological complexity and the narrow expertise pipeline for simultaneous aquaculture and horticulture management.
- Organic Practices:Certification through Emirates Authority for Standardization and Metrology protocols opens retail premium positioning, though conversion timelines and input sourcing limitations restrict commercial scale.
Deployment volume favors Precision Farming; Hydroponics gains share fastest on modular system cost reduction.
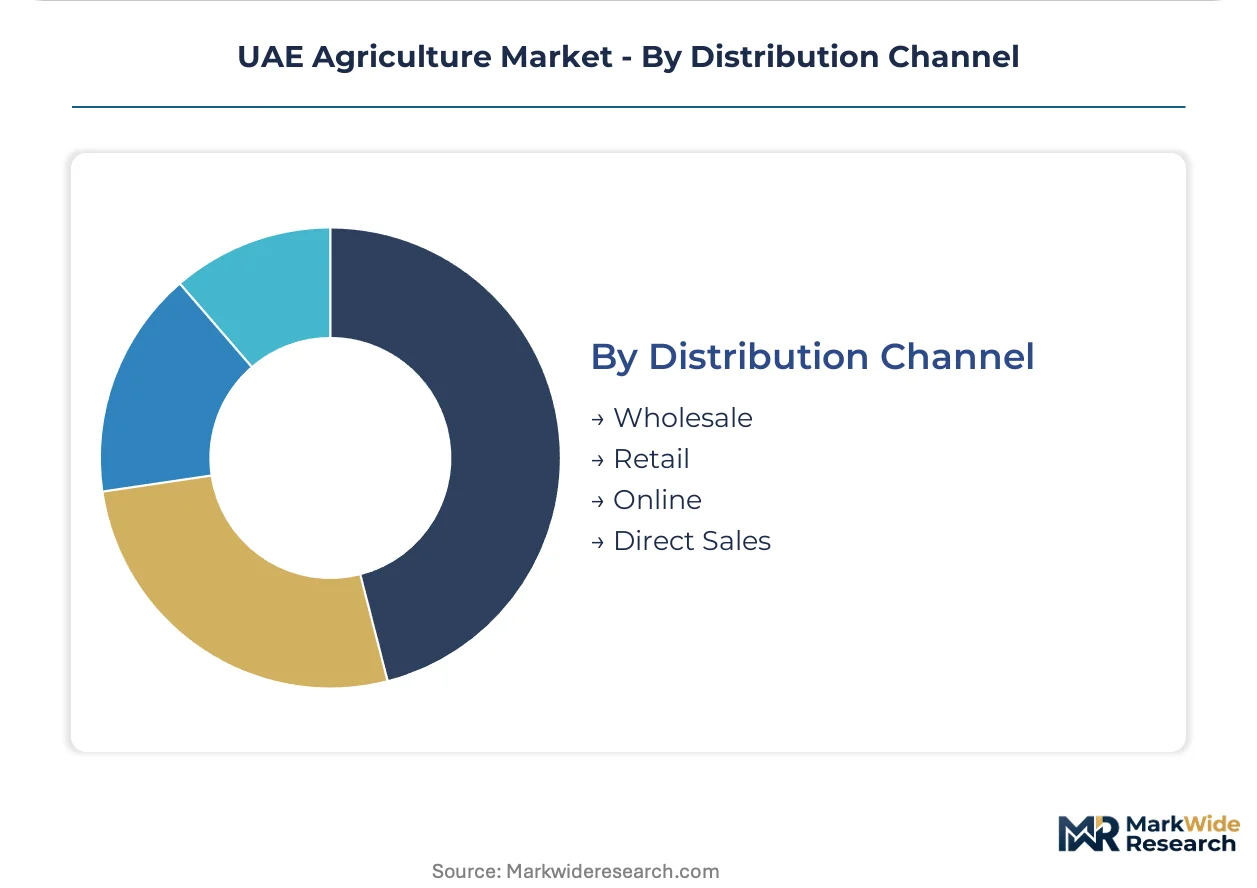
Distribution Channel:
Buyer scale and traceability requirements fragment channel power between consolidated hospitality procurement and fragmented retail placement.
- Wholesale:Traditional produce importers and domestic aggregators serve smaller Emirates retailers, though margin pressure from direct contracting trends erodes historical positioning.
- Retail:Carrefour, Lulu, and Union Coop hypermarkets dominate domestic produce shelf space, with local sourcing quotas and ESMA labeling standards determining supplier qualification.
- Online:E-grocery platforms including Talabat and InstaShop expand fresh produce categories, requiring cold-chain logistics investment that favors established agri-tech operators with traceable inventory systems.
- Direct Sales:Multi-year contracts between vertical farms and Dubai hotel groups bypass wholesale intermediaries, compressing channel margins while securing volume commitments for capacity planning.
Transaction volume runs through Retail; Direct Sales expands most quickly on hospitality sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Abu Dhabi AgriTech Park functions as the primary tax-incentive zone concentrating capital deployment, with Dubai Food Tech Valley operating as a competing magnet for controlled-environment ventures seeking differentiated land tenure arrangements.
Abu Dhabi
Emirates Poultry and Al Ain Dairy sustain livestock procurement demand through hotel and retail channels. MOHAP licensing protocols for desalinated water integration shape facility siting decisions. Khalifa Industrial Zone hosts hydroponic greenhouse clusters where Madar Farms and similar operators achieve scale under National Food Security Strategy 2051 subsidy qualification.
Dubai
Hospitality procurement mandates from Jumeirah Group and Emaar Hospitality create guaranteed offtake for leafy greens and herbs. ESMA energy-use disclosure requirements tighten operational standards for greenhouse facilities above defined output thresholds. Dubai Food Tech Valley in Al Warsan clusters vertical farming ventures near Jebel Ali port infrastructure for re-export positioning.
Sharjah
Landscape and ornamental horticulture demand concentrates around municipal greening initiatives and private villa developments. The Sharjah Research Technology and Innovation Park incubates agritech startups developing drought-resistant cultivation protocols. Hamriyah Free Zone anchors substrate import and fertilizer blending operations serving northern Emirates growers.
Ras Al Khaimah
Date palm cultivation and fodder production persist through groundwater access supplemented by partial desalination. Al Dahra Holding Company operates integrated feed-to-food supply chain facilities across multiple farm locations. The emirate's lower land costs attract conventional agriculture relative to capital-intensive controlled-environment systems dominant in Abu Dhabi and Dubai.
Northern Emirates
Fujairah's coastal infrastructure supports hamour and seabream aquaculture serving domestic hospitality demand. Umm Al Quwain faces MOHAP biosecurity protocol constraints on imported broodstock that limit aquaculture expansion. Ajman and Fujairah municipalities accelerate xeriscaping mandates reducing water-intensive landscaping across public spaces.
UAE Agriculture Market Competitive Landscape
Abu Dhabi-based producers anchor one tier through integrated supply chain control; Dubai specialists hold premium positioning via hospitality direct contracting. The market exhibits tiered concentration with three to five entities commanding volume in livestock and controlled-environment crops respectively. Strategic archetypes separate feed-to-food integrators from vertical farming technology deployers and distribution-anchored processors. Competitive moves center on zone selection between AgriTech Park and Food Tech Valley incentive structures, plus multi-year procurement contract capture.
Within the integrated supply chain tier, Al Dahra Holding Company and Agthia Group exemplify entities spanning multiple Emirates through captive feed production and controlled distribution networks respectively. Madar Farms occupies a position among technology-intensive operators concentrating vertical farming capacity in premium leafy greens for retail and hospitality channels. ARASCO and Silal represent archetypes of government-linked and private capital deployment models competing for National Food Security Strategy 2051 subsidy access.
| Leading Market Players |
|---|
| Al Dahra Holding Company |
| Agthia Group |
| Arabian Agricultural Services Company (ARASCO) |
| Silal |
| Madar Farms |
| iFarm Corporation |
| Dayma |
| ARDI (Agriculture Research and Development Initiative) |
| Jenaan |
| Others |
Pricing and Supply Chain Analysis
Hydroponic modularization across Abu Dhabi AgriTech Park and Dubai Food Tech Valley compresses capital risk while concentrating production capacity among technology-enabled operators, simultaneously lowering entry thresholds and reshaping margin distribution between substrate importers and domestic greenhouse developers.
Pricing Analysis
Short lead-time premiums dominate hospitality procurement contracts, with Dubai hotel groups paying contract premiums for 24-hour harvest-to-delivery cycles on leafy greens and herbs. Three-tier pricing structure across premium certified-organic, standard hydroponic, and economy imported produce segments reflects ESMA labeling tiers and water productivity metrics. Cost compression in standard hydroponic tiers intensifies because Madar Farms and similar operators scale modular units, squeezing margins for conventional greenhouse entrants. Retail hypermarkets exhibit highest price sensitivity, while hospitality procurement managers prioritize traceability and supply security over unit cost.
Supply Chain Analysis
Domestic-content mandates under National Food Security Strategy 2051 redirect sourcing from European and Asian produce toward Emirates-based controlled-environment operators, with MOHAP licensing protocols conditioning market access on local production verification. Geographic supply concentration draws from Netherlands for greenhouse technology, India for coconut coir substrate, and Spain for heat-tolerant seeds. Raw material dependencies center on imported rockwool, perlite, and specialized nutrient solutions. Single-source vulnerability runs through desalinated water infrastructure controlled by federal utilities. Distribution runs through direct contracting with hospitality groups and retail hypermarket consolidation, bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints around agronomic talent and ESMA certification timelines prop pricing power for qualified operators, with capacity bottlenecks in controlled-environment expertise insulating margins against commodity competition.
For Market Incumbents: To counter modular vertical farming entrants, Al Dahra Holding Company and Agthia Group should deepen backward integration into captive substrate production and secure multi-year hospitality procurement contracts before Dubai Food Tech Valley reaches operational scale. Certification investment in ESMA fast-track protocols offers defensive moat against delayed-approval competitors. For New Entrants and Emerging Players: Hospitality procurement managers represent the most penetrable channel partner type for bypassing established wholesale relationships, particularly in Abu Dhabi where government-backed hotel groups face explicit local sourcing quotas. White-space targets include precision-controlled poultry operations and automated dairy climate systems, segments where technology deployment lags crop verticals. Direct contracting with Jumeirah Group or Emaar Hospitality offers go-to-market acceleration through guaranteed offtake. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated feed-to-food conglomerates seeking technology capabilities, with IPO viability contingent on demonstrating unit economics at commercial scale. Long-term viability favors operators achieving subsidy qualification under National Food Security Strategy 2051 criteria. Acquisition target archetype: modular vertical farming platforms with demonstrated water productivity metrics and existing hospitality contracts. The signal to watch is ESMA certification timeline compression, which would accelerate revenue recognition for biological input innovators.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Environment Capacity Expansion | Abu Dhabi AgriTech Park subsidies reduce payback periods for hydroponic greenhouse investments. |
| Direct Hospitality Procurement Contracts | Jumeirah Group sustainability mandates create guaranteed offtake channels bypassing wholesale intermediaries. |
| Solar-Thermal Greenhouse Integration | Dubai green building regulations favor photovoltaic-integrated designs securing preferential grid terms. |
| Backward Integration into Substrate Production | Domestic coconut coir processing reduces shipping cost exposure from Sri Lankan and Indian suppliers. |
| ESMA Fast-Track Certification Investment | Accelerated biological input approvals compress revenue generation timelines for novel fertilizer blends. |
Research Methodology
Independent corroboration across agri-tech facility operators, hospitality procurement directors, and MOHAP regulatory officials underwrites the qualitative findings, with secondary validation drawing from Emirates Authority for Standardization and Metrology disclosure filings, National Food Security Strategy 2051 policy documents, and customs records for substrate imports. Primary interviews with vertical farming engineers, greenhouse construction specialists, and retail category buyers at Carrefour and Lulu combined with bottom-up capacity assessments and top-down demand modeling from hospitality sector procurement data.
Comparable-period anchoring referenced historical deployment patterns across Abu Dhabi AgriTech Park phases to calibrate adoption curves for Dubai Food Tech Valley entrants. Segmentation dimensions modeled include production technology, distribution channel structure, and emirate-specific regulatory cluster. CAGRs derived from iterative convergence between supply-side capacity buildout schedules and demand projections from hospitality procurement mandate timelines, with water productivity benchmarks and solar integration cost curves as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including geopolitical disruption to substrate shipping lanes and abrupt MOHAP regulatory reinterpretation. Forecasts reflect assumptions around continued subsidy eligibility criteria and desalinated water tariff stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
North America Bee Products Market
Agriculture and Agri Products
Australia Animal Protein Market
Agriculture and Agri Products
Uruguay Agricultural Products Market
Agriculture and Agri Products
Ginseng Market
Agriculture and Agri Products
Slippery Elm Market
Agriculture and Agri Products
Asia-Pacific Swine Feed Market
Agriculture and Agri Products
Poultry and Eggs Market
Agriculture and Agri Products
Canada Bamboos Market
Agriculture and Agri Products
Organic Soymeal Market
Agriculture and Agri Products
Global Palm Oil Market
Agriculture and Agri Products
Rapeseed Oil Market
Agriculture and Agri Products
South America Compound Feed Market
Agriculture and Agri Products
North America Shiitake Mushroom Market
Agriculture and Agri Products
Poultry Processing Product Market
Agriculture and Agri Products
Middle East and Africa Bonsai Market
Agriculture and Agri Products
Kuwait Poultry Meat Market