
 Soil Testing Equipment Market | 2026-2036
Soil Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Soil Testing Equipment Market Analysis
China's expanding manufacturing base for analytical instrumentation is reshaping competitive dynamics in soil testing equipment. Thermo Fisher Scientific leverages its R&D intensity across optical sensor platforms to sustain technology leadership. Humboldt Mfg. Co. anchors its position through specialized geotechnical testing systems for construction applications. Agilent Technologies competes on chromatography integration, extending its analytical instrument portfolio into soil nutrient profiling workflows.
Soil testing equipment comprises instruments that measure physical, chemical, and biological soil properties including pH, nutrient content, moisture levels, and contaminant concentrations through spectrometric, electrochemical, or gravimetric methods. These systems serve primary industrial purposes in agriculture optimization, construction site preparation, and environmental compliance verification. Laboratory equipment dominates value capture due to higher precision requirements in regulatory reporting, while portable instruments represent the fastest-expanding segment as field-deployable digital soil testing technology reduces sample transit delays. Fourier Transform Infrared Spectroscopy applications are gaining traction where rapid contaminant detection commands premium positioning among environmental monitoring clients.
The EPA enforces soil screening levels under CERCLA and RCRA frameworks, compelling remediation contractors to deploy certified laboratory-grade testing protocols. China's MEE implements GB standards for agricultural soil pollution risk control, mandating standardized heavy metal detection methodologies. ISO 11277 and ISO 11464 establish international sample preparation and particle size analysis benchmarks that equipment manufacturers must satisfy for cross-border market access. Stakeholders should monitor evolving interoperability standards between field sensors and cloud-based farm management platforms as data sovereignty requirements harden across jurisdictions.
Market Dynamics
Precision agriculture adoption by large-scale farming cooperatives is consolidating equipment procurement decisions into fewer hands, while EU Green Deal soil health mandates are tightening compliance requirements across nitrogen and phosphorus testing protocols.
Growth Catalysts
- EU Green Deal soil mandates:The EU Green Deal's soil health monitoring requirements are tightening nitrogen and phosphorus testing protocols across member states, compelling vineyard and arable operations in Germany's Rhineland agricultural belt to expand continuous soil quality validation.
- Fourier Transform Infrared Spectroscopy:FTIR applications are gaining traction where rapid contaminant detection commands premium positioning among environmental monitoring clients seeking faster turnaround than traditional gravimetric methods.
- Large-scale farming cooperatives:Precision agriculture adoption by agricultural cooperatives is consolidating equipment procurement into centralized purchasing decisions, driving volume commitments for portable and laboratory-grade testing systems.
Market Restraints
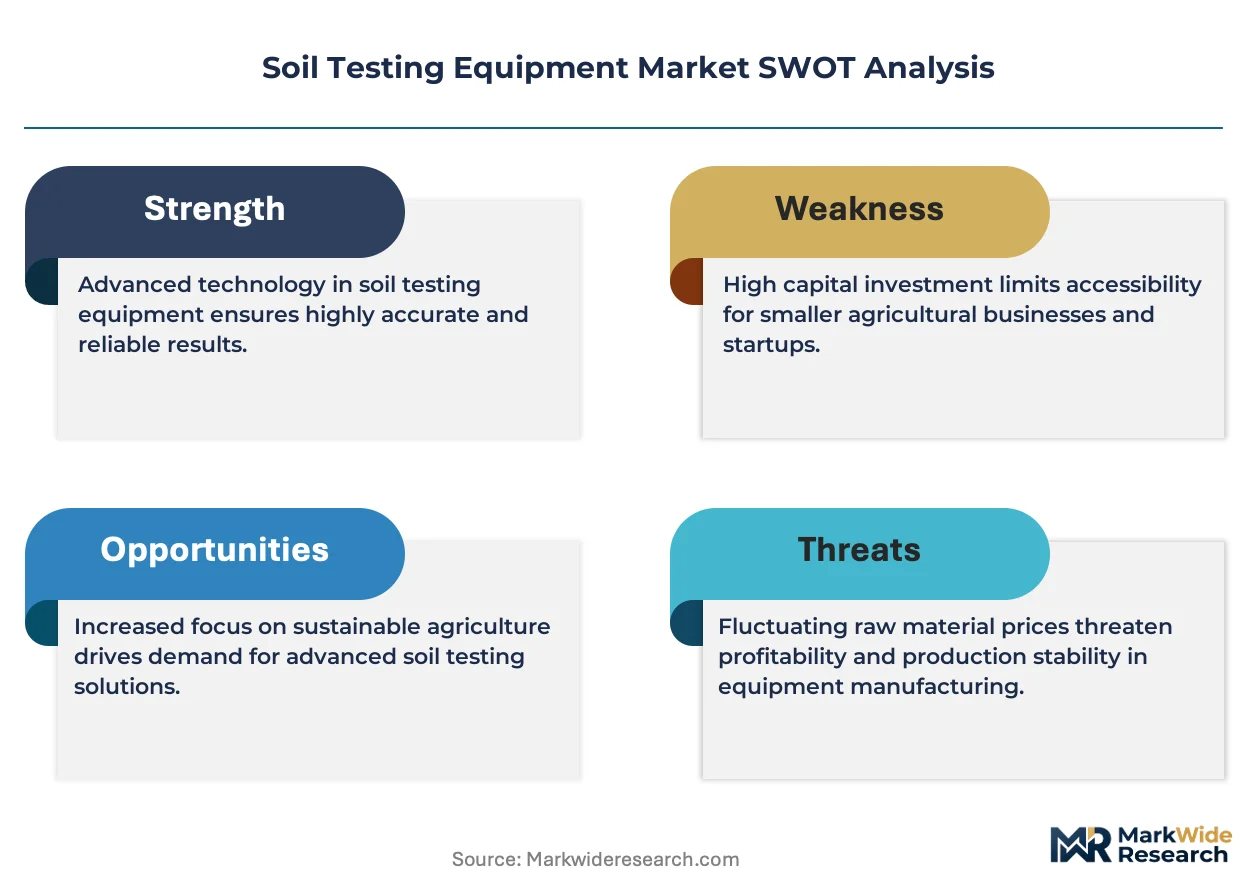
- Optical sensor component concentration:China's expanding manufacturing base for analytical instrumentation creates supply concentration risk, with domestic producers capturing share in electrochemical and spectrometric sensor modules.
- Laboratory-grade certification costs:EPA CERCLA and RCRA soil screening enforcement compels remediation contractors to deploy certified laboratory-grade testing protocols, elevating capital barriers for field-deployable equipment vendors.
- Portable-laboratory accuracy gap:Field-deployable digital soil testing technology faces persistent technical limitations in matching laboratory precision for regulatory reporting, constraining substitution rates in compliance-driven segments.
Strategic Opportunities
- Cloud-based farm management integration:Interoperability standards between field sensors and cloud-based farm management platforms represent white space, with data sovereignty requirements hardening across jurisdictions creating first-mover advantages.
- Construction geotechnical testing:Specialized geotechnical testing systems for construction site preparation remain underpenetrated relative to agricultural applications, with infrastructure investment cycles driving demand for soil compaction and bearing capacity validation.
- Chromatography-nutrient profiling convergence:Integration of chromatography platforms into soil nutrient profiling workflows enables premium positioning for multi-parameter analysis, extending equipment utility beyond single-metric field tests.
Industry Challenges
- Spectrometric calibration expertise:Talent scarcity in optical sensor calibration and FTIR methodology interpretation limits field deployment quality, particularly for environmental monitoring contractors without in-house analytical chemistry capabilities.
- ISO 11277 sample preparation standardization:Cross-border market access requires satisfaction of ISO 11277 and ISO 11464 sample preparation benchmarks, creating certification timeline friction for equipment manufacturers targeting multiple jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soil Testing Equipment Market |
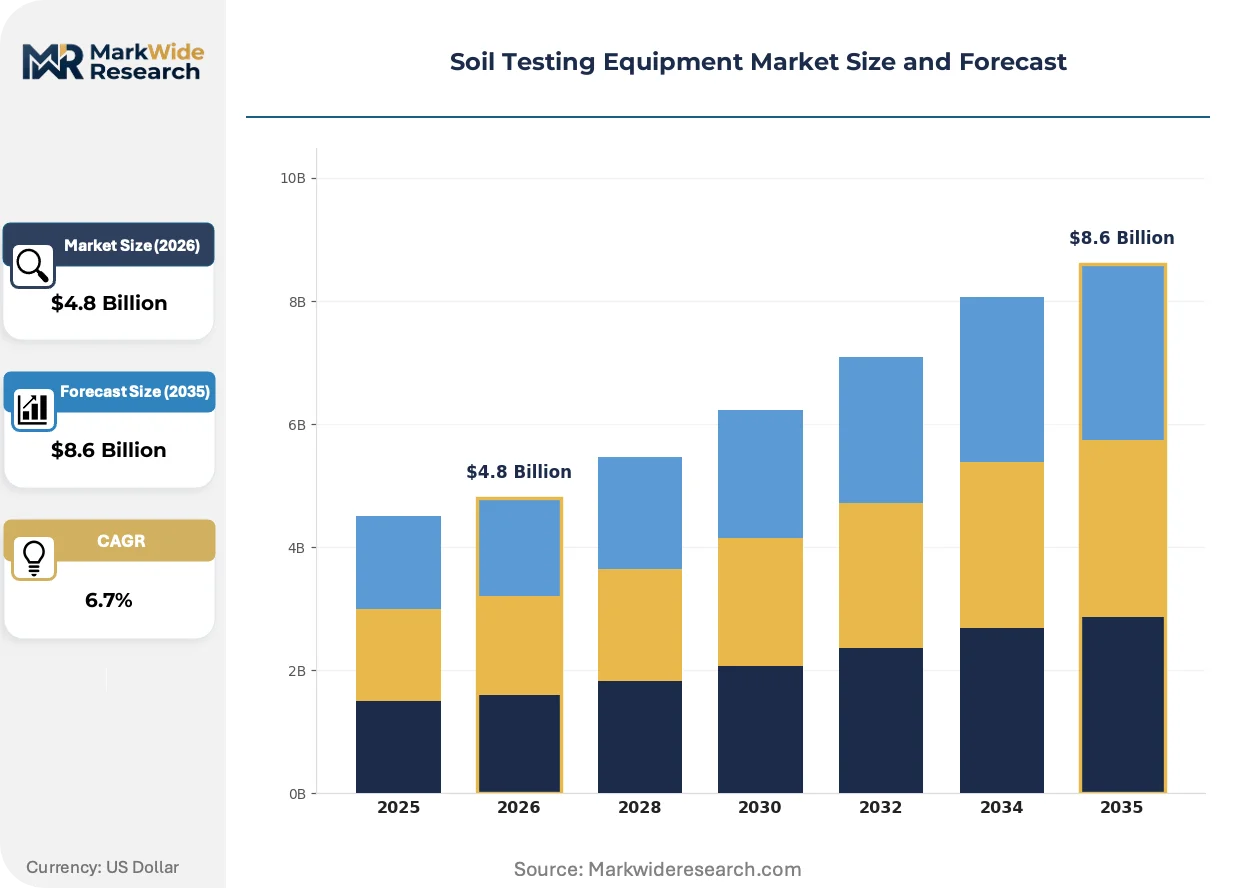
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laboratory Equipment, Field Equipment, Portable Instruments, Soil Moisture Sensors Application: Agriculture, Construction, Environmental Monitoring, Disaster Management End User: Research Institutions, Agricultural Firms, Construction Companies, Government Agencies Technology: Digital Soil Testing, Optical Sensors, Conductivity Meters, Fourier Transform Infrared Spectroscopy |
| Companies Covered | Humboldt Mfg. Co., Agilent Technologies, Thermo Fisher Scientific Inc., Merck Group, PerkinElmer Inc., Controls S.p.A, LaMotte Company, Sun Labtek Equipments Pvt. Ltd., Gilson Company Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soil Testing Equipment Market Emerging Trajectories
Digital soil testing technology is compressing the traditional laboratory-to-field workflow, with three convergent developments reshaping equipment specifications and buyer expectations across agriculture, construction, and environmental monitoring verticals.
Field-deployable near-infrared spectroscopy is collapsing the distinction between laboratory precision and on-site speed. Large-scale farming cooperatives in Germany's Rhineland belt are adopting handheld NIR units for real-time vineyard nutrient mapping. This compression is eliminating sample transit delays that previously dictated multi-day testing cycles.
REACH chemical registration requirements and EU Green Deal soil health indicators are mandating standardized heavy metal detection methodologies across Europe. Equipment manufacturers must satisfy ECHA substance data reporting obligations to maintain market access. Agricultural testing laboratories are responding by upgrading to ICP-MS platforms capable of sub-ppm contaminant quantification.
Cooperative procurement committees now bundle soil testing equipment with multi-year service contracts covering calibration and regulatory documentation. Traditional distributor networks serving individual farm operators face disintermediation as centralized purchasing bypasses regional dealers. This concentration is most visible in Germany's agricultural belt, where vineyard cooperatives negotiate enterprise pricing for fleet deployments.
Soil Testing Equipment Market Segmentation
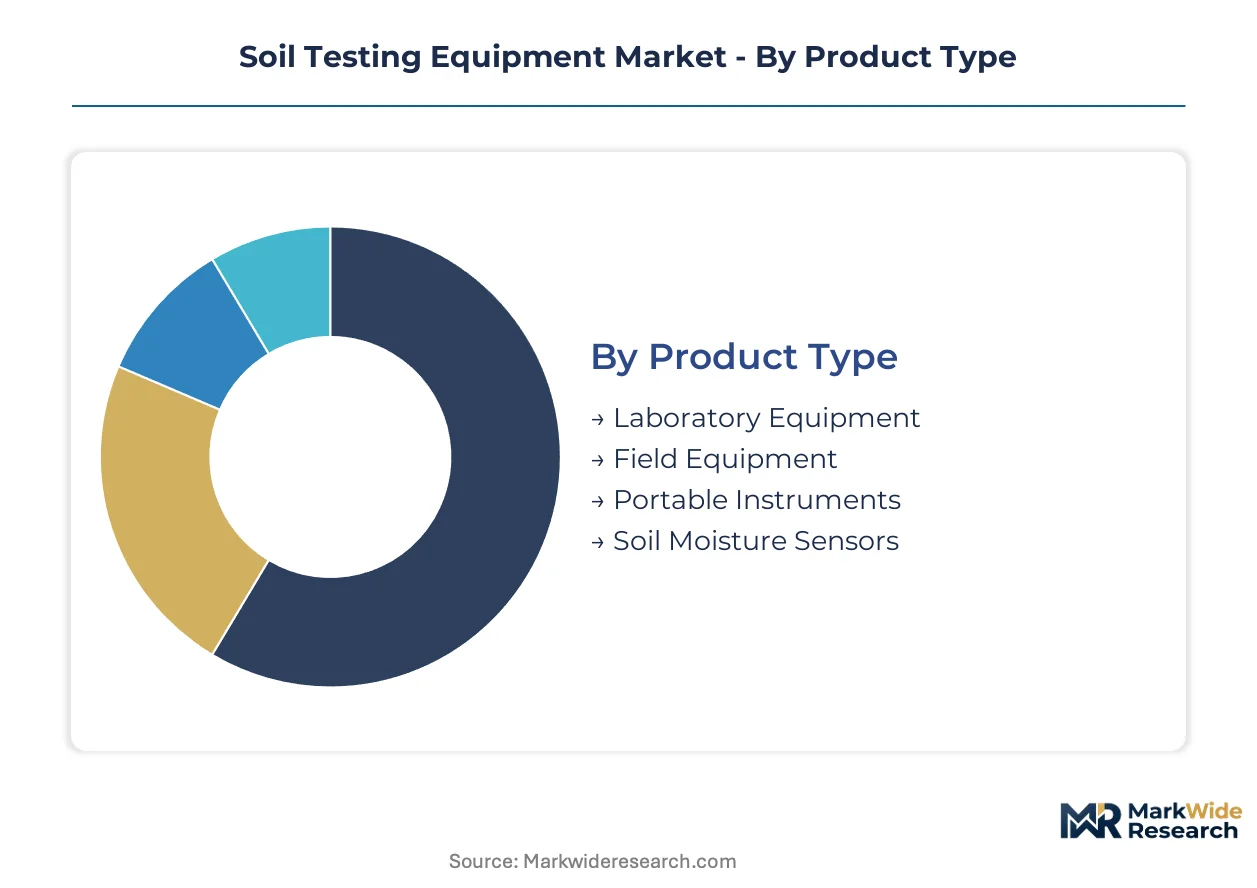
Equipment specifications diverge sharply across use cases, with laboratory precision requirements conflicting against field portability demands. Buyers face trade-offs between analytical depth and operational speed that reshape procurement patterns.
Product Type:
Mature laboratory systems anchor revenue while portable instruments emerge as the technology frontier reshaping deployment economics.
- Laboratory Equipment:High-precision spectrometric and chromatographic systems deliver regulatory-grade accuracy for EPA CERCLA compliance and EU Green Deal nitrogen reporting. Demand concentrates in Germany's Rhineland agricultural belt where vineyard cooperatives require certified documentation for continuous soil quality validation.
- Portable Instruments:Handheld NIR and electrochemical units compress multi-day testing cycles into minutes, eliminating sample transit delays. Large-scale farming cooperatives in precision agriculture programs drive fleet procurement decisions that bypass traditional distributor networks.
- Field Equipment:Vehicle-mounted or trailer-based systems bridge laboratory and portable capabilities for construction site preparation.
- Soil Moisture Sensors:Capacitance and tensiometric probes embed directly into irrigation infrastructure for real-time monitoring.
Laboratory equipment retains volume leadership; portable instruments hold the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive compliance-driven segments from price-sensitive operational optimization markets.
- Agriculture:Nutrient profiling and pH monitoring dominate procurement volumes, with EU Green Deal mandates tightening nitrogen and phosphorus testing protocols across member states. Vineyard and arable operations in Germany's Rhineland belt require continuous validation cycles that sustain equipment utilization rates.
- Environmental Monitoring:Heavy metal detection and contaminant quantification command premium positioning for FTIR and ICP-MS platforms. China's MEE GB standards for agricultural soil pollution risk control mandate standardized methodologies that drive laboratory upgrade cycles.
- Construction:Geotechnical testing for soil compaction and bearing capacity validation follows infrastructure investment cycles.
- Disaster Management:Rapid deployment kits for post-event soil stability assessment serve emergency response protocols.
Agriculture retains volume leadership; environmental monitoring holds the steepest expansion curve.
End User:
Customer type concentration shifts procurement authority toward centralized purchasing committees with multi-year service contract expectations.
- Agricultural Firms:Large-scale cooperatives consolidate equipment decisions into centralized committees that negotiate enterprise pricing for fleet deployments. Germany's vineyard cooperatives bundle soil testing equipment with calibration and regulatory documentation services.
- Research Institutions:University and government laboratories drive specifications for next-generation optical sensor platforms and FTIR methodology development.
- Construction Companies:Infrastructure contractors require geotechnical validation for site preparation compliance.
- Government Agencies:Environmental regulators and agricultural departments specify certified protocols for enforcement activities.
Agricultural firms retain volume leadership; research institutions hold the steepest expansion curve.
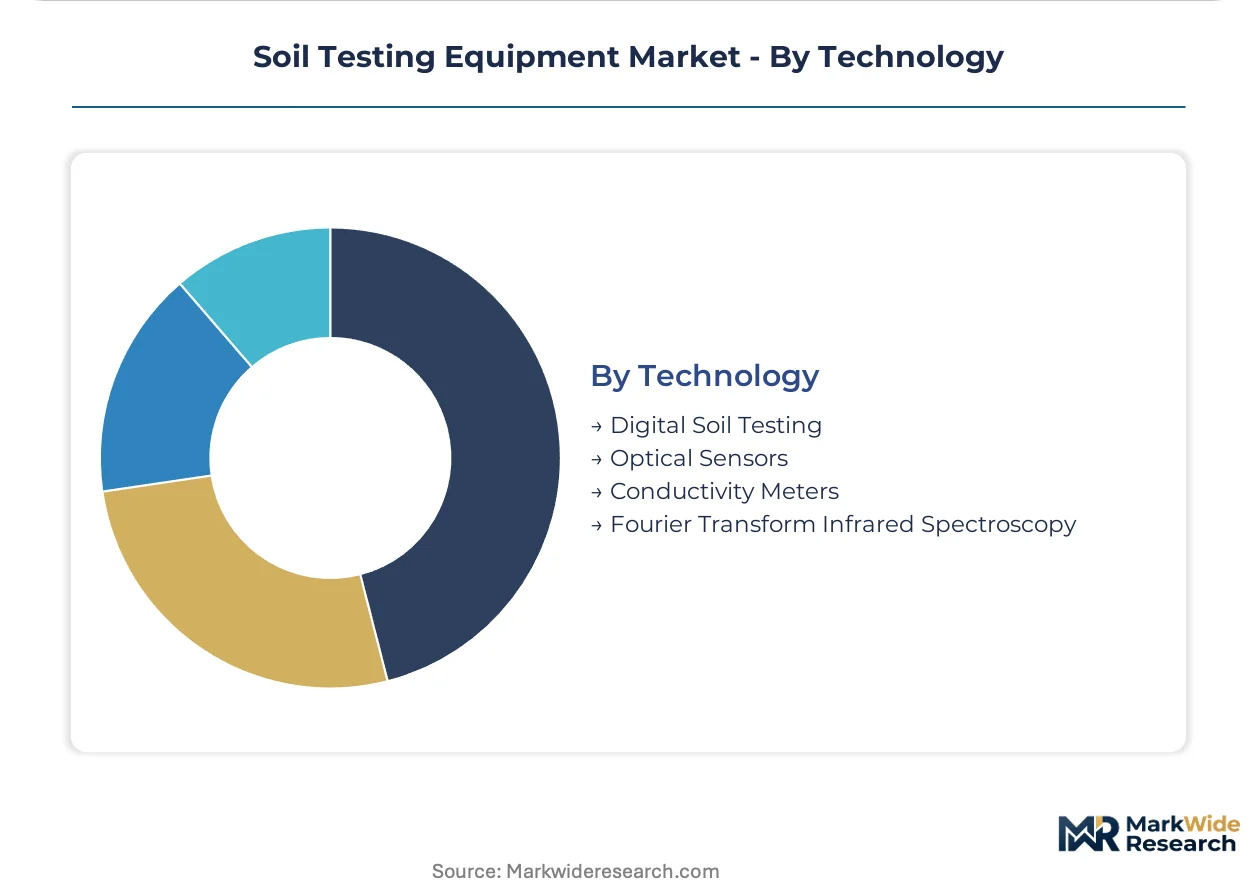
Technology:
Supply concentration in optical sensor manufacturing creates competitive dynamics around calibration expertise and component sourcing.
- Digital Soil Testing:Cloud-integrated field sensors with farm management platform interoperability represent white space opportunities. Data sovereignty requirements hardening across jurisdictions create first-mover advantages for vendors solving cross-border data flow compliance.
- Optical Sensors:Near-infrared and spectrometric modules face supply concentration risk as China's manufacturing base expands electrochemical and spectrometric component output. Talent scarcity in calibration methodology limits field deployment quality.
- Fourier Transform Infrared Spectroscopy:Rapid contaminant detection commands premium positioning where environmental monitoring clients prioritize speed over gravimetric precision.
- Conductivity Meters:Electrochemical probes serve baseline nutrient and salinity assessment with lower capital barriers.
Optical sensors retain volume leadership; digital soil testing holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's manufacturing base for analytical instrumentation concentrates electrochemical and spectrometric sensor supply. Equipment demand patterns diverge sharply between regulatory compliance markets and operational optimization segments across major economies.
Germany
Vineyard cooperatives in the Rhineland agricultural belt drive fleet procurement of laboratory-grade validation systems. EU Green Deal nitrogen and phosphorus testing protocols tighten compliance requirements for continuous soil quality monitoring. Stuttgart and Munich host precision agriculture technology clusters where cooperative purchasing committees negotiate enterprise service contracts.
United States
EPA CERCLA and RCRA enforcement compels remediation contractors to deploy certified laboratory-grade testing protocols. Infrastructure investment cycles sustain demand for geotechnical validation equipment in construction site preparation. Texas and California agricultural belts concentrate precision farming cooperative activity.
China
Domestic producers capture expanding share in optical sensor module manufacturing. MEE GB standards for agricultural soil pollution risk control mandate standardized heavy metal detection methodologies. Yangtze River Delta manufacturing clusters supply electrochemical and spectrometric components to global equipment assemblers.
India
Large-scale farming cooperatives consolidate equipment procurement into centralized purchasing decisions. FSSAI and state agricultural departments specify certified protocols for soil health monitoring programs. Maharashtra and Gujarat agricultural belts drive portable instrument adoption for field-deployable nutrient mapping.
United Kingdom
Research institutions drive specifications for next-generation optical sensor platforms and FTIR methodology development. REACH chemical registration requirements mandate standardized detection methodologies for soil contaminant assessment. Cambridge and Oxford university clusters anchor analytical chemistry capability development.
Soil Testing Equipment Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in optical sensor and electrochemical module supply. The vendor base spans multinational analytical instrument conglomerates, specialized geotechnical equipment fabricators, and emerging Chinese component manufacturers. Three archetypes dominate: diversified laboratory technology conglomerates, construction-focused geotechnical specialists, and precision agriculture equipment purveyors. Competitive moves center on chromatography-nutrient profiling convergence and cloud-based farm management platform interoperability.
Among diversified technology conglomerates, Thermo Fisher Scientific and Agilent Technologies occupy positions spanning laboratory-grade spectrometric systems through portable field-deployable units. Humboldt Mfg. Co. exemplifies the construction-specialist archetype, anchoring geotechnical testing applications distinct from agricultural market dynamics. These three entities represent the structural segmentation between multi-platform integrators and application-focused equipment fabricators.
| Leading Market Players |
|---|
| Humboldt Mfg. Co. |
| Agilent Technologies |
| Thermo Fisher Scientific Inc. |
| Merck Group |
| PerkinElmer Inc. |
| Controls S.p.A |
| LaMotte Company |
| Sun Labtek Equipments Pvt. Ltd. |
| Gilson Company Inc. |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Chinese optical sensor modules determines both pricing tier spreads and supply chain shape, as EPA CERCLA certification requirements and EU Green Deal compliance mandates force buyers into premium laboratory-grade equipment or risk regulatory exclusion.
Pricing Analysis
EPA CERCLA and EU Green Deal mandates dictate the pricing tier structure across the soil testing equipment landscape. Three-tier pricing structure across premium laboratory-grade, certified field-portable, and economy electrochemical levels separates compliance-driven remediation contractors from precision agriculture cooperatives and budget-constrained individual operators. Cost compression in the portable segment is intensifying because China's expanding sensor manufacturing base floods mid-market electrochemical modules. Agricultural cooperatives in Germany's Rhineland belt exhibit lowest price sensitivity due to bundled enterprise service contracts, while independent vineyard operators in emerging markets face acute budget constraints.
Supply Chain Analysis
Extended payment terms from Chinese component suppliers now stretch to 90-120 days, straining working capital for European and North American equipment assemblers. Manufacturing gravity centers on China for optical sensor modules and electrochemical probes, Germany for precision spectrometric assemblies, and the United States for chromatography platforms. Raw material dependencies span rare-earth elements for NIR sensors, specialized glass for optical pathways, and high-purity reagents for calibration standards. Single-source vulnerability concentrates in Yangtze River Delta optical component foundries. Distribution runs through authorized distributor networks serving individual agricultural operators, direct enterprise sales teams targeting cooperative procurement committees, and OEM channel partnerships with construction equipment rental fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities multiply as cooperative procurement consolidation and cloud-platform interoperability demands create specialized niches for vendors solving data sovereignty and calibration expertise gaps.
For Market Incumbents: Pre-empt emerging Chinese component manufacturers by securing captive supply agreements for optical sensor modules before tariff exposure hardens. Defend margin position through backward integration into FTIR calibration methodology training services, addressing talent scarcity that limits field deployment quality. Anchor laboratory-grade certification pipelines with EPA and EU regulatory bodies to elevate capital barriers for portable equipment challengers. For New Entrants and Emerging Players: Establish a beachhead in construction geotechnical testing systems, where infrastructure investment cycles sustain demand yet agricultural-focused incumbents maintain weak presence. Target India's Maharashtra and Gujarat agricultural belts with handheld NIR units bundled with state agricultural department certification documentation. Pursue cooperative procurement committee relationships directly, bypassing traditional distributor networks that agricultural specialists dominate. For Investors and Strategic Acquirers: EU Green Deal soil health indicator finalization reshapes the acquisition landscape toward vendors with established MEE GB standard compliance in China and ECHA substance data reporting capabilities in Europe. Long-term viability hinges on cloud-platform interoperability architecture that satisfies hardening data sovereignty requirements across jurisdictions. Monitor ISO 11277 and ISO 11464 certification timeline friction as inflection indicator for vendor scalability constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Platform Interoperability Development | Data sovereignty requirements across EU, India, and China create first-mover advantages for compliant vendors. |
| FTIR Calibration Methodology Training | Talent scarcity in optical sensor calibration limits field deployment quality for environmental monitoring contractors. |
| Construction Geotechnical Testing Expansion | Infrastructure investment cycles in Germany and the United States drive soil compaction validation demand. |
| Cooperative Procurement Committee Engagement | Centralized purchasing in Germany's Rhineland belt bypasses traditional agricultural distributor networks. |
| Regulatory Certification Pipeline Investment | EPA CERCLA and EU Green Deal mandates elevate capital barriers for laboratory-grade equipment competitors. |
Methodological Framework
A spread of perspectives from precision agriculture cooperative procurement managers, environmental remediation contractors, construction site engineers, and optical sensor calibration specialists converged on the working assumptions underlying this analysis. Primary field engagement combined with secondary validation drew from EPA enforcement documentation, EU Green Deal regulatory filings, MEE GB standard publications, and ISO certification records. Bottom-up equipment shipment data triangulated against top-down agricultural expenditure patterns and construction investment flows.
Demand-supply balance dynamics anchored the analytical framework across the analysis window, with segmentation modeled by product type, application vertical, end-user concentration, and technology platform. CAGRs derived from equipment replacement cycle analysis, regulatory compliance deadline clustering, and cooperative procurement committee capital allocation patterns. Forecast inputs incorporated spectrometric sensor cost curves, cloud-platform adoption trajectories in farm management systems, and infrastructure investment cycle phasing.
Stress conditions across optical sensor supply concentration, tariff regime volatility, and regulatory certification timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about cooperative procurement consolidation rates and interoperability standard emergence timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Indoor Farming Equipment Market
Agricultural Equipment
Hay and Forage Rakes Market
Agricultural Equipment
Farm Tire Market
Agricultural Equipment
Soil Mixer Market
Agricultural Equipment
Battery Powered Cultivators Market
Agricultural Equipment
Industrial Potato Graders Market
Agricultural Equipment
India Color Sorter Market
Agricultural Equipment
Cordless Handheld Cultivator Market
Agricultural Equipment
Solar Fruit Dryer Market
Agricultural Equipment
Battery-Operated Knapsack Sprayer Market
Agricultural Equipment
Australia Bird Feeder Market
Agricultural Equipment
Rotavator Market
Agricultural Equipment
Soil Aerators Market
Agricultural Equipment
Garden Tools Market
Agricultural Equipment
Stock Tanks Market
Agricultural Equipment
Agricultural Pumps Market