
 Soil Testing Kit Market | 2026-2036
Soil Testing Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Soil Testing Kit Market Analytics
Agricultural supply stores is reshaping how soil testing kits reach end users across rural and semi-urban markets. Thermo Fisher Scientific Inc. leverages its laboratory instrumentation heritage to dominate professional-grade nutrient analysis segments. LaMotte Company anchors its position through specialized colorimetric test kits calibrated for educational and environmental monitoring use cases. Merck Group competes on the strength of its chemical reagent supply chain, extending backward into precision pH meter manufacturing.
Soil testing kits are portable analytical systems designed to measure chemical, physical, and biological soil parameters through electrochemical sensors, colorimetric reagents, or chromatographic strips, typically delivering results within minutes to hours for field-level decision-making. Nutrient test kits command the largest volume share among product types, while colorimetric test kits represent the fastest-expanding category due to their low cost and minimal training requirements. Agricultural testing generates the dominant application demand, though environmental monitoring is accelerating as watershed protection mandates intensify across industrialized farming regions.
The EPA enforces soil contamination screening standards under CERCLA and RCRA frameworks, compelling environmental consultants to maintain certified testing capabilities. The EU Fertilizing Products Regulation and REACH compliance protocols restrict heavy metal thresholds in soil amendments, directly stimulating demand for validated trace-element detection kits. Stakeholders must monitor evolving national organic certification standards and emerging digital soil health platforms that threaten to displace single-use chemical test formats.
Market Dynamics
Precision agriculture platforms are compressing decision cycles for nutrient management, forcing soil testing kit manufacturers to integrate with farm management software and deliver real-time data streams that connect field sampling to variable-rate application systems.
Growth Catalysts
- EU Fertilizing Products Regulation:Mandatory nutrient management plans across member states require validated soil testing for compliance, expanding kit demand among commercial operators.
- Digital agriculture platforms:Integration with satellite imagery and yield monitoring systems positions soil testing as a data input layer rather than isolated diagnostics.
- Watershed protection mandates:Industrialized farming regions face escalating phosphorus runoff limits, compelling routine soil phosphorus testing before fertilizer application.
Market Restraints
- Reagent supply concentration:Specialty chemical precursors for colorimetric assays concentrate among German and Swiss suppliers, exposing kit manufacturers to input cost volatility.
- Electrochemical sensor calibration drift:Field-deployed pH and ion-selective electrodes require frequent recalibration, limiting unattended monitoring applications.
- Digital soil health platforms:Satellite-derived soil organic carbon estimates and remote sensing vegetation indices threaten to substitute physical sampling for certain nutrient assessments.
Strategic Opportunities
- Smallholder penetration in India:BIS certification pathways for simplified test kits open access to 120 million marginal farming operations lacking laboratory access.
- Carbon credit verification:Soil organic matter quantification for agricultural carbon offsets creates demand for standardized, auditable testing protocols.
- Environmental DNA integration:Convergence of soil microbiome sequencing with conventional chemical testing enables biological soil health scoring alongside nutrient panels.
Industry Challenges
- ISO 17025 accreditation timelines:Environmental consultants face 12-18 month certification delays for soil contaminant testing, constraining service expansion.
- Legacy colorimetric workflow integration:Agricultural extension services resist abandoning established visual test methods despite digital reader availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soil Testing Kit Market |
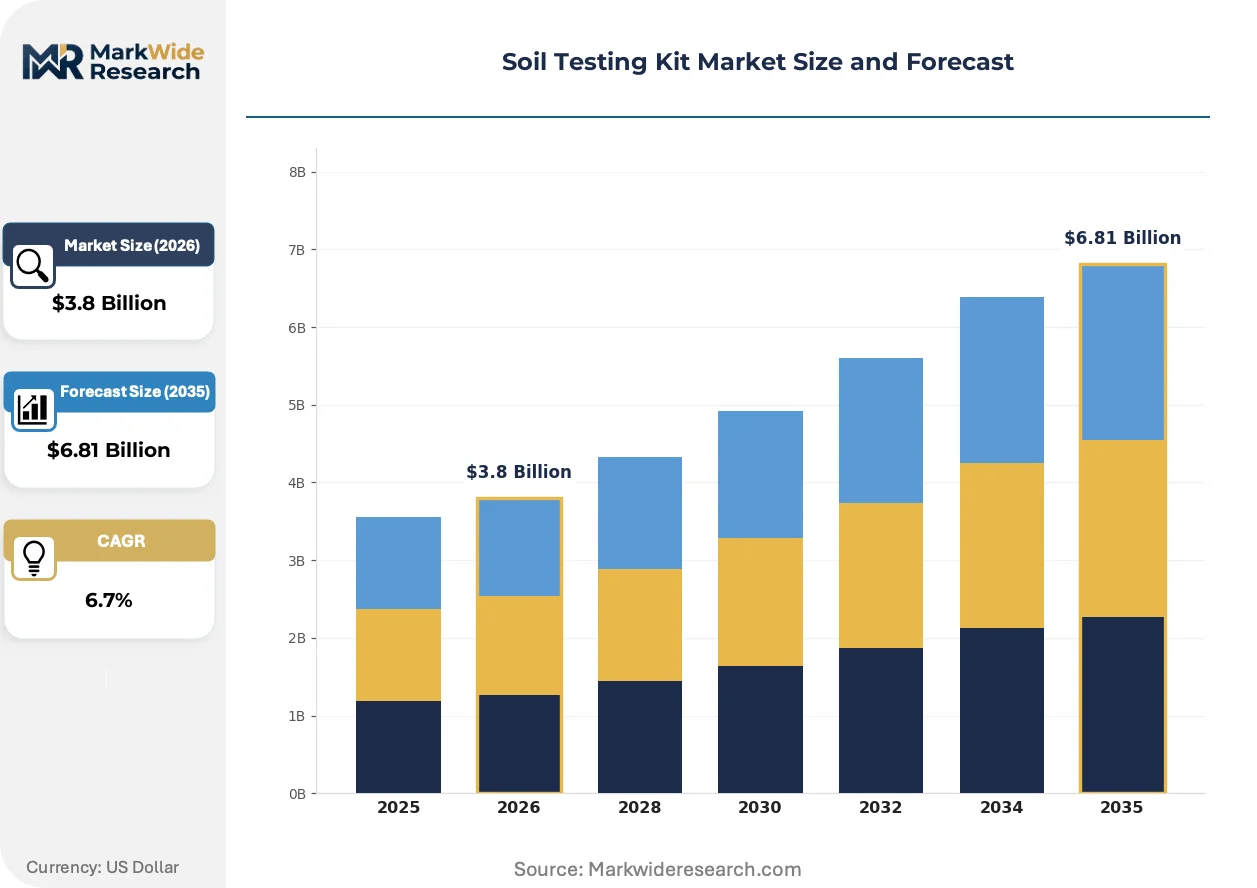
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: pH Meters, Moisture Testers, Nutrient Test Kits, Colorimetric Test Kits Application: Agricultural Testing, Environmental Monitoring, Research Labs, Home Gardening End User: Farmers, Agronomists, Environmental Scientists, Hobbyists Distribution Channel: Online Stores, Retail Outlets, Agricultural Supply Stores, Direct Sales |
| Companies Covered | Merck Group, LaMotte Company, Thermo Fisher Scientific Inc., Agilent Technologies, Humboldt Mfg. Co., Ele International, Gilson Company Inc., PerkinElmer Inc., Controls S.p.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soil Testing Kit Market Evolving Landscape
Portable analytical hardware is converging with smartphone-based data capture, collapsing the cost and skill barriers that historically separated professional laboratory testing from on-farm diagnostics.
Smartphone camera-based colorimetry is migrating from educational demonstrations to certified agricultural decision-support tools. Commercial farming cooperatives in the Netherlands and Denmark now deploy app-integrated test strip readers for real-time nitrogen recommendations. This migration is compressing the price-performance gap between professional laboratory photometers and field-portable alternatives.
REACH compliance protocols for heavy metal thresholds in soil amendments are tightening trace-element detection requirements across the European Union. Fertilizer blenders must now document cadmium, nickel, and lead content below specified limits, stimulating demand for validated field-portable XRF and colorimetric heavy metal kits. German agricultural supply chains have responded fastest, embedding testing stations at blending facilities.
Subscription-based reagent replenishment models are displacing one-time kit purchases among medium-scale farming operations. Channel partners in France and Italy now bundle seasonal testing programs with agronomic advisory services, locking in recurring revenue streams. This shift is most visible in vineyard management, where soil pH and potassium monitoring follows annual growth cycles.
Soil Testing Kit Market Segmentation
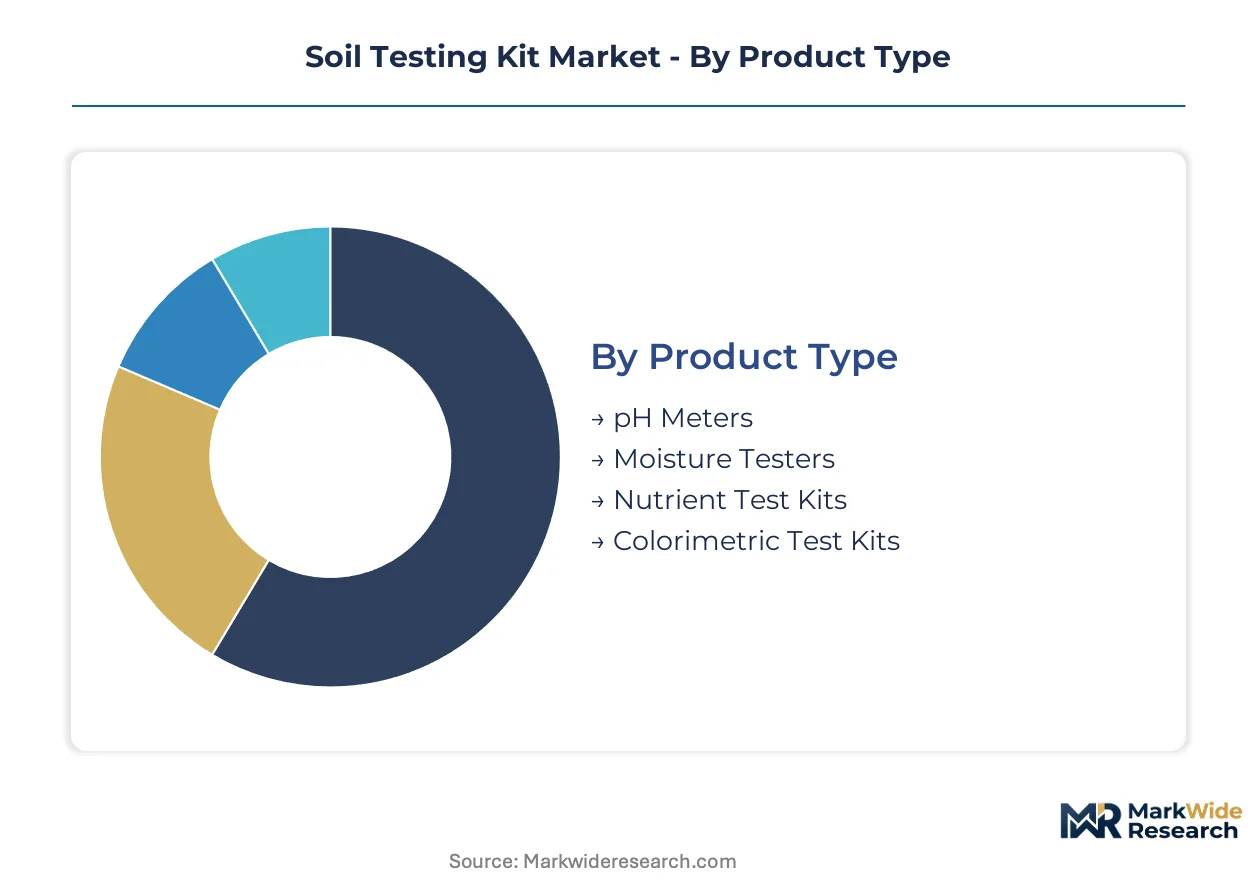
Segmentation in soil testing kits reveals how technology maturity, user sophistication, and channel economics partition demand. Each dimension exposes distinct margin structures and competitive entry points.
Product Type:
Mature electrochemical platforms anchor commercial agriculture while emerging optical methods disrupt price-sensitive segments.
- Nutrient Test Kits:These systems quantify nitrogen, phosphorus, and potassium through ion-selective electrodes or wet chemistry reagents calibrated for agronomic decision thresholds. Commercial farming cooperatives in the Netherlands and Denmark deploy these for variable-rate fertilization programs mandated by EU Fertilizing Products Regulation compliance windows.
- Colorimetric Test Kits:Visual or smartphone-camera interpretation of reagent color change enables low-cost field diagnostics without laboratory infrastructure. India's BIS certification pathways for simplified kits target 120 million marginal farming operations lacking laboratory access, compressing cost barriers to adoption.
- pH Meters:Electrochemical probes with glass or ISFET sensors deliver 0.01 precision for liming decisions in acid soil management zones.
- Moisture Testers:Tensiometers and capacitance probes support irrigation scheduling in drought-prone viticulture and specialty crop regions.
Nutrient Test Kits retain volume leadership; Colorimetric Test Kits hold the steepest expansion curve.
Application:
Regulatory compliance intensity separates premium analytical demand from discretionary consumer segments.
- Agricultural Testing:Nutrient management plans, carbon credit verification protocols, and precision agriculture platforms generate recurring testing cycles across commercial operations. German agricultural supply chains embed testing stations at fertilizer blending facilities to satisfy REACH heavy metal documentation requirements.
- Environmental Monitoring:Watershed protection mandates in industrialized farming regions impose phosphorus runoff limits, compelling pre-application soil testing. EPA CERCLA and RCRA frameworks enforce contamination screening standards for environmental consultants maintaining certified capabilities.
- Research Labs:ISO 17025 accreditation requirements drive demand for reference-grade instrumentation with documented traceability chains.
- Home Gardening:Consumer-grade pH and NPK strips serve ornamental horticulture and small-scale food production with minimal calibration demands.
Agricultural Testing commands the revenue base; Environmental Monitoring is climbing the fastest as regulatory enforcement tightens.
End User:
Technical proficiency gradients determine kit complexity tolerance and service attachment rates.
- Farmers:Commercial operators require integration with farm management software and real-time data streams connecting sampling to variable-rate application systems. Subscription-based reagent replenishment models now displace one-time purchases among medium-scale French and Italian vineyard operations.
- Agronomists:Professional advisors bundle seasonal testing programs with advisory services, locking in recurring revenue through channel partnerships.
- Environmental Scientists:12-18 month ISO 17025 certification timelines constrain service expansion for soil contaminant testing capabilities.
- Hobbyists:Price-sensitive consumers prioritize smartphone-app compatibility and educational support over analytical precision.
Farmers dominate procurement volume; Agronomists show the sharpest service-revenue attachment growth.
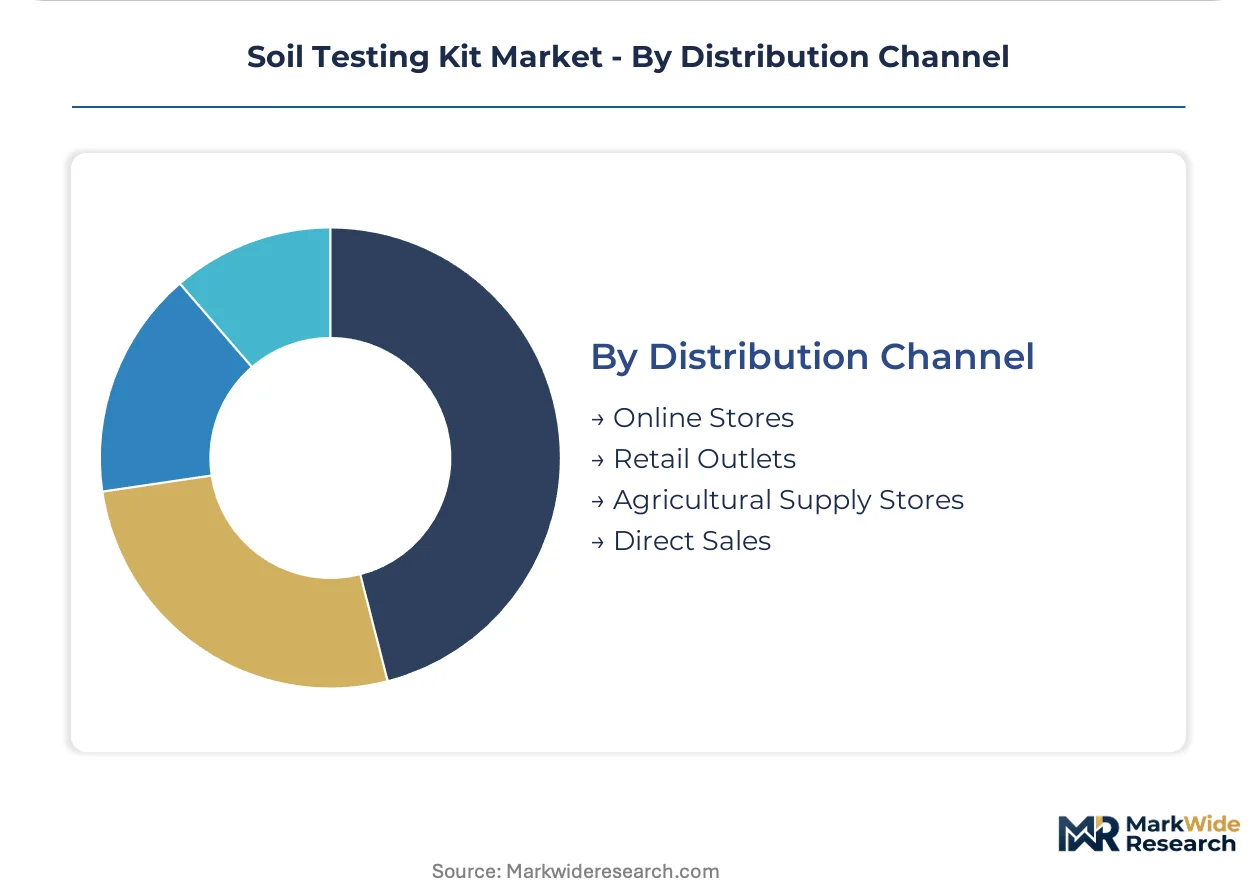
Distribution Channel:
Channel economics reflect customer acquisition costs against technical support requirements.
- Agricultural Supply Stores:Rural and semi-urban market penetration depends on trusted local relationships and immediate product availability during planting windows. Germany's Rhine-Ruhr agricultural corridor concentrates demand through cooperative-owned supply networks.
- Online Stores:Direct-to-farmer platforms reduce margin capture by intermediaries while enabling subscription reagent replenishment logistics.
- Retail Outlets:Mass-market garden centers serve hobbyist segments with limited technical consultation capacity.
- Direct Sales:Enterprise agreements with large farming cooperatives bypass channel markups for high-volume nutrient testing programs.
Agricultural Supply Stores maintain the deepest rural penetration; Online Stores are gaining share fastest through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in German precision agriculture supply chains while Indian cost-optimized distribution channels compress margins for entry-tier colorimetric formats. Regulatory divergence between REACH-compliant European markets and BIS-simplified certification pathways creates asymmetric competitive dynamics across geographies.
United States
Commercial farming cooperatives in the Corn Belt and California Central Valley drive recurring nutrient testing cycles for variable-rate fertilization programs. EPA CERCLA and RCRA frameworks enforce contamination screening standards that compel environmental consultants to maintain certified soil testing capabilities. The Midwest agricultural corridor concentrates demand through cooperative-owned supply networks embedded at fertilizer blending facilities.
Germany
Rhine-Ruhr agricultural operations anchor European demand for professional-grade electrochemical testing platforms integrated with farm management software. REACH compliance protocols mandate documented cadmium, nickel, and lead thresholds in soil amendments, stimulating validated field-portable XRF and heavy metal detection kit procurement. Bavarian fertilizer blenders have responded fastest, embedding testing stations directly at production facilities.
India
BIS certification pathways for simplified colorimetric test kits target 120 million marginal farming operations lacking laboratory infrastructure across Maharashtra, Gujarat, and Punjab. The country's national agricultural regulator has streamlined approval timelines for low-cost field diagnostics. The Indo-Gangetic Plain concentrates adoption through state agricultural extension services distributing subsidized testing programs.
Netherlands
Commercial farming cooperatives deploy smartphone-integrated test strip readers for real-time nitrogen recommendations under EU Fertilizing Products Regulation compliance windows. The Dutch national environmental agency enforces stringent phosphorus runoff limits that compel pre-application soil testing. The Randstad agricultural technology cluster hosts the densest concentration of precision agriculture platform integrations.
Brazil
Large-scale soybean and sugarcane operations in Mato Grosso and São Paulo generate volume demand for subscription-based reagent replenishment models tied to agronomic advisory services. The country's national agricultural supply agency promotes soil health monitoring as a component of sustainable intensification programs. The Cerrado biome expansion zones concentrate rapid adoption of portable pH and moisture testing for lime and irrigation management decisions.
Soil Testing Kit Market Competitive Landscape
Laboratory instrumentation heritage and specialized colorimetric manufacturing split the market between premium professional-grade and accessible field-portable segments. Market structure tilts toward consolidated professional tiers with fragmented entry-level supply. Three archetypes dominate: diversified life science conglomerates with analytical instrumentation divisions, specialized environmental testing manufacturers with educational market roots, and regional chemical reagent suppliers extending into finished kit assembly. Competitive moves center on backward integration into chemical precursor supply and forward integration with digital agriculture platform APIs.
Within the diversified instrumentation tier, Thermo Fisher Scientific Inc. and Agilent Technologies exemplify scale-driven positions anchored by laboratory-grade technology portfolios. Merck Group and PerkinElmer Inc. occupy positions reflecting chemical reagent supply chain control extending into precision measurement hardware. LaMotte Company and Humboldt Mfg. Co. represent specialized environmental testing manufacturers with educational and field-portable market foundations. Controls S.p.A and Ele International sit within European fabrication clusters serving regional compliance-driven demand.
| Leading Market Players |
|---|
| Merck Group |
| LaMotte Company |
| Thermo Fisher Scientific Inc. |
| Agilent Technologies |
| Humboldt Mfg. Co. |
| Ele International |
| Gilson Company Inc. |
| PerkinElmer Inc. |
| Controls S.p.A |
| Others |
Value Network & Pricing Analysis
Undercapacity in German precision electrochemical sensor fabrication is tightening reagent supply availability and compressing margin flexibility for kit assemblers serving EU Fertilizing Products Regulation compliance markets. This utilization squeeze simultaneously elevates spot pricing for colorimetric precursor chemicals and accelerates backward integration investments among tier-one manufacturers seeking captive supply security.
Pricing Analysis
The customization-premium spread separates ISO 17025-certified professional-grade electrochemical platforms from BIS-simplified colorimetric field kits. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling. Cost compression in entry-tier colorimetric segments is intensifying because Indian state extension services are consolidating procurement volumes. Hobbyist gardeners exhibit highest price sensitivity; commercial farming cooperatives in the Netherlands and Denmark show lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Export-control regimes limiting ion-selective electrode technology flows from Germany and Switzerland are fragmenting regional supply availability for professional-grade pH meter manufacturers. Specialty chemical precursors for colorimetric assays concentrate among German, Swiss, and Indian suppliers. Single-source vulnerability runs through Swiss glass membrane suppliers for ISFET sensors. Distribution runs through cooperative-owned agricultural supply networks in the Rhine-Ruhr corridor and direct-to-farmer online platforms with subscription replenishment logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Dutch and Danish farming cooperatives deploying precision agriculture platforms, compressing supplier margins through volume consolidation and software integration demands.
For Market Incumbents: Harden certification moats by accelerating ISO 17025 accreditation investments ahead of EU Fertilizing Products Regulation enforcement windows. Deepen backward integration into colorimetric reagent precursor supply to offset German-Swiss chemical concentration risk. Digital soil health platforms threaten substitution; API integration with farm management software becomes essential. For New Entrants and Emerging Players: Build out BIS-certified simplified test kit distribution through Maharashtra and Gujarat state agricultural extension services. India's 120 million marginal farming operations represent the most penetrable geography. Smartphone-camera colorimetry with app-based agronomic advisory bundling offers the strongest go-to-market angle against laboratory-dependent incumbents. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across colorimetric test kit manufacturing as smartphone-based readers displace dedicated photometer hardware. Long-term viability favors asset-light platform players with recurring reagent revenue over capital-heavy electrochemical instrument manufacturers. Acquisition target archetype: regional chemical reagent suppliers with backward integration potential into finished kit assembly. Watch carbon credit verification protocol adoption as inflection indicator for soil organic matter testing demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reagent Supply | German manufacturers secure captive precursor supply against Swiss chemical concentration risk. |
| API Integration with Farm Management Software | Dutch cooperatives demand real-time data streams connecting sampling to variable-rate application systems. |
| BIS Certification for Simplified Kits | Indian state extension services unlock access to 120 million marginal farming operations. |
| Subscription Reagent Replenishment Models | French and Italian vineyard operations generate recurring revenue through seasonal testing programs. |
| Carbon Credit Verification Protocol Development | Standardized soil organic matter quantification creates auditable testing demand for agricultural offsets. |
Research Methodology
A spread of perspectives from agronomic advisors at Dutch farming cooperatives, procurement leads at German fertilizer blenders, BIS certification officers, environmental consultants maintaining EPA CERCLA capabilities, and channel managers at agricultural supply stores converged on the working assumptions. Secondary validation drew from EU Fertilizing Products Regulation compliance filings, REACH heavy metal threshold documentation, SEC 10-K disclosures from laboratory instrumentation providers, and Indian state agricultural extension procurement records. Bottom-up kit shipment estimates and top-down precision agriculture platform adoption curves were triangulated.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application intensity, end-user technical proficiency, and distribution channel economics. CAGRs were derived through logistic diffusion curves for smartphone-based colorimetry adoption and regulatory compliance mandate penetration rates. Industry-specific forecast inputs encompassed EU Fertilizing Products Regulation implementation timelines and BIS certification pathway streamlining.
The forecast holds incumbent behavior within observed patterns; aggressive moves by satellite-derived soil health platform providers would shift outcomes. Material shifts in EU heavy metal threshold enforcement or Indian state subsidy allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Testing Services
Agrochemicals Testing and Inspection Service Market
Agricultural Testing Services
Asia Pacific Feed Testing Market
Agricultural Testing Services
Seed Testing Services Market
Agricultural Testing Services
Europe Feed Testing Market
Agricultural Testing Services
North American Feed Testing Market
Agricultural Testing Services
Poultry Diagnostic Testing Market
Agricultural Testing Services
Plant Disease Diagnostic Market
Agricultural Testing Services
Soil Field Testing Equipment Market
Agricultural Testing Services
Plant Nutrient Testing Equipment Market
Agricultural Testing Services
Irrigation Testing Kit Market
Agricultural Testing Services
Rapid Mycotoxin Detection Systems for Grain Handling Facilities Market
Agricultural Testing Services
Pesticide Detection Market
Agricultural Testing Services
Soil Erosion Testing Market
Agricultural Testing Services
Agricultural Testing Services Market
Agricultural Testing Services
Global Agriculture Testing Services Market
Agricultural Testing Services
Nematode Testing Services Market