
 Africa Agrochemicals Market | 2026-2036
Africa Agrochemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Agrochemicals Market Outlook
Modular input bundles combining seed treatment, foliar feed, and crop protection into single-purchase packages is rebalancing procurement patterns across African smallholder networks. Syngenta Group leverages its integrated crop solution architecture to anchor premium bundle penetration in East African markets. Bayer AG competes through biologicals-plus-chemistry combinations that extend its footprint in integrated pest management corridors. UPL Limited differentiates via open-architecture distribution partnerships that sustain last-mile coverage in fragmented rural catchments.
Africa agrochemicals encompass synthetic and biological inputs formulated for soil fertility management, pest suppression, and crop yield optimization, typically delivered as granulated fertilizers, emulsifiable concentrates, or wettable powders with active ingredient loadings calibrated to tropical agronomic conditions. Fertilizers dominate value capture across the continent given chronic soil nutrient depletion, while herbicides represent the fastest-expanding category as mechanized cultivation spreads in Sudan and Ethiopia's commercial farming zones. Application segmentation reveals cereal crops as the mature volume anchor, with fruits and vegetables commanding disproportionate margin pools through export-oriented quality protocols.
National regulators including South Africa's Registrar of Act 36 and Nigeria's NAFDAC enforce residue limits and import registration requirements that shape product formulation standards and market access timelines. The African Union's fertilizer financing mechanisms and Kenya's Crops Act compliance mandates are concentrating demand around certified, traceable input supply chains. Stakeholders must monitor evolving biopesticide registration pathways and subsidy program design shifts that will determine competitive positioning in government-procured input schemes.
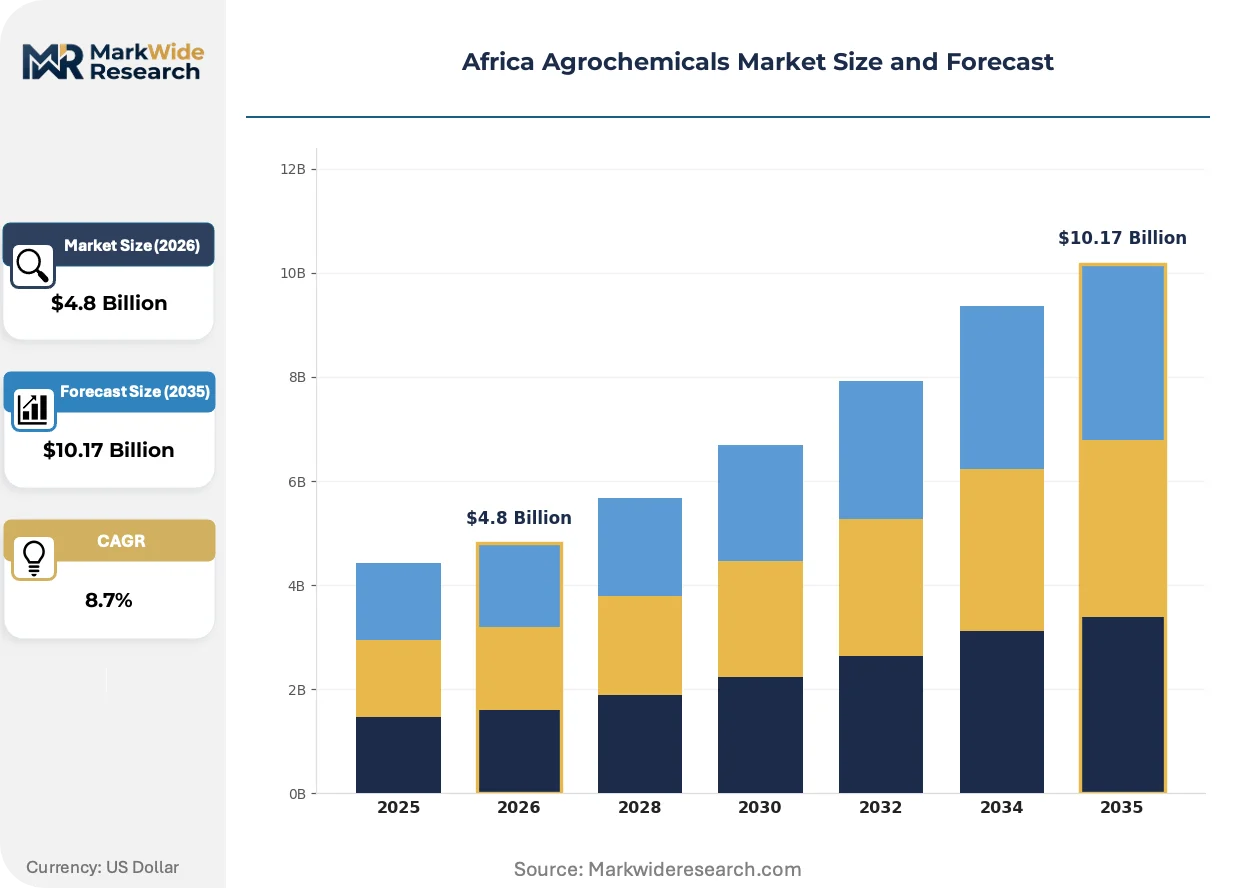
Market Dynamics
Kenya's fertilizer subsidy reforms and Nigeria's input bundling mandates are compressing procurement cycles across African smallholder networks, forcing suppliers to reconfigure distribution architectures around government-procured tender systems.
Growth Catalysts
- Climate-Smart Agriculture Programs:East African governments are embedding agrochemical access into national adaptation frameworks, channeling multilateral climate finance toward certified input subsidies.
- Sudan's Mechanized Cultivation Expansion:Commercial farming zones in the Gezira Scheme are scaling herbicide-intensive row-crop systems, creating concentrated demand corridors for selective weed control formulations.
- Biopesticide Registration Pathways:South Africa's Registrar of Act 36 is streamlining biological active ingredient approvals, reducing market access timelines for microbial and botanical formulations.
Market Restraints
- Phosphate and Potash Import Dependency:African blending operations source over 80 percent of P and K inputs from Moroccan and Russian suppliers, exposing margin structures to seaborne freight volatility and currency mismatches.
- Last-Mile Distribution Fragmentation:Rural agrodealer networks in Ethiopia's highlands and DRC's eastern provinces lack cold-chain infrastructure for biological formulations, constraining product integrity beyond urban hubs.
- Synthetic Chemistry Substitution Pressure:Export-oriented horticulture clusters in Kenya and Senegal face tightening MRL protocols from EU EFSA residue standards, accelerating grower migration toward biological alternatives.
Strategic Opportunities
- Ethiopia's Underpenetrated Cereal Belt:The Amhara and Oromia highlands maintain fertilizer application rates below 20 kilograms per hectare, presenting white-space expansion for micronutrient-enriched NPK blends.
- Digital Input Financing Convergence:Mobile money platforms and satellite-based credit scoring are collapsing cash-prepayment requirements, enabling agrochemical suppliers to embed subscription models within smallholder purchasing cycles.
- African Union Fertilizer Financing Mechanisms:The continental body's import facilitation instruments are concentrating procurement volumes around certified suppliers, rewarding traceable supply chain investments with preferential tender access.
Industry Challenges
- Soil Testing Technician Scarcity:Agronomic advisory services lack sufficient trained personnel to execute grid-based soil sampling across Nigeria's northern cereal belt, undermining precision fertilizer recommendation adoption.
- Multi-Jurisdiction Registration Complexity:Product dossier requirements diverge between Kenya's PCPB, Nigeria's NAFDAC, and South Africa's Registrar of Act 36, forcing redundant toxicology studies and field trial replication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Agrochemicals Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fertilizers, Herbicides, Insecticides, Fungicides Application: Cereal Crops, Oilseeds, Fruits, Vegetables Distribution Channel: Direct Sales, Retail, Online, Distributors Customer Type: Farmers, Agricultural Cooperatives, Agro-businesses, Retailers |
| Companies Covered | BASF SE, Syngenta Group, Bayer AG, Corteva Agriscience, UPL Limited, Omnia Group Limited, FMC Corporation, OCP Group, Nutrien, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Agrochemicals Market Strategic Shifts
Biological-synthetic formulation hybrids and digital extension platforms are compressing the traditional agrochemical value chain, displacing standalone chemistry sales with integrated crop management subscriptions.
Microencapsulated biopesticide delivery systems are electrifying pest suppression efficacy in tropical humidity conditions. Ghanaian cocoa cooperatives and Kenyan tea outgrower schemes are piloting these formulations at commercial scale. The technology is electrifying margins in high-value export crops by reducing reapplication frequency and labor costs.
South Africa's Registrar of Act 36 is tightening data requirements for novel active ingredient registrations, mandating extended environmental fate studies for groundwater vulnerability zones. This regulatory compression is lengthening pre-market timelines for synthetic chemistry entrants. Biological formulation developers are responding by accelerating dossier submissions for exempt microbial categories.
Smallholder purchasing is fragmenting across mobile-enabled input marketplaces and cooperative aggregation platforms. Traditional agrodealer networks in Tanzania's lake zone and Uganda's eastern corridor are losing volume share to farmer group procurement collectives. Kenya's Crops Act compliance mandates are reinforcing this shift by requiring traceability documentation that centralized cooperatives manage more efficiently than dispersed retailers.
Africa Agrochemicals Market Segmentation
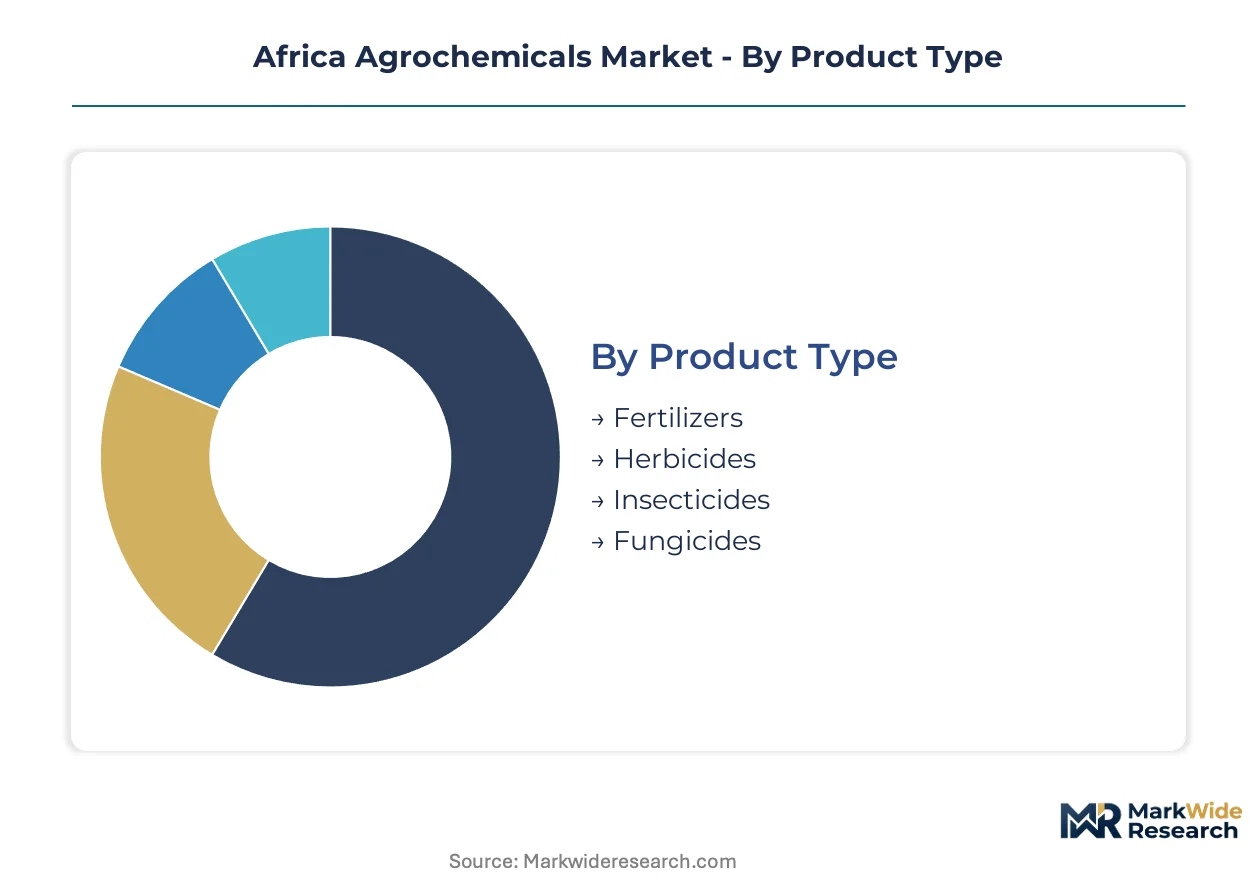
Product formulation chemistry, crop-specific agronomic requirements, and purchasing channel economics create distinct competitive arenas across African agrochemical markets. Understanding these segment boundaries enables suppliers to calibrate pricing architecture and distribution investments against actual demand concentration patterns.
Product Type:
Formulation chemistry determines margin structure and regulatory pathway complexity across tropical agronomic zones.
- Fertilizers:Granulated NPK blends, urea, and micronutrient-enriched compounds dominate volume flows given chronic soil nutrient depletion across East African highlands. Kenya's subsidy reforms and Ethiopia's cereal belt expansion anchor procurement concentration for certified, traceable formulations.
- Herbicides:Selective and non-selective weed control formulations in emulsifiable concentrate and wettable powder formats are climbing fastest as mechanized cultivation spreads through Sudan's Gezira Scheme and Ethiopia's commercial farming corridors.
- Insecticides:Synthetic pyrethroids and neonicotinoid formulations target stem borer and aphid pressure in Nigeria's northern cereal belt, with biopesticide alternatives gaining registration traction under South Africa's streamlined Act 36 pathways.
- Fungicides:Protectant and systemic formulations address rust and blight complexes in high-humidity cocoa and tea zones, with microencapsulated delivery systems piloting in Ghanaian cooperatives.
Fertilizers lead on scale; herbicides lead on momentum.
Application:
Crop value density and export orientation split demand between volume-anchored staples and margin-rich specialty production.
- Cereal Crops:Maize, wheat, and sorghum systems consume the bulk of nitrogen-heavy fertilizer blends across Nigeria's northern belt and Ethiopia's Amhara highlands, with government procurement tenders concentrating supplier relationships.
- Fruits:Export-oriented citrus, avocado, and mango clusters in Kenya and Senegal drive premium fungicide and insecticide specifications, with EU MRL compliance mandates accelerating biological formulation adoption.
- Vegetables:Tomato, onion, and leafy green production in peri-urban supply zones around Lagos and Nairobi generates concentrated herbicide demand for labor-saving weed management.
- Oilseeds:Soybean and groundnut rotations in Zambia's eastern province and Tanzania's southern corridor require specialized rhizobia-compatible fertilizer blends and selective pre-emergent herbicides.
Cereal crops anchor procurement volumes; fruits command premium pricing tiers.
Distribution Channel:
Channel selection reflects customer scale, credit access, and traceability documentation requirements under evolving national compliance mandates.
- Distributors:Regional wholesalers with cold-chain capabilities and warehouse networks bridge fragmented last-mile coverage in DRC's eastern provinces and Ethiopia's highland catchments, sustaining biological formulation integrity.
- Direct Sales:Large-scale commercial farms and agro-industrial estates in Sudan and Zambia negotiate volume contracts with manufacturers, bypassing traditional retail markups for straight fertilizer and bulk herbicide purchases.
- Retail:Agrodealer networks in Tanzania's lake zone and Uganda's eastern corridor face volume share erosion as cooperative aggregation platforms capture traceability-compliant procurement.
- Online:Mobile-enabled input marketplaces and satellite-scored credit platforms are collapsing cash-prepayment requirements for smallholder segments in Kenya's Crops Act compliance zones.
Distributors sustain rural coverage; online channels are expanding most quickly.
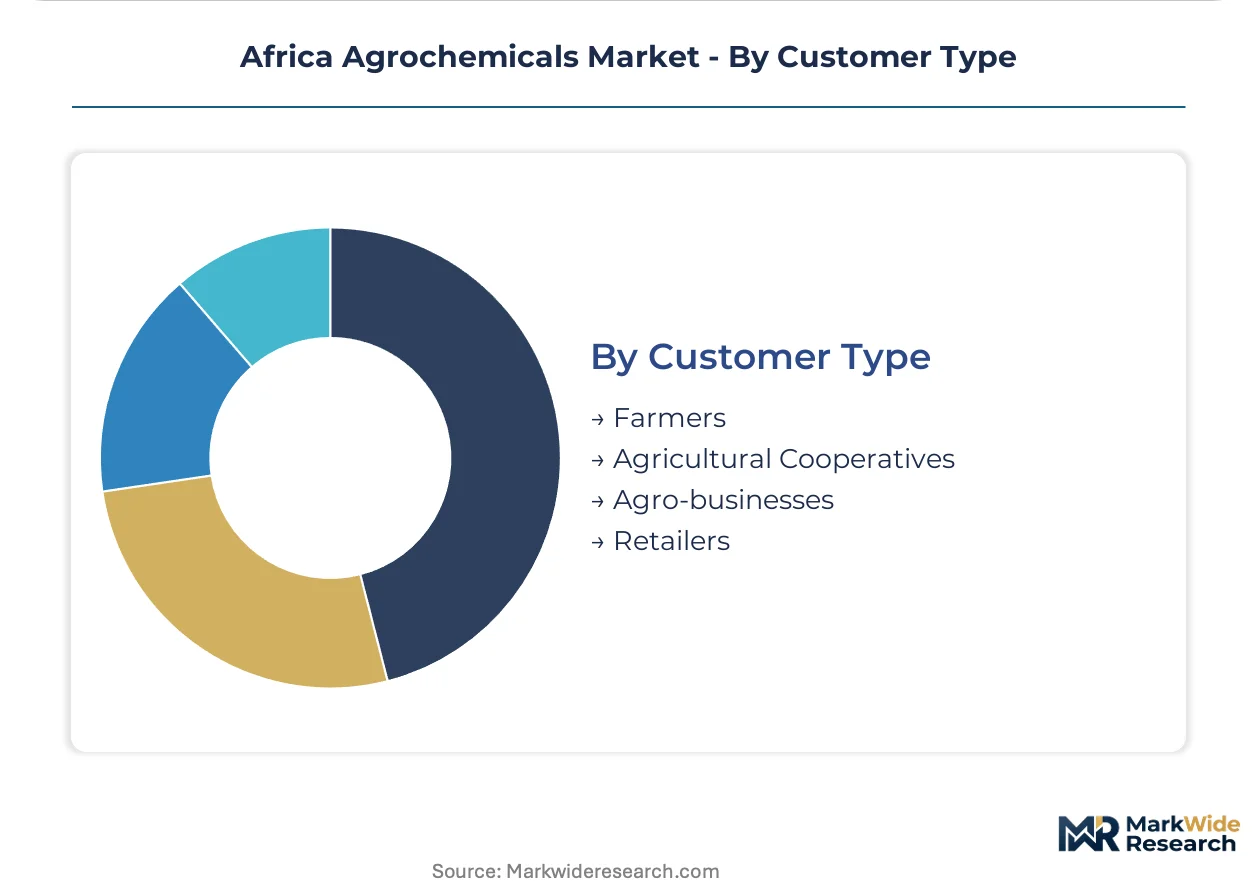
Customer Type:
Purchasing scale and organizational sophistication determine bundle complexity and advisory service bundling economics.
- Farmers:Smallholder households across East Africa's highlands represent the largest addressable population, with climate-smart program subsidies and mobile financing reshaping input access patterns.
- Agricultural Cooperatives:Centralized procurement collectives in Kenya's tea outgrower schemes and Ghanaian cocoa cooperatives manage traceability documentation more efficiently than dispersed retailers, capturing government tender preferences.
- Agro-businesses:Integrated estate operations and contract farming aggregators in Ethiopia's Oromia region and Zambia's commercial corridors negotiate specification-grade formulations with embedded agronomic advisory.
- Retailers:Independent agrodealer proprietors in fragmented rural networks face margin compression as cooperative and digital channels disintermediate traditional stocking and credit extension functions.
Farmers represent the deepest volume pool; agricultural cooperatives are gaining procurement influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial agrochemical distribution in Africa traces its modern structure to colonial plantation systems and post-independence state marketing boards. These historical foundations shaped today's fragmented but evolving procurement networks across diverse agro-ecological zones.
Kenya
Smallholder fertilizer consumption is accelerating through subsidy reform programs targeting maize and wheat belts. The country's PCPB enforces residue limits that redirect horticulture exporters toward biopesticide formulations. Nairobi-based input aggregators and Mombasa port logistics clusters anchor East African distribution corridors.
Nigeria
Northern cereal zones generate concentrated demand for herbicide-insecticide bundles in sorghum and millet production systems. NAFDAC registration requirements for imported active ingredients extend market access timelines for new entrants. Kano and Kaduna trading hubs coordinate cross-border supply movements into Niger and Chad.
South Africa
Commercial maize and citrus operations sustain premium-grade agrochemical specification demand. The Registrar of Act 36 mandates extended environmental fate studies that lengthen synthetic chemistry approval cycles. Gauteng warehousing complexes and Durban port facilities concentrate import and blending infrastructure.
Ethiopia
Amhara and Oromia highlands maintain sub-20 kilogram per hectare fertilizer application rates, creating expansion headroom for micronutrient-enriched blends. Federal input procurement tenders centralize supplier relationships around state-affiliated distribution channels. Awash Valley commercial farming zones pilot mechanized cultivation with selective herbicide protocols.
Ghana
Cocoa cooperative networks drive specialized fungicide demand for black pod and capsid control in Western and Ashanti regions. The national cocoa regulator's quality protocols influence crop protection product selection among outgrower schemes. Takoradi port infrastructure supports input import logistics for neighboring Côte d'Ivoire border zones.
Africa Agrochemicals Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation complexity and advisory service bundling. Integrated crop solution architects capture disproportionate returns in East African bundling corridors, while commodity blenders compete on price in government tender markets. Three archetypes dominate: multinational integrated solution providers, regional formulation specialists, and state-affiliated import facilitators. Capacity expansion and distribution partnership architectures represent the dominant competitive moves as suppliers reposition around subsidy program procurement cycles.
Among European-headquartered integrated solution providers, BASF SE and Bayer AG occupy positions exemplifying chemistry-biologicals hybrid strategies. Syngenta Group anchors the premium bundle penetration archetype in East African markets. UPL Limited represents the open-architecture distribution partnership model sustaining rural last-mile coverage.
| Leading Market Players |
|---|
| BASF SE |
| Syngenta Group |
| Bayer AG |
| Corteva Agriscience |
| UPL Limited |
| Omnia Group Limited |
| FMC Corporation |
| OCP Group |
| Nutrien |
| Others |
Value Chain & Pricing Dynamics
Kenya's Crops Act traceability mandates gate qualified supply access and premium-tier pricing power, compressing margins for uncertified formulations while rewarding investments in documented input chains. Smallholder procurement fragmentation and phosphate import dependency reshape how suppliers calibrate pricing architecture against distribution reach.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and bundled advisory intensity. Premium tiers attach to EU MRL-compliant biopesticide formulations for Kenyan avocado exporters, while economy tiers serve subsidy-procured urea in Ethiopia's cereal belt. Cost compression in standard-tier NPK blends intensifies as Moroccan phosphate freight volatility feeds into landed costs. Agricultural cooperatives exhibit lowest price sensitivity due to centralized tender volumes; dispersed agrodealer networks face acute margin pressure from digital marketplace disintermediation.
Supply Chain Analysis
Direct-to-estate channels handle commercial farm demand in Sudan's Gezira Scheme and Zambia's copperbelt corridors, while cooperative aggregation platforms capture traceability-compliant smallholder procurement in Kenya and Ghana. Manufacturing concentrates in South Africa's Gauteng blending complexes, Morocco's OCP phosphate processing hubs, and Nigerian northern formulation facilities. Raw material dependencies center on Moroccan phosphate rock, Russian potash, and Chinese active ingredient intermediates. Single-source vulnerability in seaborne P and K inputs exposes margin structures to currency mismatches. Distribution runs through Mombasa and Durban port logistics clusters anchoring East and Southern African coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with South Africa's Registrar of Act 36 environmental fate study mandates and Kenya's Crops Act traceability requirements accelerating demand concentration around certified supply chains.
For Market Incumbents: Anticipate synthetic chemistry substitution pressure from EU EFSA residue tightening by accelerating biological-synthetic hybrid dossier submissions. Defend channel control through backward integration into cold-chain distribution partnerships sustaining last-mile biological formulation integrity in DRC's eastern provinces and Ethiopia's highland catchments. For New Entrants and Emerging Players: Enter via Ethiopia's underpenetrated Amhara and Oromia cereal belts, where sub-20 kilogram per hectare fertilizer application rates create white-space for micronutrient-enriched NPK blends. Target cooperative procurement aggregation platforms as the most penetrable channel archetype, leveraging mobile-enabled input financing convergence to bypass traditional agrodealer credit extension requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among regional formulation specialists lacking traceability documentation capabilities but possessing established distribution networks in government tender corridors. Long-term viability hinges on positioning for African Union fertilizer financing mechanism procurement concentration. Watch biopesticide registration pathway streamlining under South Africa's Act 36 reforms as the inflection signal for biological formulation value capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Sourcing | Moroccan and Russian supplier dependency exposes margin structures to seaborne freight volatility and currency mismatches. |
| Cold-Chain Distribution Partnership Expansion | Biological formulation integrity in DRC's eastern provinces and Ethiopia's highlands requires temperature-controlled last-mile infrastructure. |
| Biopesticide Registration Dossier Acceleration | South Africa's streamlined Act 36 pathways for microbial categories compress pre-market timelines versus synthetic chemistry. |
| Cooperative Procurement Platform Integration | Kenya's Crops Act traceability mandates concentrate tender preferences around centralized aggregation collectives. |
| Micronutrient-Enriched Blend Capacity Addition | Ethiopia's Amhara and Oromia highlands present expansion headroom for precision fertilizer recommendations. |
Study Parameters
Multiple input streams — primary interviews with agrochemical distribution heads, regulatory affairs specialists at national registrars, and cooperative procurement managers; secondary validation through customs/trade data, FAO fertilizer consumption databases, and SEC filings of listed suppliers; plus bottom-up and top-down triangulation — were reconciled to construct market estimates. Field perspectives from Kenya's PCPB, Nigeria's NAFDAC, and South Africa's Registrar of Act 36 anchored regulatory pathway assessments.
Data-stream reconciliation across product formulation chemistry, crop-specific application requirements, and purchasing channel economics enabled segmentation modeling. The analytical framework projected value and volume trajectories across the analysis window by calibrating CAGRs against subsidy program disbursement cycles, mechanization adoption curves, and biological registration throughput. Key inputs included fertilizer application rate surveys, horticulture export volume correlations, and mobile money penetration indices.
The model holds under stable multilateral climate finance disbursement and subsidy program continuity; deviation in currency volatility or phosphate supply disruption would shift trajectory assumptions. Forecasts reflect documented base conditions without contingency weighting. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agrochemicals
South America Agrochemicals Market
Agrochemicals
Agrochemical Market
Agrochemicals
Egypt Agrochemicals Market
Agrochemicals
Agrochemical Active Ingredients Market
Agrochemicals
Global Glufosinate Market
Agrochemicals
India Agrochemicals Market
Agrochemicals
Indonesia Agrochemicals Market
Agrochemicals
Malaysia Agrochemicals Market
Agrochemicals
Superphosphates Market
Agrochemicals
Middle East and Africa Plant Growth Regulators Market
Agrochemicals
Canada Agrochemicals Market
Agrochemicals
North America Agrochemicals Market
Agrochemicals
Mexico Agrochemicals Market
Agrochemicals
L-Glufosinate Ammonium Market
Agrochemicals
Australia Agrochemicals Market
Agrochemicals
Potassium Humate Market