
 Europe Feed Testing Market | 2026-2036
Europe Feed Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Feed Testing Market Foresight
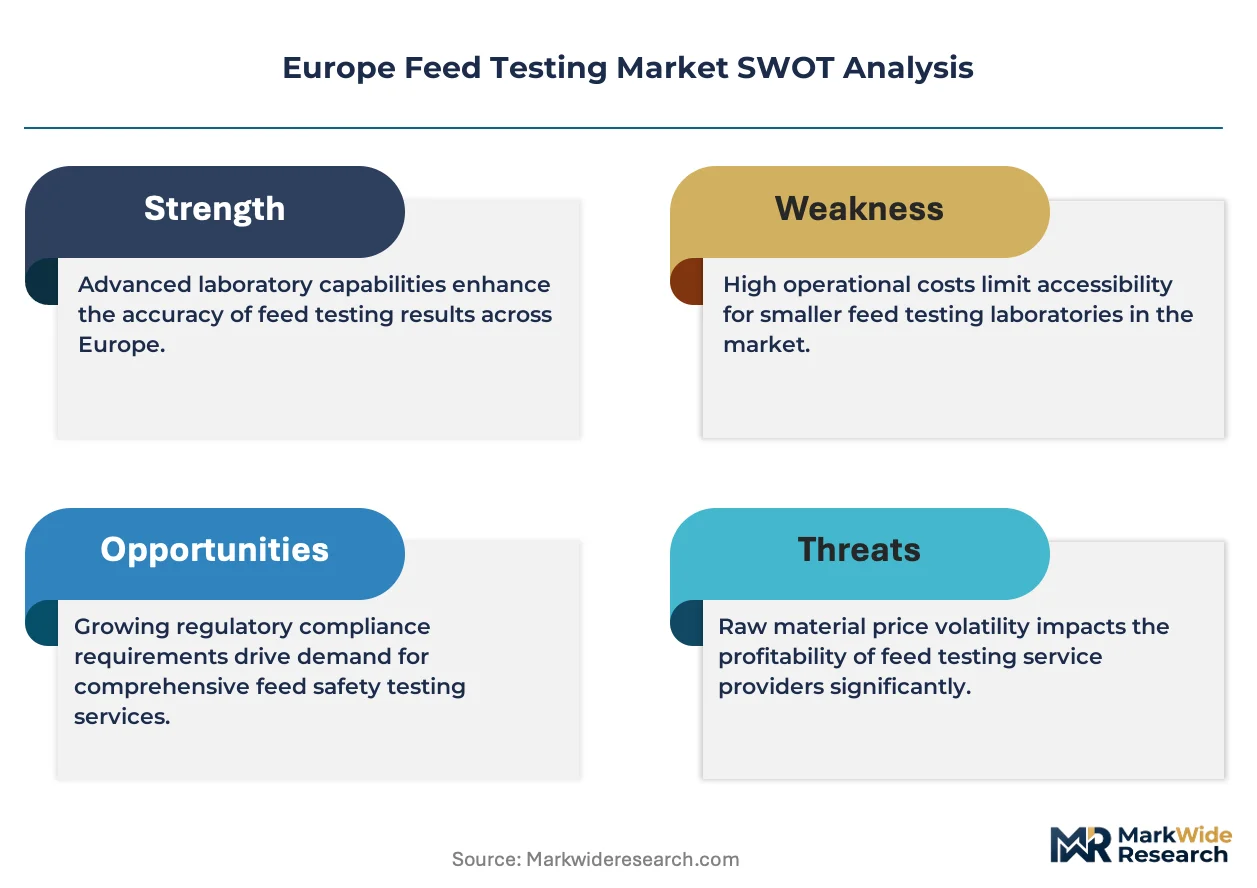
The EU Green Deal's farm-to-fork strategy is broadening mandatory residue monitoring across compound feed supply chains. Eurofins Scientific leverages its pan-European laboratory footprint to capture cross-border testing volumes. SGS Group anchors its position through ISO 17025-accredited facilities serving dairy and poultry integrators. Bureau Veritas differentiates via sustainability certification bundled with contaminant screening.
Feed testing encompasses analytical verification of nutritional composition, mycotoxin load, pathogen presence, and chemical residues in animal feedstuffs using chromatography, mass spectrometry, and PCR-based methods to ensure safety and regulatory compliance before consumption. Nutritional analysis occupies the largest service share as formulators optimize amino acid and energy density profiles under EFSA guidelines. Pathogen detection registers the fastest expansion as Salmonella and E. coli mandates tighten across member states. ELISA technology dominates routine mycotoxin screening due to throughput economics, while mass spectrometry captures premium pricing for multi-residue panels.
EMA, EFSA, and REACH collectively shape feed testing demand through maximum residue limits, contaminant thresholds, and chemical safety assessments that laboratories must validate against. The EU AI Act introduces emerging requirements for automated diagnostic systems used in high-throughput feed analysis facilities. Stakeholders must calibrate technology roadmaps against pending revisions to the F-Gas Regulation affecting analytical instrument cooling systems.
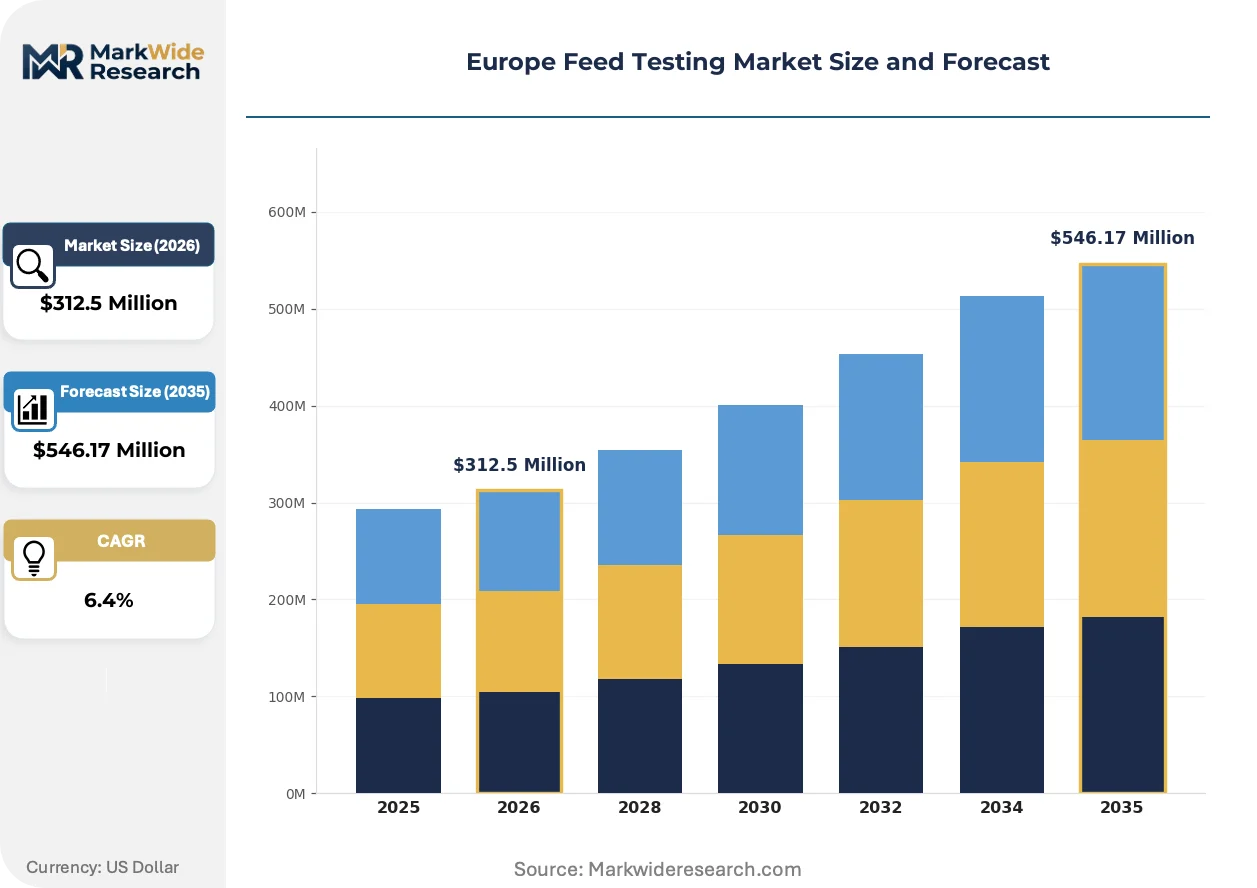
Market Dynamics
The EU Green Deal's farm-to-fork sustainability mandates are compressing testing timelines while expanding analytical scope across compound feed supply chains, forcing laboratories to retool for multi-residue panels and carbon-footprint verification.
Growth Catalysts
- EFSA contaminant thresholds:Tightening maximum residue limits for mycotoxins and heavy metals in poultry and dairy feed are mandating higher testing frequencies at mill intake points.
- PCR-based pathogen detection:Salmonella and E. coli screening requirements under member-state food safety laws are accelerating adoption of rapid molecular diagnostics over culture methods.
- Netherlands-Germany corridor:Concentrated livestock production in these markets generates cross-border testing volumes that reward laboratories with pan-European accreditation networks.
Market Restraints
- Helium supply concentration:Mass spectrometry systems depend on helium for cooling, with sourcing bottlenecks from Algerian and Russian suppliers raising operational vulnerability.
- F-Gas Regulation cooling limits:Pending restrictions on fluorinated greenhouse gases in analytical instrument cooling systems threaten thermal management for high-throughput chromatography platforms.
- ISO 17025 accreditation costs:Multi-site laboratory networks face substantial capital outlays to maintain method validation across national accreditation bodies.
Strategic Opportunities
- Poland and Romania feed mills:Underpenetrated markets in Eastern European livestock regions offer first-mover positioning as EU cohesion funds modernize agricultural infrastructure.
- Sustainability certification bundling:Laboratories can capture premium positioning by integrating carbon footprint verification with contaminant screening under the EU Green Deal's climate targets.
- AI Act automated diagnostics:Compliance frameworks for machine-learning-based mycotoxin classification systems create differentiation for laboratories investing in validated algorithmic screening.
Industry Challenges
- Mass spectrometry technician scarcity:Specialized expertise in LC-MS/MS method development and maintenance is concentrating in Western European urban centers, constraining facility expansion.
- Legacy ELISA integration:Feed mills with sunk investments in enzyme-linked immunosorbent assay infrastructure face friction migrating to multi-residue chromatographic platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Feed Testing Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Microbiological Testing, Nutritional Analysis, Chemical Testing, Pathogen Detection Application: Agriculture, Aquaculture, Livestock, Pet Food End User: Feed Manufacturers, Livestock Producers, Aquaculture Farms, Research Institutions Technology: ELISA, PCR, Mass Spectrometry, Chromatography |
| Companies Covered | Eurofins Scientific, SGS Group, Intertek Group, Neogen, Romer Labs, Biomin, Alltech, Merck, Bureau Veritas, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Feed Testing Market Shifts & Advancements
Digitalization of feed safety verification is compressing result turnaround times while expanding the data granularity available to formulators. Three interconnected developments are restructuring laboratory service models.
High-resolution mass spectrometry is rewriting contaminant detection capabilities by enabling non-targeted screening for emerging chemical hazards. Poultry integrators in France and the Netherlands are adopting these platforms at contract laboratories to satisfy EFSA data requirements on novel feed additives. The technology is compressing the window between sample intake and regulatory-compliant release decisions from days to hours.
REACH chemical safety assessments are extending liability upstream into feed ingredient supply chains. Manufacturers of novel protein sources and feed additives must now submit dossiers on environmental fate and toxicological profiles before market authorization. Dairy compounders sourcing alternative proteins face the steepest compliance burden as ECHA evaluates cumulative exposure scenarios.
Consolidated procurement by multinational feed groups is displacing transactional relationships with local testing providers. Large poultry and dairy integrators in Germany are centralizing testing contracts with accredited networks capable of harmonized reporting across multiple production sites. This concentration is visible most acutely in the Rhine-Ruhr industrial corridor, where three feed manufacturers now account for the majority of third-party mycotoxin screening volume.
Europe Feed Testing Market Segmentation
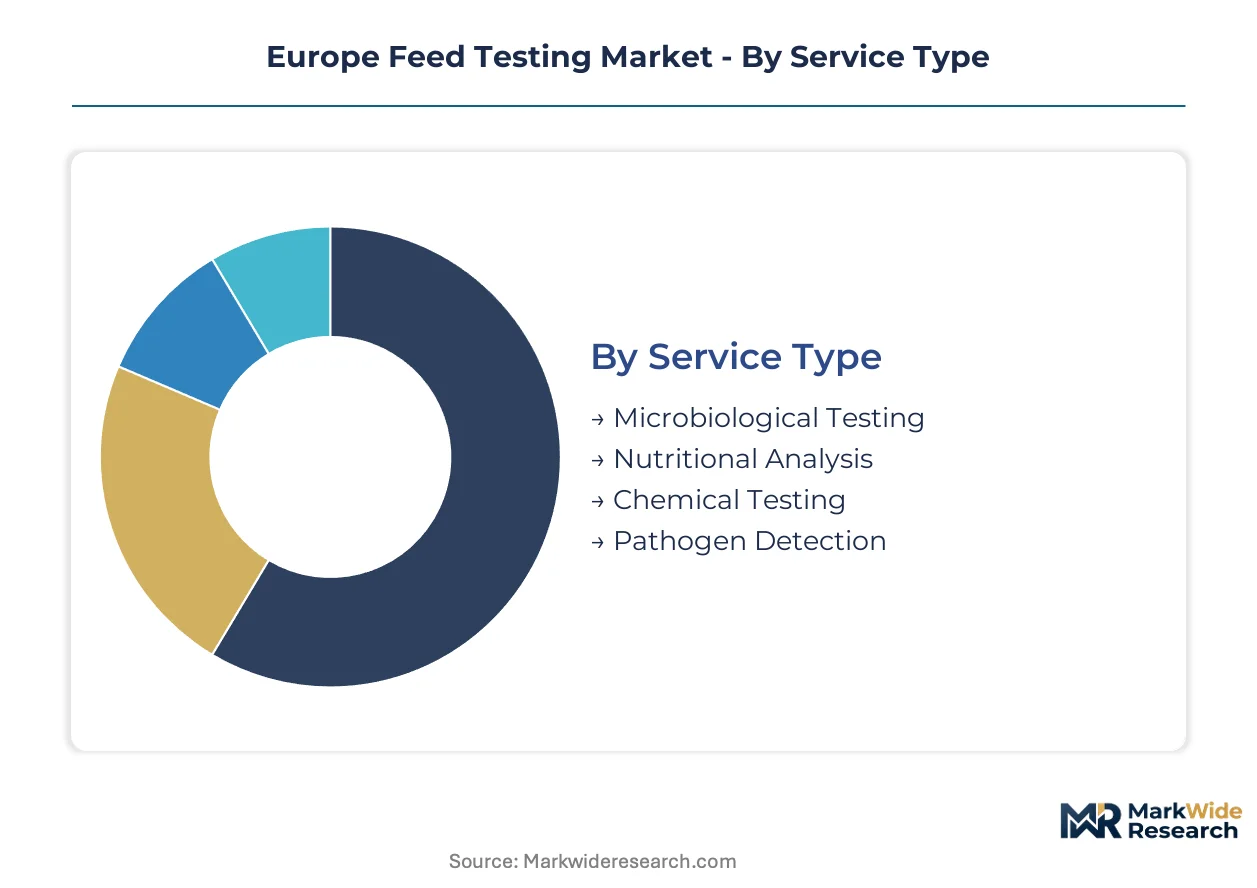
Feed testing laboratories across Europe calibrate service portfolios against divergent regulatory pressures and end-use economics. Segment boundaries reflect where EFSA mandates tighten, where integrators consolidate procurement, and where emerging protein sources create novel analytical demands.
Service Type:
Technical sophistication and throughput economics separate routine screening from premium analytical services.
- Nutritional Analysis:Laboratories quantify amino acid profiles, energy density, and mineral content using near-infrared spectroscopy and wet chemistry methods. Poultry compounders in the Netherlands and Germany commission these services most intensively as they optimize feed conversion ratios under EFSA formulation guidelines.
- Pathogen Detection:PCR-based molecular diagnostics identify Salmonella, E. coli, and Listeria in raw materials and finished feeds. Dairy integrators in France are accelerating adoption as member-state food safety laws mandate negative release certificates before distribution.
- Microbiological Testing:Culture-based and rapid methods assess total bacterial load and spoilage organisms.
- Chemical Testing:Chromatographic techniques verify pesticide residues, heavy metals, and unauthorized additives.
Nutritional analysis leads on scale; pathogen detection leads on momentum.
Application:
End-use concentration determines where laboratories anchor accredited capacity and specialist expertise.
- Livestock:Dairy and poultry operations generate the dominant testing volumes across the Rhine-Ruhr corridor and Dutch Gelderland region. EFSA mycotoxin thresholds for aflatoxin B1 and deoxynivalenol mandate pre-shipment verification at mill intake points.
- Aquaculture:Salmon and trout producers in Norway and Scotland commission specialized panels for veterinary residues and environmental contaminants. REACH assessments for novel feed ingredients are extending analytical scope into alternative protein dossiers.
- Agriculture:Equine and specialty animal feed manufacturers require customized nutritional verification.
- Pet Food:Premium companion animal brands demand contaminant screening and label claim validation.
Livestock commands absolute volume; aquaculture shows the steepest expansion trajectory.
End User:
Procurement consolidation is restructuring how testing services are contracted and delivered.
- Feed Manufacturers:Compound feed mills in Germany and France operate internal laboratories for routine nutritional analysis while outsourcing multi-residue panels to accredited third parties. ISO 17025 certification requirements favor partnerships with pan-European networks.
- Livestock Producers:Large integrators are centralizing testing contracts with providers capable of harmonized reporting across multiple production sites. Three poultry groups now account for the majority of third-party mycotoxin screening in Lower Saxony.
- Aquaculture Farms:Norwegian salmon producers coordinate testing through industry associations.
- Research Institutions:Universities and feed technology centers validate novel analytical methods.
Feed manufacturers anchor current revenue; livestock producers are driving contract restructuring fastest.
Technology:
Capital intensity and technical labor availability constrain platform selection across laboratory networks.
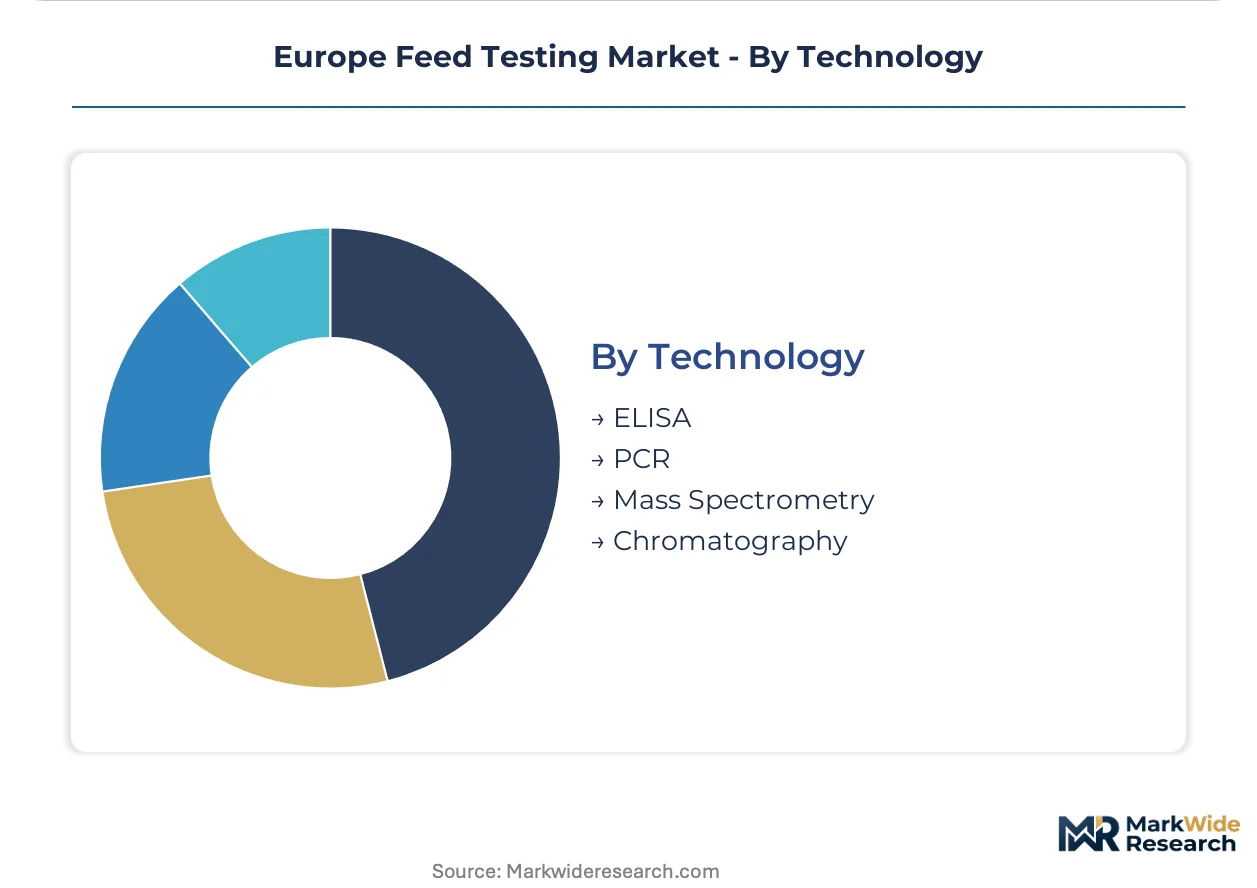
- ELISA:Enzyme-linked immunosorbent assays deliver cost-effective throughput for routine mycotoxin screening. Feed mills with sunk investments in this infrastructure face friction migrating to chromatographic platforms despite superior multi-residue capabilities.
- Mass Spectrometry:LC-MS/MS and high-resolution platforms enable non-targeted screening for emerging chemical hazards. Specialized technician scarcity in Western European urban centers constrains facility expansion beyond established metropolitan clusters.
- PCR:Polymerase chain reaction methods accelerate pathogen detection timelines.
- Chromatography:Gas and liquid chromatography systems support residue quantification under EFSA methods.
ELISA dominates transaction volume; mass spectrometry is climbing the fastest on premium panel adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized mass spectrometry technicians concentrate in Western European metropolitan clusters, anchoring laboratory capacity expansion across the Rhine-Ruhr corridor and Dutch Gelderland region.
Germany
Poultry and dairy integrators in Lower Saxony and North Rhine-Westphalia are centralizing testing contracts with pan-European accredited networks. The F-Gas Regulation imposes cooling system constraints on high-throughput chromatography platforms. Three feed manufacturers in the Rhine-Ruhr corridor now account for the majority of third-party mycotoxin screening volume.
Netherlands
Poultry compounders commission intensive nutritional analysis services to optimize feed conversion ratios under EFSA formulation guidelines. REACH chemical safety assessments extend liability upstream into novel protein supply chains. Gelderland's concentrated livestock production generates cross-border testing volumes that reward laboratories with multi-site accreditation networks.
France
Dairy integrators accelerate PCR-based pathogen detection adoption as member-state food safety laws mandate negative release certificates before distribution. EFSA contaminant thresholds for aflatoxin B1 tighten maximum residue limits at mill intake points. Poultry integrators in northern France contract high-resolution mass spectrometry platforms for non-targeted screening of emerging chemical hazards.
Poland
Underpenetrated feed mills in Eastern European livestock regions offer first-mover positioning as EU cohesion funds modernize agricultural infrastructure. The EU Green Deal's farm-to-fork sustainability mandates compress testing timelines while expanding analytical scope. Compound feed production clusters around Warsaw and Kraków are upgrading from legacy ELISA infrastructure to chromatographic platforms.
Norway
Salmon and trout producers commission specialized panels for veterinary residues and environmental contaminants under aquaculture-specific regulatory frameworks. REACH assessments for alternative protein dossiers extend analytical scope into novel feed ingredients. Bergen and Trondheim testing facilities coordinate through industry associations to harmonize reporting across multiple production sites.
Europe Feed Testing Market Competitive Landscape
Capital-heavy laboratory networks compete with asset-light diagnostic service providers across the European feed testing landscape. Pan-European accreditation consolidates procurement relationships with multinational feed groups seeking harmonized reporting across multiple production sites. Three strategic archetypes dominate: pan-European laboratory networks with ISO 17025-accredited multi-site footprints, specialized mycotoxin and pathogen detection boutiques, and diversified testing conglomerates bundling sustainability certification with contaminant screening. Dominant competitive moves include geographic expansion into underpenetrated Eastern European markets and technology licensing partnerships for AI-enabled automated diagnostic systems.
Within the pan-European network tier, Eurofins Scientific and SGS Group exemplify scale-driven positioning through extensive laboratory footprints. Bureau Veritas occupies a differentiated position bundling sustainability certification with core contaminant screening services. These three anchors represent contrasting strategic bets on geographic coverage, service integration depth, and compliance bundling under the EU Green Deal's expanding sustainability mandates.
| Leading Market Players |
|---|
| Eurofins Scientific |
| SGS Group |
| Intertek Group |
| Neogen |
| Romer Labs |
| Biomin |
| Alltech |
| Merck |
| Bureau Veritas |
| Others |
Supply & Pricing Matrix
Helium procurement costs cascade through mass spectrometry service tiers, with Algerian and Russian supply bottlenecks compressing margins at premium analytical laboratories while routine ELISA screening maintains price stability through lower thermal management overhead.
Pricing Analysis
The bundled-vs-unbundled service split separates sustainability-certified contaminant panels from standalone mycotoxin screens. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 17025 accreditation tier and multi-residue panel breadth. Cost compression in premium chromatographic services is intensifying because helium sourcing vulnerability forces operational hedging. Small Polish and Romanian feed mills exhibit highest price sensitivity, while Rhine-Ruhr poultry integrators prioritize harmonized reporting over per-test economics.
Supply Chain Analysis
Reverse-logistics flows for spent analytical columns and instrument refurbishment concentrate servicing capacity in Western European metropolitan clusters. Germany, the Netherlands, and France anchor laboratory equipment manufacturing and certified reference material production. Supply chains draw from Chinese optical component suppliers, Swiss precision engineering, and U.S. mass spectrometer manufacturers. Single-source vulnerability in helium liquefaction threatens thermal-dependent chromatography uptime. Distribution runs through pan-European accreditation networks serving multinational feed groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Feed Testing Market operates as a regulatory compounder where the EU Green Deal's farm-to-fork mandates generate compounding testing frequency requirements across member states.
For Market Incumbents: Extend pan-European accreditation footprints into Poland and Romania before EU cohesion funds complete agricultural infrastructure modernization. Consolidate technician training pipelines in Western urban centers to counter mass spectrometry expertise scarcity. Lock in long-term helium supply contracts or invest in hydrogen-cooled alternative platforms to neutralize Algerian sourcing risk.
For New Entrants and Emerging Players: The EU AI Act in Europe opens a window for algorithmic mycotoxin classification systems that laboratories lack capacity to validate internally. Target underpenetrated Eastern European feed mills upgrading from legacy ELISA infrastructure. Lead with rapid PCR pathogen detection bundled with digital reporting platforms to bypass chromatography capital requirements.
For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 17025 multi-site validation costs outrun standalone laboratory revenue bases. The five-to-ten year viability window favors accredited networks with sustainability certification bundling capabilities. Target acquisition archetype: mid-cap laboratories with dormant Eastern European permits and established EFSA method validation. Monitor F-Gas Regulation cooling system restrictions as inflection indicator for thermal-dependent platform obsolescence.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Diagnostic Validation | The EU AI Act creates first-mover advantage for laboratories with compliant machine-learning mycotoxin systems. |
| Eastern European Laboratory Expansion | Polish and Romanian feed mill modernization under cohesion funds generates captive demand for ISO 17025 services. |
| Helium Independence Programs | Hydrogen-cooled or ambient-temperature chromatography platforms neutralize Algerian supply concentration risk. |
| Sustainability Certification Bundling | Carbon footprint verification integrated with contaminant screening captures EU Green Deal procurement mandates. |
| PCR Platform Standardization | Rapid molecular pathogen detection displaces culture methods as Salmonella and E. coli mandates tighten. |
Research Methodology
Direct dialogue with laboratory operations directors, EFSA regulatory affairs specialists, feed mill procurement managers, and mass spectrometry platform engineers grounded qualitative insights. Secondary validation drew from EFSA scientific opinions, REACH substance dossiers, EU Green Deal implementation reports, and national accreditation body registers. Bottom-up service volume estimates triangulated against top-down compound feed production statistics across member states.
Segment-level projections across service type, application, end user, and technology dimensions anchored the analytical framework over the projection horizon. CAGRs derived from regression analysis of historical testing frequency intensification against regulatory mandate adoption curves. Industry-specific inputs incorporated EFSA maximum residue limit revision schedules and F-Gas Regulation cooling system phase-out timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under helium supply disruption or accelerated AI Act enforcement scenarios. Practitioners should monitor EFSA contaminant threshold revision announcements and Eastern European agricultural infrastructure investment flows for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Testing Services
Pesticide Detection Market
Agricultural Testing Services
Impact Soil Tester Market
Agricultural Testing Services
Asia Pacific Feed Testing Market
Agricultural Testing Services
Global Agriculture Testing Services Market
Agricultural Testing Services
Irrigation Testing Kit Market
Agricultural Testing Services
Plant Disease Diagnostic Market
Agricultural Testing Services
Animal Feed Testing Market
Agricultural Testing Services
Nematode Testing Services Market
Agricultural Testing Services
Soil Field Testing Equipment Market
Agricultural Testing Services
Poultry Diagnostic Testing Market
Agricultural Testing Services
North American Feed Testing Market
Agricultural Testing Services
Agricultural Testing Services Market
Agricultural Testing Services
Plant Nutrient Testing Equipment Market
Agricultural Testing Services
Rapid Mycotoxin Detection Systems for Grain Handling Facilities Market
Agricultural Testing Services
Seed Testing Services Market
Agricultural Testing Services
Pesticide Residue Testing Market