
 Soil Erosion Testing Market | 2026-2036
Soil Erosion Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Soil Erosion Testing Market Analytics
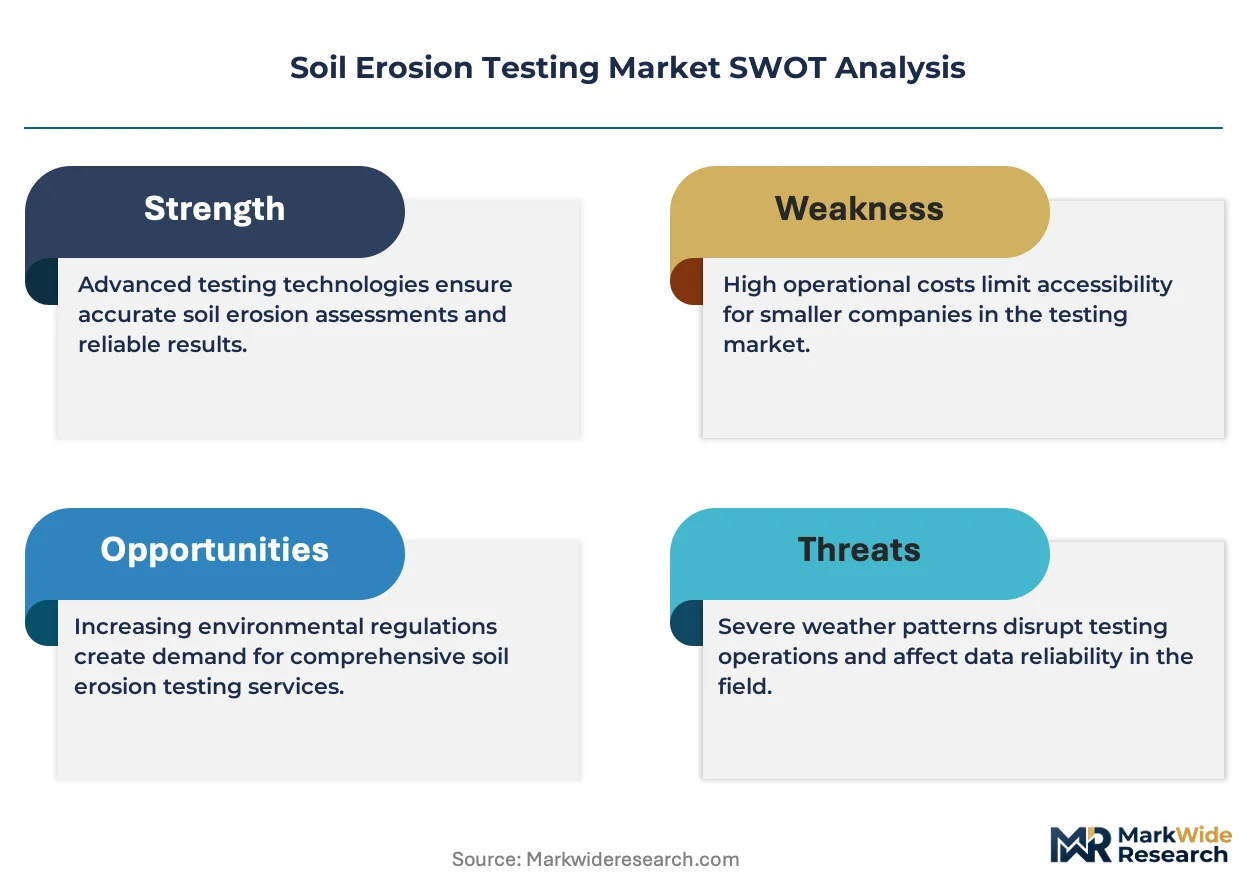
The soil erosion testing industry is recalibrating around a widening gap between premium laboratory-grade analysis and commodity field-kit diagnostics. SGS leverages its transcontinental laboratory network to anchor high-margin certification services for infrastructure megaprojects. Ward Laboratories competes on turnaround speed and regional proximity across the Great Plains agricultural belt. Teklab specializes in portable electrochemical sensors that extend real-time monitoring capabilities to construction site managers.
Soil erosion testing encompasses the quantitative assessment of sediment detachment, transport, and deposition rates through standardized protocols such as the Modified Universal Soil Loss Equation and rainfall simulation at controlled intensities. Laboratory equipment segments dominate absolute revenue, while remote sensing technology represents the fastest-expanding category as satellite-derived terrain models displace manual slope surveys. Erosion simulation applications command premium pricing in environmental impact studies, whereas field kits serve volume-driven soil conservation programs with thinner margins.
The EPA enforces NPDES construction general permit requirements that mandate sediment and erosion control plans with verified testing protocols. ISO 14001 environmental management systems and ASTM D6460 standard test methods for erosion control products shape product qualification pathways and cross-border market access. Stakeholders must monitor evolving state-level adoption of digital submission requirements for erosion control documentation, as regulatory digitization will determine which testing providers retain channel control.
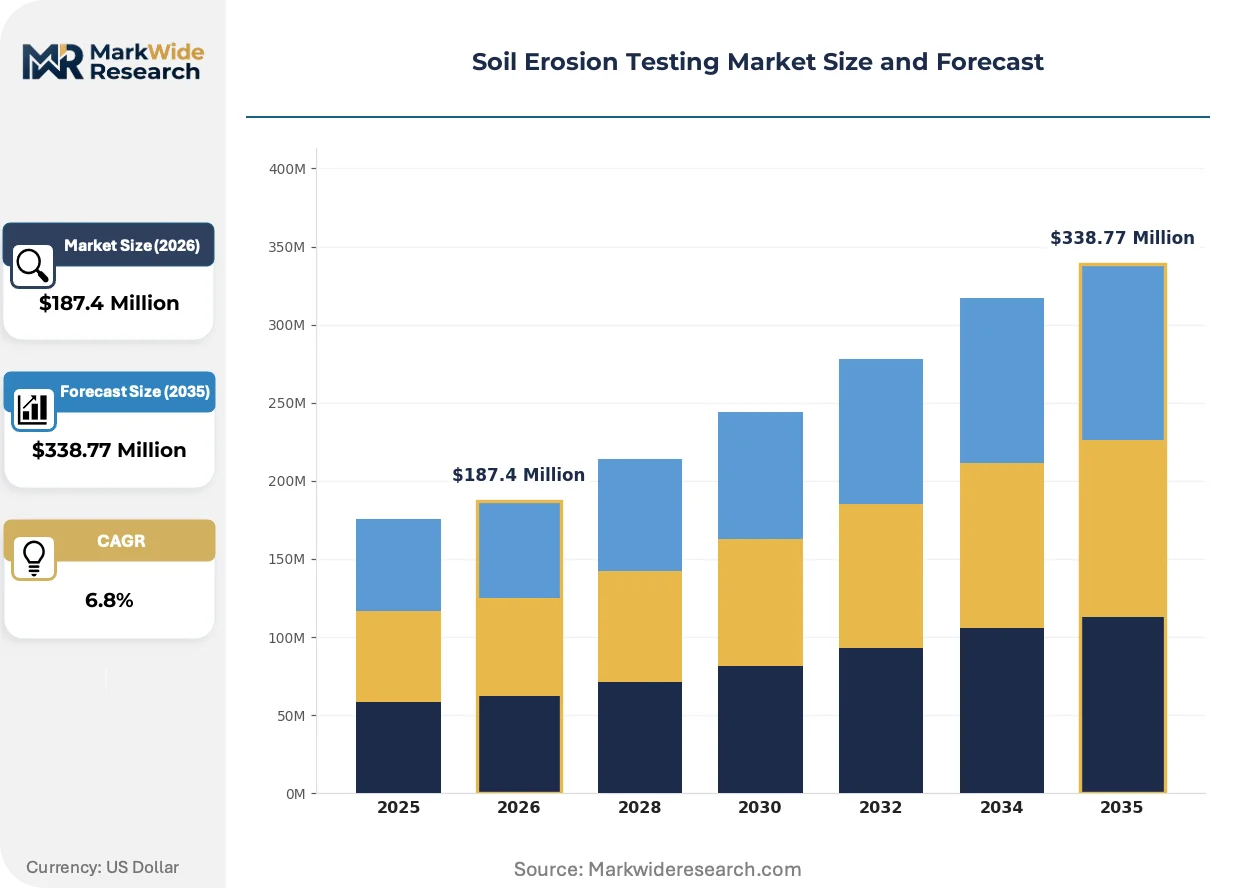
Market Dynamics
Regulatory digitization is compressing testing turnaround requirements while fragmenting procurement authority across state environmental agencies and private infrastructure consortia.
Growth Catalysts
- NPDES Permit Renewals:Infrastructure agencies across the United States face mandated sediment control verification ahead of permit deadlines, creating sustained demand for certified testing protocols.
- California Central Valley Concentration:Irrigation-intensive agriculture converges with seasonal flood risks in this corridor, driving concentrated procurement of real-time erosion monitoring systems.
- Remote Sensing Integration:Satellite-derived terrain modeling is displacing manual slope surveys, expanding addressable market for geospatial analytics providers.
Market Restraints
- Reference Standard Volatility:Laboratory-grade soil reference materials face supply concentration from limited certified producers, creating input cost instability for calibration-dependent services.
- Technical Throughput Ceilings:Rainfall simulation chambers require extended run times per sample, constraining volume scalability for high-precision erosion simulation applications.
- Cross-Border Protocol Friction:Divergent national adoption of ASTM D6460 versus ISO 14001 certification pathways creates compliance duplication costs for multi-jurisdiction projects.
Strategic Opportunities
- Construction Site Electrification:Portable electrochemical sensors enable real-time sediment monitoring without laboratory logistics, opening volume tiers among mid-sized contractors.
- State Digital Submission Mandates:Regulatory digitization of erosion control documentation creates channel control opportunities for testing providers with integrated data platforms.
- Agricultural Conservation Program Expansion:USDA-backed soil conservation initiatives fund volume-driven field kit deployment across erosion-prone watersheds.
Industry Challenges
- Geotechnical Technician Scarcity:Specialized expertise in Modified Universal Soil Loss Equation calibration remains concentrated among aging practitioner cohorts.
- Legacy Equipment Integration:Field-kit data streams require middleware development to interface with state environmental databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soil Erosion Testing Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Field Kits, Laboratory Equipment, Soil Test Kits, Erosion Control Products End Use Industry: Agriculture, Construction, Environmental Research, Land Management Technology: Remote Sensing, Soil Moisture Sensors, Geographical Information System, Erosion Simulation Application: Soil Conservation, Project Assessment, Environmental Impact Studies, Research Projects |
| Companies Covered | SGS, ALS Limited, TRI Environmental, ECS Engineering and Consulting Services, Teklab, GeoTesting Express, Ward Laboratories, ServiTech Laboratories, MVTL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soil Erosion Testing Market Evolving Landscape
Automation of sediment quantification workflows is collapsing the traditional latency between field sampling and regulatory submission, reshaping competitive advantage around data velocity rather than analytical precision alone.
Drone-mounted multispectral imaging is automating catchment-scale erosion assessment for highway corridor projects. State departments of transportation in erosion-prone regions now mandate pre-construction baseline surveys using these platforms. The technology is automating what previously required week-long ground crew deployments, compressing project mobilization timelines from days to hours.
The EPA's phased implementation of electronic NPDES reporting requirements is mandating machine-readable test result formats. Construction general permit holders must submit sediment control verification through standardized data schemas. Laboratory information management systems lacking API connectivity face exclusion from qualified vendor pools.
Consolidated procurement by infrastructure megaproject consortia is displacing fragmented site-by-site testing contracts. Engineering-procurement-construction firms now negotiate master service agreements covering multi-year sediment control verification across project portfolios. This concentration is most visible in California's high-speed rail and water infrastructure corridors.
Soil Erosion Testing Market Segmentation
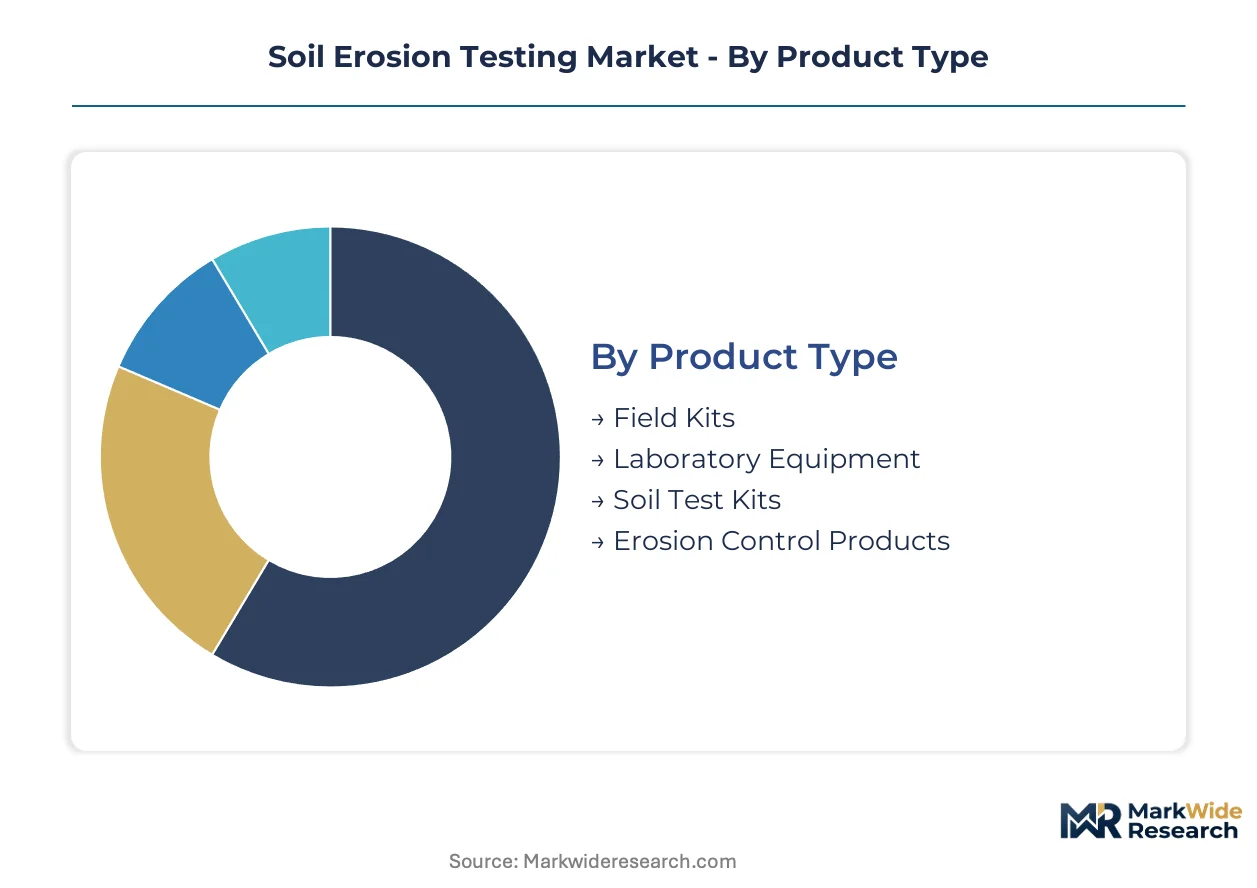
Segmentation in soil erosion testing reflects divergent procurement logics across precision-dependent certification workflows and volume-driven conservation programs. Testing providers must configure capabilities around whether clients prioritize analytical rigor for regulatory submission or operational speed for field deployment.
Product Type:
Customization intensity varies sharply across this category, from standardized field kits calibrated for USDA conservation programs to bespoke laboratory equipment requiring ASTM D6460 protocol alignment.
- Laboratory Equipment:Rainfall simulation chambers and flume-based sediment quantification systems deliver ASTM-certified precision for NPDES permit documentation. Demand concentrates among California infrastructure consortia where electronic reporting mandates require machine-readable calibration certificates.
- Field Kits:Portable electrochemical sensors and colorimetric test strips enable real-time sediment monitoring without laboratory logistics. Procurement is accelerating among mid-sized contractors in the Central Valley where mobilization speed determines bidding competitiveness.
- Soil Test Kits:Simplified diagnostic packages assess basic soil composition and erodibility indices for agricultural extension services.
- Erosion Control Products:Pre-qualified materials including geotextiles and sediment barriers requiring standardized performance validation.
Leading the category by volume: Field Kits. Growing fastest: Laboratory Equipment.
End Use Industry:
Cost tier stratification separates high-margin certification services for engineered infrastructure from thin-margin volume deployment across watershed conservation initiatives.
- Construction:Highway corridor projects and urban development drive demand for drone-mounted multispectral baseline surveys and sediment control verification. California's high-speed rail and water infrastructure megaprojects anchor procurement concentration through multi-year master service agreements.
- Agriculture:Irrigation-intensive operations in erosion-prone watersheds require continuous soil loss monitoring to maintain USDA conservation program eligibility. The Central Valley corridor generates concentrated demand for real-time sensor networks.
- Environmental Research:Academic and government research programs utilizing Modified Universal Soil Loss Equation calibration for methodology development.
- Land Management:Public and private land stewards implementing catchment-scale erosion assessment for resource planning.
Dominating procurement value: Construction. Expanding most quickly: Agriculture.
Technology:
Technology maturity spans established erosion simulation protocols and emerging satellite-derived terrain modeling disrupting manual survey methodologies.
- Remote Sensing:Satellite-derived digital elevation models and drone-mounted multispectral imaging automate catchment-scale assessment. State departments of transportation in erosion-prone regions now mandate pre-construction baseline surveys using these platforms, compressing mobilization timelines from days to hours.
- Erosion Simulation:Controlled rainfall intensity chambers and flume testing deliver ASTM D6460-compliant product qualification data. Premium pricing reflects extended run times per sample and specialized geotechnical technician requirements.
- Soil Moisture Sensors:In-situ probes supporting real-time irrigation management and erosion risk prediction in agricultural applications.
- Geographical Information System:Spatial analysis platforms integrating terrain, land cover, and hydrological data for watershed-scale modeling.
Highest revenue concentration: Erosion Simulation. Steepest expansion trajectory: Remote Sensing.
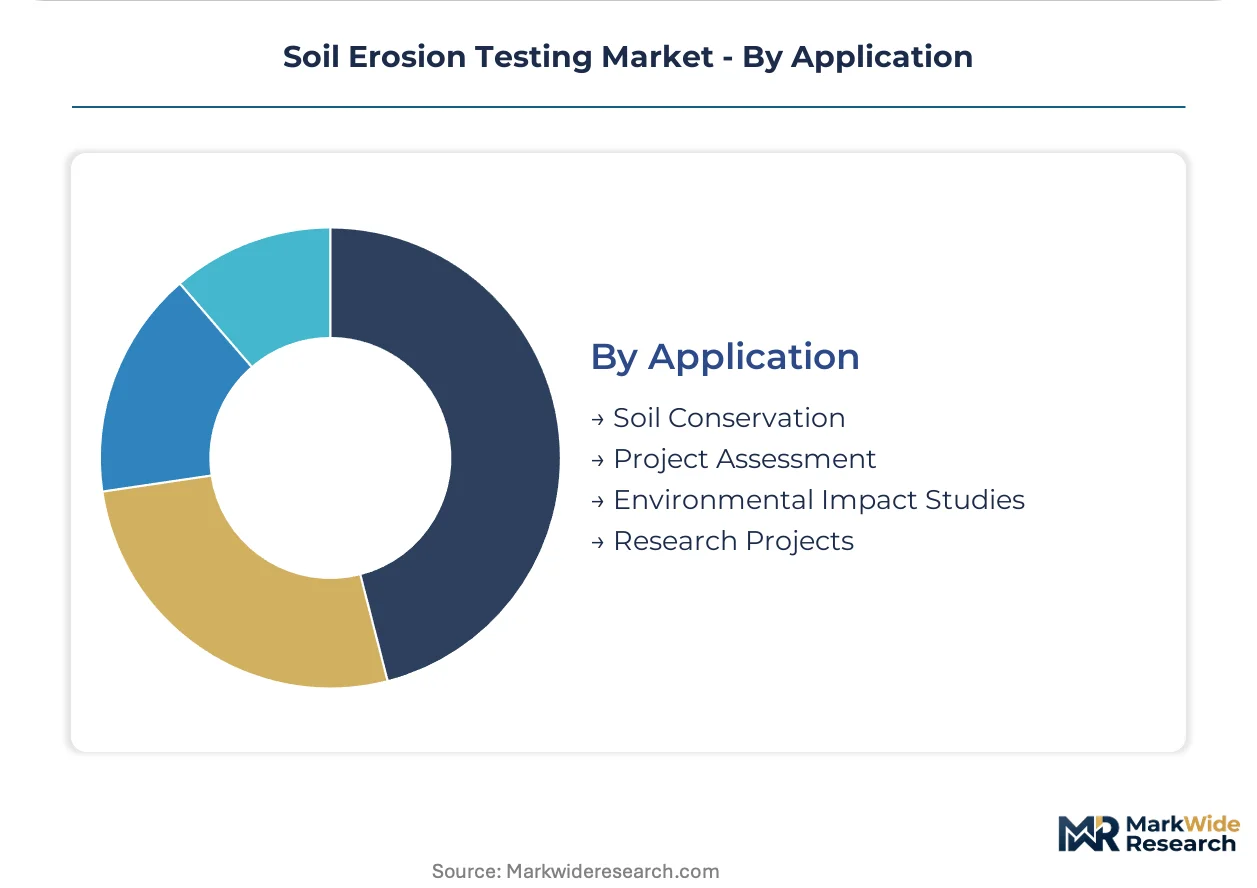
Application:
Application scope ranges from standardized soil conservation program compliance to bespoke environmental impact studies commanding premium analytical depth.
- Environmental Impact Studies:Comprehensive sediment detachment, transport, and deposition assessment for infrastructure permitting. EPA NPDES construction general permit requirements mandate verified testing protocols, creating sustained demand for certified laboratory services.
- Soil Conservation:USDA-backed initiatives fund volume-driven field kit deployment across erosion-prone watersheds. Program expansion is accelerating procurement of portable diagnostics among agricultural extension services.
- Project Assessment:Site-specific erosion risk evaluation supporting construction bidding and sediment control planning.
- Research Projects:Methodology development and protocol validation for academic and government research institutions.
Commanding premium pricing: Environmental Impact Studies. Scaling fastest: Soil Conservation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fresno anchors procurement concentration for real-time erosion monitoring systems, where irrigation-intensive agriculture converges with seasonal flood risks in California's Central Valley corridor.
United States
EPA NPDES construction general permit renewals drive sustained demand for certified sediment control verification across infrastructure megaprojects. The phased implementation of electronic reporting requirements mandates machine-readable test result formats. California's high-speed rail and water infrastructure corridors concentrate multi-year master service agreements among engineering-procurement-construction firms.
Germany
REACH compliance protocols and the EU Green Deal accelerate adoption of standardized erosion control product qualification pathways. The country's national environmental regulator enforces strict sediment management standards for linear infrastructure projects. The Rhine-Ruhr industrial belt generates concentrated procurement of laboratory-grade rainfall simulation equipment for environmental impact assessments.
China
Dual carbon goals and MEE watershed restoration mandates expand funding for catchment-scale erosion assessment across western provinces. GB standards alignment with ISO 14001 frameworks shapes cross-border project documentation requirements. The Yangtze River Delta concentrates deployment of drone-mounted multispectral imaging for pre-construction baseline surveys in highway corridor development.
Australia
Murray-Darling Basin conservation initiatives fund volume-driven field kit deployment across erosion-prone agricultural watersheds. The country's national environmental regulator mandates sediment control verification for mining and linear infrastructure permitting. Queensland and New South Wales anchor demand for portable electrochemical sensors among mid-sized contractors competing on mobilization speed.
Soil Erosion Testing Market Competitive Landscape
Capital-heavy laboratory networks compete with asset-light field-kit specialists for channel control in soil erosion testing. SGS leverages transcontinental certification infrastructure to anchor high-margin services for infrastructure megaprojects. Ward Laboratories and regional agricultural diagnostics providers compete on turnaround speed and geographic proximity. Consolidated procurement by engineering-procurement-construction consortia is displacing fragmented site-by-site contracts, while regulatory digitization favors providers with integrated data platform capabilities.
Within the transnational certification tier, SGS exemplifies laboratory network scale advantages for ASTM D6460-compliant product qualification. ALS Limited occupies a position among diversified testing conglomerates with environmental service line integration. Among regional agricultural diagnostics specialists, Ward Laboratories represents proximity-based competition models across the Great Plains belt. Teklab anchors the portable sensor archetype, extending real-time monitoring capabilities to construction site managers without laboratory logistics dependencies.
| Leading Market Players |
|---|
| SGS |
| ALS Limited |
| TRI Environmental |
| ECS Engineering and Consulting Services |
| Teklab |
| GeoTesting Express |
| Ward Laboratories |
| ServiTech Laboratories |
| MVTL |
| Others |
Value Network & Pricing Analysis
Engineering-procurement-construction consortia in California's Central Valley corridor anchor procurement volume for soil erosion testing services, compressing pricing power toward volume-tiered contract structures with multi-year master service agreements.
Pricing Analysis
Outcome-based pricing tied to NPDES permit approval timelines anchors premium tiers for laboratory-grade certification services. Three-tier pricing structure across premium, standard, and economy levels separates ASTM D6460-compliant product qualification from rapid-turnaround field diagnostics and commodity test strips. Cost compression in field-kit segments is intensifying because portable electrochemical sensor manufacturers compete on mobilization speed. Mid-sized contractors in agricultural watersheds exhibit highest price sensitivity, while infrastructure megaprojects prioritize analytical rigor over unit cost.
Supply Chain Analysis
Laboratory-grade soil reference materials rest on certified producers concentrated in the United States, Germany, and Japan. Rainfall simulation chambers, flume-based sediment quantification systems, and portable electrochemical sensors draw from precision manufacturing hubs with limited secondary sourcing. Single-source vulnerability in ASTM-certified reference standard supply creates calibration cost instability for high-precision services. Distribution runs through direct sales teams for laboratory equipment and agricultural extension networks for field-kit deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Soil erosion testing is becoming a vertical-integration race as providers pursue backward integration into portable sensor manufacturing to escape reference material cost volatility and capture field-kit margins.
For Market Incumbents: To counter regulatory digitization eroding channel control, SGS and ALS Limited should deepen API connectivity investments for laboratory information management systems and secure multi-year master service agreements with California infrastructure consortia before state digital submission mandates consolidate vendor pools.
For New Entrants and Emerging Players: Launch via agricultural extension service partnerships targeting USDA-backed soil conservation program deployment across erosion-prone watersheds in the Central Valley, where real-time sensor networks remain underpenetrated and procurement authority fragments across county-level conservation districts.
For Investors and Strategic Acquirers: The window for entry favors portable electrochemical sensor specialists with proven construction site deployment records, as regulatory digitization and electronic NPDES reporting requirements accelerate demand for machine-readable field data. Watch for state-level digital submission mandate announcements as the inflection signal for laboratory-network valuation compression.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Laboratory Platform Development | EPA electronic reporting mandates exclude non-integrated vendors from qualified pools. |
| Portable Sensor Manufacturing Integration | In-house production of electrochemical probes reduces calibration logistics dependencies. |
| Master Service Agreement Expansion | Multi-year California rail and water infrastructure contracts lock out competitors. |
| Agricultural Extension Network Partnership | USDA conservation program channels provide volume deployment without direct sales cost. |
| Drone-Mounted Multispectral Imaging Deployment | State transportation department mandates create captive demand for baseline survey services. |
Research Methodology
EPA enforcement databases, state environmental agency procurement records, and ASTM standards documentation formed the secondary backbone for this analysis. Primary interviews with geotechnical laboratory managers, construction site compliance officers, agricultural extension specialists, and NPDES permit consultants were combined with customs data on erosion control product imports and SEC filings from diversified testing conglomerates. Bottom-up and top-down triangulation validated segment-level revenue estimates against aggregate market sizing.
Bottom-up modeling built country-level projections from state-by-state permit renewal schedules and infrastructure project pipelines. Segmentation dimensions included product type, end-use industry, technology maturity, and application scope. CAGRs were derived from regression analysis of historical procurement volumes against regulatory milestone timing. Remote sensing adoption curves and rainfall simulation chamber utilization rates served as industry-specific forecast inputs across the projection horizon.
Regulatory implementation delays, reference standard supply disruptions, and geotechnical technician labor shortages are the dominant revision risks to these projections. Forecasts reflect documented assumptions about NPDES electronic reporting phase-in schedules and USDA conservation program funding continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Testing Services
Asia Pacific Feed Testing Market
Agricultural Testing Services
Testing, Inspection, and Certification for Agriculture & Food Market
Agricultural Testing Services
Soil Field Testing Equipment Market
Agricultural Testing Services
Global Agriculture Testing Services Market
Agricultural Testing Services
Animal Feed Testing Market
Agricultural Testing Services
Feed Testing Market
Agricultural Testing Services
Pesticide Detection Market
Agricultural Testing Services
Soil Testing Kit Market
Agricultural Testing Services
Plant Disease Diagnostic Market
Agricultural Testing Services
Plant Nutrient Testing Equipment Market
Agricultural Testing Services
Nematode Testing Services Market
Agricultural Testing Services
Europe Feed Testing Market
Agricultural Testing Services
Rapid Mycotoxin Detection Systems for Grain Handling Facilities Market
Agricultural Testing Services
Seed Testing Services Market
Agricultural Testing Services
Soil Sampling Services Market
Agricultural Testing Services
Impact Soil Tester Market