
 Agricultural Rake Market | 2026-2036
Agricultural Rake Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Rake Market Insights
Modular attachment configurations is shifting how hay producers evaluate rake purchases, with buyers preferring implements that integrate across multiple tractor brands rather than proprietary systems. John Deere leverages its dealer network density to sustain aftermarket attachment sales across North American farm belts. Kuhn Group anchors its position through specialized rotary and merger rake designs optimized for European grassland operations. AGCO Corporation competes by extending its implement portfolio through the Massey Ferguson and Fendt brand architectures.
An agricultural rake is a ground-driven or power-take-off implement with curved tines typically fabricated from spring steel or high-carbon alloys, designed to gather cut hay, straw, or crop residue into windrows for subsequent baling or collection. Tine spacing of 80-120 millimeters and working widths ranging from 3 to 15 meters determine throughput capacity and crop loss rates for commercial operators. Steel-tined variants dominate commercial hay operations where durability under abrasive soil conditions determines replacement economics, while aluminum and polymer materials occupy homeowner and nursery segments where weight reduction and corrosion resistance command premium positioning. Landscape professionals represent the fastest-growing end-user channel as municipal and golf-course maintenance contracts expand mechanized debris handling.
The US Department of Agriculture and EPA shape equipment demand through conservation compliance requirements tied to crop insurance eligibility, particularly residue management mandates in corn-soybean systems. REACH and CE marking obligations in Europe restrict surface coating chemistries and tine alloy compositions, elevating compliance costs for non-EU manufacturers. Stakeholders must monitor evolving carbon-accounting frameworks for agricultural machinery, as scope-three emissions disclosure requirements begin penetrating equipment procurement specifications.
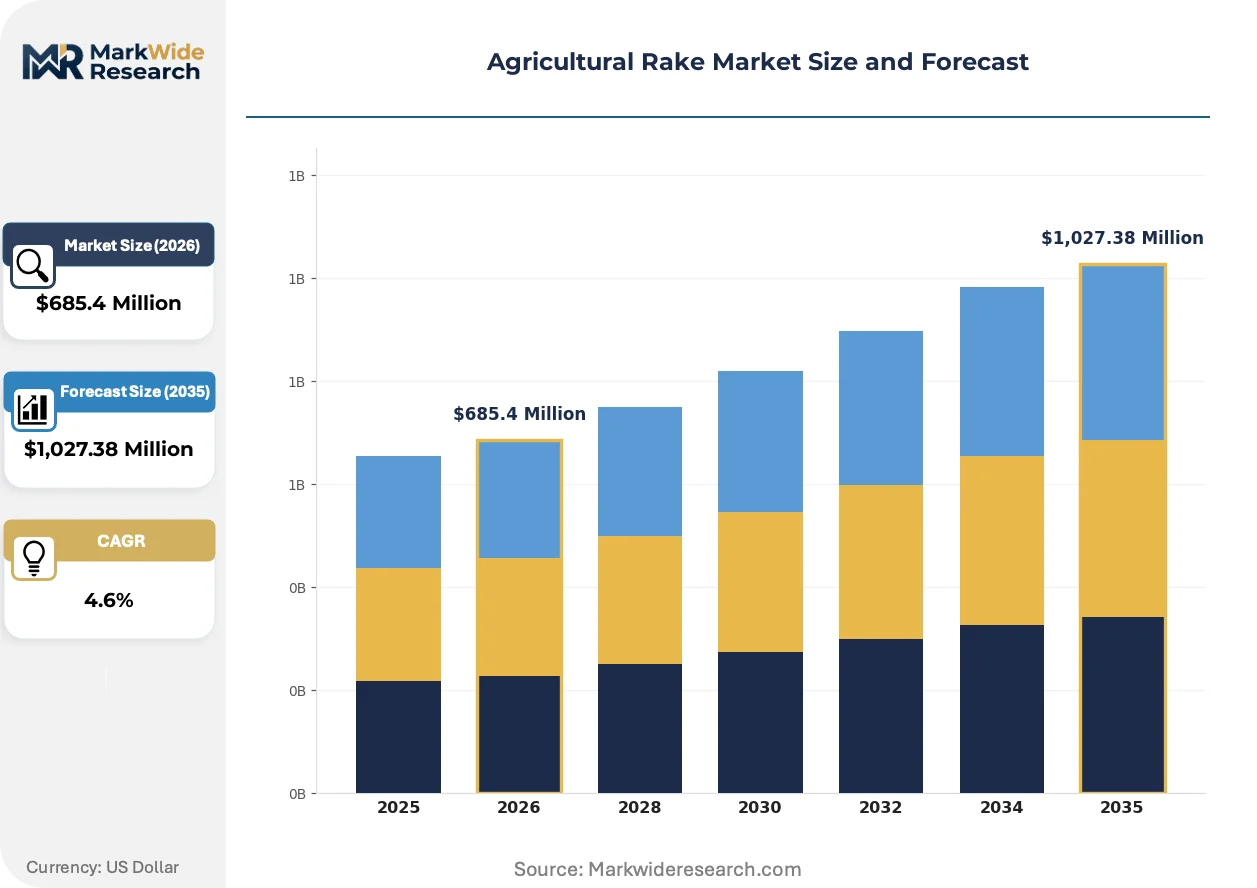
Market Dynamics
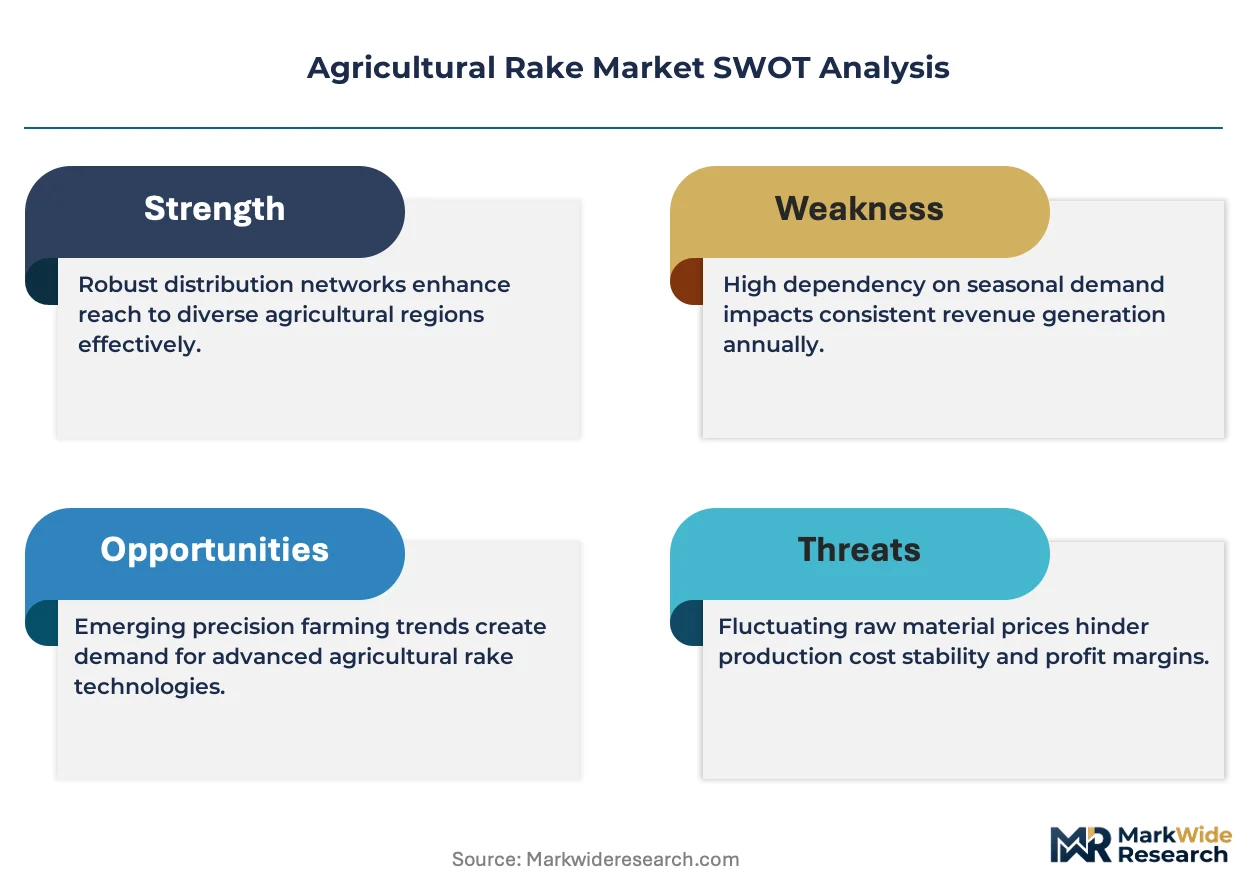
Modular attachment architectures are restructuring equipment procurement patterns across commercial hay operations, forcing manufacturers to abandon proprietary coupling systems in favor of cross-brand interoperability demanded by fleet-diversified buyers.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for high-GWP refrigerants in climate-controlled storage facilities are accelerating replacement cycles for residue management equipment tied to hay preservation infrastructure.
- Brazil's Mato Grosso corridor:Large-scale soybean-corn rotation systems generate substantial crop residue volumes requiring mechanized windrowing for no-till seedbed preparation.
- Spring steel tine advancement:High-carbon alloy formulations with enhanced abrasive wear resistance are extending service intervals for commercial operators in sandy soil regions.
Market Restraints
- Alloy input volatility:Spring steel and high-carbon tine feedstock prices fluctuate with scrap metal and coking coal markets, compressing margin predictability for fabricators.
- REACH compliance costs:European surface coating chemistry restrictions elevate certification expenses for non-EU manufacturers seeking CE marking access.
- PTO-driven alternatives:Merger rakes and rotary headers in hay-tooling portfolios cannibalize traditional wheel rake placements in high-throughput operations.
Strategic Opportunities
- Landscape professional channel:Municipal and golf-course maintenance contract expansion creates mechanized debris handling demand outside traditional agricultural buyers.
- USDA conservation compliance:Crop insurance eligibility tied to residue management mandates in corn-soybean systems subsidizes equipment acquisition for compliance-driven operators.
- Polymer-tine convergence:Glass-reinforced nylon formulations are integrating corrosion resistance with weight reduction for nursery and homeowner segments.
Industry Challenges
- Welding certification timelines:Pressure vessel and structural weld qualifications for tine attachment points delay production scaling for new market entrants.
- Legacy hydraulic integration:Proprietary tractor hydraulic protocols complicate universal attachment development across mixed-brand farm fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Rake Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,027.38 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Garden Rakes, Leaf Rakes, Bow Rakes, Cultivator Rakes Material: Steel, Aluminum, Wood, Plastic End User: Farmers, Landscape Professionals, Homeowners, Nurseries Distribution Channel: Online Retail, Direct Sales, Home Improvement Stores, Garden Centers |
| Companies Covered | John Deere, Kuhn Group, CNH Industrial, AGCO Corporation, CLAAS KGaA, Kubota Corporation, Vermeer Corporation, Pöttinger Landtechnik, Krone North America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Rake Market Trends and Innovations
Equipment intelligence and material science advances are reconfiguring rake performance benchmarks, with sensor integration and corrosion-resistant alloys displacing conventional mechanical designs in premium segments.
Variable-rate tine pressure control systems are integrating load-cell feedback and GPS-tagged terrain mapping to automate ground-following response across undulating fields. Commercial hay producers in the American Midwest are retrofitting existing implements with aftermarket kits at accelerating pace. This capability compression is integrating precision agriculture workflows into previously mechanical-only equipment categories.
REACH surface coating restrictions are prohibiting chromate conversion treatments and specific epoxy formulations historically used for tine corrosion protection. European manufacturers are pivoting toward zinc-nickel plating and ceramic-based alternatives to maintain CE marking eligibility. Non-EU fabricators face elevated third-party testing costs to demonstrate compliance with ECHA substance restrictions.
After-sales service unbundling is separating warranty maintenance from parts supply, with dealer networks now offering subscription-based tine replacement programs. Fleet operators with seasonal intensity are adopting consumption-based contracts over capital purchase models. This pattern concentrates most visibly in Australia's wheat-sheep zones where contractor services dominate hay logistics.
Agricultural Rake Market Segmentation
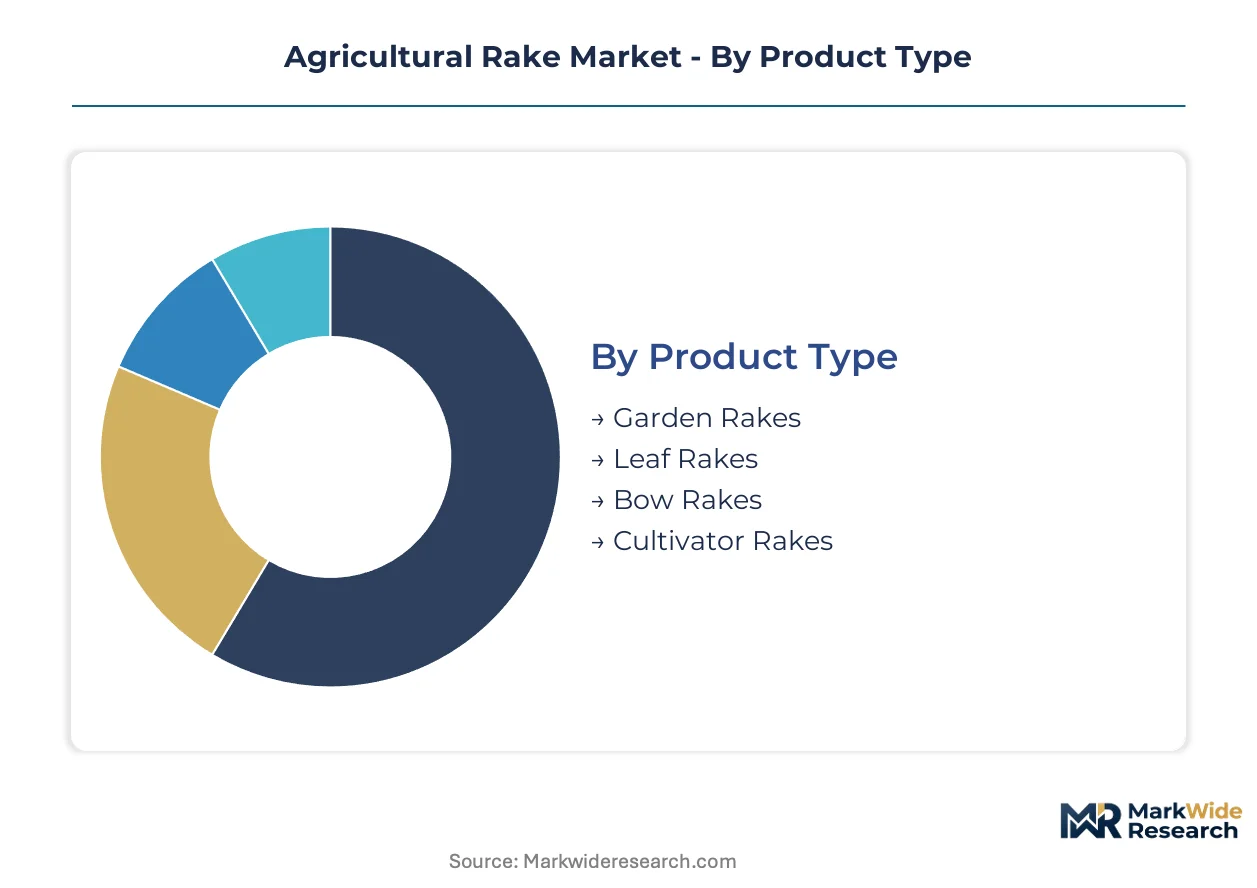
Equipment specification and user workflow requirements fragment the agricultural rake market into distinct procurement channels. Material selection and distribution access determine margin structures across commercial hay operations and consumer segments.
Product Type:
Garden rakes operate as standalone implements for soil preparation and debris collection, while bow and cultivator variants embed into broader tillage workflows.
- Garden Rakes:Flat steel or aluminum heads with short, sturdy tines penetrate compacted soil for seedbed preparation and rock removal. Demand clusters among vegetable producers in California's Central Valley where intensive cultivation cycles drive replacement frequency. Soil abrasion resistance determines tine alloy selection for commercial buyers.
- Leaf Rakes:Flexible plastic or bamboo tines with wide fan-shaped heads gather loose organic matter without turf damage. Landscape professionals in Florida's municipal maintenance sector specify polymer formulations for corrosion resistance in humid coastal conditions. Weight reduction enables extended operator use in large-scale debris clearing contracts.
- Bow Rakes:Rigid steel tines welded to curved structural frames provide leverage for grading and material spreading. Road maintenance crews in Texas county highway departments procure heavy-gauge variants for gravel redistribution.
- Cultivator Rakes:Narrow tine spacing and angled heads disrupt soil crusts around established crops. Organic vegetable cooperatives in Vermont specify adjustable-width models for between-row weed management.
Volume placements concentrate in Garden Rakes; the faster expansion belongs to Leaf Rakes.
Material:
Cost tier and durability expectations stratify raw material selection across end-use applications.
- Steel:High-carbon and spring steel alloys deliver abrasive wear resistance for commercial hay and tillage operations. Brazilian soybean-corn producers in Mato Grosso specify hardened tine formulations for residue management in sandy loam soils. Scrap metal price volatility compresses fabricator margins during commodity spikes.
- Aluminum:Weight reduction enables extended operator use without fatigue penalties. Golf course maintenance contractors in Arizona desert climates prioritize corrosion immunity from irrigation water exposure.
- Wood:Hickory and ash handles provide vibration dampening for manual raking tasks. Heritage garden tool retailers in Pacific Northwest urban markets command premium positioning for sustainably harvested variants.
- Plastic:Glass-reinforced nylon formulations integrate molded tine geometries at mass-market price points. Big-box lawn and garden seasonal displays in Midwest suburban corridors drive impulse purchase volume.
Steel commands the largest installed base; aluminum gains share fastest among professional channels.
End User:
Customer type determines specification complexity and service attachment rates.
- Farmers:Commercial hay and grain producers specify PTO-driven or heavy-duty ground-driven implements with replaceable tine components. USDA conservation compliance requirements in corn-soybean systems subsidize residue management equipment acquisition.
- Landscape Professionals:Municipal parks departments and golf course superintendents demand corrosion-resistant finishes and ergonomic handle designs for crew efficiency.
- Homeowners:Seasonal lawn maintenance drives collapsible and lightweight variant selection through retail channels.
- Nurseries:Container stock operations require precision tine spacing for root ball management without transplant damage.
Landscape professionals generate the steepest expansion trajectory; farmers retain the dominant volume position.
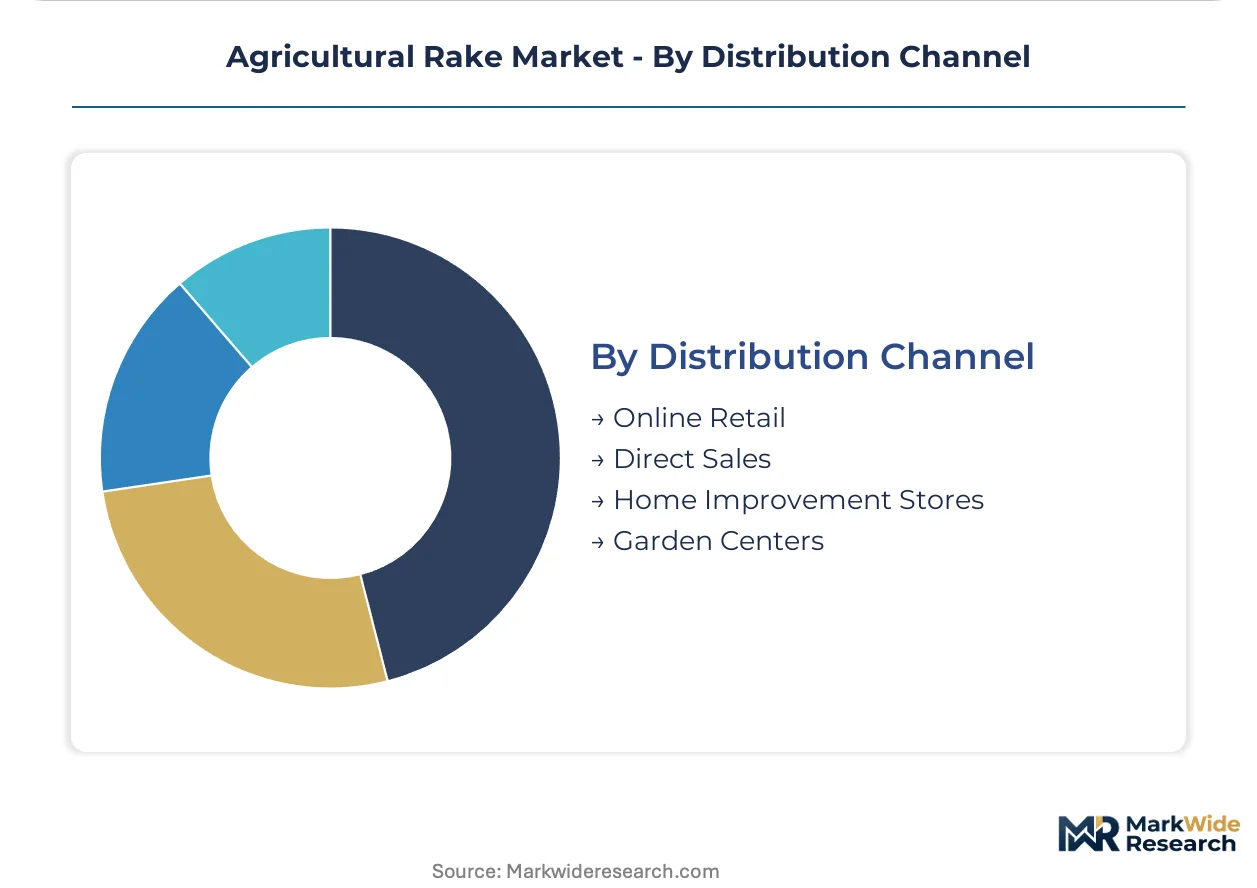
Distribution Channel:
Supply chain configuration determines geographic reach and after-sales service attachment.
- Online Retail:E-commerce platforms enable specification comparison and bulk procurement for fleet operators. Australian contractor services in wheat-sheep zones utilize digital channels for seasonal tine replacement inventory.
- Direct Sales:Manufacturer field representatives configure custom implement widths and hitch geometries for large-scale hay operations. Dealer network density in Iowa and Nebraska sustains John Deere's aftermarket attachment dominance.
- Home Improvement Stores:Mass-market retailers drive consumer segment volume through seasonal promotional cycles.
- Garden Centers:Independent retailers provide hands-on evaluation for homeowner quality-tier selection.
Direct sales capture the highest-value transactions; online retail expands most quickly among professional buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of agricultural rakes concentrates in Germany and the United States, while consumption gravity shifts toward Brazil and Australia's contractor-heavy agricultural belts. European fabricators export specialized hay tooling to North American and Latin American buyers, creating a trade flow shaped by regulatory compliance costs and seasonal demand cycles.
United States
Commercial hay producers in Iowa and Nebraska drive replacement demand for PTO-driven wheel rakes and merger attachments. The USDA ties crop insurance eligibility to residue management compliance, subsidizing equipment acquisition for corn-soybean operators. John Deere's dealer network density across the Midwest sustains aftermarket parts and attachment sales.
Brazil
Soybean-corn rotation systems in Mato Grosso generate substantial crop residue volumes requiring mechanized windrowing for no-till seedbed preparation. ANVISA oversees agricultural equipment safety certifications for imported implements. Large-scale farming cooperatives in the Cerrado agricultural corridor consolidate procurement for high-throughput rotary rake systems.
Germany
Specialized grassland operations in Bavaria and Lower Saxony specify precision merger rakes optimized for European haymaking workflows. The EU F-Gas Regulation and Machinery Directive reshape compliance requirements for surface coatings and hydraulic systems. CLAAS KGaA anchors production in Harsewinkel, exporting configured implements to EU member states and Eastern European buyers.
Australia
Contractor services in New South Wales and Victoria's wheat-sheep zones dominate hay logistics, driving demand for subscription-based tine replacement programs. The TGA's equipment safety framework intersects with state-level agricultural machinery regulations. Seasonal intensity in the Murray-Darling Basin pushes fleet operators toward consumption-based contracts over capital purchases.
France
Pasture-based dairy systems in Normandy and Brittany sustain demand for rotary and tedder-rake combinations. REACH restrictions on chromate conversion treatments elevate third-party testing costs for non-EU manufacturers seeking CE marking. Kuhn Group's production facilities in Saverne supply configured implements optimized for Atlantic climate grassland operations.
Agricultural Rake Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the agricultural rake market, creating a tiered structure where scale advantages clash with customization agility. The vendor base separates into three archetypes: full-line agricultural equipment manufacturers, specialized hay-tooling fabricators, and regional attachment producers serving local fleet operators. Consolidation pressure intensifies as modular attachment standards force proprietary system abandonment, while geographic expansion and strategic partnerships emerge as dominant competitive moves for accessing fleet-diversified buyers.
Among full-line manufacturers, John Deere exemplifies the diversified conglomerate archetype through its extensive dealer network infrastructure, while Kuhn Group represents the specialized European fabricator focused on grassland equipment optimization. AGCO Corporation occupies a position bridging both categories through its multi-brand portfolio architecture. These three anchors demonstrate how competitive positioning stratifies across scale-driven distribution density, technical specialization depth, and brand portfolio breadth.
| Leading Market Players |
|---|
| John Deere |
| Kuhn Group |
| CNH Industrial |
| AGCO Corporation |
| CLAAS KGaA |
| Kubota Corporation |
| Vermeer Corporation |
| Pöttinger Landtechnik |
| Krone North America |
| Others |
Pricing and Supply Chain Analysis
Variable-rate tine pressure control systems integrating load-cell feedback and GPS-tagged terrain mapping are simultaneously elevating R&D amortization burdens for premium-tier manufacturers and compressing margins for mechanical-only fabricators unable to retrofit legacy implements. This technology transition concentrates pricing power among sensor-integrated equipment suppliers while forcing commodity producers toward volume-scaled production economics to survive alloy input volatility.
Pricing Analysis
Margin tightening in standard-tier wheel rakes reflects scrap metal and coking coal price volatility compressing fabricator returns on spring steel tine production. Three-tier pricing structure across premium sensor-integrated, standard mechanical, and economy polymer-tine levels separates precision agriculture adopters from compliance-driven commodity buyers and seasonal homeowners. Pricing pressure stems from REACH-compliant surface coating chemistry substitutions elevating European certification costs for non-EU manufacturers. Landscape professionals exhibit lowest price sensitivity due to municipal contract pass-through mechanisms, while homeowner segments demand mass-market retail positioning.
Supply Chain Analysis
Dual-sourcing mandates from fleet-diversified hay contractors in Iowa and Nebraska are forcing tine attachment point fabricators to qualify secondary spring steel suppliers beyond traditional German and Japanese specialty alloy mills. Raw material dependencies center on high-carbon steel formulations, zinc-nickel plating chemistries, and glass-reinforced nylon polymer feedstocks. Supply chain risk concentrates in single-source vulnerability for precision-machined hydraulic coupling components proprietary to major tractor OEMs. Distribution runs through John Deere's dealer network density across the American Midwest, supplemented by direct sales configurations for large-scale Mato Grosso farming cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-integrated precision agriculture workflows are displacing purely mechanical rake architectures, creating asymmetric consolidation pressure across equipment tiers and restructuring viable competitive positioning for legacy fabricators.
For Market Incumbents: To counter merger rake and rotary header cannibalization of traditional wheel rake placements, prioritize backward integration into spring steel tine forging capacity to capture alloy margin compression and secure supply continuity. Invest in CE marking pre-certification for zinc-nickel plating alternatives ahead of chromate conversion phase-outs under REACH restrictions. For New Entrants and Emerging Players: Begin with polymer-tine convergence for nursery and golf-course maintenance segments where corrosion resistance and weight reduction command premium positioning absent entrenched dealer relationships. Target Australia's wheat-sheep contractor services through subscription-based tine replacement programs that bypass capital purchase barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by full-line agricultural equipment manufacturers seeking modular attachment interoperability capabilities. Five-to-ten year viability favors specialized grassland equipment fabricators with established ANVISA certification pathways for Brazilian market access. Monitor USDA conservation compliance rulemaking as inflection signal for residue management equipment subsidy expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Integration Partnership | Load-cell and GPS module sourcing agreements accelerate precision agriculture retrofit kit deployment. |
| REACH-Compliant Coating Transition | Zinc-nickel plating investment maintains CE marking eligibility for European hay tooling exports. |
| Dealer Network Density Expansion | Iowa and Nebraska service point additions sustain aftermarket attachment sales against direct competitors. |
| Subscription Service Launch | Consumption-based tine replacement contracts penetrate Australia's seasonal contractor services segment. |
| Brazilian Certification Pathway | ANVISA safety approval unlocks Mato Grosso soybean-corn residue management equipment procurement. |
Research Methodology
Independent corroboration across hay producer equipment managers, agricultural implement dealer principals, and specialty alloy procurement leads underwrites the qualitative findings on tine replacement economics and fleet standardization preferences. Secondary validation draws from USDA conservation compliance documentation, ANVISA equipment safety filings, and ECHA substance restriction updates. Bottom-up segmentation modeling triangulates against top-down trade flow analysis for German and American fabrication exports.
Comparable-period anchoring to historical replacement cycle data across corn-soybean and wheat-sheep production systems structures the projection horizon. Segmentation dimensions span product type, material composition, end-user archetype, and distribution channel, with precision agriculture integration intensity as an industry-specific overlay. CAGRs derive from equipment stock depreciation curves and conservation compliance subsidy elasticity estimates, incorporating spring steel price index trajectories and dealer network coverage density as forecast inputs.
Alloy input volatility, regulatory restriction expansion, and precision agriculture adoption velocity are the dominant revision risks to the outlook. Deviation in USDA residue management mandate enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Agricultural Pumps Market
Agricultural Equipment
Pond Aeration System Market
Agricultural Equipment
Fishing Net Market
Agricultural Equipment
Indoor Farming Equipment Market
Agricultural Equipment
Global Grain Bin Management Solution Market
Agricultural Equipment
Bird Scarer and Repellent Market
Agricultural Equipment
Intelligent Milking Robot Market
Agricultural Equipment
Stock Tanks Market
Agricultural Equipment
Floating Covers Market
Agricultural Equipment
Global Fishing Equipments Market
Agricultural Equipment
Battery Powered Cultivators Market
Agricultural Equipment
Pistol Grip Sprayer Market
Agricultural Equipment
OWD Moisture Meter Market
Agricultural Equipment
Agriculture Evaporative Cooling Pad Market
Agricultural Equipment
Cotton Picker Market
Agricultural Equipment
Irrigation Syringe Market