
 Plant Nutrient Testing Equipment Market | 2026-2036
Plant Nutrient Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Nutrient Testing Equipment Market Analytics
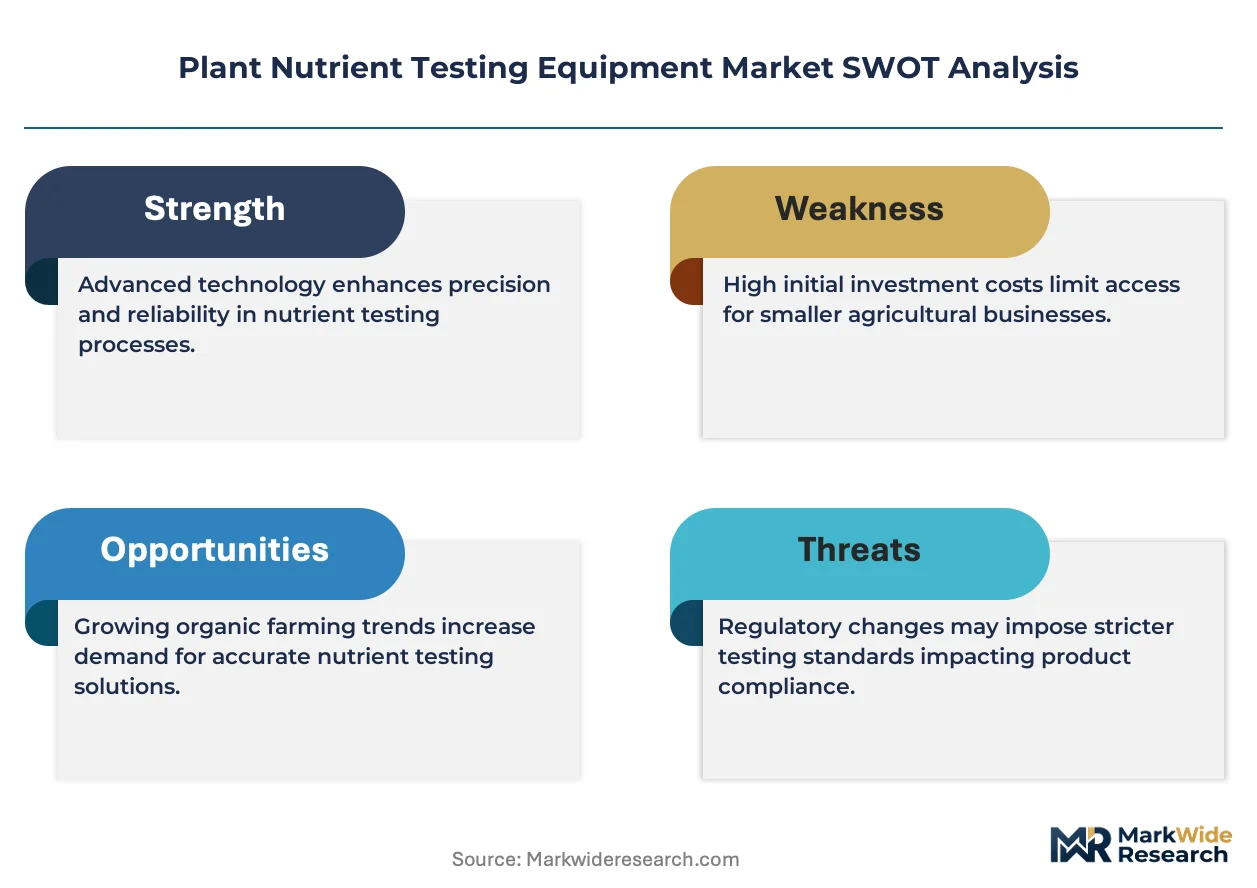
The gap between laboratory-grade spectroscopy systems and handheld colorimetric field kits is repositioning how equipment vendors structure their portfolios. Thermo Fisher Scientific leverages its mass spectrometry depth to anchor the high-throughput laboratory analyzer tier for research institutions and regulatory compliance labs. Hanna Instruments competes through dense distribution of portable meters calibrated for on-farm ion selective electrode readings, while LaMotte Company specializes in simplified soil test kits priced for agricultural consultants serving mid-size growers.
Plant nutrient testing equipment encompasses instruments that quantify nitrogen, phosphorus, potassium, and micronutrient concentrations in soil, water, and plant tissue matrices, typically achieving detection limits below one part per million through spectroscopic or electrochemical methods. These systems enable agronomists and growers to formulate precision fertilization protocols that optimize crop yield while minimizing environmental nutrient loading. Laboratory analyzers utilizing atomic absorption or inductively coupled plasma spectroscopy dominate margin pools in the research and environmental testing application segments, whereas portable meters with Bluetooth data logging represent the fastest-growing technology category as farmers shift from calendar-based to sensor-driven nutrient management. The agriculture end user segment sustains the largest volume base, though government agencies are expanding procurement for watershed monitoring programs.
The EPA enforces Clean Water Act nutrient criteria that mandate documented testing for agricultural discharge permits, directly stimulating demand for validated laboratory analyzers and certified portable meters. In parallel, the EU Green Deal's soil health monitoring requirements and REACH chemical registration standards shape product design specifications for equipment sold into European research institutions. Stakeholders must weigh capital intensity against the operational flexibility of subscription-based calibration and cloud analytics services as the installed base diversifies across farm sizes and regulatory jurisdictions.
Market Dynamics
Precision agriculture adoption is compressing the traditional divide between laboratory-grade analyzers and portable field meters, forcing vendors to recalibrate their product architectures around sensor miniaturization and cloud-connected data workflows.
Growth Catalysts
- EU Green Deal soil mandates:The EU's Farm to Fork Strategy tightens nutrient runoff limits and mandates soil health monitoring, directly accelerating procurement of validated testing equipment across European research institutions and commercial farms.
- EPA discharge permitting:Clean Water Act nutrient criteria enforcement requires documented testing for agricultural discharge permits, stimulating demand for certified portable meters and laboratory analyzers in watershed monitoring applications.
- Large-scale commercial farming:Precision agriculture adoption among industrial farming operations is accelerating capital deployment into ion-selective electrode systems and spectroscopic analyzers for real-time nutrient management.
Market Restraints
- Optical component supply concentration:German and Japanese suppliers dominate high-precision spectrophotometer source components, creating input bottlenecks for mid-tier analyzer manufacturers.
- Calibration consumable cost structure:Certified reference materials and reagent cartridges for atomic absorption systems impose recurring operational burdens that compress margins for smaller testing laboratories.
- Inductively coupled plasma technical barriers:ICP-MS systems require argon gas supply infrastructure and specialized operator training, limiting deployment flexibility outside centralized research facilities.
Strategic Opportunities
- Brazilian agricultural expansion:Soybean and sugarcane intensification in Mato Grosso and São Paulo states creates underpenetrated demand for portable nitrate and phosphate testing kits calibrated for tropical soil matrices.
- Drone-mounted hyperspectral sensors:Convergence of unmanned aerial platforms with push-broom spectroscopy enables non-destructive canopy nutrient mapping, opening subscription-based analytics services for agronomic consultancies.
- India PLI scheme alignment:Production-linked incentives for precision agriculture equipment manufacturing attract domestic assembly of electrochemical sensor modules, reducing landed costs for South Asian distributors.
Industry Challenges
- Spectroscopy technician scarcity:Atomic absorption and ICP-MS operation requires specialized analytical chemistry training that agricultural extension services struggle to staff in rural deployment zones.
- Multi-vendor data integration:Proprietary Bluetooth protocols and cloud platforms from competing meter manufacturers fragment farm management software compatibility, complicating enterprise-scale nutrient monitoring rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Nutrient Testing Equipment Market |
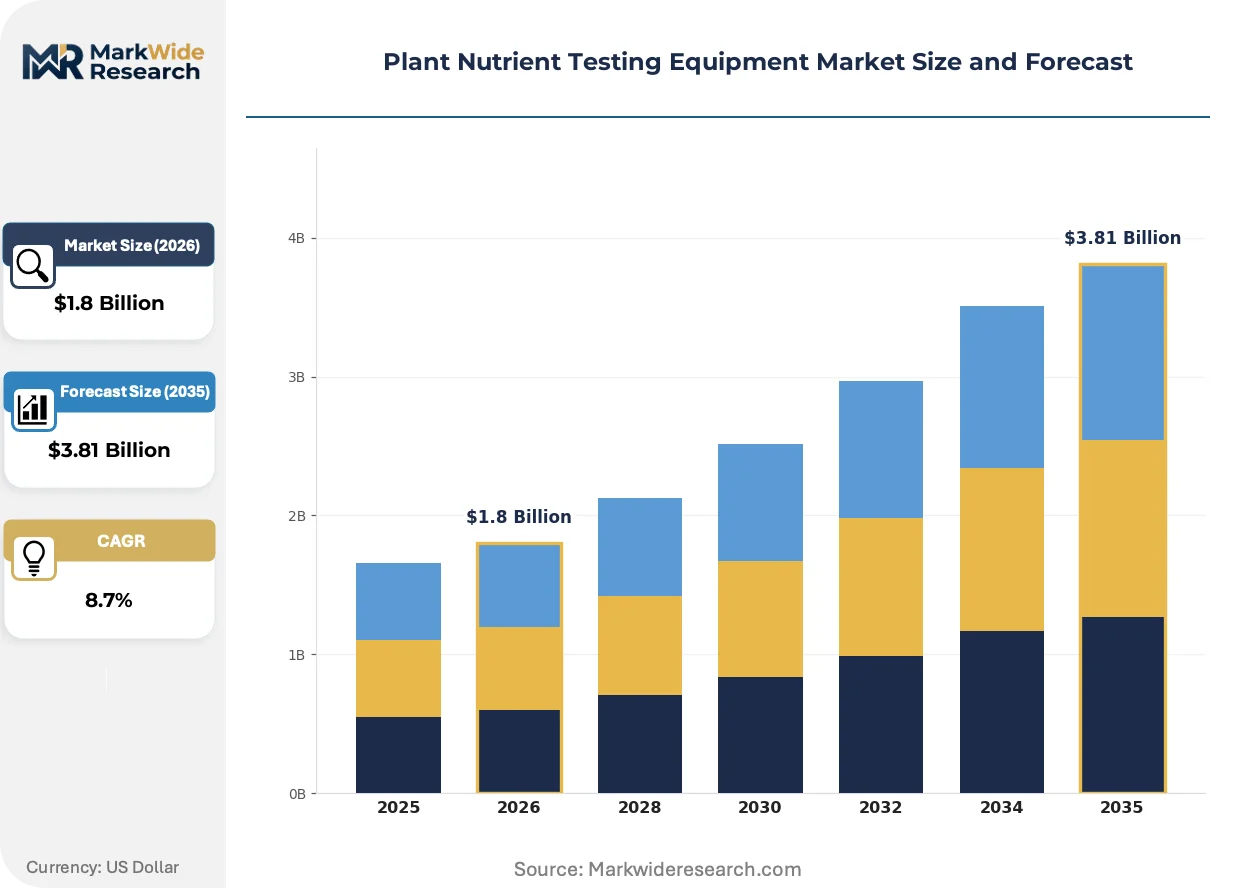
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soil Test Kits, Water Test Kits, Laboratory Analyzers, Portable Meters Application: Agriculture, Research, Gardening, Environmental Testing End User: Farmers, Agricultural Consultants, Research Institutions, Government Agencies Technology: Colorimetric Analysis, Photometric, Ion Selective Electrodes, Spectroscopy |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Horiba Ltd., PerkinElmer, Shimadzu Corporation, LaMotte Company, Merck KGaA, Hanna Instruments, FOSS Analytical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Nutrient Testing Equipment Market Evolving Landscape
Sensor fusion and edge computing are redefining how nutrient data flows from field to decision system, collapsing the latency between soil sampling and fertilization prescription.
MEMS-based ion-selective electrode arrays are modularizing portable meter architectures, enabling swappable sensor cartridges for nitrogen, phosphorus, and potassium detection within single handheld units. Mid-size agronomic consultancies in Germany and the Netherlands are adopting these systems at pace, replacing discrete single-parameter meters. The technology is modularizing vendor service models toward subscription-based calibration and cloud analytics rather than capital equipment sales.
REACH chemical registration standards are tightening specifications for reagent formulations used in colorimetric soil test kits, forcing reformulation of legacy phosphate and nitrate detection chemistries. Equipment suppliers must resubmit technical dossiers to ECHA for modified reagent compositions, extending product launch timelines. Laboratory analyzer segments serving European environmental compliance labs are absorbing the largest compliance burden through accelerated R&D cycles.
Sensor-as-a-service contracting is displacing outright equipment purchases among North American cooperative extension networks and large integrated growers. Leasing arrangements bundle hardware, calibration, and cloud data storage into per-acre pricing, transferring obsolescence risk from farm operators to equipment vendors. This model is most visible in California's Central Valley specialty crop operations and Midwestern corn-soybean rotations where capital discipline constrains upfront analyzer investment.
Plant Nutrient Testing Equipment Market Segmentation
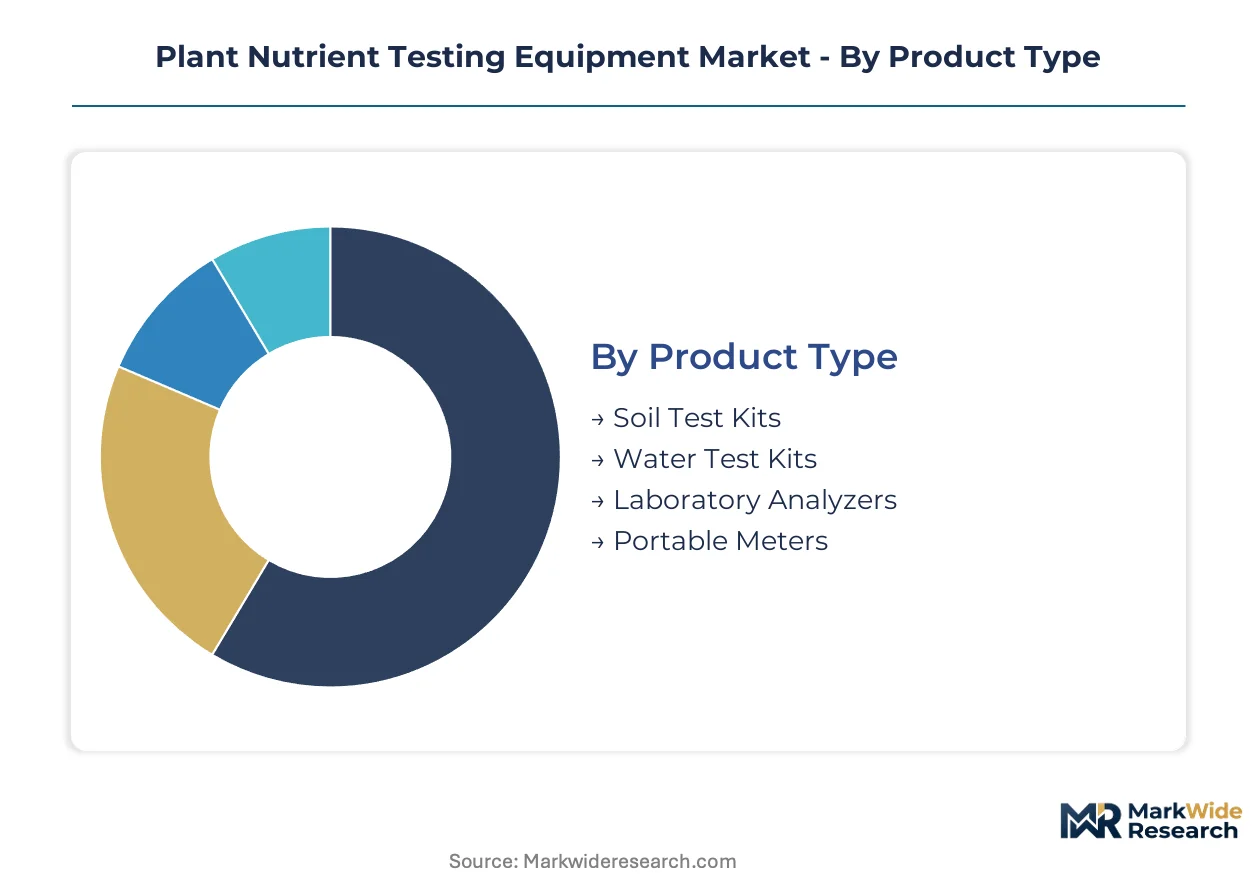
Equipment architecture in plant nutrient testing diverges sharply across use contexts, with laboratory-grade precision commanding premium positioning against field-deployable simplicity. Vendors structure portfolios around detection method, mobility constraints, and end-user analytical sophistication rather than uniform feature scaling.
Product Type:
Detection precision and capital intensity define the product hierarchy, with spectroscopic systems anchoring the high-value tier and colorimetric kits penetrating cost-sensitive deployment zones.
- Laboratory Analyzers:Atomic absorption and inductively coupled plasma systems achieve sub-ppm detection limits for regulatory compliance and research-grade validation. Demand concentrates in Germany's dense agricultural research clusters, where federal precision agriculture subsidies offset capital expenditure for institutional procurement.
- Portable Meters:Handheld units with Bluetooth data logging and ion-selective electrode modules enable real-time field decision-making. Adoption is accelerating among large-scale commercial farming operations in the US Corn Belt and São Paulo state soybean districts, driven by subscription-based sensor-as-a-service contracting that transfers obsolescence risk to vendors.
- Soil Test Kits:Simplified colorimetric reagent systems deliver rapid macronutrient screening without instrumental infrastructure. Agricultural consultants serving mid-size growers in India and Brazil deploy these for preliminary site assessment before laboratory confirmation.
- Water Test Kits:Specialized nitrate and phosphate detection chemistries target irrigation water and runoff monitoring. EPA Clean Water Act discharge permitting mandates directly stimulate procurement for watershed compliance documentation.
Mature deployment sits with Laboratory Analyzers in European environmental compliance labs. Newer deployment is concentrated in Portable Meters among North American cooperative extension networks.
Application:
Regulatory stringency and data precision requirements segment demand across use cases, with environmental compliance absorbing the highest analytical burden and gardening representing the most price-elastic entry point.
- Agriculture:Precision fertilization protocols require validated nitrogen, phosphorus, and potassium quantification across soil, tissue, and water matrices. Germany's Farm to Fork Strategy implementation and US Midwestern variable-rate application adoption are expanding procurement of certified portable meters and drone-mounted hyperspectral systems.
- Research:Academic and institutional laboratories demand trace-level micronutrient detection and method standardization for publication-grade reproducibility. REACH chemical registration standards in Europe are forcing reformulation of legacy reagent compositions, extending product launch timelines for equipment suppliers.
- Environmental Testing:Watershed monitoring and discharge permitting require documented chain-of-custody protocols and regulatory-grade validation. Government agencies in the US and EU are expanding procurement for riparian zone nutrient loading assessment.
- Gardening:Consumer-grade pH and macronutrient screening represents a volume-driven, low-margin category with minimal calibration requirements. Hobbyist demand shows seasonal concentration in North American and European spring planting periods.
Environmental Testing applications carry the steepest compliance-driven expansion trajectory. Gardening remains the most fragmented and price-sensitive application layer.
End User:
Capital availability and technical staffing depth determine equipment selection, with institutional buyers prioritizing analytical throughput and individual operators favoring operational simplicity.
- Farmers:Owner-operators and integrated growing enterprises balance capital discipline against yield optimization potential. California Central Valley specialty crop operations and Midwestern corn-soybean rotations are adopting per-acre sensor-as-a-service leasing to circumvent upfront analyzer investment.
- Research Institutions:Universities and government agricultural stations require multi-element capability and method flexibility for experimental design. EU Green Deal soil health monitoring mandates are accelerating analyzer procurement across German, Dutch, and French institutional networks.
- Agricultural Consultants:Independent agronomists and cooperative extension services need rapid turnaround for client recommendations. Mid-size consultancies in Germany and the Netherlands are replacing discrete single-parameter meters with modular MEMS-based ion-selective electrode arrays.
- Government Agencies:Environmental regulators and watershed authorities enforce compliance through standardized testing protocols. EPA nutrient criteria enforcement and EU Farm to Fork Strategy implementation are expanding procurement for certified field and laboratory systems.
Research Institutions anchor the high-value installed base. Government Agencies are gaining share fastest through regulatory mandate expansion.
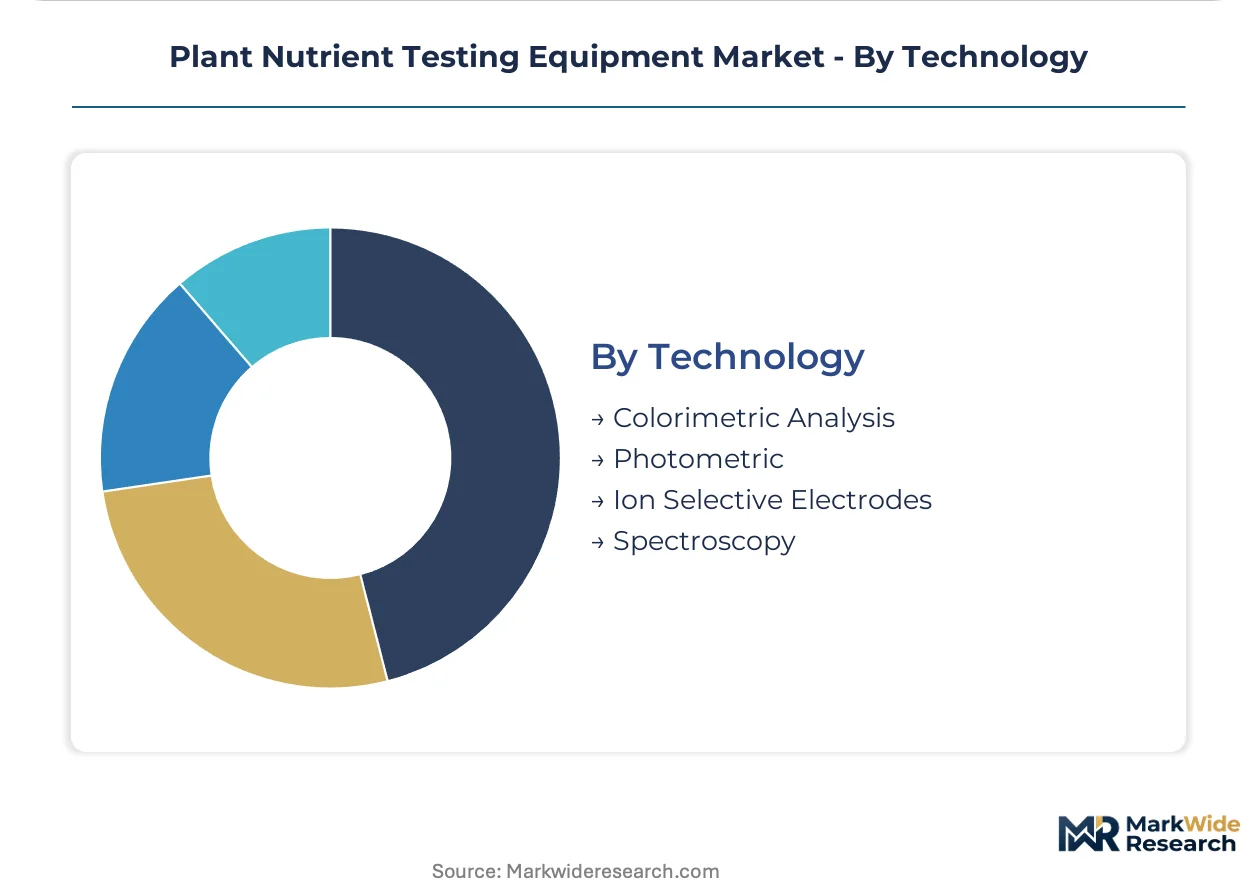
Technology:
Detection physics and component miniaturization trajectories are compressing the traditional performance gap between laboratory and field systems, forcing vendor recalibration around sensor fusion architectures.
- Spectroscopy:Atomic absorption and inductively coupled plasma systems deliver elemental quantification at trace concentrations for regulatory and research applications. Argon gas infrastructure requirements and specialized operator training limit deployment flexibility outside centralized facilities.
- Ion Selective Electrodes:Electrochemical sensors with solid-state membranes enable selective ion detection in handheld form factors. MEMS-based array modularization is enabling swappable nitrogen, phosphorus, and potassium cartridges within single units.
- Colorimetric Analysis:Reagent-based visual or photometric detection provides low-cost screening without instrumental complexity. REACH standards are tightening specifications for phosphate and nitrate detection chemistries, forcing European market reformulation.
- Photometric:Filter-based absorbance measurement bridges the gap between visual colorimetry and full spectroscopy for mid-tier laboratory applications. Brazilian and Indian distributors are absorbing growing volumes for tropical soil matrix calibration.
Spectroscopy commands the highest analytical tier. Ion Selective Electrodes are climbing the fastest through sensor miniaturization and cloud connectivity integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich's agricultural research corridor anchors European demand for laboratory-grade analyzers, while São Paulo's soybean belt and California's Central Valley drive portable meter adoption through precision agriculture contracting models.
Germany
Federal precision agriculture subsidies and dense research clusters in Bavaria and North Rhine-Westphalia accelerate laboratory analyzer procurement. The EU Green Deal's Farm to Fork Strategy mandates soil health monitoring, tightening nutrient runoff limits for commercial operations. Equipment vendors concentrate calibration service networks around the Munich-Stuttgart research axis.
United States
Midwestern corn-soybean rotations and California specialty crop operations adopt sensor-as-a-service leasing to bypass capital expenditure constraints. EPA Clean Water Act nutrient criteria enforcement requires documented testing for agricultural discharge permits across watershed monitoring programs. Procurement concentrates in Iowa, Illinois, and the Central Valley where cooperative extension networks scale deployment.
Brazil
Soybean intensification in Mato Grosso and sugarcane expansion in São Paulo states generate underpenetrated demand for tropical-calibrated portable testing kits. Federal agricultural modernization programs subsidize precision equipment for large integrated growers. Distributors cluster in Campinas and Ribeirão Preto to serve the southeastern agricultural corridor.
India
Production-linked incentives for precision agriculture equipment manufacturing attract domestic assembly of electrochemical sensor modules. The PLI scheme reduces landed costs for South Asian distributors serving Punjab and Haryana wheat-rice systems. State agricultural universities in Karnataka and Maharashtra anchor demand for research-grade photometric systems.
Netherlands
Glasshouse horticulture concentration in Westland and high-value bulb farming in North Holland drive ion-selective electrode adoption for real-time fertigation control. EU REACH chemical registration standards shape reagent specifications for colorimetric kits used in environmental compliance labs. Wageningen University's research network validates new sensor technologies before commercial scale-up.
Plant Nutrient Testing Equipment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across detection precision and calibration service depth, with laboratory-grade spectroscopy systems commanding substantially higher lifetime value than handheld field kits. The vendor base stratifies into three tiers: multinational analytical instrument conglomerates with mass spectrometry depth, specialized electrochemical sensor manufacturers with dense distribution networks, and regional kit assemblers serving price-sensitive preliminary screening. Consolidation pressure runs through M&A targeting cloud analytics capabilities, while portfolio diversification into subscription-based calibration services accelerates.
Among diversified analytical conglomerates, Thermo Fisher Scientific and Agilent Technologies exemplify the premium-tier archetype through mass spectrometry and atomic absorption system depth. Hanna Instruments occupies a position within the specialized portable meter tier, competing through ion-selective electrode distribution density calibrated for on-farm deployment. LaMotte Company represents the simplified kit segment, serving agricultural consultants with colorimetric reagent systems priced for mid-size grower preliminary assessment.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Horiba Ltd. |
| PerkinElmer |
| Shimadzu Corporation |
| LaMotte Company |
| Merck KGaA |
| Hanna Instruments |
| FOSS Analytical |
| Others |
Value Network & Pricing Analysis
EU Green Deal soil health monitoring mandates gate qualified supply access and premium-tier pricing power, as REACH-compliant reagent formulations and certified calibration services separate validated laboratory analyzer vendors from commodity field kit assemblers serving price-sensitive preliminary screening segments.
Pricing Analysis
Yield-linked subscription pricing anchors the portable meter tier, with per-acre sensor-as-a-service bundles transferring obsolescence risk from California Central Valley growers to equipment vendors. Three-tier pricing structure across laboratory analyzers, portable meters, and colorimetric kits reflects certification grade and after-sales calibration depth. Cost compression in the soil test kit segment intensifies because Indian and Brazilian distributors source from domestic electrochemical module assemblers. Agricultural consultants serving mid-size growers exhibit highest price sensitivity; research institutions purchasing atomic absorption systems show lowest.
Supply Chain Analysis
Specialized spectroscopy technician scarcity in Bavaria and North Rhine-Westphalia constrains manufacturing scale-up for German precision agriculture equipment suppliers. Optical component sourcing draws from Japanese photonics suppliers and German laser source manufacturers, while electrochemical sensor membrane production rests on South Korean and Chinese materials processors. Single-source vulnerability in argon gas infrastructure for inductively coupled plasma systems limits ICP-MS deployment flexibility. Distribution runs through agronomic consultancy networks in São Paulo and cooperative extension channels in Iowa and Illinois.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Clean Water Act nutrient criteria enforcement creates a cost-of-compliance barrier-to-entry moat, as certified portable meter validation and documented chain-of-custody protocols disqualify unqualified kit assemblers from watershed monitoring procurement.
For Market Incumbents: Hedge against MEMS-based modularization by acquiring cloud analytics platforms that consolidate multi-vendor Bluetooth data streams into unified farm management dashboards. Lock in calibration service contracts with German research institutions facing EU Green Deal soil monitoring mandates to secure recurring revenue against portable meter commoditization.
For New Entrants and Emerging Players: Agricultural drone service providers represent the most penetrable channel partner type for hyperspectral sensor payload integration, bypassing capital-intensive ground-based analyzer manufacturing. Target Mato Grosso soybean operations with tropical-calibrated nitrate detection cartridges through Brazilian federal agricultural modernization program procurement channels.
For Investors and Strategic Acquirers: Accelerated subscription contracting penetration among California specialty crop operations is the leading indicator that sensor-as-a-service business models have achieved sufficient scale for platform rollup. Prioritize targets with captive cloud analytics infrastructure and established EPA certification dossiers over pure hardware manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-as-a-Service Platform Launch | Transfers capital expenditure burden from Midwestern corn-soybean growers to equipment vendors. |
| Backward Integration into MEMS Fabrication | Reduces reliance on South Korean electrochemical sensor membrane suppliers for portable meter arrays. |
| REACH Reagent Reformulation Program | Accelerates ECHA dossier resubmission timelines for European environmental compliance lab contracts. |
| Drone Hyperspectral Partnership | Opens subscription-based canopy nutrient mapping for Brazilian agronomic consultancies in São Paulo. |
| Calibration Network Expansion | Densifies service coverage around Munich-Stuttgart research axis for laboratory analyzer maintenance. |
Research Methodology
Trade publications, customs shipment records, and EPA enforcement action databases formed the secondary backbone, cross-referenced against primary interviews with precision agriculture equipment procurement managers, agronomic consultancy principals, agricultural research station directors, and reagent formulation chemists. Bottom-up and top-down triangulation validated installed base estimates and replacement cycle assumptions across laboratory analyzer and portable meter categories.
Bottom-up modeling built from country-level equipment shipment data and subscription contract disclosures, while top-down analysis anchored total addressable market sizing against precision agriculture adoption curves and regulatory mandate implementation schedules. Segmentation dimensions included detection method, mobility tier, end-user capital availability, and regional compliance framework intensity. CAGRs derived from weighted average of historical replacement patterns and policy-driven procurement acceleration scenarios, with specific inputs from EU Farm to Fork Strategy implementation timelines and EPA discharge permit expansion rates.
Several conditions sit outside the modeled scope, including pre-commercial drone-mounted hyperspectral sensor deployment rates and potential REACH reagent ban scope expansions beyond phosphate and nitrate detection chemistries. Forecasts reflect assumptions around continued argon gas supply stability and spectroscopy technician training program scale-up. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Testing Services
Pesticide Detection Market
Agricultural Testing Services
North American Feed Testing Market
Agricultural Testing Services
Asia Pacific Feed Testing Market
Agricultural Testing Services
Soil Testing Kit Market
Agricultural Testing Services
Plant Disease Diagnostic Market
Agricultural Testing Services
Pesticide Residue Testing Market
Agricultural Testing Services
Soil Field Testing Equipment Market
Agricultural Testing Services
Nematode Testing Services Market
Agricultural Testing Services
Europe Feed Testing Market
Agricultural Testing Services
Seed Testing Services Market
Agricultural Testing Services
Agricultural Testing Services Market
Agricultural Testing Services
Impact Soil Tester Market
Agricultural Testing Services
Agrochemicals Testing and Inspection Service Market
Agricultural Testing Services
Poultry Diagnostic Testing Market
Agricultural Testing Services
Soil Sampling Services Market
Agricultural Testing Services
Soil Erosion Testing Market