
 Soil Sampling Services Market | 2026-2036
Soil Sampling Services Market Size, Share, and Industry Trends Forecast 2026-2036
Soil Sampling Services Market Analytics
Market Context
The shift from in-house agronomy departments toward outsourced multi-laboratory contracts is consolidating procurement patterns across large-scale agricultural enterprises. SGS SA leverages its global laboratory network to sustain service consistency across diverse geographies. ALS Limited anchors its competitive position through specialized geochemistry capabilities that differentiate its mining and environmental testing portfolios. Eurofins Scientific competes aggressively on turnaround speed, positioning its decentralized lab infrastructure to capture time-sensitive seasonal demand.
Technical and Structural Dimensions
Soil sampling services encompass the systematic collection, preparation, and analytical characterization of soil specimens to determine chemical composition, physical properties, and biological indicators for land-use decisions. Core sampling methods penetrate subsurface horizons to deliver stratified contaminant profiles required for environmental liability assessments and foundation engineering. Laboratory analysis commands the dominant margin pool within service-type segmentation due to capital-intensive instrumentation and certified technician requirements. Composite sampling is expanding fastest among sampling methods as precision agriculture platforms integrate GPS-guided grid protocols that demand aggregated spatial representation.
Regulatory Environment and Outlook
The EPA governs soil contaminant thresholds under CERCLA and RCRA frameworks, while ISO 10381 standards prescribe sampling methodology for international data comparability. State-level agricultural departments supplement federal requirements with nutrient management mandates that compel periodic soil testing for permitted livestock operations. Stakeholders must monitor evolving PFAS screening protocols and carbon sequestration verification standards that will reshape laboratory capability investments and service pricing structures.
Market Dynamics
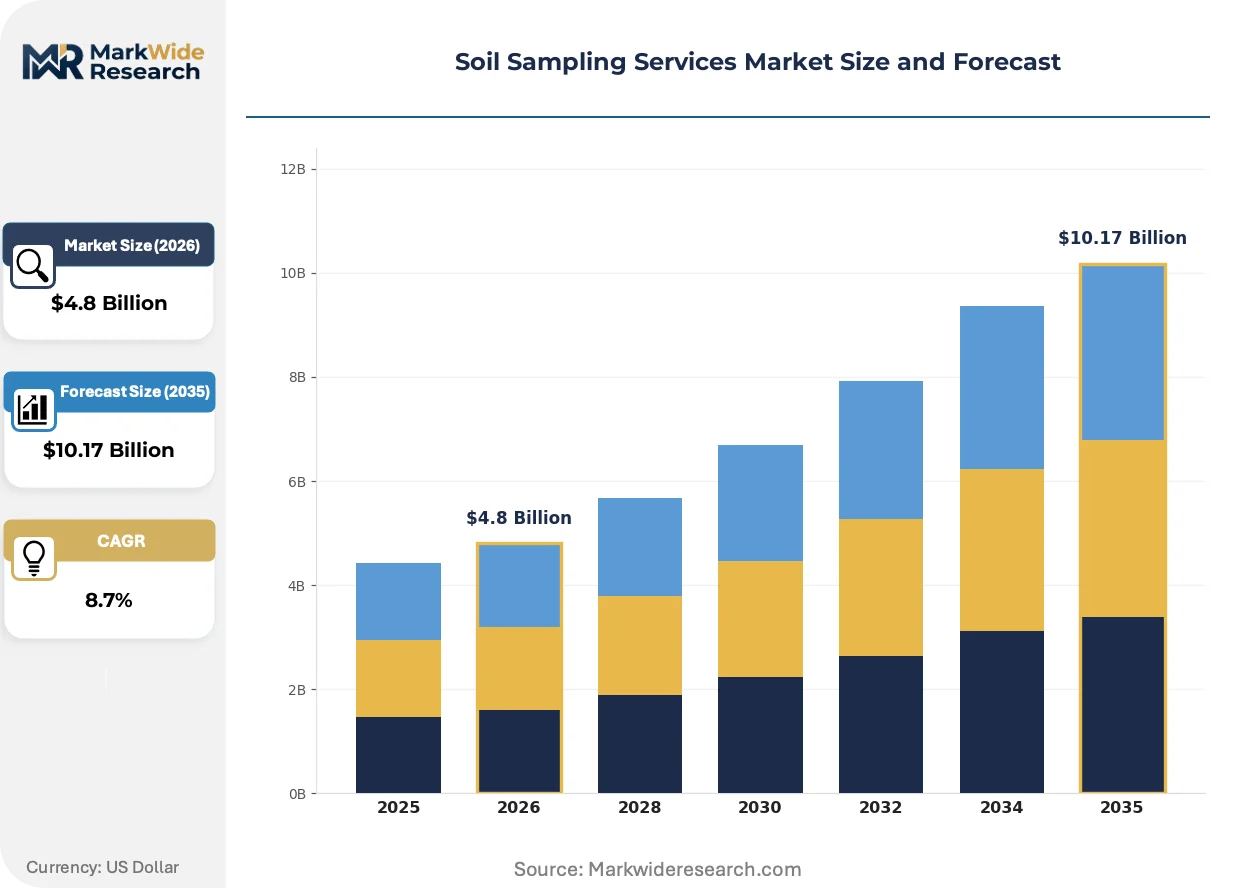
Precision agriculture platforms are consolidating soil diagnostics into seasonal subscription bundles, compressing standalone sampling margins while expanding total addressable service volume across commercial farming operations.
Growth Catalysts
- EPA Screening Protocols:Updated soil contaminant thresholds under CERCLA and RCRA frameworks are expanding mandatory testing volumes for brownfield redevelopment and industrial site transfers.
- GPS-Guided Grid Sampling:Variable-rate application systems require high-resolution spatial data, driving demand for composite sampling protocols that aggregate multiple core specimens into representative analytical units.
- Midwest Row-Crop Concentration:Large-scale corn and soybean producers in Illinois, Iowa, and Nebraska require intensive nutrient management to maintain yield optimization and environmental compliance.
Market Restraints
- Laboratory Capacity Bottlenecks:Certified technician shortages and capital-intensive ICP-MS instrumentation constrain turnaround speed during compressed spring planting windows.
- Sample Logistics Costs:Cold-chain preservation requirements and rapid transit mandates from remote agricultural sites to analytical facilities elevate per-specimen handling expenses.
- ISO 10381 Compliance Burden:International methodology standardization creates documentation overhead that smaller regional laboratories struggle to maintain against accredited competitors.
Strategic Opportunities
- Carbon Sequestration Verification:Emerging soil carbon credit markets require standardized baseline measurement protocols that accredited laboratories can monetize through MRV (measurement, reporting, verification) service contracts.
- PFAS Screening Expansion:State-level mandates for per- and polyfluoroalkyl substance detection in agricultural and residential soils are creating new analytical capability requirements that early movers can capture.
- Drone-Deployed Sensor Fusion:Proximal sensing technologies combined with ground-truthing sampling are enabling tiered service models that segment customers by data depth requirements.
Industry Challenges
- Geochemistry Talent Scarcity:Specialized expertise in soil mineralogy and contaminant speciation remains concentrated among aging practitioner cohorts with limited pipeline replacement.
- LIMS Integration Complexity:Legacy laboratory information management systems require costly retrofitting to interface with precision agriculture data platforms and farm management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soil Sampling Services Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Field Sampling, Laboratory Analysis, Testing Services, Consulting Application: Agriculture, Environmental Assessments, Construction, Mining Sampling Method: Grab Sampling, Composite Sampling, Core Sampling, Auger Sampling End User: Agronomists, Environmental Agencies, Contractors, Researchers |
| Companies Covered | SGS SA, ALS Limited, Eurofins Scientific, Intertek Group plc, Bureau Veritas SA, AGQ Labs USA, Actlabs Group of Companies, TUV SUD, Merieux NutriSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soil Sampling Services Market Evolving Landscape
Digital soil mapping and real-time sensor networks are compressing the temporal gap between field data collection and agronomic decision-making, reshaping how commercial producers contract for diagnostic services.
Portable X-ray fluorescence (pXRF) spectrometry is electrifying field-based elemental screening by enabling immediate heavy metal and nutrient quantification without laboratory transport. Agronomists at large-scale operations in California's Central Valley and Florida's citrus belt are deploying pXRF units for same-day contamination assessments. This capability is compressing the traditional two-week analytical cycle into hours, forcing laboratory service providers to reposition around certified reference methods and legal defensibility rather than speed alone.
REACH regulatory expansion into soil contaminant monitoring for industrial chemical registration is mandating expanded analytical scope across EU member states. The European Chemicals Agency's updated data requirements for persistent substances are compelling manufacturers to commission comprehensive soil background studies for facility footprints. Agricultural and environmental testing laboratories in Germany, France, and the Netherlands are investing in expanded GC-MS/MS capability to capture this compliance-driven demand.
Consolidated procurement through multi-year enterprise agreements is displacing transactional sampling contracts among large-scale agricultural enterprises. Crop input distributors and cooperative buying groups are bundling soil diagnostics with seed and fertilizer commitments, capturing volume discounts that standalone producers cannot match. This concentration is most visible across the US Midwest, where regional agronomy retailers are acquiring independent sampling operations to secure captive diagnostic flow.
Soil Sampling Services Market Segmentation
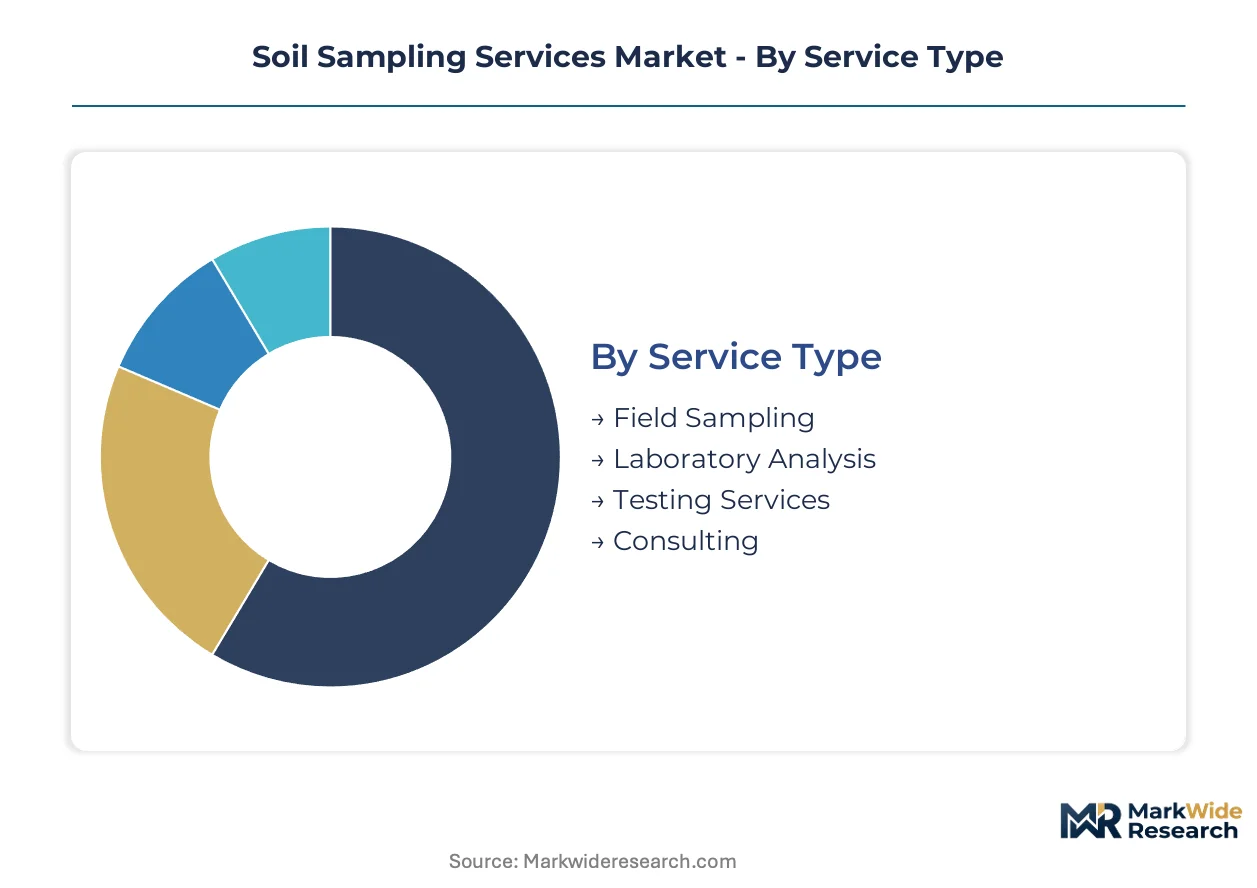
Soil sampling services fragment across distinct capability tiers and buyer sophistication levels. Procurement patterns diverge sharply between seasonal agricultural subscriptions and one-time environmental liability assessments.
Service Type:
Cost tiers separate buyers seeking basic field execution from those requiring certified analytical defensibility.
- Laboratory Analysis:Capital-intensive ICP-MS and GC-MS instrumentation delivers certified contaminant quantification for EPA CERCLA submissions. Demand concentrates among Illinois and Iowa commercial corn producers managing nitrogen leaching compliance under state nutrient management mandates.
- Field Sampling:Technician crews execute GPS-guided grid protocols and chain-of-custody documentation for precision agriculture platforms. Large-scale Nebraska soybean operations outsource entire sampling programs to capture volume discounts unavailable through in-house agronomy departments.
- Testing Services:Rapid turnaround packages bundle pXRF screening with expedited laboratory confirmation for California Central Valley contamination assessments.
- Consulting:Interpretive reporting and remediation design support brownfield redevelopment projects requiring liability quantification.
Volume sits with Laboratory Analysis; growth tilts toward Field Sampling.
Application:
Regulatory intensity and seasonality create divergent margin profiles across use cases.
- Agriculture:Nutrient management and variable-rate fertilization programs drive recurring seasonal demand. Midwest row-crop producers in Minnesota and Indiana commission intensive grid sampling to optimize input costs and satisfy permit requirements for concentrated animal feeding operations.
- Environmental Assessments:Phase I and Phase II site investigations for property transfers and brownfield redevelopment require defensible contaminant profiling. EPA RCRA corrective action programs and state-led PFAS screening mandates are expanding mandatory testing volumes.
- Construction:Geotechnical characterization for foundation engineering and soil stability assessment supports commercial development and infrastructure projects.
- Mining:Exploration geochemistry and closure rehabilitation monitoring demand specialized acid-base accounting and metal leaching protocols.
Revenue concentrates in Agriculture; expansion accelerates fastest in Environmental Assessments.
Sampling Method:
Technical sophistication and spatial resolution requirements stratify buyer preferences.
- Composite Sampling:GPS-guided aggregation of multiple core specimens into representative analytical units enables variable-rate application systems. Precision agriculture platforms in Kansas and Ohio are standardizing composite protocols to reduce per-acre sampling costs while maintaining spatial resolution.
- Core Sampling:Penetration of subsurface horizons delivers stratified contaminant profiles for environmental liability assessments and geotechnical engineering. EPA soil screening level compliance for volatile organic compounds demands intact core preservation with zero headspace techniques.
- Grab Sampling:Single-point collection for rapid reconnaissance and hotspot identification supports preliminary site characterization.
- Auger Sampling:Hand-operated or power-driven boring equipment accesses shallow subsurface layers for agricultural nutrient profiling and preliminary geotechnical assessment.
Adoption favors Composite Sampling; technical complexity peaks with Core Sampling.
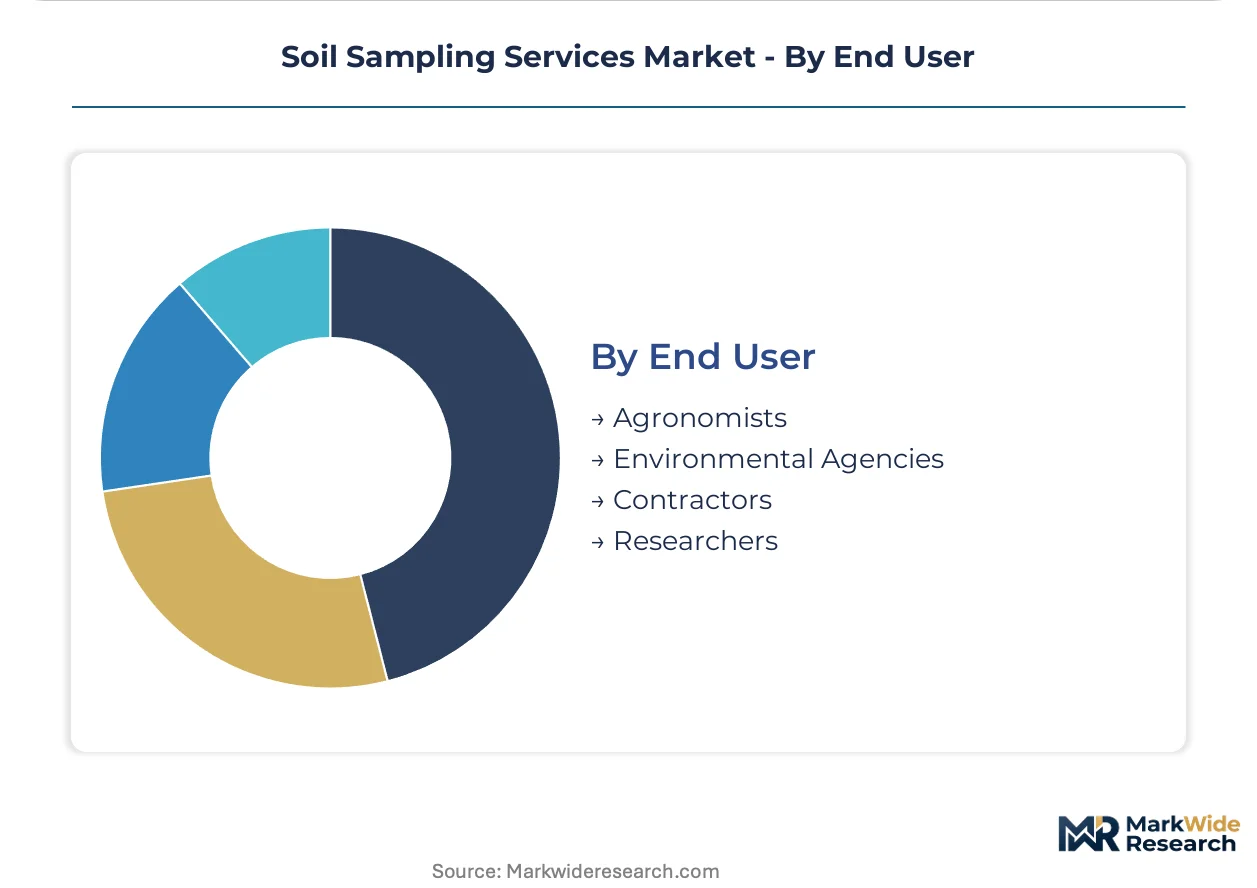
End User:
Decision-making authority and procurement scale differentiate buyer segments.
- Environmental Agencies:Federal and state regulatory bodies mandate standardized protocols for enforcement monitoring and site remediation oversight. EPA regional offices and state environmental departments specify ISO 10381 methodology for data comparability across jurisdictions.
- Agronomists:Independent consultants and cooperative extension specialists translate analytical results into input recommendations for commercial producers. Iowa and Illinois agronomists are consolidating diagnostic procurement through multi-year enterprise agreements with regional laboratory networks.
- Contractors:Environmental remediation firms and geotechnical engineering practices require rapid turnaround for project scheduling constraints.
- Researchers:Academic and government research institutions commission baseline soil carbon inventories and long-term monitoring protocols for climate and agricultural science studies.
Contracting volume clusters with Agronomists; regulatory influence rests with Environmental Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest agricultural corridors anchor soil sampling demand through intensive row-crop production systems. Corn Belt nutrient management mandates and industrial brownfield redevelopment protocols generate concentrated service procurement across distinct national markets.
United States
Illinois and Iowa corn producers commission grid-based composite sampling to satisfy state nutrient management mandates for concentrated animal feeding operations. EPA CERCLA screening protocols expand mandatory testing volumes for industrial site transfers and brownfield redevelopment. Nebraska soybean operations outsource entire sampling programs to capture volume discounts through multi-year enterprise agreements with regional laboratory networks.
Germany
REACH regulatory expansion into soil contaminant monitoring for industrial chemical registration mandates comprehensive background studies for manufacturing facility footprints. The European Chemicals Agency's updated data requirements for persistent substances compel expanded analytical scope. Agricultural and environmental testing laboratories in the Rhine-Ruhr industrial corridor invest in expanded GC-MS/MS capability to capture compliance-driven demand.
Brazil
Cerrado soybean expansion and precision agriculture adoption accelerate outsourced soil diagnostics among commercial farming operations. State-level environmental agencies in Mato Grosso and Goiás implement mandatory soil testing protocols for large-scale agricultural permits. São Paulo-based agronomy retailers acquire independent sampling operations to secure captive diagnostic flow for cooperative buying groups.
Australia
Mining closure rehabilitation monitoring and exploration geochemistry sustain specialized acid-base accounting and metal leaching protocols. Western Australian iron ore operations and Queensland coal basins require intensive baseline soil carbon inventories for rehabilitation bond calculations. Sydney and Melbourne environmental consultancies expand field crews to service remote agricultural sites with rapid transit mandates for cold-chain preservation.
Canada
Prairie Province wheat and canola producers adopt variable-rate fertilization programs driving recurring seasonal demand for GPS-guided grid sampling. Health Canada and PMRA residue monitoring programs expand mandatory soil testing for pesticide registration and re-evaluation studies. Alberta oil sands reclamation projects and Ontario brownfield redevelopment generate environmental liability assessment volumes requiring defensible contaminant profiling.
Soil Sampling Services Market Competitive Landscape
Global majors compete with regional champions across laboratory accreditation tiers and turnaround speed capabilities. The market structures around three player categories: multinational testing conglomerates with decentralized infrastructure, specialized geochemistry laboratories with mining heritage, and regional agronomy retailers integrating backward into diagnostic services. Consolidation proceeds through acquisition of independent sampling operations by crop input distributors, while technology differentiation focuses on portable field instrumentation and LIMS integration with farm management platforms.
Among Switzerland-based testing conglomerates, SGS SA exemplifies the global network archetype through service consistency across diverse geographies. ALS Limited represents specialized geochemistry capability derived from mining sector heritage. Eurofins Scientific occupies a position emphasizing turnaround velocity through decentralized laboratory infrastructure. These three players anchor competitive dynamics around accreditation breadth, geographic coverage, and seasonal capacity management rather than price alone.
| Leading Market Players |
|---|
| SGS SA |
| ALS Limited |
| Eurofins Scientific |
| Intertek Group plc |
| Bureau Veritas SA |
| AGQ Labs USA |
| Actlabs Group of Companies |
| TUV SUD |
| Merieux NutriSciences |
| Others |
Value Network & Pricing Analysis
Certified geochemist concentration in the United States Midwest and Western Australia creates labor-cost differentials that widen pricing-tier spreads between premium accredited laboratories and regional field-service providers. EPA CERCLA-compliant analytical packages command substantial premiums over rapid-turnaround screening services due to defensibility requirements and technician scarcity.
Pricing Analysis
Warranty-backed data defensibility separates bundled premium offerings from unbundled field-execution contracts. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 17025 accreditation status, with certified reference methods carrying 40-60 percent spreads over rapid pXRF screening. Cost compression in the standard tier intensifies because agronomy retailers bundle diagnostics with crop inputs at volume discounts. Commercial corn producers in Illinois and Iowa exhibit highest price sensitivity; environmental remediation contractors facing project-liability exposure show least sensitivity.
Supply Chain Analysis
ISO 17025 accreditation gating restricts laboratory network participation to facilities with capital-intensive ICP-MS and GC-MS instrumentation. Geographic supply concentration centers on the United States, Germany, and Australia, where mining heritage and agricultural scale sustain specialized geochemistry capability. Raw material dependencies include analytical-grade reagents, certified reference materials, and cold-chain logistics infrastructure. Single-source vulnerability concentrates in helium supply for GC-MS operations and specialized chromatography columns. Distribution runs through regional laboratory hubs that aggregate specimens from remote agricultural sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable X-ray fluorescence spectrometry is displacing laboratory-bound elemental analysis, compressing turnaround cycles from weeks to hours and forcing incumbent service providers to reposition around certified defensibility rather than speed alone.
For Market Incumbents: Hedge against margin erosion in rapid-turnaround screening by deepening backward integration into field-sampling operations and securing multi-year enterprise agreements with Midwest agronomy retailers. Threat substitution from drone-deployed proximal sensing demands investment in sensor-fusion capabilities that combine aerial data with ground-truthing protocols. Certification investment in PFAS analytical capability represents a critical lever for capturing state-mandated testing volumes. For New Entrants and Emerging Players: EPA's evolving PFAS screening protocols in the United States open a window for specialized analytical laboratories to capture compliance-driven demand before incumbent capacity expansion saturates the segment. White-space targets include carbon sequestration verification services for agricultural carbon credit markets and drone-deployed sensor fusion for tiered data-depth offerings. The most penetrable segment sits with mid-scale Nebraska and Kansas row-crop producers seeking alternatives to bundled agronomy-retailer contracts. Go-to-market positioning should emphasize rapid-turnaround pXRF screening with expedited laboratory confirmation. For Investors and Strategic Acquirers: Re-rating potential sits with specialized geochemistry laboratories possessing mining-sector heritage and transferable acid-base accounting capabilities, given agricultural carbon verification demand acceleration. Long-term viability across the projection horizon favors accredited facilities with established EPA CERCLA submission track records and existing ISO 17025 infrastructure. Acquisition target archetype: regional agronomy retailers with captive diagnostic flow but limited analytical depth. The signal to watch is state-level carbon credit program implementation triggering MRV service contract procurement.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS Analytical Capability Investment | EPA state-level mandates for per- and polyfluoroalkyl substance detection create first-mover advantage in compliance-driven testing volumes. |
| Carbon Sequestration Verification Service Launch | Agricultural carbon credit markets require standardized MRV protocols that accredited laboratories can monetize through baseline measurement contracts. |
| Drone Sensor Fusion Platform Integration | Proximal sensing technologies combined with ground-truthing sampling enable tiered service models segmenting customers by data depth requirements. |
| Backward Integration into Field Sampling Operations | Captive specimen collection secures volume flow and reduces per-specimen logistics costs for remote agricultural sites. |
| Multi-Year Enterprise Agreement Expansion | Consolidated procurement through cooperative buying groups captures volume discounts unavailable to standalone producers in Illinois and Iowa. |
Research Methodology
Multi-period observation of precision agriculture adoption rates, EPA regulatory enforcement patterns, and laboratory capacity utilization anchored the trend analysis, supplemented by interviews with certified geochemists, agronomy retail procurement directors, environmental remediation project managers, and precision agriculture platform engineers. Secondary validation drew from EPA enforcement and compliance databases, ISO accreditation registries, state nutrient management program filings, and agricultural cooperative purchasing records. Bottom-up specimen volume estimates triangulated against top-down agricultural acreage and mining closure liability projections.
Input-output matrix modeling connected field-sampling crew deployment, laboratory instrument utilization, and seasonal demand compression across the analysis window. Segmentation dimensions included service type tier, sampling method sophistication, application regulatory intensity, and end-user procurement scale. CAGRs were derived from trend extrapolation of adoption curves and regulatory mandate implementation schedules. Industry-specific forecast inputs encompassed variable-rate fertilization penetration in Midwest row-crop systems and PFAS screening protocol expansion timelines.
The model assumes a particular technology adoption path for portable X-ray fluorescence spectrometry; alternative pathways for drone-deployed proximal sensing would alter the outlook for laboratory-bound analytical demand. Forecasts reflect assumptions regarding EPA enforcement continuity and state nutrient management mandate persistence. A model refresh is warranted upon material change in carbon credit program implementation or PFAS regulatory scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Testing Services
Nematode Testing Services Market
Agricultural Testing Services
Soil Erosion Testing Market
Agricultural Testing Services
Feed Testing Market
Agricultural Testing Services
Impact Soil Tester Market
Agricultural Testing Services
Pesticide Residue Testing Market
Agricultural Testing Services
Rapid Mycotoxin Detection Systems for Grain Handling Facilities Market
Agricultural Testing Services
Soil Field Testing Equipment Market
Agricultural Testing Services
Animal Feed Testing Market
Agricultural Testing Services
Global Agriculture Testing Services Market
Agricultural Testing Services
Agricultural Testing Services Market
Agricultural Testing Services
Seed Testing Services Market
Agricultural Testing Services
Agrochemicals Testing and Inspection Service Market
Agricultural Testing Services
Europe Feed Testing Market
Agricultural Testing Services
Plant Disease Diagnostic Market
Agricultural Testing Services
Testing, Inspection, and Certification for Agriculture & Food Market
Agricultural Testing Services
Plant Nutrient Testing Equipment Market