
 Nematode Testing Services Market | 2026-2036
Nematode Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Nematode Testing Services Market Foresight
Certified nematode taxonomist availability is bifurcating the competitive landscape between high-throughput molecular labs and traditional morphology centers. Eurofins Scientific leverages its pan-European laboratory network to dominate soil health assessment contracts across Germany and France. SGS SA anchors its position through in-house bioinformatics pipelines that reduce turnaround times for biodiversity monitoring projects. ALS Limited specializes in PCR-based diagnostics for agricultural cooperatives across Australia and Canada.
Nematode testing services encompass laboratory protocols that detect, identify, and quantify plant-parasitic and free-living nematode populations in soil, root, and water matrices using microscopic examination, DNA extraction, and sequencing-based methods; these services enable precision agriculture decisions, phytosanitary compliance, and ecological risk assessment. Molecular diagnostics and next-generation sequencing represent the fastest-expanding service categories as growers substitute chemical-intensive nematicide programs with targeted biological interventions. Morphological identification retains stable demand from regulatory agencies requiring visual species confirmation for quarantine protocols.
The European Food Safety Authority (EFSA) and national regulators under the EU Plant Health Regulation enforce nematode surveillance for regulated pests like potato cyst nematodes, mandating certified laboratory identification for cross-border seed and plant material movement. The United States Department of Agriculture (USDA) and Environmental Protection Agency (EPA) coordinate on nematicide re-registration reviews that push agricultural laboratories toward molecular resistance monitoring. Stakeholders must weigh capital allocation between expanding NGS capacity and defending morphological expertise as regulatory acceptance standards for molecular data continue evolving.
Market Dynamics
The transition from morphology-based identification to molecular diagnostics is compressing turnaround times and reconfiguring laboratory capital allocation across agricultural and environmental testing sectors.
Growth Catalysts
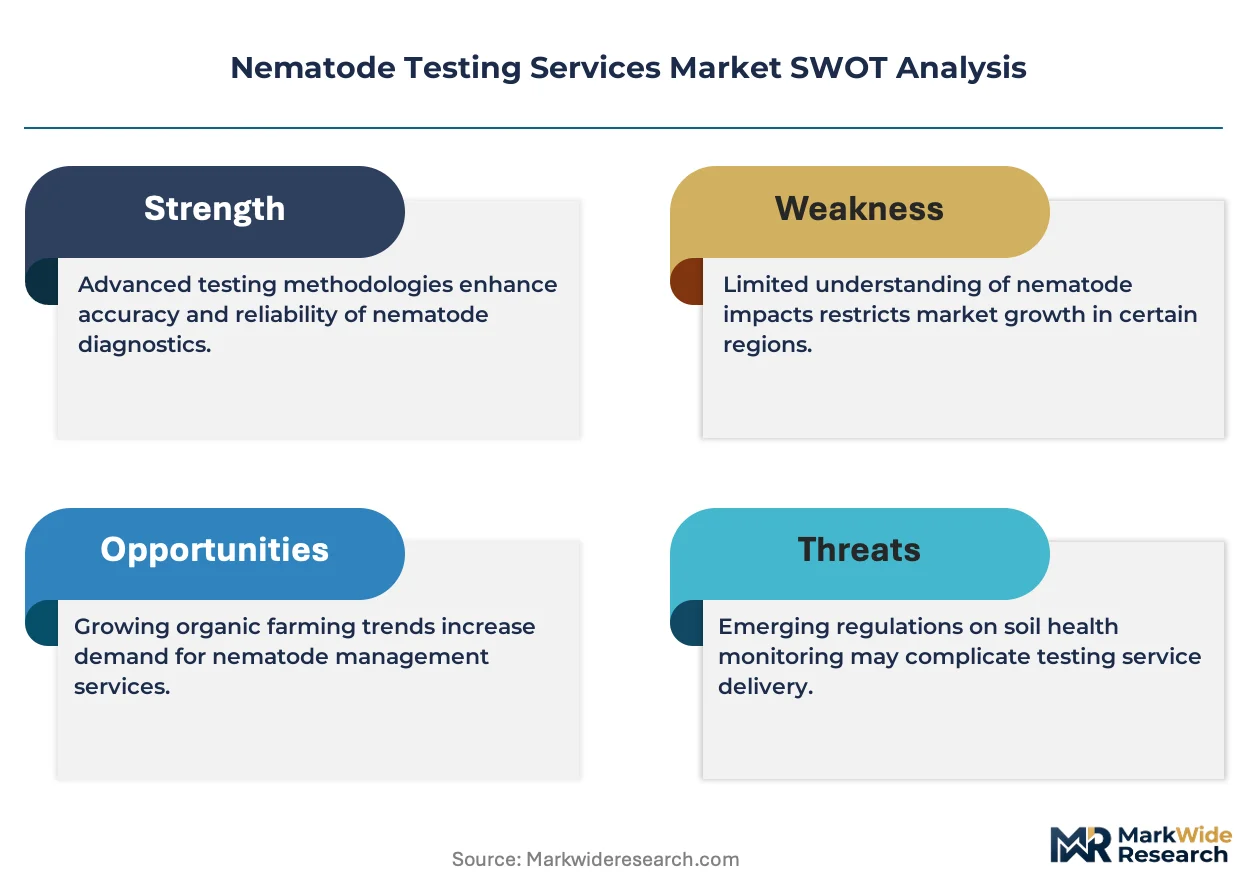
- EU F-Gas Regulation:The European Union's phasedown of sulfuryl fluoride and other chemical fumigants is compelling growers to adopt precision nematode diagnostics for targeted biological control programs.
- Soil health monitoring:Carbon credit verification protocols and regenerative agriculture certification schemes are embedding nematode biodiversity metrics as core soil quality indicators.
- qPCR assay standardization:Commercial availability of validated primer sets for potato cyst nematodes and root-knot species is democratizing molecular testing access for mid-sized agricultural laboratories.
Market Restraints
- Certified taxonomist scarcity:Retirement waves among morphology-trained specialists are creating diagnostic bottlenecks for regulatory agencies requiring visual species confirmation.
- NGS capital intensity:Illumina and PacBio sequencing platforms require substantial upfront investment, constraining independent laboratory expansion.
- Reference database gaps:Incomplete mitochondrial and ribosomal DNA libraries for free-living nematode taxa limit automated identification accuracy in ecological assessments.
Strategic Opportunities
- Digital extension services:Integration of nematode testing results with farm management software platforms creates recurring revenue streams through subscription-based advisory models.
- Biologicals registration support:Nematicide developers require standardized efficacy testing protocols, opening contract research opportunities for laboratories with GLP certification.
- Water quality monitoring:Wastewater treatment operators and drinking water utilities are adopting nematode community analysis as a bioindicator for treatment performance validation.
Industry Challenges
- Proficiency testing harmonization:Inconsistent ring trial protocols between national accreditation bodies complicate cross-border laboratory recognition.
- Sample logistics integrity:Temperature-controlled transport requirements for molecular preservation increase field collection costs and rural service coverage gaps.
- Data interoperability:Proprietary bioinformatics pipelines generate incompatible output formats, fragmenting multi-laboratory research collaborations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nematode Testing Services Market |
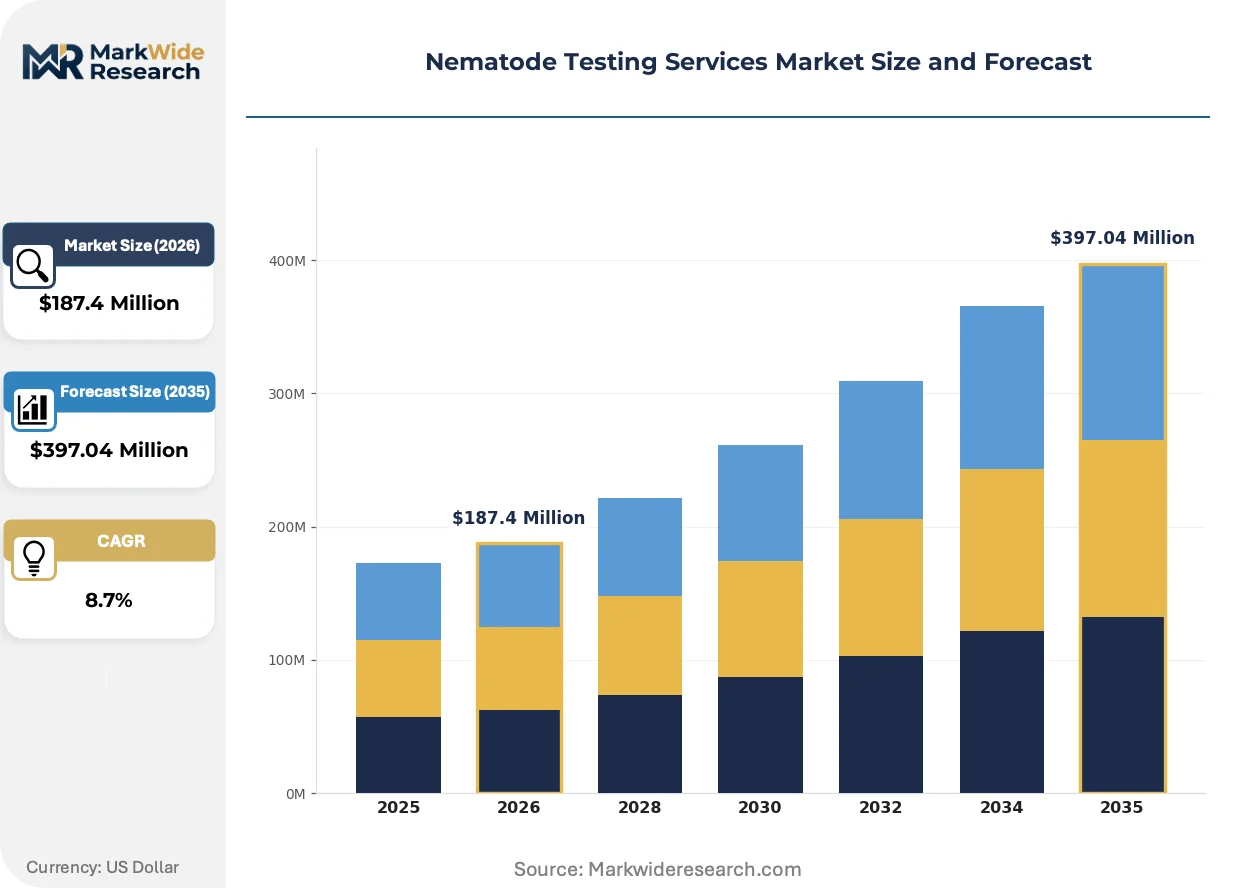
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: DNA Barcoding, Morphological Identification, Whole Genome Sequencing, Molecular Diagnostics End User: Agricultural Laboratories, Environmental Consultants, Research Institutes, Academic Institutions Application: Soil Health Assessment, Crop Protection, Biodiversity Monitoring, Pest Management Technology: PCR, Next-Generation Sequencing, Bioinformatics, Microscopy |
| Companies Covered | Eurofins Scientific, SGS SA, ALS Limited, Intertek Group, Fera Science Limited, CSP Labs, Agvise Laboratories, Midwest Laboratories, Waters Agricultural Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nematode Testing Services Market Shifts & Advancements
Portable molecular platforms and cloud-based taxonomy databases are dissolving the traditional boundary between centralized diagnostic laboratories and field-based detection systems.
Loop-mediated isothermal amplification (LAMP) technology is miniaturizing nematode diagnostics into handheld devices operable without thermal cycling infrastructure. Agricultural cooperatives in remote production regions are deploying these field kits for real-time infestation mapping. The technology is compressing the decision window between sample collection and management intervention from weeks to hours.
The EU Green Deal's Farm to Fork Strategy is mandating integrated pest management compliance documentation for CAP subsidy eligibility. Member states are interpreting this through divergent laboratory certification requirements, creating fragmented accreditation landscapes. Germany and France are accelerating mutual recognition agreements to streamline cross-border seed certification.
Consolidated buying by multinational agrichemical distributors is displacing fragmented procurement through independent crop consultants. These distributors are bundling nematode testing with biological product prescriptions, capturing diagnostic margin within input supply chains. The pattern is most pronounced in North American row crop regions where distributor consolidation has advanced furthest.
Nematode Testing Services Market Segmentation
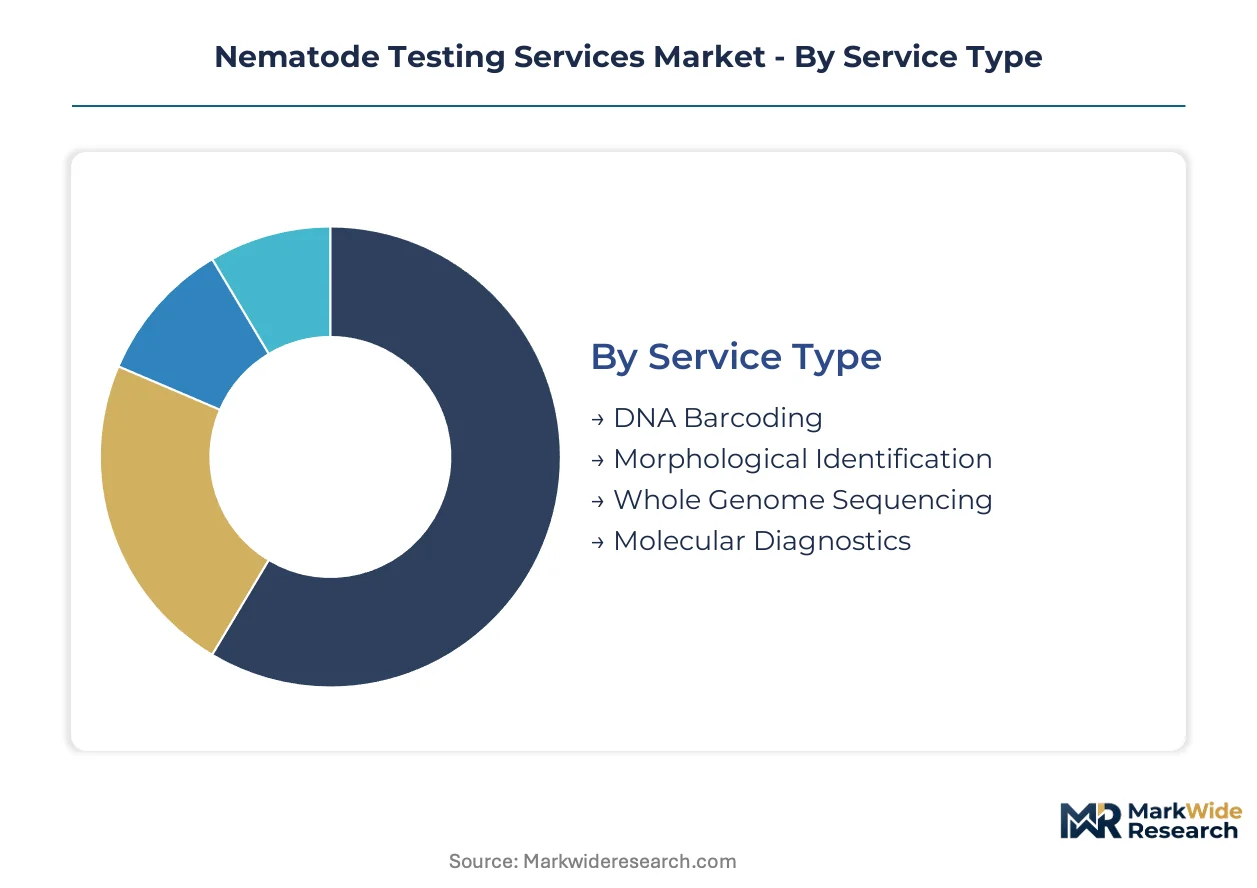
Segmentation in nematode testing services reveals how laboratory capabilities align with distinct regulatory requirements and end-user sophistication levels. Service providers configure equipment and staffing around specific technology-service combinations rather than pursuing undifferentiated full-spectrum offerings.
Service Type:
Molecular services concentrate demand in export-oriented agricultural regions where phytosanitary certification crosses borders, while morphology retains domestic regulatory anchoring.
- Molecular Diagnostics:qPCR and RT-PCR protocols detect potato cyst nematodes and root-knot species with detection thresholds below single-cyst levels. German and Dutch seed certification programs are consolidating procurement around laboratories with ISO 17025 accreditation for these assays.
- DNA Barcoding:Mitochondrial COI and ribosomal ITS region sequencing enables species-level identification without taxonomic expertise. Academic biodiversity projects across Scandinavia and the United Kingdom are driving capacity expansion for high-throughput specimen processing.
- Morphological Identification:Visual microscopy remains mandatory for regulatory agencies requiring physical voucher specimens.
- Whole Genome Sequencing:Population genomics applications track nematicide resistance allele frequencies across agricultural regions.
Molecular diagnostics holds the largest share; momentum sits with DNA barcoding.
End User:
Customer sophistication tiers separate capital-intensive laboratories from advisory-dependent field consultants.
- Agricultural Laboratories:Commercial testing facilities process thousands of soil samples monthly during planting windows. France's cooperative laboratory networks and Australia's commercial agricultural labs are automating sample prep to compress turnaround times below 72 hours during peak demand periods.
- Environmental Consultants:Ecological risk assessment contractors require free-living nematode community analysis for remediation validation. Remediation projects in contaminated industrial zones across Belgium and the Netherlands are embedding these services into long-term monitoring contracts.
- Research Institutes:Public agricultural research organizations develop novel detection protocols.
- Academic Institutions:University taxonomy departments train the shrinking cohort of certified morphologists.
Agricultural laboratories dominate current procurement volumes; environmental consultants are expanding most rapidly.
Application:
Use case maturity varies from commoditized soil screening to emerging biodiversity credit verification.
- Soil Health Assessment:Nematode community indices serve as biological indicators in regenerative agriculture certification schemes. Carbon credit protocols in France and Germany now require standardized biodiversity metrics that include nematode faunal analysis as a core soil quality component.
- Crop Protection:Pre-plant infestation mapping guides precision nematicide application. Potato production regions in the United Kingdom and seed potato exporters in Scotland are mandating certified testing for cyst nematode freedom before field planting.
- Pest Management:Post-treatment efficacy monitoring validates biological control interventions.
- Biodiversity Monitoring:Baseline ecological surveys support environmental impact assessments.
Soil health assessment commands premium pricing; crop protection shows the steepest volume trajectory.
Technology:
Platform selection determines capital intensity and staff skill requirements across laboratory tiers.
- PCR:Thermal cycling infrastructure for targeted pathogen detection represents the baseline molecular capability. Mid-sized agricultural cooperatives in Spain and Italy are adopting portable qPCR units to reduce sample logistics costs and eliminate centralized laboratory bottlenecks.
- Next-Generation Sequencing:Illumina and PacBio platforms enable untargeted community profiling. Biodiversity monitoring contracts in the United Kingdom and metagenomic research collaborations across European universities are absorbing available sequencing capacity.
- Bioinformatics:Pipeline development and reference database curation differentiate service quality.
- Microscopy:Compound and dissecting microscopes retain regulatory acceptance for visual confirmation.
PCR maintains installed base dominance; next-generation sequencing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA's surveillance mandates under the EU Plant Health Regulation anchor European demand for certified nematode diagnostics. Germany, France, and the United Kingdom concentrate procurement volumes for potato cyst nematode testing.
Germany
Seed potato exporters in Lower Saxony and Bavaria drive molecular testing volumes for phytosanitary certification. The F-Gas Regulation phases out sulfuryl fluoride fumigation, compelling growers toward precision diagnostics. Berlin-Brandenburg hosts cooperative laboratory networks automating qPCR sample prep to compress turnaround times below 72 hours during spring planting windows.
France
Carbon credit verification protocols in Île-de-France and Nouvelle-Aquitaine embed nematode biodiversity metrics into regenerative agriculture certification. The EU Green Deal's Farm to Fork Strategy mandates integrated pest management documentation for CAP subsidy eligibility. Auvergne-Rhône-Alpes concentrates commercial agricultural laboratories processing thousands of soil samples monthly for cooperative networks.
United Kingdom
Scotland's seed potato certification program mandates certified cyst nematode freedom testing before field planting. EFSA-aligned national regulators enforce surveillance for regulated pests under retained EU law. Yorkshire and East Anglia host environmental consultancies embedding nematode community analysis into long-term remediation monitoring contracts for contaminated industrial zones.
United States
USDA-APHIS coordinates with EPA on nematicide re-registration reviews pushing laboratories toward molecular resistance monitoring. Idaho and North Dakota potato production regions concentrate pre-plant infestation mapping services. Midwest Laboratories and Waters Agricultural Laboratories anchor diagnostic capacity across the Corn Belt, processing samples for distributor-bundled biological product prescriptions.
Australia
ALS Limited specializes in PCR-based diagnostics for agricultural cooperatives across Victoria and New South Wales. Carbon farming initiatives under the Emissions Reduction Fund embed soil biological indicators into project validation protocols. Queensland and Western Australia expand environmental consultant demand for free-living nematode community analysis in mine site rehabilitation monitoring.
Nematode Testing Services Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in nematode testing services. Pan-European laboratory networks dominate soil health assessment contracts through ISO 17025-accredited molecular capacity. Independent agricultural laboratories anchor regional procurement in North American row crop zones. Three archetypes define competitive positioning: diversified testing conglomerates with cross-border accreditation, cooperative-affiliated laboratories with seasonal automation, and environmental consultancies with biodiversity monitoring specialization. Consolidation pressures intensify as multinational agrichemical distributors bundle diagnostics with biological prescriptions, capturing margin within input supply chains.
Within the diversified testing tier, Eurofins Scientific and SGS SA exemplify pan-European scale advantages. Eurofins leverages its laboratory network across Germany and France to dominate seed certification procurement. SGS SA anchors positioning through in-house bioinformatics pipelines that compress turnaround times for biodiversity monitoring projects. ALS Limited occupies the agricultural cooperative specialist position, with PCR-based capacity concentrated across Australian and Canadian production regions.
| Leading Market Players |
|---|
| Eurofins Scientific |
| SGS SA |
| ALS Limited |
| Intertek Group |
| Fera Science Limited |
| CSP Labs |
| Agvise Laboratories |
| Midwest Laboratories |
| Waters Agricultural Laboratories |
| Others |
Supply & Pricing Matrix
qPCR assay standardization replacing morphology-dependent workflows simultaneously compresses turnaround economics and redistributes laboratory capital toward Germany, France, and the United Kingdom. This substitution dynamic concentrates pricing power with ISO 17025-accredited molecular facilities while margin pressure intensifies for traditional microscopy centers.
Pricing Analysis
Price spreads between German seed certification laboratories and Australian cooperative facilities reflect certification tier and automation scale differentials. Three-tier pricing structure across premium, standard, and economy levels separates GLP-certified contract research from ISO-accredited agricultural testing and unaccredited advisory services. Pricing pressure stems from multinational agrichemical distributors bundling diagnostics with biological prescriptions, capturing margin within input supply chains. Agricultural cooperatives exhibit highest price sensitivity due to seasonal volume spikes and limited capital reserves; pharmaceutical and biological developers demonstrate lowest sensitivity given regulatory compliance requirements.
Supply Chain Analysis
Strategic stockpiling of validated primer sets and reference DNA libraries dominates over just-in-time procurement due to EFSA surveillance mandate continuity requirements. Supply concentration centers on Germany, the Netherlands, and the United States for Illumina sequencing platforms and certified taxonomist training programs. Critical dependencies include thermal cycling reagents, mitochondrial COI primer libraries, and temperature-controlled logistics infrastructure. Single-source vulnerability in PacBio long-read sequencing systems creates bottleneck risk for whole-genome population studies. Distribution runs through pan-European laboratory networks and cooperative-affiliated regional facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through consolidated procurement by multinational agrichemical distributors, fragmenting independent crop consultant influence across North American and European production regions.
For Market Incumbents: Consolidate molecular capacity in Germany and France through automated qPCR sample prep investments that compress turnaround below 72 hours during spring planting windows. Acquire certified taxonomist expertise to defend regulatory agency contracts against emerging bioinformatics-specialist entrants. Channel control through distributor partnership exclusivity represents the critical defensive lever against margin compression from bundled biological-diagnostic offerings. For New Entrants and Emerging Players: ISO 17025 accreditation fast-track for potato cyst nematode qPCR protocols opens entry into Scottish seed potato certification and German export phytosanitary markets. Water quality monitoring for wastewater treatment operators presents the most penetrable white-space segment given limited incumbent specialization. Portable LAMP field kit deployment targeting remote agricultural cooperatives in Spain and Italy offers direct go-to-market access without centralized laboratory infrastructure investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed diversified testing conglomerates seeking geographic tuck-in acquisitions to complete pan-European coverage. Five-to-ten-year viability hinges on NGS capacity utilization rates and reference database completion for free-living nematode taxa. Acquisition targets should display GLP certification, in-house bioinformatics pipelines, and established distributor relationships. The signal to watch is EFSA regulatory acceptance standards for molecular data replacing morphology requirements.| Strategic Initiative | Industry Significance |
|---|---|
| NGS Capacity Expansion | Illumina platform deployment enables untargeted community profiling for biodiversity credit verification schemes. |
| Bioinformatics Pipeline Development | In-house data analysis capabilities differentiate SGS SA turnaround performance for ecological monitoring contracts. |
| GLP Certification Investment | Good Laboratory Practice accreditation opens biologicals registration support contracts with nematicide developers. |
| Digital Extension Integration | Farm management software connectivity creates recurring subscription revenue through advisory service bundling. |
| Portable LAMP Field Deployment | Handheld isothermal amplification compresses decision windows from weeks to hours for remote cooperative networks. |
Research Methodology
Operator-level perspectives from agricultural laboratory directors, certified nematode taxonomists, EFSA regulatory affairs specialists, and agrichemical distributor procurement managers anchored the qualitative base. Primary interviews combined with secondary validation from EU Plant Health Regulation implementation reports, EFSA surveillance guidance documents, USDA-APHIS nematicide re-registration reviews, and ISO 17025 accreditation databases. Bottom-up triangulation across service type, end user, application, and technology segmentation dimensions reconciled with top-down macroeconomic drivers.
Sensitivity analysis tested forecast robustness across alternative regulatory acceptance timelines for molecular data and varying capital investment assumptions for NGS platform deployment. Segmentation dimensions modeled include service type, end user sophistication tier, application maturity level, and technology platform across the projection horizon. CAGRs derived from historical volume trajectories, technology substitution curves, and regulatory mandate implementation schedules. Industry-specific inputs incorporated certified taxonomist retirement rates and qPCR assay commercialization timelines.
Decision-makers should treat outputs as directional under sustained EU F-Gas Regulation phasedown and Farm to Fork Strategy implementation assumptions; material deviation would warrant model refresh. Forecasts reflect these documented assumptions regarding regulatory acceptance standards and technology cost curves. Revision becomes warranted when EFSA molecular data recognition thresholds or Illumina sequencing platform pricing crosses inflection thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Testing Services
Plant Nutrient Testing Equipment Market
Agricultural Testing Services
Soil Field Testing Equipment Market
Agricultural Testing Services
Agricultural Testing Services Market
Agricultural Testing Services
Soil Sampling Services Market
Agricultural Testing Services
Poultry Diagnostic Testing Market
Agricultural Testing Services
Seed Testing Services Market
Agricultural Testing Services
North American Feed Testing Market
Agricultural Testing Services
Irrigation Testing Kit Market
Agricultural Testing Services
Feed Testing Market
Agricultural Testing Services
Testing, Inspection, and Certification for Agriculture & Food Market
Agricultural Testing Services
Europe Feed Testing Market
Agricultural Testing Services
Soil Erosion Testing Market
Agricultural Testing Services
Pesticide Detection Market
Agricultural Testing Services
Soil Testing Kit Market
Agricultural Testing Services
Plant Disease Diagnostic Market
Agricultural Testing Services
Pesticide Residue Testing Market