
 Agricultural Testing Services Market | 2026-2036
Agricultural Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Testing Services Market Outlook
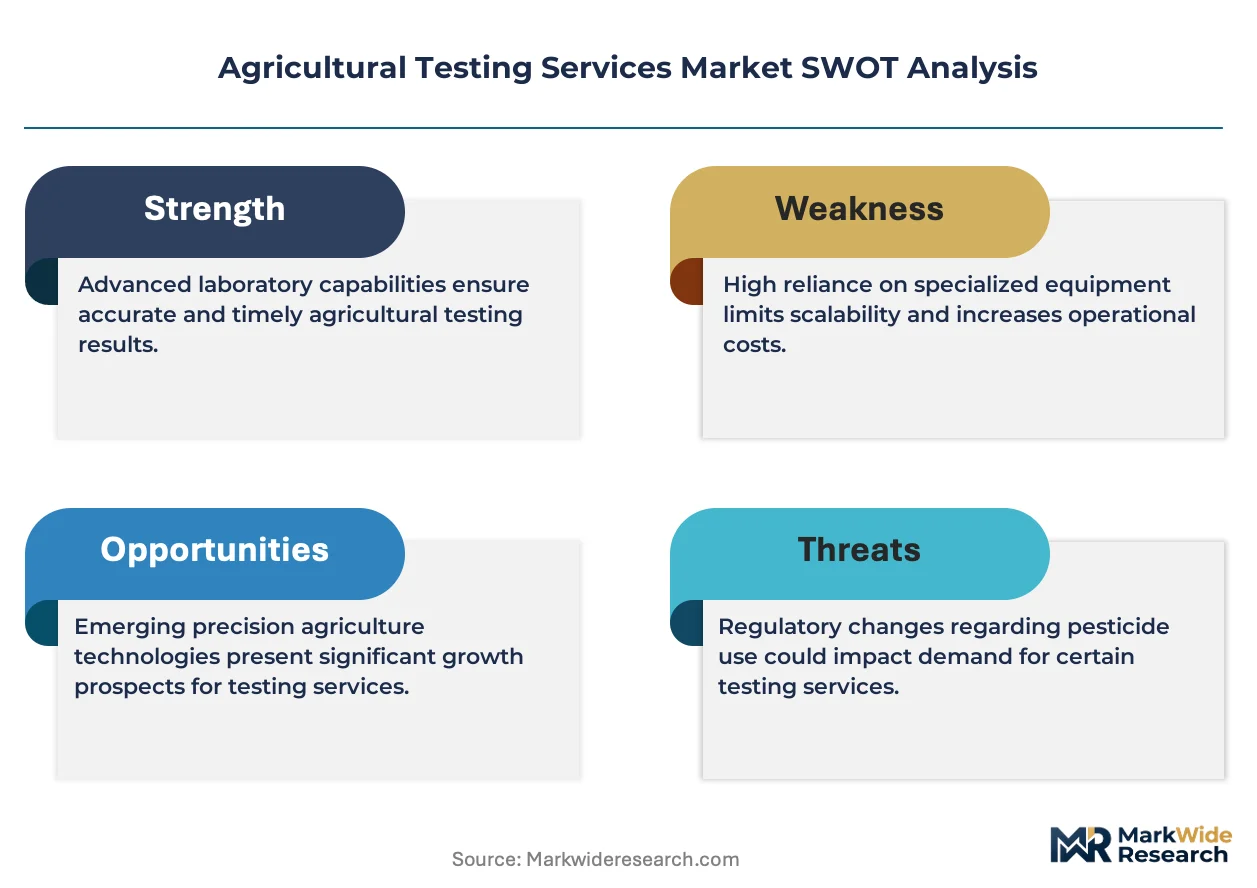
ISO/IEC 17025 accreditation is redrawing competitive boundaries in agricultural testing. Eurofins Scientific leverages its multi-continental laboratory network to sustain rapid turnaround times for pesticide residue panels. SGS anchors its position through backward integration into sampling logistics and digital chain-of-custody platforms. Bureau Veritas competes on regulatory breadth, maintaining certifications across FDA, EFSA, and multiple national agricultural ministries.
Agricultural testing services comprise analytical protocols that measure chemical, biological, and physical properties of farm inputs and outputs, employing chromatography, spectrometry, and molecular diagnostics to detect contaminants, nutrient profiles, and genetic purity with detection thresholds often reaching parts per billion. The primary commercial purpose is to verify compliance with buyer specifications, export phytosanitary requirements, and sustainability certifications before commodities enter downstream channels. Soil testing dominates service revenue due to recurring seasonal demand tied to planting cycles, while residue analysis commands premium pricing driven by tightening maximum residue limits in import markets. Laboratory analysis remains the structural core of the market, though remote sensing via satellite imagery and drone-mounted sensors is displacing visual inspection for large-scale crop health monitoring.
The EPA regulates pesticide tolerance levels in the United States under the Federal Insecticide, Fungicide, and Rodenticide Act, directly determining which residue tests laboratories must maintain in their accredited scopes. EFSA's scientific opinions on emerging contaminants cascade into binding EU-wide testing mandates that reshape laboratory investment priorities. Stakeholders must monitor divergence between Codex Alimentarius international standards and unilateral national limits, as this gap determines which laboratories can serve cross-border commodity flows without redundant testing.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing maximum residue limits and mandating nutrient management protocols, forcing laboratories to retool analytical platforms for higher throughput at lower detection thresholds. This regulatory compression is the dominant structural force reshaping investment priorities across soil, tissue, and commodity testing workflows.
Growth Catalysts
- Retailer sustainability mandates:Seed companies and contract farming operations are expanding testing protocols to verify compliance with buyer specifications before commodities enter downstream channels.
- Precision agriculture diffusion:Brazil's Mato Grosso soybean belt is driving soil and tissue sampling volumes as variable-rate input application becomes standard practice.
- ISO/IEC 17025 accreditation pressure:Cross-border commodity flows require laboratories to maintain internationally recognized quality standards, consolidating demand toward certified providers.
Market Restraints
- Helium supply volatility:Gas chromatography-mass spectrometry systems depend on helium carrier gas, with price spikes and allocation constraints disrupting laboratory operations.
- Accreditation concentration:Competent assessor availability is geographically clustered in Western Europe and North America, creating bottlenecks for laboratories in Latin America and Southeast Asia seeking initial certification.
- Codex-national divergence:Gaps between Codex Alimentarius international standards and unilateral national limits force redundant testing for cross-border shipments, inflating compliance costs.
Strategic Opportunities
- Drone-mounted sensor integration:Remote sensing platforms are creating white space between laboratory analysis and field-level monitoring, enabling real-time crop health assessment at scale.
- Digital chain-of-custody platforms:Blockchain-integrated sampling logistics are reducing disputes over sample integrity, opening premium pricing for end-to-end service bundles.
- India's FSSAI expansion:The Food Safety and Standards Authority of India is tightening pesticide residue surveillance on imported agricultural commodities, creating demand for accredited testing capacity near major ports.
Industry Challenges
- Analytical chemist scarcity:Mass spectrometry and chromatography expertise is concentrated among retiring specialists, constraining laboratory expansion timelines.
- Multi-jurisdiction certification complexity:Laboratories serving export markets must simultaneously maintain EPA, EFSA, and FDA scopes, requiring dedicated regulatory affairs functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Testing Services Market |
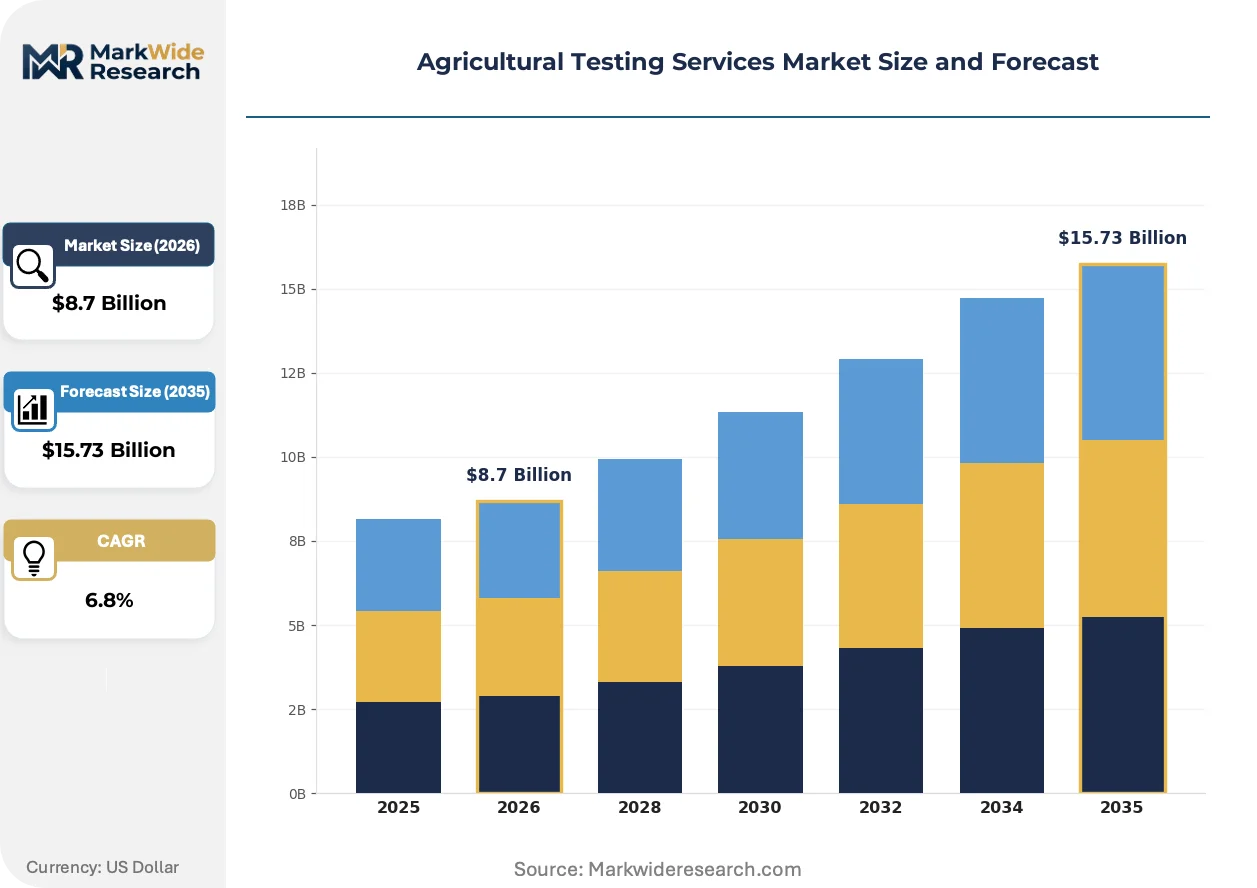
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Soil Testing, Crop Testing, Water Quality Testing, Residue Analysis Testing Method: Laboratory Analysis, Field Testing, Remote Sensing, Visual Inspection End Use Industry: Agriculture, Horticulture, Aquaculture, Viticulture Sample Type: Soil Samples, Plant Samples, Water Samples, Seed Samples |
| Companies Covered | SGS, Eurofins Scientific, Intertek Group, Bureau Veritas, ALS Limited, TUV Nord Group, bioMérieux, RJ Hill Laboratories Limited, Element Materials Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Testing Services Market Strategic Shifts
Technological convergence between laboratory instrumentation and field-deployable sensors is redrawing the boundary between centralized analysis and distributed monitoring. This shift is compressing turnaround expectations while expanding the addressable market for rapid screening methods.
High-resolution mass spectrometry is fragmenting the residue analysis market by enabling non-targeted screening for unknown metabolites and transformation products. Large-scale grain handlers and oilseed processors are adopting these platforms to preempt regulatory surprises in export shipments. The technology is fragmenting incumbent competitive positions by lowering the analytical expertise threshold required to operate advanced detection systems.
EFSA's systematic re-evaluation of existing active substances is triggering cascading testing mandate revisions across EU member states. Laboratories must continuously update validated methods as scientific opinions downgrade established tolerances. Specialty crop exporters in Southern Europe and North Africa are responding by pre-positioning dual-method capabilities to cover both current and anticipated limit structures.
Buyer concentration among multinational food retailers is compressing testing service procurement cycles from annual contracts to campaign-based arrangements tied to harvest windows. Laboratories are unbundling fixed-cost retainers in favor of variable pricing indexed to sample volume commitments. This behavioral shift is most pronounced in the Netherlands and Germany, where centralized procurement functions at retail cooperatives dictate laboratory selection across supplier networks.
Agricultural Testing Services Market Segmentation
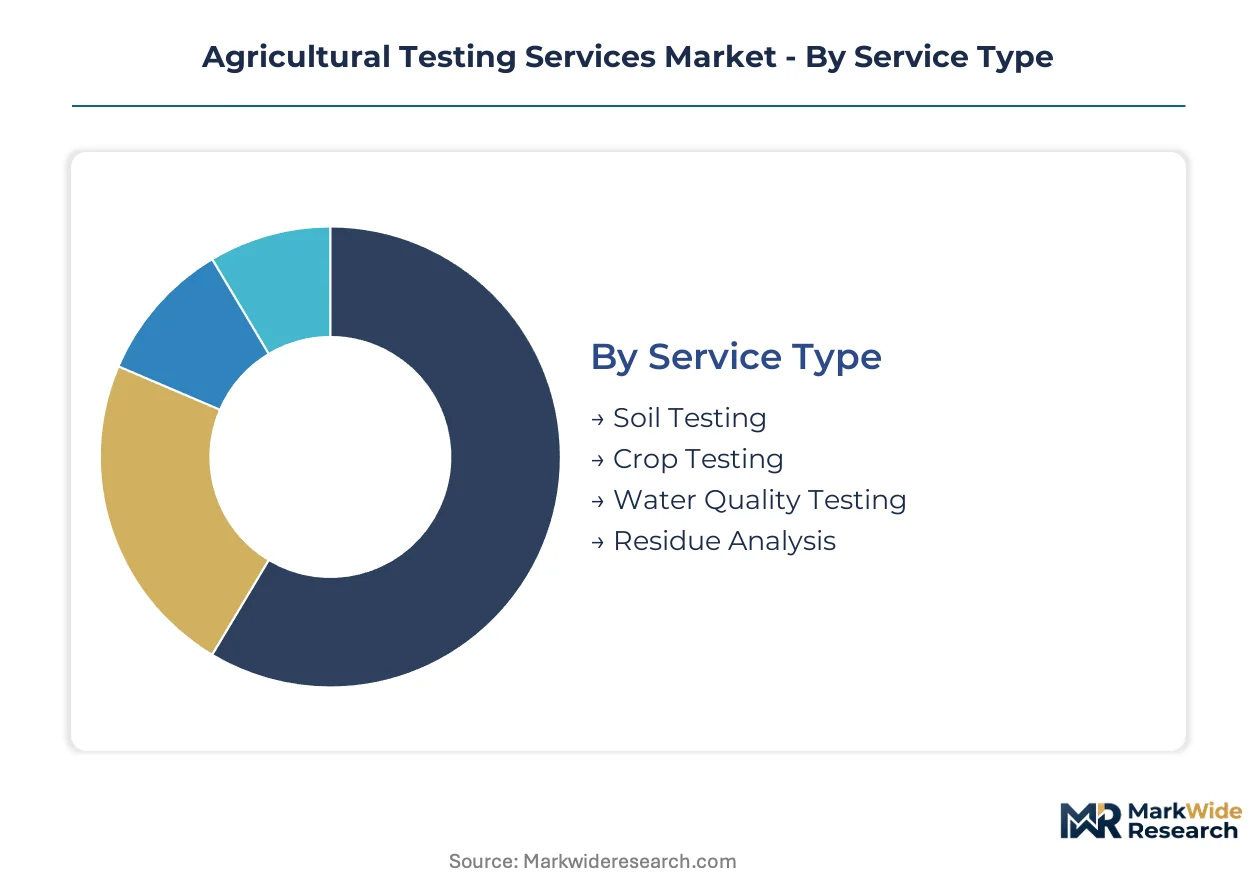
Agricultural testing services fragment across service modalities, analytical platforms, and commodity flows. Each segmentation axis reveals distinct margin structures and geographic demand patterns that reshape laboratory investment priorities.
Service Type:
Domestic consumption patterns concentrate in soil and crop testing, while residue analysis serves export-led commodity chains requiring phytosanitary clearance.
- Soil Testing:Analytical protocols measure macronutrient availability, pH balance, and micronutrient deficiencies to guide variable-rate fertilizer application. Demand concentrates in Brazil's Mato Grosso soybean belt and the US Corn Belt, where precision agriculture adoption drives recurring seasonal sampling tied to planting cycles. This segment commands the largest revenue share due to predictable annual demand from commercial farming operations.
- Residue Analysis:Chromatographic and mass spectrometry methods detect pesticide metabolites and veterinary drug traces at parts-per-billion thresholds. Export-oriented grain handlers in Argentina and Ukraine require these services to meet EU EFSA and US EPA tolerance standards before shipment. Tightening maximum residue limits under the EU Green Deal's Farm to Fork strategy are expanding method portfolios.
- Crop Testing:Tissue sampling and grain quality assessment verify nutrient uptake and mycotoxin contamination. Large-scale cooperatives in Germany and France use these services to optimize harvest timing and storage decisions.
- Water Quality Testing:Irrigation source monitoring and runoff assessment for nitrate and pathogen loads. Intensive livestock regions in Denmark and the Netherlands require compliance testing under national water framework directives.
Soil testing holds the largest share; momentum sits with residue analysis as regulatory compression accelerates.
Testing Method:
Cost structures diverge sharply between capital-intensive laboratory platforms and distributed field-deployable technologies.
- Laboratory Analysis:Centralized facilities employ gas chromatography-mass spectrometry and high-performance liquid chromatography for definitive quantitative results. ISO/IEC 17025 accreditation requirements concentrate demand toward certified providers with multi-jurisdiction scopes. This segment absorbs the majority of capital investment due to instrumentation costs and specialist chemist requirements.
- Remote Sensing:Satellite imagery and drone-mounted multispectral sensors enable real-time crop health monitoring across large landholdings. Brazilian soybean operations and Australian wheat belts are adopting these platforms to prioritize ground-truthing locations. The technology is displacing visual inspection for acreage-scale assessment.
- Field Testing:Portable spectrophotometers and test kits deliver rapid on-site screening for macronutrients and moisture content. Smallholder cooperatives in India and Kenya use these methods to reduce logistics costs before laboratory confirmation.
- Visual Inspection:Manual assessment of pest damage, disease symptoms, and physical grain defects. This method persists in developing markets with limited laboratory access but is losing share to sensor-based alternatives.
Laboratory analysis dominates revenue; remote sensing is climbing the fastest as precision agriculture diffuses.
End Use Industry:
Customer sophistication varies across commodity systems, with viticulture and aquaculture commanding premium pricing for specialized method portfolios.
- Agriculture:Broadacre grain and oilseed operations requiring soil, tissue, and commodity testing at scale. US Midwest row-crop farmers and Brazilian soybean producers represent the core volume base.
- Horticulture:Protected cultivation of vegetables and fruits with intensive nutrient management and food safety protocols. Dutch greenhouse operators and Spanish Almería cluster demand high-frequency water and substrate analysis.
- Viticulture:Vineyard soil mapping and grape quality assessment for terroir verification and export certification. Bordeaux and Napa Valley wineries require residue testing for EU and US market access.
- Aquaculture:Water quality monitoring and pathogen screening for intensive fish and shellfish production. Norwegian salmon farms and Vietnamese pangasius operations require continuous environmental parameter tracking.
Agriculture holds the largest share; momentum sits with aquaculture as marine protein demand intensifies.
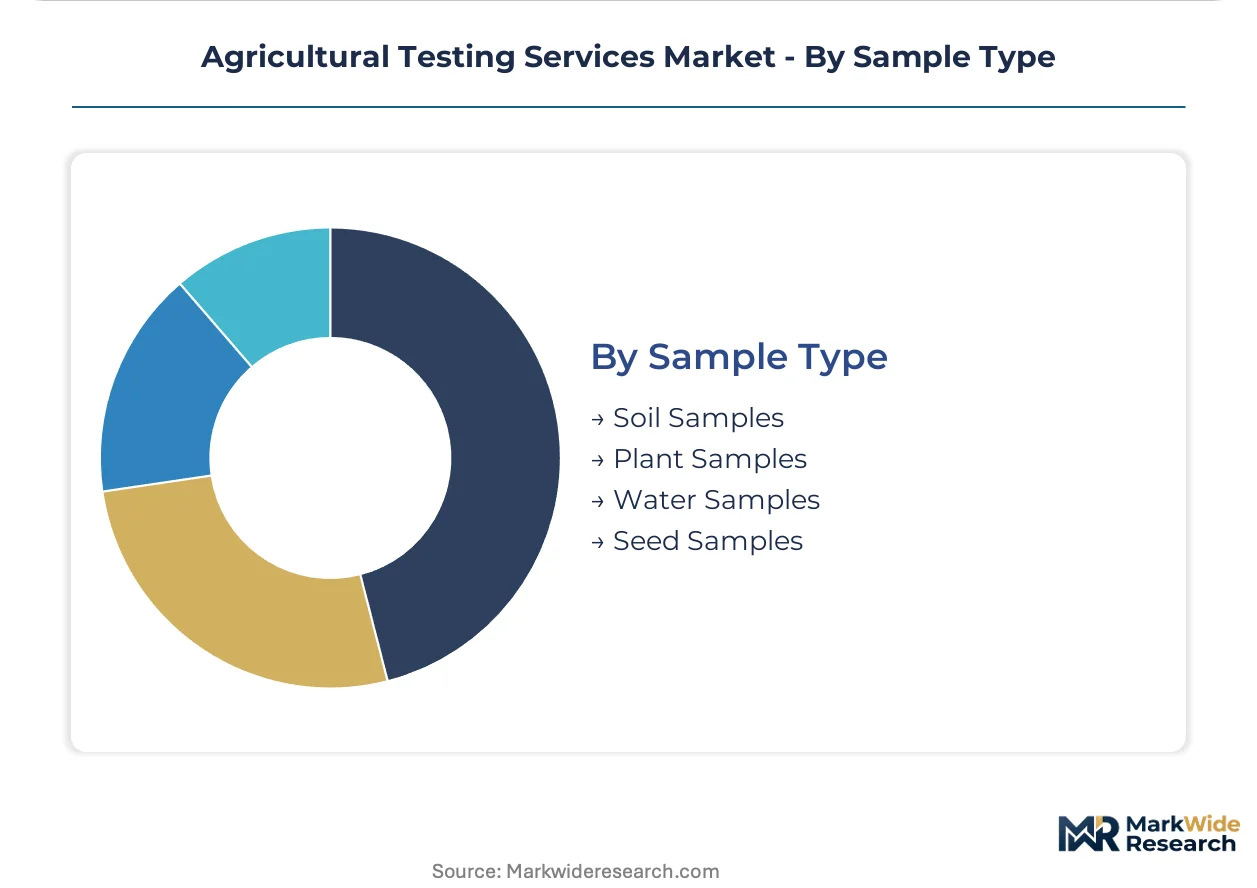
Sample Type:
Logistics complexity and chain-of-custody requirements differ materially across matrix types, shaping laboratory network configuration.
- Soil Samples:Core and composite sampling for chemical and physical property analysis. Seasonal collection windows in temperate zones create peak demand periods requiring temporary capacity expansion.
- Plant Samples:Leaf tissue and whole-plant material for nutrient status and disease diagnosis. Viticulture and horticulture operations require rapid turnaround during critical growth stages.
- Water Samples:Irrigation, drainage, and processing water for chemical and microbiological parameters. Perishable holding times constrain transport distances to laboratory facilities.
- Seed Samples:Genetic purity, germination rate, and pathogen testing for certification and commercial sale. Seed company R&D stations in Iowa and Hyderabad require specialized molecular diagnostic capabilities.
Soil samples hold the largest share; plant samples are gaining share fastest as precision nutrient management expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational grain traders and seed companies concentrate procurement decisions in four national markets that together absorb the majority of accredited testing volumes. Laboratory networks align capacity expansion with these buyer footprints.
United States
EPA tolerance enforcement under FIFRA drives residue panel demand from corn and soybean exporters in Iowa and Illinois. The Department of Agriculture's commodity grading standards mandate mycotoxin screening for interstate grain shipments. St. Louis and Minneapolis anchor private laboratory clusters serving Mississippi River grain terminals.
Brazil
Mato Grosso soybean belt operations require ISO/IEC 17025 certification for EU-bound commodity exports under EFSA-aligned phytosanitary protocols. MAPA's national residue monitoring program expands laboratory accreditation requirements annually. Rondonópolis and Sorriso host sampling logistics hubs coordinating pre-harvest tissue analysis.
Germany
Retail cooperative procurement centralization in Lower Saxony compresses testing contract cycles to campaign-based arrangements. The EU Green Deal's Farm to Fork strategy mandates nutrient management verification for imported feedstocks. Hamburg laboratories specialize in transshipment cargo screening for Black Sea grain.
India
FSSAI's tightening pesticide surveillance on imported pulses and oilseeds creates demand near Nhava Sheva and Mundra ports. APEDA export certification requirements drive laboratory accreditation among spice processors in Kerala and Gujarat. Hyderabad seed company R&D stations require genetic purity testing for hybrid cotton and rice varieties.
Netherlands
Greenhouse horticulture clusters in Westland demand high-frequency water and substrate analysis for nutrient recirculation compliance. NVWA enforcement of EU residue limits shapes method validation priorities for vegetable exporters. Wageningen University laboratories anchor public-private research partnerships in molecular diagnostics.
Agricultural Testing Services Market Competitive Environment
Player mix skews toward diversified inspection conglomerates with multi-jurisdiction accreditation scopes. Laboratory networks concentrate in Western Europe and North America, with emerging capacity in Brazil and India following commodity flow patterns. Three archetypes dominate: integrated inspection giants, specialized agricultural laboratories, and seed company captive facilities. Consolidation proceeds through accreditation scope expansion and sampling logistics integration rather than price competition.
Among diversified testing conglomerates, SGS exemplifies backward integration into chain-of-custody logistics, while Eurofins Scientific occupies a position anchored in high-throughput chromatography capacity. Bureau Veritas represents the regulatory breadth archetype, maintaining simultaneous FDA, EFSA, and national ministry certifications. These three entities collectively illustrate how multi-continental laboratory networks defend margin position through turnaround time compression and method portfolio breadth.
| Leading Market Players |
|---|
| SGS |
| Eurofins Scientific |
| Intertek Group |
| Bureau Veritas |
| ALS Limited |
| TUV Nord Group |
| bioMérieux |
| RJ Hill Laboratories Limited |
| Element Materials Technology |
| Others |
Value Chain & Pricing Dynamics
Fourteen-day analytical turnaround requirements in Brazil's Mato Grosso soybean belt concentrate pricing power among ISO/IEC 17025-accredited laboratories with established sampling logistics networks, compressing margins for providers without backward integration into chain-of-custody platforms.
Pricing Analysis
Cost-plus contracts indexed to helium carrier gas spot markets dominate residue analysis pricing, with laboratories passing through volatility to grain handlers and seed companies. Price differentiation separates rapid-turnaround premium panels from standard batch processing, while contract farming operations exhibit highest price sensitivity due to thin operating margins. Cost compression in standard soil testing intensifies as satellite-based remote sensing displaces low-complexity laboratory work.
Supply Chain Analysis
Just-in-time helium procurement strategies prevail among chromatography-dependent laboratories, with strategic stockpiling constrained by storage economics and shelf-life limitations. Instrumentation supply concentrates in Germany, Japan, and the United States, while reagent sourcing draws from specialized chemical manufacturers in Switzerland and the Netherlands. Single-source vulnerability in helium extraction—anchored in Qatar, Algeria, and Russia—creates allocation risk during geopolitical disruptions. Distribution runs through accredited sampling logistics hubs positioned near major grain terminals in Rondonópolis, St. Louis, and Hamburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among multinational grain traders and retail procurement cooperatives, with three conglomerates now controlling testing vendor selection across supplier networks in Germany and the Netherlands.
For Market Incumbents: Shield accreditation scope breadth against emerging drone-mounted sensor providers by embedding chromatography expertise into digital chain-of-custody platforms. Prioritize capacity addition in Brazil's interior to capture pre-harvest tissue sampling volumes before precision agriculture adoption accelerates. Defensive consolidation through sampling logistics integration preserves margin position against price-pressured standard testing commoditization. For New Entrants and Emerging Players: Lead with portable spectrophotometer field testing for smallholder cooperatives in India and Kenya, where laboratory infrastructure gaps create white space between centralized analysis and visual inspection. India's FSSAI port surveillance expansion offers the most penetrable geography for accredited residue testing capacity. Go-to-market positioning should emphasize rapid on-site screening bundled with laboratory confirmation workflows. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across high-resolution mass spectrometry platforms as non-targeted screening becomes standard for export grain handlers. Long-term viability favors laboratories with multi-jurisdiction EPA-EFSA-FDA scopes capable of serving cross-border commodity flows without redundant testing. Acquisition targets should demonstrate assessor relationships in Western Europe or North America to bypass accreditation bottlenecks. The signal to watch is helium allocation priority shifts among major gas suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sampling Logistics | SGS and Eurofins compress turnaround times by controlling chain-of-custody from field to laboratory. |
| High-Resolution Mass Spectrometry Adoption | Grain handlers in Argentina and Ukraine preempt regulatory surprises from EFSA tolerance revisions. |
| Drone-Mounted Sensor Deployment | Brazilian soybean operations prioritize ground-truthing locations, displacing visual inspection at scale. |
| Multi-Jurisdiction Accreditation Expansion | Bureau Veritas maintains simultaneous FDA, EFSA, and MAPA scopes for cross-border service eligibility. |
| Digital Chain-of-Custody Platform Development | Blockchain-integrated sampling logistics reduce disputes and enable premium pricing for end-to-end bundles. |
Study Parameters
Desk research of EPA tolerance databases, EFSA scientific opinions, MAPA residue monitoring reports, and ISO/IEC 17025 accreditation registries preceded structured interviews with laboratory operations directors, seed company regulatory affairs managers, grain handler procurement leads, and precision agriculture technology specialists. Secondary validation drew from customs trade data, seed industry association filings, and agricultural ministry surveillance disclosures. Bottom-up sample volume estimates triangulated against top-down market sizing from instrumentation manufacturer shipment records.
Variance decomposition across service type, testing method, and end-use industry segments structured the analytical framework over the projection horizon. CAGRs derived from regression against precision agriculture adoption curves, EU Green Deal implementation timelines, and FSSAI surveillance expansion patterns. Modeled inputs included seasonal sampling intensity in temperate zones, helium price volatility bands, and assessor availability constraints in Latin America and Southeast Asia.
Forecasts assume regulatory continuity in EPA FIFRA enforcement, EFSA Farm to Fork tolerance compression, and FSSAI import surveillance tightening; material policy shifts would require re-modeling. Revision becomes warranted when helium allocation thresholds trigger laboratory operational disruptions or when Codex-national divergence gaps force redundant testing mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Testing Services
Asia Pacific Feed Testing Market
Agricultural Testing Services
Plant Nutrient Testing Equipment Market
Agricultural Testing Services
North American Feed Testing Market
Agricultural Testing Services
Agrochemicals Testing and Inspection Service Market
Agricultural Testing Services
Pesticide Detection Market
Agricultural Testing Services
Seed Testing Services Market
Agricultural Testing Services
Impact Soil Tester Market
Agricultural Testing Services
Soil Field Testing Equipment Market
Agricultural Testing Services
Global Agriculture Testing Services Market
Agricultural Testing Services
Rapid Mycotoxin Detection Systems for Grain Handling Facilities Market
Agricultural Testing Services
Irrigation Testing Kit Market
Agricultural Testing Services
Soil Testing Kit Market
Agricultural Testing Services
Soil Erosion Testing Market
Agricultural Testing Services
Poultry Diagnostic Testing Market
Agricultural Testing Services
Europe Feed Testing Market
Agricultural Testing Services
Feed Testing Market