
 Soil Field Testing Equipment Market | 2026-2036
Soil Field Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Soil Field Testing Equipment Market Outlook
A shortage of certified geotechnical field technicians is collapsing project timelines across infrastructure and environmental remediation sites. Humboldt Mfg. Co. dominates North American distribution through its deep catalog of ASTM-compliant penetrometers and shear strength apparatus. ELE International anchors European demand with manufactured-in-Italy calibration systems that serve CE-marked compliance workflows. Thermo Fisher Scientific Inc. extends its laboratory pedigree into field-portable ion-selective electrodes for soil chemistry analysis.
Soil field testing equipment comprises portable instruments that measure in-situ mechanical, chemical, and hydrological parameters—typically operating across temperature ranges of minus 10 to 50 degrees Celsius with IP65-rated enclosures for dust and moisture ingress protection. These devices enable real-time decision-making in construction bearing-capacity verification, agricultural fertility mapping, and contaminated land assessment without laboratory transit delays. Moisture sensors and digital pH meters occupy the largest product volume tiers due to universal deployment across agronomy and land development applications. Wireless technology segments are pulling fastest growth as Bluetooth-enabled probes eliminate manual data transcription errors in large-scale soil remediation projects. Agricultural producers represent the deepest end-user margin pool where subscription-linked sensor networks create recurring calibration revenue streams.
The US EPA enforces Method 9045D for soil pH measurement in Superfund site characterization, directly specifying electrode precision thresholds that filter non-compliant device vendors from federal procurement channels. ASTM International and ISO 11277 together govern particle-size distribution and soil texture classification protocols that shape equipment design specifications for export-market access. China's MEE soil pollution prevention law and India's BIS certification requirements for agricultural testing instruments are tightening cross-border product conformity obligations. Stakeholders must monitor evolving interoperability standards between proprietary wireless protocols and open-field data platforms before committing to hardware refresh cycles.
Market Dynamics
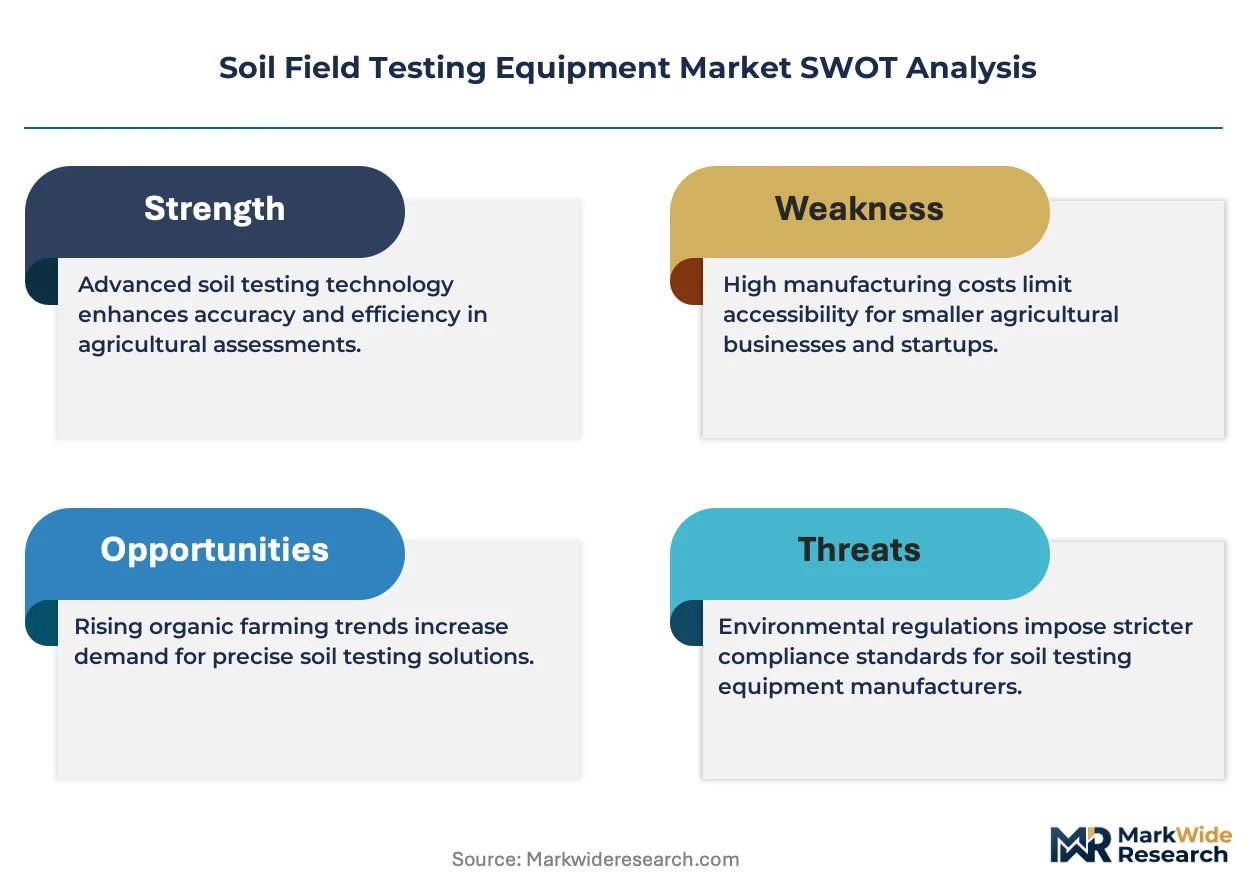
The European Union's F-Gas Regulation is compressing refrigerant-dependent calibration systems while wireless sensor networks pull capital toward subscription-based soil monitoring platforms.
Growth Catalysts
- EU Green Deal soil health targets:Mandatory soil carbon monitoring creates procurement pull for portable conductivity meters and digital penetrometers across German and Dutch agricultural clusters.
- Bluetooth-enabled probe adoption:Construction and remediation contractors eliminate manual transcription errors in large-scale soil characterization projects through wireless data capture.
- India's BIS certification expansion:Agricultural testing instrument mandates open distribution channels for pH meters and moisture sensors in state-led soil health card programs.
Market Restraints
- Certified geotechnical technician shortage:Infrastructure and environmental remediation sites face collapsed project timelines due to insufficient qualified field personnel.
- ASTM/ISO compliance costs:Dual certification requirements for particle-size distribution apparatus filter smaller vendors from export-market access.
- Laboratory-grade portable substitutes:Ion-selective electrode miniaturization threatens standalone field device margins in soil chemistry analysis.
Strategic Opportunities
- China's MEE soil pollution prevention enforcement:Contaminated land assessment mandates create demand for heavy metals detection kits in industrial corridor remediation.
- Sensor-as-a-service models:Recurring calibration revenue streams from subscription-linked agricultural networks displace one-time hardware sales.
- Open-field data platform interoperability:Proprietary wireless protocol integration with standardized cloud architectures reduces buyer lock-in risk.
Industry Challenges
- IP65 enclosure manufacturing scale-up:Dust and moisture ingress protection ratings require capital-intensive production lines for minus 10 to 50 degrees Celsius operating ranges.
- US EPA Method 9045D precision thresholds:Electrode specification compliance creates extended certification timelines for pH meter vendors seeking federal procurement eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soil Field Testing Equipment Market |
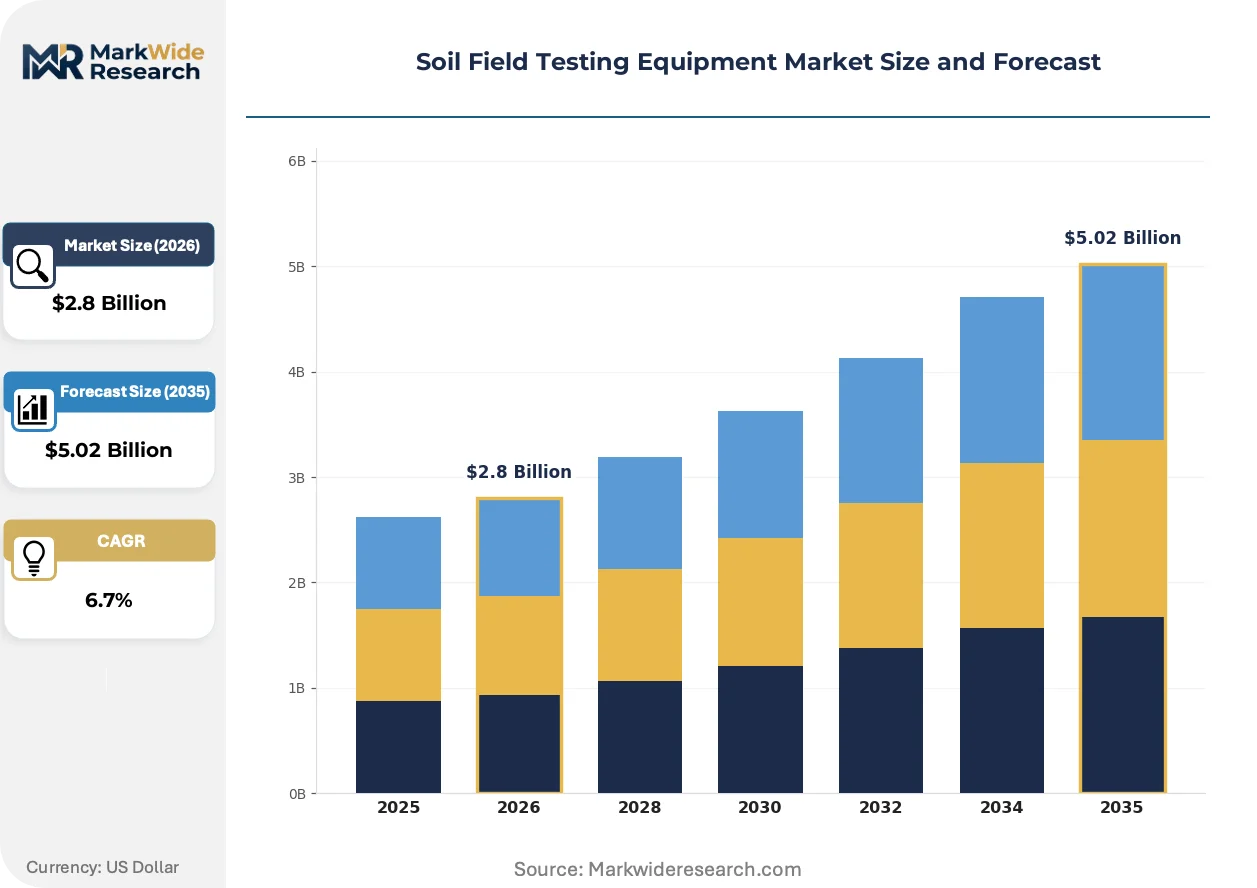
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: pH Meters, Moisture Sensors, Penetrometers, Electrical Conductivity Meters End User: Agricultural Producers, Environmental Consultants, Construction Companies, Research Institutions Technology: Digital, Analog, Wireless, Portable Application: Agronomy, Horticulture, Soil Remediation, Land Development |
| Companies Covered | Humboldt Mfg. Co., ELE International, Controls S.p.A, Agilent Technologies, Thermo Fisher Scientific Inc., PerkinElmer Inc., Merck KGaA, Gilson Company Inc., LaMotte Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soil Field Testing Equipment Market Strategic Shifts
Wireless telemetry and edge computing are compressing the gap between field measurement and real-time agronomic decision support systems.
LoRaWAN connectivity is fragmenting traditional data logger architectures in soil moisture monitoring. Large-scale farming cooperatives in the US Corn Belt deploy mesh-networked probes at accelerating density. This topology is fragmenting vendor control over data infrastructure as open-protocol adoption rises.
REACH substance restrictions on cadmium and lead in electrodes are forcing reformulation of ion-selective sensor membranes. European equipment makers accelerate ceramic-based alternative development to maintain CE-marked access. pH testing kit suppliers face compressed margin structures from raw material substitution costs.
Service unbundling is separating hardware ownership from calibration maintenance in agricultural procurement. Dealer networks in Germany's horticulture clusters now offer per-hectare monitoring subscriptions. This model is most visible where federal soil protection ordinances mandate annual testing frequency.
Soil Field Testing Equipment Market Segmentation
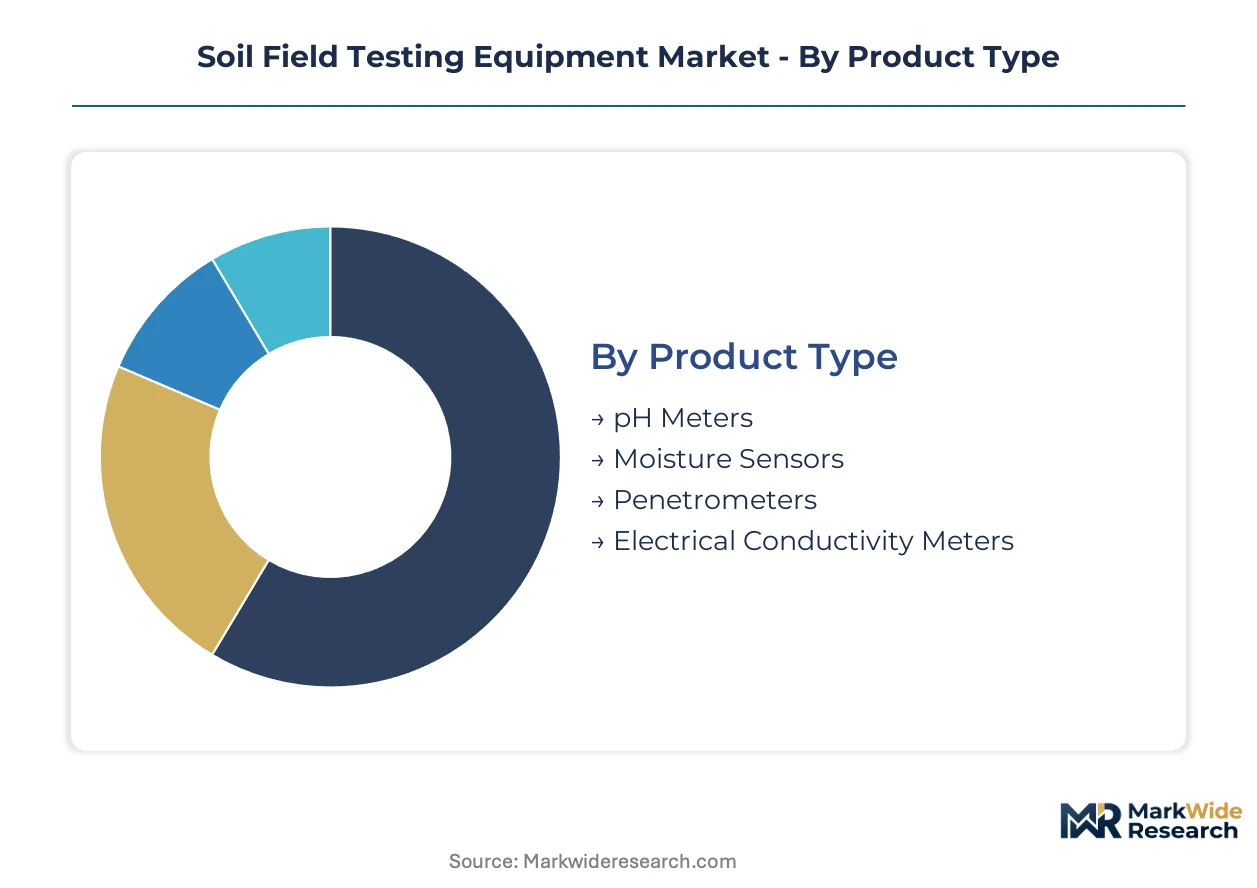
Equipment segmentation in soil field testing reveals distinct procurement patterns shaped by regulatory compliance tiers and operational intensity. Buyers select instrument categories based on whether their workflows demand laboratory-grade precision or rapid field-screening capability.
Product Type:
ASTM Method 9045D electrode precision thresholds and EU F-Gas calibration requirements create divergent certification burdens across instrument categories.
- pH Meters:Ion-selective electrode assemblies with glass or antimony sensor membranes deliver 0.01 pH resolution for contaminated land assessment. US EPA Superfund site characterization mandates directly specify these precision thresholds, filtering non-compliant vendors from federal procurement channels.
- Moisture Sensors:Capacitance, tensiometric, and time-domain reflectometry probes measure volumetric water content across minus 10 to 50 degrees Celsius operating ranges. German federal soil protection ordinances drive dense deployment in Rhine Valley horticulture clusters where irrigation optimization commands premium sensor density.
- Penetrometers:Handheld and digital cone penetration devices assess soil compaction and bearing capacity for construction verification.
- Electrical Conductivity Meters:Four-electrode and electromagnetic induction systems map salinity and nutrient distribution in precision agriculture.
Moisture sensors handle the majority of throughput; pH meters are gaining share fastest on the back of remediation liability expansion.
End User:
Procurement scale and calibration frequency separate high-volume subscription buyers from intermittent equipment purchasers.
- Agricultural Producers:Large-scale farming cooperatives in the US Corn Belt deploy mesh-networked probes at accelerating density. Subscription-linked sensor networks generate recurring calibration revenue streams that displace one-time hardware transactions.
- Environmental Consultants:Firms conducting contaminated land assessment face compressed project timelines from certified geotechnical technician shortages. Bluetooth-enabled data loggers eliminate manual transcription errors in large-scale soil characterization workflows.
- Construction Companies:Bearing-capacity verification at foundation sites drives demand for portable shear strength apparatus.
- Research Institutions:University and government laboratories require ASTM/ISO dual-certified particle-size distribution equipment for publication-grade data.
Agricultural producers dominate absolute volume; environmental consultants show the steepest expansion trajectory from soil pollution enforcement.
Technology:
Wireless protocol adoption is fragmenting traditional data logger architectures and reshaping vendor control over field infrastructure.
- Digital:Microprocessor-controlled instruments with onboard data storage and LCD readouts. REACH substance restrictions on cadmium and lead in electrodes force ceramic-based membrane reformulation for CE-marked European access.
- Wireless:Bluetooth and LoRaWAN-enabled probes transmit measurements directly to cloud platforms. Open-protocol adoption rises as farming cooperatives resist proprietary lock-in.
- Analog:Mechanical dial gauges and manual reading systems persist in price-sensitive developing markets.
- Portable:Battery-operated, IP65-rated enclosures designed for field deployment without laboratory transit.
Digital technology anchors current installed base; wireless platforms are climbing the fastest on interoperability standardization.
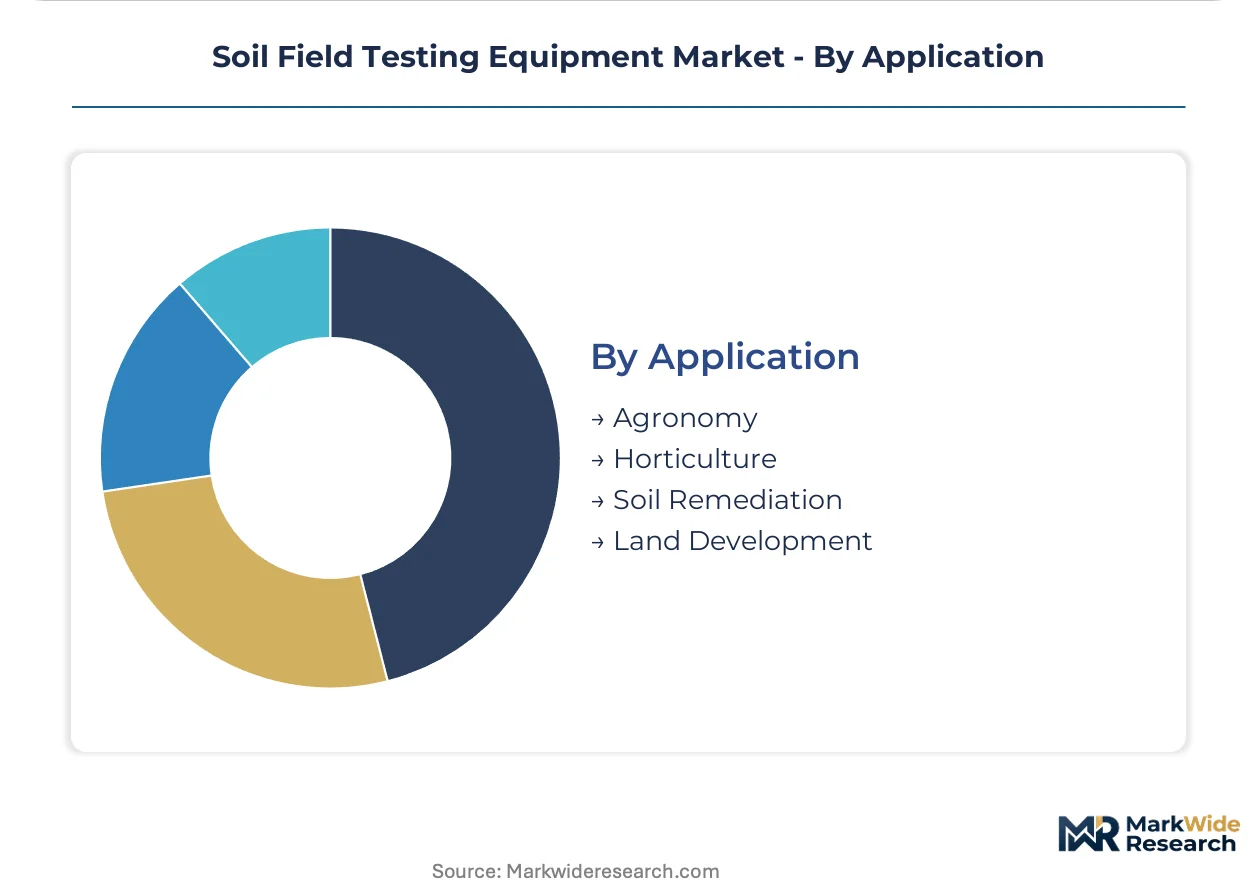
Application:
Regulatory monitoring mandates versus voluntary optimization programs create divergent pricing power across use cases.
- Agronomy:Broad-acre fertility mapping and variable-rate input management. India's BIS certification expansion for agricultural testing instruments opens distribution channels through state-led soil health card programs.
- Soil Remediation:Heavy metals detection and contaminant plume delineation at industrial corridor sites. China's MEE soil pollution prevention law creates procurement pull for field-portable detection kits.
- Horticulture:Intensive greenhouse and nursery operations in Dutch and German clusters demand high-frequency pH and conductivity monitoring.
- Land Development:Pre-construction bearing capacity and drainage assessment for commercial and residential projects.
Agronomy generates the deepest recurring revenue pools; soil remediation is expanding most quickly on regulatory enforcement timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German horticulture clusters deploy conductivity meters at triple the density of Brazilian soybean operations, reflecting divergent regulatory pressure and subsidy structures across agricultural geographies.
United States
US Corn Belt farming cooperatives mesh-network soil probes at accelerating density. EPA Method 9045D precision thresholds filter non-compliant pH meter vendors from federal Superfund procurement channels. Bluetooth-enabled data loggers eliminate transcription errors across large-scale soil characterization projects in the Midwest.
Germany
Federal soil protection ordinances mandate annual testing frequency across Rhine Valley horticulture clusters. EU F-Gas Regulation compresses refrigerant-dependent calibration system designs while Green Deal soil health targets create procurement pull for digital penetrometers. Dealer networks now offer per-hectare monitoring subscriptions in Baden-Württemberg and Lower Saxony.
China
MEE soil pollution prevention enforcement drives contaminated land assessment mandates across industrial corridors. Heavy metals detection kits face tightening cross-border conformity obligations under national environmental law. Yangtze River Delta remediation contractors deploy field-portable ion-selective electrodes for real-time plume delineation.
India
BIS certification expansion for agricultural testing instruments opens distribution through state-led soil health card programs. Subsidy-linked moisture sensor procurement concentrates in Maharashtra and Gujarat wheat belts. Variable-rate input management pilots in Punjab and Haryana pull capital toward subscription-based monitoring platforms.
Netherlands
Intensive greenhouse operations in the Randstad demand high-frequency pH and electrical conductivity monitoring. CE-marked compliance workflows favor Italian-manufactured calibration systems for particle-size distribution protocols. Dutch precision agriculture clusters deploy LoRaWAN-enabled probes to resist proprietary vendor lock-in.
Soil Field Testing Equipment Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the upper stratum controlling ASTM and ISO certification pipelines while mid-scale players compete on regional compliance agility. The market structure rewards dual-certified particle-size distribution apparatus vendors with export-market access while filtering smaller fabricators from federal procurement channels. Two strategic archetypes dominate: laboratory pedigree extenders leveraging portable ion-selective electrode miniaturization, and agricultural subscription platforms capturing recurring calibration revenue. Competitive moves concentrate on sensor-as-a-service model unbundling and open-protocol interoperability integration.
Among North American distribution anchors, Humboldt Mfg. Co. exemplifies the ASTM-compliant apparatus archetype, while Thermo Fisher Scientific Inc. occupies a position representing laboratory-to-field technology extension. ELE International anchors the European manufactured-in-Italy calibration tier serving CE-marked compliance workflows. These three entities collectively represent the geographic and certification-axis segmentation that shapes procurement channel access across divergent regulatory environments.
| Leading Market Players |
|---|
| Humboldt Mfg. Co. |
| ELE International |
| Controls S.p.A |
| Agilent Technologies |
| Thermo Fisher Scientific Inc. |
| PerkinElmer Inc. |
| Merck KGaA |
| Gilson Company Inc. |
| LaMotte Company |
| Others |
Value Chain & Pricing Dynamics
REACH substance restrictions on cadmium and lead in ion-selective electrodes are forcing ceramic-based membrane reformulation across European supply chains, simultaneously shifting procurement geography toward Italian calibration specialists and compressing margin structures for pH testing kit suppliers facing raw material substitution costs.
Pricing Analysis
Contract structures in soil field testing equipment favor project-based procurement for construction verification and subscription-linked arrangements for agricultural sensor networks. Three-tier pricing structure across ASTM/ISO dual-certified premium apparatus, CE-marked standard instruments, and economy analog devices reflects certification investment recovery timelines. Cost compression in entry-level pH meters is intensifying because REACH-compliant ceramic membrane development requires capital-intensive R&D. Agricultural cooperatives deploying mesh-networked probes show the least price sensitivity due to recurring calibration revenue lock-in, while intermittent environmental remediation contractors purchasing portable penetrometers negotiate aggressively on unit economics.
Supply Chain Analysis
Strait of Hormuz transit risk underwrites shipping cost volatility for antimony and glass sensor membrane precursors sourced from East Asian refiners. Manufacturing concentration clusters in Germany for precision-calibrated digital penetrometers, Italy for CE-marked calibration systems, and the United States for ASTM-compliant shear strength apparatus. Component dependencies include ion-selective glass membranes, ceramic sensor substrates, and IP65-rated enclosure polymers. Single-source vulnerability sits with Italian-manufactured calibration equipment serving EU Green Deal soil health monitoring mandates. Distribution runs through authorized dealer networks in horticulture clusters and direct federal procurement channels for Superfund site characterization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Soil field testing equipment sits in early-cycle expansion as wireless telemetry adoption accelerates across precision agriculture and regulatory enforcement tightens contaminated land assessment protocols.
For Market Incumbents: Consolidate ASTM and ISO certification pipelines to filter emerging competitors from export-market access. Deepen vertical integration into ceramic-based sensor membrane production to offset REACH substance restriction cost pressures. Lock long-term calibration service contracts with German horticulture clusters where federal soil protection ordinances mandate annual testing frequency. For New Entrants and Emerging Players: Anchor in India's state-led soil health card programs where BIS certification expansion opens distribution channels for moisture sensors and pH meters. Target China's Yangtze River Delta industrial corridor remediation contractors facing MEE soil pollution prevention enforcement. Pursue sensor-as-a-service go-to-market models that displace one-time hardware transactions with recurring revenue streams. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed agricultural technology platforms holding subscription-linked sensor network deployments. Five-to-ten year viability hinges on interoperability standardization between proprietary wireless protocols and open-field data platforms. Monitor LoRaWAN adoption rates across US Corn Belt farming cooperatives as inflection indicator for platform control fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-as-a-Service Platform Launch | Transforms one-time hardware sales into recurring calibration revenue streams across German horticulture clusters. |
| Backward Integration into Ceramic Membranes | Secures REACH-compliant supply for ion-selective electrodes facing cadmium and lead substance restrictions. |
| Open-Protocol Interoperability Certification | Reduces buyer lock-in risk as farming cooperatives resist proprietary wireless data infrastructure control. |
| Dual ASTM/ISO Certification Investment | Unlocks federal procurement channels for Superfund site characterization and CE-marked European market access. |
| Per-Hectare Monitoring Subscription Rollout | Captures recurring revenue from Rhine Valley horticulture operations under federal soil protection ordinances. |
Study Parameters
A standing panel of geotechnical field technicians, agricultural cooperative procurement managers, environmental remediation project directors, and calibration laboratory supervisors provided ongoing calibration against secondary validation from ASTM International standards databases, EPA Method 9045D documentation, EU F-Gas Regulation filings, and customs trade data for sensor membrane precursor flows. Bottom-up equipment shipment tracking and top-down agricultural expenditure modeling were triangulated to constrain variance.
Consistency checks validated volume and value outputs against external benchmarks including IEA agricultural technology adoption surveys and national soil health program procurement disclosures across the projection horizon. Segmentation dimensions modeled encompass product type, end-user vertical, wireless protocol technology, and application intensity from voluntary optimization to regulatory-mandated monitoring. CAGRs were derived from logistic diffusion curves fitted to wireless sensor adoption patterns and enforcement timeline acceleration for contaminated land assessment.
Material uncertainties — geotechnical technician shortage persistence, REACH substance restriction scope expansion, and open-protocol standardization timing — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as EU Green Deal soil carbon monitoring mandate implementation evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Testing Services
Animal Feed Testing Market
Agricultural Testing Services
Asia Pacific Feed Testing Market
Agricultural Testing Services
Europe Feed Testing Market
Agricultural Testing Services
Rapid Mycotoxin Detection Systems for Grain Handling Facilities Market
Agricultural Testing Services
Pesticide Detection Market
Agricultural Testing Services
Pesticide Residue Testing Market
Agricultural Testing Services
North American Feed Testing Market
Agricultural Testing Services
Irrigation Testing Kit Market
Agricultural Testing Services
Global Agriculture Testing Services Market
Agricultural Testing Services
Testing, Inspection, and Certification for Agriculture & Food Market
Agricultural Testing Services
Soil Erosion Testing Market
Agricultural Testing Services
Feed Testing Market
Agricultural Testing Services
Agricultural Testing Services Market
Agricultural Testing Services
Plant Disease Diagnostic Market
Agricultural Testing Services
Agrochemicals Testing and Inspection Service Market
Agricultural Testing Services
Soil Sampling Services Market