
 Seed Drill Machines Market | 2026-2036
Seed Drill Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Seed Drill Machines Market Outlook
REACH compliance is repositioning the cost-of-entry calculus for European manufacturers by mandating restricted substance audits across steel and polymer supply chains. Deere & Company leverages its precision agriculture ecosystem to bundle GPS-enabled seed drills with subscription-based agronomy software. AGCO Corporation sustains manufacturing scale through captive foundry operations in Brazil and assembly flexibility across multiple continents. Kubota Corporation anchors its competitive stance with compact seed drill lines engineered for rice paddy conditions across Southeast Asian markets.
A seed drill machine is a mechanized planting implement designed to deposit seeds at uniform depth and spacing through calibrated metering mechanisms, typically achieving placement accuracy within two to five centimeters. Its primary commercial purpose is to eliminate manual broadcasting, reduce seed waste, and establish optimal plant populations for cereal, oilseed, and legume crops. Pneumatic seed drills command the largest installed base due to their adaptability across variable soil textures and crop types, though vacuum seed drills are gaining traction where singulation precision for high-value hybrid seeds justifies capital outlay. Smart seed drilling systems with real-time population monitoring represent the fastest-expanding technology segment as OEMs integrate CAN-bus sensors and cloud telemetry into mid-tier product lines.
The EPA regulates particulate emissions from diesel-powered traction units that tow or carry seed drills, while the USDA's Natural Resources Conservation Service ties cost-share eligibility to equipment demonstrating measurable soil disturbance reduction. India's Central Pollution Control Board enforces noise and emission standards for engine-driven farm equipment sold through subsidized channels. Stakeholders must monitor how carbon accounting methodologies for Scope 3 agricultural emissions reshape equipment financing and trade-in valuations across primary markets.
Market Dynamics
Precision agriculture ecosystems are compressing equipment replacement cycles as farmers trade mechanical seed drills for sensor-integrated platforms that sync with prescription planting software and variable-rate fertilizer systems.
Growth Catalysts
- EU Green Deal Farm to Fork:Mandatory soil disturbance reduction targets are compelling European farmers to retire broadcast seeders and adopt low-till drill configurations.
- India's Sub-Mission on Agricultural Mechanization:State-level subsidies covering 40-50% of equipment costs are accelerating tractor-mounted seed drill procurement among smallholder cooperatives in Punjab and Haryana.
- Hybrid seed singulation:Vacuum metering technology is displacing mechanical fluted-wheel systems where high-value hybrid maize and soybean seed economics justify capital outlay.
Market Restraints
- Steel and polymer input volatility:REACH compliance mandates restricted substance audits across European supply chains, elevating raw material qualification costs for metering component foundries.
- Hydraulic actuator concentration:Precision seed drill manufacturers remain dependent on German and Italian specialist suppliers for high-pressure hydraulic seed depth control systems.
- Calibration labor intensity:Mechanical seed drills require seasonal recalibration for each crop type, limiting appeal among part-time farm operators with compressed planting windows.
Strategic Opportunities
- Carbon credit monetization:Equipment demonstrating measurable soil disturbance reduction qualifies for USDA Natural Resources Conservation Service cost-share programs and emerging private soil carbon markets.
- Telematics-as-a-service bundling:OEMs are embedding CAN-bus population monitors with cloud telemetry to capture recurring revenue from agronomic data subscriptions.
- Rice paddy specialization:Compact floating seed drill configurations engineered for saturated soil conditions address underpenetrated Southeast Asian transplanting replacement markets.
Industry Challenges
- Mechatronics skill scarcity:Rural equipment dealerships lack technicians trained to diagnose GPS guidance faults and pneumatic metering blockages in integrated seed drill systems.
- Legacy fleet interoperability:Retrofitting 1990s-era tractors with ISOBUS-compatible seed drill implements requires proprietary adapter modules that fragment precision agriculture ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seed Drill Machines Market |
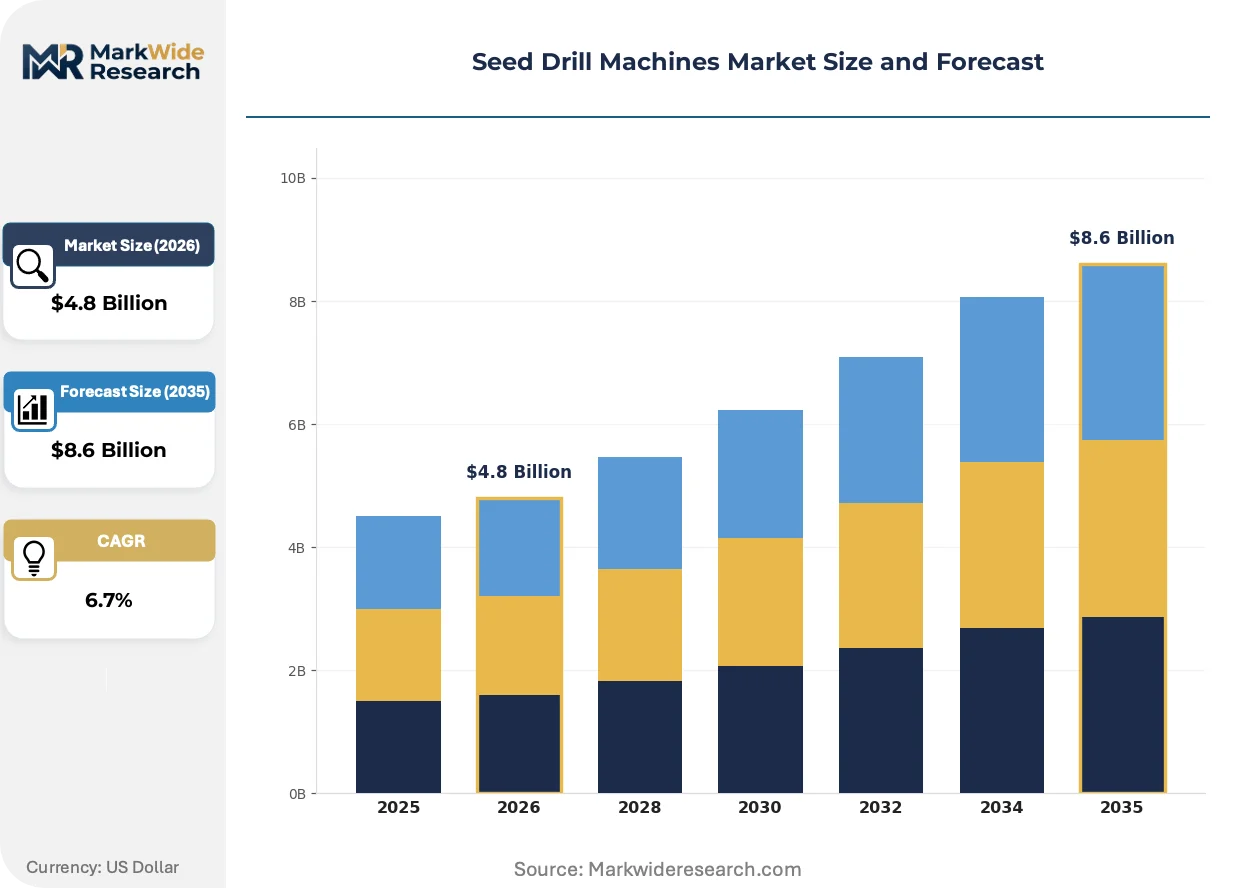
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Seed Drills, Pneumatic Seed Drills, Monosem Seed Drills, Vacuum Seed Drills Technology: Precision Agriculture, Smart Seed Drilling, GPS-Enabled Systems, Automated Seed Placement End Use: Agricultural Farms, Commercial Landscaping, Horticulture, Research Institutions Size: Small Scale, Medium Scale, Large Scale, High Capacity |
| Companies Covered | CLAAS, KUHN Group, Deere & Company, Vaderstad, Mahindra and Mahindra, AGCO Corporation, Kubota Corporation, HORSCH, CNH Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seed Drill Machines Market Strategic Shifts
Electrification of traction and metering systems is converging with autonomous navigation platforms to redefine field operating economics and equipment ownership models across cereal-producing regions.
Electric drive motors for seed metering units are electrifying the elimination of ground-wheel mechanical power take-off dependency. Large-scale Midwestern row-crop operators are adopting these systems to enable independent variable-rate population control across irregular field shapes. This electrification is compressing the cost delta between pneumatic and vacuum metering configurations.
REACH substance restriction audits are mandating supply chain requalification for steel alloys and polymer bushings used in European-manufactured seed drills. The regulation is forcing foundries to document cobalt and chromium content in wear-resistant metering components. German and French OEMs are accelerating polymer substitution programs to preempt compliance-driven supply interruptions.
Cooperative procurement consortia are aggregating smallholder demand to negotiate volume discounts on precision seed drill configurations. Aggregators in India's Maharashtra and Gujarat are displacing individual dealer relationships with centralized tendering platforms that bundle financing and seasonal maintenance contracts. This consolidation is most visible where state subsidy disbursement has shifted to direct benefit transfer mechanisms requiring digital equipment registration.
Seed Drill Machines Market Segmentation
Equipment replacement cycles in seed drill procurement vary sharply across product configurations and farm operational scales. Farmers weigh capital recovery periods against precision gains when selecting between mechanical reliability and sensor-integrated platforms.
Product Type:
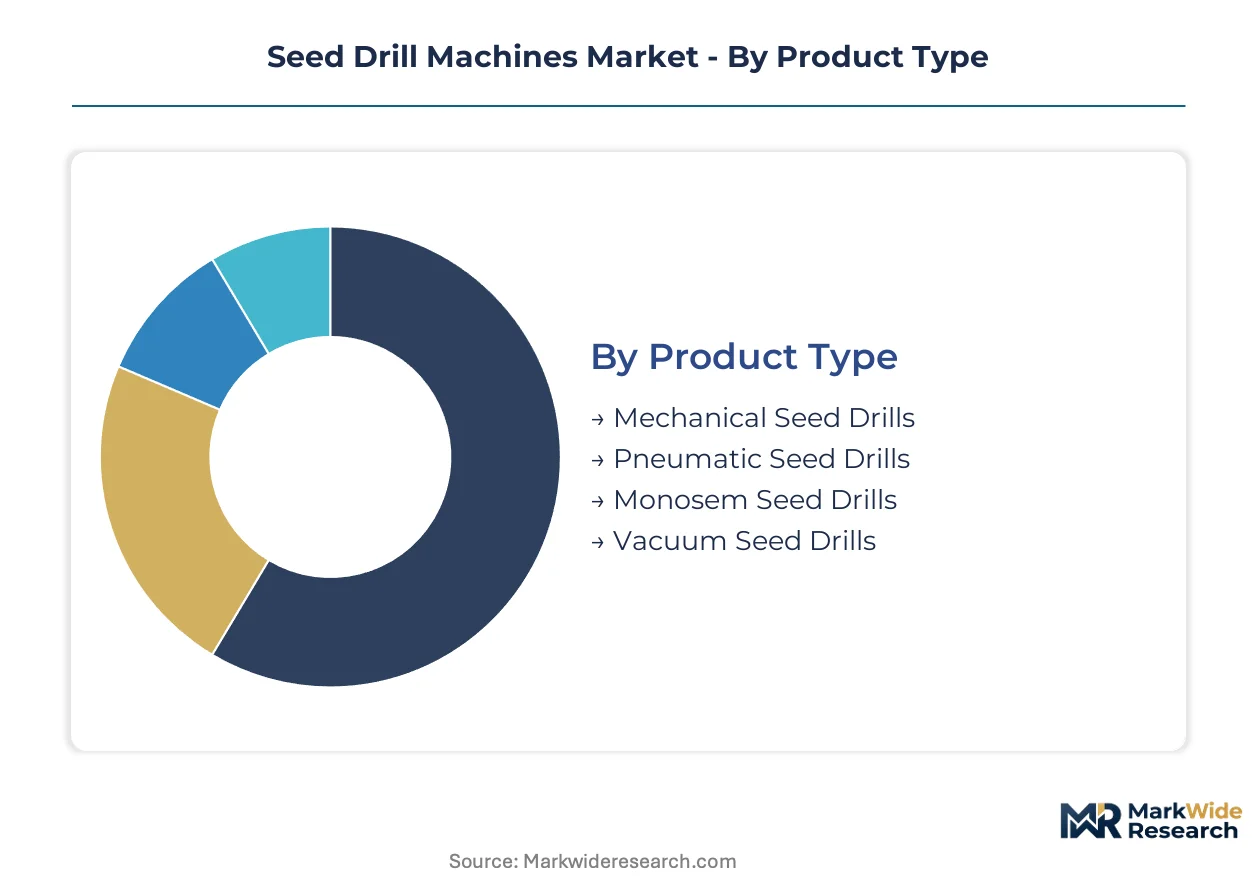
Upgrade trajectories from mechanical to pneumatic and vacuum systems dominate replacement decisions as operators seek reduced calibration burden and improved singulation accuracy.
- Pneumatic Seed Drills:These systems utilize air pressure differential to transport and meter seeds through distribution hoses, achieving uniform spacing across variable terrain. Demand concentrates in the United States where large-scale Midwestern row-crop operators prioritize adaptability across soybean and maize rotations. Their tolerance for seed size variation reduces seasonal changeover downtime.
- Vacuum Seed Drills:Precision singulation via perforated discs and negative pressure chambers enables single-seed placement for high-value hybrid crops. Adoption accelerates in India where state subsidy programs under the Sub-Mission on Agricultural Mechanization support cooperative procurement of precision equipment for cotton and hybrid maize cultivation.
- Mechanical Seed Drills:Fluted-wheel and cup-feed mechanisms remain prevalent among part-time operators with compressed planting windows and limited technical support access.
- Monosem Seed Drills:Specialized disc configurations target vegetable and high-density row crop applications where narrow row spacing and shallow depth control predominate.
Pneumatic seed drills sit at the top of the volume ranking, with vacuum seed drills climbing the fastest.
Technology:
Cost tier stratification separates subscription-enabled precision platforms from capital-only mechanical systems, reshaping manufacturer revenue models toward recurring service streams.
- Smart Seed Drilling:CAN-bus sensors and cloud telemetry enable real-time population monitoring and automatic rate adjustment based on soil conditions. European adoption accelerates under EU Green Deal Farm to Fork soil disturbance reduction mandates that reward documented planting precision.
- Precision Agriculture:Integration with prescription planting software and variable-rate fertilizer systems compresses equipment replacement cycles as farmers seek ecosystem compatibility.
- GPS-Enabled Systems:Autosteer integration reduces overlap and skip patterns, particularly valued in irregular field geometries common to consolidated holdings.
- Automated Seed Placement:Electrified metering independent of ground-wheel drive enables population modulation across in-field zones without mechanical linkage constraints.
Precision agriculture platforms command premium positioning, while smart seed drilling gains share fastest through mid-tier OEM bundling strategies.
End Use:
Application intensity drives specification divergence between high-utilization commercial operations and intermittent-use institutional settings.
- Agricultural Farms:Cereal, oilseed, and legume producers constitute the primary installed base, with large-scale operators in the United States and India driving pneumatic and vacuum system adoption respectively.
- Horticulture:Specialized bed configurations and shallow depth requirements favor compact drill geometries and precision population control for vegetable seeding.
- Commercial Landscaping:Lower duty cycles and diverse seed types sustain demand for mechanical simplicity and rapid calibration changeover.
- Research Institutions:Plot-scale replication requirements drive demand for highly configurable, data-logging platforms with documented placement accuracy.
Agricultural farms anchor volume concentration, with horticulture expanding most quickly through protected cultivation expansion.
Size:
Customer type and operational scale determine working width and hopper capacity specifications across ownership models.
- Large Scale:Working widths exceeding six meters and high-capacity hoppers match consolidated holdings where timeliness of planting windows dictates fleet sizing.
- Medium Scale:Three-to-five meter configurations balance capital efficiency with daily productivity targets for family-operated commercial farms.
- Small Scale:Tractor-mounted units under three meters address smallholder mechanization in subsidy-supported markets.
- High Capacity:Extended hoppers and rapid-fill systems minimize refill downtime for contract planting operations covering extensive acreage.
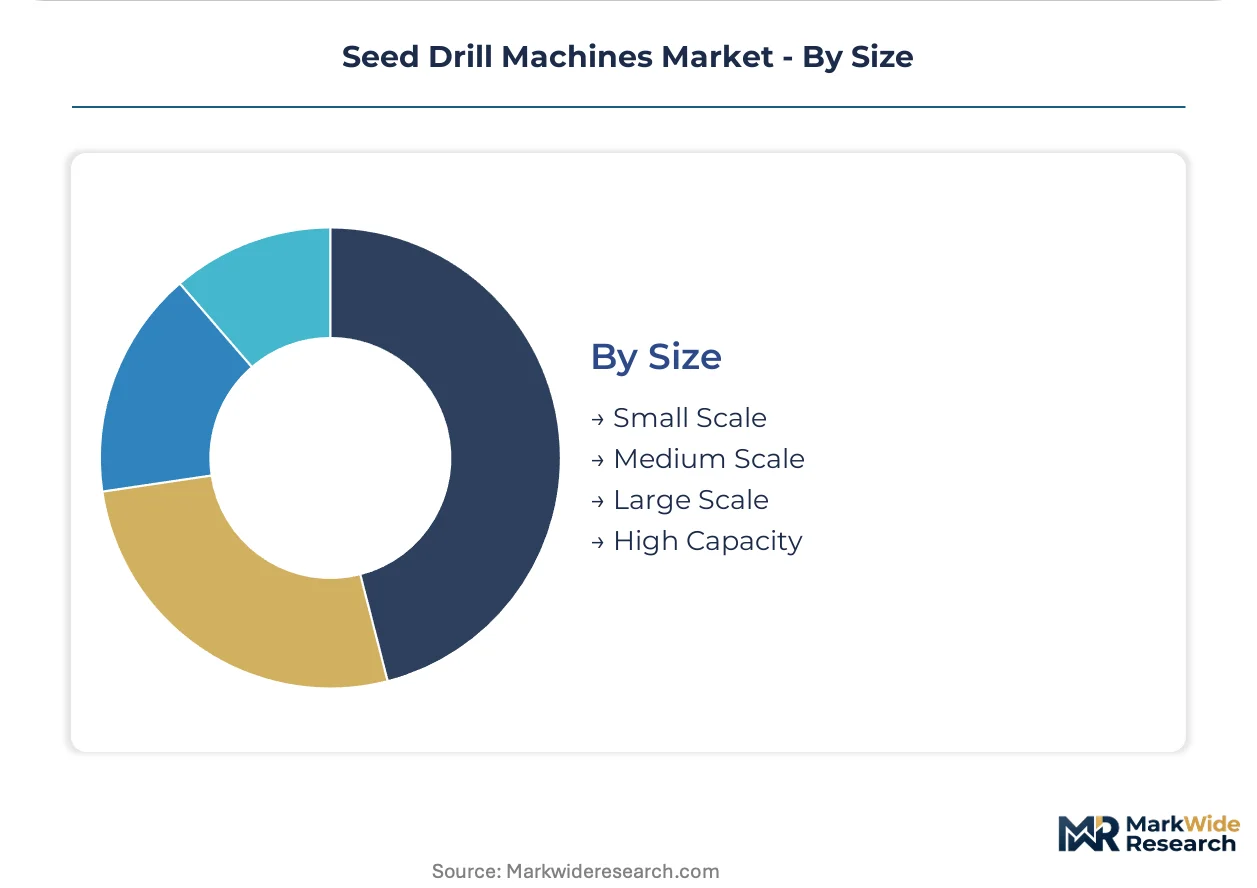
Large-scale equipment holds volume leadership, with high-capacity configurations gaining traction fastest through custom operator fleet expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturers concentrate engineering talent in Germany's Baden-Württemberg and Iowa's agricultural machinery corridor, anchoring precision seeding R&D clusters that supply farm operators across temperate cereal zones.
United States
Large-scale Midwestern row-crop operators drive pneumatic seed drill demand for soybean-maize rotations. The USDA's Natural Resources Conservation Service ties cost-share eligibility to equipment demonstrating measurable soil disturbance reduction. Iowa's manufacturing corridor hosts captive foundry operations supplying metering components to domestic OEMs.
Germany
EU Green Deal Farm to Fork mandates compel farmers to retire broadcast seeders for low-till drill configurations. REACH compliance mandates restricted substance audits across steel and polymer supply chains, elevating raw material qualification costs. Baden-Württemberg's precision engineering cluster specializes in high-pressure hydraulic seed depth control systems.
India
State-level farm mechanization subsidies under the Sub-Mission on Agricultural Mechanization accelerate tractor-mounted seed drill procurement among smallholder cooperatives in Punjab and Haryana. The Central Pollution Control Board enforces noise and emission standards for engine-driven farm equipment sold through subsidized channels. Maharashtra's cooperative procurement consortia aggregate smallholder demand through centralized tendering platforms.
Brazil
Large-scale commercial soybean and maize producers sustain demand for high-capacity pneumatic configurations. Captive foundry operations in São Paulo state supply wear-resistant metering components to South American assembly plants. The country's national agricultural machinery regulator monitors equipment safety standards for subsidized credit programs.
China
State-directed agricultural mechanization campaigns expand precision seeding equipment penetration in the North China Plain wheat belt. Dual carbon goals reshape equipment financing toward electrified traction and metering systems. Shandong Province's farm machinery manufacturing base produces compact drill configurations for domestic smallholder markets.
Seed Drill Machines Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between integrated agricultural equipment platforms and component-specialist fabricators. Three archetypes dominate: full-line OEMs bundling seed drills with precision agriculture ecosystems, regional specialists serving subsidy-driven emerging markets, and hydraulic actuator suppliers controlling critical metering subsystems. Competitive moves concentrate on M&A for precision agriculture software capabilities and captive foundry investments in Brazil and India.
Within the full-line OEM tier, Deere & Company and AGCO Corporation exemplify platform diversification strategies, while Kubota Corporation anchors the compact equipment specialist position. Among Germany-based precision engineering houses, CLAAS and HORSCH occupy positions emphasizing European regulatory compliance and low-till configuration leadership. Mahindra and Mahindra represents the emerging-market volume archetype, leveraging domestic subsidy access and cooperative procurement relationships.
| Leading Market Players |
|---|
| CLAAS |
| KUHN Group |
| Deere & Company |
| Vaderstad |
| Mahindra and Mahindra |
| AGCO Corporation |
| Kubota Corporation |
| HORSCH |
| CNH Industrial |
| Others |
Value Chain & Pricing Dynamics
Electrified metering systems are compressing the cost delta between pneumatic and vacuum configurations while simultaneously concentrating component sourcing among German and Italian hydraulic specialists. This technological transition simultaneously elevates raw material qualification burdens under REACH substance audits and reshapes procurement leverage for OEMs negotiating volume commitments with captive foundry operators in Brazil and India.
Pricing Analysis
Bundled subscription services versus unbundled capital-only sales now define the dominant pricing architecture across precision seed drill markets. Three-tier pricing structure across premium smart-drilling platforms, standard GPS-enabled configurations, and economy mechanical units separates buyers by precision agriculture ecosystem integration depth. Price differentiation hinges on ISOBUS compatibility certification and after-sales telemetry subscription tiers. Pricing pressure stems from cooperative procurement consortia in India aggregating smallholder demand through centralized tendering platforms. Part-time operators with compressed planting windows exhibit highest price sensitivity, while large-scale Midwestern row-crop operators prioritize ecosystem compatibility over unit cost.
Supply Chain Analysis
High-pressure hydraulic seed depth control systems rest on specialist manufacturing clusters in Germany and Italy, creating concentrated dependency for precision metering actuators. Steel alloy feedstock draws from integrated foundry operations in Brazil and India, while polymer bushing components source from European compounders navigating REACH cobalt and chromium documentation requirements. Single-source vulnerability in hydraulic actuator supply creates exposure to regional logistics disruptions and specialist labor shortages. Distribution runs through OEM captive dealer networks in developed markets and state-subsidized cooperative procurement platforms in emerging agricultural economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seed drill markets present a late-cycle quality story where replacement demand tilts toward premium smart-drilling configurations with telemetry integration and carbon credit eligibility documentation.
For Market Incumbents: Lock in ecosystem dominance by accelerating ISOBUS-compatible retrofit adapter development for legacy tractor fleets, preempting fragmentation of precision agriculture platforms. Prioritize captive foundry capacity expansion in São Paulo state to secure wear-resistant metering component supply against Brazilian regulatory tightening on subsidized credit program eligibility. Defend against emerging pure-play telematics specialists by bundling agronomy software subscriptions with hardware trade-in programs. For New Entrants and Emerging Players: Capture white-space opportunity in compact floating seed drill configurations engineered for saturated rice paddy conditions across Southeast Asian transplanting replacement markets. Target India's Maharashtra and Gujarat cooperative procurement consortia through centralized tendering platforms that bundle financing and seasonal maintenance contracts. Penetrate via OEM partnership routes rather than direct dealer network buildout to circumvent incumbent channel control. For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with established subsidy channel relationships and undervalued precision agriculture software capabilities. Long-term viability over the next decade favors equipment manufacturers demonstrating measurable soil disturbance reduction eligible for USDA Natural Resources Conservation Service cost-share programs and emerging private soil carbon markets. Watch for inflection signals in carbon accounting methodology standardization for Scope 3 agricultural emissions.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry-as-a-Service Bundling | Transforms OEM revenue models toward recurring agronomic data subscriptions with CAN-bus population monitors. |
| Captive Foundry Investment | Secures wear-resistant metering component supply in Brazil and India against regulatory qualification delays. |
| ISOBUS Retrofit Adapter Development | Enables legacy tractor interoperability and prevents precision agriculture ecosystem fragmentation. |
| Carbon Credit Certification Pathway | Unlocks USDA Natural Resources Conservation Service cost-share eligibility and private soil carbon market access. |
| Rice Paddy Specialization Engineering | Addresses underpenetrated Southeast Asian transplanting replacement markets with compact floating configurations. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM product managers, agricultural cooperative procurement officers, precision agriculture software engineers, and aftermarket service technicians with secondary validation against SEC filings from diversified equipment manufacturers, USDA Natural Resources Conservation Service cost-share program documentation, EU Green Deal Farm to Fork strategy implementation reports, and India Sub-Mission on Agricultural Mechanization subsidy disbursement records. Bottom-up equipment shipment modeling and top-down agricultural machinery expenditure triangulation anchored market sizing.
Comparable-period anchoring to historical replacement cycle data and subsidy program enrollment trajectories structured the projection horizon across the analysis window. Segmentation modeling spanned product type, technology tier, end-use application, operational scale, and regional regulatory cluster dimensions. CAGRs derived from equipment procurement elasticity estimates tied to farm income forecasts and mechanization policy intensity indices. Industry-specific inputs included prescription planting software adoption curves and cooperative procurement consortium formation rates.
Steel and polymer input volatility, REACH compliance audit timeline uncertainty, and subsidy program disbursement delays are the dominant revision risks to equipment demand forecasts. Forecasts reflect documented assumptions on farm consolidation trajectories and carbon credit market development. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Europe Planting Machinery Market
Agricultural Equipment & Machinery
Global Agriculture and Farm Equipment Market
Agricultural Equipment & Machinery
Europe Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Lawn and Garden Equipment Market
Agricultural Equipment & Machinery
Global Powered Agriculture Equipment Market
Agricultural Equipment & Machinery
Hammer Mill Market
Agricultural Equipment & Machinery
Planting and Fertilizing Machinery Market
Agricultural Equipment & Machinery
South Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
Global Agricultural Equipment Market
Agricultural Equipment & Machinery
Global Fishery Machinery Manufacturing Market
Agricultural Equipment & Machinery
United States Agricultural Irrigation Machinery Market
Agricultural Equipment & Machinery
Germany Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Beekeeping Equipment Market
Agricultural Equipment & Machinery
Global Seed Processing Machinery Market
Agricultural Equipment & Machinery
Planting Equipment Market
Agricultural Equipment & Machinery
Asia-Pacific Agricultural Sprayer Market