
 Heavy Tooth Drag Harrows Market | 2026-2036
Heavy Tooth Drag Harrows Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Tooth Drag Harrows Market Insights
Skilled welder and fabricator availability across Midwestern manufacturing corridors is unwinding production lead times for heavy tillage equipment. Great Plains Ag leverages its integrated supply chain across Kansas and Nebraska to sustain consistent delivery schedules for trailed and foldable configurations. Wingfield American Harrow specializes in domestically produced tooth assemblies that anchor its reputation among conservation-minded farm operators. Land Pride competes through its extensive dealer network, which controls rural equipment distribution channels across the Plains states.
Heavy tooth drag harrows are ground-engaging implements featuring multiple rows of rigid or spring-loaded steel teeth arranged on a drag frame, typically spanning widths of 12 to 40 feet and operating at depths of two to six inches for seedbed preparation and residue management. The implement fractures soil compaction layers, incorporates crop residue, and levels terrain prior to planting or seeding operations across commercial agriculture and turf establishment. Trailed harrows dominate volume shipments due to their compatibility with high-horsepower tractors on operations exceeding 500 acres, while foldable configurations capture premium positioning by enabling road transport compliance without disassembly. Steel remains the predominant material specification, though composite tooth options are gaining traction in corrosion-intensive environments where chemical fertilizer exposure accelerates wear rates.
USDA Natural Resources Conservation Service guidelines and EPA agricultural runoff standards shape equipment design requirements, particularly for residue management practices that reduce soil erosion and nutrient loss. State-level equipment safety regulations in Iowa, Illinois, and Nebraska mandate lighting and marking compliance for wide implements transported on public roadways. Buyers must evaluate tooth metallurgy specifications against regional soil abrasion profiles and assess dealer service density before committing to platform-specific harrow architectures.
Market Dynamics
Conservation compliance mandates under the USDA Environmental Quality Incentives Program are redirecting capital toward soil health-oriented tillage implements, compressing demand for conventional disc systems while elevating residue-managing drag harrow configurations.
Growth Catalysts
- USDA Environmental Quality Incentives Program:Conservation compliance requirements reshape tillage equipment specifications toward implements that preserve soil structure and reduce erosion across Corn Belt operations.
- Precision agriculture integration:Large-scale row-crop farms are replacing aging fleets with GPS-compatible drag harrow systems that enable variable-rate tillage and field mapping.
- Farm equipment technician shortages:North American equipment dealerships face constrained aftermarket service capacity, pushing original equipment demand toward simpler, modular harrow designs that reduce field downtime.
Market Restraints
- Steel price volatility:Input cost fluctuations for high-carbon and boron steel alloys directly compress manufacturing margins and destabilize equipment pricing.
- Skilled welder scarcity:Midwestern manufacturing corridors face unwinding production lead times due to fabricator availability constraints across Kansas and Nebraska production clusters.
- Substitute tillage systems:Vertical tillage tools and high-speed compact disc systems capture share among operators prioritizing speed over residue incorporation depth.
Strategic Opportunities
- Composite tooth materials:Corrosion-intensive environments with chemical fertilizer exposure create openings for non-steel tooth options that extend service intervals.
- Foldable configuration premiumization:Road transport compliance without disassembly addresses state-level lighting and marking regulations in Iowa, Illinois, and Nebraska.
- Conservation leasing programs:USDA Natural Resources Conservation Service cost-share mechanisms lower capital barriers for soil health-oriented implement adoption.
Industry Challenges
- Fabricator talent pipeline:Welding program enrollment declines across technical colleges constrain production scaling for complex frame assemblies.
- Dealer service density gaps:Rural equipment distribution channel coverage varies significantly, complicating after-sales support commitments for platform-specific architectures.
- Metallurgy-soil matching complexity:Buyers must evaluate tooth specifications against regional abrasion profiles without standardized testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Tooth Drag Harrows Market |
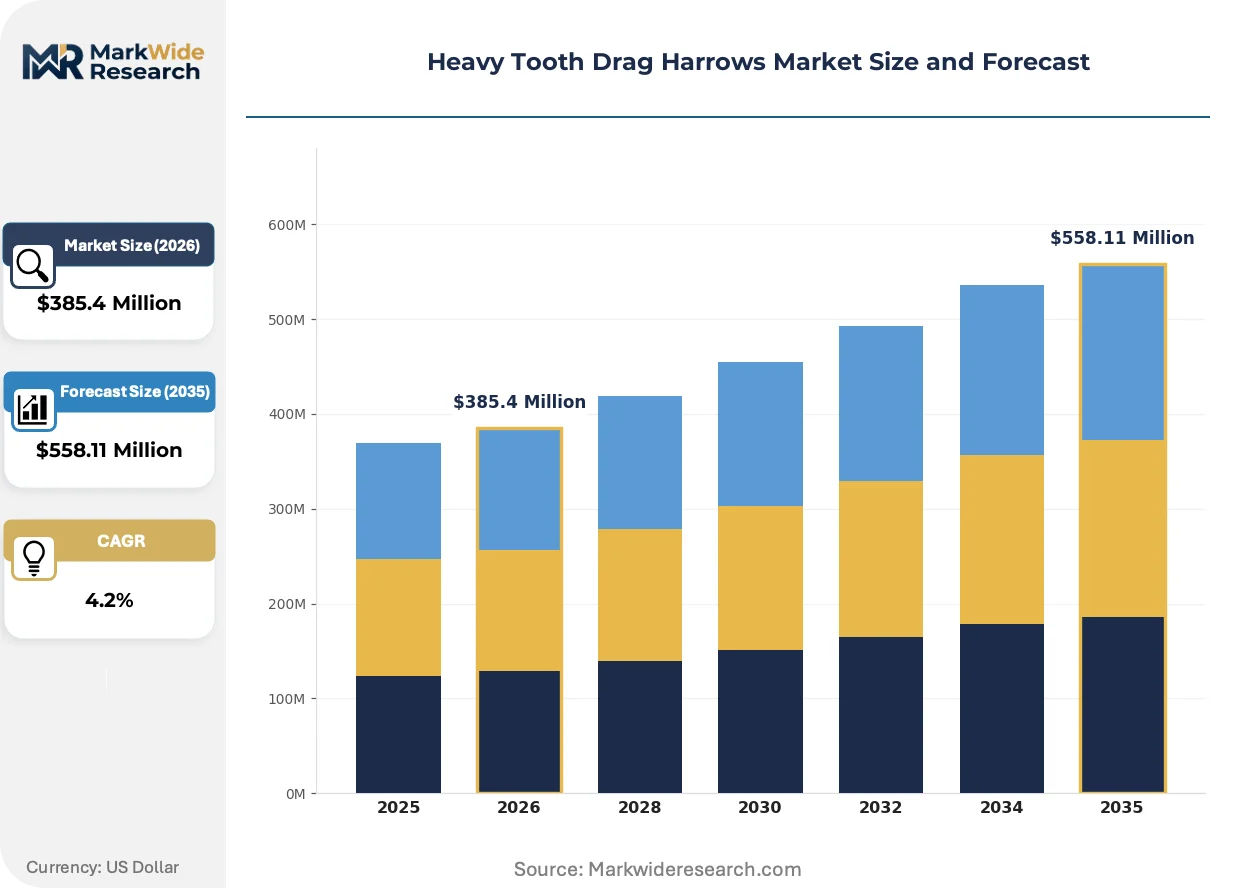
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $558.11 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mounted Harrows, Trailed Harrows, Foldable Harrows, Offset Harrows Material: Steel, Aluminum, Composite, Iron Application: Agriculture, Landscaping, Soil Preparation, Turf Maintenance End User: Farmers, Landscape Contractors, Gardening Enthusiasts, Agricultural Cooperatives |
| Companies Covered | Land Pride, Great Plains Ag, Wingfield American Harrow, Darrell Harp Enterprises, LandTop, William Hackett Harrows, Alibaba (Chain Drag Harrow Suppliers), Oregon Products, Farm Tech Supplies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Tooth Drag Harrows Market Trends and Innovations
Active innovation in heavy tooth drag harrows centers on material science advances, regulatory alignment with conservation programs, and procurement model evolution that shifts risk allocation between manufacturers and farm operations.
Spring-loaded tooth suspension systems are miniaturizing across premium trailed configurations, enabling individual tooth movement that protects frame integrity when encountering subsurface obstacles. Operators managing rocky glacial till soils in Minnesota and Wisconsin are specifying these assemblies at accelerating rates. This technology is compressing warranty claim frequencies while extending overall implement service life.
USDA Natural Resources Conservation Service guidelines and EPA agricultural runoff standards are reshaping equipment design requirements toward residue management practices that reduce soil erosion and nutrient loss. Manufacturers now engineer tooth angles and spacing patterns specifically to meet conservation compliance documentation requirements. Corn Belt equipment dealers report conservation-program eligibility has become a primary specification criterion in purchasing decisions.
Equipment procurement through cooperative purchasing agreements is consolidating buyer power among multi-farm operations and regional agricultural cooperatives. Traditional dealer-direct sales face displacement from volume-negotiated contracts that bundle implements with precision agriculture service packages. This pattern concentrates most visibly across Iowa and Illinois where farm consolidation has accelerated most rapidly.
Heavy Tooth Drag Harrows Market Segmentation
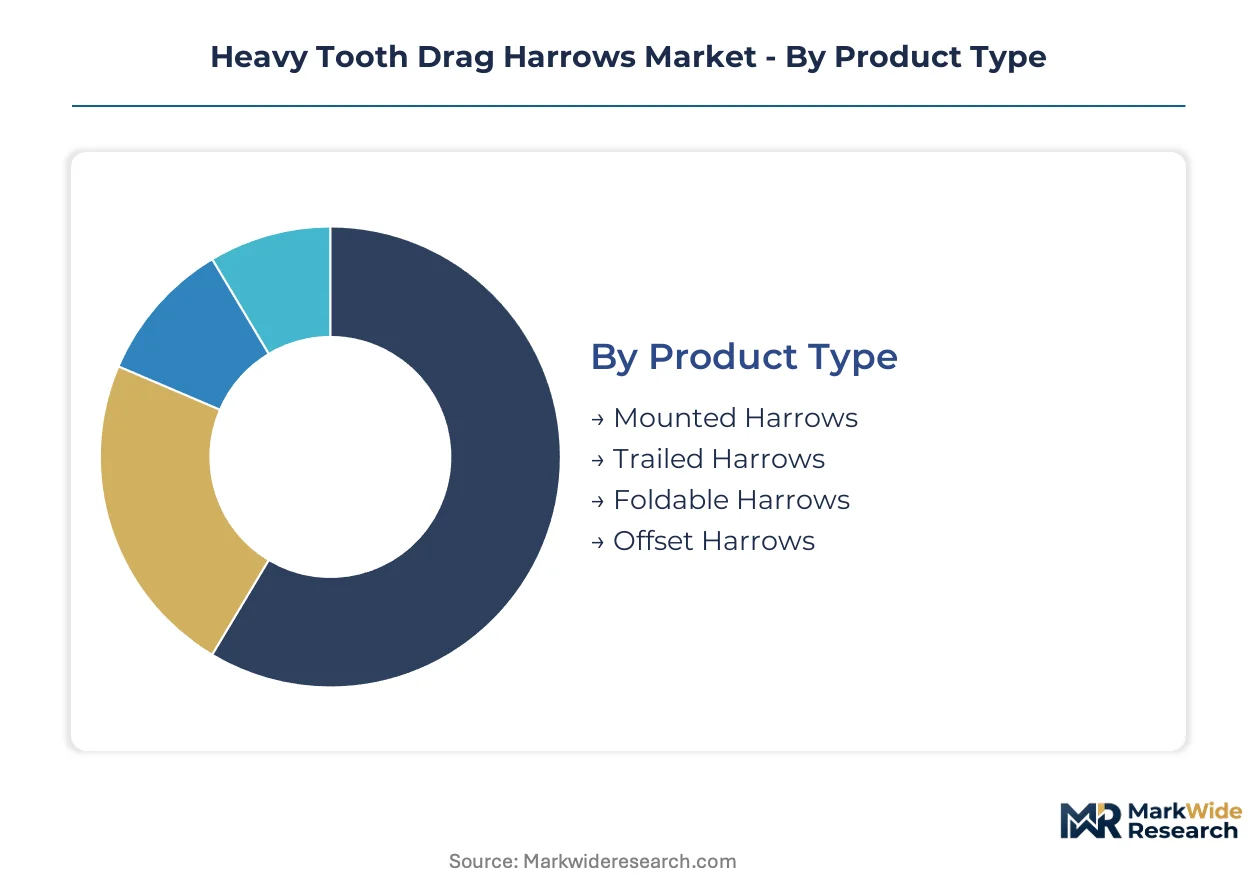
Heavy tooth drag harrow purchasing patterns diverge sharply across product configurations and user profiles. Equipment dealers in the US Corn Belt report distinct channel preferences for trailed versus mounted systems. Material selection tracks regional soil chemistry and corrosion exposure patterns.
Product Type:
Trailed configurations move through high-volume dealer networks serving operations above 500 acres, while mounted and foldable variants concentrate in specialized agricultural equipment distributors.
- Mounted Harrows:Three-point hitch attachment systems suited for mid-horsepower tractors between 75 and 150 HP. Demand clusters among Wisconsin and Minnesota dairy operations managing smaller acreages where maneuverability trumps width coverage.
- Trailed Harrows:Drawbar-connected implements spanning 12 to 40 feet, engineered for high-horsepower tractors exceeding 200 HP. Iowa and Illinois row-crop operations are replacing aging disc systems with these configurations to satisfy USDA Environmental Quality Incentives Program residue management requirements.
- Foldable Harrows:Hydraulic wing-fold mechanisms enable road transport compliance without disassembly. Nebraska and Kansas equipment dealers report premium positioning for these systems among operators navigating state-level lighting and marking regulations.
- Offset Harrows:Asymmetric frame designs for field edge and drainage ditch maintenance. Landscape contractors in the Great Lakes region specify these for right-of-way vegetation management contracts.
Trailed harrows dominate installed base. Foldable configurations are where expansion concentrates.
Material:
Cost tier stratification separates commodity steel specifications from premium corrosion-resistant alternatives, with composite options capturing niche positioning in chemically intensive environments.
- Steel:High-carbon and boron alloy specifications remain the volume standard across Midwestern manufacturing corridors. Kansas and Nebraska fabricators source from regional steel mills, though price volatility compresses margins unpredictably.
- Aluminum:Lightweight frame components reduce tongue weight for smaller tractors. Demand is climbing fastest among equine and specialty crop operators in Kentucky and Tennessee where transport frequency exceeds field hours.
- Composite:Glass-reinforced polymer tooth options resist chemical fertilizer corrosion. Ohio and Indiana operators managing high-pH soils with intensive nitrogen application are specifying these at accelerating rates.
- Iron:Cast components for wear points and hinge assemblies. Foundry capacity constraints in the Great Lakes region limit availability for replacement part channels.
Steel commands volume shipments. Composite represents the fastest-growing trajectory.
Application:
Volume concentration aligns with USDA program eligibility, while margin expansion tracks specialized turf and landscaping contracts outside commodity crop cycles.
- Agriculture:Primary seedbed preparation and residue incorporation across corn-soybean rotations. Conservation compliance documentation requirements under EPA agricultural runoff standards are elevating specification scrutiny.
- Landscaping:Commercial turf establishment and erosion control on construction sites. Municipal procurement departments in Texas and Florida are bundling these implements with maintenance service contracts.
- Soil Preparation:Pre-planting compaction fracture and leveling operations. North Dakota spring wheat producers specify aggressive tooth angles for black soil management.
- Turf Maintenance:Golf course fairway conditioning and sports field renovation. Pennsylvania and New Jersey groundskeeping contractors demand fine-tooth configurations for bentgrass surfaces.
Agriculture anchors revenue. Landscaping is where margin expansion concentrates.
End User:
Customer type determines procurement modality, with cooperatives leveraging volume negotiation against individual farmers prioritizing dealer proximity and service response.
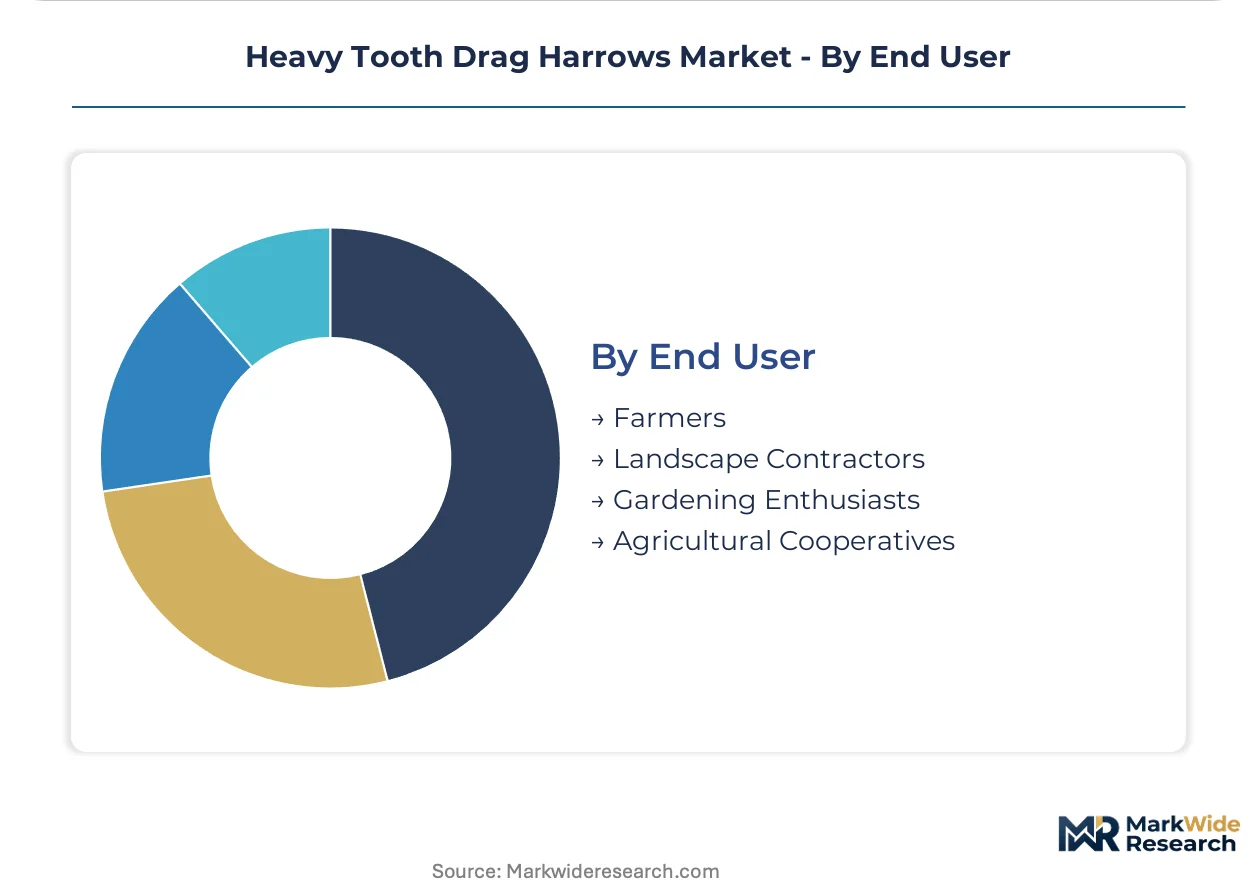
- Farmers:Owner-operators managing 200 to 2,000 acres, predominantly selecting trailed configurations through established dealer relationships. Equipment financing availability shapes timing decisions.
- Landscape Contractors:Commercial service providers with fleet standardization requirements. These buyers prioritize interchangeability and rapid parts availability across multiple job sites.
- Gardening Enthusiasts:Hobby-scale operators purchasing mounted implements for sub-50-acre properties. Online direct sales and farm store retail channels capture this fragmented demand.
- Agricultural Cooperatives:Multi-farm purchasing alliances consolidating equipment acquisition. Iowa and Illinois cooperatives are negotiating bundled precision agriculture service packages with implement manufacturers.
Farmers dominate unit volume. Agricultural cooperatives are where procurement consolidation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA conservation programs anchor equipment demand patterns across North American agricultural corridors. State-level regulations in corn-producing regions reshape procurement specifications toward residue-managing implements.
United States
Corn Belt operations drive replacement cycles for aging tillage fleets. The Environmental Protection Agency agricultural runoff standards mandate residue coverage thresholds that favor drag harrow configurations. Iowa and Illinois equipment dealers report conservation-program eligibility now dominates purchasing criteria.
Canada
Prairie wheat and canola producers specify heavy tooth configurations for black soil management. Health Canada and PMRA chemical application guidelines influence corrosion-resistant material selection. Manitoba and Saskatchewan manufacturing clusters fabricate trailed systems for domestic and export markets.
Brazil
Soybean expansion in Mato Grosso and Goiás creates demand for wide-span implements compatible with high-horsepower tractors. ANVISA fertilizer handling regulations accelerate interest in composite tooth materials. São Paulo-based distributors channel imported and domestically assembled equipment into southern agricultural zones.
Germany
Precise seedbed preparation requirements in Bavaria and Lower Saxony sustain demand for fine-tooth turf configurations. REACH chemical compliance and EU Green Deal sustainability criteria shape material specifications. Stuttgart-area engineering firms supply precision agriculture integration components for export markets.
Australia
Dryland wheat and barley operations in Western Australia and South Australia prioritize residue retention for moisture conservation. The national Department of Agriculture, Fisheries and Forestry drought resilience programs subsidize soil health equipment. Perth and Adelaide equipment dealers stock foldable configurations for vast property logistics.
Heavy Tooth Drag Harrows Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in heavy tooth drag harrow supply. The upper tier commands premium positioning through captive distribution networks and manufacturing scale. Mid-tier fabricators compete on regional proximity and customization flexibility. Consolidation pressure runs through dealer network expansion and precision agriculture bundling.
Among Midwestern integrated manufacturers, Great Plains Ag and Land Pride exemplify scale-driven archetypes with captive supply chain control. Wingfield American Harrow occupies a specialist position emphasizing domestic tooth assembly production. These three anchors illustrate the structural divide between volume-standardized and niche-customized competitive vectors.
| Leading Market Players |
|---|
| Land Pride |
| Great Plains Ag |
| Wingfield American Harrow |
| Darrell Harp Enterprises |
| LandTop |
| William Hackett Harrows |
| Alibaba (Chain Drag Harrow Suppliers) |
| Oregon Products |
| Farm Tech Supplies |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Corn Belt equipment cooperatives and Kansas-Nebraska fabricators lock in both boron steel supply access and price visibility across volatile commodity cycles, compressing spot-market exposure for high-volume buyers while anchoring manufacturer production schedules.
Pricing Analysis
Contract-based long-term offtake structures dominate procurement between agricultural cooperatives and Midwestern manufacturers, with spot purchasing limited to replacement tooth assemblies and emergency repairs. Price differentiation separates premium foldable configurations with hydraulic transport systems from standard trailed units, while volume scale drives tiered negotiations for cooperatives managing multi-fleet acquisitions. Cost compression in standard steel configurations is intensifying because boron alloy price volatility feeds directly into manufacturing margins. Individual owner-operators below 500 acres exhibit highest price sensitivity, whereas consolidated cooperatives prioritize service density and delivery reliability over unit cost.
Supply Chain Analysis
Inventory unwinding across Great Lakes foundries has extended lead times for cast iron wear components, forcing manufacturers to buffer with higher steel frame production. Geographic supply concentration centers on the United States, Canada, and Brazil, with Kansas-Nebraska manufacturing clusters feeding North American demand and São Paulo-state assemblers serving South American expansion. Raw material dependencies draw from regional steel mills, glass-reinforced polymer feedstock, and hydraulic component suppliers. Single-source vulnerability concentrates in specialized boron steel alloying capacity. Distribution runs through captive dealer networks controlling rural equipment channels across Plains states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat structure anchored in regulatory entrenchment: USDA Environmental Quality Incentives Program compliance requirements create switching costs that lock operators into residue-managing implement ecosystems once established.
For Market Incumbents: Compound dealer service density advantages by expanding certified technician programs across Iowa and Illinois, directly countering the farm equipment technician shortage that threatens aftermarket capacity. Deepen backward integration into tooth metallurgy production to offset boron steel price volatility and protect margin structure against commodity swings. For New Entrants and Emerging Players: USDA NRCS conservation certification fast-track pathways offer entry acceleration for composite tooth configurations targeting Ohio-Indiana high-pH soil operators. The most penetrable white-space sits in corrosion-resistant materials for chemically intensive environments, with direct-to-cooperative sales bypassing established dealer networks as the viable go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward regional fabricators with captive supply chain control across Kansas-Nebraska corridors, positioned for precision agriculture bundling consolidation. Long-term viability over a multi-year horizon hinges on conservation program durability and technician pipeline recovery. The signal to watch is cooperative procurement contract renewal rates as inflection indicator for manufacturer pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tooth Metallurgy | Captive boron steel alloying capacity insulates margin compression from commodity volatility. |
| Precision Agriculture Service Bundling | GPS-compatible drag harrow systems capture USDA EQIP-aligned cooperative procurement contracts. |
| Composite Material Certification Investment | Glass-reinforced polymer tooth options penetrate Ohio-Indiana corrosion-intensive nitrogen application zones. |
| Dealer Network Service Density Expansion | Certified technician programs address North American equipment dealership capacity constraints. |
| Foldable Configuration Road Compliance Engineering | Hydraulic wing-fold mechanisms satisfy Iowa-Illinois-Nebraska state-level lighting and marking regulations. |
Research Methodology
The analysis maps trailed, mounted, foldable, and offset harrow configurations, each validated through equipment dealership principals, farm cooperative procurement officers, and USDA Natural Resources Conservation Service field staff. Primary interviews with Great Plains Ag and Land Pride distribution managers, Wingfield American Harrow fabrication supervisors, and Corn Belt maintenance directors combined with secondary validation against USDA EQIP enrollment databases, EPA agricultural runoff compliance filings, and state-level equipment safety regulatory texts. Bottom-up unit shipment tracking across Kansas-Nebraska manufacturing clusters triangulates with top-down agricultural equipment expenditure models.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models product type, material specification, application segment, and end-user procurement modality dimensions throughout the forecast period. CAGRs derive from replacement cycle analysis of aging tillage fleets and conservation compliance adoption curves. Industry-specific forecast inputs include USDA Environmental Quality Incentives Program enrollment trajectories and skilled welder pipeline data from Midwestern technical college programs.
Underlying assumptions cover conservation program continuity and steel price mean-reversion, with deviation risk concentrated in trade policy shifts affecting boron alloy imports and accelerated farm consolidation altering cooperative bargaining leverage. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Manure Separator Market
Agricultural Equipment
Feller Buncher Market
Agricultural Equipment
Garden Tools Market
Agricultural Equipment
Global Infrared Heater for Agriculture Market
Agricultural Equipment
Solar Insect Trap Market
Agricultural Equipment
Gardening Tools Market
Agricultural Equipment
Cordless Sprayer Market
Agricultural Equipment
Israel Agriculture Market
Agricultural Equipment
Plow Folding System Market
Agricultural Equipment
Cordless Handheld Cultivator Market
Agricultural Equipment
Hatchery Equipment Market
Agricultural Equipment
Global Rice Transplanter Market
Agricultural Equipment
Oil Expellers Market
Agricultural Equipment
Belt Feeders Market
Agricultural Equipment
Agricultural Pumps Market
Agricultural Equipment
Industrial Potato Graders Market