
 Green Beans Harvester Market | 2026-2036
Green Beans Harvester Market Size, Share, and Industry Trends Forecast 2026-2036
Green Beans Harvester Market Insights
Organic vegetable processing is broadening the addressable base for green bean harvester OEMs beyond conventional commodity growers. Oxbo International leverages its heritage in specialty crop platforms to sustain engineering depth across North American installations. Asa-Lift anchors Nordic supply chains through purpose-built designs for compact field geometries. Weremczuk Agromachines dominates Eastern European procurement cycles with regionally calibrated service networks.
A green bean harvester is a field machine engineered to sever, collect, and convey Phaseolus vulgaris pods with minimal bruising, typically employing floating cutter bars with 8–15 mm blade spacing and gentle conveyor transitions to preserve pod integrity for fresh-market and processing grades. Mechanical harvesters retain the largest installed base across mature agricultural regions, though electric drive variants within automated systems are capturing disproportionate R&D allocation as fuel cost volatility and emissions compliance intensify. GPS navigation and IoT integration clusters are concentrating margin pools in fleet management and yield mapping services rather than hardware alone.
The EPA regulates off-road diesel emissions under Tier 4 Final standards, compelling hydraulic-to-electric retrofits and new platform designs. ISO 12100 machinery safety directives shape European export eligibility, while the EU Green Deal's agricultural mechanization subsidies are redirecting cooperative procurement toward lower-carbon technologies. Stakeholders must weigh electrification capex against contracted service revenue models as deployment flexibility becomes the decisive purchasing criterion.
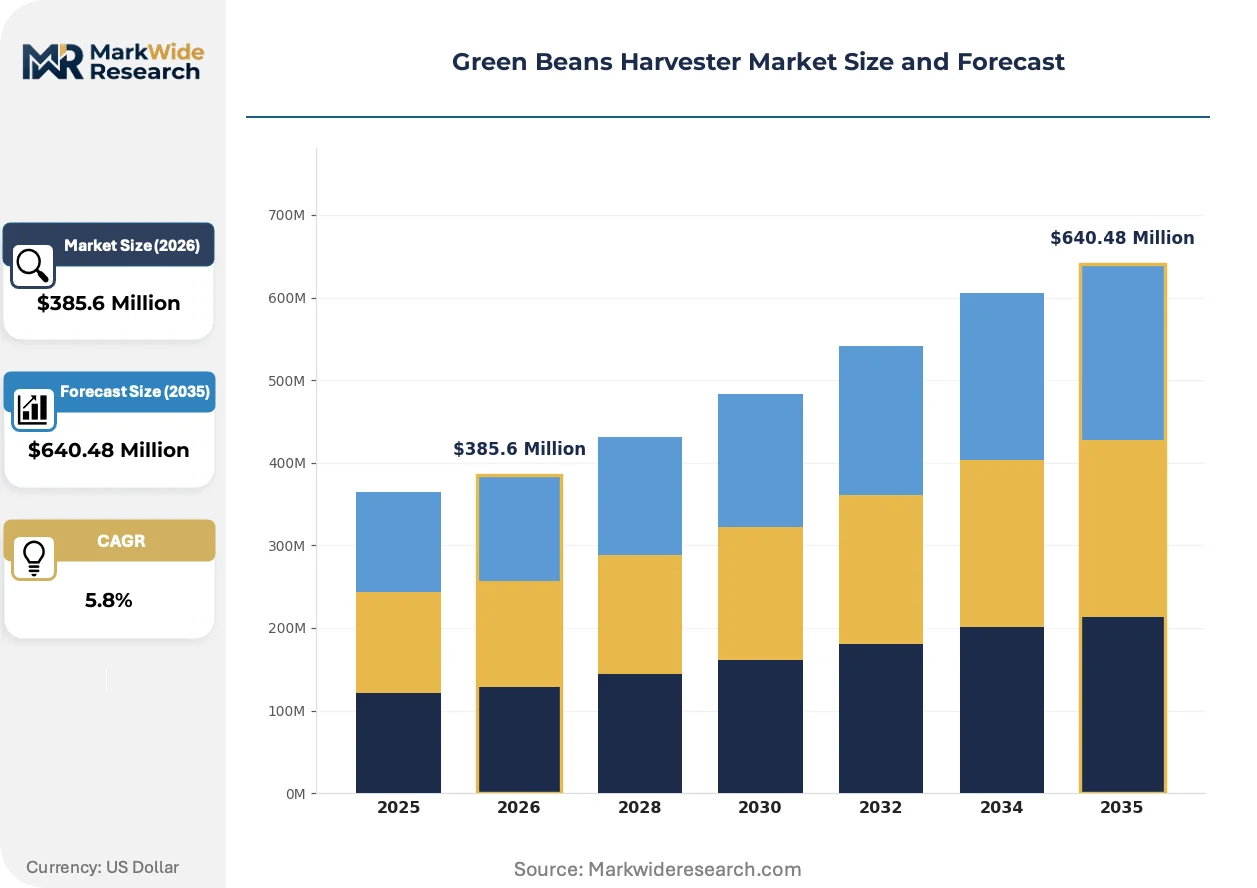
Market Dynamics
Electric drive architectures are restructuring competitive advantage across green bean harvesting fleets as European F-Gas Regulation and EPA Tier 4 Final standards simultaneously compress diesel-powered equipment margins and redirect R&D budgets toward battery-electric platforms.
Growth Catalysts
- EU Green Deal Mechanization Subsidies:Agricultural cooperatives in Poland's vegetable belt are redirecting capital toward lower-carbon harvesting systems through targeted fiscal support.
- Specialty Crop Processor Consolidation:Pacific Northwest processing facilities are scaling mechanized procurement to secure consistent pod quality at volume.
- GPS-IoT Integration:Yield mapping and fleet management software clusters are capturing recurring revenue streams beyond hardware sales.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Cell manufacturing bottlenecks in East Asian supplier networks are extending electric harvester lead times.
- Hydraulic System Obsolescence Costs:Tier 4 Final retrofit requirements for legacy diesel fleets are forcing premature capital write-downs.
- Specialized Technician Scarcity:Electric drivetrain diagnostics and battery management expertise remains concentrated among limited service networks.
Strategic Opportunities
- Organic Vegetable Processing Expansion:Certification-driven demand for gentle-handling harvesters is opening addressable base beyond conventional commodity growers.
- CE Marking Acceleration:ISO 12100 machinery safety compliance is becoming a competitive differentiator for Eastern European OEM export eligibility.
- Cooperative Fleet Electrification:Consolidated purchasing power among Nordic agricultural associations favors automated system rollouts.
Industry Challenges
- Legacy Hydraulic Integration Complexity:Retrofitting existing cutter bar and conveyor architectures with electric actuators requires extensive mechanical re-engineering.
- Service Revenue Model Transition:Shifting from equipment sales to contracted uptime guarantees demands new organizational capabilities in predictive maintenance analytics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Beans Harvester Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Harvesters, Manual Harvesters, Automated Systems, Field Vehicles End User: Agricultural Cooperatives, Individual Farmers, Large Enterprises, Research Institutions Deployment: On-Farm, Contracted Services, Leasing, Direct Purchase Technology: Hydraulic Systems, Electric Drive, GPS Navigation, IoT Integration |
| Companies Covered | Oxbo International, Asa-Lift, Fontana srl, PMC, Weremczuk Agromachines, John Deere, FMC Technologies, Ploeger Machines BV, Kovaco Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Beans Harvester Market Trends and Innovations
Autonomous navigation and pod-sorting computer vision are compressing labor dependency while redefining value capture toward software-enabled service layers.
On-board optical grading systems using multispectral cameras and machine-learning classification are decentralizing quality control from centralized processing facilities to the point of harvest. Fresh-market cooperatives in the Netherlands are deploying these units at commercial scale. This capability is decentralizing premium-grade pricing power toward field-level operators who can certify pod condition before transport.
Europe's F-Gas Regulation is accelerating refrigerant-phaseout timelines that indirectly pressure diesel-hydraulic harvester cooling systems. Equipment OEMs serving export markets must redesign thermal management architectures to maintain CE marking eligibility. Polish and Romanian cooperatives are prioritizing electric platforms to preempt compliance-driven procurement disruptions.
Cooperative buyers are consolidating fleet purchasing decisions through multi-year framework agreements that bundle equipment, maintenance, and yield optimization software. This aggregation is displacing individual farm-level negotiations across the vegetable belt. Denmark's agricultural associations demonstrate this pattern most visibly, with collective procurement covering eighty percent of annual harvester acquisitions.
Green Beans Harvester Market Segmentation
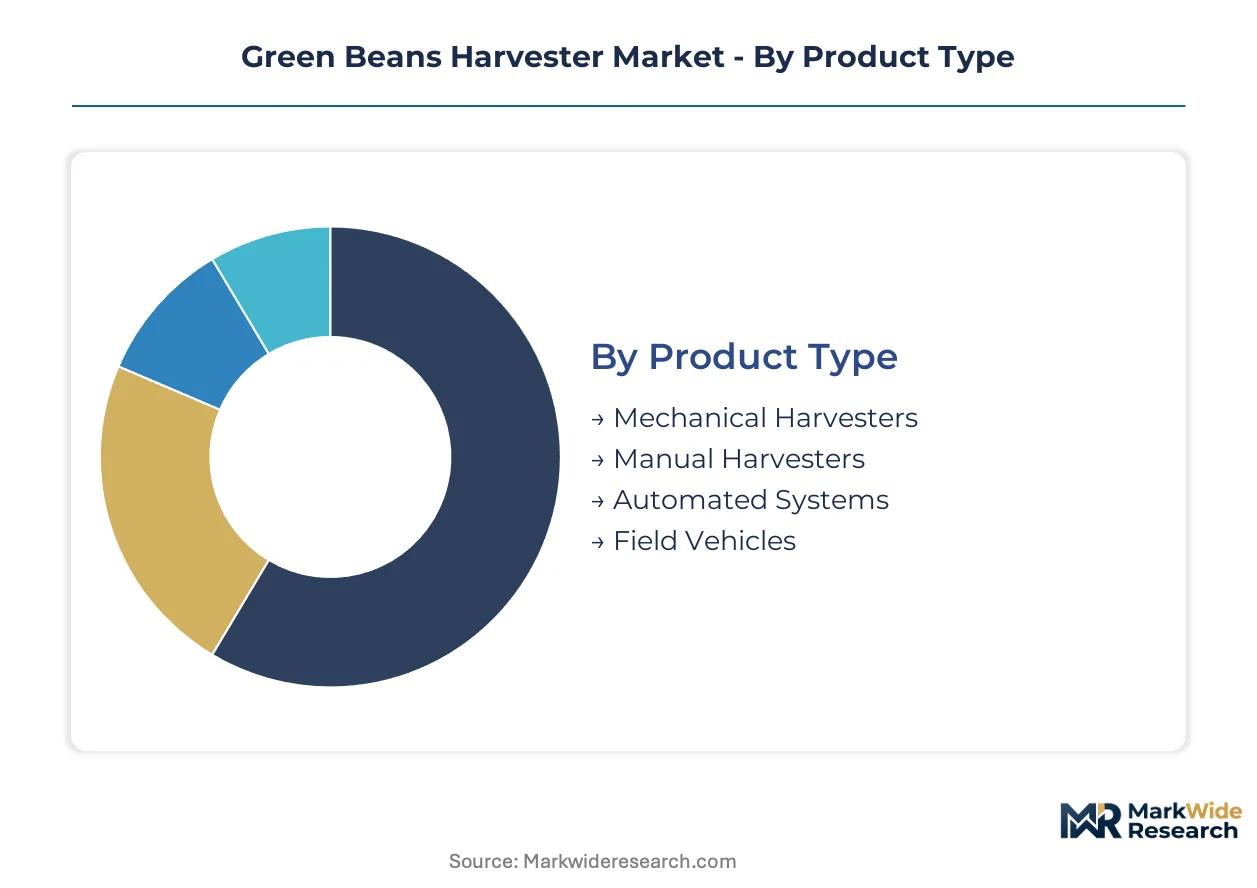
Equipment upgrade cycles in green bean harvesting vary sharply by segment, with electric platforms displacing hydraulic fleets at different velocities across cooperative and enterprise buyer pools. Segmentation reveals where replacement urgency concentrates and which procurement channels are capturing margin from hardware transitions.
Product Type:
Replacement urgency runs highest where Tier 4 Final retrofit costs exceed residual equipment value, reshaping fleet composition across mature agricultural regions.
- Mechanical Harvesters:Floating cutter bar architectures with 8–15 mm blade spacing dominate installed bases across Poland's vegetable belt and the Pacific Northwest. Cooperatives here face premature write-downs as EPA Tier 4 Final compliance costs erode diesel-hydraulic economics.
- Automated Systems:GPS-IoT integrated platforms with electric drivetrains are capturing disproportionate R&D allocation from OEMs serving Nordic cooperative buyers. Denmark's agricultural associations bundle these with predictive maintenance contracts, displacing individual farm negotiations.
- Manual Harvesters:Hand-held pod collection tools persist in research plot applications and smallholder contexts where field geometry prevents mechanized access.
- Field Vehicles:Self-propelled carrier platforms support modular cutter bar attachment across varied terrain grades in Eastern European procurement cycles.
Mechanical harvesters sit at the top of the volume ranking, with automated systems climbing the fastest.
End User:
Customer scale determines pricing leverage and service model attachment rates, with consolidated buyers extracting bundled terms unavailable to fragmented purchasers.
- Agricultural Cooperatives:Consolidated purchasing power across Poland, Romania, and Denmark enables multi-year framework agreements covering eighty percent of annual acquisitions. These buyers prioritize electric platforms to preempt F-Gas Regulation compliance disruptions.
- Large Enterprises:Specialty crop processors in the Pacific Northwest scale mechanized procurement to secure consistent pod quality at volume, driving fleet standardization across processing catchments.
- Individual Farmers:Fragmented demand concentrates in used equipment markets and leasing channels where capital constraints limit new platform adoption.
- Research Institutions:Plot-scale trials and breeding programs generate niche demand for gentle-handling configurations that preserve sample integrity.
Agricultural cooperatives command the steepest volume concentration, while large enterprises are gaining share fastest through processor consolidation.
Deployment:
Ownership models are restructuring as battery-electric capex burdens shift risk preferences toward contracted uptime guarantees.
- Direct Purchase:Capital acquisition persists among cooperatives with access to EU Green Deal mechanization subsidies redirecting procurement toward lower-carbon technologies.
- Leasing:Battery supply bottlenecks and technician scarcity are extending electric harvester lead times, pushing risk-averse buyers toward lessor balance sheets.
- Contracted Services:Yield mapping and fleet management software clusters are capturing recurring revenue streams beyond hardware sales, particularly in Dutch fresh-market cooperatives deploying optical grading at commercial scale.
- On-Farm:Captive equipment operation remains standard for large enterprises with dedicated maintenance capabilities and volume thresholds justifying dedicated fleet investment.
Direct purchase retains the largest transaction volume, with contracted services expanding most quickly through software-enabled service layers.
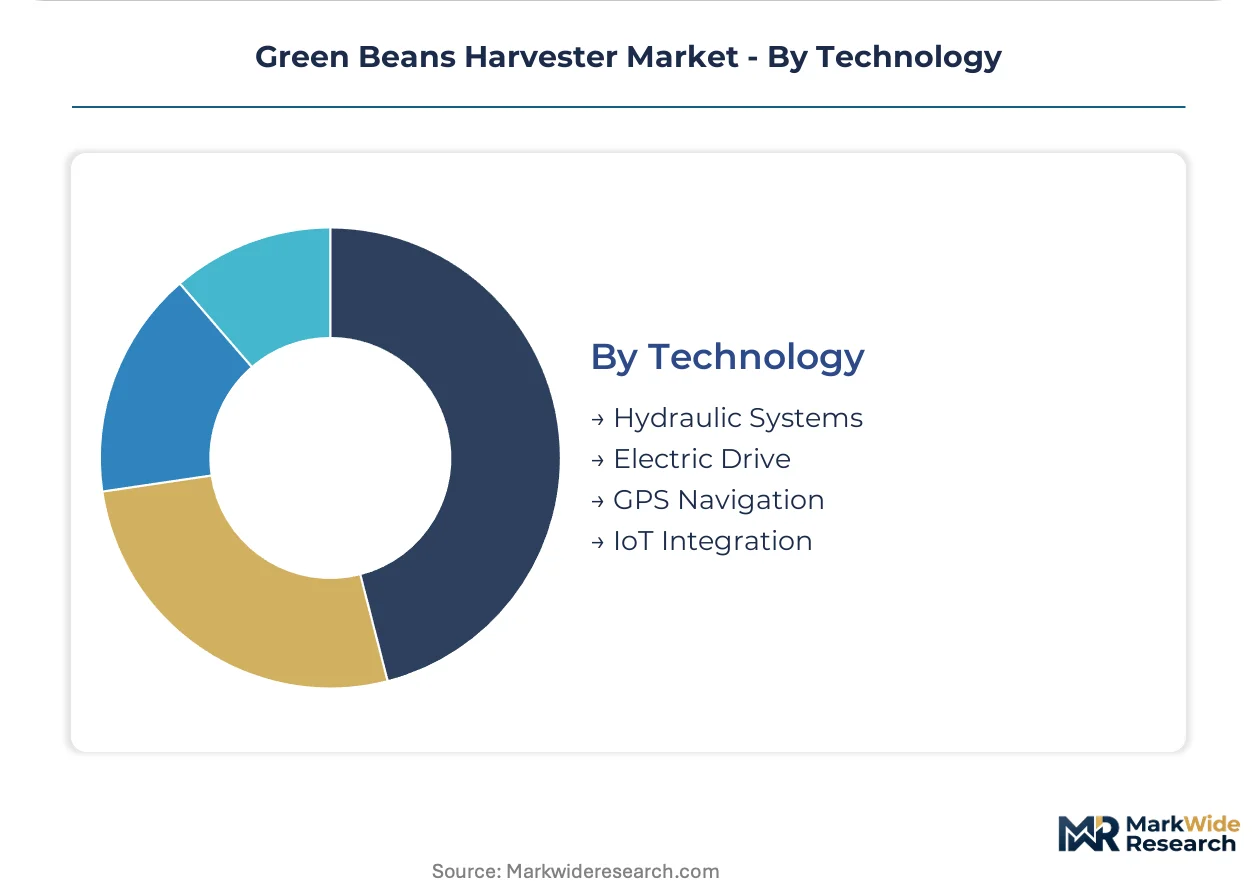
Technology:
Technology choices are hardening into competitive moats as hydraulic-to-electric retrofits demand extensive mechanical re-engineering of legacy architectures.
- Electric Drive:Battery-electric platforms with thermal management redesigned for F-Gas Regulation compliance are securing CE marking eligibility for Polish and Romanian cooperative exports. Cell manufacturing bottlenecks in East Asian supplier networks constrain availability.
- IoT Integration:Predictive maintenance analytics and yield optimization software are displacing margin pools from hardware toward service revenue models, demanding new organizational capabilities from OEMs.
- Hydraulic Systems:Legacy diesel-hydraulic cooling architectures face obsolescence costs under Tier 4 Final standards, forcing premature capital write-downs across mature installed bases.
- GPS Navigation:Autonomous navigation clusters compress labor dependency while enabling sub-inch field coverage precision for fresh-market grade certification.
Hydraulic systems retain the deepest installed base, with electric drive gaining share fastest through regulatory compression of diesel margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's vegetable belt concentrates cooperative procurement for electric harvester platforms, with EU Green Deal subsidies redirecting capital toward lower-carbon mechanization across Eastern European procurement cycles.
United States
Specialty crop processors in the Pacific Northwest drive fleet standardization for consistent pod quality at volume. EPA Tier 4 Final standards compress diesel-hydraulic margins and accelerate electric drivetrain R&D allocation. Washington State processing facilities anchor mechanized procurement scaling across regional catchments.
Poland
Agricultural cooperatives consolidate purchasing power through multi-year framework agreements covering eighty percent of annual acquisitions. EU Green Deal mechanization subsidies redirect procurement toward battery-electric platforms. The Łódź vegetable belt prioritizes electric systems to preempt F-Gas Regulation compliance disruptions.
Denmark
Nordic agricultural associations bundle GPS-IoT integrated platforms with predictive maintenance contracts. Cooperative fleet electrification favors automated system rollouts through consolidated purchasing structures. Jutland's vegetable processing clusters demonstrate collective procurement patterns displacing individual farm negotiations.
Romania
Emerging cooperative consolidation creates demand for CE-marked equipment with regionally calibrated service networks. F-Gas Regulation timelines pressure thermal management redesigns for export eligibility. The Transylvanian vegetable belt scales mechanized procurement as processing capacity expands.
Netherlands
Fresh-market cooperatives deploy optical grading systems with multispectral cameras at commercial scale. GPS-IoT integration captures recurring revenue through yield mapping and fleet management software clusters. North Holland's glasshouse-adjacent field operations anchor point-of-harvest quality certification systems.
Green Beans Harvester Market Competitive Landscape
Technology licensing dominates the current landscape as battery-electric architectures restructure competitive advantage. The vendor base separates into three tiers: integrated agricultural equipment conglomerates with broad crop portfolios, specialty harvester OEMs focused on gentle-handling pod systems, and regional fabricators serving localized field geometries. Strategic archetypes include full-line suppliers leveraging scale economies, niche specialists commanding premium pricing through crop-specific engineering depth, and emerging electric-platform entrants capturing subsidy-driven procurement windows. M&A activity concentrates on sensor and autonomy software assets, while capacity expansion targets battery pack assembly and electric drivetrain manufacturing.
Within the specialty OEM tier, Oxbo International and Asa-Lift exemplify engineering-depth positioning across distinct regional markets. Weremczuk Agromachines occupies a position calibrated to Eastern European service network requirements. These three anchors demonstrate how geographic specialization and crop-specific platform heritage create defendable positions against integrated conglomerate competition.
| Leading Market Players |
|---|
| Oxbo International |
| Asa-Lift |
| Fontana srl |
| PMC |
| Weremczuk Agromachines |
| John Deere |
| FMC Technologies |
| Ploeger Machines BV |
| Kovaco Machinery |
| Others |
Pricing and Supply Chain Analysis
Battery-electric drivetrain adoption simultaneously compresses legacy hydraulic equipment residual values and concentrates margin capture among OEMs with captive cell supply arrangements. Tier 4 Final retrofit costs and F-Gas Regulation compliance timelines are accelerating depreciation schedules across diesel-hydraulic installed bases while cooperative buyers extract bundled pricing through multi-year framework agreements.
Pricing Analysis
Input-cost pass-through from lithium-ion cell supply bottlenecks is compressing electric harvester margins and extending quoted lead times. Pricing stratifies across premium GPS-IoT integrated platforms, standard mechanical configurations, and economy-tier refurbished units, with differentiation driven by certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying as Polish and Romanian cooperatives prioritize CE-marked electric platforms. Individual farmers exhibit highest price sensitivity, constrained by capital access and residual equipment liquidity, while Nordic agricultural associations demonstrate lowest sensitivity through consolidated purchasing power and subsidy eligibility.
Supply Chain Analysis
Freight cost volatility from East Asian battery cell manufacturing hubs is amplifying landed cost uncertainty for European and North American OEM assembly operations. Cell production concentrates in China, South Korea, and Japan, while hydraulic component fabrication draws from Germany, Italy, and the United States. Supply chain risk centers on single-source vulnerability for high-nickel cathode chemistries and semiconductor content for IoT-enabled platforms. Distribution runs through cooperative purchasing consortia in Poland and Denmark, displacing traditional dealer networks across the vegetable belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The green bean harvester market reads as a late-cycle quality story as organic certification requirements and gentle-handling specifications redirect procurement toward premium-tier platforms with optical grading and predictive maintenance capabilities.
For Market Incumbents: Cement engineering-depth positioning by acquiring autonomy software assets and expanding electric drivetrain manufacturing capacity in Poland to serve EU Green Deal subsidy windows. Prioritize ISO 12100 certification investment to defend CE marking eligibility against emerging Eastern European fabricators. Channel control through cooperative framework agreements remains the priority lever against price erosion in the standard tier. For New Entrants and Emerging Players: Launch via contracted service models targeting individual farmers and research institutions underserved by cooperative procurement structures. White-space concentrates in optical grading retrofits for legacy mechanical fleets and battery-electric platforms calibrated for compact Nordic field geometries. A leasing-centered go-to-market angle bypasses capital constraints limiting direct purchase adoption among fragmented buyers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators with established service networks but limited electric platform development, offering bolt-on autonomy and battery integration opportunities. Long-term viability favors specialty OEMs with crop-specific engineering heritage over diversified agricultural equipment conglomerates. The signal to watch is cooperative procurement consolidation rates in Romania and Poland as inflection indicators for framework agreement pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Drivetrain Platform Development | Battery-electric architectures secure F-Gas Regulation compliance and CE marking eligibility for Polish cooperative exports. |
| Autonomy Software Acquisition | Computer vision and GPS-IoT assets compress labor dependency while capturing recurring service revenue from Dutch fresh-market cooperatives. |
| Cooperative Framework Agreement Expansion | Multi-year bundled contracts with Denmark's agricultural associations displace individual farm negotiations and standardize fleet composition. |
| Regional Service Network Calibration | Eastern European procurement cycles favor OEMs with technician density for electric drivetrain diagnostics and battery management. |
| Optical Grading System Integration | Multispectral camera deployment decentralizes quality control to point-of-harvest, enabling premium-grade pricing certification. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with agricultural cooperative procurement officers, OEM platform engineers, aftermarket service heads, and specialty crop processors with secondary validation against customs and trade data, SEC filings from diversified agricultural equipment conglomerates, EU Green Deal subsidy disbursement records, and EPA Tier 4 Final compliance documentation. Bottom-up equipment shipment tracking and top-down addressable market sizing were triangulated against cooperative fleet survey data.
Historical reference periods anchored the projection horizon through documented replacement cycle patterns and regulatory phase-in timelines. The analytical framework modeled segmentation across product type, end-user scale, deployment model, and technology architecture, with electric drivetrain adoption curves and cooperative consolidation rates serving as primary forecast inputs. CAGRs were derived from fitted growth trajectories adjusted for subsidy elasticity and battery supply constraint scenarios.
Several conditions sit outside the modeled scope, including unannounced regulatory accelerations, breakthrough solid-state battery commercialization timelines, and cooperative insolvency events disrupting framework agreement continuity. Forecasts reflect documented assumptions that stakeholders should weight against their own operating context, particularly regarding technician training capacity and cell supplier diversification strategies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Agriculture Seeder Market
Agricultural Equipment
Tree Transplanters Market
Agricultural Equipment
Gardening Equipment Market
Agricultural Equipment
Greenhouse Kit Market
Agricultural Equipment
Feeding Hopper Market
Agricultural Equipment
India Color Sorter Market
Agricultural Equipment
Bulk Reception Feeder Market
Agricultural Equipment
Farm Tire Market
Agricultural Equipment
Feed Mixer Market
Agricultural Equipment
Billhook Market
Agricultural Equipment
Global Rice Transplanter Market
Agricultural Equipment
Flexible Silos Market
Agricultural Equipment
Agricultural Rake Market
Agricultural Equipment
Soil Mixer Market
Agricultural Equipment
Commercial Vegetable Chopper Market
Agricultural Equipment
Electric Pruning Shears Market