
 North America Electric Zero Turn Mower Market | 2026-2036
North America Electric Zero Turn Mower Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electric Zero Turn Mower Market Analysis
Aftermarket service revenue is tilting from engine rebuilds toward battery pack diagnostics and electric motor replacement programs. Deere & Company leverages its dealer network density to capture recurring maintenance contracts across the Midwest. Husqvarna Group anchors its position through R&D intensity in brushless motor controllers. EGO POWER+ specializes in direct-to-consumer battery platforms that reduce channel friction for residential buyers.
North America electric zero turn mowers are battery-powered riding machines with independently controlled rear-wheel motors enabling zero-radius turns, typically operating at 48–72 volt DC architectures with lithium-ion phosphate or lithium-ion battery packs rated for 3–8 hours of continuous cutting. The equipment serves commercial landscaping, municipal groundskeeping, and large-property residential turf maintenance where maneuverability and reduced noise signatures matter. Commercial deployments lead volume owing to fleet replacement cycles and total cost of ownership advantages from eliminated fuel and reduced maintenance. Residential segments show faster growth as homeowner familiarity with cordless yard tools expands. Power ratings below 15 kW dominate unit shipments, though 15–30 kW configurations capture disproportionate value in professional applications.
EPA small spark-ignition engine regulations and California Air Resources Board zero-emission equipment mandates restrict gasoline-powered alternatives, directly expanding addressable demand for electric substitutes. NHTSA and OSHA guidelines on commercial equipment operator safety influence braking and rollover protection standards that manufacturers must integrate. Stakeholders must monitor battery recycling infrastructure development and state-level rebate program durability to validate long-term total cost of ownership claims against gasoline baseline economics.
Market Dynamics
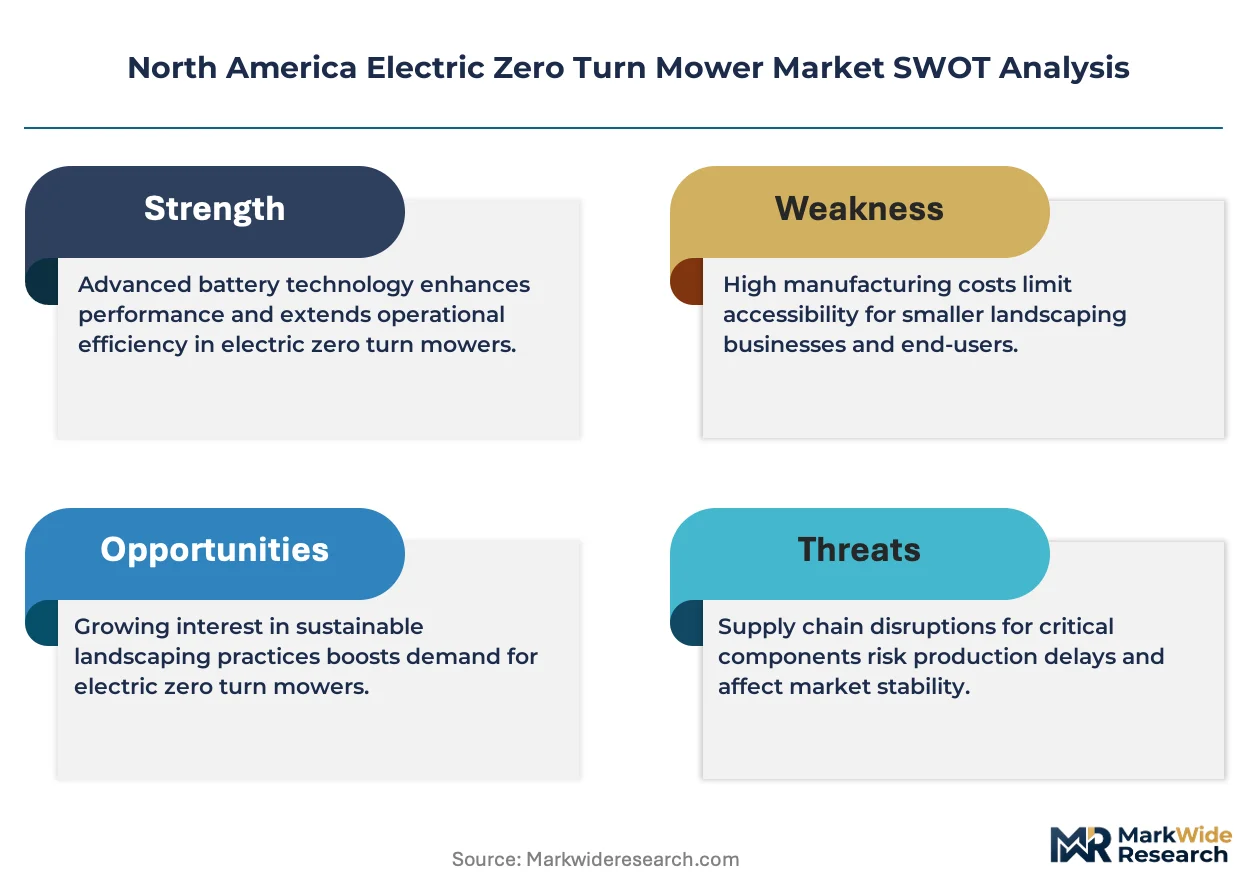
EPA Phase 3 small spark-ignition engine standards and California Air Resources Board zero-emission mandates are compressing gasoline-powered equipment replacement cycles across commercial landscaping fleets, forcing capital reallocation toward battery-electric drivetrains before natural end-of-life.
Growth Catalysts
- EPA Phase 3 Standards:Federal emissions regulations on small spark-ignition engines tighten exhaust limits, accelerating fleet turnover toward electric alternatives in commercial landscaping.
- Municipal Noise Ordinances:Urban jurisdictions across the southeastern United States restrict gasoline-powered equipment operating hours, expanding permissible deployment windows for battery-electric mowers.
- Lithium-Iron-Phosphate Chemistry:Improved cell thermal stability and cycle life reduce battery replacement frequency, improving total cost of ownership calculations for fleet managers.
Market Restraints
- Battery Pack Cost Concentration:Cathode material processing and cell manufacturing concentrate in Asian supply chains, exposing North American OEMs to input volatility and tariff exposure.
- Charging Infrastructure Gaps:Commercial landscaping depots often lack 480V three-phase service required for rapid fleet charging, necessitating costly electrical upgrades.
- Gasoline Equipment Residual Value:Secondary markets for used gasoline mowers remain liquid, creating substitution economics that delay some fleet electrification decisions.
Strategic Opportunities
- Texas Suburban Developments:Rapid master-planned community expansion around Dallas-Fort Worth and Houston creates sustained demand for commercial turf maintenance contracts favoring low-noise equipment.
- Battery-as-a-Service Models:Leasing structures that separate battery asset ownership from mower procurement reduce upfront capital barriers for mid-size landscaping operators.
- Brushless Motor Convergence:Integration of silicon carbide power electronics with permanent magnet motors enables higher power density in compact deck configurations.
Industry Challenges
- High-Voltage Technician Certification:Commercial dealer networks face scarcity of ASE-certified technicians qualified for 72V DC system diagnostics and repair.
- Battery Recycling Infrastructure:Reverse logistics for end-of-life lithium-ion packs remain underdeveloped, creating compliance exposure under emerging state extended producer responsibility frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electric Zero Turn Mower Market |
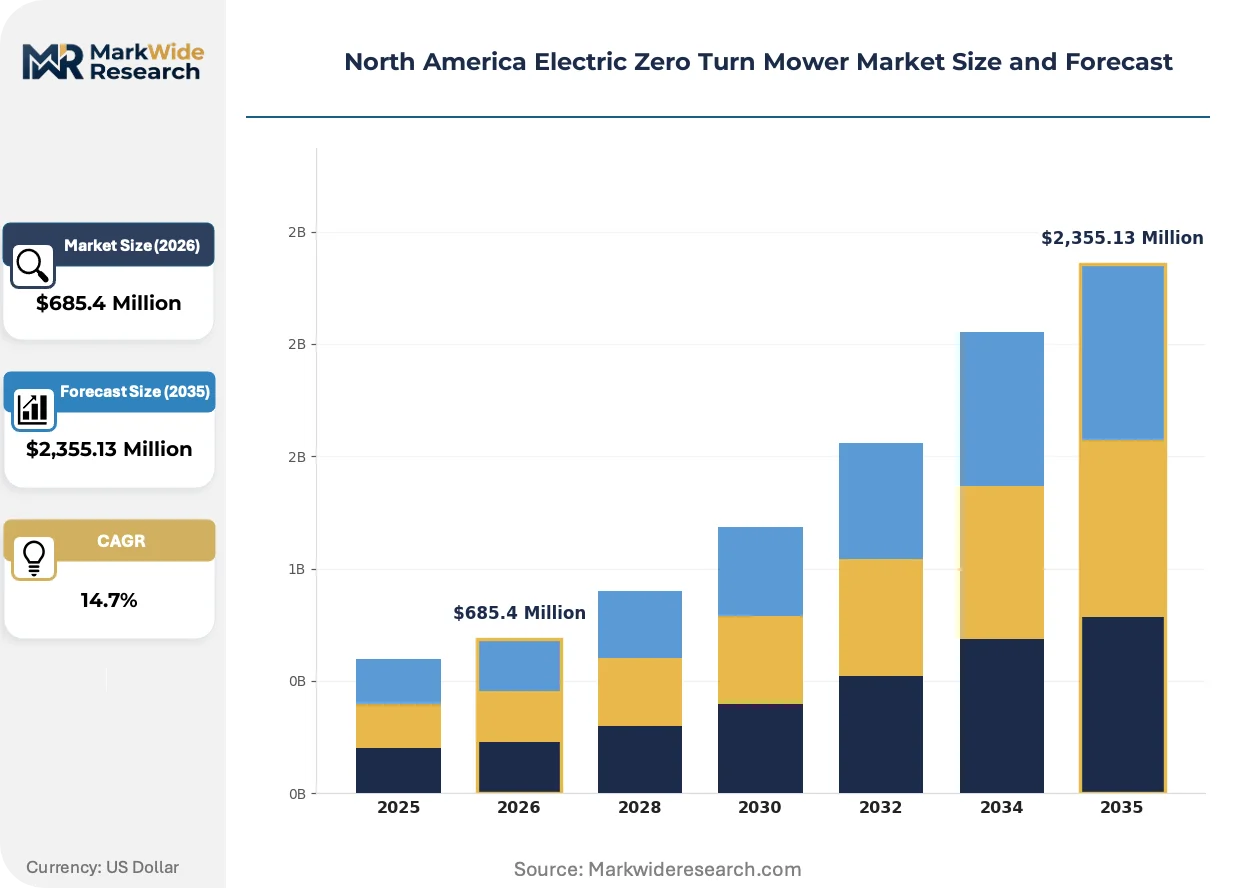
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,355.13 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial, Residential, Industrial, Turf Management Power Rating: Below 15 kW, 15–30 kW, 30–50 kW, Above 50 kW Deployment: On-site, Off-site, Rental, Subscription Customer Type: Homeowners, Landscaping Companies, Municipalities, Golf Courses |
| Companies Covered | Ariens Company, MTD Products, Husqvarna Group, EGO POWER+, Deere & Company, The Toro Company, Briggs & Stratton Corporation, Honda Power Equipment, Kubota Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electric Zero Turn Mower Market Emerging Trajectories
Electrification is compressing traditional equipment lifecycle economics while forcing parallel innovation in power electronics, thermal management, and service delivery models across the commercial landscaping value chain.
Silicon carbide MOSFETs in motor controllers are rendering obsolete conventional IGBT-based architectures that dominated earlier electric mower generations. Fleet operators in Florida and Georgia are specifying SiC-equipped models for reduced switching losses and extended runtime per charge. The technology is rendering obsolete the historical trade-off between cutting power and battery endurance that constrained early electric zero-turn adoption.
California Air Resources Board zero-emission equipment mandates prohibit gasoline-powered small off-road engine sales starting in designated model years, with phase-in schedules accelerating through the forecast window. Landscaping contractors in the Sacramento and Central Valley regions are pre-buying electric equipment ahead of compliance deadlines. The regulation is compressing replacement timelines for equipment that would otherwise operate for additional seasons under normal depreciation cycles.
Commercial buyers are consolidating procurement authority at the fleet level rather than delegating equipment selection to individual crew supervisors. National landscaping service chains are mandating standardized electric platforms across branch operations to simplify parts inventory and technician training. This concentration is most visible in the southeastern United States, where multi-state operators seek volume pricing and unified service agreements from OEMs.
North America Electric Zero Turn Mower Market Segmentation
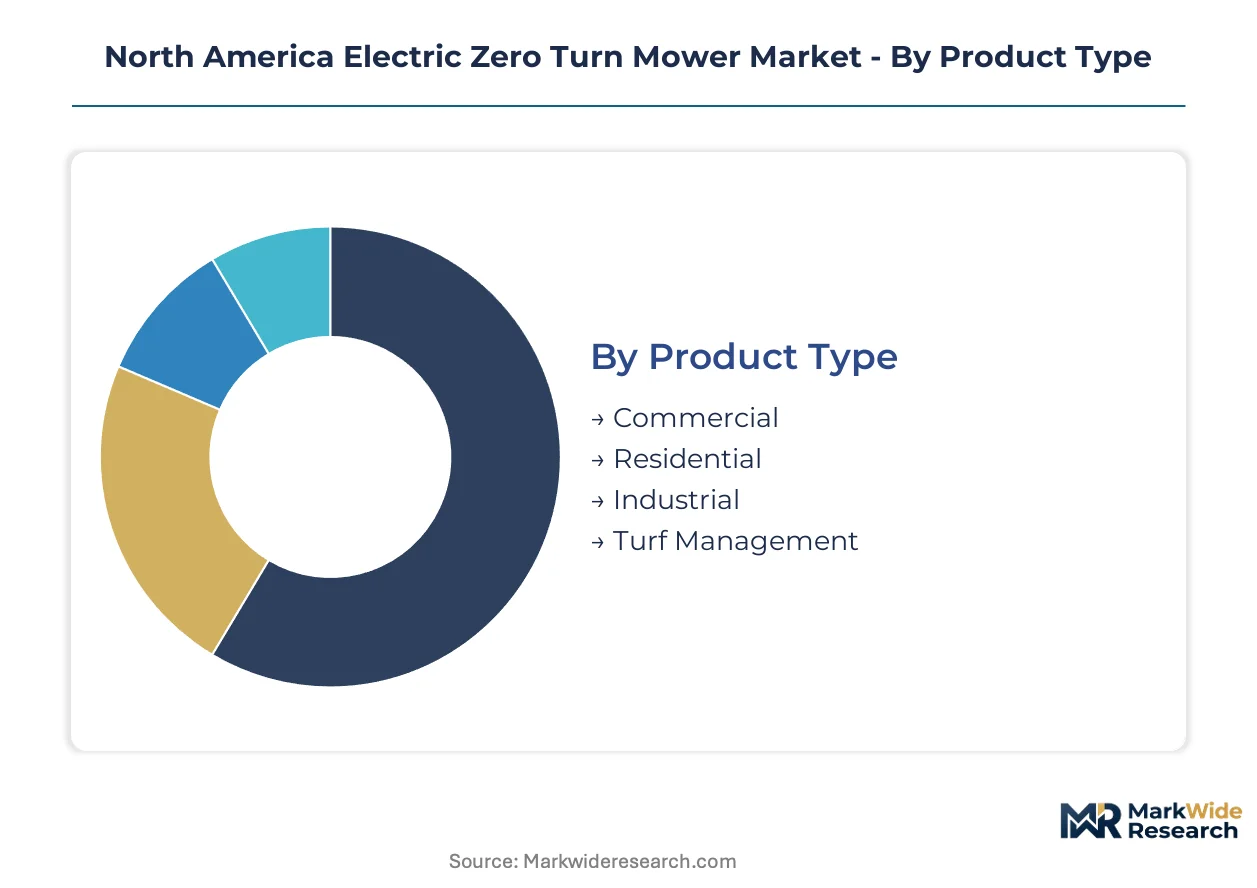
Electric zero-turn mower procurement patterns diverge sharply across user profiles, with commercial fleet operators prioritizing runtime and service integration while residential buyers emphasize acquisition cost and storage footprint. Understanding these segment boundaries clarifies where OEMs must configure distinct product architectures versus where scale economies apply.
Product Type:
Landscaping contractors deploy equipment across property scales ranging from suburban residential lots to municipal parks and sports complexes, creating tiered performance requirements that shape blade deck sizing, battery capacity, and chassis durability specifications.
- Commercial:Heavy-duty steel decks and dual-motor drivetrains rated for 2,000+ annual operating hours dominate this tier. Fleet operators in Florida and Georgia specify these units for year-round turf contracts where downtime carries penalty clauses.
- Residential:Compact lithium-ion packs and folding ROPS structures address garage storage constraints. Homeowners in Texas master-planned communities drive volume here, attracted by noise ordinances permitting early-morning weekend mowing.
- Industrial:Reinforced cutting systems handle brush clearing and rough-terrain applications beyond manicured turf. Airport authorities and utility right-of-way contractors specify these for vegetation management near infrastructure.
- Turf Management:Precision height-of-cut controls and low ground-pressure tires protect playing surfaces. Sports field managers at collegiate and professional facilities prioritize these specifications for aesthetic consistency.
Established volume favors Commercial; emerging adoption favors Residential.
Power Rating:
Electrification economics shift nonlinearly with motor sizing, as battery cost curves and thermal management complexity create distinct competitive dynamics across kilowatt tiers.
- Below 15 kW:Single-blade configurations and air-cooled motors minimize unit cost. These systems capture the bulk of residential unit shipments, though revenue per unit remains modest.
- 15–30 kW:Dual-motor architectures with silicon carbide inverters deliver professional-grade cutting power with runtime exceeding six hours. Landscaping companies in the southeastern United States concentrate procurement here, valuing the elimination of mid-day charging interruptions.
- 30–50 kW:Liquid-cooled battery thermal management and reinforced hydrostatic transmissions address sustained high-load conditions. Municipalities specify these for highway median maintenance and flood control levee mowing.
- Above 50 kW:Custom chassis integrations and extended-range battery packs serve specialty applications. Airport runway perimeter maintenance and large-scale solar farm vegetation control represent niche demand pockets.
Unit economics favor Below 15 kW; margin expansion favors 15–30 kW.
Deployment:
Capital structure preferences among landscaping operators are fragmenting traditional ownership models, with liquidity constraints and technology uncertainty driving alternative access structures.
- On-site:Purchased equipment deployed from company depots with dedicated charging infrastructure. National landscaping chains favor this model for brand standardization and technician specialization.
- Off-site:Equipment housed at third-party logistics facilities with pooled maintenance services. Regional cooperatives in the Midwest use this structure to share peak-season capacity.
- Rental:Short-term access for storm recovery, seasonal spikes, or equipment failure coverage. Hurricane response contractors in the Gulf Coast states drive episodic demand here.
- Subscription:All-inclusive per-acre pricing bundling equipment, maintenance, and battery refresh cycles. Emerging mid-size operators in California test this model to navigate CARB compliance timelines without capital commitment.
Asset control favors On-site; balance sheet flexibility favors Subscription.
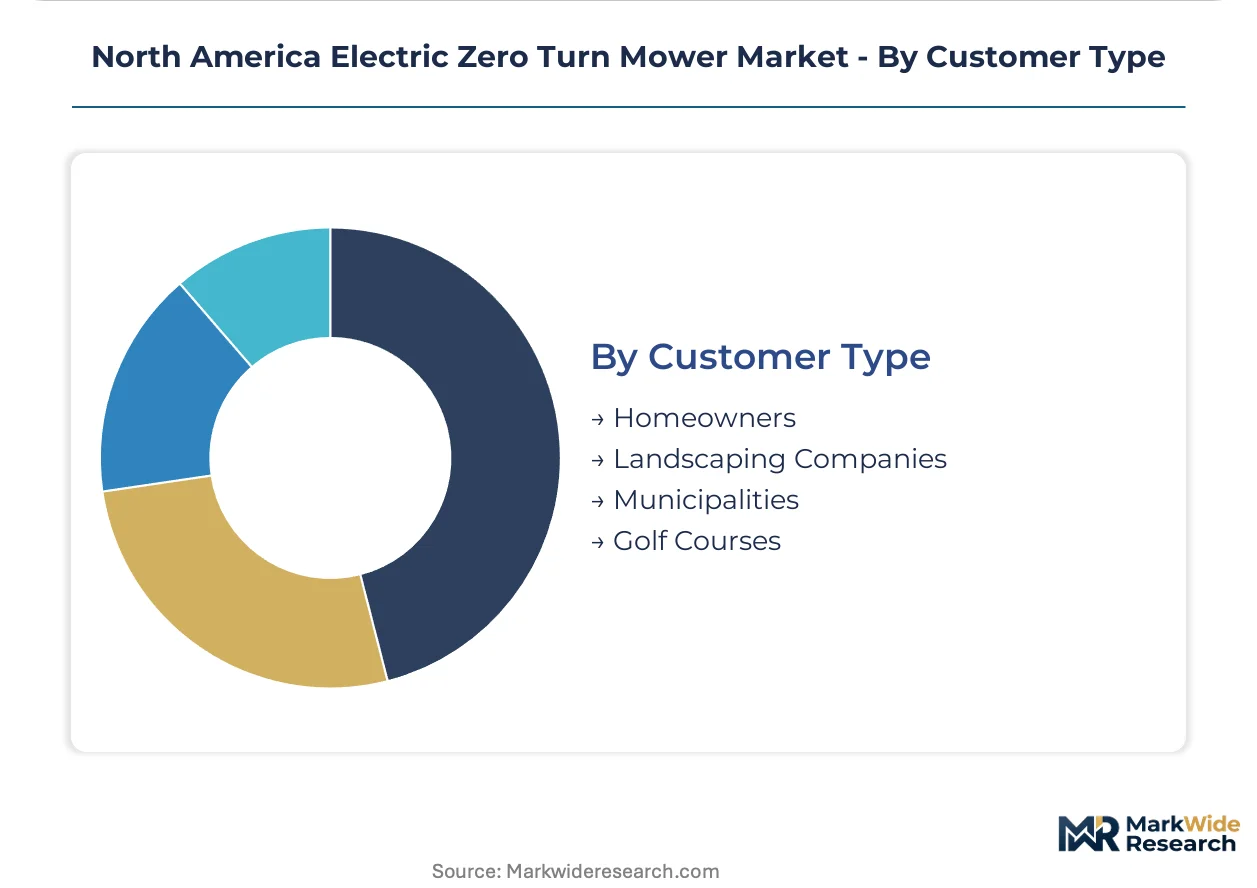
Customer Type:
Procurement authority and evaluation criteria vary systematically across buyer categories, with institutional purchasers emphasizing total cost of ownership documentation and residential buyers responding to point-of-sale incentives.
- Homeowners:Single-unit purchases triggered by gasoline equipment failure or municipal rebate program enrollment. Big-box retail and direct-to-consumer channels capture this demand.
- Landscaping Companies:Fleet-level negotiations with standardized platforms across branch operations. Multi-state operators in the southeastern United States leverage volume commitments for service agreement concessions.
- Municipalities:Formal bidding processes with emissions compliance and noise restriction documentation requirements. Procurement departments in California and Texas cities specify electric alternatives to meet sustainability mandates.
- Golf Courses:Precision performance specifications and aesthetic quality thresholds supersede pure cost metrics. Superintendents at resort and private clubs prioritize cut quality consistency for tournament preparation.
Procurement scale favors Landscaping Companies; specification intensity favors Golf Courses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential buyers in Texas and Florida exhibit the highest price elasticity, while commercial fleet operators in California accept premium pricing to secure CARB compliance. Midwest landscaping companies occupy the middle ground, negotiating volume discounts against total cost of ownership benchmarks.
United States
Commercial landscaping fleets in Florida and Georgia drive replacement demand under year-round turf maintenance contracts. EPA Phase 3 small spark-ignition engine standards accelerate turnover timelines for gasoline equipment ahead of natural depreciation cycles. Dallas-Fort Worth suburban developments concentrate procurement authority with national service chains seeking standardized electric platforms.
Canada
Municipal groundskeeping departments in Ontario and British Columbia prioritize low-noise equipment for urban park maintenance. Health Canada guidelines on commercial equipment operator safety influence braking and rollover protection specifications in procurement tenders. Toronto-area landscaping cooperatives test battery-as-a-service models to reduce upfront capital barriers for mid-size operators.
Southeastern United States
Master-planned communities across Atlanta and Charlotte sustain commercial mower utilization rates through multi-year landscaping contracts. Municipal noise ordinances in these jurisdictions restrict gasoline-powered equipment operating hours, expanding permissible deployment windows for battery-electric alternatives. Regional equipment distributors report accelerating inquiries for 15–30 kW configurations from multi-state operators.
California
Landscaping contractors in Sacramento and the Central Valley pre-buy electric equipment ahead of CARB zero-emission equipment mandate deadlines. The state's zero-emission small off-road engine sales prohibition compresses replacement timelines for equipment that would otherwise operate additional seasons. Bay Area municipalities specify electric alternatives in formal bidding processes to meet sustainability documentation requirements.
Texas
Houston-area hurricane response contractors generate episodic rental demand for storm recovery vegetation management. Rapid suburban expansion around Austin and San Antonio creates sustained demand for commercial turf maintenance contracts favoring low-noise equipment. State-level rebate program durability remains under monitoring by fleet managers validating long-term total cost of ownership claims.
North America Electric Zero Turn Mower Market Vendor Landscape
Capability concentration sits with specialized motor controller developers; scale advantage sits with established agricultural equipment manufacturers possessing dense dealer networks. The market structure tilts toward tiered competition where R&D intensity in power electronics separates premium positioning from commodity volume plays. Two strategic archetypes dominate: vertically integrated equipment manufacturers with captive battery supply arrangements, and platform specialists licensing drivetrain technology to private-label assemblers. Competitive moves center on dealer network expansion for service contract capture and silicon carbide power electronics integration for runtime differentiation.
Among North American equipment manufacturers, Deere & Company and The Toro Company anchor the premium tier through established commercial distribution infrastructure. Husqvarna Group occupies a position exemplifying R&D-intensive specialization in brushless motor control systems. EGO POWER+ represents the direct-to-consumer platform archetype, reducing channel friction through standardized battery ecosystems across residential product lines. These three companies collectively illustrate the strategic divergence between fleet-focused service integration and homeowner-accessible cordless tool ecosystems.
| Leading Market Players |
|---|
| Ariens Company |
| MTD Products |
| Husqvarna Group |
| EGO POWER+ |
| Deere & Company |
| The Toro Company |
| Briggs & Stratton Corporation |
| Honda Power Equipment |
| Kubota Corporation |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Asian lithium-ion cell manufacturing is compressing cathode material pricing and forcing North American OEMs to renegotiate annual supply agreements, while simultaneously eroding margins on finished mower packs as cell cost declines outpace end-product pricing power. This utilization-driven asymmetry rewards buyers with long-term offtake discipline and punishes spot-market procurement.
Pricing Analysis
Long-term offtake contracts dominate commercial fleet procurement, with national landscaping chains locking in three-year battery supply agreements indexed to lithium carbonate futures rather than accepting volatile spot pricing. Price differentiation separates CARB-compliant configurations from standard models, with California-bound equipment carrying certification premiums alongside extended thermal management warranties. Pricing pressure stems from residential segment commoditization as direct-to-consumer brands compress entry-level price points. Homeowners exhibit highest price sensitivity, while municipal procurement departments accept premium positioning for emissions documentation compliance.
Supply Chain Analysis
Export-control restrictions on silicon carbide wafer processing equipment limit capacity expansion outside China, constraining North American OEM access to next-generation power electronics. Cell manufacturing concentrates in China, South Korea, and Japan, with cathode active material processing anchored in Chinese chemical hubs. Raw material dependencies span lithium carbonate from Chilean and Australian brine operations, nickel sulfate from Indonesian integrated facilities, and copper foil from Japanese rolling mills. Tariff exposure on Chinese-origin cells creates margin volatility for non-vertically integrated assemblers. Distribution runs through authorized dealer networks for commercial accounts and big-box retail for residential buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among national landscaping service chains that mandate standardized electric platforms across multi-state operations, fragmenting procurement authority away from individual crew supervisors and toward centralized fleet managers.
For Market Incumbents: Entrench service contract capture through ASE-certified technician training programs at dense dealer networks, defending against emerging battery-as-a-service entrants. Prioritize backward integration into silicon carbide power electronics to secure runtime differentiation as SiC MOSFETs displace IGBT architectures. Channel control remains the critical lever for recurring maintenance revenue retention. For New Entrants and Emerging Players: Build out subscription-based fleet offerings targeting mid-size California landscaping operators navigating CARB compliance timelines without capital commitment. The most penetrable white space sits in per-acre pricing models bundling equipment, maintenance, and battery refresh cycles. Direct-to-consumer battery ecosystem compatibility offers the cleanest go-to-market angle for residential market entry. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across battery-as-a-service sub-segments as leasing structures separate asset ownership from equipment procurement. Long-term viability favors platform specialists with captive drivetrain technology licensable to private-label assemblers. Acquisition targets should demonstrate silicon carbide controller development capabilities. The signal to watch is state-level rebate program durability as validation of total cost of ownership economics against gasoline baselines.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-as-a-Service Model Launch | Reduces upfront capital barriers for mid-size landscaping operators facing CARB deadlines. |
| Silicon Carbide Controller Integration | Enables runtime differentiation through reduced switching losses in Florida and Georgia fleets. |
| ASE-Certified Technician Network Expansion | Captures recurring maintenance contracts as aftermarket revenue tilts toward battery diagnostics. |
| Direct-to-Consumer Battery Ecosystem Extension | Reduces channel friction for residential buyers in Texas master-planned communities. |
| Long-Term Cathode Material Offtake Agreement | Insulates margin structure from lithium carbonate volatility in Asian supply chains. |
Methodological Framework
The analysis maps commercial fleet procurement patterns, residential adoption trajectories, and battery-as-a-service model emergence, each validated through fleet managers at national landscaping chains, procurement officers at municipal groundskeeping departments, and aftermarket service directors at authorized dealer networks. Primary interview findings were cross-referenced against EPA Phase 3 regulatory filings, CARB zero-emission equipment mandate documentation, SEC 10-K disclosures from listed equipment manufacturers, and customs data tracking lithium-ion cell import volumes. Bottom-up unit shipment estimates from regional equipment distributors were triangulated against top-down market sizing derived from fleet replacement cycle analysis.
The forecast framework holds battery cost decline curves, regulatory phase-in schedules, and charging infrastructure deployment rates as fixed assumptions across the projection horizon, while varying fleet electrification urgency by state-level mandate stringency. Segmentation dimensions modeled include product type tier, power rating bracket, deployment structure, and customer category. CAGRs were derived from logistic diffusion curves fitted to early-adopter penetration data. Industry-specific forecast inputs incorporate lithium-iron-phosphate cycle life improvements and silicon carbide adoption rates in motor controller architectures.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated battery manufacturers into finished equipment would shift outcomes through pricing disruption. Cross-checking against state-level rebate program enrollment data and municipal procurement bid awards is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Global Fishing Equipments Market
Agricultural Equipment
Global Precision Harvesting Market
Agricultural Equipment
Smart Rice Transplanter Market
Agricultural Equipment
Commercial Vegetable Chopper Market
Agricultural Equipment
Battery-Operated Knapsack Sprayer Market
Agricultural Equipment
Agricultural Trailer Market
Agricultural Equipment
Square Silos Market
Agricultural Equipment
Pond Aeration System Market
Agricultural Equipment
Global Drip Emitters Market
Agricultural Equipment
Indoor Farming Equipment Market
Agricultural Equipment
Plow Folding System Market
Agricultural Equipment
Horse Drawn Farming Equipment Market
Agricultural Equipment
Feed Mixer Market
Agricultural Equipment
Gardening Equipment Market
Agricultural Equipment
Farm Equipment Market
Agricultural Equipment
Planter Market