
 Grain Silos and Ancillary Equipment Market | 2026-2036
Grain Silos and Ancillary Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Grain Silos and Ancillary Equipment Market Insights
ISO 11601 certification for grain storage equipment is rotating the competitive landscape by filtering out fabricators lacking welding and structural validation capabilities. Sukup Manufacturing Co. anchors the North American market through captive steel fabrication and extensive dealer networks. CTB Inc. leverages vertical integration from galvanized steel coil to finished bin assembly. SYMAGA competes aggressively across Eastern European and Latin American markets with modular flat-bottom designs.
Grain silos and ancillary equipment comprise cylindrical or rectangular structures engineered from corrugated galvanized steel, reinforced concrete, or aluminum alloys, designed to store cereal grains at moisture levels below 14% to prevent spoilage and pest infestation. These systems integrate aeration ducts, temperature monitoring sensors, and unloading mechanisms to preserve commodity quality across seasonal cycles. Flat bottom silos dominate volume sales among commercial storage operators due to their superior capacity economics, while hopper silos command premium positioning among feed manufacturers requiring rapid discharge. Steel construction materials sustain the largest share of new installations given their strength-to-weight ratio and field-repair accessibility.
OSHA grain handling standards in the United States, the EU Machinery Directive with CE marking requirements, and Brazil's ANVISA-adjacent agricultural storage regulations collectively mandate explosion-proof electrical systems, confined-space entry protocols, and structural load certifications. These compliance layers increase capital costs for new entrants while creating recurring retrofit demand among existing operators. Stakeholders must monitor evolving fire suppression mandates and carbon accounting rules that could reshape material selection and aeration energy specifications in forthcoming procurement cycles.
Market Dynamics
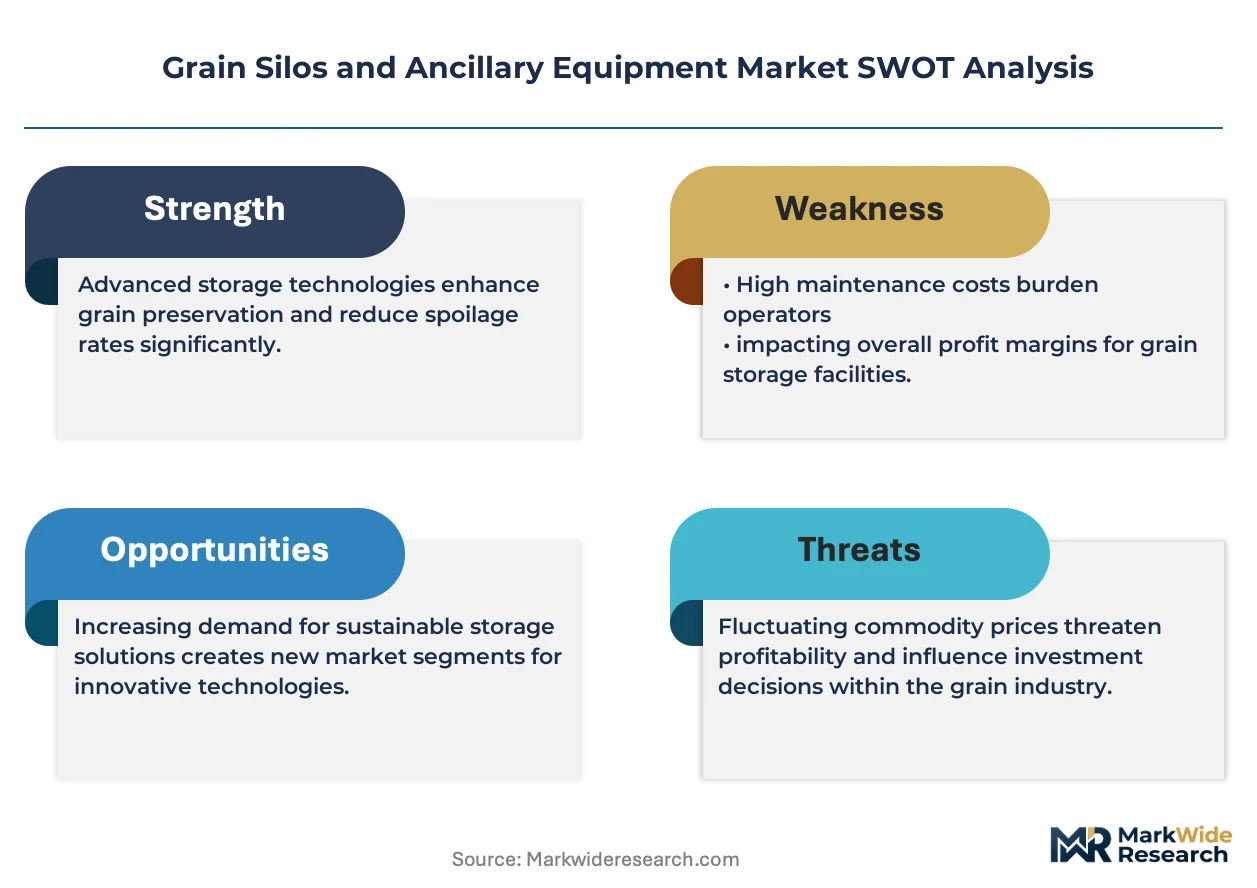
Harvest volatility across major grain belts is forcing commercial operators to overbuild storage capacity, tightening the link between silo procurement decisions and commodity price hedging strategies. This structural pressure favors larger-capacity installations with integrated aeration and monitoring systems.
Growth Catalysts
- OSHA grain handling standards:United States operators face mandatory explosion-proof electrical retrofits and confined-space entry protocols, accelerating replacement cycles for aging concrete elevators.
- Steel fabrication clustering:Brazil's agricultural expansion concentrates demand near integrated steel mills, reducing logistics costs for corrugated galvanized bin delivery.
- EU Machinery Directive CE marking:European procurement now requires validated structural load certifications, filtering tenders toward fabricators with ISO 11601 welding qualifications.
Market Restraints
- Galvanized steel coil volatility:Zinc price swings and energy-intensive hot-dip processing create margin compression for bin fabricators without captive metallurgical supply.
- Regional production concentration:Corrugated roll-forming capacity clusters in the United States Midwest and Eastern Europe, exposing Latin American buyers to extended lead times and currency risk.
- Concrete silo durability:Existing reinforced concrete structures in Ukraine and Argentina deliver 40-plus-year service lives, delaying steel replacement demand.
Strategic Opportunities
- India post-harvest infrastructure gap:Food Corporation of India procurement mandates and state-level grain buffer policies create first-mover positioning for modular flat-bottom designs.
- Carbon accounting integration:EU Green Deal reporting requirements for agricultural supply chains favor aeration systems with verified energy efficiency, creating premium tier positioning.
- IoT sensor convergence:Temperature and moisture monitoring hardware bundling with silo sales generates recurring telemetry revenue streams among commercial elevator operators.
Industry Challenges
- Welding certification bottlenecks:ISO 11601 structural validation requires specialized inspector training, constraining expansion for mid-scale fabricators.
- Legacy aeration retrofit complexity:Existing flat-bottom installations in the United States Corn Belt require custom ductwork modifications to accommodate new sensor arrays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grain Silos and Ancillary Equipment Market |
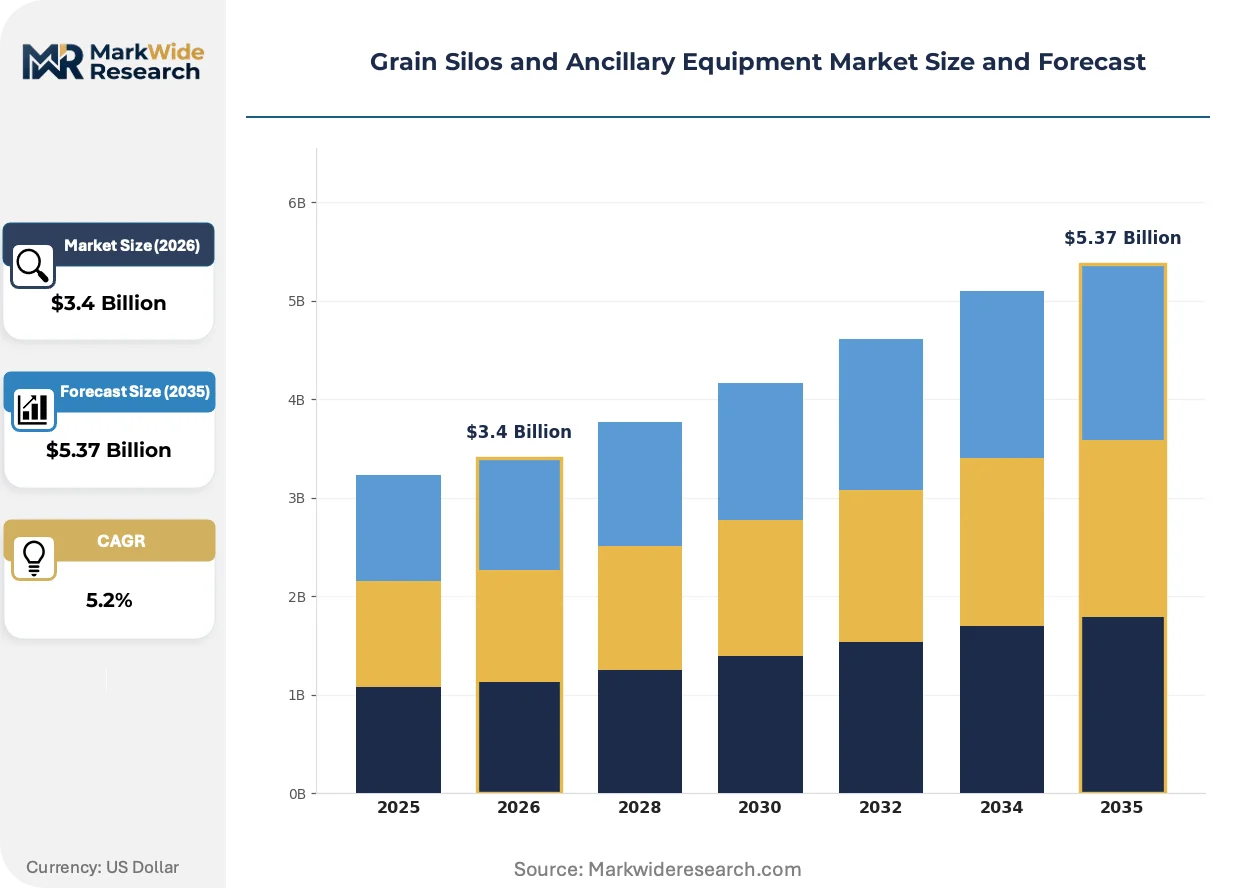
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.37 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bottom Silos, Hopper Silos, Bins, Accessories Customer Type: Agriculture Producers, Commercial Storage, Feed Manufacturers, Cooperative Societies Material: Steel, Concrete, Aluminum, Composite Installation Type: On-site, Pre-assembled, Modular, Custom-built |
| Companies Covered | SYMAGA, CTB Inc., Sukup Manufacturing Co., Behlen Mfg. Co., SCAFCO Grain Systems Co., Ag Growth International Inc., TSC Silos, Brock Grain Systems Inc., Prado Silos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grain Silos and Ancillary Equipment Market Trends and Innovations
Digital telemetry and predictive maintenance architectures are compressing the operational boundary between grain storage hardware and farm management software platforms.
Wireless sensor networks for moisture and temperature monitoring are miniaturizing from discrete probe installations to distributed mesh architectures embedded directly into aeration ductwork. Large-scale farming cooperatives in Brazil and Ukraine are deploying these systems at 10,000-tonne-plus facilities. This compression is eliminating separate cabling infrastructure and enabling real-time quality alerts that trigger automated ventilation cycles.
EU F-Gas Regulation phase-down mandates are accelerating refrigerant-based aeration cooling system redesigns toward ammonia and CO2 alternatives. Equipment fabricators must recertify compressor packages and heat exchanger specifications under revised safety protocols. Hopper silo installations for feed mill applications face the tightest compliance timelines given their dependency on rapid temperature suppression.
Service unbundling is fragmenting traditional turnkey contracts into separate hardware, installation, and telemetry subscription components. Commercial grain elevators in the United States now procure bins through dealer networks while negotiating direct data platform relationships with sensor OEMs. This bifurcation concentrates pricing pressure on fabrication margins while shifting value capture toward recurring software revenue.
Grain Silos and Ancillary Equipment Market Segmentation
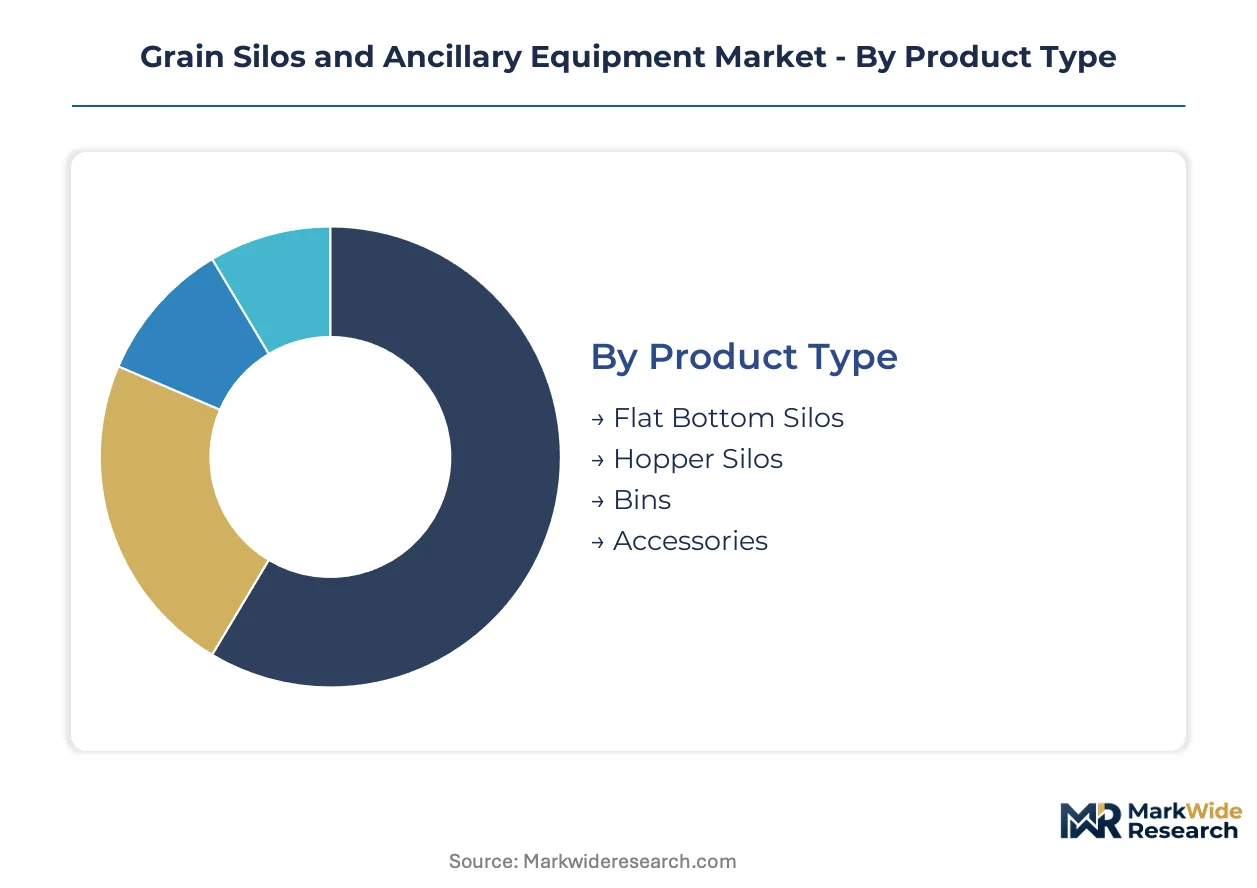
Segmentation in grain silo procurement reveals how capital deployment, operational scale, and regulatory exposure reshape channel economics across installation types and customer categories. Procurement patterns diverge sharply between large commercial elevators seeking integrated systems and smaller agricultural producers prioritizing modular flexibility.
Product Type:
Flat bottom silos flow through dealer networks and direct OEM relationships, while hopper silos concentrate in feed mill verticals with engineering-procurement-construction contractors.
- Flat Bottom Silos:Cylindrical structures with concrete or steel floors engineered for 5,000 to 100,000 tonne capacities, integrating full-floor aeration and temperature monitoring systems. Demand concentrates among commercial grain elevators in the United States Corn Belt and Ukrainian port terminals, driven by harvest volatility forcing overbuilt storage capacity and extended holding periods.
- Hopper Silos:Conical-bottom steel bins designed for rapid gravity discharge, typically 100 to 2,000 tonnes, with integrated ventilation and fumigation ports. Feed manufacturers in Brazil and Germany represent the core demand cluster, pressured by ANVISA-adjacent storage regulations and EU F-Gas cooling mandates requiring temperature suppression capabilities.
- Bins:Smaller-diameter corrugated steel containers, 50 to 500 tonnes, serving on-farm buffer storage with basic aeration.
- Accessories:Aeration fans, temperature cables, level indicators, and sweep augers sold as retrofit kits or bundled with new installations.
Flat bottom silos dominate installed base. Hopper silos are where expansion concentrates among feed sector automation investments.
Customer Type:
Cost tier segmentation separates capital-intensive commercial operators from price-sensitive agricultural producers with divergent financing structures and payback horizons.
- Agriculture Producers:Individual farms and family operations purchasing 500 to 5,000 tonne systems through cooperative financing or equipment loans. Brazilian soybean growers and Ukrainian wheat farmers anchor this tier, responding to commodity price hedging needs and post-harvest loss reduction targets.
- Commercial Storage:Grain elevator companies and logistics operators deploying 50,000-plus tonne facilities with full telemetry integration. United States operators face OSHA-mandated explosion-proof electrical retrofits, accelerating replacement of aging concrete infrastructure.
- Feed Manufacturers:Compound feed mills requiring rapid inventory turnover and precise moisture control for batch consistency.
- Cooperative Societies:Farmer-owned aggregators pooling capital for shared storage infrastructure, prevalent in India's Food Corporation of India procurement zones.
Commercial storage commands capital deployment. Agriculture producers are climbing the fastest as farm consolidation accelerates.
Material:
Supply concentration in galvanized steel coil production shapes regional availability and lead time differentials across material categories.
- Steel:Corrugated hot-dip galvanized sheets, 0.6 to 1.2 millimeter thickness, with G90 to G235 zinc coatings for corrosion resistance. United States Midwest and Eastern European roll-forming clusters supply Brazil and Argentina, though currency exposure and ocean freight compress margins for distant buyers.
- Concrete:Reinforced cast-in-place or precast structures delivering 40-plus-year service lives in Ukrainian and Argentine installations, delaying replacement demand despite higher initial capital requirements.
- Aluminum:Lightweight alloy panels for coastal or high-humidity environments where salt corrosion accelerates steel degradation.
- Composite:Fiberglass-reinforced polymer panels emerging in specialty chemical-resistant applications.
Steel commands new installation volume. Concrete sustains longest replacement cycles.
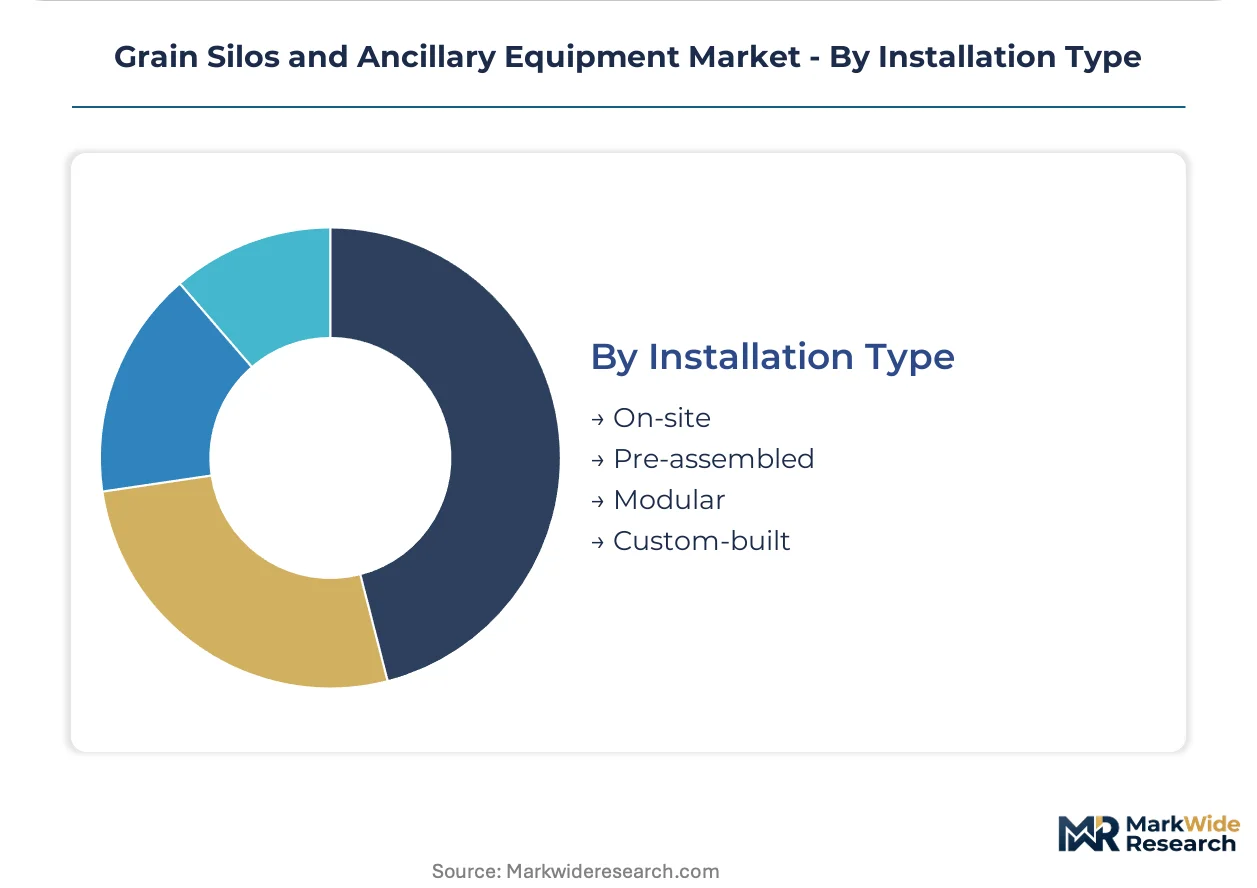
Installation Type:
Volume scale and site constraints determine whether silos ship as component kits or pre-assembled modules, with logistics costs driving channel selection.
- On-site:Component delivery with field erection using mobile roll-forming and crane assembly, standard for flat bottom silos exceeding 10,000 tonnes where transport dimensions prohibit pre-assembly.
- Pre-assembled:Factory-welded hopper bins and small-diameter units shipped complete to feed mills and on-farm locations, reducing field labor and weather exposure.
- Modular:Flat-pack panel systems with standardized bolted connections, enabling rapid capacity expansion and relocation, favored by Indian cooperative societies and Brazilian agricultural startups.
- Custom-built:Engineered-to-order concrete or hybrid structures for port terminals and industrial processors with non-standard dimensional or load requirements.
On-site construction dominates large commercial projects. Modular systems are gaining share fastest among emerging market entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial grain elevators and large-scale farming operations concentrate procurement decisions in agricultural powerhouses where harvest volatility meets infrastructure modernization cycles. Buyers prioritize integrated aeration systems and telemetry capabilities to manage extended holding periods and supply chain continuity.
United States
Corn Belt commercial elevators drive flat-bottom silo demand as operators overbuild capacity to hedge commodity price swings. OSHA grain handling standards mandate explosion-proof electrical retrofits and confined-space entry protocols, accelerating replacement of aging concrete infrastructure. Iowa and Illinois manufacturing clusters anchor steel fabrication supply chains for domestic and export markets.
Brazil
Soybean growers and feed manufacturers anchor demand for hopper silos with rapid discharge capabilities. ANVISA-adjacent agricultural storage regulations tighten sanitary requirements for temperature-controlled grain preservation. São Paulo state and Mato Grosso farming cooperatives concentrate procurement through dealer networks serving consolidated farm operations.
Ukraine
Port terminals and inland elevators drive flat-bottom installations despite reinforced concrete structures delivering 40-plus-year service lives. Post-harvest infrastructure modernization programs prioritize steel replacement for export corridor efficiency. Black Sea port cities cluster engineering-procurement-construction activity for 50,000-tonne-plus facilities.
Germany
Compound feed mills and bioethanol processors command hopper silo installations with precise moisture control for batch consistency. EU Machinery Directive CE marking requirements filter tenders toward fabricators with ISO 11601 welding qualifications. Bavaria and Lower Saxony industrial zones concentrate equipment fabrication and system integration expertise.
India
Food Corporation of India procurement mandates and state-level grain buffer policies create first-mover positioning for modular flat-bottom designs. BIS standards and DGFT import regulations shape material specifications for domestic assembly versus complete unit imports. Punjab and Haryana cooperative societies pool capital for shared storage infrastructure serving wheat and rice procurement zones.
Grain Silos and Ancillary Equipment Market Competitive Landscape
Player mix skews toward mid-scale fabricators with captive steel processing capabilities and regional dealer networks. Market structure fragments across welding-certified specialists and vertically integrated metallurgical suppliers. Three archetypes dominate: steel-coil-integrated manufacturers controlling galvanizing throughput; modular design specialists targeting emerging market price sensitivity; and telemetry-integrated system bundlers capturing recurring software revenue. Competitive moves concentrate on ISO 11601 certification acquisition and geographic expansion through distributor partnerships.
Within the steel-integrated tier, Sukup Manufacturing Co. and CTB Inc. exemplify North American fabricators with in-house galvanizing and extensive dealer networks. SYMAGA occupies a position among modular design specialists competing aggressively across Eastern European and Latin American markets with standardized flat-bottom configurations. These three anchors represent distinct strategic postures: captive metallurgical supply, vertical manufacturing control, and emerging market modularity.
| Leading Market Players |
|---|
| SYMAGA |
| CTB Inc. |
| Sukup Manufacturing Co. |
| Behlen Mfg. Co. |
| SCAFCO Grain Systems Co. |
| Ag Growth International Inc. |
| TSC Silos |
| Brock Grain Systems Inc. |
| Prado Silos |
| Others |
Pricing and Supply Chain Analysis
Galvanized steel coil substitution for concrete in new Ukrainian and Brazilian installations simultaneously redraws procurement geography toward United States Midwest and Eastern European roll-forming clusters while compressing fabrication margins through zinc price indexation. This material shift concentrates pricing power among captive metallurgical suppliers and fragments margin capture across distant buyers facing currency and freight exposure.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange zinc pricing dominate large-capacity flat-bottom silo procurement for United States Corn Belt elevators. Three-tier pricing structure across premium, standard, and economy levels separates ISO 11601-certified fabricators with full telemetry bundling from modular specialists and basic kit suppliers. Cost compression in economy-tier bin sales is intensifying because Brazilian agricultural startups prioritize capital efficiency over aeration integration. Agriculture producers in India's cooperative societies exhibit highest price sensitivity, while commercial storage operators in Germany accept premium positioning for EU Machinery Directive compliance and carbon-accounting-ready specifications.
Supply Chain Analysis
Inventory cycles stretching six to eight months for corrugated galvanized sheet shipments from United States Midwest mills to Brazilian Mato Grosso farming cooperatives expose buyers to zinc price volatility and ocean freight rate swings. Manufacturing gravity centers on Iowa and Illinois steel fabrication clusters for North American demand, with Eastern European roll-forming capacity serving Ukrainian port terminals and German feed manufacturers. Raw material flows draw from hot-dip galvanizing lines, G90-to-G235 zinc coating baths, and specialized welding wire feedstock. Single-source vulnerability concentrates in United States captive galvanizing throughput controlled by Sukup Manufacturing Co. and CTB Inc. Distribution runs through regional dealer networks for on-site construction projects and direct OEM relationships for pre-assembled hopper silo deliveries to feed mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grain silo and ancillary equipment demand sits at an early-cycle expansion phase driven by post-harvest infrastructure gaps in India's Food Corporation of India procurement zones and Brazilian agricultural consolidation. Harvest volatility forcing commercial operators to overbuild storage capacity creates sustained procurement tailwinds across multiple geographies.
For Market Incumbents: Compound defensive positioning through captive steel galvanizing capacity additions in Eastern Europe and ISO 11601 welding certification acquisition to filter tender competition. Mid-scale fabricators lacking structural validation capabilities represent an emerging threat requiring certification barriers. Channel control through dealer network exclusivity in United States Corn Belt states anchors pricing power against modular specialists.
For New Entrants and Emerging Players: Telemetry subscription under-penetration among existing flat-bottom installations in United States Corn Belt elevators offers white-space capture through sensor-array retrofit bundling. India's cooperative society procurement clusters present the most penetrable geography given Food Corporation of India mandate expansion and domestic assembly cost advantages. Direct data platform relationships with sensor OEMs bypass traditional turnkey contracting fragmentation.
For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors vertically integrated metallurgical suppliers with regional dealer network density. Five-to-ten-year viability hinges on carbon-accounting integration and refrigerant-transition compliance under EU F-Gas Regulation phase-down mandates. Acquisition targets should demonstrate ISO 11601 welding qualifications and telemetry hardware bundling capabilities. The signal to watch is EU Green Deal reporting requirement enforcement tightening aeration energy efficiency specifications in commercial elevator procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 11601 Certification Acquisition | Structural welding validation filters tender competition toward qualified fabricators in EU and United States procurement. |
| Captive Galvanizing Capacity Expansion | In-house zinc coating throughput insulates margin compression from London Metal Exchange price volatility. |
| Telemetry Hardware Bundling | Sensor-array integration with new silo sales captures recurring software revenue from commercial elevator operators. |
| Modular Flat-Bottom Design Localization | India domestic assembly cost positioning aligns with Food Corporation of India procurement mandate expansion. |
| Refrigerant Transition Compliance | Ammonia and CO2 aeration cooling recertification satisfies EU F-Gas Regulation phase-down timelines for feed mill installations. |
Research Methodology
Desk research of trade association filings, customs and steel shipment data, and regulatory directive texts preceded structured interviews with grain elevator operations managers, agricultural cooperative procurement officers, steel fabrication plant engineers, and aftermarket service heads. Primary fieldwork across United States Corn Belt states, Brazilian Mato Grosso farming zones, and Ukrainian Black Sea port cities validated installation capacity assumptions and procurement timeline elasticity. Secondary sources included OSHA grain handling standard enforcement records, EU Machinery Directive CE marking databases, and Food Corporation of India tender documentation. Bottom-up silo shipment tallies triangulated against top-down agricultural storage capacity expansion estimates.
Variance decomposition across product type, customer category, material specification, and installation format shaped volume and value outputs over the projection horizon. Segmentation dimensions modeled encompassed flat-bottom versus hopper silo geometries, commercial storage versus agriculture producer end-use tiers, steel versus concrete versus aluminum material grades, and on-site versus pre-assembled versus modular delivery structures. CAGRs derived from historical shipment elasticities to grain price volatility and harvest yield variance, cross-referenced with regulatory retrofit mandate timelines and infrastructure modernization program disbursements.
Forecasts assume regulatory continuity in OSHA grain handling standards, EU Machinery Directive CE marking requirements, and Brazil ANVISA-adjacent agricultural storage regulations; material policy shifts would require re-modeling capital expenditure timing and certification cost burdens. Zinc price volatility, currency fluctuation in Brazilian real and Indian rupee procurement, and concrete-to-steel substitution acceleration in Ukrainian reconstruction represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
United States Agricultural Irrigation Machinery Market
Agricultural Equipment & Machinery
Commercial Oil Extraction Machine Market
Agricultural Equipment & Machinery
Asia-Pacific Planting Machinery Market
Agricultural Equipment & Machinery
Seed Drill Machines Market
Agricultural Equipment & Machinery
Asia-Pacific Agricultural Sprayer Market
Agricultural Equipment & Machinery
Lawn and Garden Equipment Market
Agricultural Equipment & Machinery
Global Fishery Machinery Manufacturing Market
Agricultural Equipment & Machinery
Global Agricultural Equipment Market
Agricultural Equipment & Machinery
South Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
Planting and Fertilizing Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Seed Drill and Broadcast Seeder Machinery Market
Agricultural Equipment & Machinery
Global Lawn Mowers Market
Agricultural Equipment & Machinery
Hammer Mill Market
Agricultural Equipment & Machinery
Global Agriculture and Farm Equipment Market