
 Global Agriculture and Farm Equipment Market | 2026-2036
Global Agriculture and Farm Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Agriculture and Farm Equipment Market Analysis
Dealer networks and digital procurement platforms is rewriting how farmers access capital equipment across major agricultural belts. Deere & Company leverages its precision agriculture ecosystem to lock in recurring software revenue alongside hardware sales. CNH Industrial anchors its position through extensive manufacturing scale in Europe and Latin America. AGCO Corporation differentiates via focused brand portfolios serving distinct farm-size tiers without direct internal competition.
Agriculture and farm equipment encompasses motorized and implements machinery designed for soil preparation, planting, cultivation, harvesting, and post-harvest processing, typically powered by diesel engines ranging from 15 to 600 horsepower and increasingly governed by Stage V and Tier 4 Final emissions architectures. Its primary commercial purpose centers on labor substitution, yield optimization, and operational timing precision in crop and livestock production systems. Tractors occupy the largest revenue pool given universal demand across all farm scales and applications, while precision agriculture technology represents the fastest-expanding margin segment as subscription-based telemetry and autosteer systems displace standalone mechanical sales. Harvesters command premium pricing in North American and European grain belts where field efficiency metrics determine purchasing decisions.
The EPA and California Air Resources Board enforce Tier 4 Final and emerging zero-emission standards that force engine redesigns and alternative powertrain investment across OEM portfolios. The EU Green Deal and F-Gas Regulation compound compliance costs while redirecting R&D budgets toward electrification and biofuel compatibility. India's Central Pollution Control Board and Bureau of Indian Standards are tightening local emissions norms that reshape product configurations for the world's largest tractor market. Stakeholders must monitor regulatory divergence between jurisdictions and decide whether to pursue modular powertrain architectures or region-specific product lines.
Market Dynamics
Diesel engine electrification is forcing fundamental powertrain redesigns across OEM portfolios as Stage V and Tier 4 Final emissions architectures reach their engineering limits. The shift compresses development cycles and redirects capital toward battery-hydrogen hybrid systems and alternative fuel compatibility.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:The tightening emissions standards for diesel-powered machinery are accelerating fleet turnover in European grain operations. Farmers face compliance deadlines that compress replacement cycles.
- Large-scale grain operations in Brazil:Expanding mechanized harvesting fleets are pulling in high-horsepower tractors and combine harvesters. Field efficiency metrics now dominate purchasing decisions.
- Precision agriculture telemetry:Subscription-based autosteer and variable-rate application systems are displacing standalone mechanical sales. This creates recurring revenue streams alongside hardware.
Market Restraints
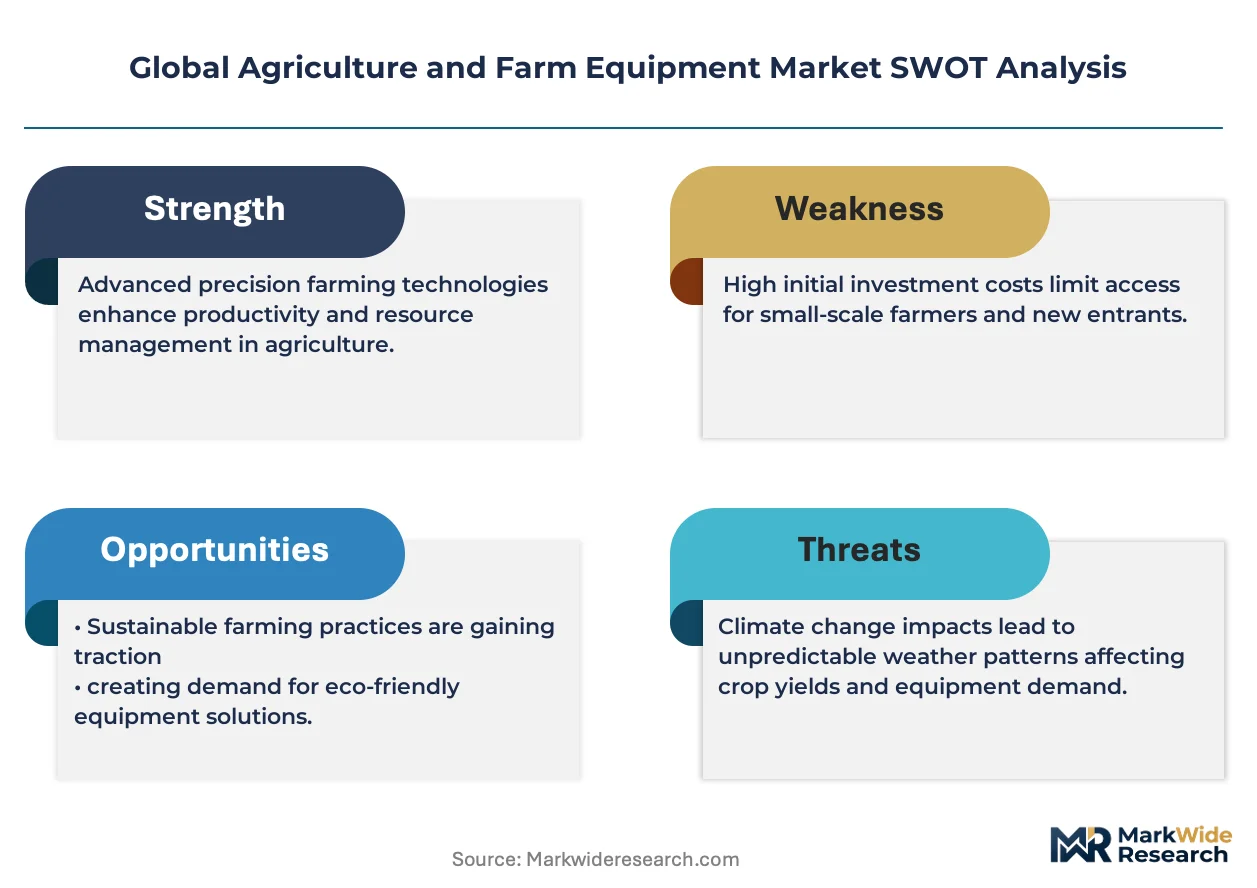
- Steel and rare earth input volatility:Battery-grade lithium and permanent magnet materials face concentrated supply from limited geographies. OEM margins compress when raw material costs spike without pricing power.
- Tier 4 Final engine redesign costs:The EPA and California Air Resources Board standards forced exhaust after-treatment systems that added complexity and maintenance burden. Smaller OEMs lack capital to absorb these compliance investments.
- Manual labor substitution limits in specialty crops:Harvesting equipment for fruits and vegetables requires delicate handling that mechanization has not yet replicated. This caps addressable market expansion in high-value horticulture.
Strategic Opportunities
- India's Punjab and Haryana states:Tractor replacement cycles are shortening as farm consolidation accelerates. Local emissions norm tightening by the Central Pollution Control Board creates upgrade demand.
- Dealer network digitization:Digital procurement platforms are rewriting capital equipment access across major agricultural belts. Embedded financing and telematics bundling capture customer lifetime value.
- Biofuel compatibility mandates:The EU F-Gas Regulation and parallel standards are redirecting R&D toward engines that run on renewable diesel and biomethane. First-movers gain regulatory goodwill and fleet contracts.
Industry Challenges
- Powertrain engineering talent scarcity:Electrification requires software-defined vehicle expertise that traditional diesel engine departments lack. OEMs compete with automotive and aerospace for embedded systems engineers.
- Legacy fleet integration complexity:New precision agriculture platforms must communicate with fifteen-year-old mechanical systems still in field service. Retrofit hardware and protocol translation add cost and failure points.
- Certification timeline compression:Multiple jurisdictions now run parallel emissions certification processes. The Bureau of Indian Standards, EPA, and EU type-approval cycles rarely align, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Agriculture and Farm Equipment Market |
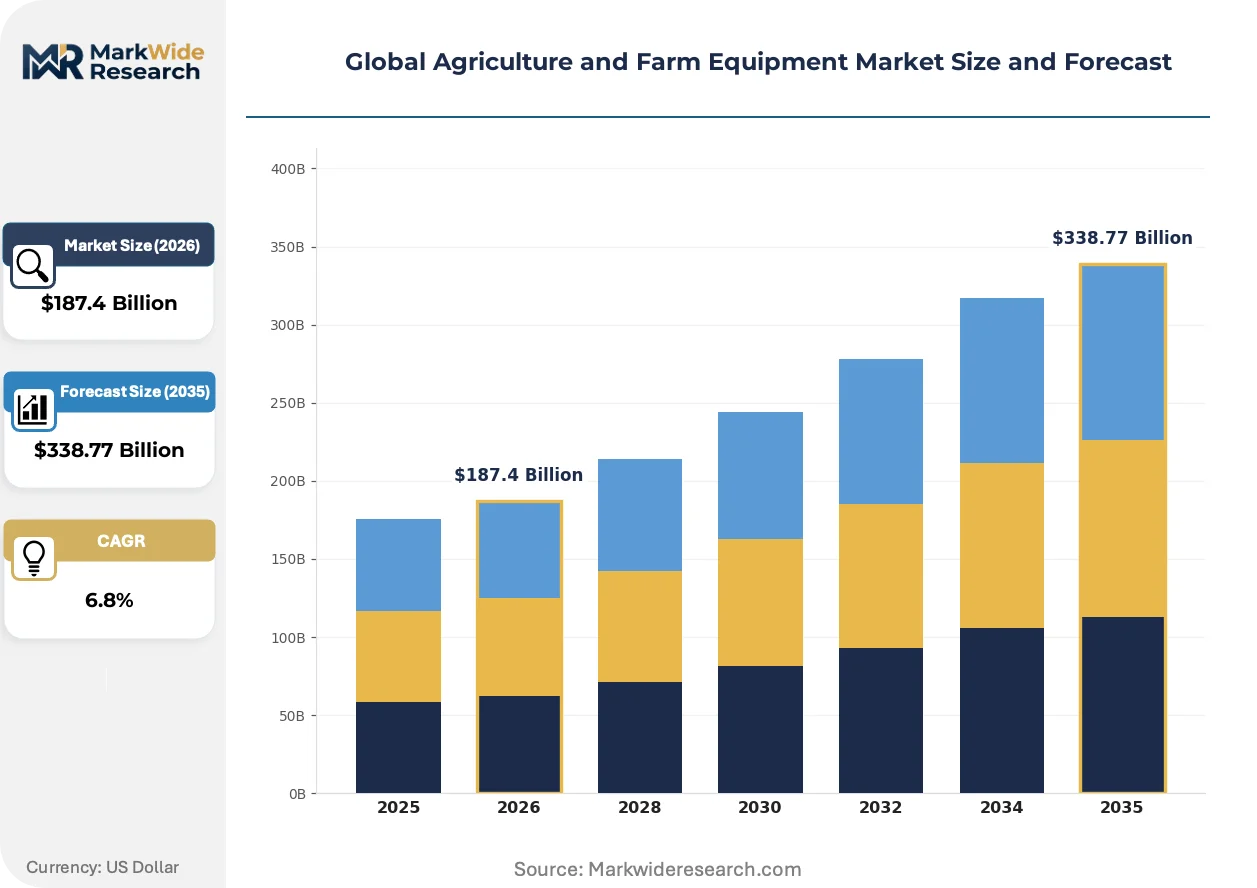
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Harvesters, Plows, Seeders Application: Crop Farming, Livestock Farming, Aquaculture, Horticulture End User: Farmers, Cooperatives, Agricultural Contractors, Agro-Processors Technology: Precision Agriculture, Automation, Smart Farming, IoT Solutions |
| Companies Covered | Deere & Company, CNH Industrial, AGCO Corporation, Kubota Corporation, CLAAS KGaA, Mahindra & Mahindra, SDF, China National Machinery Industry Corporation, Alamo Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Agriculture and Farm Equipment Market Emerging Trajectories
Telemetry and automation are virtualizing core machinery functions, converting mechanical assets into data-generating platforms. This transformation redefines value capture and competitive differentiation across the equipment value chain.
Autonomous field operations technology is virtualizing the operator function in planting and cultivation workflows. Large grain operations in the US Corn Belt and Brazilian Cerrado are deploying supervised autonomy fleets that reduce labor dependency during critical weather windows. The technology compresses the effective cost structure of 24-hour operations while raising the bar for dealer service capabilities.
The EU Green Deal and F-Gas Regulation are mandating refrigerant transitions and electrification pathways that compound compliance costs. Engine manufacturers must redesign thermal management systems and validate alternative powertrains under compressed timelines. European OEMs with manufacturing scale in Latin America are leveraging regulatory divergence to test biofuel-hybrid architectures in less restrictive markets before EU homologation.
Equipment-as-a-service contracting is fragmenting traditional ownership models across North American row-crop operations. Dealer networks and manufacturer finance arms are unbundling hardware from uptime guarantees, shifting risk to OEM balance sheets. This pattern concentrates in high-value specialty crop regions where seasonal utilization rates make ownership economics marginal.
Global Agriculture and Farm Equipment Market Segmentation
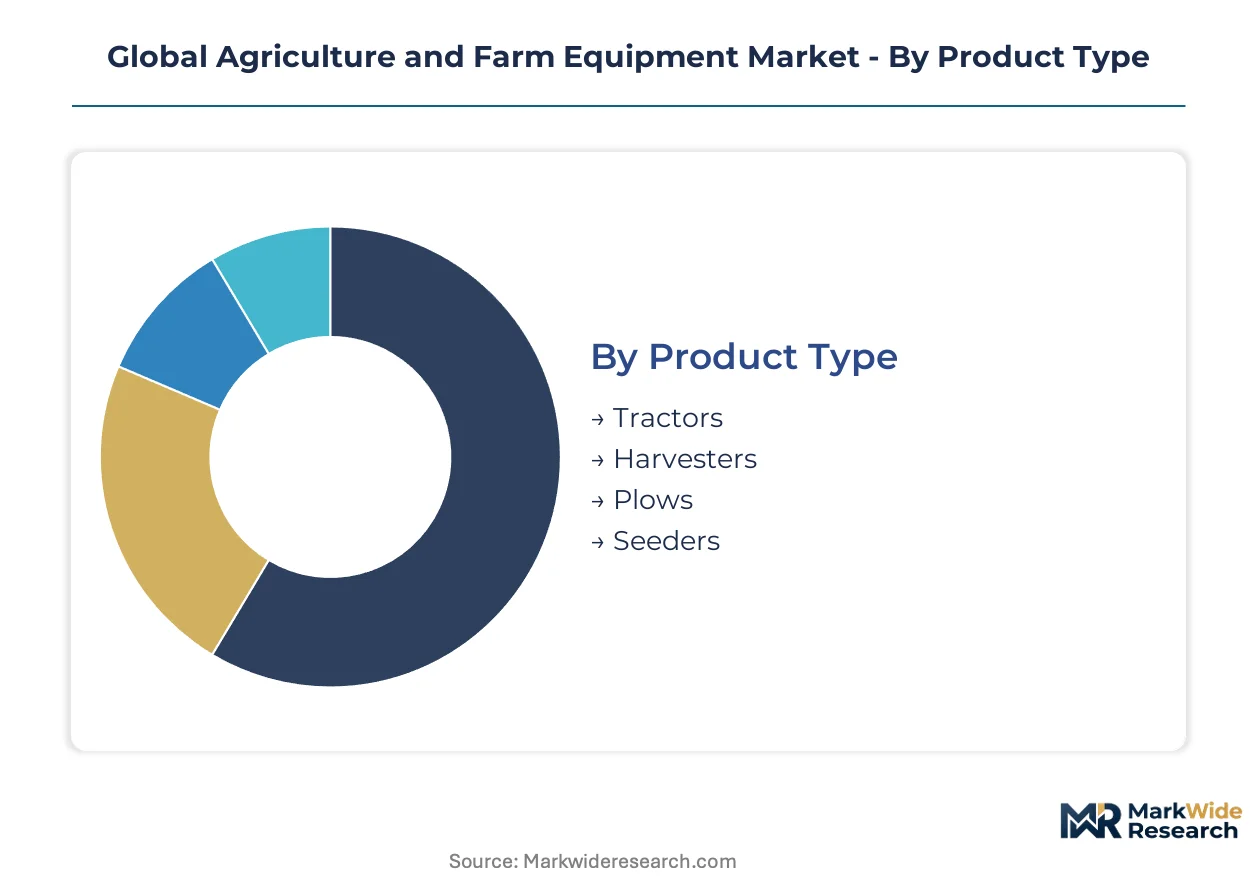
Equipment segmentation reveals divergent margin structures across mechanical hardware versus data-enabled platforms. Product type and technology dimensions now interact dynamically as precision agriculture reshapes traditional machinery categories.
Product Type:
Equipment cost tiers separate universal infrastructure from specialized seasonal assets with utilization constraints.
- Tractors:Diesel-powered platforms ranging from 15 to 600 horsepower serve as the foundational mobility and power-takeoff infrastructure for virtually all mechanized operations. Demand concentrates in India's Punjab and Haryana states where replacement cycles are compressing due to farm consolidation and tightening Central Pollution Control Board emissions norms. Tractors hold installed capacity.
- Harvesters:Combine platforms and specialized grain headers command premium pricing in North American and Brazilian grain belts where field efficiency metrics determine purchasing decisions. Large-scale operations in Brazil's Cerrado are expanding mechanized harvesting fleets to capture weather-critical planting windows. Harvesters are rotating up the share rankings.
- Plows:Soil preparation implements attach to tractor three-point hitch systems for primary and secondary tillage operations.
- Seeders:Planting equipment ranges from mechanical drills to precision air-seeders with variable-rate capabilities.
Tractor universalism anchors manufacturer portfolios. Harvester specialization commands pricing power in grain belts.
Application:
Operational context dictates equipment specifications, duty cycles, and financing structures across production systems.
- Crop Farming:Row-crop and broadacre grain operations drive volume demand for high-horsepower tractors, combines, and precision agriculture telemetry. The EU Green Deal's Farm to Fork strategy accelerates fleet turnover in European grain operations facing compliance deadlines. Crop farming holds installed capacity.
- Livestock Farming:Dairy and cattle operations require feeding equipment, manure handling systems, and barn ventilation machinery with distinct maintenance profiles. Automation is displacing manual labor in confined animal feeding operations. Livestock farming is rotating up the share rankings.
- Aquaculture:Fish and shellfish production systems utilize specialized feeding barges, net handling equipment, and water quality monitoring platforms.
- Horticulture:Fruit and vegetable operations face mechanization limits where delicate handling requirements resist automation.
Crop farming dominates capital deployment. Horticulture presents mechanization headroom constrained by biological handling complexity.
End User:
Customer scale and organizational structure reshape procurement patterns, service expectations, and technology adoption curves.
- Farmers:Individual owner-operators represent the volume base for tractor and implement sales across all horsepower segments. Dealer network digitization is rewriting capital equipment access for this fragmented customer base through embedded financing and telematics bundling. Farmers hold installed capacity.
- Cooperatives:Member-owned aggregation entities pool capital for shared high-value equipment with seasonal utilization optimization. Cooperatives are rotating up the share rankings.
- Agricultural Contractors:Custom service providers monetize equipment through acreage-based billing rather than crop ownership.
- Agro-Processors:Vertically integrated operations source equipment for captive farming operations and contract grower networks.
Individual farmers anchor unit volumes. Cooperatives and contractors concentrate demand for highest-horsepower platforms.
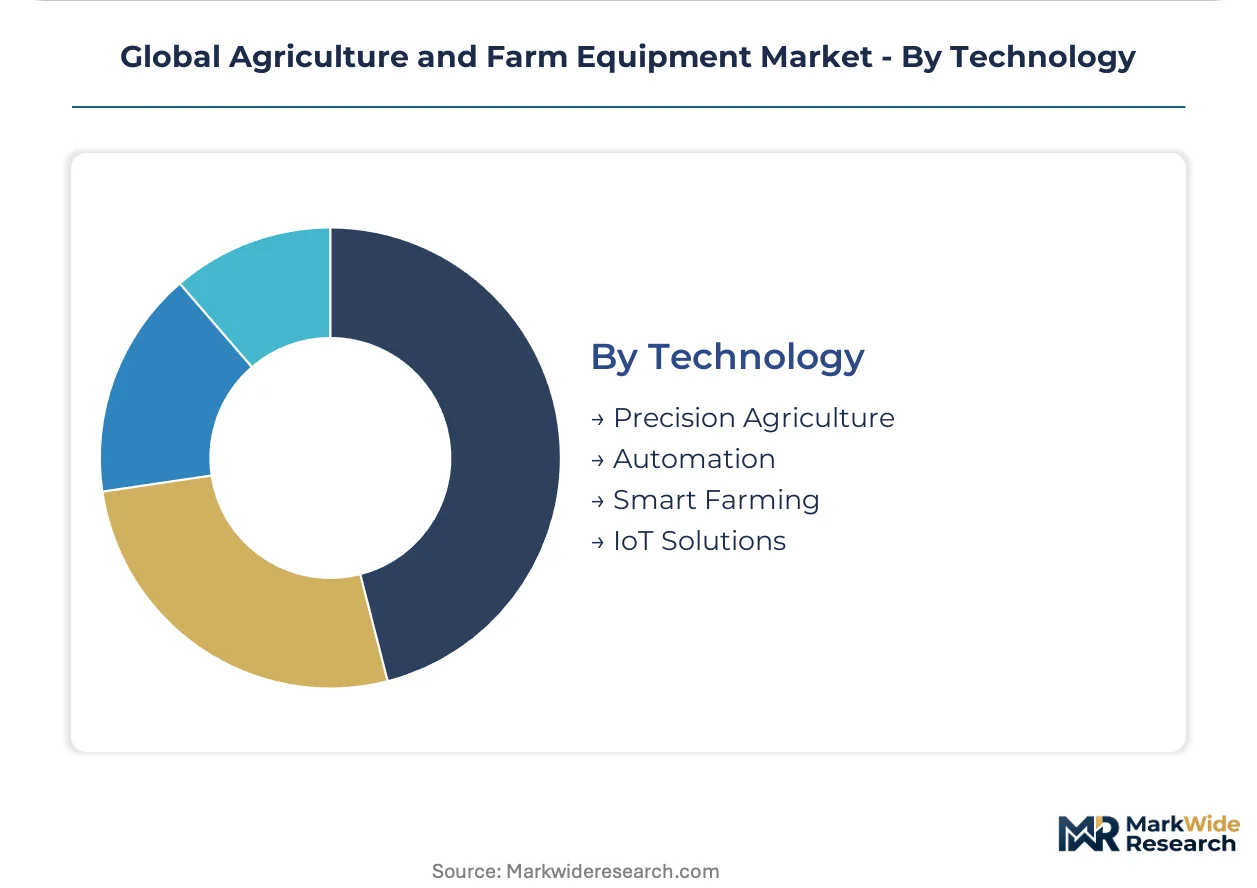
Technology:
Margin architecture separates mechanical hardware from recurring software revenue streams with divergent valuation multiples.
- Precision Agriculture:Subscription-based telemetry, variable-rate application, and yield monitoring systems displace standalone mechanical sales. The EPA and Tier 4 Final emissions standards redirect R&D budgets toward electrification compatibility. Precision agriculture is expanding most quickly.
- Automation:Supervised autosteer and autonomous field operations reduce labor dependency during critical weather windows in US Corn Belt and Brazilian Cerrado operations. Automation is rotating up the share rankings.
- Smart Farming:Integrated sensor networks and decision support platforms optimize input application timing and rates.
- IoT Solutions:Connected machinery ecosystems enable predictive maintenance and fleet management across distributed operations.
Precision agriculture captures recurring revenue premiums. Smart farming and IoT build data infrastructure for outcome-based service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and US precision-agriculture markets while Indian and Brazilian tractor segments compete on volume and localization economics. Equipment manufacturers extract premiums where telemetry bundling and emissions compliance create switching costs. Regional regulatory divergence now shapes product architecture decisions more than raw market scale.
United States
Large grain operations in the Corn Belt and Pacific Northwest drive demand for high-horsepower autonomous tractors and precision seeding systems. The EPA and California Air Resources Board enforce Tier 4 Final standards that force exhaust after-treatment investments. Equipment-as-a-service contracting concentrates in California's Central Valley specialty crop regions where seasonal utilization rates favor subscription models over ownership.
Germany
The EU Green Deal's Farm to Fork strategy accelerates fleet turnover in Bavarian and North Rhine-Westphalian grain operations facing compliance deadlines. ECHA and REACH regulations compound powertrain redesign costs while redirecting R&D toward electrification. Stuttgart and Munich industrial clusters anchor development of Stage V-compatible engine architectures and biofuel-hybrid validation programs.
Brazil
Large-scale operations in Mato Grosso and Goiás states expand mechanized harvesting fleets to capture weather-critical planting windows. ANVISA and national emissions standards create parallel certification requirements that delay product launches. São Paulo-based manufacturing hubs test alternative powertrain architectures under less restrictive frameworks before EU homologation.
India
Farm consolidation in Punjab and Haryana states shortens tractor replacement cycles for 40-horsepower platforms. The Central Pollution Control Board and Bureau of Indian Standards tighten local emissions norms that reshape configurations for the world's largest tractor market. Faridabad and Pune industrial corridors concentrate domestic assembly operations serving price-sensitive owner-operators.
China
Mechanization policy targets in Heilongjiang and Henan provinces drive demand for mid-size tractors and combine harvesters. MEE and MIIT enforce dual carbon goals that redirect state-owned enterprise R&D budgets toward electrification. Shandong and Jiangsu manufacturing bases supply domestic grain belts while exporting standardized platforms to Southeast Asian markets.
Global Agriculture and Farm Equipment Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying engines, hydraulics, and precision sensors to multiple OEMs. The vendor base structures around three tiers: diversified industrial conglomerates with captive agricultural divisions, dedicated farm equipment specialists with focused brand portfolios, and regional fabricators serving price-sensitive emerging markets. Consolidation pressures concentrate among mid-scale European and Japanese manufacturers lacking electrification capital. Dominant competitive moves include strategic partnerships for battery supply and geographic licensing to bypass tariff barriers.
Within the diversified industrial tier, Deere & Company and CNH Industrial occupy positions as integrated platform providers spanning precision software and hardware ecosystems. AGCO Corporation exemplifies the dedicated specialist archetype through distinct brand portfolios serving non-overlapping farm-size segments. Mahindra & Mahindra anchors the emerging-market volume tier with manufacturing scale calibrated to cost-sensitive replacement demand in South Asian tractor markets.
| Leading Market Players |
|---|
| Deere & Company |
| CNH Industrial |
| AGCO Corporation |
| Kubota Corporation |
| CLAAS KGaA |
| Mahindra & Mahindra |
| SDF |
| China National Machinery Industry Corporation |
| Alamo Group |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese tractor assembly plants is compressing supplier margins and forcing extended payment terms onto component vendors across Shandong and Jiangsu manufacturing corridors. This utilization imbalance simultaneously erodes pricing power for standardized platforms while amplifying premiums for precision-agriculture configurations that carry proprietary telemetry bundling.
Pricing Analysis
The customization-premium spread between configured-to-order precision tractors and standard utility models now exceeds three-to-one in North American grain belts. Three-tier pricing structure across premium, standard, and economy levels reflects horsepower segmentation, emissions certification tier, and telemetry subscription bundling. Pricing pressure stems from battery-grade lithium and permanent magnet cost volatility that OEMs cannot fully pass to price-sensitive Indian and Brazilian owner-operators. Individual farmers in South Asian markets exhibit highest price sensitivity, while large-scale cooperatives in the US Corn Belt absorb premium positioning for autonomy-enabled fleets.
Supply Chain Analysis
Supplier-financing facilities extended by Deere and CNH Industrial to their Tier 1 component networks have become critical liquidity bridges during raw material cost spikes. Manufacturing concentration in China, India, and Germany feeds from battery cell, precision sensor, and forged axle dependencies. Single-source vulnerability concentrates in rare earth processing for permanent magnet motors, where Chinese refining capacity dominates global throughput. Distribution runs through captive dealer networks in mature markets and digital procurement platforms penetrating Indian and Brazilian agricultural belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a service-attach opportunity where subscription-based telemetry and predictive maintenance contracts are expanding faster than hardware unit sales across North American and European grain operations.
For Market Incumbents: Pre-empt precision-agriculture platform commoditization by deepening software ecosystem lock-in through API-controlled third-party implement integration. Consolidate dealer network digitization investments to capture customer lifetime value before emerging electric-only entrants establish direct-to-farmer channels. Vertical integration into battery pack assembly mitigates lithium supply volatility threatening margin stability.
For New Entrants and Emerging Players: Mid-market commercial farming cooperatives in Southeast Asia represent the most penetrable entry point, where existing OEM service infrastructure remains sparse and price sensitivity runs lower than individual owner-operators. Equipment-as-a-service contracting models for seasonal specialty crop operations bypass capital-intensive dealer network builds. Partner with regional agricultural banks for embedded financing integration rather than competing for hardware margin.
For Investors and Strategic Acquirers: Capital is best deployed toward precision-agriculture software specialists with proven API integration layers and recurring revenue bases above fifty percent of total sales. Long-term viability hinges on regulatory compliance capability across divergent emissions architectures rather than manufacturing scale alone. Watch Bureau of Indian Standards certification timeline compression as the inflection signal for emerging-market product launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Network Digitization | Embedded financing and telematics bundling capture customer lifetime value across fragmented farmer bases. |
| Battery Supply Agreement | Long-term lithium and cell contracts insulate margins from raw material volatility in electrification transition. |
| Precision Software Ecosystem | API-controlled platform integration creates switching costs that defend recurring revenue streams. |
| Regional Certification Investment | Parallel EPA, EU, and BIS homologation capabilities accelerate product launch velocity across regulatory clusters. |
| Equipment-as-a-Service Launch | Uptime guarantee contracting shifts balance sheet risk while penetrating seasonal utilization markets. |
Methodological Framework
Desk research of OEM financial disclosures, emissions certification databases, and agricultural trade flow records preceded structured interviews with precision agriculture product managers, dealer network operations directors, and aftermarket service heads. Primary fieldwork with farm equipment procurement officers at large-scale cooperatives and individual owner-operators in Punjab and Mato Grosso validated demand assumptions. Secondary triangulation drew from EPA certification filings, EU type-approval registries, and Bureau of Indian Standards notification records. Bottom-up equipment shipment analysis and top-down agricultural GDP attribution were reconciled across the modeling period.
Assumptions held fixed include regulatory compliance timeline divergence between EPA Tier 4 Final, EU Stage V, and Indian CPCB norms, while battery cost decline trajectories and biofuel mandate adoption rates were varied across sensitivity scenarios. Segmentation modeling incorporated product type, application, end user scale, and technology architecture dimensions. CAGRs were derived from equipment replacement cycle compression analysis and precision agriculture subscription attach rate projections. Forecast inputs included farm consolidation velocity in India and Brazil, and EU Green Deal compliance deadline clustering.
Practitioners should monitor lithium carbonate price volatility, Indian emissions norm enforcement intensity, and precision agriculture platform consolidation for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Grain Silos and Ancillary Equipment Market
Agricultural Equipment & Machinery
Asia-Pacific Planting Machinery Market
Agricultural Equipment & Machinery
Seed Drill and Broadcast Seeder Machinery Market
Agricultural Equipment & Machinery
Beekeeping Equipment Market
Agricultural Equipment & Machinery
Global Agricultural Equipment Market
Agricultural Equipment & Machinery
Asia-Pacific Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Germany Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Global Tillage Equipment Market
Agricultural Equipment & Machinery
Global Powered Agriculture Equipment Market
Agricultural Equipment & Machinery
Agriculture Equipment Market
Agricultural Equipment & Machinery
Europe Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Global Lawn Mowers Market
Agricultural Equipment & Machinery
China Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Agricultural Sprayer Market
Agricultural Equipment & Machinery
Europe Planting Machinery Market
Agricultural Equipment & Machinery
India Combine Harvester Market