
 Europe Planting Machinery Market | 2026-2036
Europe Planting Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Planting Machinery Market Foresight
CE-marked precision tiers is redrawing competitive boundaries in European planting equipment. Deere & Company leverages its integrated precision agriculture stack to dominate high-horsepower automated planter configurations. AGCO Corporation anchors its position through specialized seeder lines tailored to Central European cereal rotations. Kuhn Group differentiates via dense dealer networks across France and Benelux, controlling aftermarket service access for cooperative buyers.
Planting machinery encompasses mechanized equipment designed to deposit seeds, seedlings, or bulbs at controlled depths, spacing, and rates, typically operating at working widths of 3–18 metres and row spacings calibrated to crop geometry. These systems serve the fundamental commercial purpose of establishing crop stands with uniform emergence, directly influencing yield potential and input efficiency for arable and specialty crop producers. Seeder and planter configurations absorb the dominant share of replacement demand, while precision agriculture technology commands the fastest expansion as variable-rate control and section shut-off become baseline specifications in subsidy-eligible equipment. Transplanter demand remains structurally concentrated in vegetable and tobacco belts, where horticultural intensity justifies unit premiums over commodity grain systems.
The EU Machinery Directive and CE marking framework mandate conformity assessment for all planting equipment sold within member states, while the F-Gas Regulation constrains refrigerant choices in climate-controlled cab variants. The EU Green Deal's soil health targets are redirecting national agricultural subsidies toward minimum-tillage compatible drills, altering procurement criteria for government agency fleets. Stakeholders must monitor the interplay between CAP pillar funding revisions and national precision agriculture incentive schemes to anticipate equipment specification shifts.
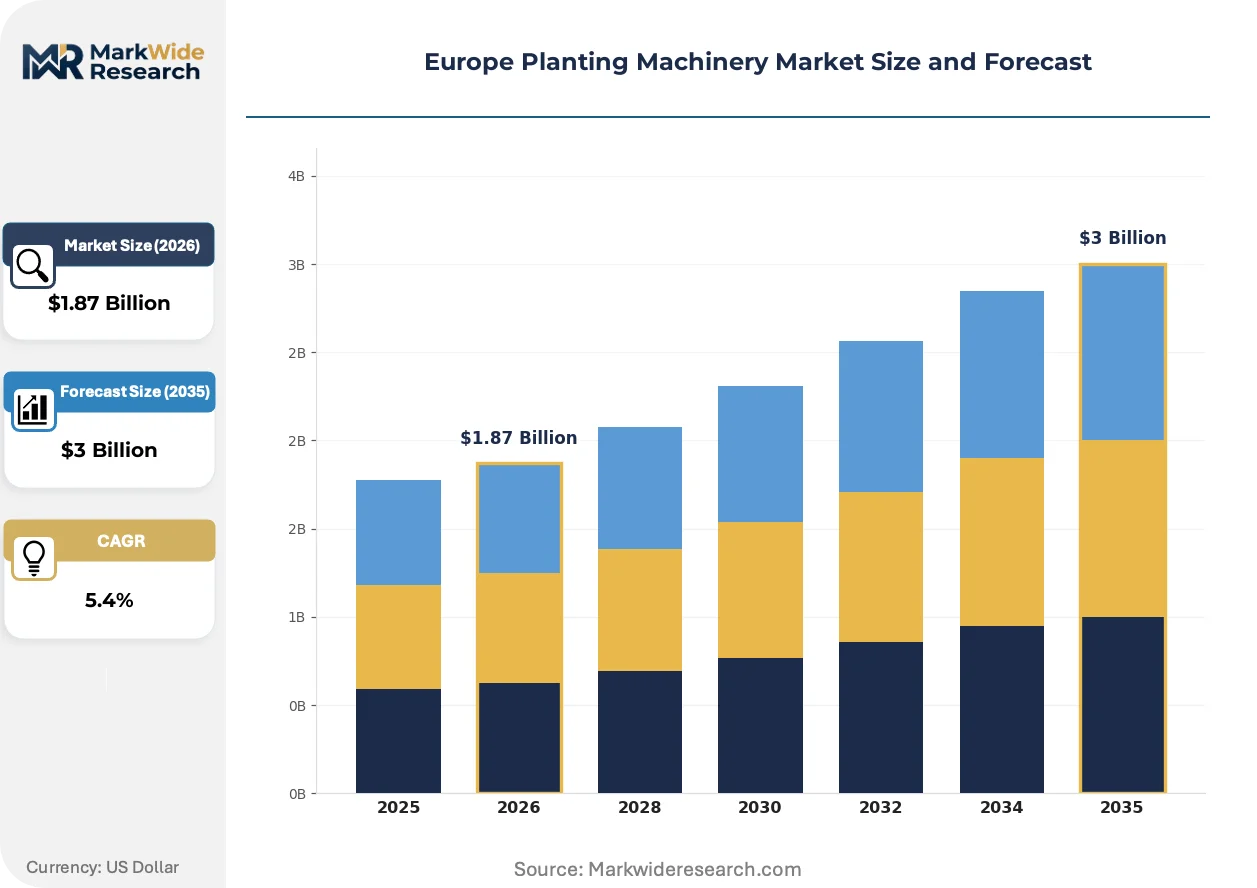
Market Dynamics
CE-marking compliance under the EU Machinery Directive is compressing equipment replacement cycles as farmers accelerate upgrades ahead of anticipated 2027 F-Gas Regulation phase-downs for climate-controlled cabs. This regulatory pressure converges with subsidy retooling under CAP pillar revisions.
Growth Catalysts
- EU Green Deal soil health mandates:National agricultural ministries in France and Germany now tie direct payments to minimum-tillage drill adoption, redirecting cooperative procurement toward conservation-compatible seeders.
- Variable-rate control technology:Section shut-off and prescription mapping capabilities are becoming baseline specifications in subsidy-eligible equipment tenders across Dutch high-value horticulture operations.
- Horticultural intensity in the Netherlands:Vegetable and tobacco belt producers justify transplanter premiums over commodity grain systems, concentrating advanced adoption in North Brabant and Flevoland clusters.
Market Restraints
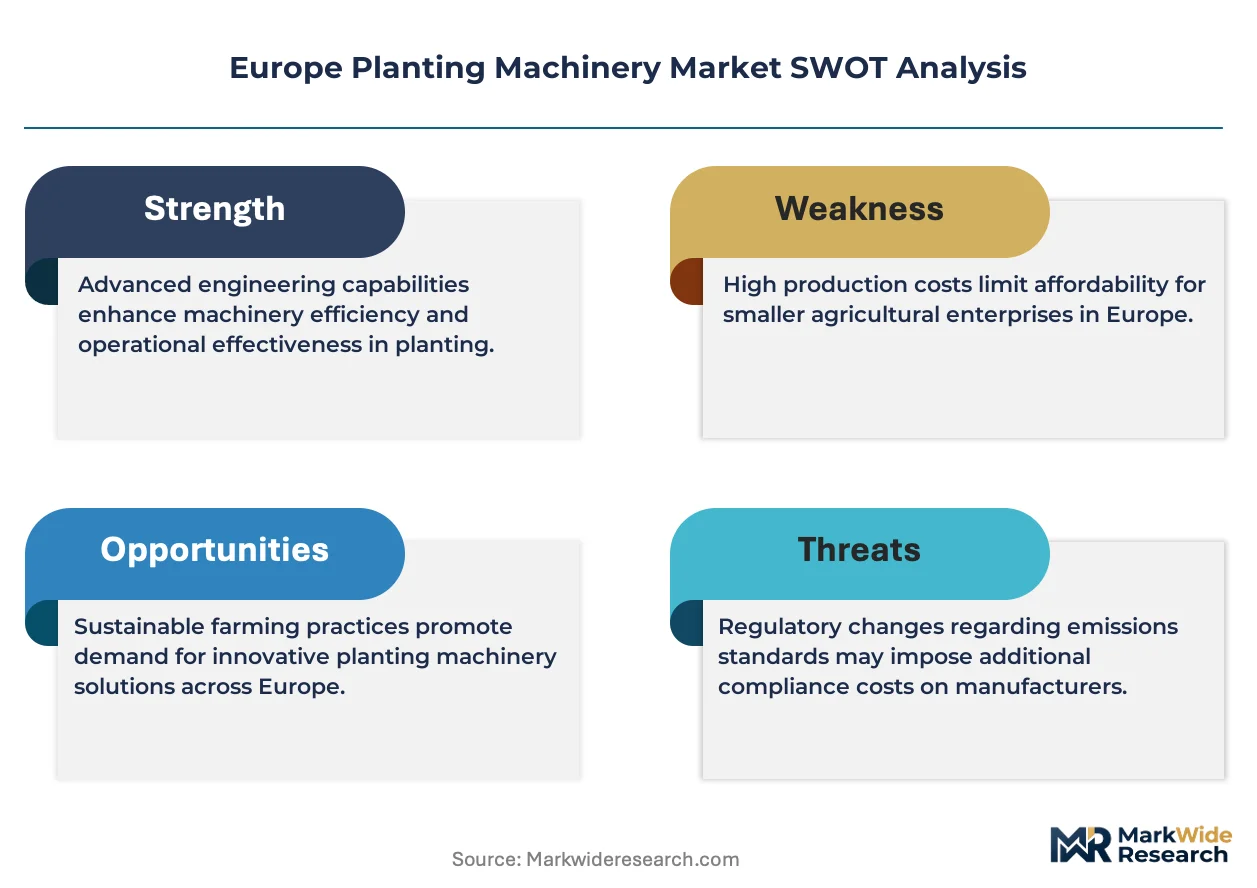
- Steel and hydraulic component volatility:Input cost swings for precision planter frames constrain manufacturer margin stability and OEM pricing predictability.
- Dealer network concentration in France:Dense service infrastructure controlled by incumbent manufacturers limits independent aftermarket access for cooperative buyers in Benelux border regions.
- F-Gas refrigerant constraints:Climate-controlled cab variants face phasedown timelines under EU regulation, complicating fleet standardization for mixed-age operations.
Strategic Opportunities
- Eastern European precision agriculture underpenetration:Polish and Romanian arable sectors present whitespace for retrofit guidance systems and used-equipment upgrade pathways.
- CAP eco-scheme stacking:Cross-compliance incentives for carbon farming create bundled equipment specification demand combining no-till drills with cover crop seeders.
- Telematics-to-insurance convergence:Usage-based coverage models for automated planting equipment are emerging through partnerships between machinery lenders and agricultural mutuals in Germany.
Industry Challenges
- ISOBUS certification timelines:Third-party conformity assessment bottlenecks delay precision agriculture feature launches by 8-14 months for mid-tier manufacturers.
- Legacy fleet integration complexity:Retrofit kit installation for 2015-2019 tractor parc compatibility absorbs disproportionate dealer technician capacity during peak planting windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Planting Machinery Market |
| Market Size in 2026 | $1.87 Billion |
| Market Size in 2035 | $3 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seeder, Planter, Transplanter, Drill End User: Agricultural Cooperatives, Individual Farmers, Government Agencies, Research Institutions Technology: Precision Agriculture, Conventional, Automated, Hybrid Distribution Channel: Direct Sales, Online Retail, Distributors, Dealers |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial, Kubota Corporation, Bucher Industries, ASKO Holding, Claas, Kuhn Group, Lemken, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Planting Machinery Market Shifts & Advancements
Electrification of implement hydraulics and seed meter drives is converging with autonomous tractor platforms to reconfigure power transmission architectures. Equipment specifications now prioritize electrical interface standardization over mechanical PTO compatibility.
Electric seed meter drives is supplanting hydraulic and ground-driven mechanisms in high-speed planter configurations. German large-scale arable cooperatives are specifying all-electric row units for 18-metre working widths to enable precise population control at 20+ km/h. This shift is compressing hydraulic component supplier relevance in premium planter tier supply chains.
The EU F-Gas Regulation phase-down schedule is forcing refrigerant transitions in climate-controlled cab variants ahead of 2027 deadlines. Manufacturers must redesign HVAC systems using lower-GWP alternatives, adding certification burden to new model introductions. Dutch greenhouse-adjacent equipment fleets face the most compressed retrofit timelines due to concurrent sustainability audit requirements.
Cooperative procurement consortia are consolidating equipment specification authority away from individual farm managers. Centralized tendering through French CUMA structures and German Raiffeisen machinery rings is standardizing precision agriculture feature bundles across multi-fleet deployments. This concentration is most visible in the Ile-de-France cereal belt and Lower Saxony cooperative clusters.
Europe Planting Machinery Market Segmentation
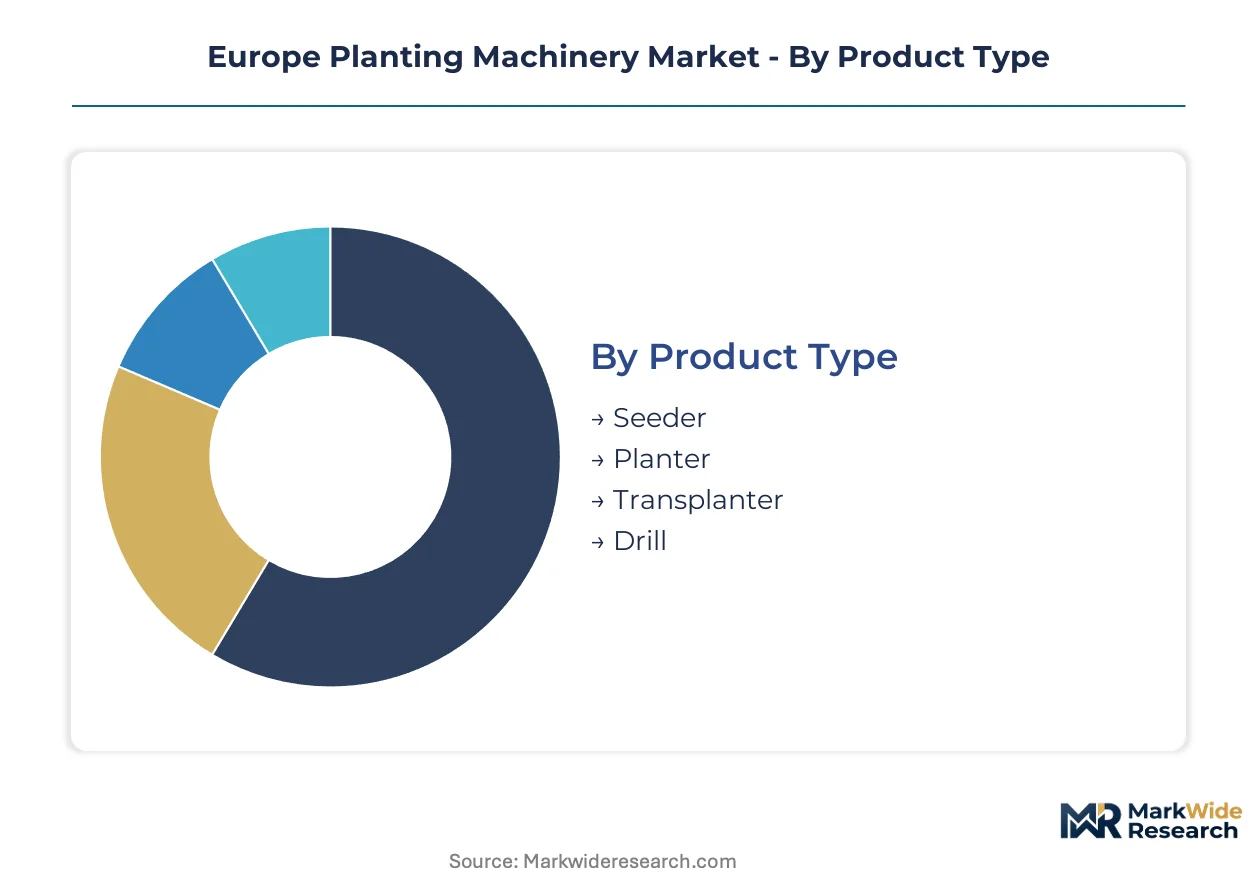
Segmentation in European planting machinery reveals how CE marking tiers, subsidy eligibility rules, and precision agriculture mandates reshape procurement patterns across cooperatives and individual operators. Equipment specification diverges sharply between conservation-tillage compliant systems and legacy conventional configurations.
Product Type:
CE marking requirements under the EU Machinery Directive create divergent compliance burdens across mechanized planting equipment categories, with precision-enabled variants facing extended conformity assessment timelines.
- Seeder:Mechanisms designed for cereal and oilseed establishment at calibrated depths and rates, typically 3–12 metre working widths. French cereal cooperatives in the Ile-de-France belt concentrate demand for minimum-tillage compatible drills tied to CAP eco-scheme eligibility.
- Planter:Row-crop systems with precision population control for maize, sunflower, and sugar beet. Dutch high-value horticulture operations and German large-scale arable cooperatives specify variable-rate and section shut-off capabilities as baseline for subsidy access.
- Transplanter:Specialized equipment for vegetable, tobacco, and ornamental crop establishment. North Brabant and Flevoland clusters justify unit premiums through horticultural intensity.
- Drill:Direct seeding systems optimized for narrow row spacing and reduced soil disturbance. Polish and Romanian arable sectors present whitespace for retrofit guidance integration.
Seeder configurations handle the majority of throughput across European cooperative fleets; planter systems with precision agriculture integration are expanding most quickly on share.
End User:
Procurement authority concentrates differently across customer types, with cooperative structures leveraging consolidated tendering power against fragmented individual farm decision-making.
- Agricultural Cooperatives:CUMA structures in France and Raiffeisen machinery rings in Germany standardize precision agriculture feature bundles across multi-fleet deployments through centralized specification authority.
- Individual Farmers:Owner-operators with sub-200 hectare holdings prioritize used-equipment upgrade pathways and retrofit kit compatibility with 2015-2019 tractor parc.
- Government Agencies:National agricultural ministries in France and Germany redirect fleet procurement toward conservation-compatible seeders through direct payment conditionality.
- Research Institutions:Trial stations and university extension services specify ISOBUS-certified platforms for plot-level experimentation and cultivar evaluation protocols.
Agricultural cooperatives command the dominant procurement volume; government agency fleet replacement is gaining share fastest under CAP pillar revisions.
Technology:
Margin structures diverge across technology tiers, with precision-enabled systems capturing premium positioning through subsidy eligibility and automated configurations absorbing disproportionate R&D investment.
- Precision Agriculture:Variable-rate control, prescription mapping, and section shut-off capabilities. Dutch greenhouse-adjacent operations and German cooperatives treat these as baseline specifications.
- Conventional:Mechanical ground-driven or hydraulic seed metering without electronic population control. Remains prevalent in Eastern European markets with limited telematics infrastructure.
- Automated:Autonomous tractor platform integration with electrical implement interfaces and real-time kinematic guidance. German large-scale arable cooperatives specify all-electric row units for 18-metre working widths.
- Hybrid:Mixed mechanical-electronic architectures bridging legacy fleet compatibility and precision feature adoption. Addresses retrofit complexity for 2015-2019 tractor parc integration.
Precision agriculture technology commands the dominant margin pool; automated configurations are climbing the fastest as electrification converges with autonomous platforms.
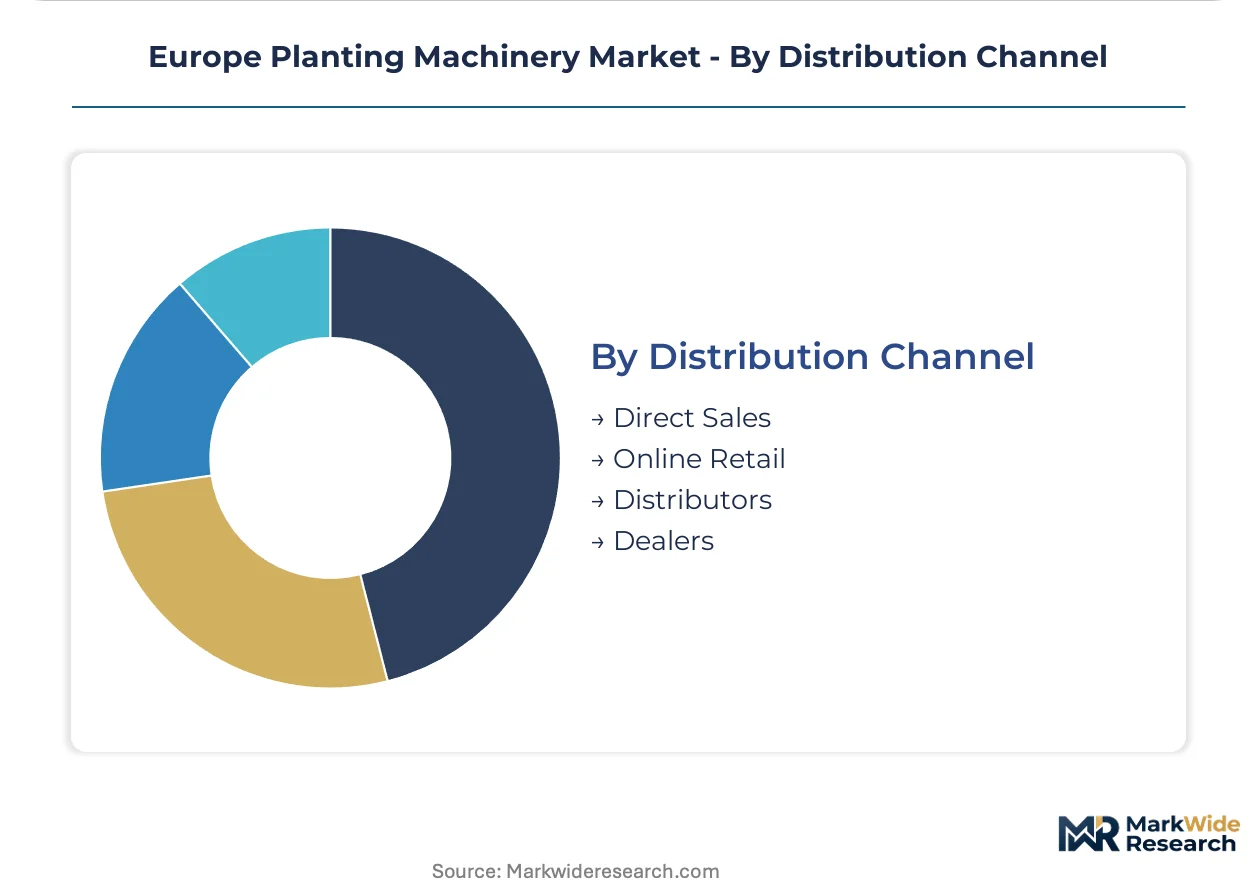
Distribution Channel:
Service infrastructure density determines channel viability, with dealer network concentration in France and Benelux limiting independent aftermarket access for cooperative buyers.
- Direct Sales:Manufacturer-to-cooperative tendering for multi-unit fleet deployments. Kuhn Group leverages dense dealer networks across France and Benelux to control aftermarket service access.
- Online Retail:Spare parts, consumables, and precision agriculture software subscriptions. Limited traction for capital equipment due to CE marking compliance verification requirements.
- Distributors:Regional inventory holding and specification consulting for mid-tier manufacturers. Polish and Romanian markets show whitespace for retrofit guidance system distribution.
- Dealers:Local service capacity, technician training, and warranty administration. Dealer technician capacity constraints peak during compressed planting windows.
Dealer networks handle the majority of equipment throughput; direct sales channels are gaining share fastest as cooperative procurement consortia consolidate tendering authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across European planting machinery demand. French and German cooperatives absorb technology premiums for precision-enabled systems. Polish and Romanian operators prioritize used-equipment pathways and retrofit compatibility.
Germany
Lower Saxony and Schleswig-Holstein cooperative clusters drive automated planter specification with all-electric row units for 18-metre working widths. The EU Machinery Directive's CE marking framework compresses replacement cycles ahead of 2027 F-Gas Regulation phase-downs. Raiffeisen machinery rings in Lower Saxony standardize precision agriculture bundles across multi-fleet deployments through centralized tendering authority.
France
CUMA structures in the Ile-de-France cereal belt concentrate demand for minimum-tillage compatible drills tied to CAP eco-scheme eligibility. The EU Green Deal's soil health targets redirect national agricultural subsidies toward conservation-compatible seeders. Dense dealer networks across France and Benelux control aftermarket service access for cooperative buyers.
Netherlands
North Brabant and Flevoland horticultural clusters justify transplanter premiums over commodity grain systems through vegetable and tobacco belt intensity. F-Gas Regulation refrigerant transitions face compressed timelines due to concurrent sustainability audit requirements for greenhouse-adjacent equipment fleets. Variable-rate control and section shut-off capabilities function as baseline specifications in subsidy-eligible equipment tenders.
Poland
Arable sectors in Greater Poland and Pomeranian Voivodeships present whitespace for retrofit guidance systems and used-equipment upgrade pathways. Limited telematics infrastructure sustains prevalence of conventional mechanical ground-driven seed metering without electronic population control. Regional distributors show expansion potential for mid-tier manufacturer inventory holding and specification consulting.
Romania
The Banat and Transylvania plains exhibit underpenetration for precision agriculture retrofit kits compatible with 2015-2019 tractor parc. National agricultural ministries lack direct payment conditionality for conservation-compatible equipment procurement. Dealer technician capacity constraints peak during compressed planting windows, delaying installation complexity for legacy fleet integration.
Europe Planting Machinery Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across European planting equipment. The market structure consolidates around integrated precision agriculture stacks, specialized seeder lines, and dense service infrastructure networks. Three archetypes dominate: full-stack precision agriculture integrators, regional specialization specialists, and dealer-network-dependent service providers. Competitive moves concentrate on strategic partnerships for telematics-to-insurance convergence and portfolio diversification into electrified implement architectures.
Within the integrated precision agriculture tier, Deere & Company occupies a position exemplifying high-horsepower automated planter dominance. AGCO Corporation and Kuhn Group represent contrasting specialization strategies—AGCO anchors through cereal rotation-tailored seeder lines, while Kuhn Group exemplifies dealer-network-dependent aftermarket control across France and Benelux cooperative markets.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial |
| Kubota Corporation |
| Bucher Industries |
| ASKO Holding |
| Claas |
| Kuhn Group |
| Lemken |
| Others |
Supply & Pricing Matrix
CE marking under the EU Machinery Directive gates market access while simultaneously stratifying price tiers across European planting equipment, forcing manufacturers to absorb conformity assessment costs into premium positioning or sacrifice margin at standard tiers. French cooperative buyers and Dutch horticultural operators face divergent total-cost-of-ownership calculations as after-sales service bundling displaces upfront equipment pricing in procurement evaluations.
Pricing Analysis
Aftermarket parts and service contracts now drive lifetime value capture across automated planter configurations, with annual maintenance agreements absorbing 15-25% of original equipment cost over a seven-year depreciation cycle. Three-tier pricing structure across premium, standard, and economy levels separates ISOBUS-certified precision systems from mechanical ground-driven alternatives, with CE marking compliance and F-Gas refrigerant compatibility commanding tier premiums. Pricing pressure stems from steel and hydraulic component input volatility compressing manufacturer margins, particularly for mid-tier OEMs without captive foundry capacity. Individual farmers with sub-200 hectare holdings exhibit acute price sensitivity, while German Raiffeisen machinery rings and French CUMA structures absorb technology premiums through consolidated tendering volume.
Supply Chain Analysis
Germany and Italy anchor precision planter frame fabrication and hydraulic component manufacturing for European OEM supply chains. High-grade steel sheet, precision seed meter drives, and ISOBUS-certified electronic control modules constitute critical input dependencies. Single-source vulnerability concentrates in electric drive motor suppliers serving German large-scale cooperative demand for 18-metre all-electric row units. Distribution runs through dense dealer networks across France and Benelux, with Kuhn Group and incumbent manufacturers controlling aftermarket service access and constraining independent channel development.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through CE marking and F-Gas compliance creates durable defensive moats for established players, as third-party conformity assessment timelines delay precision feature launches by 8-14 months for challengers.
For Market Incumbents: Fortify dealer technician capacity and ISOBUS certification pipelines against emerging electrification specialists threatening hydraulic component supplier relevance. Deepen backward integration into electric seed meter drive production to capture margin compression from external motor suppliers. Prioritize CAP eco-scheme bundling expertise to maintain specification authority as cooperative procurement consortia consolidate tendering power. For New Entrants and Emerging Players: Retrofit guidance system installation capacity gaps in Poland and Romania offer whitespace penetration paths where legacy fleet integration complexity absorbs disproportionate incumbent dealer resources. Target Eastern European arable sectors with hybrid mechanical-electronic architectures bridging 2015-2019 tractor parc compatibility. Pursue distributor partnerships rather than direct dealer establishment to circumvent entrenched service infrastructure in France and Benelux. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated planter configurations as electrification R&D and autonomous platform integration absorb disproportionate investment. Mid-tier manufacturers with ISOBUS certification progress and Eastern European distribution relationships present viable acquisition profiles. Monitor CAP pillar revision implementation timelines as inflection indicators for conservation-compatible equipment specification demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Network Consolidation | Dense service infrastructure in France and Benelux controls cooperative buyer access and aftermarket revenue capture. |
| Electric Drive Integration | All-electric row unit specification by German cooperatives compresses hydraulic supplier relevance in premium tiers. |
| CAP Eco-Scheme Bundling | Cross-compliance incentive stacking creates bundled demand combining no-till drills with cover crop seeders. |
| Telematics Partnership Development | Usage-based insurance models through agricultural mutuals in Germany monetize planting equipment data streams. |
| Eastern European Distribution Buildout | Polish and Romanian whitespace for retrofit guidance systems enables mid-tier manufacturer market entry. |
Research Methodology
A standing panel of agricultural cooperative procurement managers, dealer network operations directors, OEM product strategy leads, and precision agriculture software engineers provided ongoing calibration across the study period. Primary interview findings combined with secondary validation from EU Machinery Directive conformity assessment databases, CAP implementation monitoring reports, customs trade data for planting equipment imports, and SEC filings from listed agricultural equipment manufacturers. Bottom-up equipment unit forecasts triangulated against top-down agricultural subsidy allocation trends.
Consistency checks validated volume and value outputs against external benchmarks including national agricultural ministry fleet procurement disclosures and cooperative machinery ring tender documentation. Segmentation modeling spanned product type, end user archetype, technology tier, and distribution channel across the projection horizon. CAGRs derived from equipment replacement cycle analysis, subsidy eligibility rule changes, and precision agriculture adoption curve modeling informed by ISOBUS certification timeline data.
Underlying assumptions cover CAP pillar revision implementation pace, F-Gas Regulation phase-down adherence, and steel input cost stabilization, with deviation risk concentrated in Eastern European subsidy uptake rates and electrification technology cost curves. Recalibration cycles align with material shifts in EU Green Deal soil health target enforcement and cooperative procurement consortium structural changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Global Fishery Machinery Manufacturing Market
Agricultural Equipment & Machinery
Global Lawn Mowers Market
Agricultural Equipment & Machinery
Europe Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Seed Drill Machines Market
Agricultural Equipment & Machinery
Global Powered Agriculture Equipment Market
Agricultural Equipment & Machinery
Asia-Pacific Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Agriculture Equipment Market
Agricultural Equipment & Machinery
India Combine Harvester Market
Agricultural Equipment & Machinery
Hammer Mill Market
Agricultural Equipment & Machinery
Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
Germany Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Planting Equipment Market
Agricultural Equipment & Machinery
China Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Grain Silos and Ancillary Equipment Market
Agricultural Equipment & Machinery
Planting and Fertilizing Machinery Market
Agricultural Equipment & Machinery
Global Tillage Equipment Market