
 Digital Agriculture Solutions Market | 2026-2036
Digital Agriculture Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Agriculture Solutions Market Insights
Large-scale commercial farming operations is unwinding from smallholder cooperatives as the dominant buyer archetype in digital agriculture procurement. Deere & Company leverages its captive dealer network and in-house manufacturing of precision guidance hardware to sustain pricing power across North American row-crop regions. Trimble Inc. competes through specialized GNSS correction services that anchor its position in high-accuracy autosteering applications for specialty crop producers.
Digital agriculture solutions encompass integrated hardware-software systems that collect, transmit, and analyze agronomic data to optimize input application and field-level decision-making, typically operating through IoT sensor networks with sub-meter GPS accuracy and cloud-based telemetry dashboards. Precision farming platforms dominate current revenue pools through bundled equipment-and-subscription models, while farm management software represents the fastest-expanding segment as growers seek to consolidate fragmented data streams from multiple equipment brands. Machine learning applications within crop monitoring and yield prediction command premium pricing due to their direct linkage to variable-rate input savings and harvest timing optimization.
The EPA enforces water quality reporting requirements that compel growers toward automated nutrient management systems, while the USDA's conservation programs increasingly mandate digital record-keeping for subsidy eligibility. ISO 11783 standards govern tractor-implement communication protocols, creating compliance barriers for non-integrated equipment entrants. Stakeholders must weigh the capital intensity of full-stack platform ownership against the interoperability risks of modular, multi-vendor architectures as regulatory data submission requirements tighten.
Market Dynamics
Large-scale commercial farming operations are displacing smallholder cooperatives as the dominant procurement force, with EPA water quality mandates and USDA carbon verification requirements accelerating platform consolidation across North American row-crop regions.
Growth Catalysts
- EPA Water Quality Enforcement:Automated nutrient management systems capture regulatory compliance demand as the agency tightens discharge reporting requirements for nitrogen and phosphorus runoff.
- Brazilian Digital Agriculture Subsidies:Federal credit lines for precision farming equipment reshape procurement patterns across Mato Grosso and Goiás soybean belts.
- Machine Learning Crop Monitoring:Variable-rate input optimization algorithms command premium positioning by directly linking predictive analytics to harvest timing decisions.
Market Restraints
- Silicon Supply Concentration:Taiwan and South Korea semiconductor fabrication bottlenecks constrain IoT sensor production for field telemetry networks.
- ISO 11783 Compliance Barriers:Non-integrated equipment manufacturers face exclusion from tractor-implement communication protocols dominated by vertically integrated platform owners.
- Cellular Connectivity Gaps:Rural broadband infrastructure deficits in the US Corn Belt and Brazilian Cerrado limit real-time cloud dashboard functionality.
Strategic Opportunities
- Indian Smallholder Digitization:The country's PLI scheme for agricultural machinery creates subsidy-backed entry points for farm management software aggregators.
- Carbon Credit Verification Platforms:USDA conservation program digitization mandates open revenue streams for soil carbon quantification and third-party audit services.
- Drone-Satellite Sensor Fusion:Convergence of aerial imagery and hyperspectral satellite data enables sub-field resolution without ground sensor capital intensity.
Industry Challenges
- Agronomic Data Science Talent Scarcity:The intersection of crop physiology and machine learning engineering commands compensation premiums that strain mid-tier platform vendors.
- Multi-Brand Equipment Integration:Legacy John Deere, Case IH, and AGCO telemetry silos force growers toward expensive middleware or single-brand lock-in.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Agriculture Solutions Market |
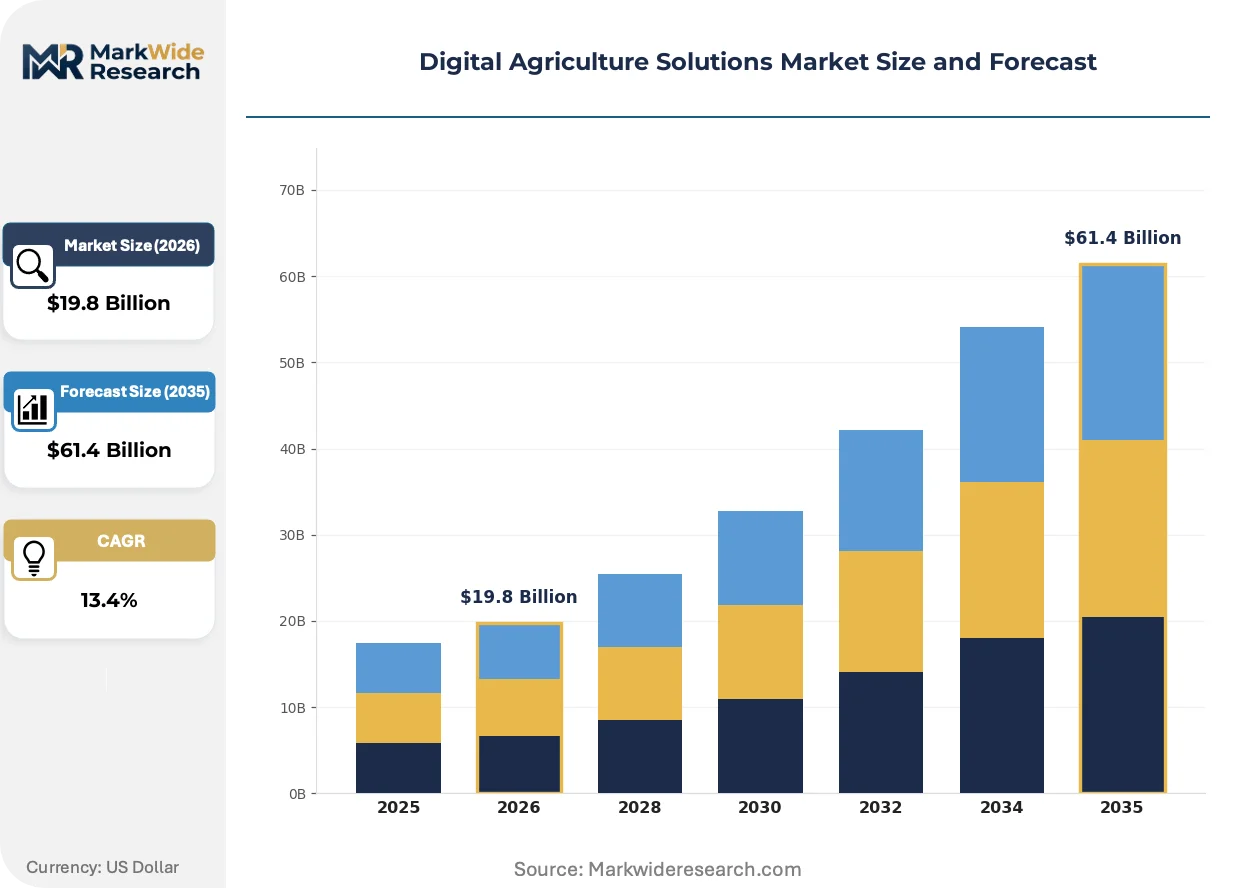
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $61.4 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Precision Farming, Farm Management Software, IoT Sensors, Data Analytics Tools Technology: Machine Learning, Blockchain, Cloud Computing, Remote Sensing End User: Agronomists, Farmers, Agricultural Cooperatives, Crop Advisors Application: Soil Management, Crop Monitoring, Yield Prediction, Pest Control |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial N.V., Trimble Inc., Bayer AG, Topcon Corporation, IBM Corporation, Microsoft Corporation, Kubota Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Agriculture Solutions Market Trends and Innovations
Precision farming platforms are fragmenting into specialized layers as growers resist full-stack vendor dependence, with interoperability standards and modular software architectures gaining traction against captive equipment ecosystems.
Autosteering guidance hardware is bifurcating into two performance tiers. High-accuracy RTK-GNSS correction services anchor premium positioning for specialty crop producers in California's Central Valley and Florida's citrus belts. Commodity row-crop operators in Iowa and Illinois adopt sub-meter GPS alternatives that sacrifice absolute precision for capital efficiency. This split is compressing mid-tier guidance vendors into irrelevance.
REACH chemical registration requirements in the European Union are forcing reformulation of agrochemical active ingredients used in variable-rate application systems. The regulation's hazard classification protocols disqualify legacy chemistries from precision spraying platforms. German and Dutch specialty crop producers face the steepest compliance timelines as their existing digital agriculture workflows embed now-restricted compounds.
Subscription bundling is displacing perpetual licensing across farm management software procurement. North American growers consolidate fragmented data streams from John Deere, Raven, and Trimble equipment through annual SaaS contracts rather than capital-intensive platform purchases. This rotation is most visible among 5,000-50,000 acre operations in Nebraska and Kansas seeking to avoid single-brand telemetry lock-in.
Digital Agriculture Solutions Market Segmentation
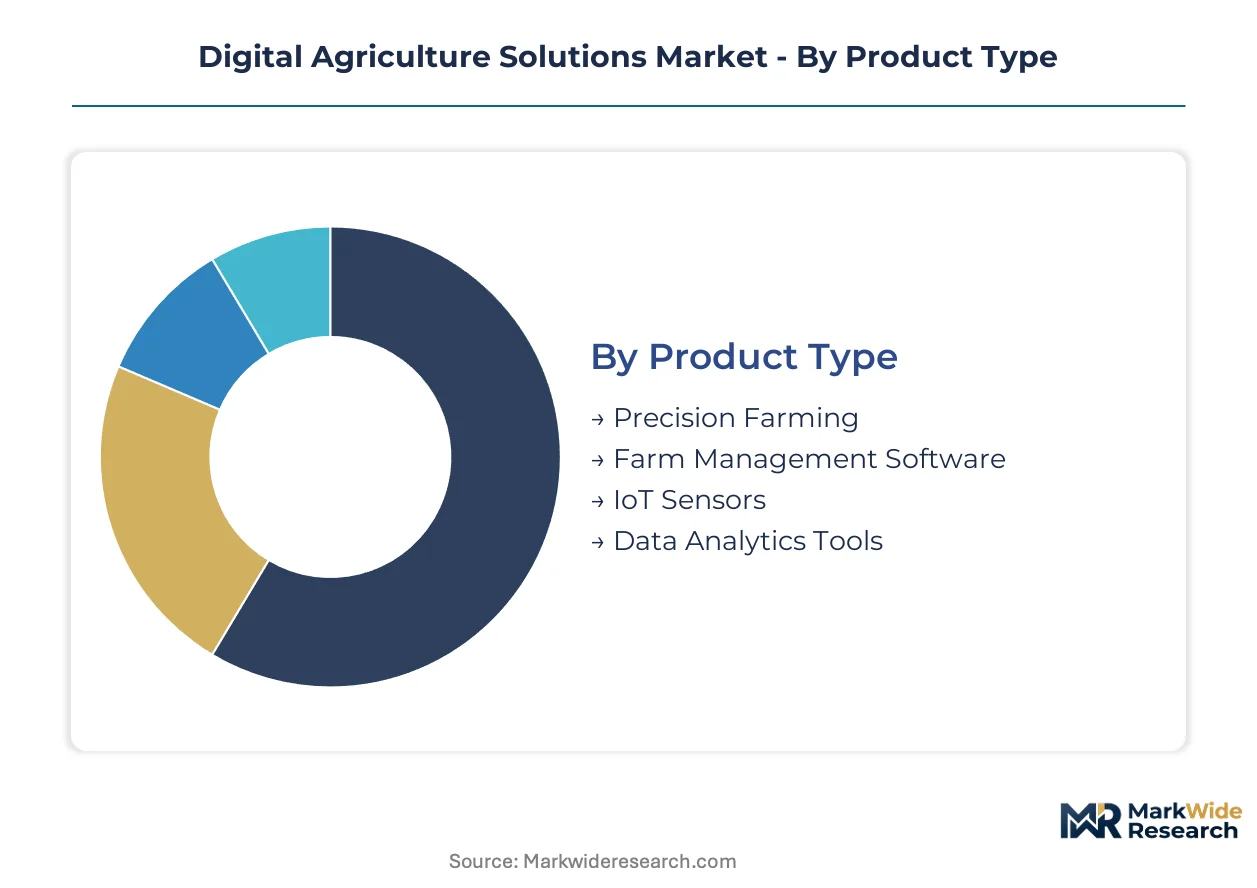
Digital agriculture solutions fragment across four distinct taxonomies that reshape procurement priorities. Product type divisions determine capital intensity and recurring revenue models. Technology layers govern interoperability constraints and regulatory compliance pathways.
Product Type:
EPA water quality mandates and USDA carbon verification protocols create divergent compliance burdens across hardware-software bundles.
- Precision Farming:Integrated guidance hardware and variable-rate application systems achieve sub-meter GPS accuracy through RTK-GNSS correction services. Large-scale Iowa and Illinois row-crop operations deploy these platforms to satisfy nitrogen runoff reporting requirements while optimizing input placement.
- Farm Management Software:Cloud-based telemetry dashboards consolidate fragmented data streams from multiple equipment brands through annual SaaS contracts. Nebraska and Kansas operations spanning 5,000-50,000 acres favor this segment to avoid single-brand telemetry lock-in.
- IoT Sensors:Field-deployed soil moisture and weather monitoring nodes transmit real-time agronomic data.
- Data Analytics Tools:Standalone visualization and reporting platforms process historical yield and input records.
Precision Farming handles the majority of throughput; Farm Management Software is gaining share fastest as subscription models displace perpetual licensing.
Technology:
Cost tier stratification separates capital-intensive infrastructure from lightweight deployment options.
- Machine Learning:Predictive algorithms for crop monitoring and yield prediction command premium positioning through direct linkage to harvest timing optimization. California Central Valley specialty crop producers deploy these tools for irrigation scheduling under state water conservation mandates.
- Cloud Computing:Distributed server architecture enables real-time dashboard access and multi-user collaboration. Brazilian Mato Grosso soybean operations leverage cloud platforms to synchronize field data across dispersed management teams despite cellular connectivity gaps in the Cerrado.
- Blockchain:Distributed ledger systems verify supply chain provenance and carbon credit origination.
- Remote Sensing:Satellite and aerial imagery platforms capture field-level vegetation indices without ground sensor installation.
Cloud Computing anchors current deployment volume; Machine Learning shows the steepest expansion trajectory as growers prioritize predictive over descriptive analytics.
End User:
Customer type determines purchasing authority and integration complexity across the value chain.
- Farmers:Direct operators of commercial acreage drive platform selection based on equipment compatibility and dealer support networks. Large-scale North American row-crop producers increasingly displace smallholder cooperatives as dominant procurement force.
- Agricultural Cooperatives:Member-owned aggregators negotiate volume discounts and shared data infrastructure. Midwestern US cooperatives consolidate purchasing for input optimization across pooled acreage.
- Agronomists:Technical advisors influence platform selection through recommendation authority.
- Crop Advisors:Independent consultants prescribe digital tools without direct purchasing control.
Farmers control the dominant share of procurement decisions; Agricultural Cooperatives are climbing fastest as consolidation concentrates buying power.
Application:
Functional use case determines sensor configuration and algorithm training requirements.
- Crop Monitoring:Vegetation index tracking and stress detection systems enable early intervention for nutrient deficiency or disease pressure. Florida citrus belt operations deploy these tools under state agricultural water quality regulations.
- Yield Prediction:Harvest forecasting models integrate weather data, soil conditions, and historical performance. Dutch specialty crop producers utilize these systems to satisfy EU Green Deal sustainability reporting requirements.
- Soil Management:Nutrient mapping and pH monitoring platforms guide lime and fertilizer application.
- Pest Control:Insect population monitoring and predictive spraying systems reduce chemical application volume.
Crop Monitoring processes the highest data volume; Yield Prediction is expanding most quickly as carbon credit verification creates new revenue linkages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports precision farming equipment and agronomic expertise to neighboring Argentine and Paraguayan soybean belts, while Dutch greenhouse technology providers supply controlled-environment systems to Middle Eastern and Asian markets seeking water-efficient production methods.
United States
EPA water quality enforcement and USDA carbon verification mandates drive automated nutrient management procurement across Iowa and Illinois row-crop regions. The Conservation Stewardship Program increasingly requires digital record-keeping for subsidy eligibility. Nebraska and Kansas operations spanning 5,000-50,000 acres consolidate fragmented telemetry through annual SaaS contracts to avoid single-brand lock-in.
Brazil
Federal credit lines for precision farming equipment reshape procurement across Mato Grosso and Goiás soybean belts. ANVISA agrochemical registration requirements intersect with variable-rate application system deployment. The Cerrado region faces persistent cellular connectivity gaps that limit real-time cloud dashboard functionality despite expanding 4G infrastructure investments.
Netherlands
EU Green Deal sustainability reporting requirements and REACH chemical registration protocols force reformulation of agrochemical active ingredients in precision spraying systems. Wageningen University research clusters anchor machine learning crop monitoring development for specialty greenhouse producers. Dutch firms export controlled-environment expertise to water-stressed markets in the Middle East and Asia.
India
The PLI scheme for agricultural machinery creates subsidy-backed entry points for farm management software aggregators serving smallholder cooperatives. FSSAI traceability mandates accelerate blockchain supply chain verification pilots. Maharashtra and Gujarat agritech clusters concentrate drone-satellite sensor fusion development for sub-field resolution without ground sensor capital intensity.
China
MIIT smart agriculture directives and dual carbon goals propel precision farming platform adoption across Yangtze River Delta rice production zones. GB standards for agricultural IoT devices create compliance frameworks for domestic equipment manufacturers. Shandong Province machinery manufacturers integrate satellite navigation correction services into autosteering guidance systems for export markets.
Digital Agriculture Solutions Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and interoperability dimensions. The vendor base stratifies into three tiers: vertically integrated equipment manufacturers with captive dealer networks, modular software specialists enabling multi-brand data consolidation, and component suppliers providing GNSS correction or sensor hardware. Consolidation pressure intensifies as EPA and USDA compliance requirements favor full-stack platform ownership over fragmented architectures. Dominant competitive moves include strategic partnerships between machinery OEMs and cloud infrastructure providers, plus backward integration into semiconductor and sensor fabrication.
Among North American equipment manufacturers, Deere & Company and Trimble Inc. exemplify divergent strategic archetypes. Deere leverages captive dealer networks and in-house precision guidance hardware production to sustain pricing power across row-crop regions. Trimble occupies a specialist position anchored in high-accuracy GNSS correction services for autosteering applications. AGCO Corporation represents the mid-tier equipment challenger seeking interoperability advantages against closed telemetry ecosystems. These three firms illustrate the competitive tension between full-stack platform control and modular, multi-vendor flexibility.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial N.V. |
| Trimble Inc. |
| Bayer AG |
| Topcon Corporation |
| IBM Corporation |
| Microsoft Corporation |
| Kubota Corporation |
| Others |
Pricing and Supply Chain Analysis
Subscription-based SaaS models replacing perpetual licensing in farm management software simultaneously concentrate value capture with cloud infrastructure providers and compress margins for hardware-centric platform vendors. This substitution dynamic shifts procurement authority toward annual contract negotiators in Nebraska and Kansas while fragmenting equipment manufacturers' traditional pricing power.
Pricing Analysis
Current-generation RTK-GNSS correction services command substantial premiums over sub-meter GPS alternatives, while next-generation machine learning crop monitoring tools justify value-based pricing through harvest timing optimization. Three-tier pricing structure across premium, standard, and economy levels separates high-accuracy specialty crop applications from commodity row-crop deployments. Pricing pressure stems from Brazilian federal credit line subsidies that cap equipment financing costs for Mato Grosso soybean operators. Large-scale commercial farming operations exhibit lowest price sensitivity due to compliance-driven procurement mandates, whereas smallholder cooperatives in India face acute budget constraints under PLI scheme limitations.
Supply Chain Analysis
Extended lead times for semiconductor components constrain IoT sensor production schedules across precision farming hardware manufacturers. Taiwan and South Korea anchor semiconductor fabrication for field telemetry networks, while China and Germany concentrate specialized agricultural machinery production. Raw material dependencies span silicon wafers, rare earth magnets for guidance motors, and lithium cells for remote sensor power. Single-source vulnerability in Taiwan semiconductor foundries exposes vendors to geopolitical disruption. Distribution runs through captive dealer networks for Deere and AGCO equipment, with modular software vendors deploying direct cloud sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine learning crop monitoring represents a high-growth disruption as EPA water quality mandates and USDA carbon verification requirements compel automated data collection across Iowa and Illinois row-crop regions.
For Market Incumbents: Fortify telemetry ecosystem control by embedding ISO 11783 compliance into proprietary tractor-implement communication protocols. Backward integration into semiconductor inventory buffers against Taiwan foundry bottlenecks. Prioritize cloud infrastructure partnerships to defend subscription revenue streams against modular software specialists. For New Entrants and Emerging Players: ISO 11783 certification fast-track unlocks equipment interoperability positioning against closed telemetry silos. Target Indian smallholder digitization under PLI scheme subsidies as the most penetrable geography. Deploy drone-satellite sensor fusion to bypass ground sensor capital intensity requirements. For Investors and Strategic Acquirers: USDA conservation program digitization reshapes the acquisition landscape toward soil carbon quantification platform specialists. Five-to-ten year viability hinges on regulatory data submission requirements tightening across multiple jurisdictions. Pursue modular software aggregators with multi-brand integration capabilities. Watch EPA enforcement intensity in the US Corn Belt as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Infrastructure Partnership | Microsoft Azure and AWS partnerships enable real-time telemetry dashboard deployment for Brazilian Cerrado operations. |
| GNSS Correction Service Expansion | RTK-GNSS network densification in California Central Valley anchors premium positioning for specialty crop producers. |
| Machine Learning Crop Monitoring Launch | Predictive yield algorithms directly link to variable-rate input savings under EPA nitrogen runoff reporting mandates. |
| Carbon Credit Verification Platform | Third-party audit services capture USDA conservation program digitization revenue streams. |
| Drone-Satellite Sensor Fusion | Hyperspectral aerial imagery convergence eliminates ground sensor capital intensity for Maharashtra smallholders. |
Research Methodology
A spread of perspectives from precision farming platform executives, agricultural cooperative procurement directors, EPA compliance officers, and cloud infrastructure specialists converged on the working assumptions. Primary interviews with Deere and Trimble dealer network managers supplemented secondary validation through USDA Conservation Stewardship Program filings, EPA water quality discharge reports, Brazilian federal credit line disclosures, and ISO 11783 technical documentation. Bottom-up equipment shipment tallies triangulated against top-down subscription revenue estimates across the analysis window.
Segmentation dimensions modeled include product type, technology layer, end user archetype, and application function across the projection horizon. CAGRs derive from regression analysis of historical adoption curves adjusted for regulatory inflection timing. Forecast inputs incorporate EPA enforcement intensity indices and Brazilian subsidy allocation trajectories without year-specific anchors.
Decision-makers should treat outputs as directional under sustained EPA water quality mandate enforcement and continued Brazilian federal credit availability; material deviation in either assumption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Automated Pest Monitoring System Market
Precision Agriculture
Crop Monitoring Market
Precision Agriculture
Asia-Pacific Agricultural Sensors Market
Precision Agriculture
Agriculture IoT Sensor Market
Precision Agriculture
Remote Fertigation Monitoring Services Market
Precision Agriculture
Global Agriculture Sensors Market
Precision Agriculture
Precision Farming Software Market
Precision Agriculture
Precision Farming Market
Precision Agriculture
Connected Agriculture Software Market
Precision Agriculture
Global Digital Agriculture Platform Market
Precision Agriculture
Agricultural Sensors Market
Precision Agriculture
Soil Monitoring System Market
Precision Agriculture
Europe Precision Farming Market
Precision Agriculture
Variable Rate Technology Market
Precision Agriculture
Global Internet of Things (IoT) Agriculture Market
Precision Agriculture
Precision Viticulture Market