
 United Kingdom Crop Protection Chemicals Market | 2026-2036
United Kingdom Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Crop Protection Chemicals Market Analytics
The gap between premium formulated products and commodity generic active ingredients is shifting wider as UK farmers face squeezed margins and patchwork resistance management needs. BASF SE anchors its position through proprietary fungicide formulations targeting septoria in wheat, while Syngenta Group leverages integrated seed-and-chemistry bundles to control distribution channels across East Anglia. Nufarm Limited competes on volume-scale generic herbicides that supply the national combinable crops sector.
Crop protection chemicals encompass synthetic and biological formulations designed to control weeds, pests, and fungal pathogens in agricultural production, typically containing specified active ingredients at concentrations governed by UK Chemicals Regulation post-BREXIT and requiring MAPP authorization before field application. Herbicides command the largest share of UK product type demand, driven by blackgrass and ryegrass pressure in winter cereals, while bio-pesticides represent the fastest-expanding category as the Sustainable Farming Incentive rewards reduced synthetic chemical inputs. Application through soil treatment is gaining structural importance as farmers adopt pre-emergence programs to delay herbicide resistance onset and protect yield potential.
The Health and Safety Executive serves as the UK's national regulator for pesticide authorization through its MAPP registration system, while the Environment Agency enforces water quality standards that restrict active ingredient use near catchment-sensitive zones. The EU Green Deal's Farm to Fork targets still shadow UK policy debates, though Westminster now controls divergence timing. Stakeholders must monitor whether DEFRA accelerates its own hazard-based cut-off criteria independently of Brussels, as this would force reformulation investments ahead of any EU timeline.
Market Dynamics
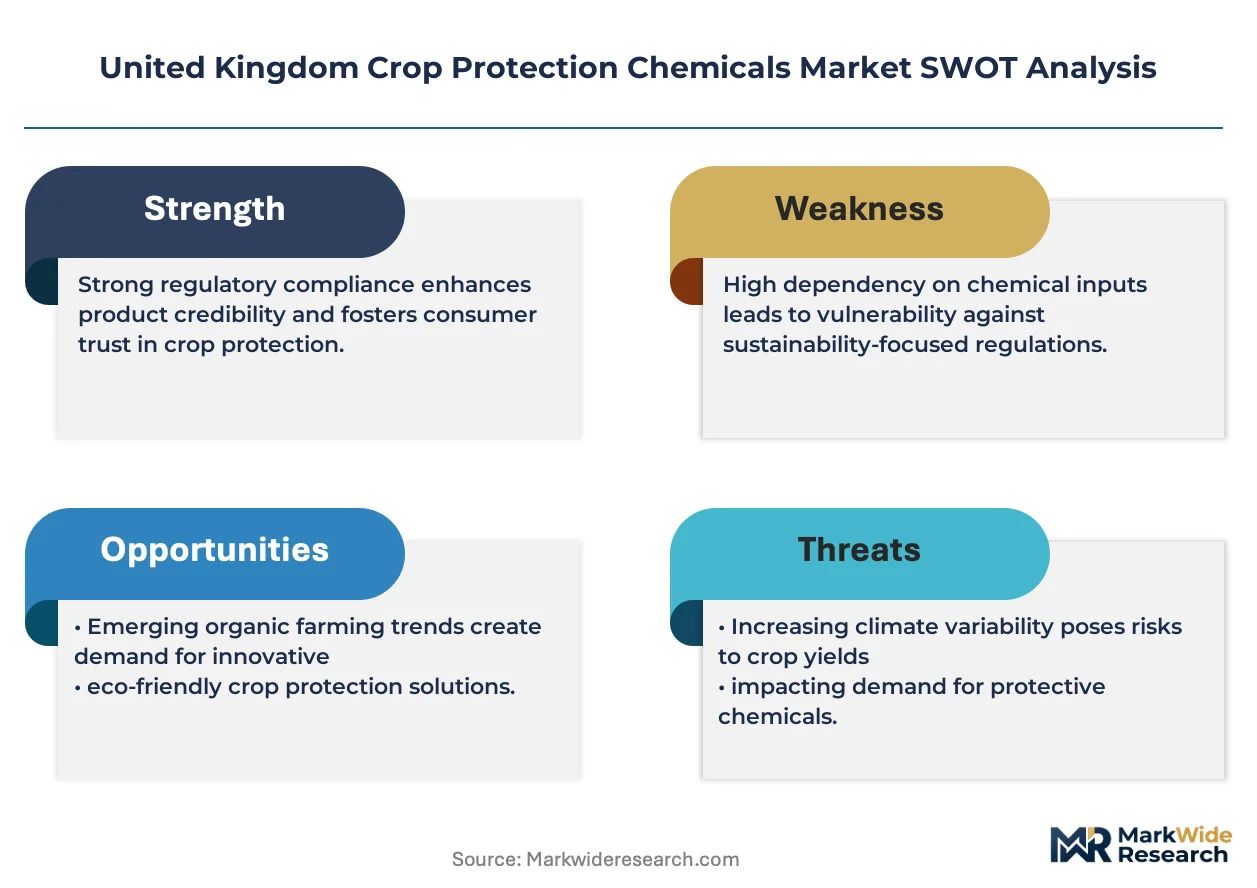
Post-Brexit regulatory divergence from EU REACH standards is fragmenting product approval pathways and forcing manufacturers to maintain parallel compliance dossiers for the UK MAPP system. This structural friction concentrates investment capacity among larger formulators while squeezing mid-tier generic suppliers.
Growth Catalysts
- Sustainable Farming Incentive:DEFRA's payment scheme rewards reduced synthetic chemical inputs, accelerating farmer adoption of precision application equipment and bio-pesticide rotations.
- East Anglia cereal belt:Large-scale wheat and barley operations in England's eastern counties generate concentrated procurement volumes that justify dedicated distribution infrastructure and technical service investment.
- Septoria resistance pressure:Fungal pathogen evolution in winter wheat is shortening product lifecycles and compelling growers to upgrade to premium formulated fungicides with novel modes of action.
Market Restraints
- Active ingredient supply concentration:Chinese manufacturers dominate upstream synthesis of generic herbicide actives, exposing UK formulators to shipping cost volatility and geopolitical supply interruptions.
- MAPP authorization timelines:Health and Safety Executive review periods for new active substances extend 36-48 months, delaying product launches and compressing commercialization windows before patent expiry.
- Water framework directive catchments:Environment Agency restrictions on neonicotinoid and chlorpyrifos use near sensitive water bodies eliminate entire product categories from arable zones covering 15% of England's cereal area.
Strategic Opportunities
- Biological formulation partnerships:UK research institutes with microbial screening capabilities offer licensing pathways for next-generation bio-fungicides targeting take-all and eyespot in wheat.
- Drone application services:Unmanned aerial systems enable variable-rate spot spraying that cuts chemical volumes 30-40% while satisfying Sustainable Farming Incentive environmental metrics.
- Pre-emergence soil treatment programs:Farmer education on residual herbicide layering creates demand for specialist application equipment and technical advisory services beyond commodity product sales.
Industry Challenges
- Resistance management expertise:Agronomists with deep knowledge of herbicide mode-of-action rotation protocols are scarce outside major distributor technical teams, limiting independent farm advice quality.
- Legacy sprayer calibration:Older boom sprayers in the UK fleet lack pulse-width modulation and individual nozzle control, degrading application accuracy and undermining precision chemistry performance claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Crop Protection Chemicals Market |
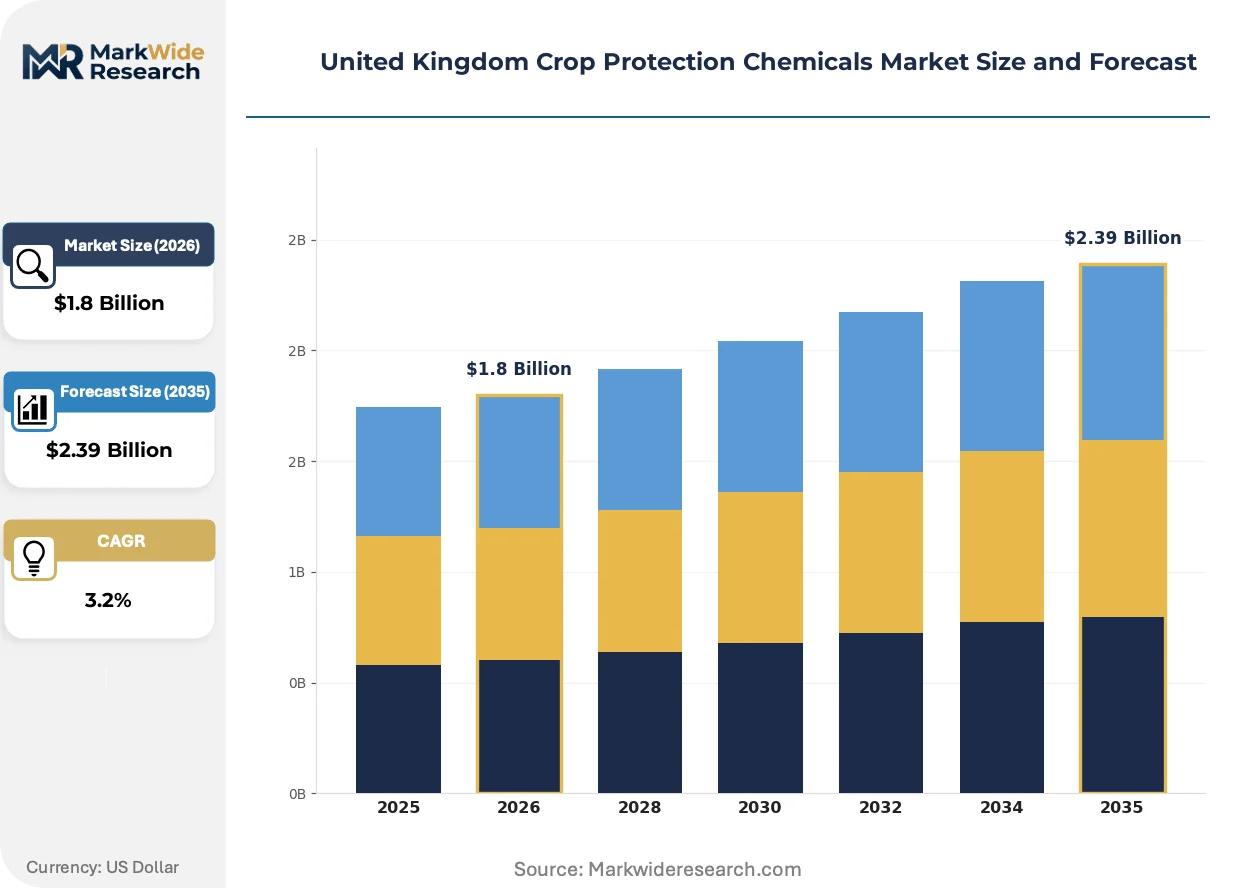
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.39 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Bio-pesticides Application: Agricultural, Horticultural, Soil Treatment, Post-Harvest Packaging Type: Bulk, Sachets, Bottles, Boxes Customer Type: Farmers, Agro-dealers, Cooperatives, Exporters |
| Companies Covered | Syngenta Group, FMC Corporation, BASF SE, ADAMA Agricultural Solutions Ltd, UPL Limited, Bayer AG, Nufarm Limited, Sumitomo Chemical Co. Ltd, Corteva Agriscience, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Crop Protection Chemicals Market Evolving Landscape
Digital agriculture platforms are merging real-time weather data with field-specific disease models to trigger just-in-time fungicide applications. This capability is compressing traditional calendar-based spraying schedules and redistributing chemical demand toward rapid-response logistics networks.
Variable-rate application technology is consolidating field management around prescription maps generated from satellite imagery and soil conductivity surveys. Large East Anglia estates are retrofitting self-propelled sprayers with section-control booms that shut off over buffer zones and previously treated areas. The technology is consolidating input purchasing power among operators who can demonstrate measurable chemical savings to landlord investors.
DEFRA's divergence from EU hazard-based cut-off criteria is creating a separate UK regulatory trajectory for endocrine-disrupting active substances. Formulators must now prepare UK-specific data packages for substances that Brussels may delist earlier or later than Westminster. Wheat fungicide portfolios face the greatest exposure, as triazole chemistry already sits under review in both jurisdictions with diverging evidentiary standards.
Buying clubs and cooperative procurement groups are aggregating smaller farm orders to access volume-tier pricing previously reserved for 500-hectare-plus operators. This behavior is fragmenting the traditional distributor-retailer hierarchy and forcing manufacturers to develop direct digital rebate programs. The shift is most visible in Lincolnshire and Yorkshire, where machinery rings have expanded into input supply coordination.
United Kingdom Crop Protection Chemicals Market Segmentation
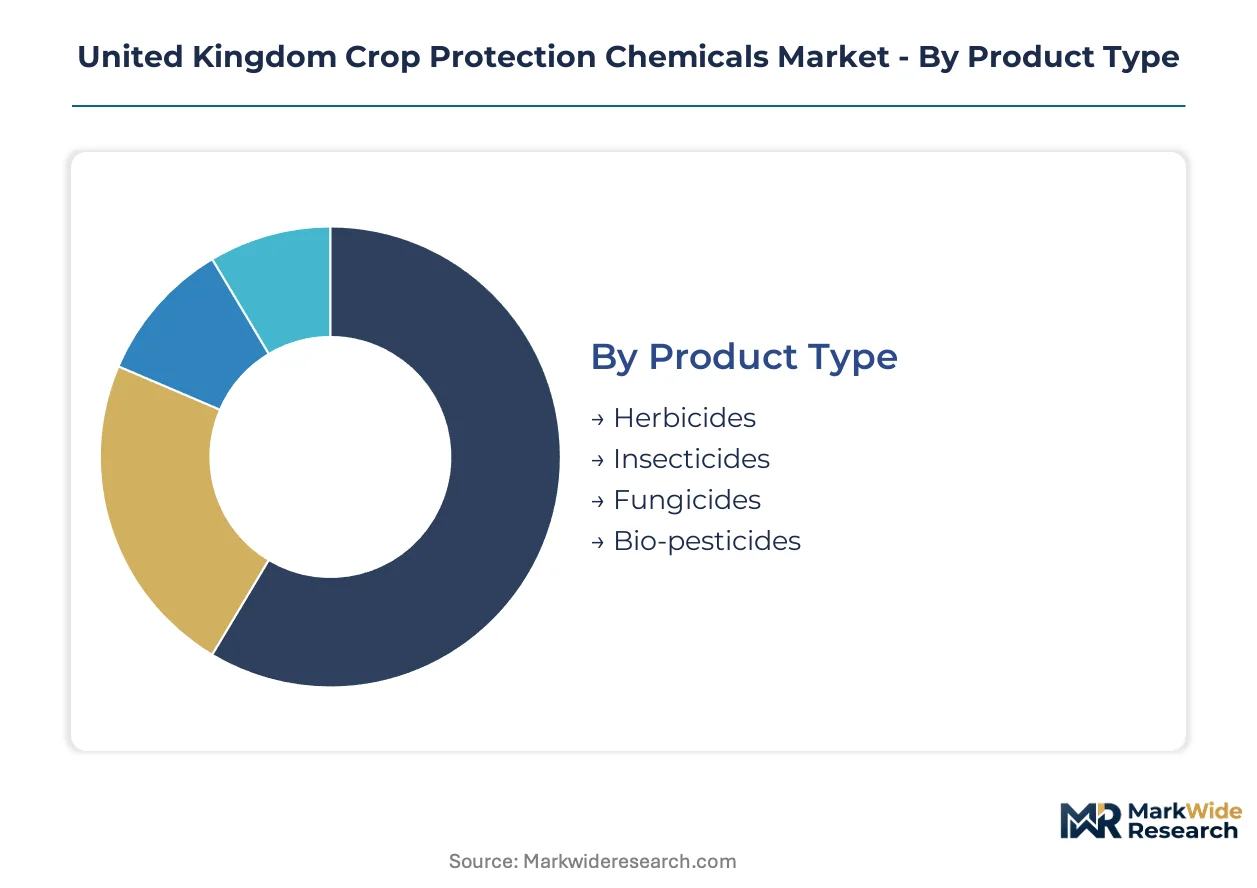
Segmentation in the UK crop protection market reveals how procurement power, application methods, and regulatory compliance requirements fragment demand across distinct customer behaviors and product specifications. Understanding these divides exposes where margin concentrates and where volume flows.
Product Type:
Farmer prioritization of resistance management and yield protection drives product selection more than price alone, with chemistry lifecycle stage and mode-of-action novelty commanding premium positioning.
- Herbicides:Formulations containing glyphosate, sulfonylurea, and auxin-based actives dominate UK arable procurement. Blackgrass and ryegrass pressure in East Anglia's winter cereal belt sustains demand for pre-emergence residual chemistry despite tightening water framework restrictions near catchment-sensitive zones.
- Fungicides:Triazole and SDHI-based products targeting septoria tritici in wheat represent the most technically contested segment. Novel modes of action command substantial premia as resistance erosion shortens effective product lifecycles below patent protection periods.
- Insecticides:Neonicotinoid restrictions have eliminated formerly dominant chemistry classes, redirecting demand toward pyrethroid and biological alternatives with narrower spectrums and shorter residual activity windows.
- Bio-pesticides:Microbial and botanical formulations derived from Bacillus subtilis, Trichoderma species, and plant extracts are gaining MAPP registrations. DEFRA's Sustainable Farming Incentive payments for reduced synthetic inputs accelerate farmer trial adoption, particularly among estate managers with environmental KPI obligations to institutional landlords.
Herbicides lead on scale; bio-pesticides lead on momentum.
Application:
Application method selection hinges on crop timing windows, equipment capital intensity, and the labor availability constraints that differentiate large East Anglia estates from smaller mixed farms.
- Agricultural:Foliar spraying of combinable crops—wheat, barley, oilseed rape—generates the core volume base. Self-propelled sprayers with pulse-width modulation and GPS section control now dominate equipment fleets above 400 hectares, enabling variable-rate prescription applications that reduce chemical volumes 20-30%.
- Soil Treatment:Pre-emergence herbicide incorporation and seed treatments are expanding as resistance management protocols emphasize residual chemistry layering. Specialist application equipment requirements create advisory service bundling opportunities beyond commodity product margins.
- Horticultural:Protected cropping systems in Kent, Sussex, and the West Midlands demand low-volume, high-frequency applications with strict pre-harvest intervals. MRL compliance for supermarket supply contracts drives product selection toward reduced-risk chemistry with established residue clearance data.
- Post-Harvest:Grain store and potato storage treatments constitute a smaller, specification-driven segment where phosphine alternatives and biological sprout suppressants are displacing legacy actives under changing food safety audit standards.
Agricultural applications anchor volume concentration; soil treatment is climbing the fastest as resistance protocols reshape farmer behavior.
Packaging Type:
Packaging selection reflects order scale, storage infrastructure, and the regulatory traceability requirements that differentiate commercial distributors from direct farm supply.
- Bulk:Returnable intermediate bulk containers and dedicated tanker deliveries serve estates above 1,000 hectares and cooperative procurement groups. Container tracking systems satisfy HSE waste regulations while enabling volume-tier pricing negotiations.
- Bottles:Standard 1-10 litre HDPE containers dominate distributor-retailer channels serving farms below 200 hectares. Label compliance with UK-specific MAPP authorization numbers and buffer zone restrictions requires country-specific packaging runs that fragment production economics.
- Sachets:Water-soluble pouches and single-dose packaging address horticultural and specialty crop applications where measurement accuracy and operator safety drive premium positioning.
- Boxes:Carton packaging for granular formulations and seed treatment products serves the amenity and small-scale agricultural segments with lower chemical load requirements.
Bulk packaging leads on scale; sachet formats are gaining share fastest in horticultural premium channels.
Customer Type:
Customer category determines pricing transparency, technical service intensity, and the loyalty mechanisms that manufacturers deploy to defend market position.
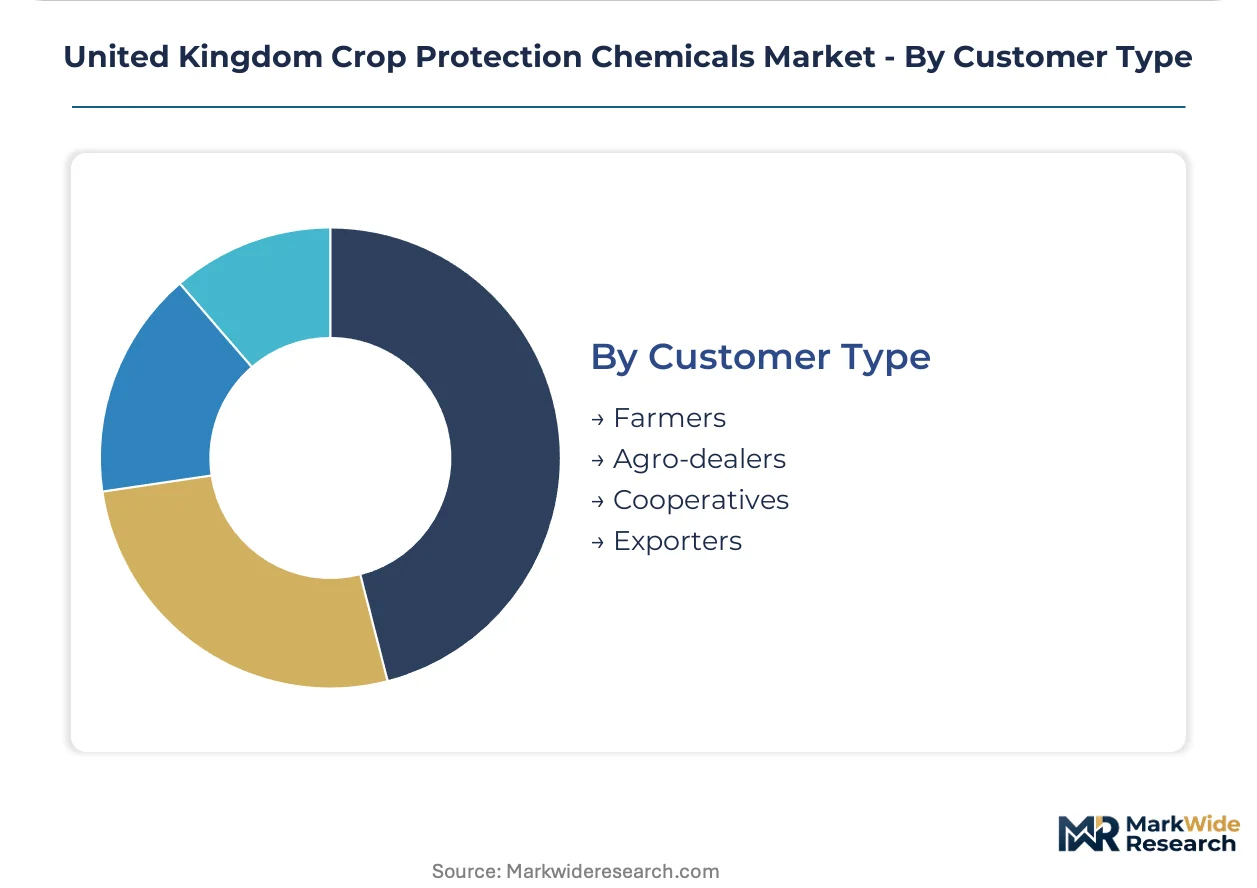
- Farmers:Direct procurement by estates above 500 hectares concentrates in England's cereal belt, where technical agronomists influence product selection through resistance management protocols and yield response data. Buying clubs in Lincolnshire and Yorkshire aggregate smaller holdings to access volume-tier terms.
- Agro-dealers:Independent distributors with technical advisory capabilities capture margin through application timing recommendations and equipment calibration services. Their field staff scarcity outside major networks constrains service coverage in peripheral arable regions.
- Cooperatives:Farmer-owned supply groups negotiate collective purchasing agreements and operate shared application equipment pools. Their governance structures prioritize input cost reduction over brand loyalty, intensifying price competition among manufacturers.
- Exporters:traders supplying crop protection products to overseas markets, particularly Commonwealth agricultural sectors, represent a specialized channel with distinct registration and labeling requirements.
Farmers lead on scale; cooperatives lead on procurement leverage expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical agronomists and precision agriculture specialists concentrate in England's eastern counties, anchoring the UK's crop protection demand geography around specialized advisory capacity rather than simple acreage statistics.
East Anglia
Large-scale wheat and barley operations across Norfolk, Suffolk, and Cambridgeshire generate the UK's densest chemical procurement volumes. The Environment Agency's catchment-sensitive farming regulations restrict neonicotinoid applications near the Broads and river systems. BASF SE and Syngenta Group maintain dedicated distribution depots in Bury St Edmunds and Peterborough to service 500-hectare-plus estates with just-in-time fungicide logistics.
East Midlands
Blackgrass-resistant winter cereal rotations in Lincolnshire and Nottinghamshire sustain demand for pre-emergence herbicide layering protocols. DEFRA's Sustainable Farming Incentive pilot zones here reward reduced synthetic input programs with payment premiums above standard rates. Buying clubs centered on machinery rings in the Lincolnshire Wolds aggregate smaller farm orders to access manufacturer volume-tier pricing.
Yorkshire and the Humber
Mixed arable-livestock systems across North Yorkshire and the East Riding require flexible crop protection portfolios spanning combinable crops and forage maize. The Health and Safety Executive's MAPP authorization requirements apply uniformly, but regional distributor networks vary in technical service intensity. Wilton Centre near Redcar hosts formulation research partnerships between agrochemical majors and UK crop science institutes.
South East England
Horticultural and viticultural operations in Kent, Sussex, and the Thames Valley demand low-volume, high-frequency applications with strict MRL compliance for supermarket supply contracts. The EU Green Deal's Farm to Fork residue targets shadow procurement decisions despite post-Brexit regulatory divergence. Glasshouse clusters around the Isle of Thanet and Worthing anchor biological pesticide trial adoption.
Scotland
Spring barley and potato production in Aberdeenshire and the Borders generates distinct seasonal demand peaks offset from England's winter cereal calendar. Scottish Environment Protection Agency water framework restrictions on chlorothalonil and other actives eliminate certain products from catchment-sensitive areas covering Tayside and Fife. SRUC research stations at Craibstone and Edinburgh supply regional trial data supporting MAPP registration dossiers.
United Kingdom Crop Protection Chemicals Market Competitive Landscape
Capital-heavy integrated manufacturers compete with asset-light generic formulators for positioning across the UK's bifurcated procurement channels. The market structure concentrates margin capture among three global conglomerates with proprietary active ingredient pipelines, while volume flows through mid-tier suppliers competing on price in commodity herbicide segments. Two strategic archetypes dominate: integrated innovators defending premium fungicide positions through novel mode-of-action development, and scale-driven generic specialists capturing procurement contracts from cooperative buying groups. Competitive moves center on seed-chemistry bundling to lock distribution channels and biological formulation partnerships to satisfy Sustainable Farming Incentive environmental metrics.
Within the integrated innovator tier, BASF SE, Syngenta Group, and Bayer AG exemplify the capital intensity required to maintain proprietary fungicide pipelines against shortening product lifecycles from resistance evolution. These conglomerates anchor their UK positions through East Anglia-focused technical service teams and integrated seed-treatment bundles that raise switching costs for large cereal estates. Nufarm Limited occupies a distinct position representing the scale-driven generic archetype, competing on volume supply to national combinable crop sectors without the R&D overhead of proprietary active development. The competitive tension between these models intensifies as DEFRA's regulatory divergence from EU REACH standards forces parallel compliance investments that favor balance-sheet capacity over portfolio agility.
| Leading Market Players |
|---|
| Syngenta Group |
| FMC Corporation |
| BASF SE |
| ADAMA Agricultural Solutions Ltd |
| UPL Limited |
| Bayer AG |
| Nufarm Limited |
| Sumitomo Chemical Co. Ltd |
| Corteva Agriscience |
| Others |
Value Network & Pricing Analysis
Precision application technology adoption across East Anglia estates simultaneously compresses chemical volumes per hectare and consolidates procurement power among operators who can demonstrate measurable input savings to institutional landlords. This equipment transition reshapes cost economics by favoring formulators who bundle technical advisory services with product supply, while squeezing commodity generic suppliers unable to support variable-rate prescription workflows.
Pricing Analysis
Product-and-service bundling separates premium formulated fungicides from unbundled generic herbicide supply in UK crop protection. Pricing stratifies across premium novel-mode-of-action fungicides, standard established chemistry, and economy generic actives, with differentiation driven by resistance management efficacy and technical support intensity. Cost compression in commodity herbicide tiers is intensifying because cooperative buying clubs aggregate smaller farm orders to access volume-tier terms previously reserved for 500-hectare-plus estates. Cooperative members exhibit highest price sensitivity; large East Anglia estates with environmental KPI obligations to institutional landlords prioritize performance guarantees over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese manufacturers who dominate upstream synthesis of generic herbicide actives including glyphosate and sulfonylurea chemistry. UK formulators draw from Chinese, Indian, and German supply bases for active ingredients, with formulation and packaging concentrated in domestic facilities near Peterborough and Hull. Raw material dependencies center on petrochemical-derived intermediates, phosphate-based adjuvants, and specialty solvent blends. Tariff exposure on Chinese-origin technical grade materials threatens margin stability for mid-tier generic suppliers. Distribution runs through manufacturer-owned depots serving large estates, independent agro-dealer networks for mid-scale farms, and cooperative procurement groups aggregating smaller holdings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UK crop protection functions as a geographic-arbitrage play where post-Brexit regulatory divergence from EU REACH standards creates compliance cost differentials favoring manufacturers with balance-sheet capacity to maintain parallel UK and EU dossiers.
For Market Incumbents: Extend proprietary fungicide lifecycle value through integrated seed-treatment bundles that raise switching costs for East Anglia cereal estates facing septoria resistance pressure. Deepen backward integration into biological formulation partnerships with UK research institutes to preempt DEFRA's hazard-based cut-off criteria. Channel control through dedicated distribution depots in Bury St Edmunds and Peterborough remains the critical defensive lever against cooperative buying club encroachment. For New Entrants and Emerging Players: Direct-to-farmer digital rebate programs offer the lowest-friction route to bypass entrenched agro-dealer hierarchies, particularly in Lincolnshire and Yorkshire where machinery rings have expanded into input supply coordination. Target bio-pesticide segments where Sustainable Farming Incentive payments accelerate farmer trial adoption and MAPP registration pathways remain less congested than synthetic chemistry. Specialist drone application services for variable-rate spot spraying represent the most penetrable service layer. For Investors and Strategic Acquirers: Roll-up economics work for regional agro-dealer networks because technical agronomist scarcity outside major distributor teams constrains independent advisory capacity, creating consolidation value in fragmented peripheral arable regions. Platform aggregation of smaller dealer networks with shared application equipment pools offers viable five-to-ten year value creation. Watch DEFRA's divergence timing on hazard-based cut-off criteria as the inflection signal determining reformulation investment windows.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Formulation Partnership | Licensing microbial screening capabilities from SRUC and John Innes Centre accelerates MAPP registration for next-generation bio-fungicides. |
| Precision Application Equipment Integration | Retrofitting self-propelled sprayers with pulse-width modulation enables variable-rate prescriptions that satisfy Sustainable Farming Incentive metrics. |
| Cooperative Procurement Group Penetration | Direct digital rebate programs aggregate machinery ring members in Lincolnshire Wolds to access volume-tier pricing negotiations. |
| Seed-Chemistry Bundle Expansion | Integrated seed-treatment offerings raise switching costs for large East Anglia estates dependent on septoria resistance management protocols. |
| Drone Application Service Launch | Unmanned aerial systems enable spot spraying that cuts chemical volumes 30-40% while generating recurring service revenue streams. |
Research Methodology
Multiple input streams — technical discussions with crop protection formulators, agronomist interviews across distributor networks, and regulatory consultations with Health and Safety Executive officials — were reconciled against customs data tracking active ingredient imports, DEFRA subsidy scheme disclosures, and Environment Agency water framework restriction maps. Primary engagement spanned R&D directors at integrated manufacturers, procurement leads at cooperative buying groups, and farm managers operating above 400 hectares in East Anglia. Secondary validation drew from MAPP registration databases, SRUC trial station reports, and Chemicals Regulation Division authorization timelines. Bottom-up product volume estimates and top-down market sizing were cross-referenced to establish analytical consistency.
Historical volume trajectories were compared against panel-based growth assumptions from industry participants to construct projection scenarios across the analysis window. Segmentation modeling incorporated product type, application method, packaging format, and customer category dimensions alongside regional regulatory cluster variations between England, Scotland, and Wales. CAGRs were derived from trend extrapolation adjusted for policy intervention impacts. Key forecast inputs included Sustainable Farming Incentive payment rate evolution, MAPP authorization backlog clearance rates, and precision agriculture equipment penetration curves.
The model assumes a particular technology adoption path where variable-rate application equipment achieves majority penetration among estates above 500 hectares; alternative pathways for drone-based spot spraying would alter the outlook by accelerating bio-pesticide substitution rates. Forecasts reflect assumptions regarding DEFRA's regulatory divergence pace, Chinese supply chain stability, and resistance management protocol adherence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Fogger Market
Crop Protection
US Insecticide Market
Crop Protection
Herbicide Safeners Market
Crop Protection
Soil Fumigant Market
Crop Protection
Dicamba Market
Crop Protection
Synthetic Pesticide Market
Crop Protection
Pest Resistant Crops Market
Crop Protection
China Insecticide Market
Crop Protection
India Insecticide Market
Crop Protection
US Pest Control Market
Crop Protection
Pest Control Market
Crop Protection
Canada Nematicides Market
Crop Protection
North America Crop Protection Chemicals Market
Crop Protection
Global Acaricides Market
Crop Protection
Fruit and Vegetable Crop Protection Market
Crop Protection
Sweet Potato Fly Market