
 Agricultural Packaging Market | 2026-2036
Agricultural Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Packaging Market Intelligence
The division between high-performance packaging for export-grade produce and basic commodity-grade materials for domestic use is hardening. Amcor plc leverages its global scale to offer advanced modified atmosphere packaging for high-value exports. Mondi Group competes effectively by specializing in sustainable paper-based solutions like sacks and bags for bulk agricultural goods. Sonoco Products Company focuses on rigid and flexible packaging for processed foods.
Agricultural packaging comprises materials and containers engineered to protect crops from physical damage and environmental factors during storage and transit. These solutions often incorporate specific barrier properties against moisture and oxygen to preserve freshness. While polyethylene bags and sacks remain the volume leaders in packaging forms, biodegradable polymers represent a high-growth material type. Bulk containers are gaining share for transporting grains, driven by efficiency demands from large agricultural cooperatives.
Regulations like the FDA's rules on food-contact materials in the United States and the EU's Packaging and Packaging Waste Regulation (PPWR) directly influence material selection. These frameworks mandate safety standards and push for recyclability, shaping product development. Stakeholder success depends on navigating the trade-offs between packaging performance, cost, and compliance with evolving sustainability targets.
Market Dynamics
The central dynamic in agricultural packaging is the collision between sustainability mandates and the technical performance required for global food supply chains. This tension forces material science innovation to reconcile demands for extended shelf life with new regulatory frameworks, like the EU Green Deal, that prioritize circularity and waste reduction.
Growth Catalysts
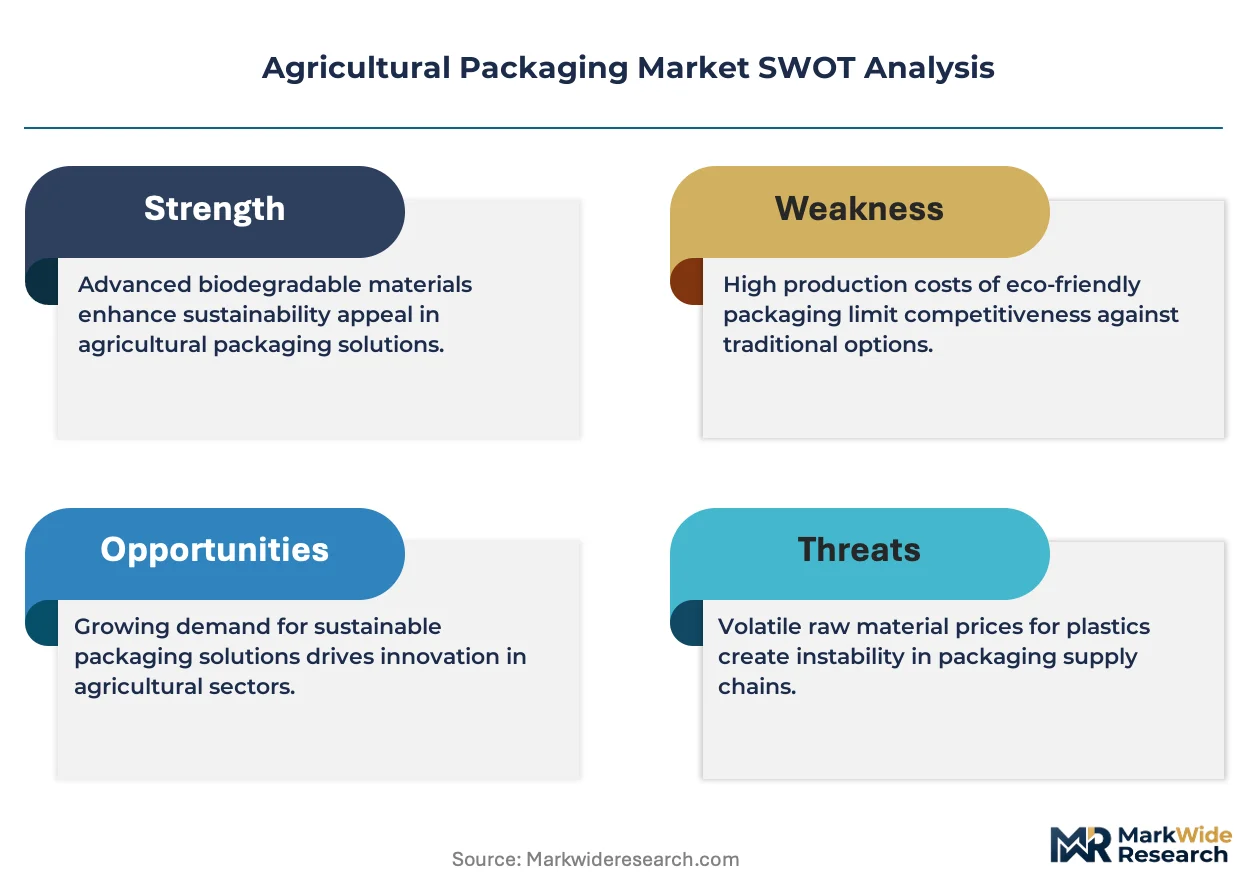
- Regulatory Mandates:The EU's Packaging and Packaging Waste Regulation (PPWR) and similar policies create direct demand for recyclable monomaterials and certified compostable packaging, accelerating the phase-out of legacy plastics.
- Food Processor Demand:Growing demand from food processors for packaging that extends the shelf life of fresh produce is a significant catalyst, particularly for modified atmosphere and vacuum skin packaging formats.
- Export-Oriented Agriculture:Major agricultural exporting nations, including Brazil and India, require higher-performance packaging solutions to protect produce during long-distance transit and meet the quality standards of import markets.
Market Restraints
- Input Cost Volatility:Fluctuation in the price of polymer resins and pulp, key raw materials for both conventional and paper-based packaging, creates margin pressure and complicates long-term procurement planning.
- Performance Trade-offs:Many current-generation biodegradable and compostable polymers exhibit lower barrier performance against moisture and oxygen compared to conventional plastics, limiting their use for sensitive produce.
- Regulatory Fragmentation:Navigating disparate food-contact material regulations, such as the differing standards of the FDA in the United States and EFSA in Europe, adds cost and complexity for exporters.
Strategic Opportunities
- Active Packaging Integration:Incorporating ethylene scavengers, antimicrobial agents, or moisture absorbers directly into packaging materials offers a path to premium pricing by actively preserving freshness and reducing food waste.
- Emerging Market Adoption:There is significant white space for advanced packaging solutions in developing agricultural economies in Southeast Asia and Africa as their export infrastructure modernizes.
- Digitalization of Packaging:The convergence of QR codes and sensor technology with packaging enables enhanced traceability and real-time quality monitoring, meeting retailer and consumer demands for transparency.
Industry Challenges
- Recycling Infrastructure Gaps:The viability of recyclable packaging solutions is constrained by the lack of standardized collection, sorting, and processing infrastructure, particularly for flexible films and new polymer types.
- Certification Timelines:Obtaining necessary food safety and compostability certifications from bodies like the Biodegradable Products Institute (BPI) is a time-consuming and costly process that can delay product launches.
- Capital Investment Cycles:Shifting production from traditional plastics to paper or biopolymer-based alternatives requires significant capital expenditure to retool or replace existing packaging machinery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Packaging Market |
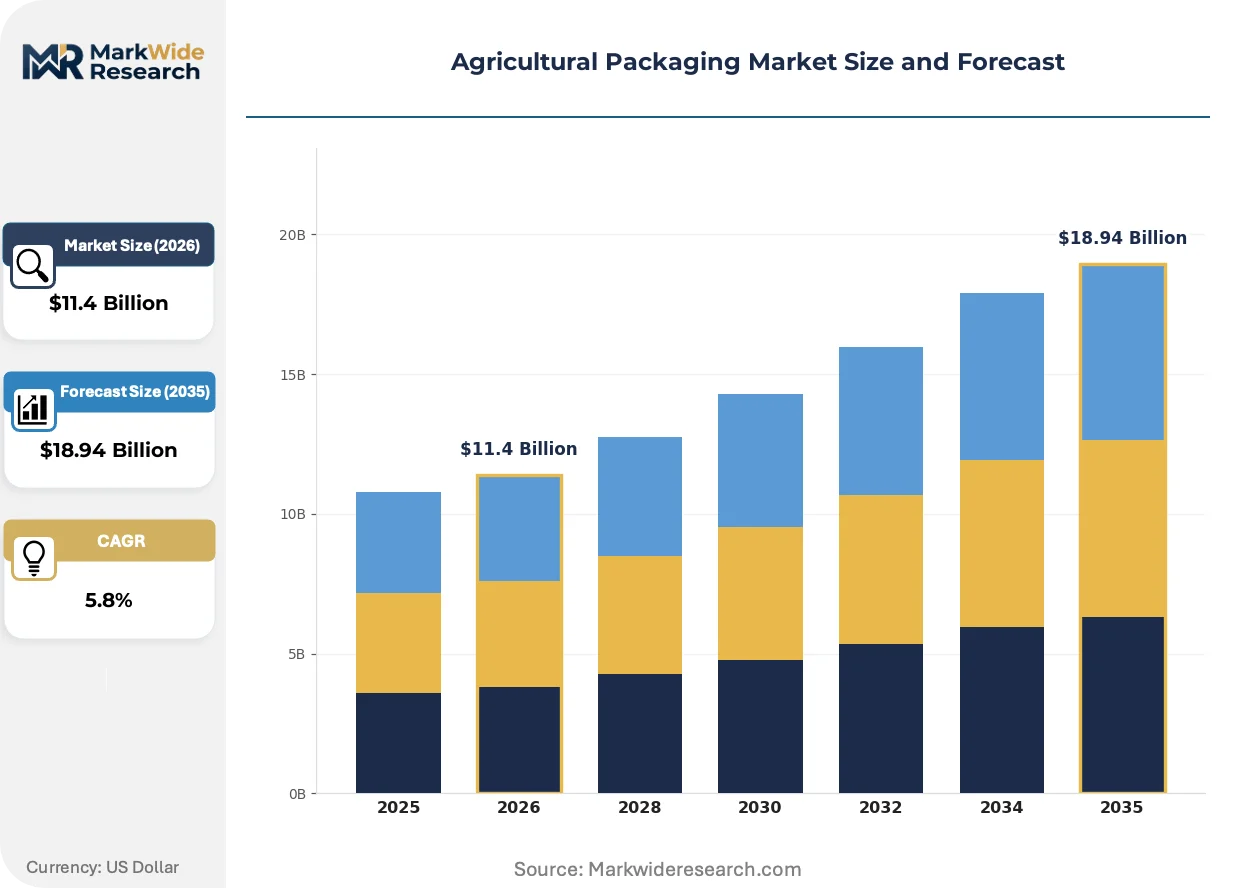
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, Jute, Kraft Paper, Biodegradable Polymers, Burlap Packaging Form: Bags, Sacks, Boxes, Trays, Pallet Wraps, Bulk Containers Crop Type: Grains, Fruits, Vegetables, Seeds, Flowers, Herbs End User: Farmers, Agricultural Cooperatives, Food Processors, Distributors, Exporters, Seed Producers |
| Companies Covered | Amcor plc, Sonoco Products Company, Mondi Group, Berry Global Inc., Smurfit Kappa Group Plc, ProAmpac, Greif Inc., LC Packaging International BV, International Paper Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Packaging Market Strategic Shifts & Innovations
Innovation in the agricultural packaging market is driven by the dual pursuit of enhanced product preservation and environmental sustainability. This is leading to a material science evolution toward solutions that are either functionally circular, like monomaterial plastics, or biologically circular, like compostable biopolymers, without compromising food safety.
Active and intelligent packaging technologies provide real-time data and actively manage the internal environment of a package. Food processors and exporters of high-value fruits are adopting these systems to monitor temperature and atmospheric conditions during transit. This technology is rewriting the value equation for packaging, shifting the focus from a simple cost-per-unit to the total value preserved by preventing spoilage.
The European Union's Packaging and Packaging Waste Regulation (PPWR) is a significant regulatory driver. Its mandates for recycled content and design-for-recyclability are forcing a fundamental reassessment of packaging materials and formats across the industry. Flexible packaging producers exporting to the EU are most affected, prompting a shift away from complex multi-layer laminates toward simpler, monomaterial structures.
A clear shift in procurement patterns is evident among large agricultural cooperatives and retailers. These buyers increasingly favor bulk packaging formats, such as large-capacity sacks and rigid bulk containers, for transporting grains, nuts, and certain produce. This trend disrupts the dominance of smaller, consumer-facing packs in the primary distribution leg, particularly in North American and European domestic supply chains.
Agricultural Packaging Market Segmentation
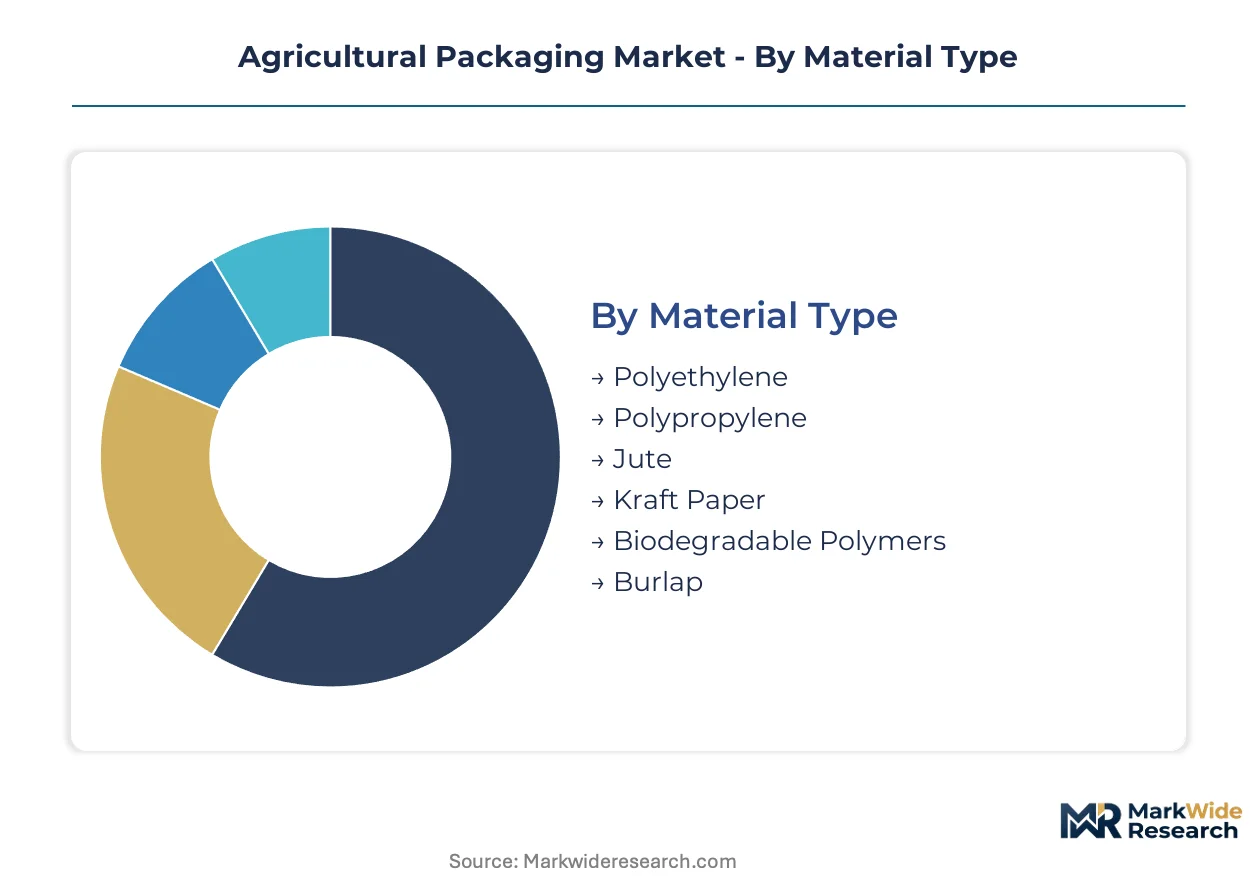
The agricultural packaging market segments by produce characteristics, transit requirements, and evolving regulatory environments. Understanding these divisions helps align material science innovations with specific market demands. This segmentation highlights critical areas for strategic investment.
Material Type:
Material types are differentiated by required barrier properties, cost-effectiveness, and sustainability commitments for agricultural products.
- Polyethylene:This thermoplastic polymer offers excellent moisture barrier properties and strength for flexible films and bags. Its low cost drives demand in bulk grain and produce.
- Biodegradable Polymers:Derived from renewable resources, these materials decompose naturally, reducing environmental impact. Adoption accelerates in fresh produce due to EU Green Deal.
- Polypropylene:High strength-to-weight ratio and chemical resistance make it suitable for woven sacks and rigid seed containers.
- Jute:A natural fiber, jute forms breathable sacks for potatoes and onions, favored in traditional markets.
- Kraft Paper:Durable and recyclable, this paper is used for multi-wall bags for flour, sugar, and animal feed.
- Burlap:This coarse fabric provides breathability for root vegetables and offers protective layering during transit.
Volume sits with Polyethylene; growth tilts toward Biodegradable Polymers.
Packaging Form:
Packaging forms are selected based on physical protection, logistical demands, and end-user handling preferences.
- Bags:Flexible pouches and bags, often polyethylene, provide cost-effective solutions for various produce. Volume is significant in both domestic and export markets.
- Bulk Containers:Large-capacity containers enable efficient transport of grains and commodities, reducing handling costs. Agricultural cooperatives in North America use these.
- Sacks:Woven or multi-wall paper sacks are common for bulk dry goods, offering strength and breathability.
- Boxes:Corrugated or solid board boxes protect delicate fruits and vegetables, often with ventilation for temperature control.
- Trays:Molded plastic or pulp trays individually cradle delicate fruits, preventing bruising and enhancing retail presentation.
- Pallet Wraps:Stretch films secure stacked products on pallets, ensuring stability and protection during shipping.
Efficiency gains drive demand in Bulk Containers, while Trays expand most quickly for high-value produce.
Crop Type:
Crop type dictates packaging requirements based on perishability, physical fragility, and sensitivity to environmental factors.
- Grains:Bulk grains like wheat and rice require robust, moisture-resistant packaging, typically large sacks, to prevent spoilage during storage. Volume efficiency is paramount.
- Fruits:Delicate fruits demand protective packaging preventing bruising, controlling ripening, and extending shelf life, often using modified atmosphere. Export markets require advanced preservation.
- Vegetables:This diverse category needs varied packaging, from mesh bags for root vegetables to specialized films for leafy greens.
- Seeds:Seed packaging maintains viability by protecting against moisture, pests, and physical damage in barrier bags.
- Flowers:Packaging for cut flowers prioritizes physical protection and temperature control, involving sleeves and water elements.
- Herbs:Fresh herbs require packaging maintaining moisture and preventing wilting, typically using clamshells or flow-wrap films.
High-value crops favor specialized solutions for Fruits; bulk commodities drive demand for Grains.
End User:
End users select packaging solutions based on operational scale, processing needs, and compliance obligations across supply chain stages.
- Food Processors:These entities require packaging integrating with automated lines, extending processed food shelf life, and meeting stringent food safety regulations like FDA.
- Exporters:Focused on long-distance transit, exporters demand high-performance packaging with superior barrier properties and durability to meet quality standards in import markets.
- Farmers:Farmers primarily use basic, cost-effective packaging for immediate harvest and local distribution, focusing on initial physical protection.
- Agricultural Cooperatives:These organizations prioritize bulk packaging for efficient collection, storage, and transport of commodities, seeking cost-efficiency.
- Distributors:Distributors require packaging facilitating efficient handling, stacking, and display, balancing cost with ease of use.
- Seed Producers:Packaging for seeds must protect against moisture, pests, and physical damage to maintain germination rates.
Compliance requirements shape decisions for Food Processors, while Agricultural Cooperatives seek cost-effective bulk solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sao Paulo, Brazil, serves as a significant hub for agricultural packaging demand, driven by its expansive export-oriented agriculture. This region's need for high-performance packaging solutions for long-distance transit influences material science innovations. Sustainability mandates and food safety regulations shape packaging development across major agricultural economies.
Brazil
Brazil's vast agricultural exports, particularly of grains and fruits, create substantial demand for advanced packaging solutions. The Ministry of Agriculture, Livestock and Food Supply (MAPA) regulations influence material choices for export-grade produce. The agricultural belts around Mato Grosso and Paraná concentrate demand for bulk containers and modified atmosphere packaging.
India
India's diverse agricultural output and growing processed food sector drive packaging innovation. The Food Safety and Standards Authority of India (FSSAI) sets guidelines for food-contact materials, promoting safe and compliant packaging. Packaging clusters in states like Maharashtra and Gujarat focus on solutions for spices, grains, and fresh produce.
United States
The United States agricultural sector requires specialized packaging for both domestic consumption and international exports. FDA regulations on food-contact materials directly impact packaging design and material selection for food processors. California's Central Valley, a major fruit and vegetable producing region, drives demand for protective trays and active packaging solutions.
Germany
Germany's focus on sustainable practices and high-value food exports influences its agricultural packaging market. The EU's Packaging and Packaging Waste Regulation (PPWR) mandates design-for-recyclability, accelerating the shift to monomaterials. The Rhine-Main region, with its strong logistics infrastructure, supports innovation in advanced packaging for perishable goods.
China
China's large agricultural production and increasing food processing capabilities generate significant packaging demand. Government initiatives supporting food security and environmental protection promote the use of efficient and sustainable packaging. Agricultural hubs in provinces like Shandong and Henan are developing advanced solutions for grains, fruits, and vegetables.
Agricultural Packaging Market Key Industry Players
Premium-margin players sit above commodity-margin players across performance and sustainability offerings. The market exhibits a tiered structure, with global conglomerates offering integrated solutions and specialized firms focusing on niche segments. Strategic archetypes include large-scale diversified packaging providers, sustainable material innovators, and regional specialists. Companies pursue capacity expansion and strategic partnerships to strengthen their market positions.
Within the diversified packaging tier, Amcor plc exemplifies global scale in advanced modified atmosphere packaging for high-value exports. Mondi Group, a European-based provider, represents a strong focus on sustainable paper-based solutions for bulk agricultural goods. Sonoco Products Company, a US-headquartered corporation, anchors the rigid and flexible packaging segment for processed foods.
| Leading Market Players |
|---|
| Amcor plc |
| Sonoco Products Company |
| Mondi Group |
| Berry Global Inc. |
| Smurfit Kappa Group Plc |
| ProAmpac |
| Greif Inc. |
| LC Packaging International BV |
| International Paper Company |
| Others |
Cost & Logistics Intelligence
Specialized polymer processing expertise in East Asian manufacturing hubs drives labor-cost differentials, which in turn influences pricing spreads across advanced packaging tiers. This dynamic creates a distinct separation between high-performance export solutions and basic domestic commodity packaging.
Pricing Analysis
Value-based pricing for advanced packaging anchors on spoilage reduction and shelf-life extension for high-value produce. The dominant pricing model involves contract-based long-term offtake agreements for bulk volumes and per-unit transactional pricing for specialized applications. Price differentiation stems from barrier performance capabilities, such as modified atmosphere packaging, and FDA food-contact certification levels. Input cost volatility, particularly for polymer resins and pulp, creates margin pressure across all segments. Farmers exhibit the highest price sensitivity, while exporters and food processors prioritize performance over cost.
Supply Chain Analysis
Skilled labor availability in packaging manufacturing centers across China, India, and Germany influences production capacity and cost structures. The supply chain draws heavily on polymer resins, pulp, and specialized additives as key raw materials. Commodity price volatility presents a structural risk, impacting material procurement and finished product costs. Distribution runs through direct sales channels to large agricultural cooperatives, food processors, and specialized packaging distributors serving export markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The agricultural packaging market is witnessing a vertical-integration race, as players seek to control advanced material production to secure supply and differentiate offerings.
For Market Incumbents: Anchor existing market share by investing in circular economy infrastructure for flexible films, countering regulatory shifts like the EU PPWR. Develop robust R&D programs focused on high-barrier monomaterials to maintain performance parity with conventional plastics. Expand capacity for bulk containers in key agricultural exporting regions to leverage efficiency demands. Consolidate smaller players to gain material science expertise and market access.
For New Entrants and Emerging Players: The EU's Packaging and Packaging Waste Regulation (PPWR) in Europe opens a window for specialized biopolymer producers to capture market share. Target the underpenetrated market for certified compostable packaging solutions for fresh produce. Differentiate through certification-led marketing and transparent sustainability claims. Focus on niche applications requiring specific barrier properties that conventional biopolymers struggle to meet.
For Investors and Strategic Acquirers: Re-rating potential sits with agile material science startups given the accelerating demand for certified sustainable packaging solutions. Long-term viability hinges on companies demonstrating verifiable progress toward circularity and regulatory compliance. Identify acquisition targets with proprietary biopolymer technologies or established recycling infrastructure. Successful commercialization of high-barrier biopolymers for sensitive produce is a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental footprint, meeting global sustainability mandates from regulators. |
| Long-term Supply Agreement | Secures access to critical biopolymer feedstocks amidst market volatility. |
| Product Launch | Introduces advanced monomaterial films for EU export markets. |
| Strategic Partnership | Collaborates with waste management firms to close packaging recycling loops. |
| Capacity Expansion | Increases production of bulk containers for agricultural cooperatives. |
Research Approach
Independent corroboration across industry reports, company financial statements, and regulatory publications underwrites the qualitative findings and quantitative projections. Primary research involved in-depth interviews with packaging executives, food processors, agricultural cooperative managers, and sustainability officers. Secondary data sources included FDA regulations, EU PPWR documents, and trade association reports, triangulated with bottom-up and top-down analyses.
The forecast framework anchored the projection horizon to historical market performance and established growth trajectories across the analysis window. The model segmented the market by material type, packaging form, crop type, end user, and regional adoption patterns. Compound Annual Growth Rates (CAGRs) were derived from historical trends and future projections, incorporating key forecast inputs such as raw material prices and regulatory compliance costs.
Caveats apply where unforeseen geopolitical events, rapid shifts in raw material supply, or new, disruptive packaging technologies could materially shift the outlook. Forecasts reflect assumptions regarding market stability and technological progression. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging
Edible Oil Packaging Market
Packaging
North America Biodegradable Paper and Plastic Packaging Market
Packaging
Flow Pack Machine Market
Packaging
Multihead Weighers Market
Packaging
Counter Bags Market
Packaging
Sanitizer Sachet Market
Packaging
Gift Packaging Market
Packaging
Plastic Adhesive Tapes Market
Packaging
Tissue Roll Unwinders Market
Packaging
Paper Pouch Market
Packaging
Cork Packaging Market
Packaging
Insulated Drum Covers Market
Packaging
Europe Pharmaceutical Packaging Market
Packaging
Heavy-Duty Paper and Multiwall Shipping Sack Market
Packaging
Egypt Paperboard Packaging Market
Packaging
Processed Meat Packaging Market