
 Heavy-Duty Paper and Multiwall Shipping Sack Market | 2026-2036
Heavy-Duty Paper and Multiwall Shipping Sack Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy-Duty Paper and Multiwall Shipping Sack Market Analysis
Modular valve configurations are decoupling from fixed-format bulk packaging, letting buyers match sack geometry to specific filling equipment and pallet footprints. Mondi Plc leverages its integrated kraft pulp position to sustain margin control across European cement and chemical accounts. ProAmpac Holdings Inc. anchors North American supply through its specialty films-to-sack converting network. Smurfit Kappa differentiates via recycled-content certifications that satisfy retailer sustainability scorecards.
Heavy-duty paper and multiwall shipping sacks are engineered paper containers, typically constructed from multiple plies of extensible kraft paper with grammages exceeding 80 g/m², designed to withstand stacking loads above 25 kg in palletized distribution. Their primary purpose centers on dry bulk containment for construction materials, agricultural commodities, and chemical powders where moisture protection and tear resistance outweigh cost minimization. Valve bags lead in cement and mortar applications where high-speed filling lines dominate, while gusseted configurations capture agricultural seed and feed segments requiring stable pallet geometry. Barrier paper grades command premium positioning in hygroscopic chemical markets where polyethylene laminations face regulatory pressure.
The EU Packaging and Packaging Waste Regulation and FDA food-contact substance notifications shape material migration limits and recyclability claims across European and North American supply chains. India's BIS certification mandates for paper sacks used in food grain distribution enforce ply strength and print-ink safety standards that filter smaller converters from government tender participation. Stakeholders must monitor how extended producer responsibility fee structures in the EU and pending state-level packaging legislation in the US redirect converter capital toward recyclable mono-material barrier technologies.
Market Dynamics
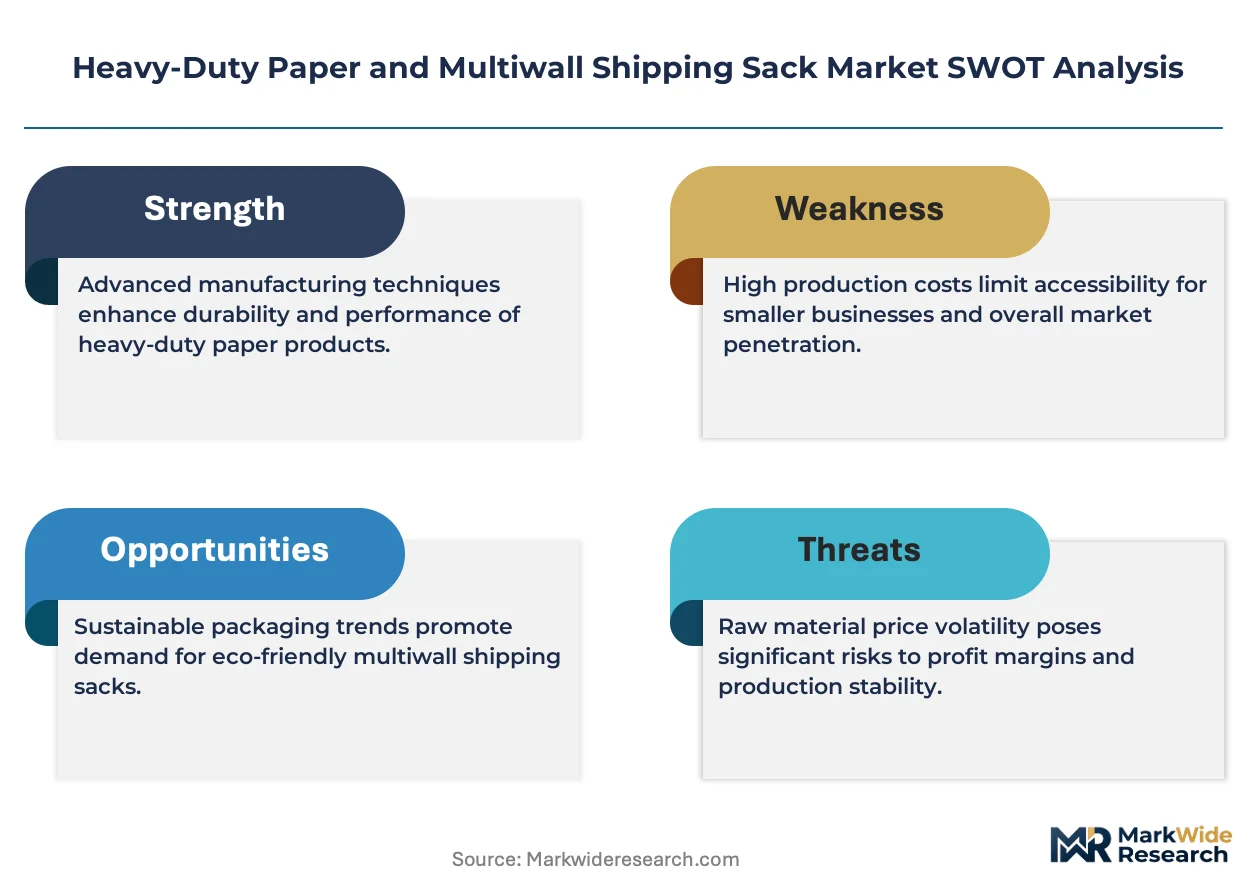
The EU Packaging and Packaging Waste Regulation is forcing converters to abandon polyethylene laminations in favor of recyclable mono-material kraft constructions, compressing legacy margin structures while opening premium positioning for barrier-grade paper specialists.
Growth Catalysts
- Infrastructure investment corridors:India's National Infrastructure Pipeline directs cement demand toward valve sacks for last-mile distribution in tier-2 and tier-3 cities. BIS certification requirements filter out informal suppliers, concentrating volume with certified converters.
- REACH compliance migration:Chemical manufacturers across the EU are substituting plastic bulk containers with multiwall sacks to satisfy extended producer responsibility fee structures and recyclability mandates.
- Agricultural mechanization:Automated grain handling systems in Brazil and Argentina specify gusseted sack geometries compatible with robotic palletizing, displacing woven polypropylene in export terminals.
Market Restraints
- Pulp cost volatility:Extensible kraft fiber prices track Scandinavian softwood supply disruptions, squeezing converter margins during energy price spikes.
- Barrier performance ceiling:Uncoated natural kraft cannot match aluminum-laminated flexible packaging for oxygen transmission rates, limiting penetration in oxygen-sensitive chemical markets.
- Substitution by FIBCs:Flexible intermediate bulk containers capture palletized cement shipments above 500 kg, eroding multiwall sack volume in bulk terminal-to-batch-plant logistics.
Strategic Opportunities
- Mono-material barrier films:Water-based coatings and bio-wax laminations are integrating with extensible kraft to create heat-sealable, recyclable constructions that qualify for EU Green Deal procurement preferences.
- Specialty chemical verticals:Hygroscopic fertilizer and polymer additive producers in Germany and the Netherlands seek moisture-vapor-transmission rates below 5 g/m²/day without plastic content.
- Digital printing adaptation:HP Indigo and Xeikon systems enable short-run customized valve sacks for construction chemical brands requiring batch-traceable QR codes and anti-counterfeit features.
Industry Challenges
- Skilled operator scarcity:Multiwall tube forming and bottomer machine operation requires apprenticeship-level training unavailable in regions with aging paper industry workforces.
- Certification timeline compression:FDA food-contact substance notifications and EU 10/2011 migration testing extend new product qualification cycles to 18-24 months, delaying barrier coating launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy-Duty Paper and Multiwall Shipping Sack Market |
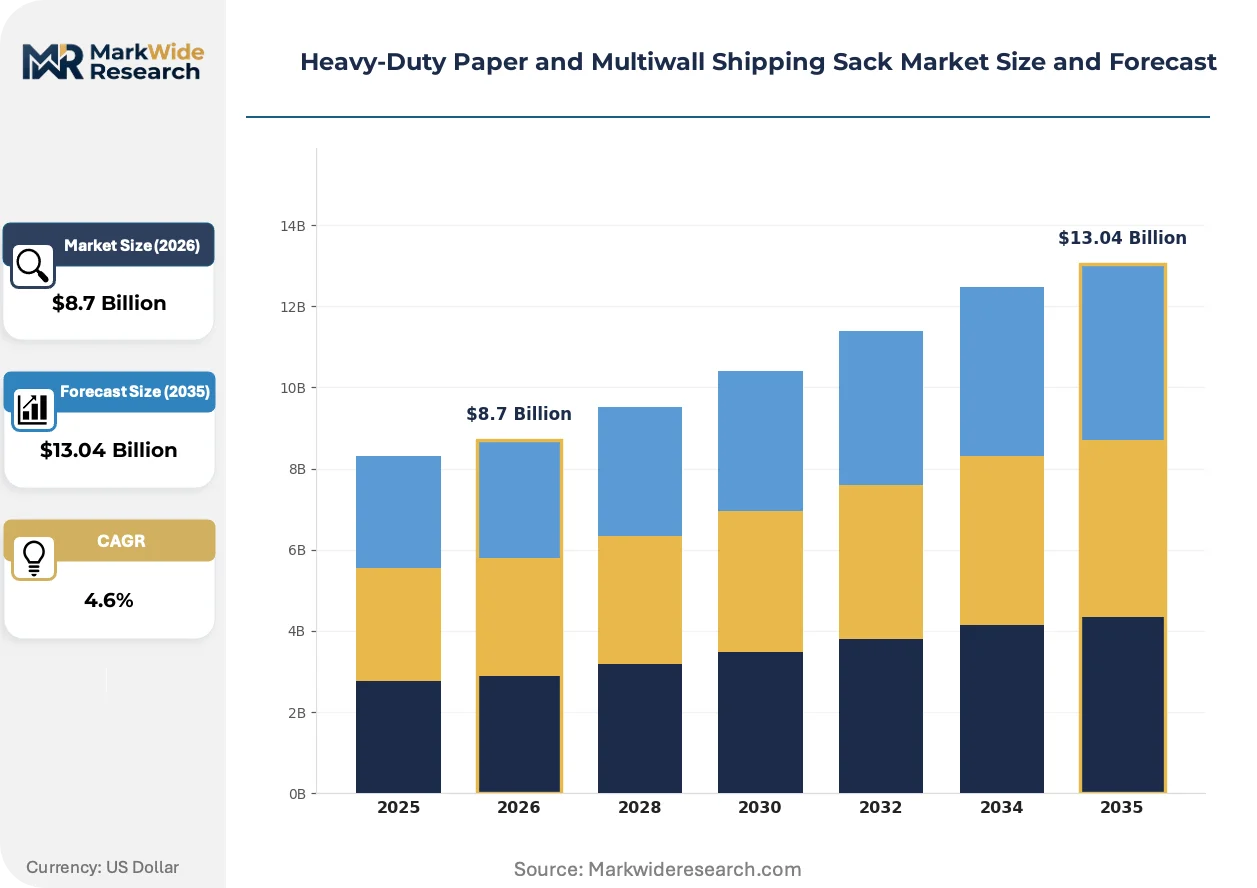
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Gusseted Bags, Valve Bags, Paper Sacks End Use Industry: Agriculture, Food & Beverage, Construction, Chemicals Material: Recycled Paper, Virgin Paper, Kraft Paper, Barrier Paper Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Hood Packaging Corporation, Endpak Packaging Inc., Mondi Plc, Northeast Packaging Company, Global-Pak, Inc., ProAmpac Holdings Inc., Shanghai Ailu package CO.,Ltd, Gelpac, Smurfit Kappa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy-Duty Paper and Multiwall Shipping Sack Market Emerging Trajectories
Active reformulation of barrier layers and digital workflow integration are compressing the traditional trade-off between moisture protection and end-of-life recyclability, forcing equipment and chemistry suppliers to coordinate on mono-material validation protocols.
High-barrier water-based coatings incorporating bio-derived wax emulsions and nanocellulose dispersions are integrating into 3-ply kraft constructions for hygroscopic chemical applications. German and Dutch specialty chemical distributors are specifying these constructions for polymer additive shipments to satisfy retailer sustainability scorecards. The technology is integrating moisture protection performance comparable to polyethylene laminations while maintaining repulpability certification under PTS-RH 021 standards.
The EU Packaging and Packaging Waste Regulation mandates 70% recyclability by weight and modulated extended producer responsibility fees based on recyclability performance ratings. Multiwall sack converters are accelerating elimination of aluminum oxide metallized layers and solvent-based adhesives to avoid penalty fee tiers. Cement and mortar packaging across France, Germany, and Poland is transitioning to certified recyclable mono-material constructions ahead of 2030 enforcement deadlines.
Construction chemical procurement teams are consolidating supplier panels and demanding integrated design-to-delivery partnerships covering sack geometry optimization, pallet footprint engineering, and filling line integration support. Regional distributors in India and Southeast Asia are displacing spot-market sack purchasing with multi-year framework agreements tied to volume commitments and joint specification development. This consolidation is most visible in India's western and southern states where infrastructure project bundling concentrates demand with three to four certified converters per region.
Heavy-Duty Paper and Multiwall Shipping Sack Market Segmentation
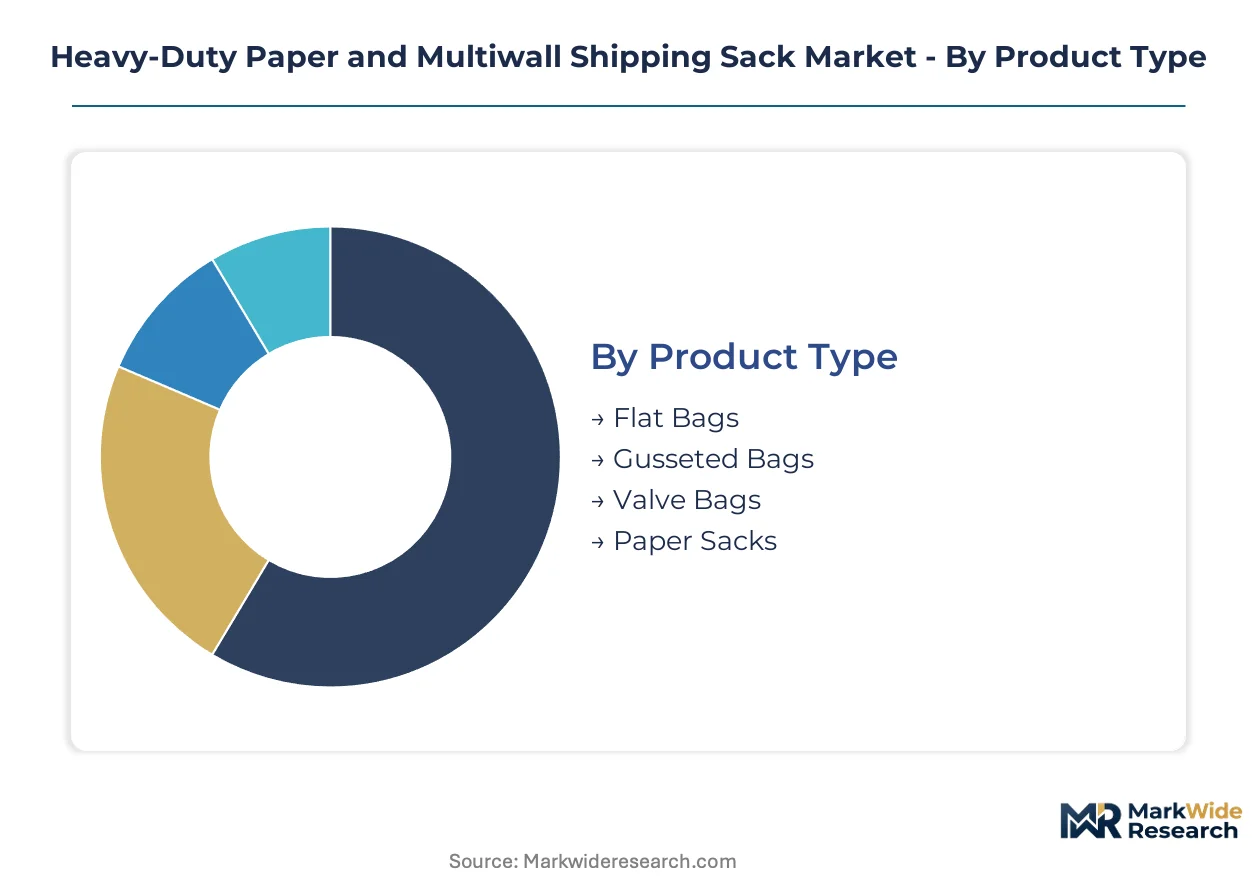
Segmentation in heavy-duty paper and multiwall shipping sacks reveals how construction specifications, regulatory compliance tiers, and distribution logistics create distinct margin pools. Buyers select configurations based on filling equipment compatibility, pallet stability requirements, and end-of-life recyclability mandates.
Product Type:
Valve bags dominate volume shipments for high-speed cement lines, while gusseted and flat configurations serve specialty applications where pallet geometry or manual handling prevails.
- Valve Bags:Self-sealing constructions with integrated filling valves enable 3,000+ bags per hour on rotary packers. Cement manufacturers in India specify these for National Infrastructure Pipeline projects where BIS certification filters informal suppliers.
- Gusseted Bags:Side-folded designs create stable rectangular profiles for robotic palletizing in Brazilian and Argentine grain export terminals. Agricultural mechanization is displacing woven polypropylene with these paper alternatives.
- Flat Bags:Simple open-mouth constructions serve manual filling operations in small-scale chemical packaging. Limited automation compatibility constrains volume expansion.
- Paper Sacks:Generic category capturing non-valve, non-gusseted specialty formats for artisanal food and feed applications. Niche positioning limits economies of scale.
Mature deployment sits with valve bags in cement infrastructure. Newer deployment is concentrated in gusseted bags for automated grain handling.
End Use Industry:
Construction and agriculture anchor demand volume, while chemicals and food applications command premium pricing for barrier performance and regulatory compliance.
- Construction:Cement, mortar, and construction chemical packaging consumes multiwall sacks for last-mile distribution from bulk terminals. India's tier-2 and tier-3 infrastructure corridors are expanding valve bag specifications.
- Agriculture:Seed, feed, and grain handling requires moisture-resistant constructions compatible with automated handling. Mechanized terminals in South America specify gusseted geometries for robotic palletizing.
- Chemicals:Hygroscopic fertilizer and polymer additive producers in Germany and the Netherlands seek moisture-vapor-transmission rates below 5 g/m²/day. REACH compliance is substituting plastic bulk containers with certified recyclable sacks.
- Food & Beverage:FDA food-contact substance notifications and EU 10/2011 migration testing extend qualification cycles to 18-24 months. BIS certification in India enforces ply strength and print-ink safety for government grain tenders.
Volume concentration centers on construction. Margin expansion is climbing the fastest in chemicals and food-contact applications.
Material:
Virgin and recycled kraft papers serve cost-sensitive bulk applications, while barrier-grade formulations capture regulatory-driven substitution from plastic laminations.
- Kraft Paper:Extensible kraft fiber with grammages exceeding 80 g/m² provides tear resistance for 25 kg stacking loads. Scandinavian softwood supply disruptions create pulp cost volatility for converters.
- Barrier Paper:Water-based coatings and bio-wax laminations integrate with kraft for heat-sealable, recyclable constructions. EU Packaging and Packaging Waste Regulation mandates are accelerating elimination of polyethylene and aluminum oxide layers.
- Virgin Paper:Unbleached softwood pulp delivers consistent strength for high-speed filling lines. Energy price spikes in Nordic regions squeeze converter margins.
- Recycled Paper:Post-consumer fiber content satisfies retailer sustainability scorecards and EU Green Deal procurement preferences. Smurfit Kappa differentiates via recycled-content certifications.
Standard-grade deployment dominates virgin and recycled kraft. Premium positioning is expanding most quickly in barrier paper for hygroscopic chemical markets.
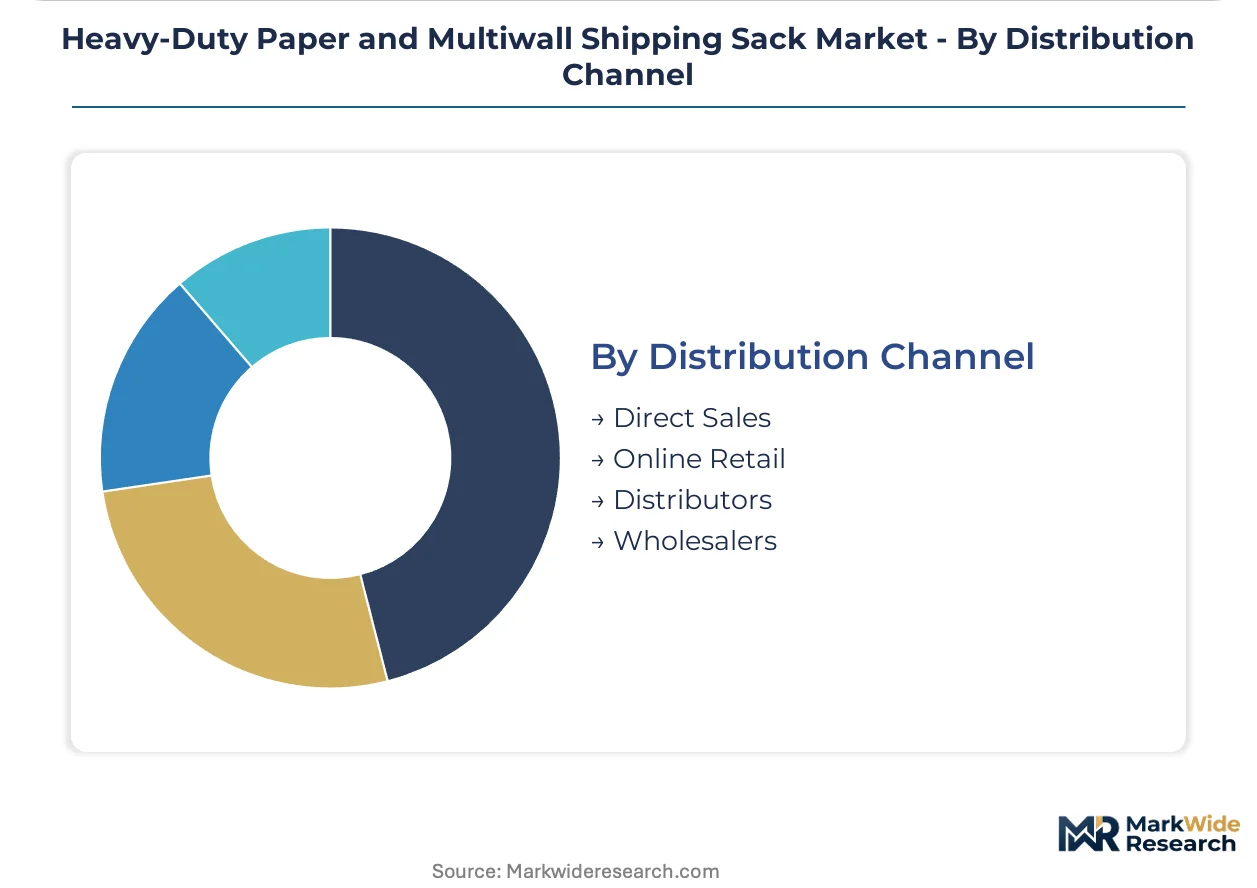
Distribution Channel:
Direct sales and distributor networks serve distinct buyer profiles, with framework agreements displacing spot-market purchasing in concentrated demand regions.
- Distributors:Regional stockists provide technical specification support and just-in-time delivery for mid-tier cement and chemical accounts. India's western and southern states concentrate demand with three to four certified converters per region.
- Direct Sales:Integrated design-to-delivery partnerships cover sack geometry optimization, pallet footprint engineering, and filling line integration. Construction chemical procurement teams are consolidating supplier panels.
- Wholesalers:Bulk aggregators serve price-sensitive agricultural buyers with standardized specifications. Limited technical support capability constrains premium penetration.
- Online Retail:Digital platforms enable short-run customized valve sacks with batch-traceable QR codes. HP Indigo and Xeikon systems support anti-counterfeit features for construction chemical brands.
Established volume flows through distributors and direct sales. Digital channel adoption is gaining share fastest in customized short-run applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scandinavian pulp mills supply extensible kraft fiber to converters worldwide, while India and Brazil consume the majority of finished valve and gusseted sacks for cement and grain handling. This production-consumption divide shapes regional investment patterns and certification requirements.
India
The National Infrastructure Pipeline directs cement procurement toward certified valve sack suppliers for tier-2 and tier-3 city distribution. BIS certification mandates for food grain packaging filter informal converters from government tenders. Western and southern states concentrate demand with framework agreements bundling infrastructure projects through three to four certified converters per region.
Germany
Specialty chemical distributors in the Rhine-Ruhr and Bavarian industrial corridors specify moisture-vapor-transmission rates below 5 g/m²/day for polymer additive shipments. REACH compliance and extended producer responsibility fee structures under the EU Packaging and Packaging Waste Regulation substitute plastic bulk containers with recyclable multiwall constructions. Hamburg and Bremen port clusters handle barrier-grade sack exports to Benelux chemical accounts.
United States
Construction chemical procurement teams in Texas and the Southeast consolidate supplier panels around integrated design-to-delivery partnerships. FDA food-contact substance notifications govern grain and feed packaging specifications across Midwest agricultural terminals. Chicago and Minneapolis distribution hubs coordinate just-in-time valve sack delivery for high-speed cement filling lines.
Brazil
Automated grain handling systems in São Paulo and Paraná state export terminals specify gusseted sack geometries compatible with robotic palletizing. Agricultural mechanization displaces woven polypropylene with paper alternatives for soybean and corn shipments. Santos port infrastructure investments expand multiwall sack specification for containerized bulk exports.
Netherlands
Rotterdam chemical distributors demand mono-material barrier constructions qualifying for EU Green Deal procurement preferences. Water-based coating validation protocols coordinate between German equipment suppliers and Dutch converters. Eindhoven and Amsterdam logistics clusters consolidate specialty chemical sack sourcing for German and Belgian polymer additive producers.
Heavy-Duty Paper and Multiwall Shipping Sack Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Integrated paper producers leverage captive pulp supply for margin control, while independent converters compete on customization speed and regional logistics. Three archetypes dominate: vertically integrated kraft producers, specialty films-to-sack converters, and recycled-content certification specialists. Capacity expansion and strategic partnerships constitute the primary competitive moves, with framework agreement bundling displacing spot-market purchasing in concentrated demand regions.
Among European-based integrated producers, Mondi Plc exemplifies the captive pulp archetype through its kraft manufacturing position. ProAmpac Holdings Inc. and Smurfit Kappa occupy distinct competitive positions within North American and European supply networks respectively. These three entities represent the spectrum from upstream fiber control to recycled-content certification differentiation, anchoring industry-level competitive dynamics without dictating specific strategic outcomes for any single firm.
| Leading Market Players |
|---|
| Hood Packaging Corporation |
| Endpak Packaging Inc. |
| Mondi Plc |
| Northeast Packaging Company |
| Global-Pak, Inc. |
| ProAmpac Holdings Inc. |
| Shanghai Ailu package CO.,Ltd |
| Gelpac |
| Smurfit Kappa |
| Others |
Supply Flow & Price Mechanics
Skilled tube-forming machine operators in Germany and the Nordic region command wage premiums that widen spreads between premium barrier-grade sacks and standard kraft constructions. Labor-cost differentials between Western European certified converters and emerging-market competitors feed directly into three-tier pricing stratification across global supply networks.
Pricing Analysis
Margin tightening in standard-grade kraft traces to pulp cost volatility and energy price spikes in Scandinavian softwood regions. Three-tier pricing structure across premium, standard, and economy levels separates barrier-certified chemical sacks from construction-grade valve bags and generic agricultural formats. Certification tier and volume scale drive price differentiation, with BIS-compliant Indian converters capturing premiums over informal suppliers. Cost compression in economy-grade recycled kraft accelerates because of spot-market pulp purchasing and wholesaler channel dominance. Small-scale chemical packagers exhibit highest price sensitivity; German specialty chemical distributors show lowest, prioritizing moisture-vapor-transmission performance over unit cost.
Supply Chain Analysis
Extensible kraft fiber supply rests on Scandinavian softwood pulp mills in Sweden, Finland, and Norway, with Brazilian eucalyptus pulp emerging as secondary source. Raw material dependencies center on unbleached softwood pulp, water-based barrier coatings, and bio-wax emulsions. Single-source vulnerability concentrates in Nordic energy-intensive pulp production exposed to natural gas price volatility. Distribution runs through direct sales partnerships for construction chemical accounts and regional distributor networks for mid-tier cement and agricultural buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The heavy-duty paper and multiwall shipping sack sector sits in a materials-transition phase, with water-based barrier coatings and nanocellulose dispersions displacing polyethylene laminations under EU regulatory pressure.
For Market Incumbents: Anchor market position through captive kraft pulp supply integration and accelerated mono-material barrier certification. Mondi Plc's integrated fiber position demonstrates margin defense against pulp volatility. Smurfit Kappa's recycled-content certifications provide defensive moat against sustainability-driven procurement consolidation. Incumbents must prioritize REACH-compliant coating R&D to preempt regulatory exclusion. For New Entrants and Emerging Players: E-commerce-enabled short-run customization offers white-space entry around digital-printed valve sacks with batch-traceable QR codes. India's western and southern states present most penetrable geography, with infrastructure project bundling concentrating demand and BIS certification filtering legacy informal suppliers. Construction chemical brands seeking anti-counterfeit features provide specific go-to-market angle through HP Indigo system partnerships. For Investors and Strategic Acquirers: Re-rating potential sits with barrier-grade paper specialists given EU Packaging and Packaging Waste Regulation enforcement tightening. Long-term viability favors converters with validated mono-material constructions and direct sales integration capabilities. Acquisition target archetype: mid-scale European converters with water-based coating validation and established chemical distributor relationships. Watch EU extended producer responsibility fee tier announcements as inflection signal for capital reallocation toward recyclable technologies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Pulp Supply | Captive fiber production insulates Mondi Plc from Scandinavian energy price volatility. |
| Mono-Material Barrier Certification | EU Green Deal procurement preferences reward converters eliminating polyethylene laminations. |
| Digital Printing System Deployment | HP Indigo and Xeikon installations enable short-run customized valve sacks with anti-counterfeit QR codes. |
| Framework Agreement Bundling | Multi-year volume commitments with Indian infrastructure projects displace spot-market purchasing. |
| Recycled-Content Certification Investment | Smurfit Kappa's certified post-consumer fiber satisfies retailer sustainability scorecards. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with multiwall sack plant managers, cement procurement leads at infrastructure developers, chemical distributor technical directors, and agricultural terminal operations heads combined with secondary validation. Bottom-up and top-down triangulation cross-checked converter capacity announcements, BIS certification registries, and EU ECHA substance notifications.
Granularity-level modeling operated at product-type, end-use industry, material grade, and regional production hub dimensions across the analysis window. CAGRs derived from volume shipment trajectories by segment, with explicit modeling of India's National Infrastructure Pipeline cement demand, EU REACH compliance substitution effects, and Brazilian agricultural mechanization adoption curves.
The model holds under sustained EU regulatory enforcement and stable pulp supply from Nordic regions; deviation in energy price spikes or trade restriction implementation would shift volume and value outputs. Forecasts reflect documented assumptions about certification timeline compression and barrier coating validation protocols. A small set of named triggers—EU extended producer responsibility fee tier adjustments, Indian BIS enforcement intensity, and Scandinavian pulp mill energy cost volatility—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy Duty Packaging
Europe High Density Polyethylene Jerrycan Market
Heavy Duty Packaging
Hazmat Packaging Market
Heavy Duty Packaging
Hazardous Goods Packaging Market
Heavy Duty Packaging
High-Stress PCR HDPE Detergent Bottles Market
Heavy Duty Packaging
Heavy-Duty Corrugated Boxes Market
Heavy Duty Packaging
Global Heavy Duty Bags and Sacks Market
Heavy Duty Packaging
Heavy Duty Bins Market
Heavy Duty Packaging
Heavy Duty Corrugated Packaging Market
Heavy Duty Packaging
High Impact Corrugated Boxes Market
Heavy Duty Packaging
Large Blow Molded Products Market
Heavy Duty Packaging
High-Density Packaging Market
Heavy Duty Packaging
Heavy Duty Paper Tags Market