
 Sanitizer Sachet Market | 2026-2036
Sanitizer Sachet Market Size, Share, and Industry Trends Forecast 2026-2036
Sanitizer Sachet Market Analytics
Asset-light contract manufacturing is rewriting competitive entry barriers in sanitizer sachet production, allowing regional brands to scale without captive filling lines. Unilever leverages its South Asian distribution density to push single-serve packs through kirana stores and rural pharmacies. GOJO Industries specializes in institutional-grade alcohol sachets for healthcare procurement channels. Kimberly-Clark anchors North American supply through its hygiene contract manufacturing network.
Sanitizer sachets are single-use flexible pouches, typically 1–3 ml, containing alcohol-based or antimicrobial gel/liquid formulations sealed in multi-layer laminated film with tear-notch access; they serve portable hygiene needs where bottle carrying proves impractical. Alcohol-based formulations dominate volume due to established efficacy against enveloped viruses, though moisturizing variants command higher unit margins in travel and premium consumer segments. Eco-friendly packaging, including biodegradable films and reduced-plastic laminates, represents the fastest-growing structural pocket as procurement policies at institutional buyers harden around sustainability criteria. The online distribution channel extends reach into subscription and bulk-direct models that bypass traditional retail slotting fees.
FDA topical antiseptic monograph revisions shape alcohol concentration thresholds and allowable efficacy claims in the United States, while India's BIS packaging standards govern seal integrity and labeling for consumer hygiene products. The EU REACH framework and F-Gas Regulation indirectly pressure film laminate suppliers to eliminate fluorinated barrier chemistries from sachet substrates. Stakeholders must monitor how fragmented national labeling rules for alcohol content and child-safety warnings affect cross-border SKU rationalization and regional production siting decisions.
Market Dynamics
Asset-light contract manufacturing is compressing capital barriers for regional entrants, while FDA monograph tightening on alcohol concentration claims forces reformulation cycles that favor technically sophisticated compounders over commodity packagers.
Growth Catalysts
- India's rural pharmacy penetration:Low unit pricing and kirana store density drive volume uptake of sachet formats over bottled alternatives in tier-3 and tier-4 towns.
- REACH and F-Gas Regulation pressure:EU fluorinated chemistry elimination mandates accelerate biodegradable film adoption, creating first-mover advantage for laminate suppliers with certified compostable substrates.
- Airline amenity kit procurement:Post-pandemic hygiene protocols institutionalize single-serve sanitizer inclusion in premium and economy cabin service, locking in annual volume commitments.
Market Restraints
- Alcohol input cost volatility:Ethanol and isopropyl alcohol pricing tied to agricultural feedstock and energy markets squeezes margin predictability for fixed-price institutional contracts.
- Film laminate supply concentration:Multi-layer barrier film production clusters in China and South Korea, exposing converters to shipping cost spikes and currency fluctuation.
- FDA label claim friction:Evolving topical antiseptic monograph requirements on efficacy statements force SKU-specific regulatory reviews that delay new product launches.
Strategic Opportunities
- Subscription direct-to-consumer channels:Online bulk-direct models bypass traditional retail slotting fees and capture recurring revenue from hygiene-conscious households.
- Healthcare procurement convergence:Hospital systems consolidating vendor lists create entry points for institutional-grade alcohol sachet suppliers with documented lot traceability.
- Moisturizing variant premiumization:Aloe and vitamin-E enriched formulations command higher unit margins in travel retail and corporate gifting segments.
Industry Challenges
- Child-resistant packaging certification timelines:BIS seal-integrity testing and ISO 8317 compliance for alcohol-containing sachets extend product development cycles by 4-6 months.
- Laminate-to-filling line integration complexity:Converters retrofitting legacy form-fill-seal equipment for biodegradable films face yield loss and speed degradation during qualification runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanitizer Sachet Market |
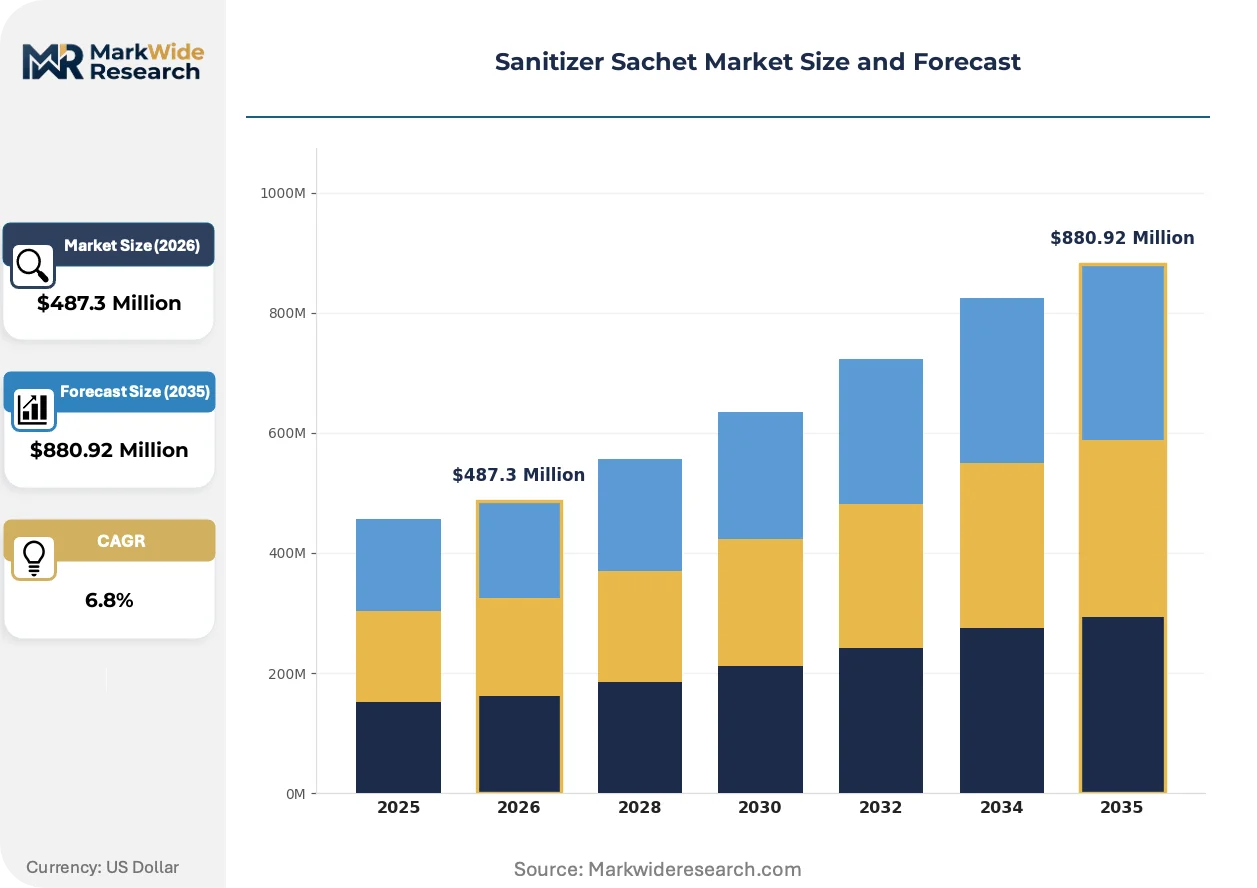
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alcohol-Based, Non-Alcoholic, Antimicrobial, Moisturizing Packaging Type: Single-Serve, Multi-Pack, Eco-Friendly, Resealable End Use: Consumer, Institutional, Healthcare, Travel Distribution Channel: Online, Supermarkets, Pharmacies, Convenience Stores |
| Companies Covered | Unilever, Procter & Gamble, Reckitt Benckiser, Johnson & Johnson, 3M, Kimberly-Clark, GOJO Industries, Colgate-Palmolive, SC Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanitizer Sachet Market Evolving Landscape
Formulation chemistry and substrate engineering are converging to redefine portability, efficacy communication, and end-of-life disposal expectations across consumer and institutional segments.
Water-soluble film technology is virtualizing the sachet-to-skin application boundary. Polyvinyl alcohol-based pouches dissolve upon moisture contact, eliminating tear-notches and plastic residue. Premium hospitality chains and corporate travel programs are piloting these units for amenity kits. This substrate shift is virtualizing the distinction between packaging and product, compressing regulatory classification debates around what constitutes a disposable article.
India's BIS packaging standards are tightening seal-strength and label-legibility requirements for consumer hygiene products. The 2024 amendments mandate batch coding visibility and alcohol percentage disclosure in regional languages. Domestic contract manufacturers are requalifying printing and lamination processes. Small-format converters without in-house testing laboratories face outsourcing costs that favor scaled regional players.
Bulk-direct institutional procurement is displacing distributor-mediated replenishment in airline and hospitality supply chains. Procurement officers negotiate annual volume contracts with manufacturers, bypassing wholesale intermediaries. This channel compression concentrates price negotiation leverage with buyers possessing scale. North American and Middle Eastern hospitality groups lead this shift, driven by sustainability scorecard requirements that demand supplier transparency.
Sanitizer Sachet Market Segmentation
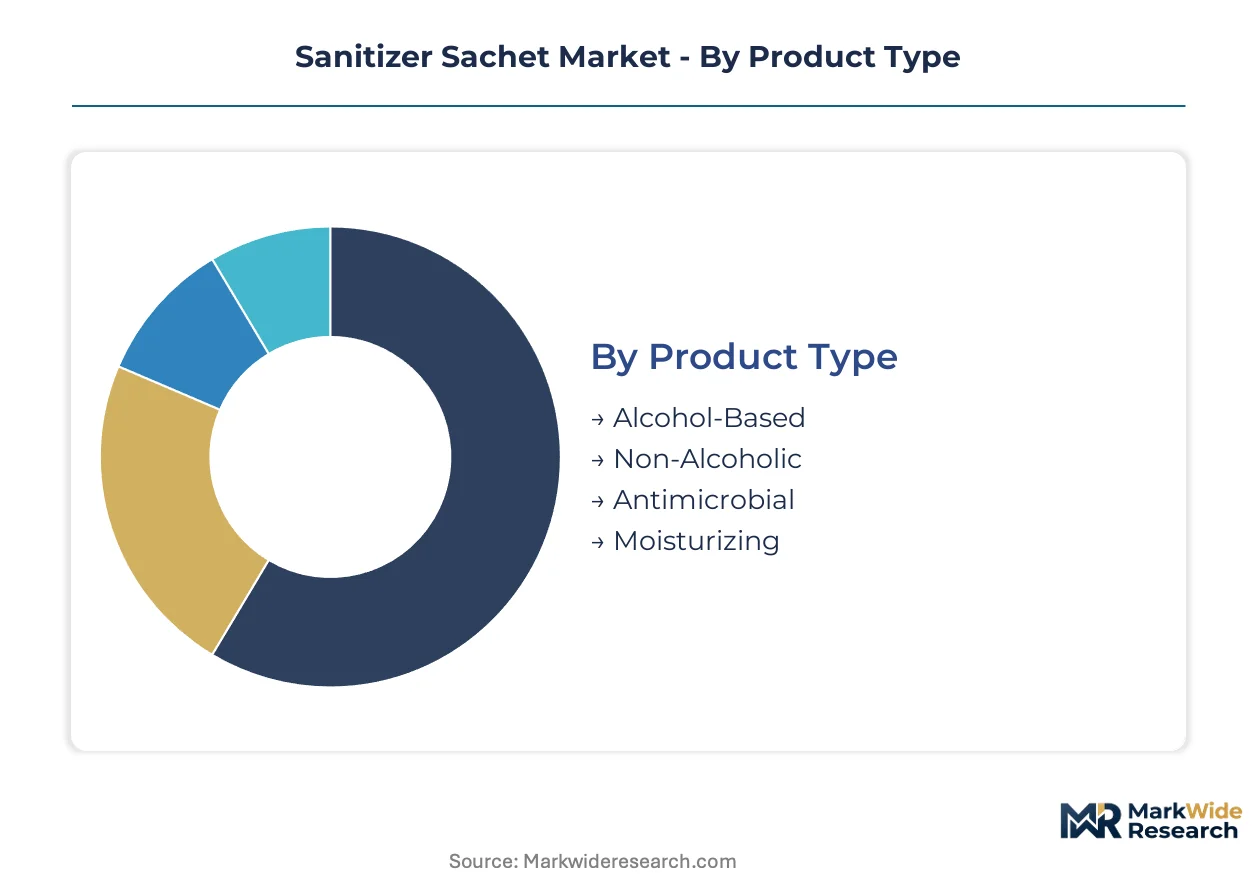
Sanitizer sachet segmentation reveals distinct velocity profiles across product chemistry, packaging formats, and channel access. Each dimension carries different margin structures and regulatory exposure that shape procurement priorities for institutional buyers versus consumer households.
Product Type:
Alcohol-based formulations turn inventory fastest through pharmacy and travel retail channels, while moisturizing variants sit longer on shelves but command premium reorder cycles.
- Alcohol-Based:Ethanol or isopropyl alcohol formulations at 60-70% concentration deliver rapid virucidal action against enveloped pathogens. Hospital procurement in India and airline amenity programs drive bulk volume commitments with quarterly replenishment schedules. FDA monograph compliance on concentration claims adds qualification overhead that slows new entrant speed-to-shelf.
- Moisturizing:Aloe vera, glycerin, and vitamin-E enriched gels reduce dermal irritation for frequent-use environments. Corporate gifting programs and premium hospitality chains in Dubai and Singapore absorb supply at price points 40-60% above standard alcohol sachets, though order cycles stretch to annual contracting.
- Non-Alcoholic:Benzalkonium chloride and quaternary ammonium alternatives serve religious and institutional settings with alcohol restrictions.
- Antimicrobial:Persistent-acting formulations target food-service and childcare facilities requiring residual protection between applications.
Alcohol-based sachets anchor the volume base while moisturizing variants gain share at the steepest rate.
Packaging Type:
Cost tiers separate commodity converters from sustainability-certified suppliers, with laminate substrate choice determining access to EU and North American institutional procurement.
- Eco-Friendly:Biodegradable films and compostable laminates certified to EN 13432 or ASTM D6400 standards unlock hospitality and airline contracts with mandatory sustainability scorecards. European REACH fluorinated chemistry bans accelerate substrate switching costs that favor scaled laminate suppliers with in-house compostable film lines.
- Single-Serve:Standard 1-3 ml tear-notch pouches in multi-layer PET/aluminum/PE construction dominate pharmacy and convenience store distribution. Indian kirana stores and rural dispensaries absorb billions of units annually at sub-rupee price points, with weekly replenishment cycles from regional contract manufacturers.
- Multi-Pack:Aggregated 10-20 unit flow-wrap configurations reduce per-unit handling cost for household stockpiling.
- Resealable:Zip-lock and adhesive-strip variants target multi-day travel and fieldwork applications with partial-use retention.
Single-serve sachets capture the highest absolute unit volume while eco-friendly formats expand most quickly as procurement policies harden.
End Use:
Application context dictates performance certification requirements, with healthcare and travel segments imposing the most stringent documentation burdens.
- Healthcare:Institutional-grade alcohol sachets require lot traceability, sterility validation, and documented supply chain custody for hospital system vendor consolidation programs. North American health networks and Saudi hospital procurement authorities now mandate ISO 13485 manufacturing certification as a baseline qualification.
- Travel:Airline amenity kit inclusion and hotel guest room placement demand compact formats with multilingual labeling and TSA-compliant liquid volumes. Emirates, Qatar Airways, and Singapore Airlines lock in annual volume commitments with direct manufacturer contracts, bypassing wholesale intermediaries.
- Consumer:Individual household purchase through retail and online channels prioritizes unit affordability over certification depth.
- Institutional:Schools, offices, and food-service operations balance cost control with bulk dispensing compatibility.
Healthcare and travel segments impose the steepest compliance gradients while consumer demand delivers the broadest geographic dispersion.
Distribution Channel:
Customer type separates recurring subscription revenue from transactional retail purchase, with channel choice determining working capital intensity and price transparency.
- Online:Direct-to-consumer subscription models and bulk institutional procurement bypass slotting fees and distributor margins. Amazon, Flipkart, and specialized hygiene subscription services capture recurring household revenue with auto-replenishment algorithms, while manufacturer-direct portals serve airline and hospitality procurement with annual contract pricing.
- Pharmacies:Licensed dispensaries in India, Brazil, and Nigeria provide rural penetration with regulatory credibility for alcohol-based formulations. CDSCO and ANVISA registration requirements create channel gatekeeping that filters unqualified suppliers.
- Supermarkets:Mass retail placement demands promotional funding and shelf-space negotiation.
- Convenience Stores:Impulse-purchase positioning at transit hubs and fuel stations captures unplanned hygiene needs.
Pharmacies anchor volume in emerging markets while online channels climb fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airline procurement officers in Dubai and Singapore negotiate annual volume contracts directly with manufacturers, while rural pharmacy chains in India absorb billions of units through weekly replenishment cycles from regional contract manufacturers.
India
Kirana store density in tier-3 and tier-4 towns drives volume uptake of sachet formats over bottled alternatives, with weekly replenishment cycles dominating distribution. BIS packaging standards mandate batch coding visibility and alcohol percentage disclosure in regional languages, forcing domestic contract manufacturers to requalify printing processes. Ahmedabad and Surat host concentrated clusters of small-format converters retrofitting legacy form-fill-seal equipment for biodegradable films.
United States
Hospital systems consolidating vendor lists create procurement convergence for institutional-grade alcohol sachets with documented lot traceability and ISO 13485 manufacturing certification. FDA topical antiseptic monograph revisions tighten alcohol concentration claims and allowable efficacy statements, forcing SKU-specific regulatory reviews. Chicago and Cincinnati anchor North American supply through hygiene contract manufacturing networks serving healthcare and hospitality channels.
Germany
REACH framework and F-Gas Regulation pressure accelerate biodegradable film adoption among laminate suppliers with certified compostable substrates, creating first-mover advantage for sustainability-certified converters. EU fluorinated chemistry elimination mandates reshape substrate sourcing decisions for sachet producers serving hospitality procurement with mandatory sustainability scorecards. Düsseldorf and Hamburg concentrate multi-layer barrier film trading and converter relationships.
United Arab Emirates
Emirates and Qatar Airways lock in annual volume commitments for amenity kit inclusion, bypassing wholesale intermediaries through direct manufacturer contracts with multilingual labeling requirements. MOHAP procurement policies for hospital systems emphasize documented supply chain custody and sterility validation. Dubai International Airport transit retail captures impulse-purchase positioning for premium moisturizing variants in corporate gifting segments.
Singapore
Singapore Airlines institutionalizes single-serve sanitizer inclusion in premium and economy cabin service, locking in annual volume commitments with compact TSA-compliant formats. Changi Airport transit hub density supports convenience store distribution for unplanned hygiene needs among business travelers. The city-state's procurement digitization accelerates online bulk-direct models that bypass traditional retail slotting fees.
Sanitizer Sachet Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Consumer goods conglomerates leverage South Asian distribution density to push single-serve packs through rural pharmacy networks, while institutional-grade suppliers anchor healthcare procurement with documented lot traceability. Three archetypes dominate: multinational FMCG houses with captive filling capacity, regional contract manufacturers with asset-light scaling models, and hygiene-specialist compounders with FDA monograph technical sophistication. Competitive moves center on backward integration into laminate substrate supply and geographic expansion through distribution partnerships in high-penetration pharmacy markets.
Among multinational FMCG houses, Unilever and Procter & Gamble exemplify the channel-control archetype through South Asian kirana store penetration. GOJO Industries occupies a position within the institutional-specialist tier, representing technical sophistication in healthcare procurement channels. These three companies anchor distinct competitive vectors: mass-market volume, premium consumer positioning, and institutional compliance depth.
| Leading Market Players |
|---|
| Unilever |
| Procter & Gamble |
| Reckitt Benckiser |
| Johnson & Johnson |
| 3M |
| Kimberly-Clark |
| GOJO Industries |
| Colgate-Palmolive |
| SC Johnson |
| Others |
Value Network & Pricing Analysis
Ahmedabad and Surat converter clusters in Gujarat state anchor global sachet laminate supply, with weekly production cycles feeding downstream pricing power to bulk-procurement officers at Emirates and Singapore Airlines who negotiate annual volume locks. This geographic concentration of multi-layer barrier film capacity creates asymmetric leverage where institutional buyers with scale extract fixed-price commitments while regional contract manufacturers absorb ethanol cost volatility.
Pricing Analysis
Certification level creates the primary spread between institutional-grade and consumer-grade sachets, with ISO 13485 manufacturing validation commanding 35-50% premiums over standard pharmacy-tier products. Three-tier pricing structure separates premium moisturizing variants with aloe enrichment from standard alcohol formats and economy single-serve units for rural Indian kirana stores. Price differentiation intensifies as FDA monograph compliance costs compound with BIS seal-integrity testing overhead, squeezing margin predictability for fixed-price healthcare contracts. Consumer households through online subscription channels prove least price-sensitive, while tier-3 Indian pharmacy distributors operate at sub-rupee unit economics with minimal tolerance for input cost pass-through.
Supply Chain Analysis
Export-control regimes on fluorinated barrier chemistries under EU REACH and F-Gas Regulation increasingly restrict laminate substrate flows into North American and Middle Eastern hospitality procurement channels. Multi-layer film production concentrates in China, South Korea, and India, with ethanol and isopropyl alcohol feedstocks drawing from agricultural commodity markets in Brazil and the United States. Single-source vulnerability pervades biodegradable film certification, where EN 13432 and ASTM D6400 compostable substrate suppliers number fewer than twelve globally. Distribution runs through bulk-direct manufacturer contracts with airline and hospital procurement officers, displacing wholesale intermediary tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sanitizer sachet market sustains defensive moats through regulatory entrenchment, where FDA monograph compliance and BIS packaging certification create 4-6 month qualification barriers that filter commodity entrants.
For Market Incumbents: Entrench position by backward integration into certified compostable laminate substrate supply, capturing sustainability scorecard mandates from EU and North American hospitality procurement. Add captive filling capacity in Ahmedabad or Surat clusters to compress lead times for Indian rural pharmacy replenishment cycles. Counter emerging asset-light regional contract manufacturers by locking exclusive annual volume commitments with Emirates, Qatar Airways, and Singapore Airlines amenity kit programs. For New Entrants and Emerging Players: Pursue white-space opportunity in water-soluble polyvinyl alcohol film technology for premium hospitality pilot programs, where dissolution-on-contact formats command experimental placement with corporate travel managers. Target India's tier-3 and tier-4 towns through kirana store distribution partnerships with regional pharmacy chains, leveraging sub-rupee unit economics that multinational FMCG houses disfavor. Deploy direct-to-consumer subscription models via Amazon and Flipkart to bypass slotting fees and capture recurring household revenue with auto-replenishment algorithms. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hygiene-specialist compounders with FDA monograph technical sophistication over commodity packaging converters facing biodegradable film yield degradation. Long-term viability rests on laminate suppliers with certified compostable substrate lines and documented lot traceability systems for hospital procurement convergence. Watch for inflection signals in airline sustainability scorecard adoption rates, as mandatory eco-friendly packaging thresholds would accelerate substrate switching costs and consolidate supplier tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Film Certification | EN 13432 and ASTM D6400 compliance unlocks EU and North American hospitality procurement with mandatory sustainability scorecards. |
| Direct Manufacturer Contracts | Bulk-direct annual volume locks with Emirates and Qatar Airways bypass wholesale intermediaries and concentrate pricing leverage. |
| Water-Soluble Film Pilot Programs | Polyvinyl alcohol dissolution technology trials with premium hospitality chains virtualize packaging-product boundaries for amenity kit differentiation. |
| Rural Pharmacy Distribution Partnerships | Kirana store density in Indian tier-3 towns drives volume uptake through weekly replenishment cycles from regional contract manufacturers. |
| ISO 13485 Manufacturing Certification | Hospital system vendor consolidation programs in the United States and Saudi Arabia mandate documented sterility validation and lot traceability. |
Research Methodology
Desk research of FDA topical antiseptic monograph filings, BIS packaging standard amendments, EU REACH regulatory updates, and airline procurement contract disclosures preceded structured interviews with contract manufacturing executives, laminate substrate suppliers, hospital procurement managers, and hospitality supply chain officers. Primary fieldwork across Ahmedabad, Surat, Chicago, and Düsseldorf converter clusters combined with secondary validation from customs trade data and hygiene product registration databases. Bottom-up unit volume modeling triangulated against top-down market sizing from institutional buyer annual report disclosures.
Forecast assumptions held fixed the current FDA alcohol concentration claim thresholds and EU fluorinated chemistry elimination timelines while varying biodegradable film adoption rates across procurement segments. The analytical framework segmented by formulation chemistry, packaging substrate certification, end-use application, and distribution channel across the projection horizon. CAGRs derived from regression analysis of quarterly replenishment cycle data and annual contract volume commitments, with ethanol feedstock pricing and laminate substrate switching costs as key volatility inputs.
Sensitivities concentrate around FDA monograph revision timing, BIS labeling amendment enforcement, and airline sustainability scorecard threshold adoption. Forecasts reflect documented assumptions on procurement digitization velocity and biodegradable film yield improvement curves. Material shifts in REACH fluorinated chemistry bans or alcohol input cost volatility would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sachet Packaging
Japan Sachet Packaging Market
Sachet Packaging
US Sachet Packaging Market
Sachet Packaging
Germany Sachet Packaging Market
Sachet Packaging
Single Dose Sachet Market
Sachet Packaging
Sachet and Pouch Handling Systems Market
Sachet Packaging
Sachet Packaging Machines Market
Sachet Packaging
India Plastic Packaging Market
Sachet Packaging
Full Container Shrink Sleeves Market
Sachet Packaging
China Sachet Packaging Market
Sachet Packaging
Sachet Packaging Market
Sachet Packaging
India Sachet Packaging Market
Sachet Packaging
Snap Sachets Market
Sachet Packaging
Asia Pacific Sachet Packaging Market
Sachet Packaging
Aluminium Foil Sachet Market
Sachet Packaging
North America Sachet Packaging Market
Sachet Packaging
Canada Sachet Packaging Market