
 Egypt Paperboard Packaging Market | 2026-2036
Egypt Paperboard Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Paperboard Packaging Market Foresight
REACH compliance is decoupling export-oriented producers from informal supply chains. Mondi plc leverages integrated pulp-to-board operations across its Egyptian facilities. Huhtamaki Egypt L.L.C. anchors flexible food-service packaging lines for quick-service restaurant chains. Smurfit WestRock plc dominates corrugated containerboard through recycled fiber networks in the Nile Delta.
Paperboard packaging comprises multi-ply fiber sheets, typically 200–400 gsm, formed through kraft pulping and calendering to achieve specific stiffness and printability thresholds for consumer goods protection and display. Folding cartons lead product type demand from pharmaceutical blister packs and personal care boxes, while corrugated boxes capture volume growth through e-commerce fulfillment requirements. Multi-pack configurations in beverage distribution command margin premiums over standard boxed formats due to structural complexity and brand differentiation needs.
Egypt's Ministry of Environment enforces industrial waste protocols that mandate post-consumer recycled content thresholds, while BIS-aligned import standards govern board stiffness and food-contact safety for cross-border shipments. The country's national pharmaceutical regulator requires tamper-evident paperboard specifications for OTC drug distribution. Stakeholders must monitor how recycling infrastructure investments in Upper Egypt reshape fiber availability and cost structures for packaging converters.
Market Dynamics
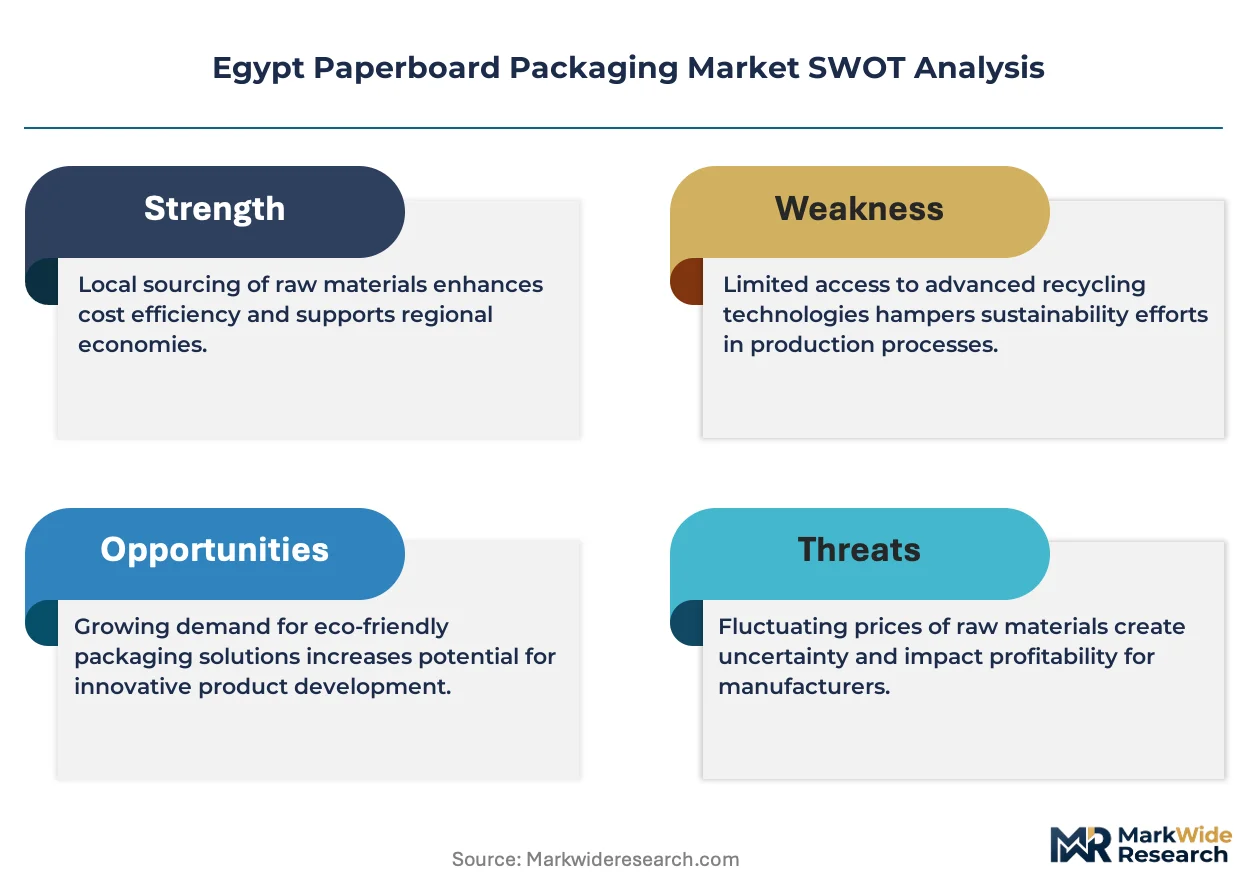
Egypt's paperboard packaging sector is compressing around regulatory mandates for post-consumer recycled content, forcing converters to restructure fiber sourcing away from informal collection networks toward certified supply chains.
Growth Catalysts
- Food and beverage shelf-ready formats:Quick-service restaurant chains and retail distributors are specifying paperboard for display-ready secondary packaging in Greater Cairo logistics corridors.
- Egypt's Ministry of Environment industrial waste protocols:Mandatory recycled content thresholds are pulling formal investment into collection infrastructure and pulping capacity.
- E-commerce fulfillment box specifications:Corrugated demand from Alexandria-based distribution centers is tightening structural standards for stackability and print registration.
Market Restraints
- Recycled fiber cost volatility:Dependence on informal waste collection networks in Upper Egypt creates input price instability during seasonal supply disruptions.
- BIS-aligned import stiffness standards:Cross-border board shipments face rejection risk at Port Said when caliper tolerances deviate from prescribed ranges.
- Plastic flexible substitution in moisture-critical applications:Dairy and chilled meat processors retain polymer-based primary packaging where paperboard barrier coatings underperform.
Strategic Opportunities
- Upper Egypt recycling infrastructure:Formal collection and sorting investments in Minya and Assiut governorates could unlock captive fiber supply for Nile Delta mills.
- Pharmaceutical tamper-evident specifications:Egypt's national pharmaceutical regulator mandates paperboard with integrated tear-tape and holographic verification for OTC distribution.
- Digital print-on-demand convergence:Short-run variable data printing is enabling brand owners to regionalize packaging artwork without plate-changeover delays.
Industry Challenges
- Skilled calendering and coating technicians:Specialized operators who manage gloss control and moisture barriers command premiums that smaller converters cannot match.
- Food-contact safety certification timelines:Migration testing for board-to-food substance transfer extends product qualification cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Paperboard Packaging Market |
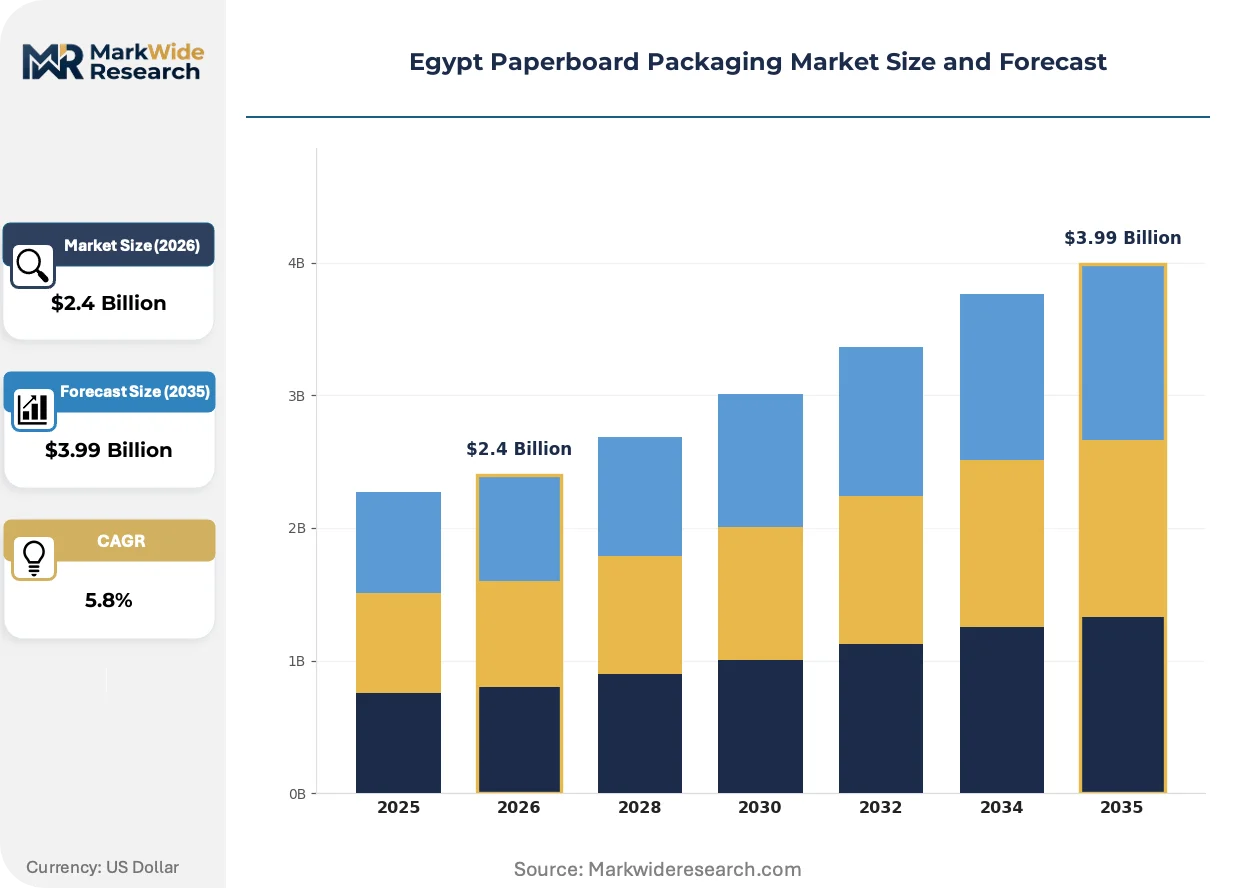
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Cartons, Corrugated Boxes, Rigid Boxes, Paper Bags End User: Food & Beverages, Personal Care, Pharmaceuticals, Electronics Packaging Type: Boxed, Padded, Multi-Pack, Sleeve Distribution Channel: Online Retail, Supermarkets, Wholesale, Convenience Stores |
| Companies Covered | Mondi plc, Cepack Group, Huhtamaki Egypt L.L.C., Graphic Packaging International Egypt, Indevco Group, International Paper Company, Tetra Pak Egypt Ltd, National Bag Company, Smurfit WestRock plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Paperboard Packaging Market Shifts & Advancements
Active transformation in Egypt's paperboard sector centers on digitization of production workflows, regulatory tightening around circular material flows, and the restructuring of buyer-supplier contracting models across pharmaceutical and food-service verticals.
Water-based barrier coating technology is replacing polyethylene extrusion layers in folding carton applications. Pharmaceutical blister pack manufacturers in 10th of Ramadan City are qualifying these coatings for humidity protection. The shift is decentralizing coating supply away from petrochemical-integrated producers toward specialty chemical formulators with local blending operations.
Egypt's Ministry of Environment enforcement of post-consumer recycled content mandates is compelling mills to document chain-of-custody from collection through pulping. Board converters serving export channels must maintain batch-level traceability records. The pharmaceutical segment is responding fastest, embedding recycled fiber claims into tender specifications for hospital and pharmacy distribution.
Consolidated procurement by quick-service restaurant chains is compressing supplier rosters and extending contract durations. Multi-year agreements with fixed volume commitments are displacing spot purchasing for corrugated containers. This concentration is most visible in Alexandria's free zone, where international food-service operators have reduced their approved packaging vendor lists from twelve to four suppliers.
Egypt Paperboard Packaging Market Segmentation
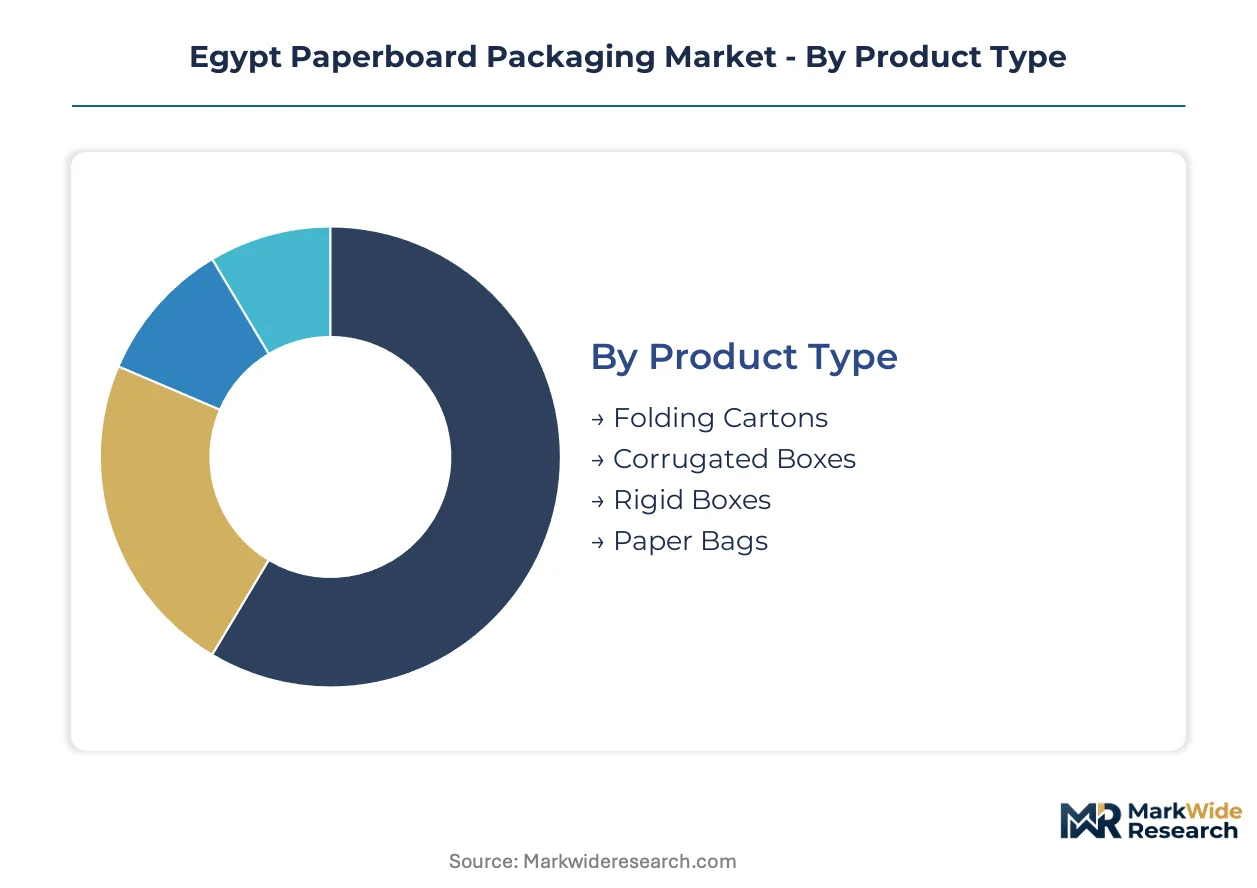
Paperboard packaging in Egypt fragments across four structural dimensions that determine fiber sourcing strategies, coating specifications, and distribution logistics. Each segmentation axis reveals distinct margin profiles and regulatory exposure for converters operating in Greater Cairo and Alexandria industrial corridors.
Product Type:
Converter capacity concentrates in the Nile Delta where integrated pulp-to-board operations serve high-volume folding carton and corrugated demand.
- Folding Cartons:Multi-ply fiber sheets ranging 200–400 gsm deliver calibrated stiffness for pharmaceutical blister packs and personal care boxes. Demand clusters in 10th of Ramadan City where quick-service restaurant chains specify shelf-ready formats with premium print registration.
- Corrugated Boxes:Fluted medium sandwiched between linerboards achieves stackability for e-commerce fulfillment from Alexandria distribution centers. Egypt's Ministry of Environment recycled content mandates are restructuring fiber sourcing toward certified supply chains for this segment.
- Rigid Boxes:Thick paperboard over wrapped cores serves luxury cosmetics and gift packaging with structural integrity requirements that command skilled hand-assembly labor.
- Paper Bags:Kraft paper constructions with twisted handles capture grocery and retail carryout demand where plastic bag restrictions are tightening municipal procurement.
Folding cartons absorb the bulk of installed capacity; corrugated boxes are expanding most quickly.
End User:
Customer procurement patterns diverge sharply between regulated pharmaceutical channels and price-sensitive food-service volumes.
- Food & Beverages:Shelf-ready secondary packaging specifications from quick-service restaurant chains drive folding carton volumes in Greater Cairo logistics corridors. Water-based barrier coatings are displacing polyethylene extrusion for humidity-sensitive beverage multi-packs.
- Personal Care:Premium rigid boxes and printed folding cartons serve cosmetics brands with gloss control requirements that demand specialized calendering technicians.
- Pharmaceuticals:Egypt's national pharmaceutical regulator mandates tamper-evident paperboard with integrated tear-tape and holographic verification for OTC drug distribution.
- Electronics:Anti-static corrugated and padded formats protect consumer devices through Alexandria free zone export channels where BIS-aligned stiffness standards govern cross-border shipments.
Food and beverages command the greatest tonnage; pharmaceuticals generate the steepest margin premiums.
Packaging Type:
Structural complexity tiers separate commodity box formats from value-added configurations requiring die-cutting and assembly automation.
- Boxed:Standard six-panel corrugated containers dominate e-commerce fulfillment with stackability specifications tightening from Alexandria-based distribution centers.
- Padded:Corrugated inserts and fiber-based cushioning replace polymer foams in electronics and fragile goods where recyclability claims support brand positioning.
- Multi-Pack:Beverage carriers and retail-ready groupings command margin premiums through structural complexity and brand differentiation requirements.
- Sleeve:Printed paperboard wraps secure multipacks and promotional bundles with high-visibility graphics for supermarket shelf impact.
Boxed formats anchor volume throughput; multi-pack configurations are climbing the fastest on margin expansion.
Distribution Channel:
Channel logistics dictate run lengths, print variability, and geographic concentration of converter assets.
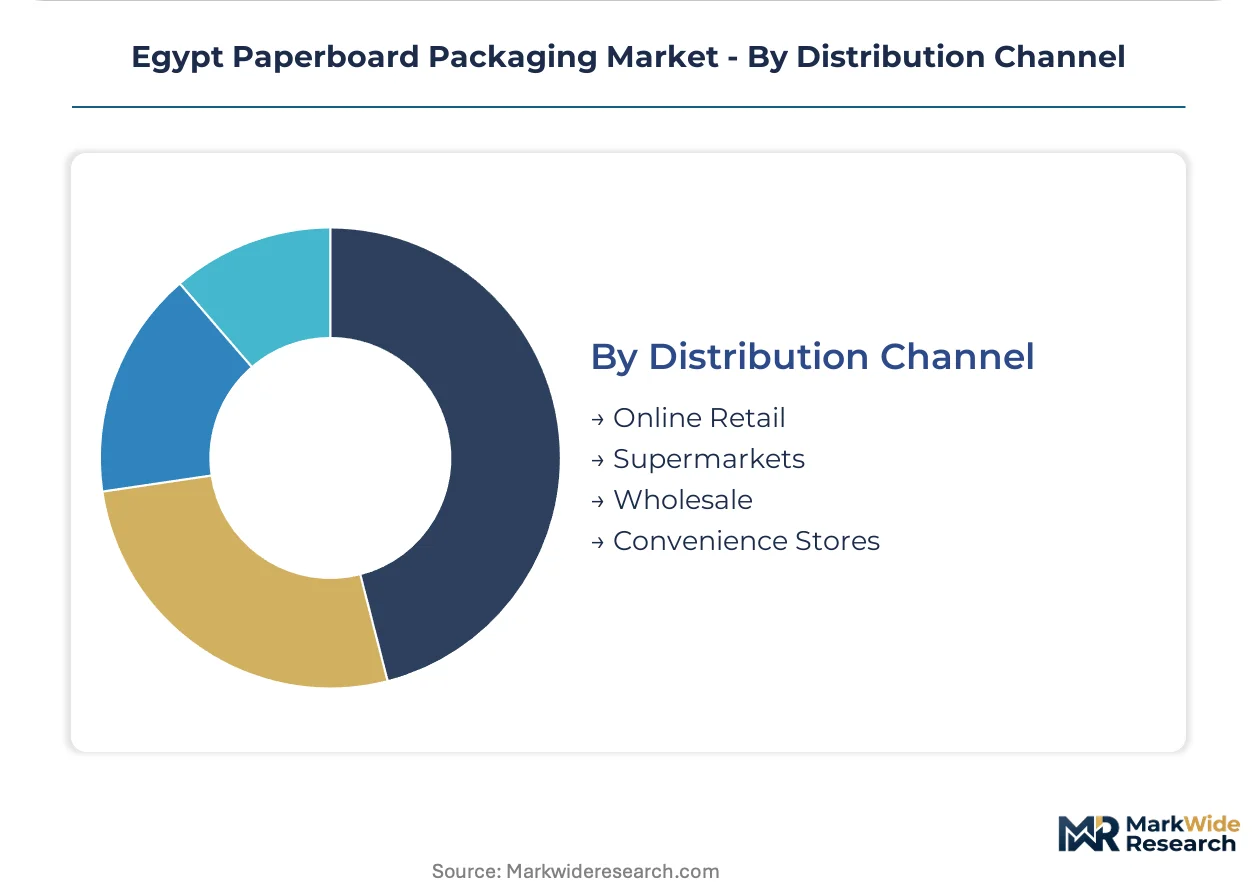
- Online Retail:Corrugated demand from Alexandria fulfillment centers requires variable box sizing and print-on-demand capabilities for brand regionalization.
- Supermarkets:Shelf-ready packaging specifications from retail chains concentrate folding carton procurement around Greater Cairo manufacturing clusters.
- Wholesale:Bulk corrugated and standard carton formats serve industrial and institutional buyers with long-run efficiency requirements.
- Convenience Stores:Small-format multi-packs and promotional sleeves target impulse purchase occasions with rapid artwork turnaround needs.
Supermarkets absorb the bulk of folding carton capacity; online retail is gaining share fastest on fulfillment infrastructure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alexandria's free zone status and Port Said logistics corridors concentrate paperboard demand from export-oriented food processors and pharmaceutical distributors serving Middle East and North African markets.
Greater Cairo
Quick-service restaurant chains and retail distributors specify shelf-ready folding cartons for secondary packaging across 10th of Ramadan City industrial clusters. Egypt's Ministry of Environment enforces post-consumer recycled content mandates that restructure fiber sourcing for converters operating in Obour and Badr industrial zones. Calendering and coating specialists command wage premiums as brand owners tighten gloss control specifications for premium cosmetics boxes.
Alexandria
E-commerce fulfillment centers drive corrugated box demand with stackability requirements for palletized export shipments through Dekheila port. BIS-aligned import stiffness standards govern cross-border board shipments, creating compliance bottlenecks at customs inspection points. International food-service operators in the free zone have consolidated approved packaging vendor lists from twelve to four suppliers, extending contract durations to multi-year agreements.
Nile Delta
Integrated pulp-to-board operations serve high-volume corrugated demand from agricultural exporters shipping through Damietta port. Smurfit WestRock plc dominates containerboard production through recycled fiber networks that feed die-cutting and flexographic printing lines. Seasonal cotton harvests compete for trucking capacity, disrupting just-in-time fiber deliveries to mills in Kafr El Sheikh and Dakahlia governorates.
Upper Egypt
Formal collection infrastructure investments in Minya and Assiut governorates aim to unlock captive fiber supply for Nile Delta mills currently dependent on informal waste networks. The Ministry of Environment's industrial waste protocols mandate documentation of chain-of-custody from collection through pulping. Small-scale sorting facilities in Sohag face capital constraints for optical separation equipment that would upgrade recovered fiber quality to food-contact grades.
Suez Canal Zone
Transit packaging for re-export goods generates demand for standardized corrugated formats that withstand humidity exposure during Red Sea shipping routes. Electronics manufacturers in Ismailia specify anti-static corrugated and padded formats for consumer devices bound for Gulf Cooperation Council markets. Port Tawfik logistics hubs require rapid box sizing variability to accommodate mixed-container consolidation for East African destinations.
Egypt Paperboard Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Egypt's paperboard packaging sector, creating a tiered structure where scale advantages clash with customization agility. Integrated pulp-to-board operators leverage captive fiber supply and calendering capacity to serve high-volume food and beverage contracts. Independent converters survive on short-run flexibility for pharmaceutical and personal care segments where artwork variability commands premium pricing. Dominant competitive moves center on backward integration into recycling infrastructure and strategic partnerships with quick-service restaurant chains for multi-year supply agreements.
Within the integrated multinational tier, Mondi plc exemplifies operators with pulp-to-board capabilities across Egyptian facilities, while Huhtamaki Egypt L.L.C. occupies a position among food-service packaging specialists serving quick-service restaurant chains. Smurfit WestRock plc anchors the corrugated containerboard segment through recycled fiber networks concentrated in the Nile Delta. These three represent divergent strategic postures: full integration, food-service specialization, and corrugated scale.
| Leading Market Players |
|---|
| Mondi plc |
| Cepack Group |
| Huhtamaki Egypt L.L.C. |
| Graphic Packaging International Egypt |
| Indevco Group |
| International Paper Company |
| Tetra Pak Egypt Ltd |
| National Bag Company |
| Smurfit WestRock plc |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between food-contact compliant board and standard industrial grades manifests in both pricing premiums and fiber sourcing configurations across Egypt's paperboard sector. Premium folding cartons for pharmaceutical and quick-service restaurant chains command structural margins due to Egypt's Ministry of Environment chain-of-custody documentation requirements and BIS-aligned import stiffness standards.
Pricing Analysis
Short lead-time premiums for just-in-time folding carton deliveries to 10th of Ramadan City quick-service restaurant chains contrast with spot-market discounts for bulk corrugated orders from Alexandria distribution centers. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade certified board from food-service packaging and industrial corrugated grades. Cost compression in standard corrugated is intensifying because seasonal cotton harvests compete for Nile Delta trucking capacity. Food and beverage processors show greatest price sensitivity, while pharmaceutical distributors absorb premiums for tamper-evident specifications.
Supply Chain Analysis
Direct-to-converter channels handle high-volume folding carton demand from Greater Cairo manufacturing clusters, while distributor-mediated procurement serves smaller Upper Egypt converters. Egypt's fiber supply draws from domestic informal collection networks in Minya and Assiut governorates, supplemented by imported kraft pulp through Port Said. Single-source vulnerability concentrates in recycled fiber supply from informal waste networks during seasonal disruptions. Distribution runs through Alexandria free zone logistics corridors for export-oriented pharmaceutical and food-service shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's paperboard packaging sector is becoming a vertical-integration race as converters pursue backward control over certified recycled fiber supply to meet Ministry of Environment mandates and escape informal network volatility.
For Market Incumbents: Anticipate margin compression from consolidated quick-service restaurant procurement by locking multi-year supply agreements before vendor roster reductions conclude. Prioritize in-house pulping capacity additions in Kafr El Sheikh to secure captive fiber supply against seasonal collection disruptions. Defend pharmaceutical segment positioning through accelerated food-contact safety certification investments. For New Entrants and Emerging Players: Launch via digital print-on-demand service models targeting convenience store promotional sleeves and short-run regionalized artwork for e-commerce fulfillment boxes. Upper Egypt's formalizing collection infrastructure in Sohag and Assiut presents the most penetrable white space for fiber supply integration. Partner with Nile Delta mills as toll coating operators to bypass capital-intensive calendering equipment barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated multinational packaging conglomerates seeking Egyptian manufacturing footholds. Long-term viability hinges on converters with documented chain-of-custody systems and pharmaceutical certification pipelines. Monitor Egypt's Ministry of Environment enforcement intensity as the inflection signal for fiber cost structure normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling Infrastructure | Captive fiber supply from Minya and Assiut collection networks reduces dependence on informal seasonal supply. |
| Water-Based Barrier Coating Qualification | Pharmaceutical blister pack manufacturers in 10th of Ramadan City are displacing polyethylene extrusion layers. |
| Multi-Year Supply Agreement Consolidation | Alexandria free zone quick-service restaurant operators have compressed approved vendor lists from twelve to four. |
| Digital Print-on-Demand Capability Investment | Short-run variable data printing enables brand regionalization without plate-changeover delays for e-commerce. |
| Food-Contact Safety Certification Acceleration | Egypt's national pharmaceutical regulator mandates tamper-evident specifications with holographic verification. |
Research Methodology
Trade association filings, customs import records, and Ministry of Environment regulatory gazettes formed the secondary backbone for fiber supply and compliance requirement mapping. Primary interviews with folding carton plant managers, quick-service restaurant procurement leads, pharmaceutical packaging specification directors, and Nile Delta mill operations heads combined with secondary validation through bottom-up and top-down triangulation.
Historical trendline analysis of installed capacity, fiber input costs, and end-user procurement patterns established baseline growth trajectories across the analysis window. Segmentation dimensions modeled include product type, end-user industry, packaging format complexity, and geographic production cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating e-commerce fulfillment infrastructure expansion and pharmaceutical regulatory compliance timelines.
Recycled fiber supply disruptions, Ministry of Environment enforcement intensity variations, and quick-service restaurant vendor consolidation pace are the dominant revision risks to modeled outcomes. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
North America Corrugated Packaging Market
Paper & Paperboard Packaging
Unbleached Kraft Paperboard Market
Paper & Paperboard Packaging
Paper Cones Market
Paper & Paperboard Packaging
Letterpress Card Market
Paper & Paperboard Packaging
Boxboard Packaging Market
Paper & Paperboard Packaging
Corrugated Shippers Market
Paper & Paperboard Packaging
Micro Flute Paper Market
Paper & Paperboard Packaging
China Corrugated Packaging Market
Paper & Paperboard Packaging
Envelope Market
Paper & Paperboard Packaging
Folding Paperboard Boxes Market
Paper & Paperboard Packaging
Shredded Paper Filler Market
Paper & Paperboard Packaging
United States Paper Packaging Market
Paper & Paperboard Packaging
Kraft Paper Bags Market
Paper & Paperboard Packaging
South Africa Paper Packaging Market
Paper & Paperboard Packaging
Honeycomb Mailers Market
Paper & Paperboard Packaging
Beverage Filter Paper Market