
 Flow Pack Machine Market | 2026-2036
Flow Pack Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Flow Pack Machine Market Analysis
The flow pack machine market is rebalancing between premium servo-driven systems and commodity mechanical configurations as food processors split procurement budgets by output volume. ULMA Packaging leverages its Basque engineering base to sustain high-margin horizontal lines for protein packaging. Bosch Packaging Technology anchors European pharmaceutical demand with validated cold-seal systems. Fuji Machinery dominates Asian snack packaging through compact footprint vertical machines engineered for tropical humidity conditions.
A flow pack machine is a form-fill-seal packaging system that wraps products in a continuous flexible film web, typically achieving speeds of 30 to 800 packs per minute depending on servo motor configuration and product dimensions. The machine forms a tube around the product, seals it longitudinally and transversely, and cuts individual packs for retail distribution. Horizontal configurations command the widest installed base across bakery and confectionery lines where product fragility demands gentle infeed handling. Biodegradable material compatibility is the fastest-growing technical requirement as converters retrofit sealing jaws and temperature controls for PLA and cellulose films. Heat seal technology retains dominant share but ultrasonic sealing is displacing legacy methods in moisture-sensitive pharmaceutical applications where cold seal adhesive costs have risen.
FDA validation protocols for pharmaceutical packaging and EU MDR traceability requirements shape machine specification across regulated end uses, forcing OEMs to embed serialization-ready controls and audit trail software. REACH compliance on film additives and emerging state-level extended producer responsibility laws in California and New York are narrowing the approved material set for plastic-based systems. Stakeholders must weigh total cost of ownership against retrofit flexibility as substrate regulations tighten and end users demand format changeover times under three minutes.
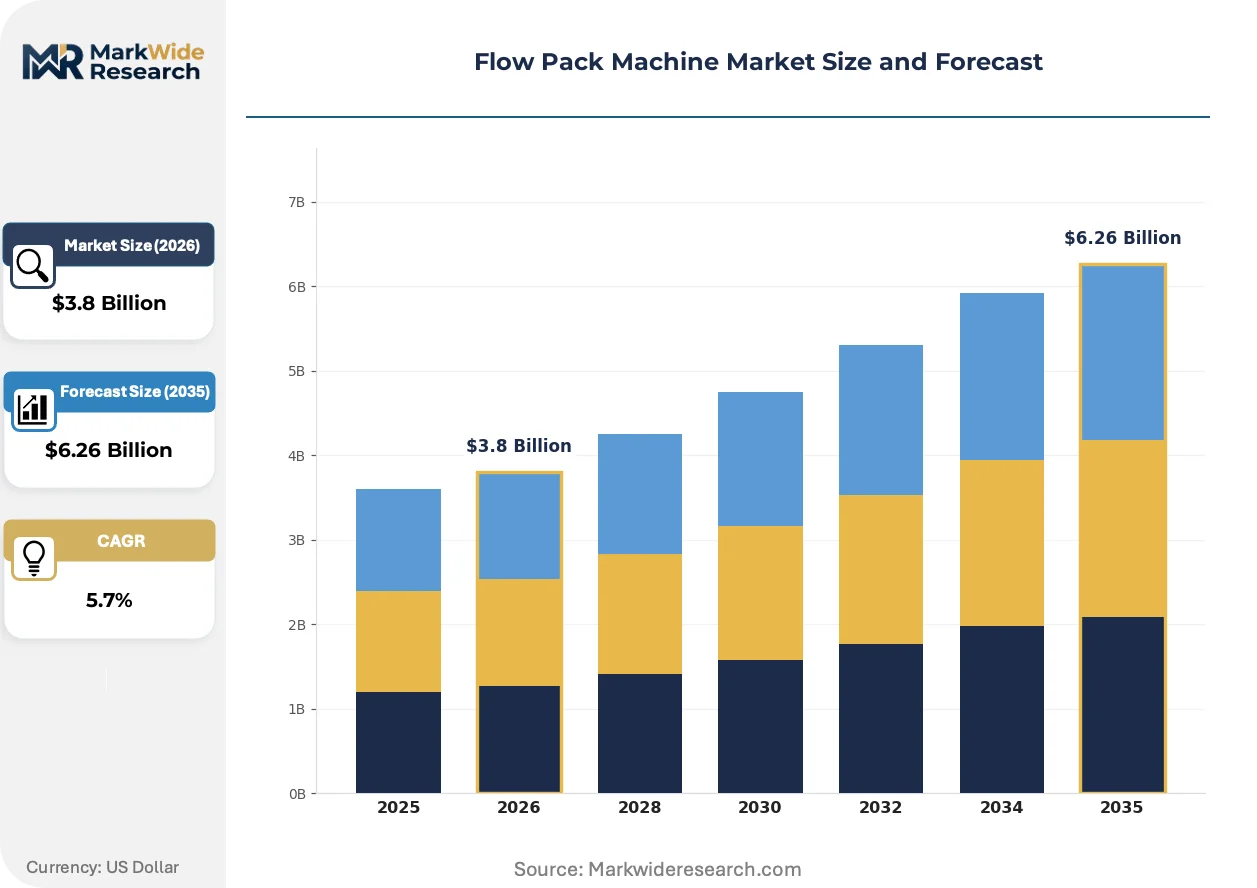
Market Dynamics
The flow pack machine market is experiencing a fundamental rebalancing as servo-driven automation converges with biodegradable film mandates, forcing OEMs to engineer sealing systems that accommodate both high-speed precision and temperature-sensitive sustainable substrates without compromising throughput.
Growth Catalysts
- EU Green Deal packaging directives:Extended producer responsibility frameworks are mandating biodegradable film integration across European food packaging lines, creating retrofit demand for temperature-calibrated sealing jaws and servo-controlled heat management systems.
- Confectionery export manufacturing:Vietnam's contract packaging corridor near Ho Chi Minh City is scaling automated horizontal flow pack capacity to serve European and North American retail private-label demand.
- Ultrasonic cold-seal advancement:Moisture-sensitive pharmaceutical applications are migrating from heat-seal to ultrasonic sealing technology as cold-seal adhesive input costs escalate, driving equipment replacement cycles in validated packaging environments.
Market Restraints
- Biodegradable film substrate volatility:PLA and cellulose film supply remains concentrated among specialty converters in Germany and Italy, exposing packaging lines to input cost fluctuations and batch consistency variability.
- REACH additive compliance:ECHA restrictions on plasticizers and slip agents in flexible films are narrowing the approved material set, forcing machine builders to qualify alternative sealing surface coatings at extended development timelines.
- Mechanical system substitution:Commodity food processors in price-sensitive segments are extending legacy mechanical flow pack lifecycles rather than upgrading to servo-driven systems, compressing OEM margin pools in standard configurations.
Strategic Opportunities
- Indian pharmaceutical packaging:CDSCO serialization mandates and rising domestic generic drug manufacturing are creating demand for validated flow pack systems with integrated track-and-trace software and audit trail capabilities.
- California extended producer responsibility:State-level packaging waste legislation is accelerating biodegradable film adoption ahead of federal timelines, positioning early-moving OEMs with PLA-compatible sealing technology.
- Ultrasonic-vision system convergence:Machine builders integrating real-time seal inspection with ultrasonic welding are capturing pharmaceutical and medical device accounts where zero-defect packaging is non-negotiable.
Industry Challenges
- Servo-motion programming expertise:The shift from mechanical to servo-driven architectures has created acute shortages of automation engineers capable of optimizing multi-axis motion profiles for fragile product handling.
- FDA validation timeline compression:Pharmaceutical packers are demanding 21 CFR Part 11 compliant documentation and installation qualification protocols within compressed project windows, straining OEM field service organizations.
- Legacy system integration friction:Food processors with existing mechanical flow pack fleets face complex retrofit decisions when biodegradable films require incompatible temperature and dwell time parameters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flow Pack Machine Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical, Horizontal, High-Speed, Automation Material Type: Plastic, Paper, Aluminum, Biodegradable End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Technology: Heat Seal, Cold Seal, Ultrasonic, Laser Welding |
| Companies Covered | ULMA Packaging, Cavanna Packaging Group, HOPAK MACHINERY CO., LTD, JOIEPACK Industrial Co., Ltd., Chengdu SANKE Industry Co., Ltd, IMA Group, Bosch Packaging Technology, Fuji Machinery, Technopack Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flow Pack Machine Market Emerging Trajectories
Active intelligence layers and sustainable substrate engineering are converging to redefine flow pack machine specifications, with end users prioritizing format flexibility and regulatory traceability over raw speed metrics.
Ultrasonic sealing technology is rewriting competitive positioning in moisture-sensitive packaging segments. This cold-weld method eliminates thermal degradation of heat-sensitive films and pharmaceutical products. Mid-tier pharmaceutical contract packers in Switzerland and Germany are adopting ultrasonic-equipped horizontal lines at accelerating rates. The technology is compressing the addressable market for conventional heat-seal systems in applications where seal integrity validation is mandatory.
EU MDR traceability requirements are mandating serialization-ready machine controls across European pharmaceutical packaging installations. The regulation forces OEMs to embed centralized database connectivity and electronic signature capture at the machine level. Cold-seal flow pack lines for medical device sterile barrier packaging are experiencing the most acute compliance pressure, with manufacturers retrofitting audit trail software to avoid regulatory exclusion.
Service unbundling is fragmenting traditional OEM revenue models in mature European markets. Food processors in France and Spain are separating hardware procurement from aftermarket service contracts, engaging third-party maintenance providers for mechanical flow pack fleets. This behavior is most visible in bakery and confectionery segments where standardized machines dominate installed bases and specialized service expertise has proliferated among independent technicians.
Flow Pack Machine Market Segmentation
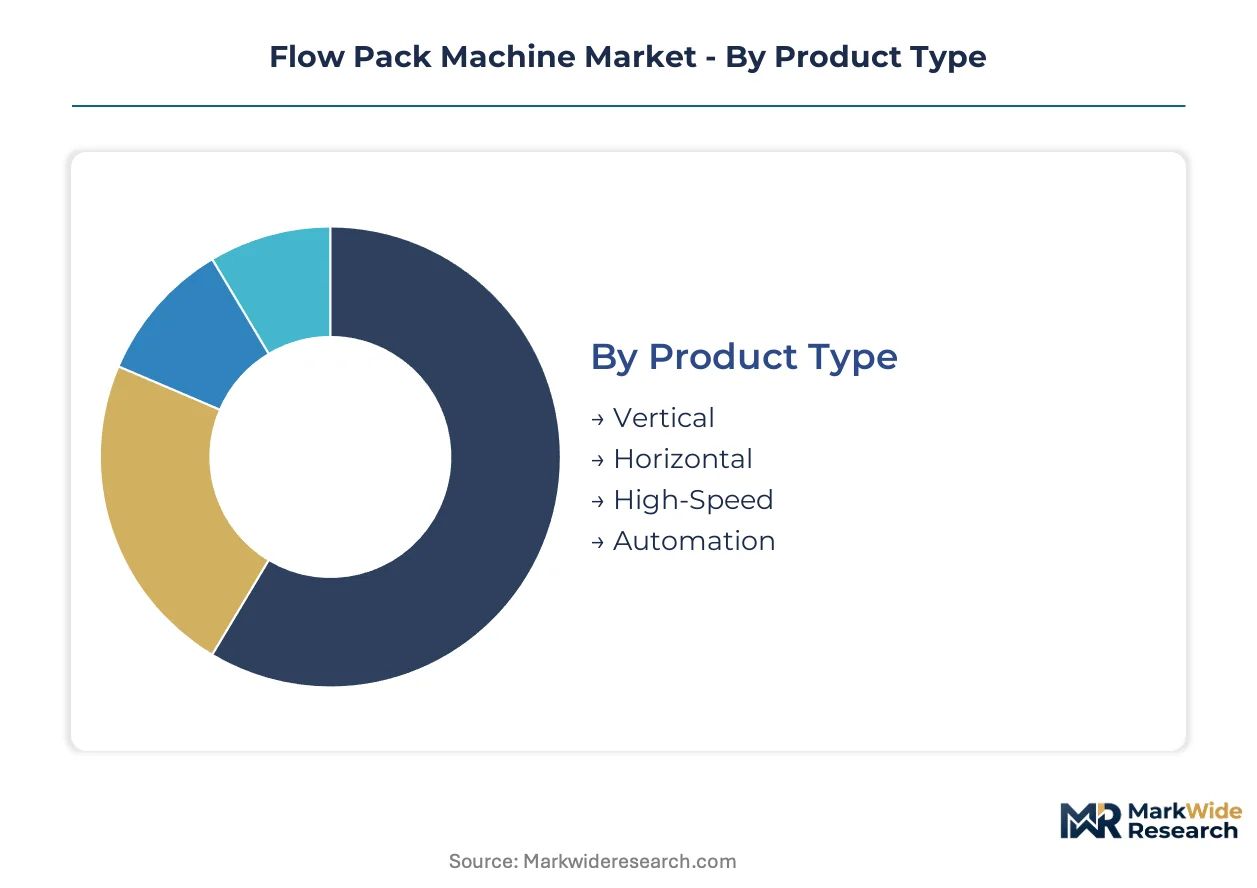
Flow pack machine procurement splits sharply between output volume requirements and substrate compatibility mandates. Food processors prioritize gentle handling configurations for fragile products, while pharmaceutical packers validate sealing technology against regulatory audit protocols.
Product Type:
Capital expenditure thresholds and line speed requirements drive the buyer decision calculus across machine configurations.
- Horizontal:These machines dominate bakery and confectionery installations where product fragility demands controlled infeed handling. Vietnam's contract packaging corridor near Ho Chi Minh City is scaling automated horizontal lines to serve European retail private-label demand.
- Vertical:Compact footprint designs engineered for tropical humidity conditions dominate Asian snack packaging installations. Fuji Machinery leverages this configuration for space-constrained factory floors where throughput density matters.
- High-Speed:Servo-driven architectures achieving 800 packs per minute serve mass-market confectionery and biscuit producers with continuous shift operations.
- Automation:Integrated robotics and vision systems reduce format changeover times under three minutes for multi-SKU contract packers.
Volume sits with Horizontal configurations; growth tilts toward Automation systems.
Material Type:
Regulatory compliance timelines and converter supply geography constrain material selection for new machine qualification.
- Biodegradable:PLA and cellulose films require temperature-calibrated sealing jaws and servo-controlled heat management systems. The EU Green Deal's packaging waste directives are accelerating retrofit demand across European installations.
- Plastic:Polypropylene and polyethylene laminates retain dominant installed base across cost-sensitive food segments. REACH restrictions on plasticizers and slip agents are narrowing the approved material set for these systems.
- Paper:Fiber-based barrier coatings serve premium confectionery and dry bakery applications where tactile shelf presence commands price premiums.
- Aluminum:Metallized films and foil laminates provide oxygen and moisture barriers for pharmaceutical blister alternatives and high-fat food products.
Plastic holds the largest installed base; Biodegradable gains share fastest.
End User:
Validation depth and traceability requirements separate procurement specifications across vertical applications.
- Food & Beverage:Horizontal configurations with gentle product handling dominate bakery, confectionery, and fresh produce packaging. Southeast Asian packaged food producers are expanding capacity to serve urban retail expansion.
- Pharmaceuticals:FDA validation protocols and EU MDR traceability requirements mandate serialization-ready controls and audit trail software. Cold-seal and ultrasonic systems serve moisture-sensitive drug packaging where seal integrity is non-negotiable.
- Cosmetics:Premium positioning demands drive investment in aesthetic seal quality and tamper-evident features for personal care products.
- Electronics:Anti-static films and precision cutting systems protect sensitive components during automated packaging operations.
Food & Beverage commands the widest installed base; Pharmaceuticals shows the steepest expansion trajectory.
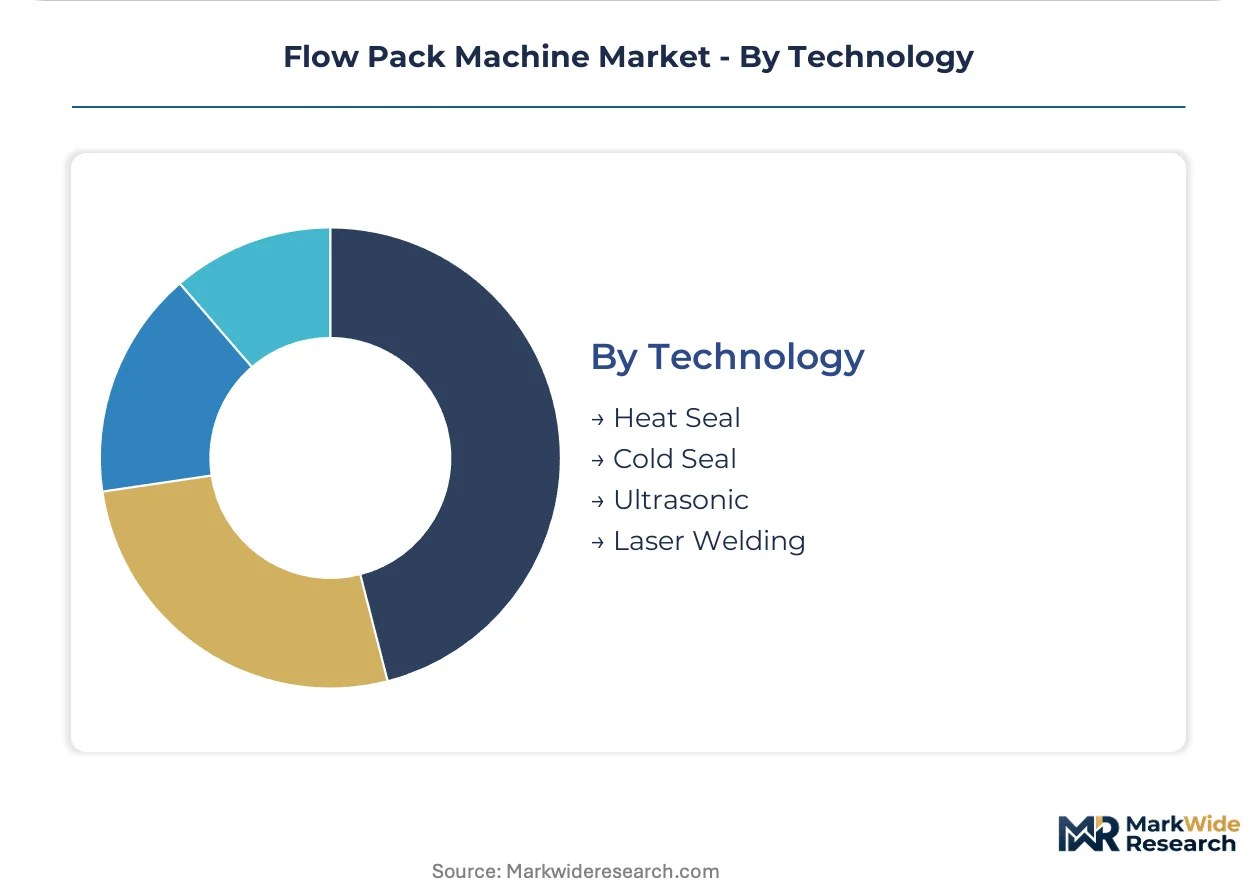
Technology:
Seal integrity validation methods and substrate thermal sensitivity determine technology selection for regulated applications.
- Ultrasonic:Cold-weld sealing eliminates thermal degradation of heat-sensitive films and pharmaceutical products. Swiss and German pharmaceutical contract packers are adopting ultrasonic-equipped horizontal lines at accelerating rates.
- Heat Seal:Conventional jaw sealing with temperature and dwell time controls retains cost advantage across commodity food applications. Biodegradable film integration is forcing retrofit of temperature management systems.
- Cold Seal:Pressure-sensitive adhesive sealing serves chocolate and heat-sensitive confectionery where thermal exposure causes product damage. Rising adhesive input costs are compressing this segment's economics.
- Laser Welding:Precision energy delivery enables hermetic seals for medical device sterile barrier packaging with minimal thermal footprint.
Heat Seal retains dominant share; Ultrasonic climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ho Chi Minh City's manufacturing corridor anchors Southeast Asian flow pack capacity expansion, with contract packers scaling automated horizontal lines for confectionery export to European and North American retail private-label clients.
Germany
Engineering-intensive horizontal flow pack systems serve protein packaging and pharmaceutical sterile barrier applications. ECHA REACH restrictions on plasticizers and slip agents in flexible films force machine builders to qualify alternative sealing surface coatings. The Baden-Württemberg industrial cluster around Stuttgart concentrates OEM engineering talent for servo-driven architectures.
Vietnam
Export-oriented contract packaging for European confectionery brands drives automated horizontal line procurement. The country's national food safety regulator enforces packaging material compliance for imported retail goods. Binh Duong Province's industrial zones adjacent to Ho Chi Minh City host scaling automated packaging operations for private-label export.
Switzerland
Pharmaceutical contract packers adopt ultrasonic-equipped horizontal lines for moisture-sensitive drug packaging where seal integrity validation is mandatory. Swissmedic medical device regulations mandate audit trail software and electronic signature capture at the machine level. The Basel pharmaceutical manufacturing cluster drives demand for validated cold-seal and ultrasonic sealing systems.
United States
California's extended producer responsibility legislation accelerates biodegradable film adoption ahead of federal timelines, positioning OEMs with PLA-compatible sealing technology. FDA 21 CFR Part 11 validation protocols compress project windows for pharmaceutical packaging installations. The Chicago metropolitan area concentrates food processing headquarters driving horizontal flow pack procurement for bakery and snack applications.
India
CDSCO serialization mandates and rising domestic generic drug manufacturing create demand for validated flow pack systems with integrated track-and-trace software. The FSSAI food safety authority enforces packaging material standards for processed food exports. Maharashtra's pharmaceutical manufacturing belt around Mumbai and Pune scales validated packaging capacity for regulated export markets.
Flow Pack Machine Market Vendor Landscape
Premium-margin players sit above commodity-margin players across servo-motion sophistication and validation depth. The vendor base separates into three tiers: European engineering houses with pharmaceutical validation capabilities, Asian fabricators optimizing compact footprint designs for tropical conditions, and mechanical specialists serving price-sensitive commodity food processors. Two dominant competitive moves define current positioning: technology licensing partnerships for ultrasonic sealing integration and geographic expansion through regional assembly facilities to compress delivery timelines and field service response.
Among European engineering houses, ULMA Packaging and Bosch Packaging Technology occupy positions at the premium-validation intersection, while Fuji Machinery exemplifies the Asian compact-footprint optimization archetype. These three anchors represent divergent strategic responses to substrate diversification pressures—European players embedding regulatory compliance layers, Japanese and Chinese fabricators engineering humidity-resistant servo architectures for dense factory floors.
| Leading Market Players |
|---|
| ULMA Packaging |
| Cavanna Packaging Group |
| HOPAK MACHINERY CO., LTD |
| JOIEPACK Industrial Co., Ltd. |
| Chengdu SANKE Industry Co., Ltd |
| IMA Group |
| Bosch Packaging Technology |
| Fuji Machinery |
| Technopack Corporation |
| Others |
Supply Flow & Price Mechanics
Automation engineer shortages in Germany's Baden-Württemberg industrial cluster drive labor-cost differentials that widen pricing-tier spreads between servo-driven pharmaceutical systems and commodity mechanical configurations for cost-sensitive food processors.
Pricing Analysis
Value-based pricing anchored to validated uptime guarantees and seal integrity outcomes dominates pharmaceutical procurement, while food processors transact on per-unit equipment costs. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated systems with audit trail software from standard servo configurations and legacy mechanical lines. Pricing pressure stems from commodity food processors extending legacy equipment lifecycles rather than upgrading. Contract packers in Vietnam's export corridor show least price sensitivity; bakery cooperatives in Southern Europe exhibit highest.
Supply Chain Analysis
India's PLI scheme for machinery manufacturing and Vietnam's local-content rules for imported packaging equipment are reshaping sourcing patterns for European and Asian OEMs. Component supply draws from Germany for precision servo drives, Japan for humidity-resistant control systems, and China for structural fabrications. Sealing jaw alloys and PLA film substrates from German and Italian specialty converters create single-source vulnerability. Distribution runs through regional assembly facilities that compress field service response times for pharmaceutical and food processing clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
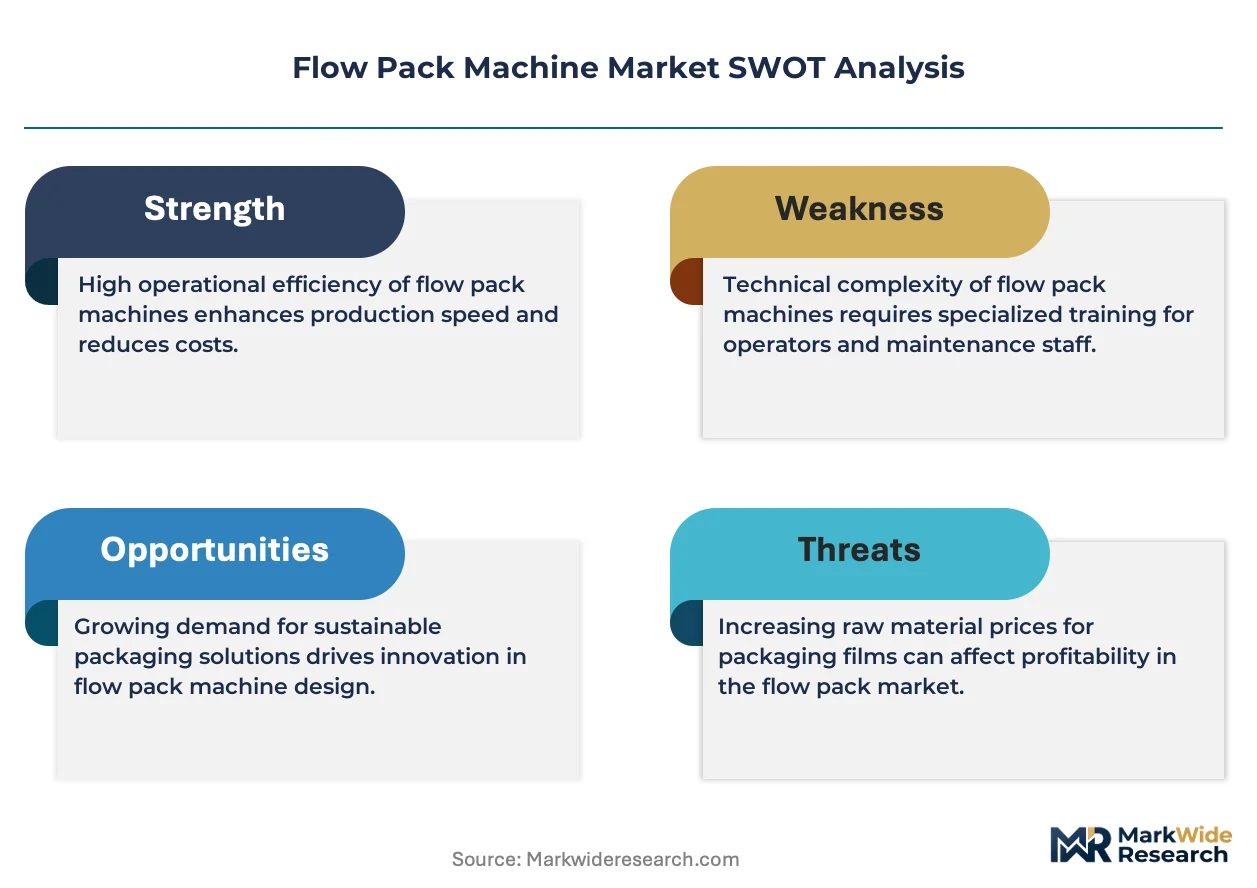
This market reads as a cost-of-compliance story where EU MDR traceability requirements and FDA 21 CFR Part 11 validation protocols erect barrier-to-entry moats favoring OEMs with embedded regulatory software layers.
For Market Incumbents: Deploy ultrasonic sealing technology licensing partnerships to capture pharmaceutical contract packers migrating from cold-seal systems. Acquire regional service capabilities in Vietnam's Binh Duong Province to defend installed base against Asian fabricators. Consolidate aftermarket software revenue streams as European food processors unbundle service contracts. For New Entrants and Emerging Players: California's extended producer responsibility legislation opens a window for PLA-compatible sealing technology specialists to establish beachheads ahead of federal mandates. Target Indian pharmaceutical packaging with CDSCO-compliant track-and-trace integrations as the most penetrable white space. Pursue technology licensing arrangements rather than full system manufacturing to bypass validation timeline barriers. For Investors and Strategic Acquirers: Re-rating potential sits with ultrasonic-vision system integrators given Swiss and German pharmaceutical packers' accelerating adoption rates. Long-term viability favors OEMs with captive servo-motion programming expertise and biodegradable film retrofit capabilities. Watch FDA validation timeline compression as the inflection signal for field service scalability constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Sealing Technology Licensing | Captures pharmaceutical demand migrating from heat-seal and cold-seal systems. |
| Regional Assembly Facility Expansion | Compresses delivery timelines for Vietnam's contract packaging export corridor. |
| Biodegradable Film Retrofit Programs | Positions OEMs for EU Green Deal packaging waste directive compliance. |
| Audit Trail Software Integration | Meets EU MDR and FDA 21 CFR Part 11 traceability mandates for sterile barrier packaging. |
| Servo-Motion Programming Talent Acquisition | Addresses acute engineering shortages constraining multi-axis optimization for fragile product handling. |
Methodological Framework
Independent corroboration across OEM engineering directors, pharmaceutical packaging validation leads, food processor maintenance directors, and contract packer procurement officers underwrites the qualitative findings. Secondary validation drew from EU MDR implementation guidance, FDA 510(k) filings for packaging equipment, ECHA REACH restriction updates, and trade flow data for PLA and cellulose film imports. Bottom-up equipment shipment analysis triangulated against top-down capital expenditure surveys across pharmaceutical and food processing verticals.
Rate-of-change decomposition across machine configuration, sealing technology, material compatibility, and end-use validation depth structured the analytical framework. Segmentation modeling spanned horizontal versus vertical architectures, heat-seal versus ultrasonic versus cold-seal technologies, biodegradable versus plastic versus paper substrates, and food versus pharmaceutical versus cosmetics end uses. CAGRs derived from installed base replacement cycles, regulatory compliance deadlines, and export manufacturing capacity expansion in Southeast Asia.
The model assumes a particular technology adoption path; alternative pathways for ultrasonic sealing penetration in moisture-sensitive pharmaceutical applications would alter the outlook. Forecasts reflect assumptions regarding REACH additive restriction timelines, biodegradable film converter supply scaling, and servo-motion engineering labor availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Bakery Packaging Machine Market
Packaging Machinery
Food Powder Packaging Machine Market
Packaging Machinery
Automated Poly Bagging Machines Market
Packaging Machinery
Metal Banding Machine Market
Packaging Machinery
Cigarette Packaging Machine Market
Packaging Machinery
Enveloping & Stacking Machine Market
Packaging Machinery
Automatic Paper Cutter Market
Packaging Machinery
In-Line Thermoforming Machine Market
Packaging Machinery
Vertical Injection Molding Machine Market
Packaging Machinery
Envelope Sealing Machines Market
Packaging Machinery
Tray Forming Machine Market
Packaging Machinery
Overwrapping Machines Market
Packaging Machinery
Injection Blow Molding Machine Market
Packaging Machinery
Blow Fill Seal (BFS) Technology Market
Packaging Machinery
Automatic Auger Fillers Market
Packaging Machinery
Stacking Machine Market