
 Shrink Plastic Films Market | 2026-2036
Shrink Plastic Films Market Size, Share, and Industry Trends Forecast 2026-2036
Shrink Plastic Films Market Analytics
Buyer concentration among large-format retail chains is shifting procurement power toward centralized packaging specifications that favor multi-site film suppliers. Sealed Air Corporation leverages its integrated equipment-film bundling to lock in high-volume accounts across North American grocery distribution centers. Amcor plc anchors its position through backward integration into resin compounding, securing margin control on specialized polyolefin grades. Berry Global competes by dominating the thin-gauge segment for lightweight beverage multipacks, where freight economics favor reduced film mass per unit.
Shrink plastic films are thermoplastic polymer sheets engineered to contract tightly around products when exposed to controlled heat, typically achieving 30-70% shrinkage in either single-axis or biaxial orientation depending on extrusion and stretching parameters. These films serve primarily to unitize multipacks, protect surfaces from contamination, and create tamper-evident seals across consumer and industrial distribution channels. Polyolefin formulations lead volume due to superior clarity and seal strength in high-speed form-fill-seal operations, while PET films capture premium applications demanding higher heat resistance and dimensional stability. The bags form factor generates the fastest growth as e-commerce fulfillment centers adopt pre-sized shrink bags to accelerate parcel consolidation without custom wrapping equipment.
The US FDA maintains strict migration limits for additives in food-contact films under 21 CFR 177.1520, directly shaping resin selection and antioxidant packages for domestic suppliers. REACH compliance across Europe forces substitution of legacy plasticizers in PVC shrink films, accelerating converter migration toward polyolefin alternatives that avoid Substance of Very High Concern classifications. China's SAMR enforces GB standards for food packaging plastics that mandate specific testing protocols for heavy metals and overall migration, creating divergent certification burdens for multinational film producers. Stakeholders must monitor how diverging national packaging extended producer responsibility schemes reshape the cost structure of virgin versus recycled-content film grades.
Market Dynamics
Mono-material polyolefin formulations are displacing multi-layer laminates as EU recyclability mandates tighten, forcing converters to redesign film architectures without sacrificing barrier performance or optical clarity.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets are accelerating converter migration toward compatible mono-material structures that simplify post-consumer sorting and reprocessing streams.
- E-commerce fulfillment automation:Pre-sized shrink bags are displacing manual wrapping stations in parcel consolidation centers, cutting labor cost per shipment and accelerating throughput.
- Food retail consolidation:Centralized procurement by large-format grocery chains is standardizing film specifications across multi-site distribution networks, favoring suppliers with national coverage.
Market Restraints
- Ethylene feedstock volatility:Crude-linked naphtha pricing swings compress margin predictability for non-integrated converters lacking captive resin supply.
- Mechanical recycling contamination limits:Cross-contamination between polyolefin grades and legacy PVC shrink films degrades reprocessed pellet quality, constraining closed-loop supply expansion.
- Heat-seal speed ceilings:Conventional polyolefin formulations hit throughput limits above 400 packages per minute on high-speed form-fill-seal lines, capping adoption in beverage bottling plants.
Strategic Opportunities
- Chemical recycling infrastructure:Pyrolysis and depolymerization investments in Germany and the Netherlands are creating outlets for mixed-flexible waste streams that mechanical sorting cannot valorize.
- Medical device sterilization packaging:Gamma-stable polyolefin shrink films are penetrating ethylene oxide and radiation sterilization workflows for surgical kits and implantable device kits.
- Extended Producer Responsibility schemes:France's Citeo and Italy's CONAI eco-modulated fees are rewarding high-recycled-content films with reduced compliance levies, creating price advantages for certified suppliers.
Industry Challenges
- Migration testing protocol divergence:FDA 21 CFR 177.1520, EU 10/2011, and China's GB 4806.7 impose incompatible additive notification requirements, multiplying certification costs for multinational film portfolios.
- Thin-gauge extrusion expertise scarcity:Operating stable bubble geometry below 12 micron thickness demands precise die gap control and melt homogeneity that legacy converter workforces rarely possess.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shrink Plastic Films Market |
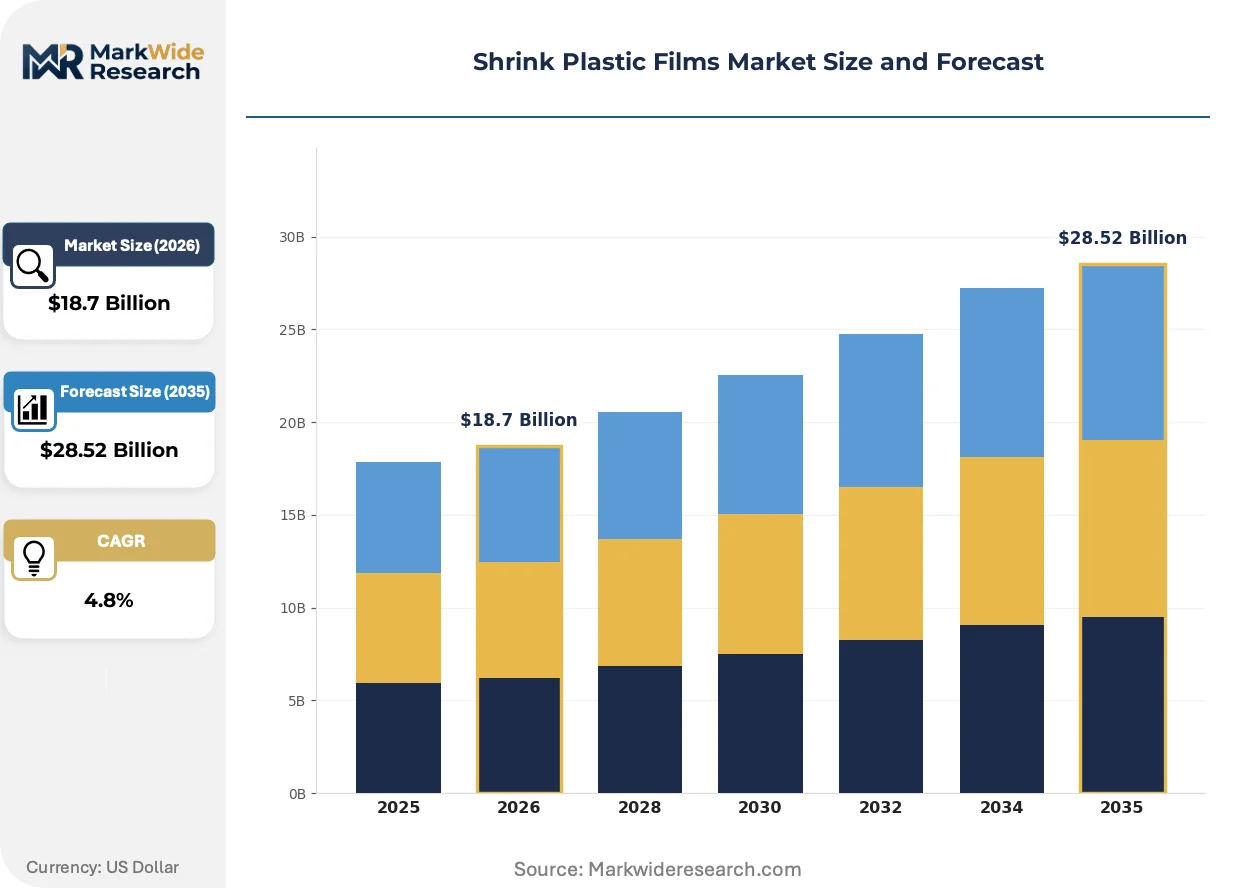
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyolefin, PVC, PET, Others End User: Food Packaging, Consumer Goods, Pharmaceuticals, Electronics Form: Rolls, Bags, Sheets, Tubing Thickness: Thin, Medium, Heavy, Ultra-thin |
| Companies Covered | RKW SE, Sealed Air Corporation, Amcor plc, Berry Global Inc, Coveris Holdings S.A., Clondalkin Group Holdings, Plastotecnica Spa, Sigma Plastics Group, Klöckner Pentaplast Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shrink Plastic Films Market Evolving Landscape
Film performance requirements are bifurcating between commodity clarity specifications and specialized functional grades, with equipment-film bundling emerging as the dominant lock-in mechanism for high-volume accounts.
Cross-linked polyolefin shrink film is consolidating position in high-abuse distribution environments. Palletized beverage loads and building materials shipments increasingly specify irradiated or peroxide-cross-linked grades that resist puncture propagation and seal fracture under stacking stress. Major retail distributors in Germany and the United States are consolidating supplier relationships around converters offering integrated wrapping equipment leases, compressing standalone film-only procurement.
REACH Substance of Very High Concern listings are accelerating PVC displacement in European shrink applications. Legacy phthalate plasticizers and heavy-metal stabilizers face authorization sunset dates, forcing meat and dairy processors toward polyolefin alternatives that avoid SVHC classification complexity. Converter technical service teams are expanding to manage formulation transitions without disrupting existing heat-tunnel operating windows.
Pre-sized bag formats are capturing share from centerfold rollstock in e-commerce parcel operations. Third-party logistics providers operating multi-tenant fulfillment centers in the Netherlands and California are specifying dimensionally precise shrink bags that eliminate manual measuring and cutting steps, compressing pack station cycle times. Equipment capital avoidance is driving adoption among mid-volume shippers lacking dedicated wrapping line infrastructure.
Shrink Plastic Films Market Segmentation
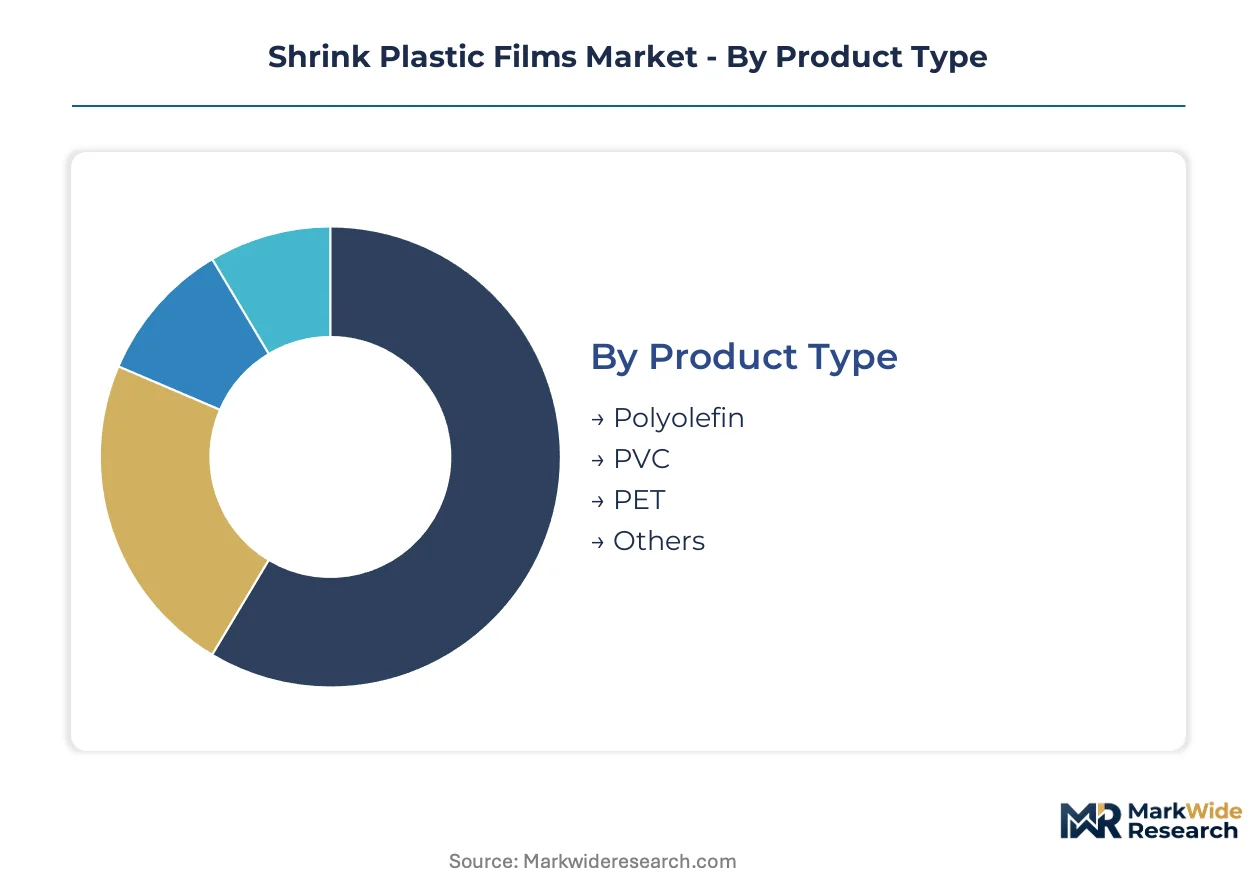
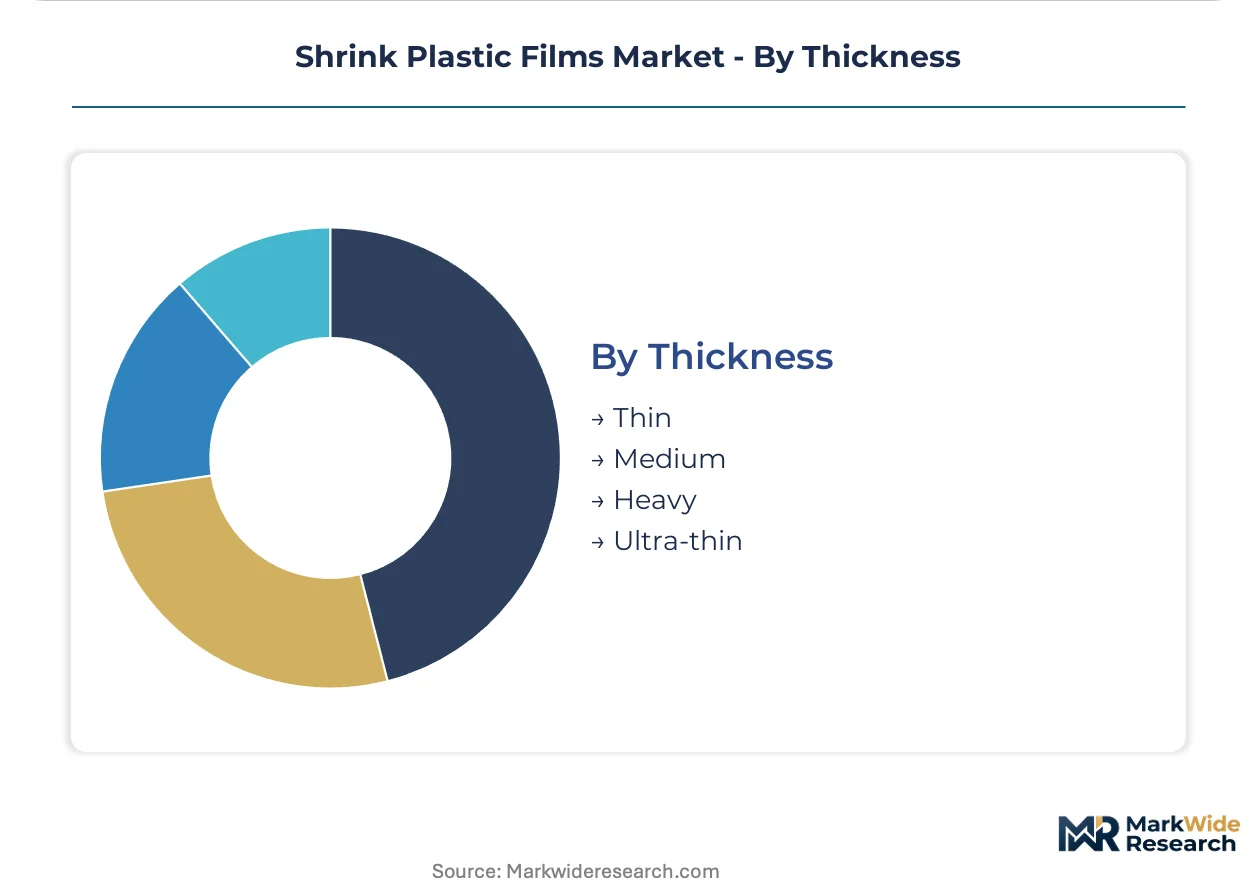
Segmentation in shrink plastic films reveals how material science, end-use requirements, and processing economics intersect to create distinct competitive battlegrounds. Each axis—chemistry, application, format, and gauge—carries unique margin profiles and technical barriers that reshape supplier positioning.
Product Type:
Material chemistry governs heat-seal performance, optical clarity, and recyclability compliance across regulatory jurisdictions.
- Polyolefin:Linear low-density polyethylene and polypropylene copolymers deliver superior seal strength above 400 packages per minute on high-speed lines. German meat processors and Dutch dairy cooperatives specify these grades to meet EU Packaging and Packaging Waste Regulation recyclability mandates without sacrificing shelf appeal.
- PVC:Legacy formulations retain cost advantages in static-sensitive electronics packaging where low surface resistivity matters. REACH Substance of Very High Concern listings for phthalate plasticizers and heavy-metal stabilizers are accelerating displacement toward polyolefin alternatives across European food-contact applications.
- PET:Biaxially oriented polyester films withstand gamma sterilization cycles for surgical kit packaging. Medical device manufacturers in Switzerland and the United States specify PET grades for implantable device kits requiring dimensional stability through ethylene oxide processing.
- Others:Polylactic acid and bio-based polyesters serve niche premium cosmetic applications in France where Citeo eco-modulated fees reward non-fossil feedstocks.
Polyolefin leads on scale; PET leads on momentum in medical sterilization workflows.
End User:
Application-specific performance requirements drive formulation differentiation and certification burdens.
- Food Packaging:Barrier against moisture and oxygen extension dominates retailer specifications. Automated wrapping lines in German meat processing plants consume premium cross-linked grades that resist puncture under pallet stacking stress.
- Consumer Goods:Multipack unitization for beverages and personal care products prioritizes optical clarity for shelf merchandising. Lightweight thin-gauge formulations reduce freight cost per thousand units in California distribution centers.
- Pharmaceuticals:Gamma-stable polyolefin shrink films penetrate radiation sterilization protocols for surgical kits. FDA 21 CFR 177.1520 migration limits directly shape antioxidant packages for domestic suppliers.
- Electronics:Anti-static PVC formulations protect circuit boards and semiconductor components from electrostatic discharge damage during transit.
Food packaging dominates volume concentration; pharmaceuticals posts the steepest expansion trajectory as sterilization packaging standards tighten.
Form:
Processing equipment compatibility and labor economics determine format selection across fulfillment environments.
- Rolls:Centerfold and single-wound rollstock feed continuous-flow wrapping machinery in high-volume beverage bottling plants. Capital-intensive equipment lines lock in converter relationships through integrated leasing arrangements.
- Bags:Pre-sized shrink bags eliminate manual measuring steps in e-commerce parcel consolidation. Third-party logistics providers in the Netherlands and California specify dimensionally precise formats to compress pack station cycle times without dedicated wrapping infrastructure.
- Sheets:Flat die-cut sheets serve industrial pallet covering and construction material protection where irregular load geometries resist tubular formats.
- Tubing:Continuous seamless tubing accommodates variable-length product runs in custom manufacturing and prototype fulfillment workflows.
Rolls anchor installed base economics; bags gain share fastest in automated fulfillment expansion.
Thickness:
Gauge selection balances material cost, freight efficiency, and mechanical abuse resistance in distribution channels.
- Thin:Sub-15 micron gauges reduce polymer mass per thousand units in lightweight beverage multipacks. Berry Global dominates this segment where freight economics favor minimized film mass.
- Medium:15-30 micron grades balance clarity and puncture resistance for standard retail multipack applications across grocery distribution networks.
- Heavy:Above-30 micron formulations withstand stacking stress in palletized building materials and agricultural supply shipments. Cross-linked polyolefin architectures prevent seal fracture under warehouse compression.
- Ultra-thin:Below-12 micron extrusion demands precise die gap control and melt homogeneity that legacy converter workforces rarely possess, creating capability scarcity among suppliers.
Medium gauges capture mainstream volume; ultra-thin formats face supply constraints from technical expertise gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized extrusion technicians and polymer engineers concentrate in Germany's industrial belt, anchoring Europe's technical leadership in high-performance shrink film formulations. This talent density shapes regional competitive advantages across formulation chemistry and thin-gauge processing expertise.
Germany
Automated meat and dairy processing plants in Lower Saxony and Bavaria drive premium cross-linked polyolefin consumption for palletized distribution. The EU Packaging and Packaging Waste Regulation mandates mono-material recyclability, forcing converters near Cologne to redesign multi-layer architectures. Technical service teams in the Ruhr industrial cluster manage heat-tunnel calibration for processors migrating from PVC.
United States
Centralized grocery chain procurement across the Midwest and Southeast standardizes film specifications for multi-site distribution networks. FDA 21 CFR 177.1520 migration limits shape antioxidant packages for domestic food-contact suppliers. E-commerce fulfillment centers in California's Inland Empire adopt pre-sized shrink bags to accelerate parcel consolidation without dedicated wrapping infrastructure.
China
SAMR's GB 4806.7 standards for food packaging plastics impose heavy metal and overall migration testing protocols that diverge from Western certification requirements. Yangtze River Delta converters supply lightweight beverage multipacks for domestic brands expanding cold-chain distribution. Technical expertise gaps below 12-micron extrusion create supply constraints for ultra-thin formats.
Netherlands
Third-party logistics providers operating multi-tenant fulfillment centers near Rotterdam specify dimensionally precise shrink bags to compress pack station cycle times. Chemical recycling infrastructure investments in Groningen and Limburg create pyrolysis outlets for mixed-flexible waste streams mechanical sorting cannot valorize. Dutch dairy cooperatives specify polyolefin grades meeting EU recyclability mandates.
India
BIS certification requirements for food-contact plastics multiply compliance burdens for multinational film portfolios entering the market. Maharashtra's beverage bottling plants consume medium-gauge rollstock for high-speed form-fill-seal operations. Converter technical capabilities concentrate in Gujarat's chemical processing corridor, though thin-gauge expertise remains limited.
Shrink Plastic Films Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers and end-use verticals. The vendor base spans resin-integrated multinationals, equipment-film bundlers, and regional converters serving single-country procurement networks. Three archetypes dominate: backward-integrated resin compounders securing margin control, thin-gauge specialists capturing freight-sensitive beverage accounts, and integrated equipment-film providers locking in high-volume grocery distribution centers. Competitive dynamics center on M&A-driven geographic expansion and captive resin supply investments.
Among European-based industrial packaging groups, RKW SE and Klöckner Pentaplast Group occupy positions anchored in specialized film extrusion capabilities. Sealed Air Corporation represents the equipment-film bundling archetype, while Amcor plc exemplifies backward-integrated resin control. Berry Global sits within the thin-gauge specialization tier. Coveris Holdings S.A., Clondalkin Group Holdings, Plastotecnica Spa, and Sigma Plastics Group each represent distinct regional or application-focused positioning strategies.
| Leading Market Players |
|---|
| RKW SE |
| Sealed Air Corporation |
| Amcor plc |
| Berry Global Inc |
| Coveris Holdings S.A. |
| Clondalkin Group Holdings |
| Plastotecnica Spa |
| Sigma Plastics Group |
| Klöckner Pentaplast Group |
| Others |
Value Network & Pricing Analysis
Ethylene feedstock volatility originating from crude-linked naphtha markets cascades through converter margins and downstream pricing tiers, with integrated resin compounders capturing cost advantages that non-integrated suppliers cannot match across German meat processing and Dutch dairy procurement networks.
Pricing Analysis
Bundled equipment-film service packages command premium positioning against standalone film procurement. Three-tier pricing structure across premium, standard, and economy levels separates cross-linked irradiated grades for palletized beverage loads from commodity clarity films for lightweight multipacks. Price differentiation rests on certification grade and volume scale, with FDA 21 CFR 177.1520 compliance tiers adding qualification overhead. Cost compression in standard polyolefin grades is intensifying because ethylene feedstock swings compress margin predictability for converters lacking captive resin supply. Large-format grocery chains exhibit lowest price sensitivity due to centralized procurement standardization, while mid-volume e-commerce shippers face acute pressure from freight economics favoring reduced film mass per unit.
Supply Chain Analysis
Dual-sourcing requirements mandated by large-format retail chains force converters to qualify secondary suppliers across Germany, the United States, and China. Raw material dependencies center on ethylene and propylene monomer feeds, antioxidant packages for migration compliance, and specialized cross-linking additives for high-abuse grades. Supply chain risk concentrates in tariff exposure on Chinese resin imports entering European compounding operations. Distribution runs through converter-direct relationships with grocery distribution centers and third-party logistics fulfillment networks, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU recyclability mandates under PPWR impose formulation costs that Asian converters avoid, creating margin expansion potential for suppliers with multi-regional certification capabilities.
For Market Incumbents: Extend backward integration into resin compounding to secure margin control on specialized polyolefin grades as ethylene feedstock volatility threatens converter profitability. Lock in high-volume grocery accounts through equipment-film bundling arrangements that raise switching costs against emerging thin-gauge specialists. Prioritize certification investment for FDA 21 CFR 177.1520 and EU 10/2011 compliance tiers to maintain access to centralized procurement networks. For New Entrants and Emerging Players: Third-party logistics providers operating multi-tenant fulfillment centers represent the most penetrable channel partner type for pre-sized shrink bag formats lacking dedicated wrapping infrastructure. Target California's Inland Empire and Netherlands Rotterdam corridor where e-commerce automation accelerates parcel consolidation demand. Pursue white-label supply agreements with regional beverage bottlers seeking lightweight thin-gauge alternatives to reduce freight cost per thousand units. For Investors and Strategic Acquirers: Consolidation pressure builds where technical expertise gaps below 12-micron extrusion create supply constraints that scaled players can exploit through capability acquisition. Long-term viability favors converters with integrated equipment-film bundling platforms and captive resin supply across the analysis window. Target acquisition archetype: thin-gauge specialists with stable bubble geometry expertise in Germany's industrial belt. Signal to watch: chemical recycling infrastructure commissioning in Groningen and Limburg creating pyrolysis outlets for mixed-flexible waste streams.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Secures margin control on specialized polyolefin grades for FDA-compliant food-contact applications. |
| Equipment-Film Bundling Arrangements | Raises switching costs for high-volume grocery distribution centers through integrated leasing platforms. |
| Pre-sized Shrink Bag Format Expansion | Captures e-commerce fulfillment automation demand in California and Netherlands logistics corridors. |
| Chemical Recycling Infrastructure Partnership | Creates pyrosis outlets for mixed-flexible waste streams that mechanical sorting cannot valorize. |
| Cross-linked Polyolefin Grade Development | Addresses pallet stacking stress requirements for German meat and dairy processing plants. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with film extrusion plant managers, procurement leads at meat and dairy processors, technical R&D directors at resin compounders, and channel partners in third-party logistics with secondary validation against customs/trade data, SEC 10-K filings, Cefic industry reports, and FDA/EU regulatory filings. Bottom-up volume modeling triangulated against top-down macroeconomic drivers.
Segment-weighting approaches distributed growth assumptions across material chemistry, end-use application, processing format, and gauge thickness dimensions throughout the forecast period. CAGRs derived from elasticity modeling against ethylene feedstock price indices, e-commerce parcel volume trajectories, and EU regulatory compliance cost curves. Industry-specific inputs included automated wrapping line throughput specifications and heat-tunnel calibration requirements for PVC-to-polyolefin migration scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PPWR recyclability mandate enforcement timelines and chemical recycling infrastructure commissioning delays. Deviation in ethylene feedstock volatility or REACH SVHC authorization sunset schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Africa BOPP Films Market
Plastic Packaging
Global Plastic Container Market
Plastic Packaging
Russia Plastic Packaging Market
Plastic Packaging
Plastic Corrugated Sheets Market
Plastic Packaging
North America Blow Molded Plastics Market
Plastic Packaging
Poland Plastic Bottles Market
Plastic Packaging
Blow Molded Plastics Market
Plastic Packaging
Thailand Plastic Bottles Market
Plastic Packaging
Mushroom Plastics Market
Plastic Packaging
Canada Plastic Bottles Market
Plastic Packaging
United States Plastic Packaging Films Market
Plastic Packaging
South America Polyethylene Terephthalate (PET) Market
Plastic Packaging
Plastic Packaging Market
Plastic Packaging
Folding Plastic Crates Market
Plastic Packaging
Global Plastic Packaging Sacks Market
Plastic Packaging
North America PET Bottle Market