
 Strip Pack Laminates Market | 2026-2036
Strip Pack Laminates Market Size, Share, and Industry Trends Forecast 2026-2036
Strip Pack Laminates Market Analytics
ISO 15378 certification for primary packaging materials is redrawing competitive boundaries in strip pack laminates. Amcor leverages its pharmaceutical-grade film extrusion network across multiple continents. Huhtamaki sustains leadership in cold-form foil laminates for moisture-sensitive drug formulations. Constantia Flexibles anchors European supply through dedicated healthcare packaging facilities in Austria and Germany.
Strip pack laminates are multilayer flexible structures, typically combining oriented polyamide or PET outer webs with aluminum foil cores and heat-seal lacquer coatings, produced via adhesive lamination or extrusion coating to achieve oxygen transmission rates below 0.1 cc/m²/day for pharmaceutical stability. The format dimension shows child-resistant and senior-friendly designs commanding premium positioning as regulatory agencies tighten poison-prevention standards. Composite material grades represent the fastest-growing structural category, displacing monolayer alternatives where barrier performance must coexist with downgauging targets. Application demand from pharmaceuticals dominates value generation, while food packaging segments compete on volume throughput with thinner gauge specifications.
US FDA 21 CFR Part 11 compliance requirements and EU MDR traceability provisions shape converter investment priorities, forcing documentation systems that link laminate batch records to finished package serialization. India's CDSCO has tightened packaging integrity standards for exported generics, redirecting subcontinent sourcing toward qualified laminate suppliers. ISO 15378, US FDA, and EU MDR collectively determine market access credentials. Stakeholders must monitor evolving child-resistance test protocols in major jurisdictions to preempt reformulation costs.
Market Dynamics
ISO 15378 certification requirements are compressing the qualified supplier base for pharmaceutical-grade strip pack laminates, forcing converters to consolidate extrusion and lamination capabilities under unified quality management systems or exit the regulated segment entirely.
Growth Catalysts
- EU Falsified Medicines Directive enforcement:Serialization mandates across European distribution channels are accelerating demand for certified barrier laminates with integrated tamper-evidence features.
- Unit-dose compliance packaging:Geriatric and pediatric medication adherence programs in Germany and France are driving specification upgrades toward child-resistant, senior-friendly strip pack formats.
- Aluminum foil core downgauging:Advanced cold-forming alloys are enabling thinner gauge structures without barrier degradation, reducing material intensity per thousand doses.
Market Restraints
- Aluminum price volatility:Primary metal cost swings transmit directly to laminate converters, compressing margin predictability for long-term pharmaceutical supply contracts.
- Adhesive supply concentration:Solvent-free polyurethane laminating adhesive production clusters in Germany and Austria, creating single-source vulnerability for pan-European converters.
- Monolayer substitution ceiling:High-barrier pharmaceutical applications cannot migrate to single-material structures without compromising oxygen transmission performance below 0.1 cc/m²/day.
Strategic Opportunities
- Central and Eastern European contract packaging expansion:Poland and Czech Republic are attracting pharmaceutical packaging investments from Western European brand owners seeking cost-advantaged, EU-regulated production.
- Biologic drug cold-chain compatibility:Strip pack laminates with enhanced thermal stability are capturing specification opportunities in temperature-sensitive monoclonal antibody packaging.
- Digital watermark integration:Covert authentication features embedded during extrusion coating are enabling brand protection value-adds beyond basic barrier function.
Industry Challenges
- ISO 15378 audit backlog:Certification body capacity constraints are extending qualification timelines for new laminate suppliers entering pharmaceutical supply chains.
- Legacy serialization line retrofitting:Existing slitting and pouching equipment requires hardware and software upgrades to achieve EU MDR traceability compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Strip Pack Laminates Market |
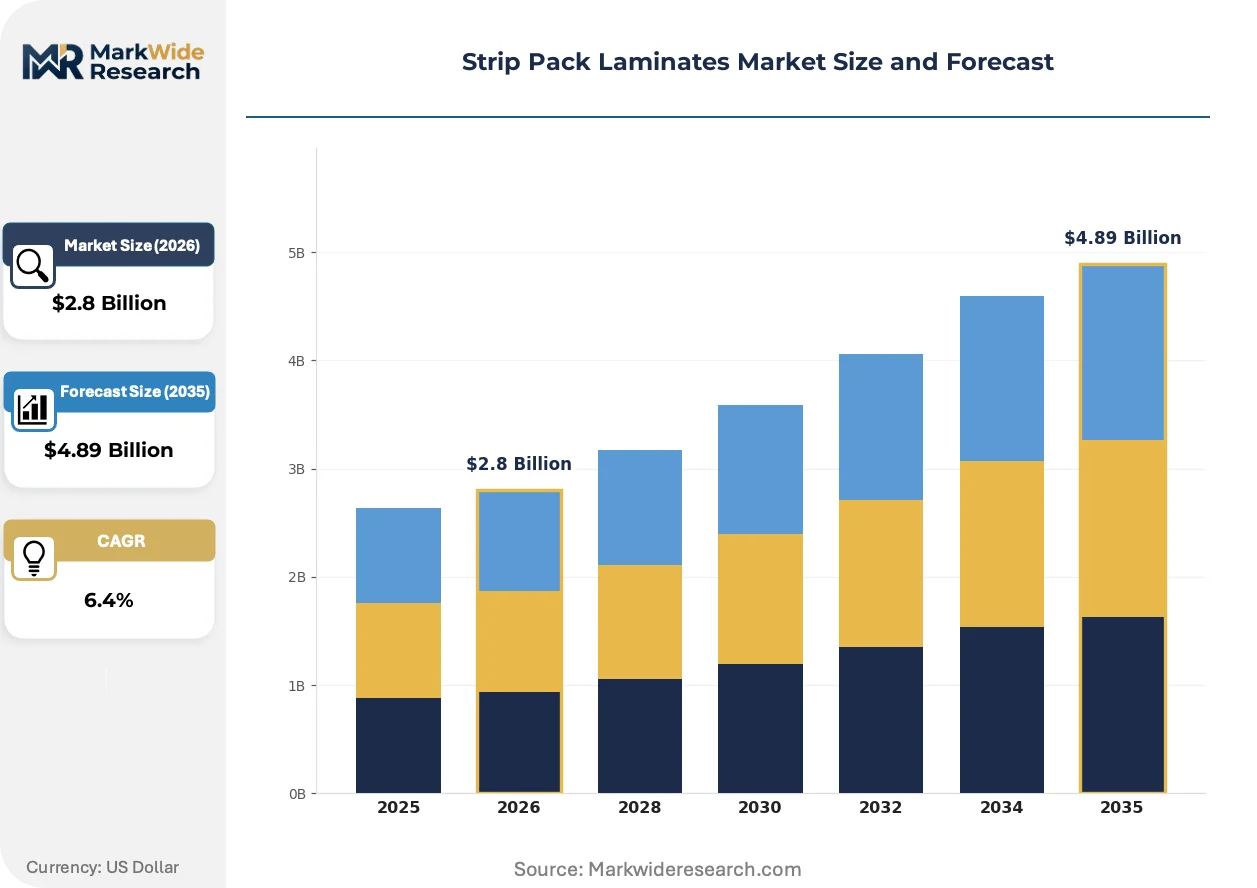
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polymer, Aluminum Foil, Paper, Composite Application: Pharmaceuticals, Food Packaging, Electronics, Consumer Goods End User: Healthcare, Food Industry, Retail Sector, E-commerce Format: Standard, Child-Resistant, Eco-Friendly, Customizable |
| Companies Covered | Amcor, Huhtamaki, UFlex, Constantia Flexibles, Glenroy, Winpak, ProAmpac, Sonoco, Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Strip Pack Laminates Market Evolving Landscape
Active pharmaceutical ingredient stability requirements are pushing laminate structures toward higher complexity, with converters integrating functional coatings and authentication layers that transform packaging from passive containment into an active compliance tool.
Coextruded barrier films with nanocomposite clay interlayers are displacing conventional adhesive-laminated structures in moisture-sensitive oral solid dosage applications. Mid-tier pharmaceutical contract packagers in Germany and the Netherlands are adopting these films to reduce lead times and eliminate solvent-based lamination emissions. The shift is compressing demand for standalone aluminum foil suppliers without integrated film extrusion capabilities.
EU MDR traceability provisions now require batch-level documentation linking laminate production records to finished package serialization. Converters serving pan-European distribution must implement manufacturing execution systems capable of real-time data capture and retention for minimum ten-year periods. Small and mid-sized laminate producers in Austria and Switzerland are prioritizing IT infrastructure investments ahead of capacity expansion.
Pharmaceutical procurement teams are consolidating supplier panels around converters offering integrated design, extrusion, and regulatory documentation services. This behavior is displacing traditional merchant market transactions where brand owners sourced aluminum foil, films, and adhesives separately. The concentration is most visible among German generic drug exporters supplying CDSCO-regulated markets, where single-source accountability reduces compliance risk exposure.
Strip Pack Laminates Market Segmentation
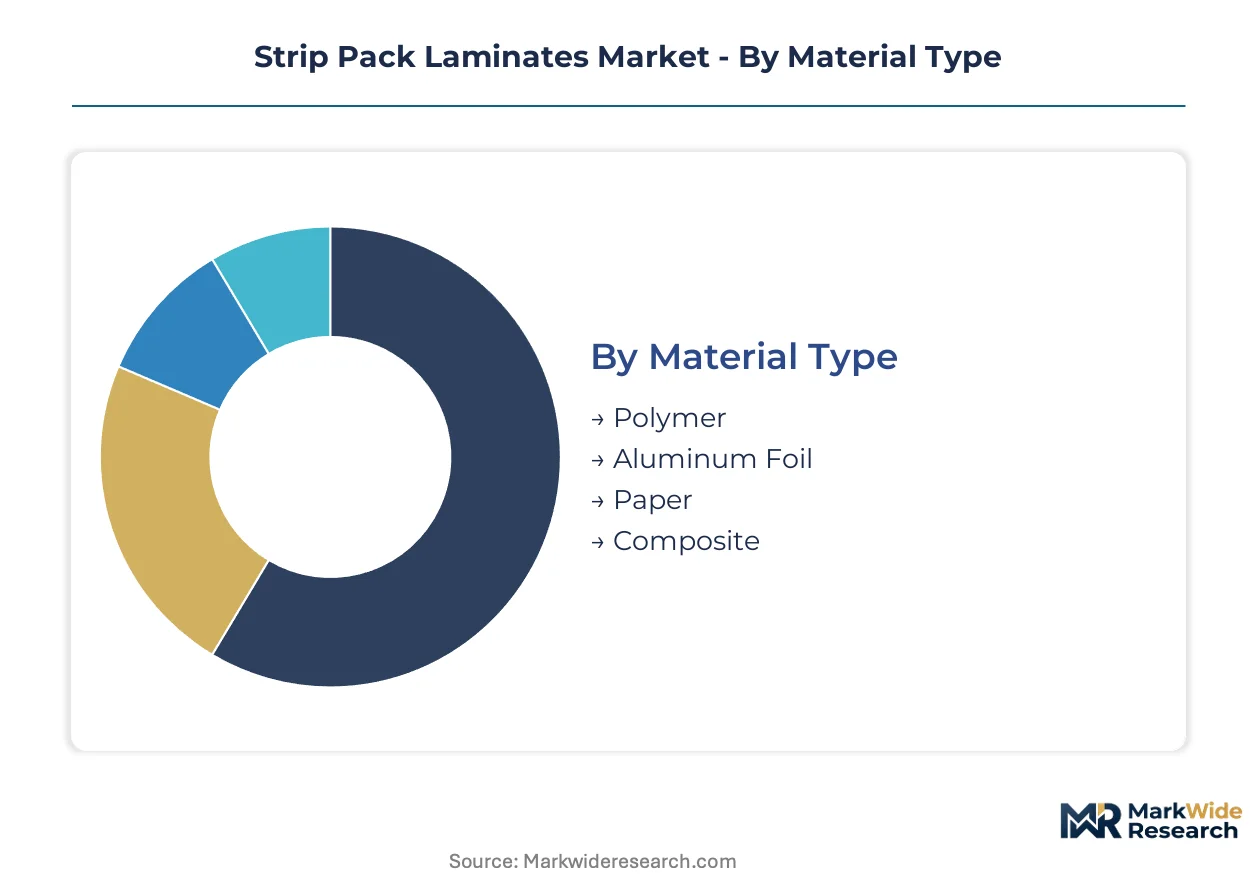
Strip pack laminates serve divergent performance requirements across pharmaceutical barrier protection, food shelf-life extension, and consumer goods presentation. Segmentation reveals how material specifications, regulatory compliance tiers, and end-use durability demands fragment converter capabilities and pricing architectures.
Material Type:
Domestic pharmaceutical production in Germany and Austria consumes premium aluminum-polymer laminates, while export-oriented converters in India and China compete on polymer-heavy structures for cost-sensitive food applications.
- Aluminum Foil:Cold-form alloys deliver oxygen transmission below 0.1 cc/m²/day for moisture-sensitive drug formulations. German contract packaging organizations specify this grade for pan-European distribution under EU Falsified Medicines Directive serialization mandates.
- Composite:Multilayer structures combining oriented polyamide, aluminum cores, and heat-seal lacquers displace monolayer alternatives where barrier performance must coexist with downgauging targets. Demand concentrates in Austrian healthcare packaging facilities serving biologic drug cold-chain requirements.
- Polymer:Coextruded barrier films with nanocomposite clay interlayers reduce lead times for mid-tier pharmaceutical contract packagers in the Netherlands.
- Paper:Fiber-based outer webs serve cosmetic and promotional strip packs where printability outweighs barrier function.
Aluminum foil commands the established base. The steepest expansion runs through composite structures.
Application:
Cost tier separation is pronounced: pharmaceutical specifications absorb three to four times the material cost per square meter versus food packaging volumes.
- Pharmaceuticals:Unit-dose compliance packaging for geriatric and pediatric adherence programs drives ISO 15378-certified laminate demand. French and German procurement teams consolidate supplier panels around converters offering integrated regulatory documentation.
- Food Packaging:Thinner gauge specifications compete on throughput volume with reduced barrier tolerances. Indian food exporters prioritize polymer-dominant laminates to manage landed cost in Middle Eastern retail channels.
- Electronics:Static-dissipative laminates protect sensitive components during Asia-Pacific manufacturing distribution.
- Consumer Goods:Cosmetic strip packs emphasize holographic and tactile surface finishes over functional barrier metrics.
Pharmaceuticals anchor margin concentration. Food packaging scales volume throughput fastest.
End User:
Customer type determines certification burden: healthcare procurement mandates batch-level traceability that retail and e-commerce channels rarely require.
- Healthcare:Hospital and pharmacy distribution networks in Germany specify child-resistant, senior-friendly formats with ten-year documentation retention under EU MDR provisions. CDSCO-regulated Indian generic exporters redirect sourcing toward qualified laminate suppliers with unified quality management systems.
- Food Industry:Pan-European brand owners seek cost-advantaged production from Polish and Czech Republic contract packaging investments.
- Retail Sector:Mass-market merchandisers prioritize shelf-impact graphics and supply continuity over technical barrier specifications.
- E-commerce:Direct-to-consumer shipment durability demands puncture-resistant outer webs without pharmaceutical-grade documentation overhead.
Healthcare dominates value extraction. E-commerce channels expand addressable volume most aggressively.
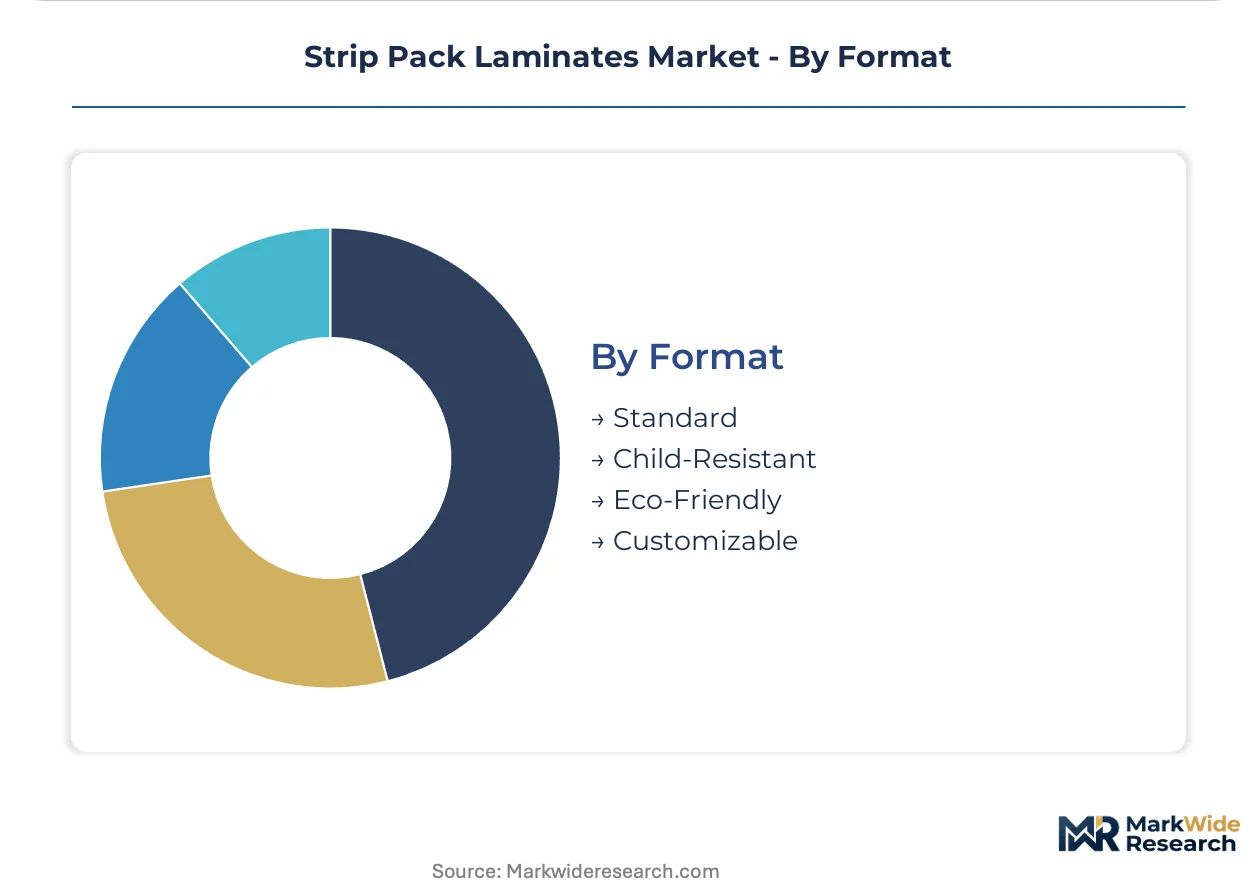
Format:
Supply concentration in German and Austrian adhesive production shapes format availability, with solvent-free polyurethane systems enabling compliant child-resistant structures.
- Child-Resistant:Senior-friendly opening mechanisms command premium positioning as poison-prevention standards tighten across US FDA and EU jurisdictions. Swissmedic and TGA protocols drive harmonized test method adoption.
- Eco-Friendly:Downgauged aluminum cores and recyclable polymer selections respond to EU Green Deal packaging waste directives.
- Standard:Conventional peel-open formats serve generic drug volumes where cost minimization outweighs regulatory premium.
- Customizable:Digital watermark integration and covert authentication features embed brand protection during extrusion coating.
Standard formats maintain volume dominance. Child-resistant specifications gain share fastest on regulatory compulsion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor positions Germany as the continental distribution hub for pharmaceutical-grade strip pack laminates serving pan-European supply chains.
Germany
Contract packaging organizations in Bavaria and Baden-Württemberg process unit-dose compliance orders for geriatric adherence programs. The country's national pharmaceutical regulator enforces serialization mandates under the EU Falsified Medicines Directive. Heidelberg and Mannheim host concentrated adhesive lamination clusters where solvent-free polyurethane systems enable child-resistant format production.
United States
FDA 21 CFR Part 11 compliance requirements drive specification upgrades for domestic generic drug manufacturers. The agency's poison-prevention standards tighten test protocols for senior-friendly opening mechanisms. New Jersey and Pennsylvania pharmaceutical corridors anchor North American demand for certified barrier structures with integrated tamper-evidence features.
India
CDSCO packaging integrity standards for exported generics redirect subcontinent sourcing toward qualified laminate suppliers. The regulator's tightened oversight compresses the vendor base for Western European-bound shipments. Ahmedabad and Mumbai pharmaceutical zones concentrate contract packaging investments serving Middle Eastern and African distribution channels.
Austria
Healthcare packaging facilities in Vienna and Linz supply biologic drug cold-chain compatible laminates across Central Europe. EMA-aligned quality management systems support pan-European traceability documentation. The country's ISO 15378-certified extrusion networks serve German generic exporters seeking unified batch record accountability.
Switzerland
Swissmedic protocols drive harmonized child-resistance test method adoption for premium pharmaceutical formats. Basel and Zurich clusters specialize in covert authentication layer integration during extrusion coating. The country's regulatory alignment with EU MDR provisions attracts brand protection investments from multinational drug manufacturers.
Strip Pack Laminates Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with publicly traded packaging conglomerates commanding pharmaceutical-grade volume while family-owned converters retain niche flexibility in regional food applications. The supplier base concentrates around converters offering unified extrusion, lamination, and regulatory documentation services. Three archetypes dominate: integrated film extruders with captive adhesive supply, merchant aluminum foil specialists seeking downstream integration, and healthcare-dedicated converters with dedicated cleanroom capacity. Competitive moves center on ISO 15378 certification acquisition and manufacturing execution system deployment for EU MDR traceability compliance.
Within the integrated multinational tier, Amcor and Huhtamaki exemplify scale-driven positioning across multiple continents, while Constantia Flexibles occupies a specialized position anchoring European healthcare supply through dedicated regional facilities. These three represent contrasting strategic postures: extrusion network breadth, cold-form foil laminate concentration, and geographic focus within regulated medical packaging corridors.
| Leading Market Players |
|---|
| Amcor |
| Huhtamaki |
| UFlex |
| Constantia Flexibles |
| Glenroy |
| Winpak |
| ProAmpac |
| Sonoco |
| Berry Global |
| Others |
Value Network & Pricing Analysis
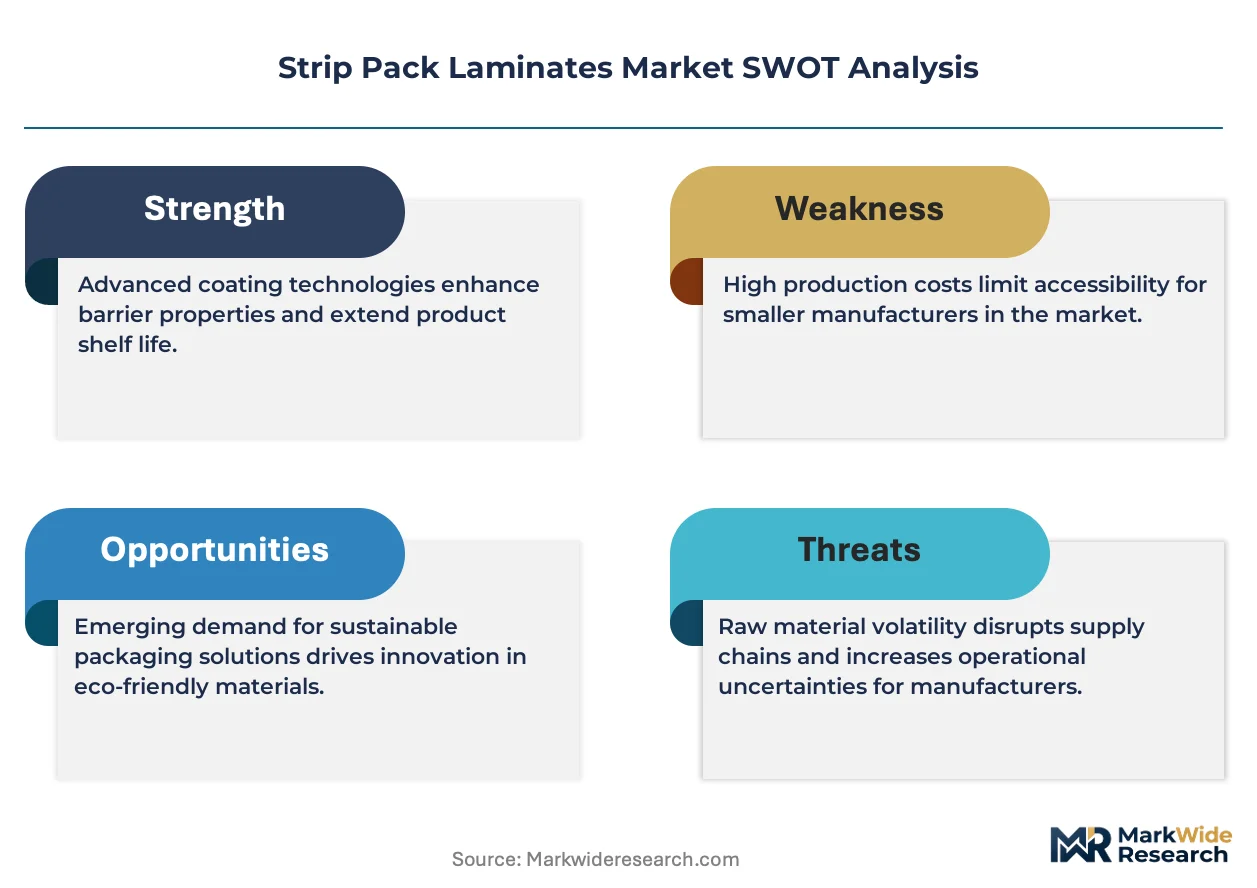
Capacity utilization at ISO 15378-certified extrusion facilities in Germany and Austria determines price floors across pharmaceutical-grade strip pack laminates, concentrating supply power among converters with unified quality management systems while marginalizing merchant aluminum foil suppliers lacking integrated film production.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 15378-certified pharmaceutical laminates from industrial food-grade specifications and commodity polymer-heavy alternatives. Price differentiation rests on certification grade and volume scale, with German contract packaging organizations absorbing premium positioning for EU MDR-compliant documentation. Cost compression in food packaging tiers is intensifying because Indian exporters prioritize landed cost management for Middle Eastern retail channels. Healthcare procurement teams show least price sensitivity where batch-level traceability reduces compliance risk exposure.
Supply Chain Analysis
Strategic stockpiling of cold-form aluminum alloys dominates converter inventory strategy, buffering against primary metal cost volatility that transmits directly to long-term pharmaceutical supply contracts. Supply concentrates in Germany, Austria, and India, with Heidelberg and Mannheim hosting adhesive lamination clusters and Ahmedabad serving export-oriented generic packaging. Raw material dependencies center on aluminum foil cores, solvent-free polyurethane laminating adhesives, and oriented polyamide films. Single-source vulnerability in German and Austrian adhesive production creates structural risk for pan-European converters. Distribution runs through the Rhine-Main-Danube waterway corridor serving pan-European pharmaceutical distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified supplier scarcity for pharmaceutical-grade strip pack laminates compresses the vendor base around converters with captive extrusion, lamination, and regulatory documentation capabilities, rewarding unified quality management system investments while penalizing fragmented supply chain sourcing.
For Market Incumbents: Consolidate extrusion and lamination capabilities under unified ISO 15378 quality management systems to preempt regulatory exclusion from EU MDR-compliant supply chains. Expand manufacturing execution system deployment for real-time batch record capture and ten-year documentation retention. Deepen backward integration into solvent-free polyurethane adhesive supply to mitigate single-source vulnerability from German and Austrian production concentration. For New Entrants and Emerging Players: Differentiate on biologic drug cold-chain compatibility specifications, targeting Austrian and Swiss healthcare packaging facilities serving temperature-sensitive monoclonal antibody demand. Penetrate Central and Eastern European contract packaging expansion in Poland and the Czech Republic, where Western European brand owners seek cost-advantaged EU-regulated production. Pursue digital watermark integration capabilities as a brand protection value-add beyond basic barrier function. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among healthcare-dedicated converters with dedicated cleanroom capacity and established pharmaceutical procurement panel positions. Long-term viability favors acquisition targets with ISO 15378 certification already achieved and EU MDR traceability infrastructure deployed. Monitor aluminum price volatility transmission to laminate converter margins as the primary inflection indicator for sector profitability compression.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15378 Certification Acquisition | Qualifies converters for EU Falsified Medicines Directive pharmaceutical supply chains. |
| Manufacturing Execution System Deployment | Enables real-time batch record linkage to finished package serialization under EU MDR. |
| Backward Integration into Adhesive Supply | Reduces single-source vulnerability from German and Austrian solvent-free polyurethane concentration. |
| Biologic Cold-Chain Format Development | Captures specification opportunities in temperature-sensitive monoclonal antibody packaging. |
| Digital Watermark Integration Capability | Embeds covert authentication features during extrusion coating for brand protection value-adds. |
Research Methodology
Desk research of pharmaceutical packaging regulatory filings, customs trade databases, and industry association technical standards preceded structured interviews with contract packaging organization procurement directors, laminate converter plant managers, pharmaceutical regulatory affairs leads, and healthcare distribution logistics specialists. Primary fieldwork combined with secondary validation from FDA 21 CFR Part 11 guidance documents, EMA MDR implementation guidelines, and CDSCO packaging integrity circulars. Bottom-up capacity modeling and top-down demand triangulation anchored volume and value estimates.
Variance decomposition across material type, application, end user, and format segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate aggregation with cross-validation against macroeconomic pharmaceutical expenditure trends. Forecast inputs incorporated aluminum price trajectory assumptions, EU MDR implementation timeline phasing, and serialization mandate enforcement intensity across European distribution channels.
The analysis sits within stated boundaries; outcomes outside sustained pharmaceutical packaging regulatory tightening or aluminum supply chain stability would require recalibration. Forecasts reflect assumptions regarding certification body audit capacity and converter IT infrastructure investment pacing. Revision becomes warranted when aluminum price volatility crosses thresholds that compress laminate converter margins beyond contract renegotiation flexibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Packaging Primers Market
Packaging Materials
VCI Shrink Films Market
Packaging Materials
Non-Plastic Punnets Market
Packaging Materials
Release Film for OCA Market
Packaging Materials
Primary Packaging Market
Packaging Materials
Disposable Icepacks Market
Packaging Materials
Laminated Tubes Market
Packaging Materials
Cash Management Supplies Packaging Market
Packaging Materials
Gift Wrapping Product Market
Packaging Materials
Lid Laminates Market
Packaging Materials
Thailand Packaging Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
Shrink Packaging Market
Packaging Materials
Tertiary Packaging Market
Packaging Materials
Greaseproof Sheets Market
Packaging Materials
PVC Packing Straps Market