
 Insulated Drum Covers Market | 2026-2036
Insulated Drum Covers Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Drum Covers Market Foresight
Asset-light leasing models for industrial thermal equipment is narrowing the capital barrier for mid-size chemical processors seeking temperature-controlled drum storage. Thermal Products Company leverages captive manufacturing of fiberglass-composite jackets to sustain margin control across North American chemical corridors. Insulated Products Corporation anchors its position through specialized neoprene formulations designed for sub-zero pharmaceutical logistics. Laird Thermal Systems differentiates via integrated heating-element designs that extend functional range beyond passive insulation.
Insulated drum covers are engineered thermal barriers, typically fabricated from layered composites such as fiberglass-reinforced polyester or closed-cell neoprene with aluminized reflective surfaces, designed to maintain stable internal temperatures for 55-gallon and intermediate bulk containers across variable ambient conditions. Standard covers dominate volume shipments due to their compatibility with universal drum dimensions, while custom solutions command premium positioning in pharmaceutical cleanrooms where validated temperature protocols are mandatory. Thermal jackets represent the fastest-expanding material category as processors replace fixed heating systems with portable, energy-efficient alternatives for seasonal viscosity management.
The US EPA enforces spill prevention and containment standards that elevate demand for sealed thermal protection in above-ground chemical storage, while OSHA workplace safety rules mandate surface-temperature limits on process equipment. The EU REACH framework restricts certain flame-retardant chemistries, pushing manufacturers toward halogen-free silicone and ceramic-fiber alternatives. Stakeholders must monitor evolving refrigerant-phase-down schedules and polymer-recycling mandates, as these will reshape material qualification requirements and retrofit timelines for installed drum cover fleets.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant-phase-down timelines, forcing chemical processors to replace fixed heating infrastructure with portable thermal jackets that eliminate refrigerant-dependent temperature control.
Growth Catalysts
- REACH compliance deadlines:German chemical manufacturers are accelerating thermal jacket procurement to meet ECHA-mandated containment standards for temperature-sensitive intermediates.
- Petrochemical corridor clustering:The US Gulf Coast concentration of specialty chemical production generates concentrated demand for validated drum insulation protocols.
- Neoprene formulation advances:Closed-cell elastomer composites with aluminized reflective layers now achieve sub-zero pharmaceutical logistics performance without active cooling.
Market Restraints
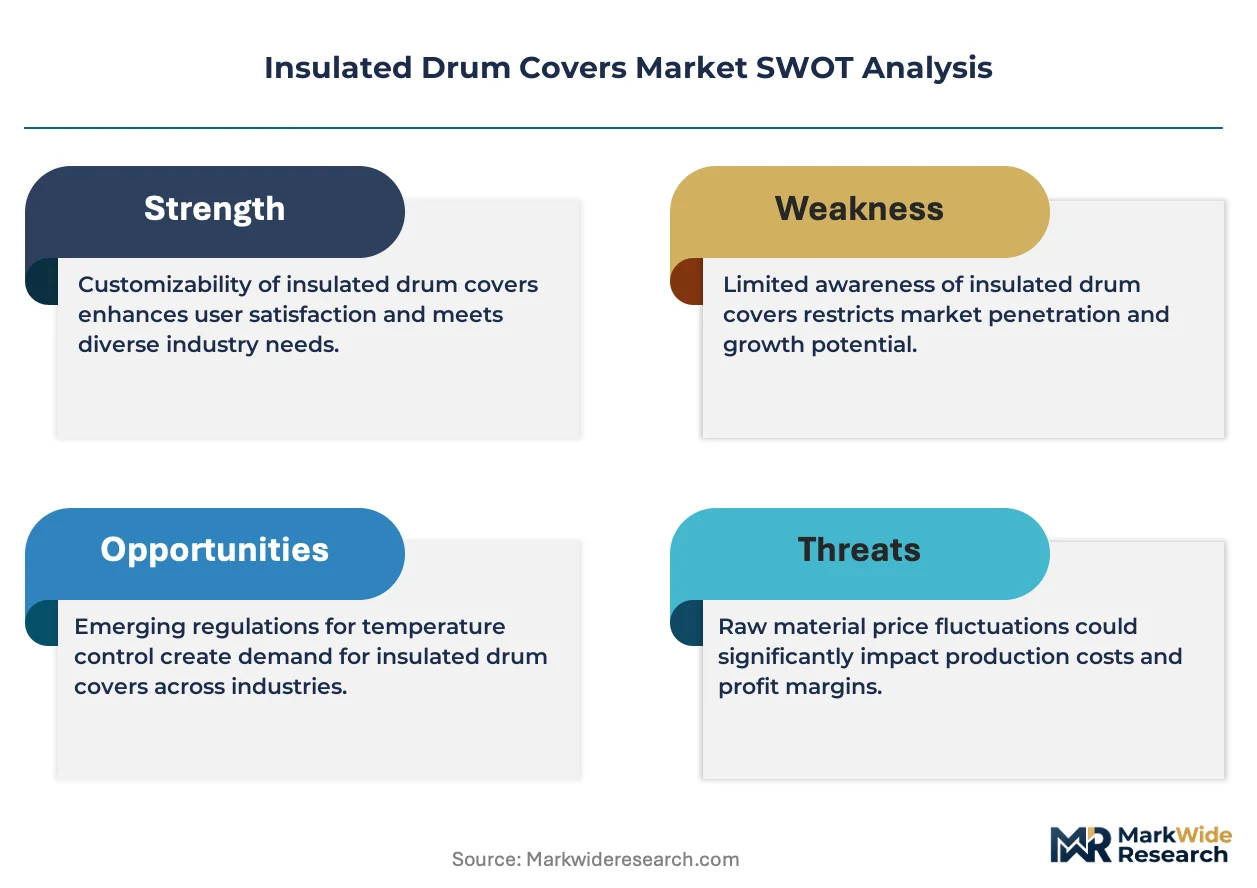
- Aluminum and silicone input volatility:Raw material price swings for reflective barrier metals and halogen-free elastomers compress margin predictability for jacket fabricators.
- Specialized neoprene supply concentration:Three Southeast Asian compounders control pharmaceutical-grade closed-cell formulations, creating single-source vulnerability.
- Fixed heating system inertia:Capital-intensive boiler infrastructure at legacy chemical plants delays portable thermal jacket adoption despite operational advantages.
Strategic Opportunities
- India PLI scheme alignment:Domestic chemical manufacturing incentives under the Production Linked Incentive framework are expanding temperature-controlled storage requirements for active pharmaceutical ingredients.
- Asset-light leasing models:Rental programs for seasonal viscosity management bypass capital approval cycles at mid-size processors.
- Heating-element integration:Convergence of passive insulation with resistive warming circuits extends functional range into cryogenic logistics applications.
Industry Challenges
- Pharmaceutical validation timelines:FDA and EMA temperature-protocol documentation requirements extend sales cycles for cleanroom-qualified covers.
- Composite recycling compliance:EU polymer-recycling mandates for fiberglass-reinforced polyester create end-of-life liability for installed drum cover fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Drum Covers Market |
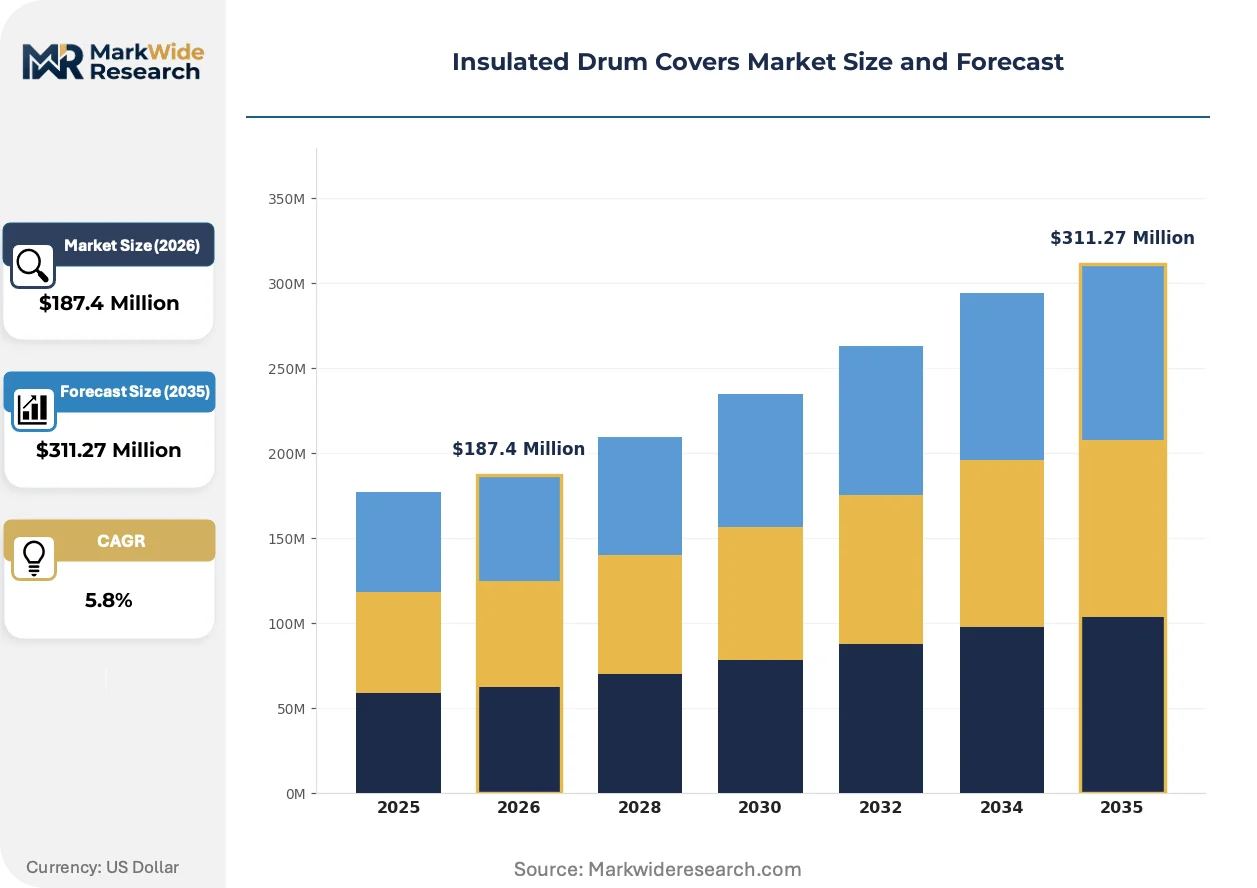
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Covers, Thermal Jackets, Custom Solutions, Replacement Liners Material: Polyester, PVC, Neoprene, Fiberglass End User: Food Processing, Chemical Manufacturing, Pharmaceuticals, Beverage Industry Application: Temperature Control, Energy Savings, Environmental Protection, Product Preservation |
| Companies Covered | Thermal Products Company, Insulated Products Corporation, Laird Thermal Systems, Apex Industries, Skolnik Industries, Cannon Instrument Company, LMK Thermosafe, Rimatek, Powerblanket, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Drum Covers Market Shifts & Advancements
Sensor-embedded thermal management is digitizing drum-level temperature monitoring, compressing the gap between passive insulation and active environmental control.
Phase-change material integration is digitizing thermal mass storage for 55-gallon containers, enabling pharmaceutical distributors to maintain cold-chain integrity during multi-day transit without powered refrigeration. Specialty logistics providers in the Benelux region are piloting these jackets for vaccine distribution.
The EU F-Gas Regulation is tightening containment standards for industrial thermal management, mandating refrigerant-free alternatives in chemical processing facilities. German processors are replacing fixed heating systems with portable thermal jackets to eliminate regulatory exposure.
Buyers are consolidating vendor relationships around integrated heating-element suppliers, displacing discrete procurement of passive covers and separate warming equipment. Petrochemical operators on the US Gulf Coast are negotiating multi-year thermal management contracts with single-source providers.
Insulated Drum Covers Market Segmentation
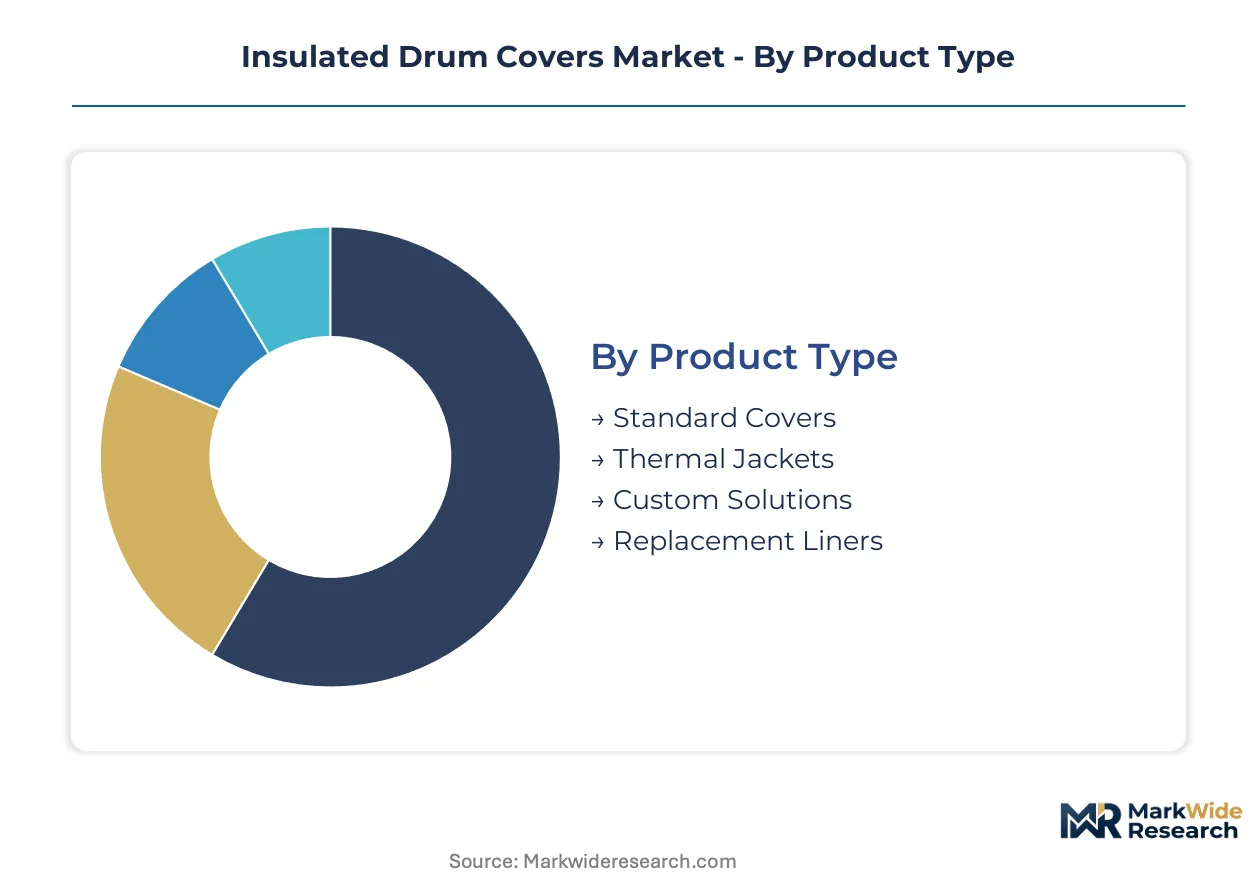
Segmentation in the insulated drum covers market reflects divergent technical requirements across passive thermal management and active heating applications. Procurement patterns vary sharply between seasonal viscosity management in chemical processing and year-round validated protocols in pharmaceutical logistics.
Product Type:
After-sales-service intensity escalates dramatically from passive standard covers through integrated heating-element systems requiring calibration support and warranty field service.
- Standard Covers:Universal-fit designs fabricated from layered fiberglass-reinforced polyester with aluminized reflective surfaces address ambient temperature stabilization for 55-gallon drums. Demand concentrates in US Gulf Coast petrochemical corridors where OSHA surface-temperature mandates drive bulk procurement for above-ground chemical storage.
- Thermal Jackets:Portable, zippered enclosures with closed-cell neoprene cores and adjustable heating-element pockets replace fixed boiler infrastructure. German chemical manufacturers under EU F-Gas Regulation pressure are accelerating adoption to eliminate refrigerant-dependent temperature control systems.
- Custom Solutions:Validated cleanroom-qualified covers with documented temperature protocols for pharmaceutical intermediates.
- Replacement Liners:Consumable barrier layers for thermal jacket refurbishment and end-of-life fleet renewal.
By volume, Standard Covers leads. By growth pace, Thermal Jackets is ahead.
Material:
Cost tier stratification separates commodity-grade synthetics from pharmaceutical-grade elastomers commanding premium positioning through specialized compounding expertise.
- Neoprene:Closed-cell elastomer formulations with aluminized reflective layers achieve sub-zero pharmaceutical logistics performance without active cooling. Three Southeast Asian compounders control pharmaceutical-grade supply, creating single-source vulnerability for FDA-validated cleanroom applications.
- Fiberglass:Reinforced polyester composites deliver structural rigidity and thermal resistance for industrial chemical storage. EU polymer-recycling mandates for fiberglass-reinforced polyester create emerging end-of-life liability for installed drum cover fleets.
- Polyester:Woven synthetic base layers for standard cover construction.
- PVC:Cost-competitive barrier films for general industrial temperature management.
Neoprene captures the premium tier. Fiberglass dominates volume shipments.
End User:
Application maturity varies from established chemical processing protocols to emerging pharmaceutical cold-chain requirements with extended validation timelines.
- Chemical Manufacturing:Seasonal viscosity management and ECHA-mandated containment standards for temperature-sensitive intermediates drive thermal jacket procurement. Asset-light leasing models are narrowing capital barriers for mid-size processors seeking temperature-controlled drum storage.
- Pharmaceuticals:FDA and EMA temperature-protocol documentation requirements extend sales cycles for cleanroom-qualified covers. Phase-change material integration is enabling multi-day transit cold-chain integrity without powered refrigeration.
- Food Processing:Temperature stability for edible oils and dairy intermediates during seasonal ambient variation.
- Beverage Industry:Fermentation temperature control and syrup viscosity management.
Chemical Manufacturing anchors current demand. Pharmaceuticals is climbing the fastest.
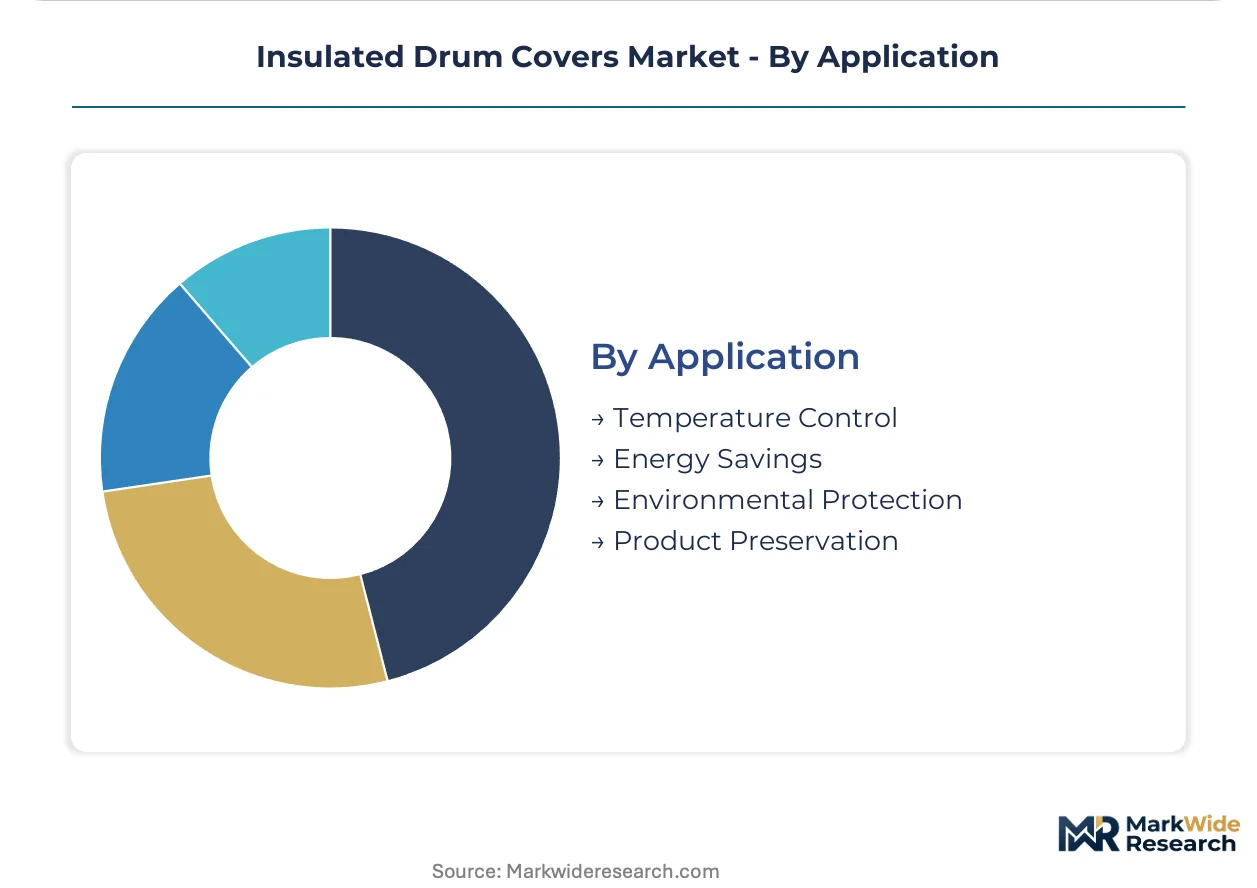
Application:
Customer type differentiation separates operational cost-reduction buyers from regulatory-compliance-driven procurement with distinct vendor relationship patterns.
- Temperature Control:Active and passive thermal management for viscosity maintenance and reaction stability across variable ambient conditions. Sensor-embedded designs are digitizing drum-level monitoring and compressing the gap between passive insulation and active environmental control.
- Product Preservation:Cold-chain integrity for pharmaceutical intermediates and temperature-sensitive biological materials. Benelux specialty logistics providers are piloting phase-change material jackets for vaccine distribution networks.
- Energy Savings:Reduced heating loads and eliminated fixed boiler operation.
- Environmental Protection:Spill containment and EPA-compliant sealed thermal protection.
Temperature Control leads by installed base. Product Preservation shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation is compressing refrigerant-phase-down timelines across industrialized economies, redirecting capital toward portable thermal management solutions. Chemical processors in Germany and the United States are replacing fixed heating infrastructure with jacket-based alternatives. Pharmaceutical cold-chain requirements in India and Japan are accelerating validated cover procurement.
United States
OSHA surface-temperature mandates and EPA spill-prevention standards drive bulk procurement for above-ground chemical storage. The US Gulf Coast petrochemical corridor concentrates demand for validated drum insulation protocols among specialty chemical producers. Houston-area processors are negotiating multi-year thermal management contracts with integrated heating-element suppliers.
Germany
ECHA-mandated containment standards for temperature-sensitive intermediates accelerate thermal jacket procurement among chemical manufacturers. The EU F-Gas Regulation forces elimination of refrigerant-dependent temperature control systems in industrial facilities. BASF-Ludwigshafen and Bayer-Leverkusen clusters are piloting sensor-embedded covers for real-time viscosity monitoring.
India
Domestic chemical manufacturing incentives under the PLI scheme expand temperature-controlled storage requirements for active pharmaceutical ingredients. CDSCO cold-chain validation protocols extend sales cycles for cleanroom-qualified covers. Maharashtra and Gujarat pharmaceutical corridors are adopting asset-light leasing models for seasonal API storage.
Japan
PMDA temperature-protocol documentation requirements drive premium positioning for validated pharmaceutical logistics covers. METI energy-efficiency standards encourage displacement of fixed boiler infrastructure with portable thermal alternatives. Osaka-Kobe chemical processors are integrating phase-change material jackets for biological intermediate distribution.
United Kingdom
EMA-aligned temperature validation requirements post-Brexit sustain demand for documented cold-chain integrity solutions. HSE workplace safety rules mandate surface-temperature limits on process equipment in chemical handling facilities. Teesside and Humber industrial clusters are retrofitting drum fleets with halogen-free silicone alternatives to meet evolving polymer-recycling mandates.
Insulated Drum Covers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The vendor base stratifies between captive-manufacturing integrated suppliers and outsourced-fabrication distributors. Three archetypes dominate: fiberglass-composite specialists, neoprene-formulation experts, and heating-element integrators. Capacity expansion and strategic technology licensing represent the primary competitive vectors as firms seek to differentiate beyond commodity jacket fabrication.
Among North American fabricators, Thermal Products Company exemplifies the captive-manufacturing archetype through in-house fiberglass-composite production, while Insulated Products Corporation occupies a position within specialized elastomer formulation. Laird Thermal Systems represents the convergence archetype, integrating resistive warming circuits with passive insulation substrates. These three firms anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Thermal Products Company |
| Insulated Products Corporation |
| Laird Thermal Systems |
| Apex Industries |
| Skolnik Industries |
| Cannon Instrument Company |
| LMK Thermosafe |
| Rimatek |
| Powerblanket |
| Others |
Supply & Pricing Matrix
Overcapacity in Southeast Asian neoprene compounding is compressing margin capture for pharmaceutical-grade thermal jacket fabricators, forcing tiered pricing discipline across certification levels while accelerating backward integration moves among North American specialists seeking input cost stability.
Pricing Analysis
Certification level creates the primary spread across the insulated drum covers market, with FDA-validated cleanroom-qualified covers commanding substantial premiums over standard OSHA-compliant industrial variants. Three-tier pricing structure across premium, standard, and economy levels reflects this divergence, where pharmaceutical-grade neoprene formulations with documented temperature protocols price distinctly from commodity fiberglass-reinforced polyester alternatives. Pricing pressure stems from aluminum and silicone input volatility, which compresses margin predictability for jacket fabricators serving mid-size chemical processors. Chemical manufacturing procurement teams exhibit highest price sensitivity due to capital approval cycles, while pharmaceutical logistics buyers prioritize validation documentation over unit cost.
Supply Chain Analysis
Upstream feedstock concentration in Malaysia, Thailand, and Indonesia controls pharmaceutical-grade closed-cell neoprene formulations, creating single-source vulnerability for FDA-validated applications. Raw material dependencies center on aluminized reflective metals, halogen-free silicone elastomers, and fiberglass-reinforced polyester composites. Supply chain risk manifests as specialized neoprene supply concentration, with tariff exposure on Southeast Asian chemical imports amplifying cost unpredictability. Distribution runs through industrial equipment distributors and direct OEM relationships, with multi-year thermal management contracts consolidating vendor relationships around integrated heating-element suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insulated drum covers market functions as a service-attach opportunity where calibration support and warranty field service for integrated heating-element systems expand faster than passive cover hardware sales, rewarding vendors who bundle recurring-revenue service layers.
For Market Incumbents: Insulate margin position through captive manufacturing of fiberglass-composite jackets and specialized neoprene formulations that resist commoditization pressure from emerging Asian fabricators. Deepen backward integration into halogen-free silicone alternatives ahead of EU polymer-recycling mandates. Prioritize certification investment for FDA and EMA temperature-protocol documentation to extend competitive moats in pharmaceutical logistics. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-aligned chemical manufacturing corridor, where domestic API production incentives generate unmet demand for asset-light leasing models. Target mid-size processors in Maharashtra and Gujarat with rental programs that bypass capital approval friction. Pursue sensor-embedded cover development as a differentiated entry vector against established passive insulation suppliers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among heating-element integrators with calibration service contracts, making this archetype the preferred acquisition target for cash-flow-quality-focused portfolios. Long-term viability hinges on regulatory tailwinds from refrigerant-phase-down schedules and cold-chain validation requirements. Watch for inflection in pharmaceutical distributor adoption of phase-change material jackets as a signal of technology transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Neoprene Compounding | Captive supply of pharmaceutical-grade formulations eliminates Southeast Asian single-source vulnerability for FDA-validated covers. |
| Sensor-Embedded Cover Development | Real-time temperature monitoring bridges passive insulation and active control, opening premium positioning in German chemical clusters. |
| Asset-Light Leasing Program Launch | Rental models for seasonal viscosity management unlock mid-size processor segments with constrained capital approval cycles. |
| Phase-Change Material Integration | Multi-day transit cold-chain capability without powered refrigeration addresses vaccine distribution requirements in Benelux logistics networks. |
| Halogen-Free Silicone Transition | EU REACH compliance and polymer-recycling mandate alignment future-proofs installed fleet liability for Teesside industrial clusters. |
Research Methodology
Desk research of customs trade databases, chemical industry association filings, and regulatory submission records preceded structured interviews with plant engineers at Gulf Coast petrochemical facilities, procurement leads at pharmaceutical distributors, thermal jacket fabricators, and aftermarket service heads. Primary fieldwork with maintenance directors and OEM procurement teams was cross-validated against secondary sources including EPA enforcement data, ECHA REACH registrations, and SEC filings from listed chemical processors. Bottom-up unit economics and top-down market sizing were triangulated to establish volume and value estimates.
Assumptions around EU F-Gas Regulation enforcement timelines, PLI scheme disbursement rates in India, and pharmaceutical cold-chain validation adoption curves were held fixed across baseline scenarios while aluminum and silicone price volatility bands were stress-tested. Segmentation modeling incorporated product type, material grade tier, end-use industry, and regional production hub dimensions. CAGRs were derived from installed base growth, replacement cycle compression, and technology substitution rates for integrated heating-element systems.
Stress conditions across raw material price swings, regulatory phase-down acceleration, and pharmaceutical validation timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including single-source neoprene supply disruption and composite recycling compliance cost inflation. Cross-checking against IEA industrial energy-efficiency benchmarks and Cefic chemical production data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Asia-Pacific Warehouse Drums and Barrel Market
Industrial Packaging
Dunnage Trays Market
Industrial Packaging
MENA Industrial Packaging Market
Industrial Packaging
Global Dunnage Packaging Market
Industrial Packaging
Rigid IBC Market
Industrial Packaging
Indonesia Industrial Packaging Market
Industrial Packaging
Fiber Drums Market
Industrial Packaging
Industrial Jugs Market
Industrial Packaging
Corrugated Automotive Packaging Market
Industrial Packaging
Transport Racks Market
Industrial Packaging
Middle East and Africa Octabin Market
Industrial Packaging
Industrial Chemical Packaging Market
Industrial Packaging
Slip Sheets Market
Industrial Packaging
Industrial Plastic Bags Market
Industrial Packaging
Corrugated Octabins Market
Industrial Packaging
Cone Bottom Tank Market