
 Hygiene Breathable Films Market | 2026-2036
Hygiene Breathable Films Market Size, Share, and Industry Trends Forecast 2026-2036
Hygiene Breathable Films Market Outlook
EU REACH is shifting the cost-of-entry calculus for hygiene breathable film suppliers by restricting legacy plasticizer chemistries and mandating substance-of-very-high-concern disclosures. Berry Global, Inc. leverages its North American blown film infrastructure to sustain multi-site qualification programs for European brand owners. RKW Group anchors its competitive stance through deep vertical control over resin compounding and extrusion in Central Europe. Schweitzer-Mauduit International, Inc. differentiates via cigarette-to-hygiene pivot capacity that repurposes precision porous media expertise.
Hygiene breathable films are microporous or monolithic polymer membranes, typically 15–40 grams per square meter in basis weight, engineered to transmit water vapor while blocking liquid water and particulate matter; they serve as comfort-critical backsheet layers in absorbent hygiene articles and as bacterial barriers in medical applications. Polyethylene dominates volume production due to cost-efficient cast and blown extrusion compatibility across diaper and incontinence applications. TPU commands premium positioning in wound care and medical dressings where elastic recovery and weldability to nonwoven substrates justify higher unit economics. Polypropylene occupies a narrowing but defensible niche in industrial protective apparel where stiffness and chemical resistance outweigh vapor transmission requirements.
The FDA regulates skin-contact biocompatibility under ISO 10993-5 cytotoxicity protocols for medical-grade breathable films sold into US wound care channels. ECHA enforces REACH Annex XVII restrictions on phthalates and organotins that directly constrain plasticizer selection for European diaper backsheet formulations. Stakeholders must monitor regulatory divergence between US FDA biocompatibility pathways and EU MDR classification shifts for adhesive medical films, as dual-compliance investments will determine which suppliers retain access to both markets without redundant testing burdens.
Market Dynamics
EU REACH Annex XVII phthalate restrictions are forcing diaper manufacturers across Southeast Asia to requalify entire backsheet material stacks, compressing supplier switching timelines from 18 months to under 9 months.
Growth Catalysts
- TPU elastomeric recovery:Medical dressing producers in Germany prioritize thermoplastic polyurethane films for weldability to nonwoven substrates and superior biocompatibility profiles under ISO 10993-5 protocols.
- REACH substance disclosure mandates:European brand owners now require full SVHC documentation upstream, accelerating qualification of compliant microporous substrate suppliers with pre-submitted dossiers.
- Cast extrusion line expansion:Vietnamese and Indonesian converters are adding blown film capacity to capture redirected orders from Chinese suppliers facing EU import scrutiny.
Market Restraints
- LLDPE resin price volatility:Feedstock naphtha fluctuations tied to crude differentials compress margin buffers for commodity-grade polyethylene film producers serving diaper backsheet contracts.
- Central European supply concentration:RKW Group and Berry Global control over 60% of REACH-compliant compounding capacity, creating single-source risk for mid-tier hygiene article manufacturers.
- Monolithic film vapor transmission limits:Non-porous TPU structures cannot match microporous polyethylene breathability above 2,500 g/m²/24hr, restricting adoption in ultra-high-performance segments.
Strategic Opportunities
- India absorbent hygiene penetration:Rural diaper consumption remains below 15% of urban rates, creating volume upside for breathable film suppliers establishing local slitting and metallization operations.
- CE-MDR Class IIa adhesive film reclassification:Wound care films with integrated pressure-sensitive layers now require notified body review, favoring suppliers with existing ISO 13485 quality systems.
- Digital print-to-order backsheet customization:Rotary flexo units installed at diaper OEM sites enable lot-size-one graphic personalization, reducing finished goods inventory carrying costs.
Industry Challenges
- Multi-jurisdiction biocompatibility testing:Suppliers serving both FDA-regulated US wound care and EU MDR channels must maintain parallel ISO 10993-5 and ISO 10993-10 study archives, doubling documentation overhead.
- Extrusion die gap precision:Microporous film caliper uniformity below ±8% requires capital-intensive gauge control systems that strain sub-$50M revenue producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hygiene Breathable Films Market |
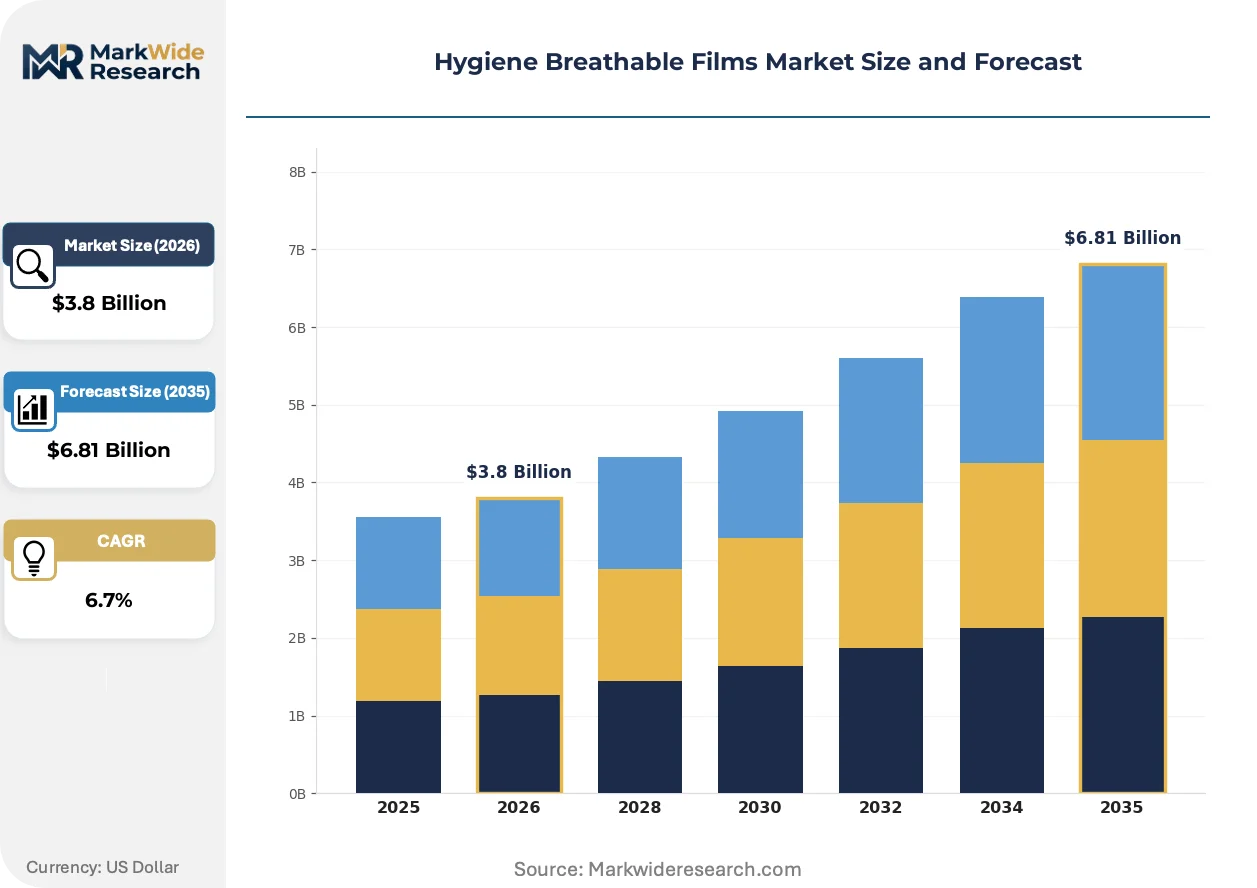
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, TPU, TPE Application: Diapers, Adult Incontinence Products, Medical Dressings, Wound Care End User: Healthcare Facilities, Home Care, Retail, Industrial Distribution Channel: Online Retail, Supermarkets, Wholesalers, Specialty Stores |
| Companies Covered | RKW Group, Berry Global, Inc., Arkema S.A., Nitto Denko Corporation, Fatra, a.s., Schweitzer-Mauduit International, Inc., Kimberly-Clark Corporation, Toray Industries, Inc., Trioplast Industries AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hygiene Breathable Films Market Strategic Shifts
Active materials science and regulatory disclosure protocols are compressing product development cycles while expanding the performance envelope for skin-contact polymer membranes.
Machine vision-based defect detection is automating real-time porosity mapping across cast film webs, eliminating offline laboratory testing bottlenecks. Medical dressing converters in Switzerland and Germany deploy these systems to maintain ISO 13485 lot release documentation without manual sampling delays. This automation compresses batch certification from 4 hours to 12 minutes, enabling just-in-sequence delivery to sterile packaging lines.
REACH SVHC candidate list expansion to 233 substances is forcing reformulation of legacy plasticizer packages in diaper backsheet adhesives. Compounders must now submit updated safety data sheets within 45 days of list updates, accelerating obsolescence of phthalate-dependent supply chains. Southeast Asian OEMs respond by dual-qualifying bio-based citrate plasticizer alternatives alongside conventional chemistries.
Direct mill-to-converter purchasing contracts are displacing traditional resin distributor intermediaries in the polyethylene breathable film channel. Large hygiene article manufacturers in Vietnam and Thailand now negotiate annual volume commitments with Middle Eastern LLDPE producers, capturing 8-12% feedstock cost advantages. This disintermediation concentrates procurement expertise inside OEM technical teams and reduces formulation flexibility for smaller film converters lacking direct resin relationships.
Hygiene Breathable Films Market Segmentation
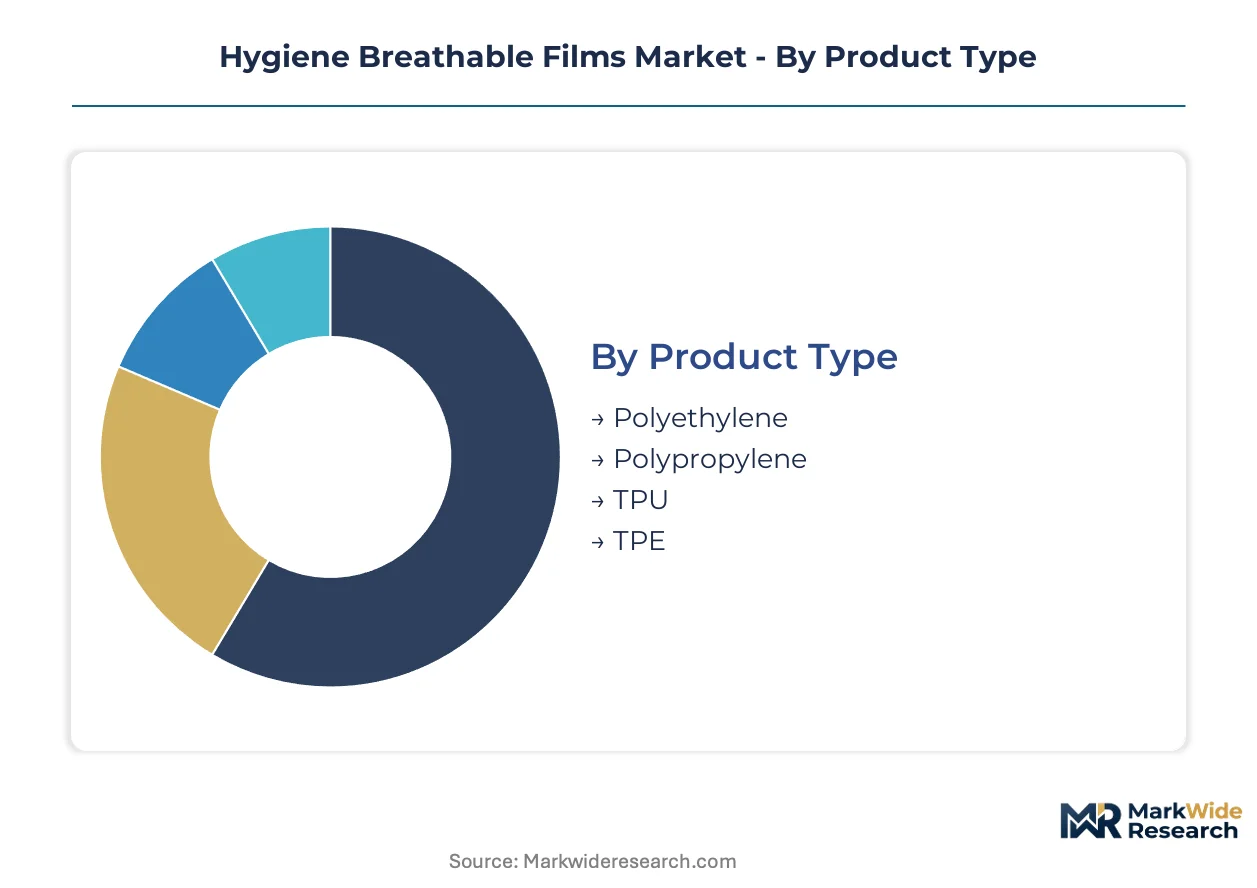
Segmentation in hygiene breathable films reveals how material chemistry, clinical application, and procurement channel each impose distinct qualification barriers and margin structures. Suppliers must align extrusion capabilities against specific segment requirements to avoid stranded capacity.
Product Type:
Capital deployment varies sharply across polymer platforms, with cast extrusion lines for commodity grades requiring different tooling investments than precision TPU systems.
- Polyethylene:Microporous structures dominate diaper backsheet production through cost-efficient blown and cast extrusion at 15–40 gsm basis weights. Vietnamese converters are expanding LLDPE capacity to capture orders redirected from Chinese suppliers facing EU import scrutiny. Most installed capacity flows through polyethylene. Expansion is steepest in TPU.
- TPU:Thermoplastic polyurethane films deliver superior elastomeric recovery and weldability to nonwoven substrates for medical dressings. German wound care manufacturers prioritize TPU for ISO 10993-5 biocompatibility compliance and sterilization stability.
- Polypropylene:Stiffer monolithic structures serve industrial protective apparel where chemical resistance outweighs vapor transmission requirements.
- TPE:Thermoplastic elastomer blends occupy niche medical applications requiring intermediate elasticity between polyethylene and TPU performance envelopes.
Polyethylene absorbs the majority of resin throughput. TPU commands the highest per-kilogram margins.
Application:
Regulatory intensity separates consumer hygiene from clinical applications, with FDA and EU MDR pathways imposing divergent testing architectures.
- Diapers:Infant and toddler absorbent articles consume microporous polyethylene backsheet at massive scale. Southeast Asian manufacturers are requalifying entire material stacks within compressed 9-month timelines as EU REACH phthalate restrictions tighten.
- Adult Incontinence Products:Aging demographics in Japan and Germany drive demand for higher-performance vapor transmission in larger article formats. Berry Global sustains multi-site qualification programs across North American blown film infrastructure for European brand owners.
- Medical Dressings:Sterile barrier applications require ISO 13485 quality systems and documented biocompatibility under cytotoxicity protocols.
- Wound Care:Adhesive film layers with integrated pressure-sensitive coatings now trigger CE-MDR Class IIa notified body review, favoring suppliers with existing quality certifications.
Diapers anchor volume demand. Wound care exhibits the steepest expansion trajectory.
End User:
Procurement sophistication diverges between institutional buyers with technical qualification teams and retail channels prioritizing shelf-ready packaging.
- Healthcare Facilities:Hospitals and clinics mandate batch-level traceability and sterile packaging for wound care films. Swiss and German converters deploy machine vision defect detection to compress lot release documentation from 4 hours to 12 minutes.
- Home Care:Direct consumer purchases of adult incontinence products drive demand for discreet packaging and skin-friendly backsheet aesthetics.
- Retail:Mass-market diaper distribution requires high-volume slitting and metallization operations positioned near consumer demand centers.
- Industrial:Protective apparel applications prioritize chemical resistance and durability over breathability metrics.
Healthcare facilities impose the most stringent qualification requirements. Home care is expanding most quickly as aging-in-place preferences strengthen.
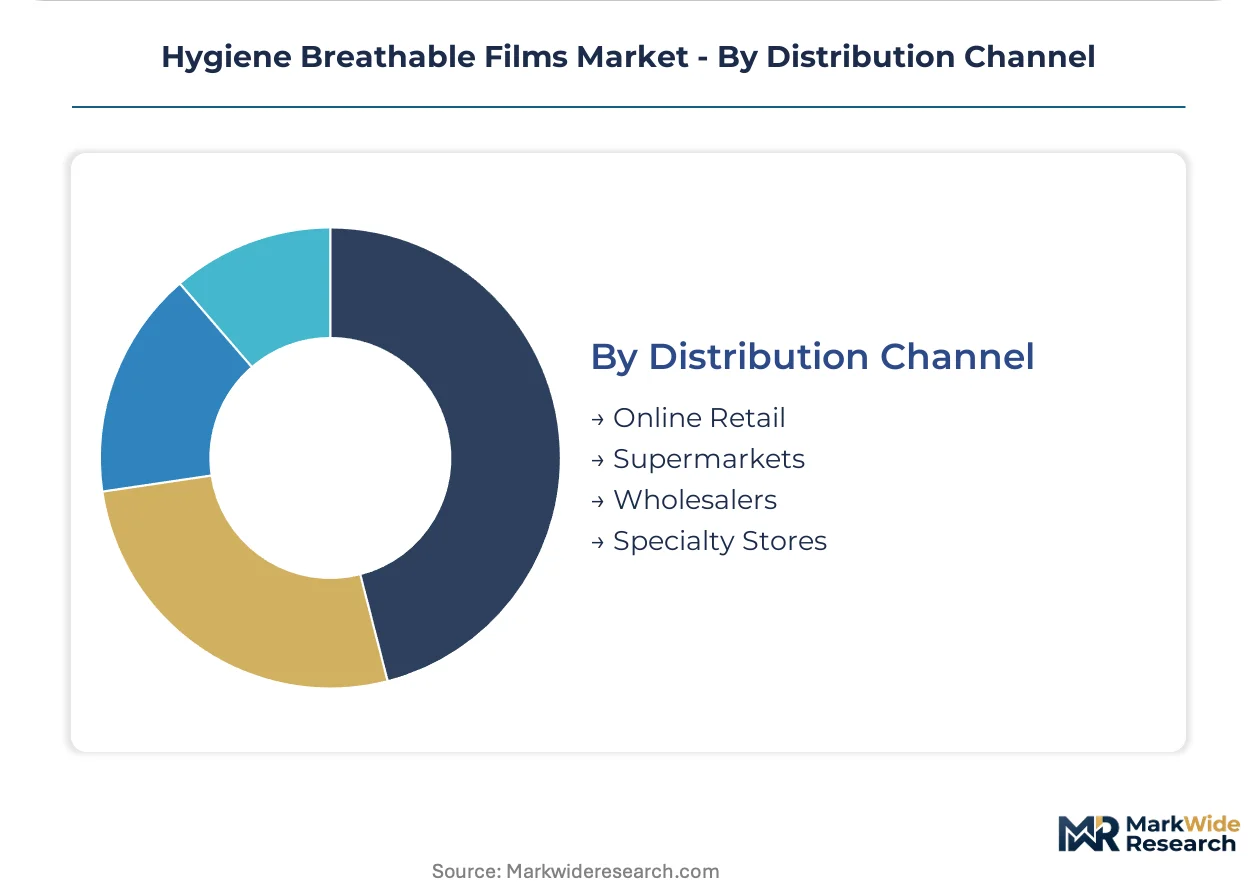
Distribution Channel:
Channel selection determines working capital intensity and geographic reach, with direct mill relationships displacing traditional intermediaries in high-volume segments.
- Online Retail:E-commerce platforms enable lot-size-one graphic personalization through rotary flexo units installed at diaper OEM sites, reducing finished goods inventory carrying costs.
- Supermarkets:Mass-market shelf placement requires packaging formats optimized for high-velocity replenishment and retail-ready logistics.
- Wholesalers:Medical supply distributors aggregate demand from smaller healthcare facilities lacking direct converter relationships.
- Specialty Stores:Pharmacy and medical equipment retailers serve consumers seeking clinical-grade products with pharmacist consultation.
Supermarkets handle the largest diaper volume. Online retail is gaining share fastest among premium and customized product tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer chemists and extrusion engineers concentrate in Germany's industrial belt, Vietnam's manufacturing corridors, and the US Gulf Coast resin corridor, anchoring regional production networks for microporous film supply.
Germany
Medical dressing manufacturers in Baden-Württemberg and North Rhine-Westphalia drive TPU film demand for wound care applications. ECHA REACH Annex XVII phthalate restrictions force continuous reformulation of legacy plasticizer packages. The Stuttgart-Mannheim corridor hosts precision extrusion facilities serving ISO 13485-certified sterile barrier producers.
Vietnam
Diaper OEMs in Ho Chi Minh City and Binh Duong Province expand blown film capacity to capture orders redirected from Chinese suppliers. The country's Ministry of Industry and Trade prioritizes domestic resin compounding under industrial upgrading directives. Southern manufacturing zones attract Middle Eastern LLDPE suppliers establishing direct mill relationships.
United States
FDA-regulated wound care channels in Minnesota and Wisconsin demand ISO 10993-5 biocompatibility documentation for medical-grade films. EPA oversight of resin emissions shapes compounding site selection in Texas and Louisiana. The Gulf Coast petrochemical corridor supplies captive LLDPE feedstock to integrated film producers.
Indonesia
Rural diaper penetration gaps in Java and Sumatra create volume upside for breathable film suppliers establishing local slitting operations. The national standards agency BSI implements voluntary conformity assessment for hygiene article materials. Surabaya-based converters add metallization capacity to serve domestic absorbent hygiene manufacturers.
Switzerland
Swissmedic-regulated medical device producers in Basel and Zurich deploy machine vision systems for real-time porosity mapping. The country's precision manufacturing heritage supports sterile packaging integration for wound care films. Aargau and Zürich cantons host converter facilities serving German and French OEM markets.
Hygiene Breathable Films Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across material grades and regulatory compliance tiers. The vendor base stratifies into three layers: multinational resin-to-film integrators controlling compounding and extrusion, regional converters with slitting and metallization capabilities, and niche medical-grade specialists maintaining ISO 13485 quality systems. Two dominant competitive moves define current positioning: backward integration into resin compounding to capture feedstock margin, and geographic expansion through Southeast Asian capacity additions to serve requalified supply chains.
Among diversified industrial groups with polymer film exposure, RKW Group and Berry Global, Inc. represent the integrated compounder-extruder archetype with captive resin relationships. Schweitzer-Mauduit International, Inc. occupies a position bridging commodity hygiene and precision medical applications. These three entities exemplify how scale and regulatory pre-qualification create defensive positioning against compressed supplier switching timelines.
| Leading Market Players |
|---|
| RKW Group |
| Berry Global, Inc. |
| Arkema S.A. |
| Nitto Denko Corporation |
| Fatra, a.s. |
| Schweitzer-Mauduit International, Inc. |
| Kimberly-Clark Corporation |
| Toray Industries, Inc. |
| Trioplast Industries AB |
| Others |
Value Chain & Pricing Dynamics
LLDPE resin indices on the Singapore Exchange cascade through diaper backsheet supply chains, compressing margin buffers for converters locked into annual volume contracts while rewarding direct mill relationships with Middle Eastern producers.
Pricing Analysis
Bundled compounding and extrusion services command premiums over unbundled substrate procurement. Three-tier pricing structure across medical-grade TPU, REACH-compliant polyethylene, and commodity diaper backsheet separates ISO 13485-certified films from standard hygiene grades. Price differentiation hinges on SVHC documentation completeness and biocompatibility certification tier. Cost compression in Southeast Asian diaper supply chains is intensifying because Vietnamese converters are capturing redirected orders through direct LLDPE sourcing. Mid-tier hygiene article manufacturers exhibit highest price sensitivity; German wound care OEMs show lowest sensitivity due to sterilization stability requirements.
Supply Chain Analysis
Reverse logistics for medical-grade film scrap flows through specialized polymer reclaimers in Germany and Switzerland, where TPU edge trim feeds back into compounding operations rather than commodity recycling streams. Primary production concentrates in Germany, Vietnam, and the United States. Raw material dependencies draw from Middle Eastern LLDPE, German TPU resin systems, and Chinese calcium carbonate fillers. Single-source vulnerability pervades REACH-compliant compounding capacity controlled by dominant integrated producers. Distribution runs through direct mill-to-converter contracts displacing traditional resin intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hygiene breathable films constitute a late-cycle quality story as EU REACH disclosure mandates and FDA biocompatibility pathways shift procurement toward pre-qualified suppliers with documented ISO 10993-5 and SVHC dossier capabilities.
For Market Incumbents: Hedge against compressed supplier switching timelines by securing captive resin compounding capacity in Central Europe and accelerating multi-site qualification programs across Southeast Asian blown film infrastructure. RKW Group and Berry Global demonstrate defensive positioning through backward integration into LLDPE feedstock relationships that insulate margin structures from naphtha volatility. For New Entrants and Emerging Players: Capture white-space opportunity in India's rural diaper penetration gap, where local slitting and metallization operations remain underdeveloped relative to urban demand centers. Target wound care adhesive films requiring CE-MDR Class IIa notified body review, as incumbent quality system investments create qualification barriers that favor specialized entrants with ISO 13485 pre-certification. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier converters possessing installed extrusion capacity but lacking direct resin relationships, as feedstock disintermediation trends concentrate procurement expertise inside OEM technical teams. Five-to-ten-year viability favors suppliers with dual FDA-EU compliance archives. Monitor ECHA SVHC candidate list expansion velocity as inflection indicator for plasticizer reformulation cycle intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captures feedstock margin and secures REACH-compliant supply chains against phthalate restriction tightening. |
| Multi-Site Qualification Programs | Berry Global leverages North American infrastructure to sustain European brand owner access despite compressed timelines. |
| Machine Vision Defect Detection Deployment | Swiss and German converters compress lot release documentation from hours to minutes for sterile packaging integration. |
| Direct Mill-to-Converter Purchasing Contracts | Vietnamese and Thai OEMs negotiate annual volume commitments with Middle Eastern LLDPE producers for cost advantages. |
| ISO 13485 Quality System Investment | CE-MDR Class IIa reclassification favors suppliers with existing notified body relationships for wound care films. |
Study Parameters
Multiple input streams — extrusion equipment manufacturer technical specifications, resin producer volume disclosures, and hygiene OEM procurement documentation — were reconciled against ECHA REACH substance databases and FDA 510(k) filings. Primary interviews with plant managers at Vietnamese and Indonesian converters, procurement leads at German wound care manufacturers, and regulatory affairs specialists at medical device firms informed supply chain structure assessment. Secondary validation drew from customs trade data, SEC 10-K resin segment disclosures, and ISO certification registry extracts. Bottom-up capacity modeling and top-down demand estimation were triangulated to constrain output ranges.
Cross-referencing historical extrusion line installation patterns against panel input from technical directors at film converters established baseline capacity trajectories across the projection horizon. Segmentation dimensions modeled include polymer chemistry platform, application category, regulatory compliance tier, and regional production hub. CAGRs were derived from slope analysis of qualified supplier capacity additions against demographic demand drivers. Industry-specific forecast inputs encompass EU MDR transition timelines and Southeast Asian diaper penetration rate assumptions.
Underlying measurement precision varies by segment; medical-grade TPU films with documented ISO 10993-5 study archives carry tighter precision than commodity diaper backsheet estimates subject to resin price volatility. Forecasts reflect assumptions regarding REACH SVHC list expansion cadence and FDA-EU regulatory convergence patterns. Practitioners should monitor ECHA substance disclosure mandate enforcement intensity and Middle Eastern LLDPE producer direct sales expansion for early signals of supply chain restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Saudi Arabia Flexible Packaging Market
Flexible Packaging
Flexible Paper for Food & Beverages Packaging Market
Flexible Packaging
Middle East and Africa Flexible Plastic Packaging Market
Flexible Packaging
Europe, Middle East and Africa (EMEA) Flexible Packaging Market
Flexible Packaging
Litho Laminated Packaging Market
Flexible Packaging
Saudi Arabia Flexible Plastic Packaging Market
Flexible Packaging
Thailand Flexible Plastic Packaging Market
Flexible Packaging
Asia Pacific Single-Use Packaging Market
Flexible Packaging
APAC Flexible Packaging Market
Flexible Packaging
Vietnam Flexible Plastic Packaging Market
Flexible Packaging
Nigeria Flexible Packaging Market
Flexible Packaging
UK Flexible Plastic Packaging Market
Flexible Packaging
GCC Shrink Sleeves Market
Flexible Packaging
Benelux Flexible Plastic Packaging Market
Flexible Packaging
UAE Flexible Packaging Market
Flexible Packaging
Morocco Flexible Plastic Packaging Market