

Cork Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Cork Packaging Market Insights
Multi-source sourcing of raw cork bark is repositioning supply security across the value chain. Amorim Cork leverages vertical integration from forest management through finished stopper production to control quality consistency. Diam Bouchage differentiates through patented surface treatment technologies that eliminate cork taint risk. Jelinek Cork Group anchors North American distribution through dedicated sheeting and fabrication facilities.
Cork packaging comprises harvested bark of Quercus suber, a renewable cellular material with density ranging from 180 to 260 kg per cubic meter, valued for compressibility, elastic recovery, and impermeability to liquids and gases. Bottle stoppers command the dominant share of value given wine industry attachment to natural closure authenticity and oxygen transfer rate performance. Composite cork and expanded cork categories capture faster volume expansion as cosmetics and electronics sectors seek biodegradable protective formats with precise moldability.
EU REACH restrictions on synthetic polymer additives and F-Gas Regulation phase-downs indirectly elevate cork's competitiveness against plastic and aluminum alternatives. EFSA contact material standards and FDA food additive regulations govern migration limits for cork treatments and coatings in food and pharmaceutical applications. Stakeholders must track evolving compostability certification requirements and forest stewardship chain-of-custody rules that will determine premium market access.
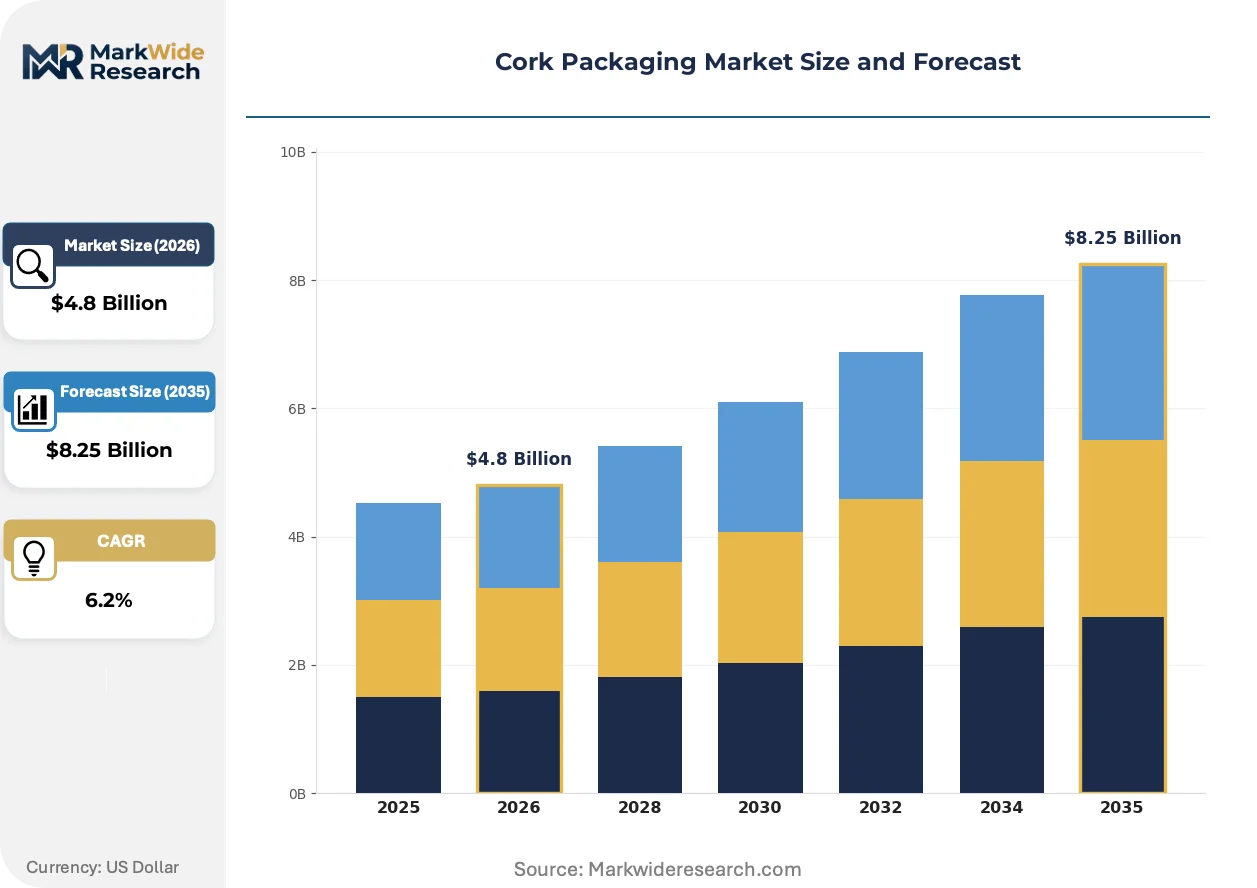
Market Dynamics
EU Green Deal carbon neutrality mandates and REACH chemical restrictions are systematically elevating cork's cost-competitiveness against petroleum-derived synthetic closures, restructuring procurement priorities across beverage and cosmetics packaging value chains.
Growth Catalysts
- REACH chemical restrictions:ECHA's tightening controls on plasticizer additives in polymer stoppers redirect wine bottlers toward natural cork alternatives that bypass hazardous substance registration requirements.
- Cosmetics sector biodegradability mandates:Premium skincare brands in France and Italy are specifying molded cork trays and caps to satisfy retailer sustainability scorecards and consumer disposal preferences.
- Alentejo forest certification density:Portugal's concentrated cork oak belt enables chain-of-custody verification at scale, reducing audit costs for FSC and PEFC compliance.
Market Restraints
- Raw bark harvest volatility:Quercus suber stripping cycles run nine-year intervals, creating supply inelasticity that amplifies price swings during poor weather years in southern Iberia.
- Aluminum screw-cap substitution:Mass-market wine producers in Australia and Chile have standardized metal closures for cost and consistency, capping cork's volume ceiling in sub-premium tiers.
- Processing labor intensity:Natural stopper production requires skilled manual sorting and grading that resists full automation, constraining throughput expansion relative to synthetic alternatives.
Strategic Opportunities
- US craft spirits segment:American whiskey and small-batch distilleries are adopting cork-finished closures for premium positioning, opening a category historically dominated by synthetic or metal seals.
- EU F-Gas Regulation phase-down:Refrigeration-dependent supply chains face rising compliance costs that indirectly favor cork's ambient-temperature stability during transport and storage.
- 3D-printed cork composite tooling:Convergence of additive manufacturing with granulated cork feedstocks enables rapid prototyping of custom protective packaging for electronics and medical devices.
Industry Challenges
- Bark grading expertise shortage:Experienced cork selectors capable of identifying taint-risk material by visual and tactile inspection are aging out of Portugal's workforce faster than training programs replace them.
- Compostability certification lag:Industrial composting facilities in Germany and the Netherlands lack standardized acceptance protocols for coated cork products, creating disposal uncertainty for brand marketing claims.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cork Packaging Market Trends and Innovations
Surface treatment chemistry and composite formulation advances are eliminating historical quality defects while expanding cork's addressable applications beyond traditional wine sealing into precision-engineered protective formats.
Supercritical CO2 extraction technology is unifying quality assurance protocols across natural stopper production. High-volume wineries in California and Bordeaux are adopting these treated closures to eliminate 2,4,6-trichloroanisole contamination risk without sacrificing oxygen transmission precision. The technology is compressing the historical premium-commodity price spread by standardizing performance across grade tiers.
EU F-Gas Regulation mandates on hydrofluorocarbon phase-down are indirectly elevating cork's logistics competitiveness. Cold-chain-dependent synthetic closure producers face rising refrigerant compliance costs that natural cork's ambient stability avoids. Wine distributors in Italy and Spain are restructuring procurement specifications to favor closures with lower temperature-control requirements through the supply chain.
Direct-to-consumer subscription wine channels are fragmenting traditional bulk-shipment packaging norms. California-based wine clubs and European cellar-door operators are specifying individual bottle protective formats that prioritize unboxing experience and disposal simplicity over palletization efficiency. This behavioral shift favors molded cork inserts and composite cushioning over expanded polystyrene in premium subscription tiers.
Cork Packaging Market Segmentation
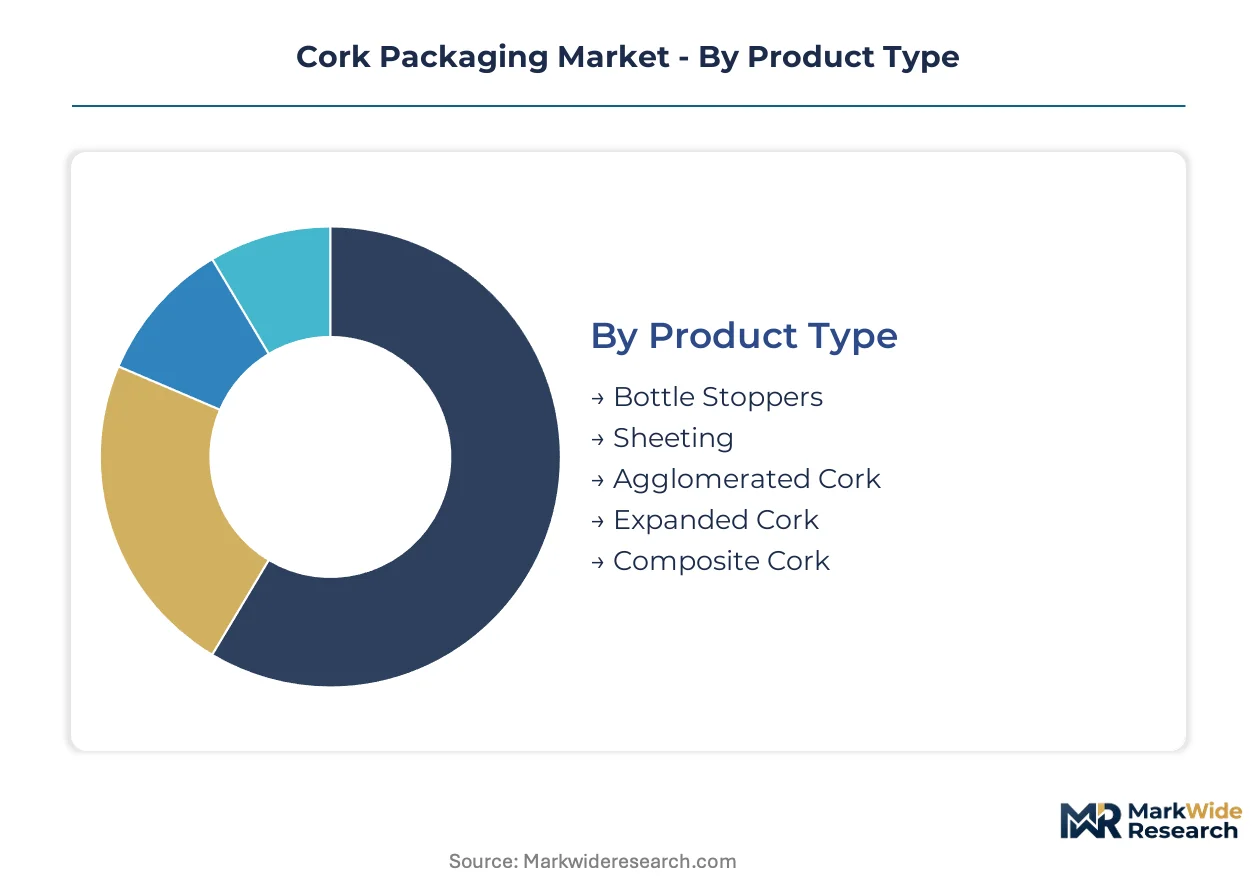
Cork packaging segmentation reveals how material form and functional requirements dictate procurement priorities across beverage, cosmetics, and industrial applications. Upgrade cycles vary dramatically by end-use, with wine bottlers replacing stoppers per vintage while electronics manufacturers redesign protective formats only at product generation shifts.
Product Type:
Replacement intensity and performance specifications drive upgrade patterns across cork product categories, with premium wine closures commanding the shortest procurement cycles.
- Bottle Stoppers:Natural Quercus suber bark processed into cylindrical seals with calibrated oxygen transmission rates between 0.0001 and 0.001 mg O2 per day. Bordeaux and Napa Valley wineries specify these for reserve-tier bottlings despite supercritical CO2 treatment costs that add 15-20% to raw material outlays.
- Expanded Cork:Heat-processed granulated cork achieving densities of 120-180 kg per cubic meter for shock-absorbing applications. Portuguese fabricators supply this to German automotive component suppliers seeking biodegradable dunnage alternatives to polyurethane foam.
- Sheeting:Laminated bark layers for gasket and flooring substrates.
- Agglomerated Cork:Bonded granules for cost-sensitive sealing applications.
- Composite Cork:Polymer-cork blends for moldable precision formats.
Bottle Stoppers sits at the top of the volume ranking, with Expanded Cork climbing the fastest.
Application:
End-use performance thresholds create distinct margin tiers, with oxygen-sensitive applications commanding premium pricing over mechanical protection uses.
- Wine Bottling:Closure selection directly impacts sensory development through controlled oxygen ingress, with EFSA migration limits governing surface treatment chemistry. Italian and Spanish cooperatives maintain multi-year supply contracts with Alentejo processors to secure consistent quality lots.
- Cosmetics Containers:Molded cork caps and trays serve L'Oréal and Estée Lauder sustainability commitments, with biodegradability certification requirements from French retailer scorecards driving specification changes faster than traditional packaging refresh cycles.
- Pharmaceutical Packaging:Inert barrier properties for sensitive compounds.
- Electronics Protection:Static-dissipative cork composites for component shipping.
- Food Storage:Natural antimicrobial properties for specialty preserves.
Wine Bottling captures the dominant revenue share, while Cosmetics Containers gains share fastest on sustainability mandates.
End User Industry:
Customer procurement sophistication spans from commodity spot purchasing to integrated forest-to-bottle partnership structures.
- Winemaking:Technical buyers evaluate oxygen transmission curves and TCA risk probabilities, with Champagne houses specifying individual forest provenance for prestige cuvées. Vertical integration into cork oak forest management has become a competitive necessity for major négociants.
- Beauty & Personal Care:Brand marketing teams prioritize unboxing aesthetics and disposal narratives over unit cost, with Sephora and Douglas sustainability scorecards filtering supplier eligibility before technical evaluation begins.
- Medical Supplies:Sterile barrier validation requirements for cork-based primary packaging.
- Consumer Electronics:Protective format specifications tied to product launch calendars.
- Food & Beverage Production:Commodity-grade cork for preserves and specialty oils.
Winemaking maintains the deepest supplier relationships, with Beauty & Personal Care expanding contract values most steeply.
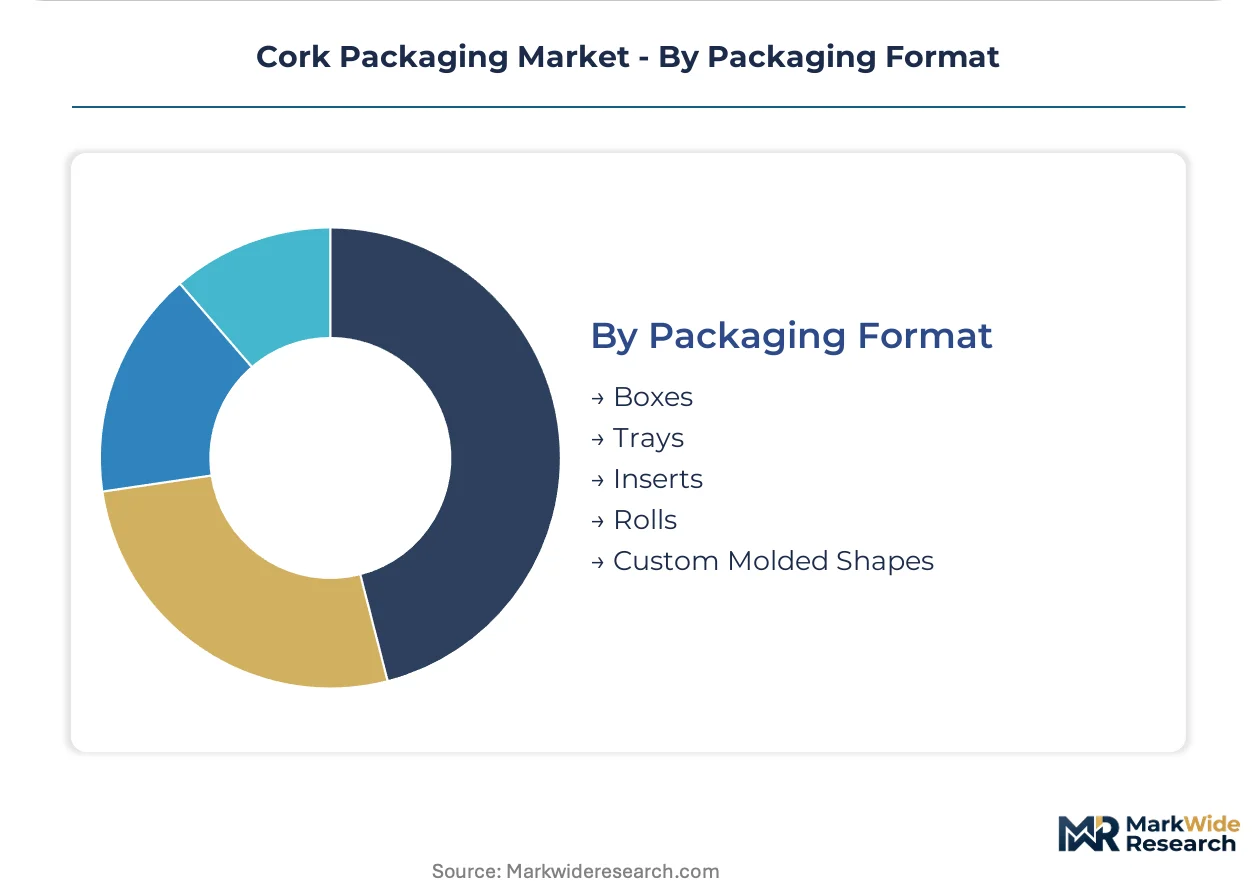
Packaging Format:
Manufacturing process constraints and logistics optimization shape format selection across customer segments.
- Custom Molded Shapes:CNC-machined or compression-molded formats achieving dimensional tolerances of ±0.1mm for precision component nesting. Dutch electronics distributors specify these for high-value semiconductor shipments requiring drop-test certification to ISTA 3A standards.
- Inserts:Die-cut cork layers for box lining and cushioning applications.
- Boxes:Rigid corkboard constructions for luxury presentation.
- Trays:Thermoformed or pressed formats for retail display.
- Rolls:Continuous sheeting for industrial gasket and flooring supply.
Inserts dominates shipment volumes, with Custom Molded Shapes showing the steepest expansion trajectory on precision electronics demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping cork packaging production geography. EU REACH compliance costs and F-Gas Regulation burdens favor Iberian processors over synthetic closure competitors facing elevated refrigerant and chemical registration expenses.
Portugal
Alentejo's cork oak belt supplies raw bark for premium natural stoppers. ECHA REACH enforcement on polymer additives redirects French and German wine bottlers toward Portuguese suppliers. Amorim's integrated operations in Santa Maria da Feira exemplify captive supply from forest through finished closure.
Spain
Catalonia and Extremadura processing clusters serve cosmetics brands seeking biodegradable packaging. EU Green Deal carbon neutrality mandates pressure L'Oréal and Puig to specify cork over petroleum-derived alternatives. Barcelona-area fabricators are expanding molded cork capacity for electronics protective formats.
Italy
Champagne houses and Franciacorta producers specify individual forest provenance for prestige cuvées. EFSA contact material standards govern surface treatment chemistry for food-grade applications. Tuscan cooperatives maintain multi-year supply contracts with Alentejo processors to secure consistent quality lots.
France
Bordeaux négociants evaluate oxygen transmission curves and TCA risk probabilities in closure procurement. ANSM pharmaceutical packaging standards create compliance barriers for synthetic alternatives in medical applications. Champagne processing facilities near Épernay are standardizing supercritical CO2 treated closures.
United States
California wineries and craft spirits distilleries adopt cork-finished closures for premium positioning. FDA food additive regulations govern migration limits for cork treatments. Napa Valley distributors are restructuring procurement specifications to favor closures with lower temperature-control requirements through supply chains.
Cork Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue composite formulation and 3D-printed tooling adjacent spaces. The vendor base concentrates around vertically integrated forest-to-finish operators and specialized surface treatment technology holders. Three archetypes dominate: captive supply chain controllers, patented process licensors, and regional distribution anchors. Competitive moves center on backward integration into forest management and strategic partnerships with cosmetics brand sustainability programs.
Within the captive supply tier, Amorim Cork and Diam Bouchage exemplify contrasting strategic positions. Amorim represents the archetype of upstream control over raw material through finished stopper production. Diam Bouchage occupies a position as a patented technology licensor eliminating historical quality defects. Jelinek Cork Group anchors North American distribution infrastructure for sheeting and fabrication supply.
| Leading Market Players |
|---|
| Amorim Cork |
| Diam Bouchage |
| Jelinek Cork Group |
| Sugherificio Martinese & Figli |
| M. A. Silva |
| Cork Supply |
| J. C. Ribeiro |
| Korkindustrie |
| Underwood Cork |
| Others |
Pricing and Supply Chain Analysis
Supercritical CO2 extraction technology adoption is compressing cost economics across natural stopper grades while concentrating processing capability among Alentejo-based operators with capital-intensive treatment installations. This production-method transition simultaneously elevates quality consistency and reinforces pricing power for certified-taint-free supply tiers.
Pricing Analysis
Distributor margins in Portuguese export channels absorb 12-18% of final delivered cost before French and Italian bottler procurement. Three-tier pricing structure across premium, standard, and economy levels separates supercritical-treated stoppers from conventional grades and agglomerated alternatives. Cost compression in mass-market tiers intensifies because Australian and Chilean wineries standardize aluminum screw-cap specifications. Mass-market wine producers exhibit highest price sensitivity; Champagne houses and reserve-tier Napa Valley operations demonstrate lowest sensitivity to per-unit closure cost.
Supply Chain Analysis
Skilled bark grading workforce availability in Portugal's Alentejo region and Extremadura processing clusters constrains throughput expansion relative to synthetic closure automation. Raw material supply draws from managed Quercus suber forests in Portugal, Spain, and scattered North African stands. Single-source vulnerability concentrates in nine-year stripping cycles that amplify price volatility during southern Iberian drought periods. Distribution runs through dedicated sheeting and fabrication facilities anchored in regional wine production clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cork packaging market represents a late-cycle quality story as direct-to-consumer wine subscriptions and premium cosmetics sustainability mandates shift procurement specifications toward certified provenance and disposal simplicity.
For Market Incumbents: Anchor forest management control through backward integration into Alentejo cork oak belt holdings to secure raw material priority access against emerging composite competitors. Defend against aluminum screw-cap substitution in sub-premium tiers by expanding supercritical CO2 treatment capacity to standardize quality across grade tiers. Certification investment in FSC and PEFC chain-of-custody verification preserves premium market access as EU Green Deal procurement rules tighten.
For New Entrants and Emerging Players: Enter via 3D-printed cork composite tooling for electronics protective formats where precision moldability and biodegradable credentials command specification changes. White-space targets include American craft spirits closures and German automotive component dunnage applications. Go-to-market positioning should emphasize rapid prototyping capabilities against incumbent lead times for custom molded shapes.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional distribution anchors without captive forest supply. Long-term viability over the analysis window hinges on sustained EU REACH enforcement against synthetic polymer additives and compostability certification standardization. Acquisition target archetype: surface treatment technology licensors with patented taint-elimination processes. Monitor German and Dutch industrial composting facility acceptance protocols for coated cork products as inflection indicator for cosmetics sector expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forest Management | Captive Quercus suber supply secures priority access during poor harvest years in Alentejo. |
| Supercritical CO2 Treatment Scale-Up | Eliminates TCA contamination risk for high-volume California and Bordeaux winery contracts. |
| Composite Formulation R&D Partnership | Enables moldable precision formats for L'Oréal and Estée Lauder sustainability commitments. |
| 3D-Printed Tooling Capability Investment | Accelerates custom protective packaging prototyping for Dutch semiconductor distributors. |
| Compostability Certification Program | Resolves disposal uncertainty blocking Sephora and Douglas sustainability scorecard eligibility. |
Research Methodology
Direct dialogue with cork forest managers, Alentejo processing plant operators, French négociant procurement directors, and Italian cooperative technical buyers grounded qualitative assessment of supply constraints and quality grading protocols. Secondary validation drew from ECHA REACH substance registrations, EFSA contact material migration standards, FSC chain-of-custody audit reports, and Portuguese agricultural ministry harvest statistics. Bottom-up and top-down triangulation reconciled individual processor capacity estimates with aggregate export value flows.
Bottom-up volume modeling built from named processor capacity disclosures, stripping cycle yields per hectare, and grade-tier recovery rates across the projection horizon. Segmentation dimensions spanned product type, application end-use, and regional regulatory cluster. Value projections incorporated oxygen transmission rate performance premiums and supercritical treatment cost pass-through structures. CAGRs derived from fitted growth curves against historical export volume trajectories and substitution elasticity assumptions.
The model holds under sustained EU Green Deal enforcement and REACH chemical restriction trajectories; deviation in F-Gas Regulation phase-down pace or composting facility certification standardization would shift cosmetics sector penetration timelines. Practitioners should monitor German and Dutch industrial composting acceptance protocols and Alentejo workforce training program graduation rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.