
 Age Related Vision Dysfunction Market | 2026-2036
Age Related Vision Dysfunction Market Size, Share, and Industry Trends Forecast 2026-2036
Age Related Vision Dysfunction Market Analysis
European ophthalmic device manufacturing is realigning toward higher-precision optical implant production. Novartis leverages its integrated pharmaceutical-ophthalmology platform to sustain leadership in anti-VEGF therapy development. Regeneron Pharmaceuticals anchors its competitive position through specialized biologics manufacturing for retinal disease. Roche dominates diagnostic innovation while competing across the presbyopia management value chain.
Age related vision dysfunction encompasses progressive optical deterioration including presbyopia, cataract formation, and myopic degeneration, typically addressed through corrective lenses, pharmacological intervention, or surgical implantation of intraocular devices with biocompatible materials such as hydrophobic acrylic and silicone optics. Its primary commercial purpose centers on restoring functional visual acuity for aging populations to maintain workforce participation and independent living capacity. Glasses and contact lenses occupy mature, high-volume positions with compressed margins, while surgical implants and augmented rehabilitation devices represent faster-expanding segments where technology differentiation commands premium positioning. Presbyopia management and cataract treatment applications concentrate the largest patient pools, though vision therapy is gaining traction in home care settings through assistive device integration.
FDA oversight of intraocular lenses under Class III medical device standards, combined with EMA's MDR framework for optical implants and ISO 11979 biocompatibility requirements, creates layered compliance barriers that filter market entrants and shape R&D investment priorities. These regulatory structures elevate quality thresholds while channeling demand toward validated manufacturers with established clinical data portfolios. Stakeholders must monitor reimbursement policy shifts in Medicare and national health systems as these decisions directly determine patient access velocity for premium implant technologies.
Market Dynamics
EU MDR certification requirements for intraocular lenses are compressing vendor margins while filtering marginal manufacturers from the optical implant supply base. Ophthalmology clinics in Germany and France face extended procurement cycles as notified bodies process Class III device submissions under stricter clinical evidence thresholds.
Growth Catalysts
- Population aging in Western Europe:Italy's over-65 demographic expansion is expanding the addressable patient pool for presbyopia management and cataract intervention across its national health service regions.
- EMA MDR framework harmonization:Unified certification standards across EU member states are reducing regulatory fragmentation and enabling pan-European distribution for validated optical implant manufacturers.
- Biocompatible material advances:Hydrophobic acrylic and silicone optic platforms are extending device longevity and reducing posterior capsule opacification rates in intraocular lens applications.
Market Restraints
- Silicone polymer supply concentration:Raw material sourcing for premium intraocular lenses depends on a limited German and Swiss chemical supplier base, exposing manufacturers to input cost volatility.
- Notified body capacity constraints:EMA-designated conformity assessment organizations face backlog pressures, extending optical implant certification timelines by 12-18 months and delaying market entry.
- Corrective lens substitution:Advanced progressive spectacle lenses and multifocal contact options retain cost advantages for early-stage presbyopia patients, limiting surgical conversion rates.
Strategic Opportunities
- Home care vision therapy expansion:Assistive device integration for aging-in-place populations in France is opening reimbursement pathways for digital refractive training platforms.
- CSRD sustainability disclosure alignment:EU corporate sustainability reporting requirements are creating procurement preference for optical implant manufacturers with validated lifecycle assessment data.
- Teleophthalmology channel development:Remote diagnostic workflows in Italian regional health systems are compressing referral pathways and accelerating specialist consultation access for rural cataract patients.
Industry Challenges
- Specialized surgical training deficits:Premium intraocular lens implantation requires advanced capsulorhexis and toric alignment competencies that residency programs in Spain and Portugal are struggling to scale.
- ISO 11979 biocompatibility testing complexity:Extended cytotoxicity and implantation study timelines for novel optic materials are stretching R&D payback periods beyond traditional ophthalmic device planning horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Age Related Vision Dysfunction Market |
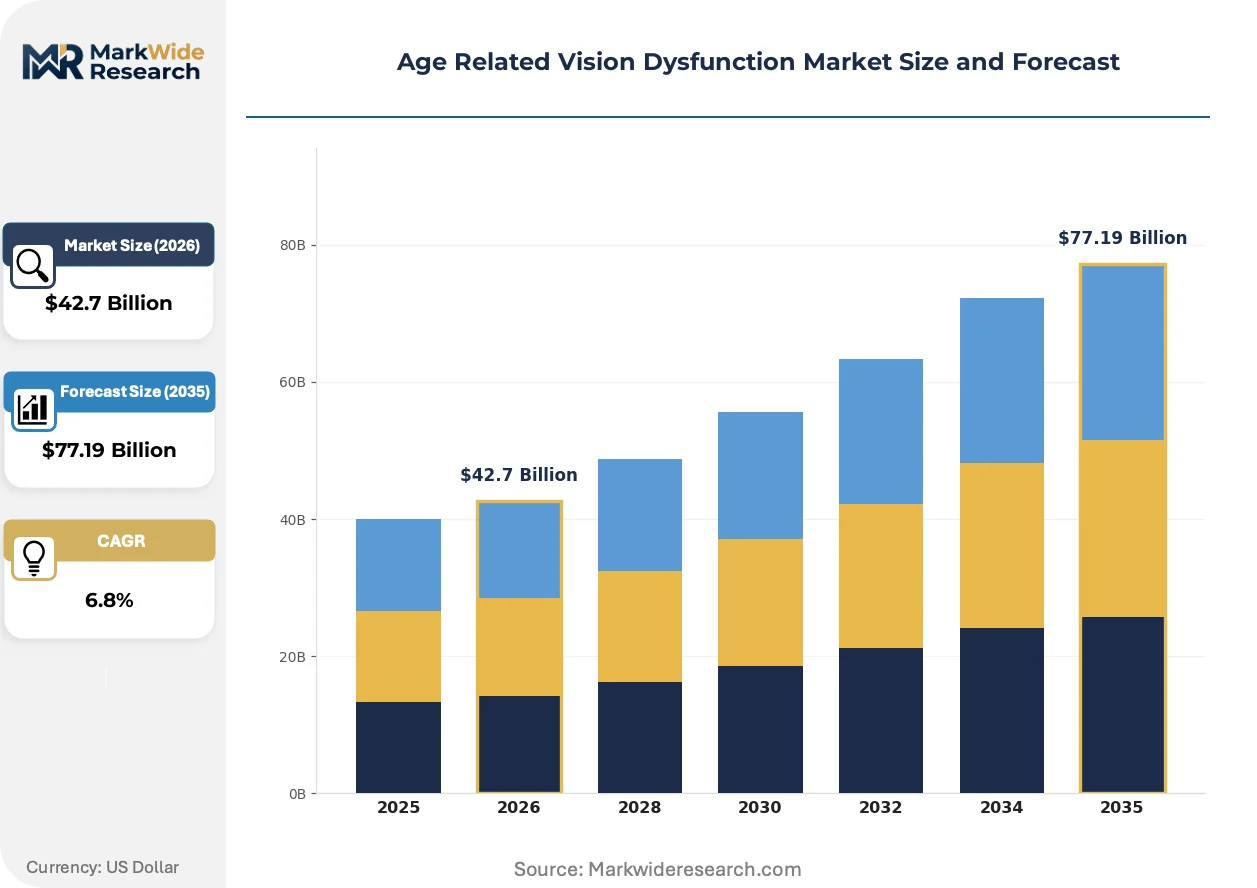
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $77.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glasses, Contact Lenses, Surgical Implants, Augmented Rehabilitation Devices Technology: Laser Surgery, Medication, Optical Sensors, Assistive Devices End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Application: Myopia Correction, Presbyopia Management, Cataract Treatment, Vision Therapy |
| Companies Covered | Novartis, Regeneron Pharmaceuticals, Roche, Bayer, Alcon, Bausch + Lomb, Genentech, Johnson & Johnson Vision, AbbVie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Age Related Vision Dysfunction Market Emerging Trajectories
Extended depth-of-focus intraocular lens platforms are compressing the boundary between presbyopia management and cataract treatment modalities. Device manufacturers and ophthalmology clinics across Germany, France, and Italy are recalibrating service portfolios around these converging clinical pathways.
Accommodating intraocular lens technology is decentralizing presbyopia correction from spectacle-dependent models toward surgical intervention at earlier disease stages. German ophthalmology clinics are accelerating adoption of these devices for patients aged 45-55 previously managed through progressive lenses. The technology is decentralizing volume from mature corrective lens retail channels into premium surgical service lines with differentiated reimbursement positioning.
EMA's MDR post-market surveillance requirements are mandating systematic clinical follow-up data collection for all implanted optical devices. Manufacturers must now maintain active implant registries and report adverse events through Eudamed, elevating quality management system investments. Cataract treatment applications face the steepest compliance burden as these devices carry the highest patient contact volume across EU ophthalmology practices.
Patient self-referral patterns are fragmenting traditional gatekeeper relationships between optometry and ophthalmology in French and Italian healthcare systems. Direct-to-clinic digital scheduling platforms are displacing optometric referral channels for presbyopia evaluation and surgical candidacy assessment. This behavioral shift concentrates most visibly in urban catchment areas of Milan, Paris, and Munich where clinic density supports competitive appointment access.
Age Related Vision Dysfunction Market Segmentation
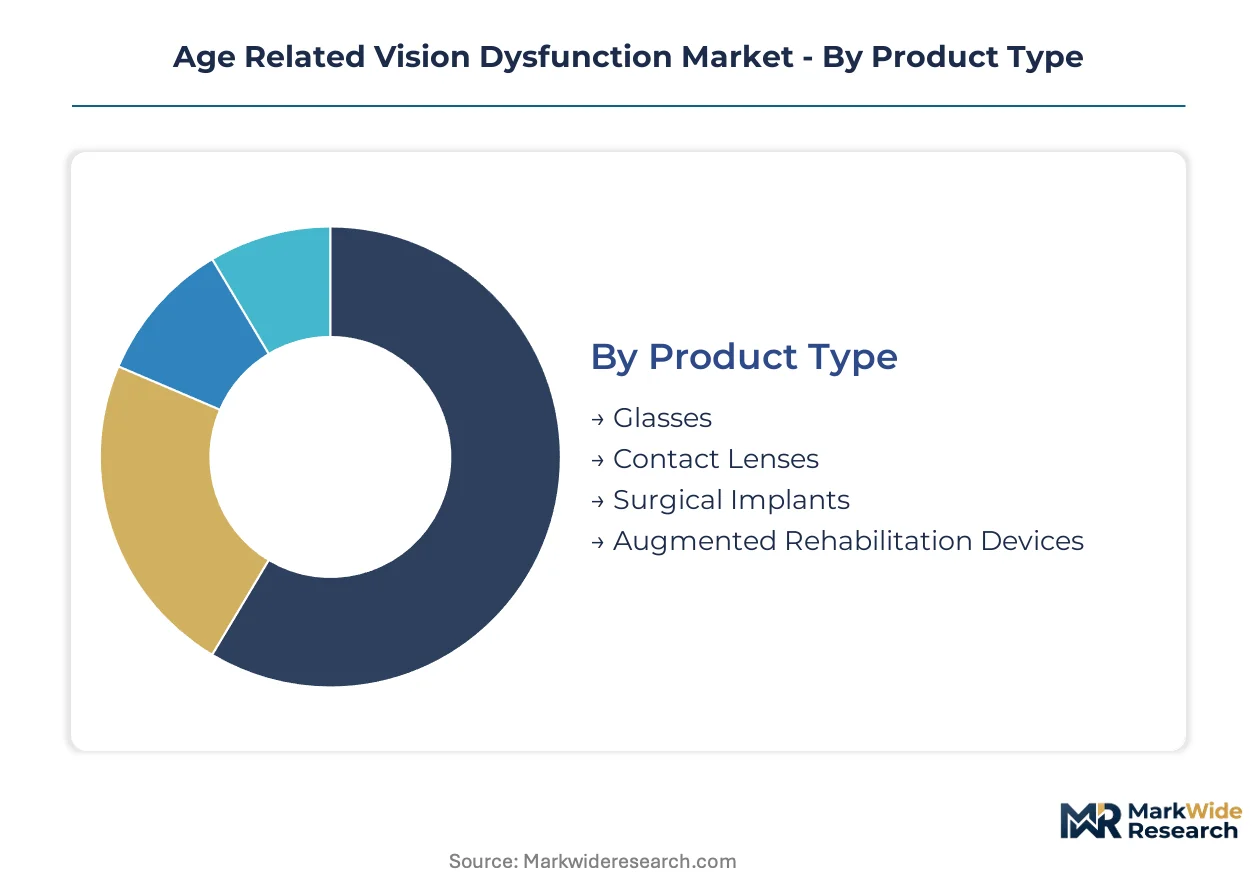
Segmentation in the Age Related Vision Dysfunction Market reveals how patient acuity, reimbursement pathways, and surgical candidacy stratify demand across distinct product and service tiers. Understanding these divides enables manufacturers to align R&D investments with clinically validated segments and procurement-sensitive channels.
Product Type:
Supply concentration in hydrophobic acrylic and silicone polymer production concentrates manufacturing leverage among German and Swiss chemical suppliers, elevating input cost sensitivity for premium implant categories.
- Surgical Implants:Intraocular lenses utilizing hydrophobic acrylic and silicone optics command premium positioning through extended longevity and reduced posterior capsule opacification rates. German ophthalmology clinics are expanding presbyopia management services around accommodating IOL platforms for patients aged 45-55 previously managed through progressive lenses.
- Glasses:Progressive spectacle lenses occupy mature, high-volume distribution with compressed margins, though advanced multifocal designs retain cost advantages for early-stage presbyopia patients in Italy's national health service regions. Corrective lens substitution limits surgical conversion rates among price-sensitive demographics.
- Contact Lenses:Multifocal and toric soft lens platforms serve intermediate visual correction needs with lower clinical intervention thresholds than surgical alternatives.
- Augmented Rehabilitation Devices:Assistive device integration for aging-in-place populations in France is opening reimbursement pathways for digital refractive training platforms.
Today's leader: Surgical Implants. Tomorrow's challenger: Augmented Rehabilitation Devices.
Technology:
Cost tier stratification separates capital-intensive laser platforms from consumable pharmacological therapies, with reimbursement intensity varying sharply across EU member state health systems.
- Medication:Anti-VEGF biologics dominate retinal disease management through specialized manufacturing requirements and cold-chain distribution infrastructure. Novartis leverages its integrated pharmaceutical-ophthalmology platform to sustain leadership in therapy development for age-related macular degeneration.
- Laser Surgery:Femtosecond and excimer platforms enable precise corneal reshaping with differentiated capital equipment amortization models across hospital and ambulatory surgery center settings.
- Assistive Devices:Digital magnification and text-to-speech systems support functional independence for advanced vision loss patients in home care environments.
- Optical Sensors:Remote monitoring technologies are compressing referral pathways in Italian regional health systems through teleophthalmology channel development.
Current reimbursement concentration: Medication. Emerging access pathway: Optical Sensors.
End User:
Volume distribution across delivery settings reflects procedure complexity, capital requirements, and regulatory certification burdens under EMA MDR frameworks.
- Clinics:Ophthalmology clinics across Germany, France, and Italy are recalibrating service portfolios around extended depth-of-focus IOL platforms that compress boundaries between presbyopia management and cataract treatment modalities.
- Hospitals:Tertiary centers manage complex comorbid cases and train surgical residents in advanced capsulorhexis and toric alignment competencies that residency programs in Spain and Portugal are struggling to scale.
- Home Care:Vision therapy is gaining traction through assistive device integration for aging-in-place populations with reimbursement pathway development in French healthcare systems.
- Rehabilitation Centers:Post-surgical and low-vision rehabilitation services concentrate in urban catchment areas of Milan, Paris, and Munich where clinic density supports competitive appointment access.
Volume anchor: Clinics. Margin expansion zone: Home Care.
Application:
Patient pool size and technology substitution dynamics determine segment maturity, with presbyopia management and cataract treatment commanding the largest addressable populations.
- Cataract Treatment:Intraocular lens implantation carries the highest patient contact volume across EU ophthalmology practices and faces the steepest EMA MDR post-market surveillance compliance burden through Eudamed adverse event reporting requirements.
- Presbyopia Management:Accommodating IOL technology is decentralizing volume from mature corrective lens retail channels into premium surgical service lines with differentiated reimbursement positioning in German and French healthcare systems.
- Myopia Correction:Laser and orthokeratological interventions address progressive refractive error in younger aging cohorts before presbyopia onset.
- Vision Therapy:Digital refractive training platforms are expanding through assistive device integration for aging-in-place populations with CSRD sustainability disclosure alignment creating procurement preference for validated lifecycle assessment data.
Established revenue base: Cataract Treatment. Steepest expansion trajectory: Vision Therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's ophthalmology clinic density exceeds Italy's by a factor of nearly two, yet both markets face identical EMA MDR certification bottlenecks that compress vendor margins and extend procurement cycles for intraocular lens procurement.
Germany
Bavarian medical device clusters around Munich and Erlangen concentrate intraocular lens manufacturing alongside specialized chemical suppliers of hydrophobic acrylic polymers. The country's notified bodies face 12-18 month backlogs for Class III optical implant submissions under tightened clinical evidence thresholds. Frankfurt's university hospital networks are expanding accommodating IOL services for presbyopia patients aged 45-55 previously managed through progressive lenses.
France
Île-de-France's aging demographic is expanding demand for cataract intervention across Paris metropolitan health service regions while Auvergne-Rhône-Alpes develops teleophthalmology referral pathways. ANSM post-market surveillance requirements align with EMA MDR frameworks through systematic Eudamed adverse event reporting. Lyon-based ophthalmology clinics are pioneering digital refractive training platforms with emerging reimbursement pathways for home care vision therapy.
Italy
Lombardy's over-65 population expansion is driving presbyopia management demand across Milan's dense clinic networks. The national health service regions face procurement delays as EMA-designated conformity assessment organizations process optical implant certifications. Veneto's regional health systems are compressing specialist consultation access for rural cataract patients through remote diagnostic workflows.
Switzerland
Swissmedic maintains parallel certification standards with EU MDR while preserving independent market access for optical implant manufacturers. Basel's pharmaceutical-ophthalmology integrated platforms anchor anti-VEGF therapy development for age-related macular degeneration. Zurich's chemical suppliers concentrate silicone polymer production for premium intraocular lens raw material sourcing.
United States
Medicare reimbursement policy shifts directly determine patient access velocity for premium implant technologies across ambulatory surgery centers. FDA Class III medical device oversight of intraocular lenses creates layered compliance barriers that filter market entrants. The Southeast's retiree population concentration in Florida is expanding the addressable patient pool for cataract treatment applications.
Age Related Vision Dysfunction Market Vendor Landscape
Swiss and German producers anchor the premium optical implant tier; US-based biopharmaceutical specialists hold retinal disease management through anti-VEGF platforms. The vendor base concentrates among integrated pharmaceutical-ophthalmology conglomerates and specialized surgical device manufacturers with established clinical data portfolios. Three archetypes dominate: chemical-integrated implant fabricators, biologics-focused retinal therapy developers, and diversified vision care conglomerates. Competitive moves center on M&A for manufacturing capacity and strategic partnerships for teleophthalmology channel access.
Within the integrated pharmaceutical-ophthalmology tier, Novartis and Roche exemplify platform consolidation across diagnostic innovation and therapy development. Regeneron Pharmaceuticals occupies a specialized position representing biologics manufacturing archetypes for retinal disease applications. These three entities anchor competitive positioning through distinct strategic postures—Novartis through pharmaceutical-ophthalmology integration, Roche through diagnostic-lead expansion, and Regeneron through focused biologics specialization.
| Leading Market Players |
|---|
| Novartis |
| Regeneron Pharmaceuticals |
| Roche |
| Bayer |
| Alcon |
| Bausch + Lomb |
| Genentech |
| Johnson & Johnson Vision |
| AbbVie |
| Others |
Supply Flow & Price Mechanics
Backward integration into hydrophobic acrylic polymer production anchors pricing power for German and Swiss optical implant manufacturers, compressing margin exposure to raw material volatility while elevating barriers for contract-dependent competitors across the EU MDR certification landscape.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for premium intraocular lenses as Bavarian medical device clusters expand hydrophobic acrylic fabrication. Three-tier pricing structure across premium, standard, and economy levels separates EMA MDR-certified manufacturers from notified body backlog-affected entrants. Pricing pressure stems from corrective lens substitution in Italy's national health service regions. Early-stage presbyopia patients demonstrate highest price sensitivity; cataract treatment candidates show lowest.
Supply Chain Analysis
Dual-sourcing requirements from EMA MDR frameworks are mandating multi-supplier qualification for silicone polymer inputs across German, Swiss, and Austrian chemical fabricators. Raw material dependencies center on hydrophobic acrylic resins, silicone elastomers, and precision molding equipment. Single-source vulnerability concentrates in Swiss polymer production for premium optic substrates. Distribution runs through ophthalmology clinic procurement committees and hospital GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in surgical implant tiers where biocompatible material advances justify premium positioning, while home care vision therapy opens reimbursement-aligned volume growth.
For Market Incumbents: Anchor market position through captive control of hydrophobic acrylic supply chains and accelerated EMA MDR certification investments. Defensive priorities include neutralizing accommodating IOL substitution threats from emerging device manufacturers and securing exclusive clinic procurement contracts in Munich, Paris, and Milan clusters. Capacity additions in German notified body processing capabilities represent a critical lever. For New Entrants and Emerging Players: Teleophthalmology platform providers offer the most penetrable channel partnership avenue for digital refractive training solutions. White-space targets include rural Italian regional health systems and French home care vision therapy reimbursement pathways. Go-to-market execution should prioritize ANSM-aligned clinical validation for assistive device integration. For Investors and Strategic Acquirers: Consolidation pressure builds where EMA MDR compliance burdens exceed standalone R&D payback capacity for mid-tier optical implant manufacturers. Long-term viability favors integrated pharmaceutical-ophthalmology platforms with established Eudamed adverse event reporting infrastructure. Acquisition target archetypes include specialized biologics manufacturers for retinal disease and teleophthalmology channel specialists. Watch notified body capacity expansion as inflection signal for certification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Certification Investment | Accelerates market entry velocity through reduced notified body backlog exposure. |
| Teleophthalmology Channel Partnership | Compresses referral pathways in Italian regional health systems for rural cataract patients. |
| Biocompatible Material R&D Expansion | Extends device longevity through hydrophobic acrylic and silicone optic platform advances. |
| Home Care Reimbursement Strategy | Opens ANSM-aligned pathways for digital refractive training platform adoption in France. |
| CSRD Sustainability Disclosure Alignment | Creates procurement preference for optical implant manufacturers with validated lifecycle data. |
Methodological Framework
Direct dialogue with ophthalmology clinic directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers grounded the qualitative foundation. Secondary validation drew from EMA MDR submission databases, Eudamed adverse event registries, ANSM post-market surveillance filings, and ISO 11979 biocompatibility test records. Bottom-up and top-down triangulation reconciled procedure volume estimates with manufacturer shipment data.
Bottom-up modeling aggregated clinic-level cataract intervention volumes and presbyopia management service line expansion across German, French, and Italian metropolitan clusters. Top-down validation cross-checked against EMA-designated notified body certification throughput and optical implant import records. Segmentation dimensions spanned product type, technology platform, end-user setting, and application severity. CAGRs derived from patient demographic projections and reimbursement policy trajectory assumptions across the analysis window.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EMA MDR enforcement intensity and Medicare reimbursement policy shifts for premium implant technologies. Deviation in notified body capacity expansion timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Pseudotumor Cerebri Market
Ophthalmology
Global Ocular Inflammation Treatment Market
Ophthalmology
US Ophthalmic Sutures Market
Ophthalmology
Retinal Vein Occlusion Treatment Market
Ophthalmology
Ophthalmic Eye Drops Market
Ophthalmology
Global Ophthalmic Viscoelastic Devices Market
Ophthalmology
Ptosis Treatment Market
Ophthalmology
3D Printed Ophthalmic Implants Market
Ophthalmology
Optic Nerve Glioma Market
Ophthalmology
Dacryocystitis Market
Ophthalmology
Head Band Ophthalmoscopes Market
Ophthalmology
Australia Ophthalmic Devices Market
Ophthalmology
Europe Ophthalmology Drug and Device Market
Ophthalmology
Global Proliferative Vitreoretinopathy Market
Ophthalmology
Global Glaucoma Treatment Market
Ophthalmology
Global Posterior Segment Eye Disorders Market