
 Global Glaucoma Treatment Market | 2026-2036
Global Glaucoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glaucoma Treatment Market Foresight
Subscription-based medication adherence monitoring is recalibrating how pharmaceutical firms package chronic care for glaucoma patients. Novartis leverages its established ophthalmology infrastructure to sustain patient retention across long-term prostaglandin therapy regimens. Pfizer anchors its competitive stance through manufacturing scale in preservative-free formulation production.
Glaucoma treatment encompasses pharmacological, laser-based, and surgical interventions designed to reduce intraocular pressure and prevent optic nerve damage, with prostaglandin analogs typically achieving 25-33% pressure reduction as first-line therapy. Medications dominate current revenue flows due to daily chronic administration requirements, while implantable devices represent the fastest-expanding delivery mode as sustained-release platforms reduce patient compliance burdens. Laser therapy occupies a mature but stable position as an intermediate intervention between drops and incisional surgery.
The FDA, EMA, and Japan's PMDA collectively enforce stringent efficacy and safety benchmarks for intraocular pressure-lowering therapies, with the FDA's Breakthrough Therapy designation accelerating pathways for sustained-release implants. The EU Medical Device Regulation imposes elevated clinical evidence standards on surgical micro-shunts and drainage devices, reshaping market access timelines for device manufacturers. Stakeholders must monitor how regulator convergence on real-world evidence requirements will reshape post-market surveillance investments and competitive differentiation strategies.
Market Dynamics
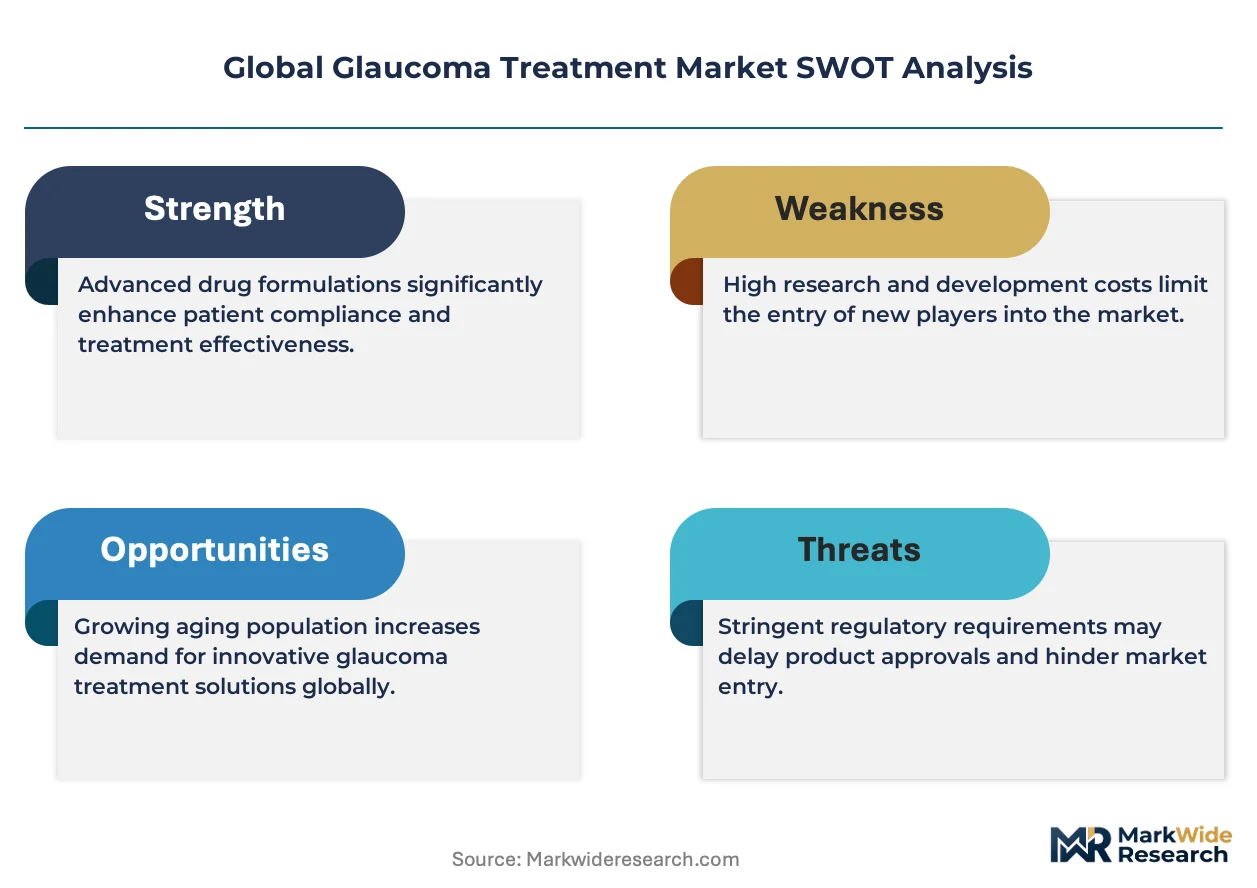
The FDA's Breakthrough Therapy designation for sustained-release intraocular implants is compressing development timelines and redirecting R&D budgets toward long-acting delivery platforms that reduce patient compliance burdens.
Growth Catalysts
- Japan's PMDA Accelerated Review Pathway:Sustained-release implants gain priority review status, shortening market access timelines for device manufacturers targeting aging populations in Tokyo and Osaka metropolitan clusters.
- Ophthalmic Clinic Consolidation:Large clinic chains in the United States and Germany are standardizing procurement around minimally invasive surgical platforms, creating volume pull for micro-shunt devices.
- Preservative-Free Formulation Demand:Surface-active polymer technologies enable multi-dose bottles without benzalkonium chloride, addressing ocular surface toxicity concerns in chronic prostaglandin therapy.
Market Restraints
- EU MDR Clinical Evidence Burden:Surgical drainage devices face elevated clinical trial requirements under the Medical Device Regulation, extending certification timelines by 18-24 months for European market entry.
- Active Pharmaceutical Ingredient Concentration:Three contract manufacturers in India supply over 60% of latanoprost API, creating supply vulnerability for generic prostaglandin producers.
- Laser Therapy Substitution Ceiling:Selective laser trabeculoplasty achieves pressure reduction comparable to monotherapy but shows durability limitations beyond 36 months, capping displacement of pharmaceutical first-line use.
Strategic Opportunities
- Brazil's ANVISA Streamlined Registration:The country's pharmaceutical regulator offers priority review for sustained-release implants, opening Latin America's largest ophthalmology market with 1.2 million diagnosed glaucoma patients.
- Telemedicine-Enabled Adherence Monitoring:Remote intraocular pressure tracking via home tonometers creates subscription revenue streams and reduces drop-out rates in rural United States markets.
- Biodegradable Polymer Convergence:PLGA-polymer matrix technology combined with micro-needle injection platforms enables office-based sustained-release administration without surgical implantation.
Industry Challenges
- Ocular Pharmacokinetic Modeling Talent Scarcity:Device firms struggle to recruit computational biologists capable of predicting anterior chamber drug distribution for implant design optimization.
- Legacy EMR Integration Friction:New adherence monitoring platforms require costly API development to interface with entrenched electronic medical record systems in United States hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glaucoma Treatment Market |
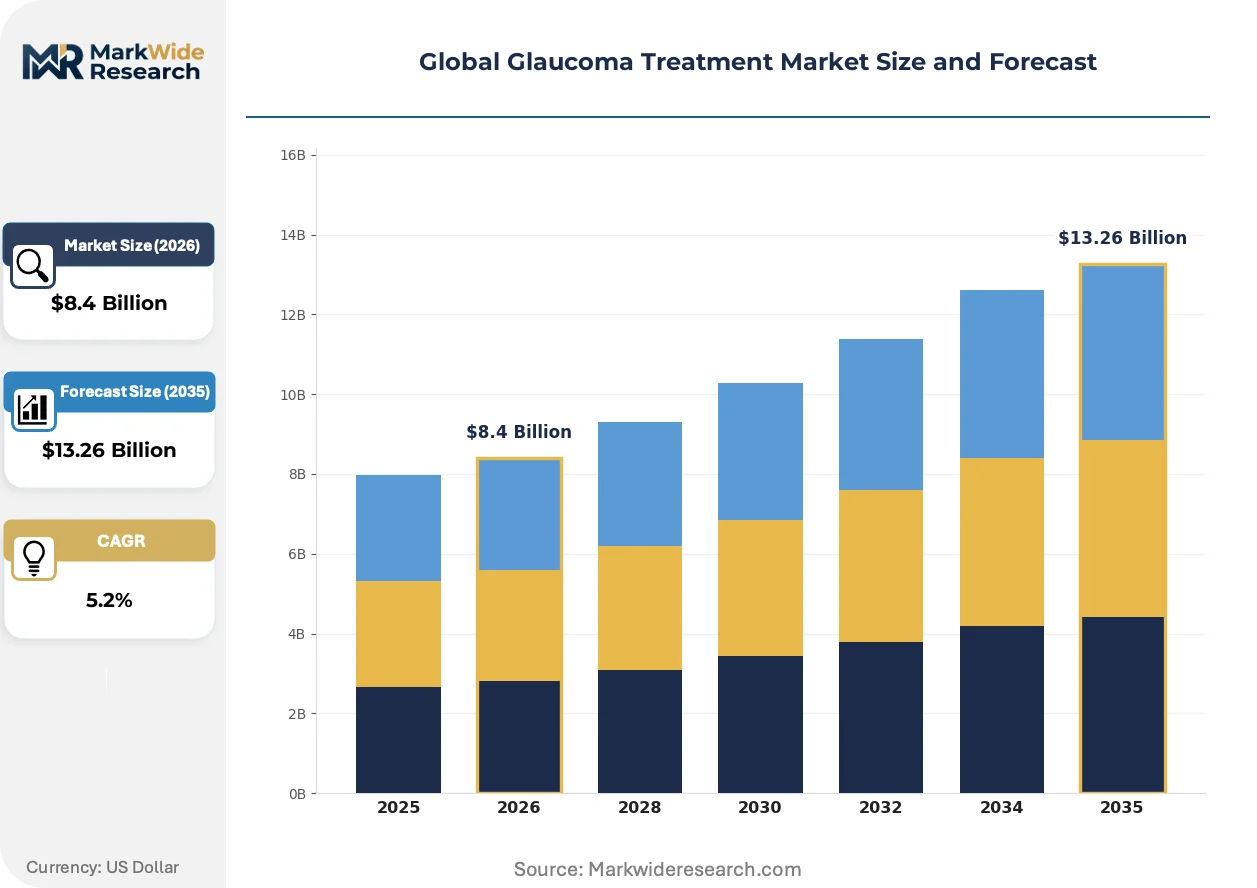
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Laser Therapy, Surgical Devices, Diagnostic Equipment, Monitoring Tools Therapy Area: Open-Angle Glaucoma, Angle-Closure Glaucoma, Normal-Tension Glaucoma, Secondary Glaucoma, Congenital Glaucoma End User: Ophthalmic Clinics, Eye Hospitals, Ambulatory Surgical Centers, Research Institutes, Specialty Care Centers Delivery Mode: Topical, Oral, Intracameral Injection, Laser Procedures, Implantable Devices |
| Companies Covered | AbbVie, Novartis, Pfizer, Bausch + Lomb, Alcon, Aerie Pharmaceuticals, Merck, Santen Pharmaceutical, Teva Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glaucoma Treatment Market Shifts & Advancements
Sustained-release drug delivery platforms are compressing the chronic care model for glaucoma, shifting value capture from daily pharmaceutical consumption toward long-acting interventions that reduce patient touchpoints.
Biodegradable intracameral implants containing bimatoprost are absorbing market share from conventional eye drop regimens by eliminating dosing frequency as a compliance variable. Academic medical centers in Boston and Rotterdam are piloting these devices in treatment-naïve patients, with early adoption signals suggesting preference for single-administration alternatives among working-age demographics. The technology is absorbing reimbursement complexity previously managed through pharmacy benefit structures, forcing payers to recalibrate cost-allocation models across surgical and pharmaceutical silos.
The EU Medical Device Regulation's post-market surveillance requirements are mandating real-world evidence collection for drainage devices, compelling manufacturers to fund multi-year patient registries. This policy shift elevates compliance costs for mid-tier device firms while creating data assets that larger competitors leverage for product differentiation. German and French notified bodies are applying divergent interpretations of clinical evidence standards, fragmenting market access timelines within the European Union.
Direct-to-patient subscription models for medication adherence monitoring are disrupting traditional pharmacy distribution channels in the United States. Patients receive connected devices measuring intraocular pressure at home, with data feeds triggering automated refill protocols and physician alerts. This behavioral shift concentrates most visibly in Medicare Advantage plans seeking HEDIS quality metric improvements, where remote monitoring reduces emergency department visits for acute pressure spikes.
Global Glaucoma Treatment Market Segmentation
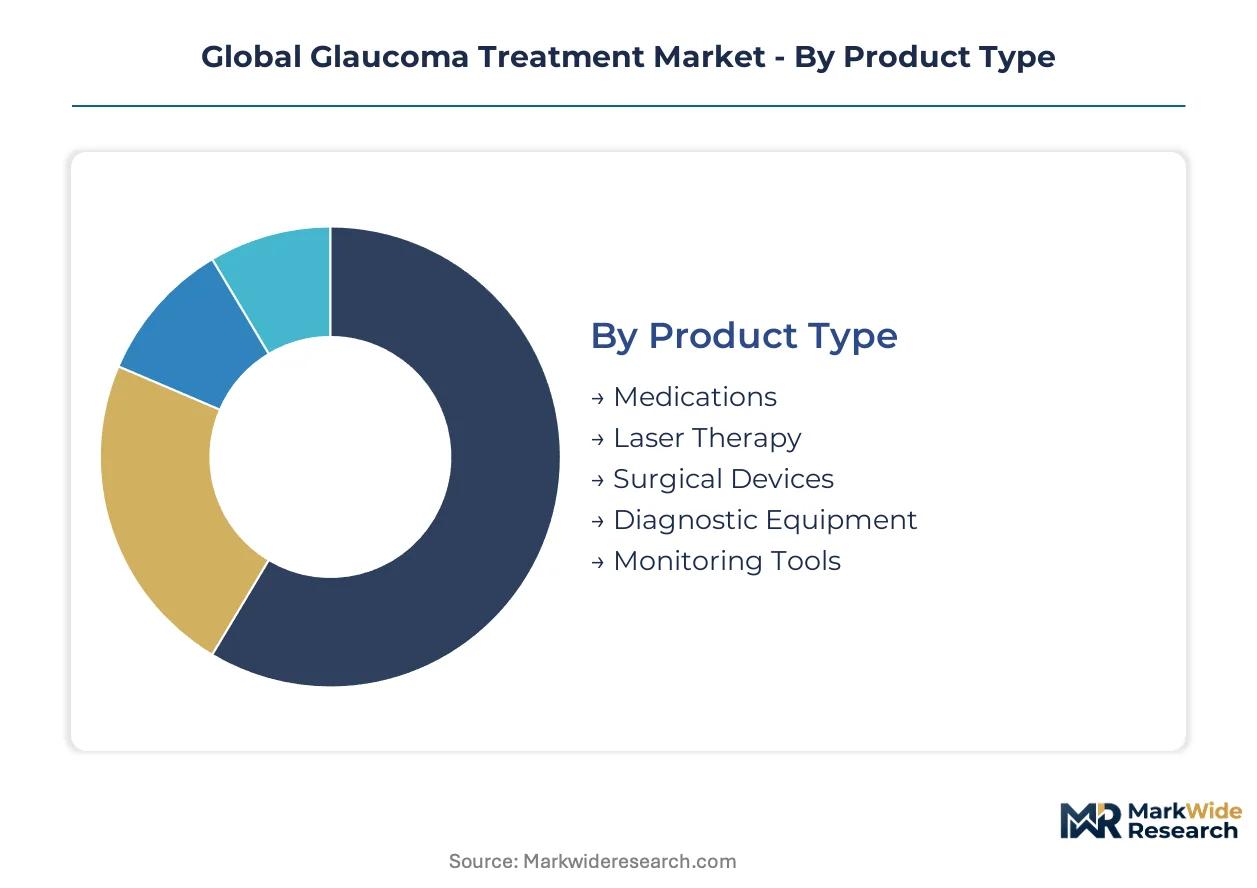
Glaucoma treatment segmentation reveals divergent commercial models across chronic pharmaceutical management versus acute surgical intervention. Manufacturers must align R&D portfolios with distinct reimbursement pathways, patient compliance profiles, and regulatory evidence requirements that vary sharply by delivery mechanism and care setting.
Product Type:
Customization intensity spans from mass-produced generic formulations to patient-matched surgical implants requiring operative planning.
- Medications:Prostaglandin analogs, beta-blockers, and carbonic anhydrase inhibitors formulated as preserved or preservative-free ophthalmic solutions dominate prescription volumes. Demand concentrates in Germany and Japan where aging populations sustain chronic refill patterns, though benzalkonium chloride toxicity concerns are redirecting procurement toward surface-active polymer multi-dose systems.
- Laser Therapy:Selective laser trabeculoplasty and argon laser trabeculoplasty devices deliver intermediate intervention between pharmaceutical and surgical management. United States ophthalmic clinics in metropolitan clusters standardize around single-platform laser systems to streamline technician training and maintenance contracts.
- Surgical Devices:Trabeculectomy kits, aqueous shunts, and micro-invasive glaucoma surgery tools address refractory cases.
- Diagnostic Equipment:Optical coherence tomography and visual field analyzers enable early structural assessment.
- Monitoring Tools:Home tonometry and adherence tracking platforms support remote patient management.
Leading the category by volume: Medications. Expanding most quickly: Surgical Devices.
Therapy Area:
Prevalence distribution and treatment resistance patterns create distinct addressable markets across glaucoma subtypes.
- Open-Angle Glaucoma:The predominant subtype characterized by gradual trabecular meshwork dysfunction and elevated intraocular pressure. First-line prostaglandin therapy captures sustained volumes in United States Medicare and Japanese national health insurance formularies.
- Angle-Closure Glaucoma:Acute or chronic presentation requiring immediate pressure reduction through laser iridotomy or surgical intervention. Emergency presentation patterns in Indian and Chinese urban centers drive demand for rapid-access laser platforms.
- Normal-Tension Glaucoma:Optic nerve damage without elevated pressure, challenging conventional therapeutic targets.
- Secondary Glaucoma:Pressure elevation from trauma, steroid use, or uveitis requiring etiology-specific management.
- Congenital Glaucoma:Rare pediatric presentation demanding specialized surgical expertise and microsurgical instrumentation.
Primary volume concentration: Open-Angle Glaucoma. Steepest unmet need trajectory: Normal-Tension Glaucoma.
End User:
Procurement sophistication ranges from centralized hospital purchasing to distributed clinic inventory management.
- Ophthalmic Clinics:Independent and chain-affiliated outpatient facilities managing stable chronic patients through pharmaceutical and laser modalities. Consolidated clinic networks in the United States negotiate formulary placement directly with prostaglandin manufacturers.
- Eye Hospitals:Tertiary referral centers handling complex surgical cases and fellowship training. Academic medical centers in Boston and Rotterdam pilot sustained-release implants, generating real-world evidence for regulatory submissions.
- Ambulatory Surgical Centers:Focused procedure volume with compressed episode-of-care economics.
- Research Institutes:Early-phase clinical trial sites for novel delivery mechanisms.
- Specialty Care Centers:Glaucoma-specific practices with advanced imaging and surgical capabilities.
Highest procedure value capture: Eye Hospitals. Fastest site-of-service shift: Ambulatory Surgical Centers.
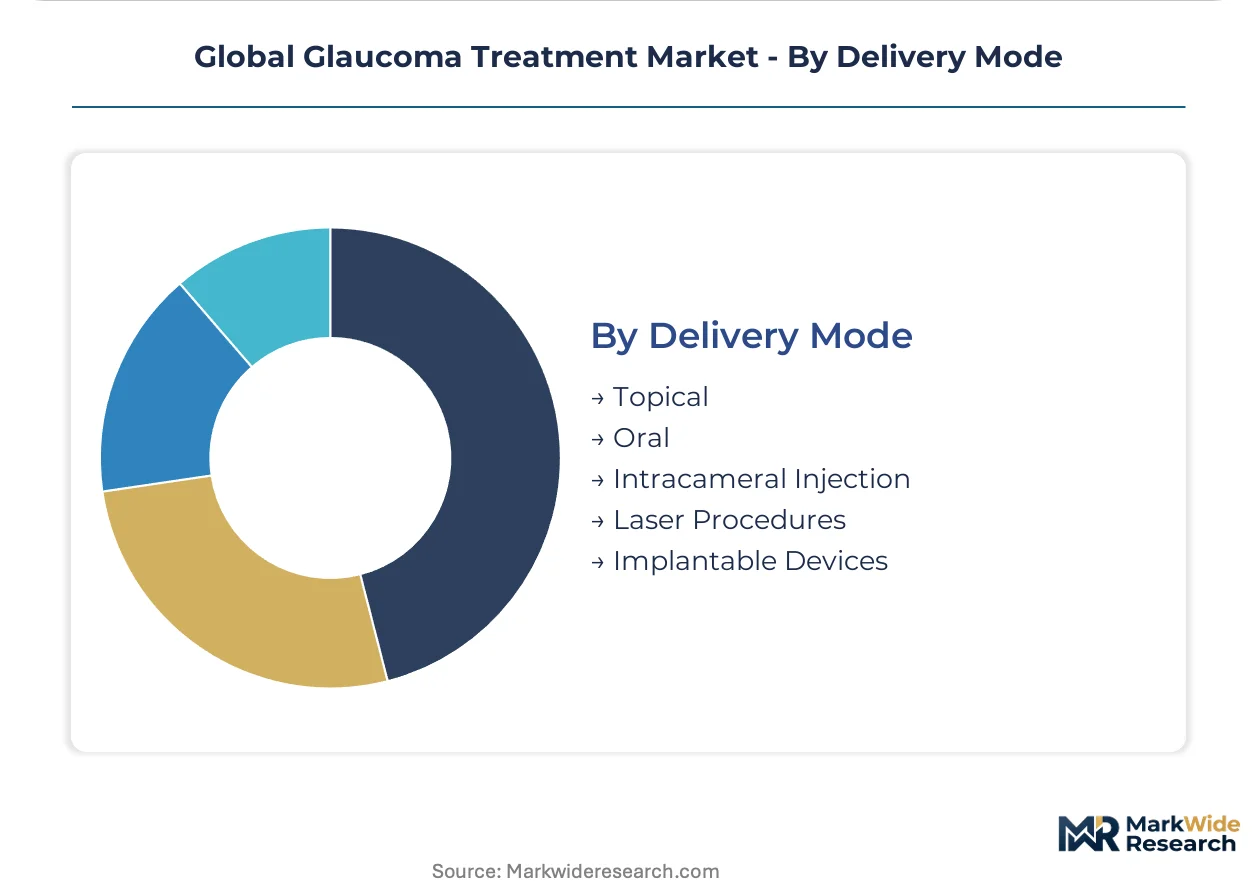
Delivery Mode:
Patient burden and compliance economics drive migration from frequent self-administration toward long-acting interventions.
- Topical:Eye drops requiring patient adherence to daily dosing regimens, with preservative-free formulations commanding premium positioning. Surface toxicity concerns in chronic Japanese and German populations sustain multi-dose bottle innovation.
- Implantable Devices:Sustained-release intracameral and subconjunctival implants eliminating dosing frequency as a compliance variable. FDA Breakthrough Therapy designations compress development timelines for bimatoprost-eluting biodegradable matrices.
- Oral:Systemic carbonic anhydrase inhibitors reserved for refractory cases due to side effect profiles.
- Intracameral Injection:Office-based depot administration without surgical implantation.
- Laser Procedures:Non-pharmaceutical pressure reduction with defined durability limitations.
Dominant current modality: Topical. Gaining share fastest: Implantable Devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's Kanto corridor anchors sustained-release implant development, with academic medical centers piloting biodegradable intracameral devices that eliminate daily dosing burdens for Japan's aging glaucoma population.
United States
Medicare Advantage plans drive remote intraocular pressure monitoring adoption across metropolitan clusters in Texas and Florida. The FDA's Breakthrough Therapy designation compresses development timelines for bimatoprost-eluting implants. Boston's academic medical centers generate real-world evidence for sustained-release platforms in treatment-naïve patients.
Germany
Aging populations in Bavaria and North Rhine-Westphalia sustain chronic prostaglandin refill patterns through statutory health insurance formularies. The EU Medical Device Regulation imposes elevated clinical evidence standards on surgical micro-shunts, extending certification timelines for drainage device manufacturers. Frankfurt's ophthalmic clinic chains standardize procurement around minimally invasive surgical platforms.
Japan
PMDA's Accelerated Review Pathway grants priority status to sustained-release implants targeting Tokyo and Osaka metropolitan clusters. Surface toxicity concerns redirect procurement toward preservative-free formulations using surface-active polymer multi-dose systems. Nagoya's device manufacturers collaborate with academic centers on office-based depot administration technologies.
Brazil
ANVISA's streamlined registration pathway opens Latin America's largest ophthalmology market with diagnosed patient concentrations in São Paulo and Rio de Janeiro. Sustained-release implants receive priority review status, reducing market access timelines for foreign device manufacturers. Minas Gerais emerges as a hub for telemedicine-enabled adherence monitoring pilot programs.
India
Contract manufacturers in Hyderabad and Ahmedabad supply over sixty percent of latanoprost active pharmaceutical ingredient, creating supply concentration vulnerability for generic prostaglandin producers. The national pharmaceutical regulator enforces stringent good manufacturing practice standards on export-oriented facilities. Delhi-NCR's tertiary eye hospitals manage complex surgical referrals from secondary care networks across northern states.
Global Glaucoma Treatment Market Competitive Landscape
Capital-heavy pharmaceutical manufacturers compete with asset-light device designers across divergent reimbursement pathways. The market structures around three tiers: integrated ophthalmology divisions of diversified conglomerates, standalone specialty pharmaceutical firms, and surgical device pure-plays. Strategic moves concentrate on sustained-release delivery platform acquisitions and preservative-free formulation capacity expansion. Geographic licensing agreements for biodegradable polymer technologies reshape competitive boundaries between pharmaceutical and device domains.
Within the integrated conglomerate tier, Novartis and Pfizer occupy positions that leverage established ophthalmology infrastructure against manufacturing scale advantages. Novartis exemplifies the patient retention archetype through long-term prostaglandin therapy regimens, while Pfizer anchors the manufacturing efficiency vector in preservative-free production. Among standalone specialty players, Aerie Pharmaceuticals represents the sustained-release innovation archetype, and Santen Pharmaceutical sits within the Asia-Pacific geographic specialization tier. Alcon and Bausch + Lomb exemplify the surgical-device-dominant archetype with historical strength in micro-invasive glaucoma surgery platforms.
| Leading Market Players |
|---|
| AbbVie |
| Novartis |
| Pfizer |
| Bausch + Lomb |
| Alcon |
| Aerie Pharmaceuticals |
| Merck |
| Santen Pharmaceutical |
| Teva Pharmaceutical |
| Others |
Supply & Pricing Matrix
Biodegradable polymer matrix manufacturing is concentrating production economics among three contract manufacturers in India while simultaneously elevating cost barriers for preservative-free formulation facilities in Europe. This dual shift compresses margins for generic prostaglandin producers while rewarding integrated players with captive API supply.
Pricing Analysis
Value-based pricing anchors on pressure reduction durability and compliance elimination rather than unit dose economics. Three-tier pricing structure across premium sustained-release implants, standard preservative-free formulations, and economy generic prostaglandins stratifies the market. Cost compression in the generic tier intensifies because Indian API supply concentration enables aggressive tender competition. Ophthalmic clinic chains in Germany exhibit highest price sensitivity due to statutory insurance reimbursement ceilings, while United States Medicare Advantage plans absorb premium implant pricing for HEDIS metric gains.
Supply Chain Analysis
Workforce availability for ocular pharmacokinetic modeling constrains device design optimization in Boston and Rotterdam academic clusters, forcing manufacturers to recruit from computational biology programs in Basel and Singapore. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland, with latanoprost precursor chemistry drawing from specialized fermentation capacity. Single-source vulnerability permeates the biodegradable polymer feedstock segment where three suppliers control PLGA resin grades. Distribution runs through ophthalmic clinic procurement consortia in Germany and United States group purchasing organizations for hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into sustained-release polymer manufacturing and API fermentation capacity is reshaping competitive economics as device firms seek supply security and pharmaceutical players pursue margin capture.
For Market Incumbents: Anticipate substitution pressure from biodegradable intracameral implants by securing exclusive polymer sourcing agreements and expanding preservative-free bottling capacity in Switzerland. Laser therapy platform consolidation in United States metropolitan clusters threatens procedural volume retention for pharmaceutical divisions. Backward integration into latanoprost API production insulates margin position against Indian contract manufacturer pricing volatility. For New Entrants and Emerging Players: Begin with telemedicine-enabled adherence monitoring subscriptions targeting rural United States Medicare Advantage networks where remote intraocular pressure tracking remains underpenetrated. Brazil's ANVISA priority review pathway for sustained-release implants offers the most penetrable regulatory entry point in Latin America. Direct-to-patient device distribution bypasses entrenched pharmacy benefit structures. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated ophthalmology conglomerates seeking sustained-release platform technology. Five-to-ten year viability hinges on reimbursement consolidation across surgical and pharmaceutical silos. Acquisition target archetype: device pure-plays with biodegradable polymer IP and FDA Breakthrough Therapy designation. Watch for PMDA accelerated review decisions as inflection indicators for Asia-Pacific market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Polymer Manufacturing Scale-Up | Captive PLGA resin production secures implant supply against feedstock concentration in three global suppliers. |
| Preservative-Free Formulation Facility Expansion | Surface-active polymer multi-dose capacity addresses benzalkonium chloride toxicity concerns in German and Japanese populations. |
| FDA Breakthrough Therapy Pathway Pursuit | Accelerated review compresses development timelines for bimatoprost-eluting intracameral implants. |
| Telemedicine Platform Integration | Home tonometer data feeds automate refill protocols and reduce dropout rates in rural United States markets. |
| Asia-Pacific Licensing Agreement Execution | Sustained-release technology partnerships with Nagoya device manufacturers access PMDA priority review channels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with glaucoma specialists, hospital purchasing committee members, formulary directors, and biomedical engineers validated demand assumptions. FDA 510(k) submissions, EMA centralized procedure documents, PMDA review reports, and clinical trial registries supplied procedural and approval timeline data. Bottom-up modeling of implant procedure volumes and top-down pharmaceutical consumption estimates triangulated market sizing.
Granularity-level modeling dissected the analysis window by delivery mode, therapy area, end-user facility type, and regional regulatory cluster. CAGRs derived from procedure volume growth rates, pricing trajectory assumptions, and technology substitution curves. Forecast inputs incorporated PMDA accelerated review probability weightings, EU MDR certification timeline distributions, and Medicare Advantage remote monitoring adoption curves.
Underlying measurement precision varies by segment; sustained-release implant forecasts carry tighter precision than generic pharmaceutical volumes due to concentrated manufacturer disclosure. Forecasts reflect assumptions on reimbursement consolidation timing and regulatory convergence trajectories. Material deviation in FDA Breakthrough Therapy grant rates or Indian API export policy warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Choroidal Neovascularization Market
Ophthalmology
Choroideremia Treatment Market
Ophthalmology
Ophthalmology Devices Market
Ophthalmology
Retina Health Market
Ophthalmology
Global Automated Ophthalmic Perimeters Market
Ophthalmology
Ophthalmic Ultrasound Systems Market
Ophthalmology
Vernal Keratoconjunctivitis Treatment Market
Ophthalmology
Japan Ophthalmic Devices and Drugs Market
Ophthalmology
Global Vitreous Tamponades Market
Ophthalmology
Global Tonometer Market
Ophthalmology
UAE Ophthalmic Devices Market
Ophthalmology
Global Ophthalmic Knives Market
Ophthalmology
Aesthetic Ophthalmology Device Market
Ophthalmology
Global Aphakia Market
Ophthalmology
Panuveitis Treatment Market
Ophthalmology
Non-Infectious Macular Edema Treatment Market