
 Capsulorhexis Forceps Market | 2026-2036
Capsulorhexis Forceps Market Size, Share, and Industry Trends Forecast 2026-2036
Capsulorhexis Forceps Market Analytics
German precision instrument manufacturing is rebalancing toward ophthalmic microsurgery as Asian producers scale capacity. ASICO LLC leverages its R&D intensity in titanium alloy forceps to sustain technical leadership in North American cataract suites. Carl Zeiss Meditec AG anchors European demand through integrated surgical microscopy ecosystems that bundle capsulorhexis instruments. Katena Products Inc. competes on specialized tip geometries for complex anterior segment procedures.
Capsulorhexis forceps are microsurgical grasping instruments, typically manufactured from titanium alloy or stainless steel with tip diameters below 0.12 millimeters, designed to create a continuous curvilinear capsulotomy during cataract extraction. The instrument requires torsional rigidity and tactile feedback to prevent radial tears in the anterior lens capsule. Ophthalmic forceps command the largest volume share as the default category for routine phacoemulsification, while disposable forceps represent the fastest-growing segment as surgical centers prioritize infection control and eliminate reprocessing costs. Titanium alloy instruments capture premium margin pools due to their superior strength-to-weight ratio and biocompatibility profile.
FDA 510(k) clearance pathways govern U.S. market entry for capsulorhexis forceps, while the EU Medical Device Regulation imposes stricter clinical evidence requirements on reusable instruments. India's CDSCO aligns with ISO 13485 quality management standards to streamline domestic manufacturing approvals. Stakeholders must monitor how MDR transition timelines and FDA digital health pre-certification pilots reshape competitive access for smart instrument variants.
Market Dynamics
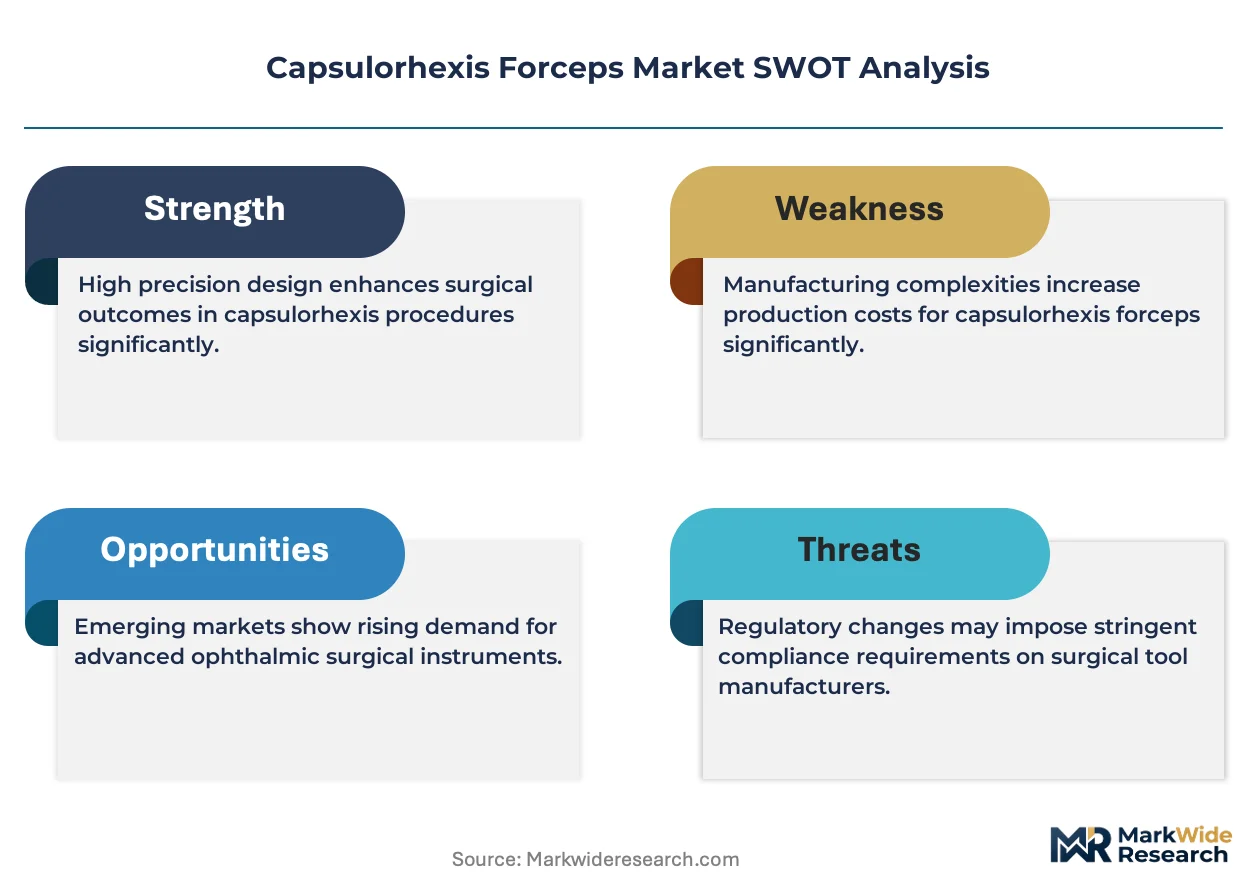
Titanium alloy sourcing concentration and the EU MDR's clinical evidence requirements are compressing vendor margins while accelerating consolidation among German and Japanese precision manufacturers.
Growth Catalysts
- India's PLI scheme for medical devices:Domestic production incentives are drawing contract manufacturers to establish titanium machining clusters in Gujarat and Tamil Nadu, reducing import dependency for South Asian cataract surgical centers.
- Ambulatory surgical center expansion:Freestanding ophthalmic clinics in the United States are installing dedicated phacoemulsification suites, generating instrument replacement cycles at 18-24 month intervals.
- Femtosecond laser-capsulorhexis hybrid workflows:Anterior segment surgeons are demanding forceps with enhanced tactile feedback to complement laser-assisted capsulotomy, elevating specifications for tip geometry and alloy purity.
Market Restraints
- Titanium sponge supply concentration:Russian and Chinese producers control 67% of global titanium feedstock, exposing instrument fabricators to price volatility and export restriction risk.
- EU MDR clinical evidence burdens:Reusable forceps now require biocompatibility testing documentation and post-market surveillance systems that add 14-18 months to certification timelines.
- Disposable polymer substitutes:Single-use capsulorhexis devices from polymer injection molding are capturing routine cases in cost-sensitive hospital purchasing, compressing addressable volume for premium reusable instruments.
Strategic Opportunities
- Saudi Arabia's Vision 2030 healthcare privatization:Greenfield ophthalmology hospitals in Riyadh and Jeddah are specifying European-manufactured titanium instruments for premium service tiers.
- Smart instrument integration:Forceps with embedded pressure sensors and RFID traceability are unifying surgical documentation with hospital inventory management systems.
- Brazil's SUS supplemental insurance expansion:Middle-income cataract patients in São Paulo and Minas Gerais are accessing phacoemulsification through private coverage, expanding addressable surgical volume.
Industry Challenges
- Micro-welding technician scarcity:Precision joining of 0.12mm titanium tips requires specialized electron beam operators, with training pipelines concentrated in Solingen and Seki City.
- ISO 13485 audit backlogs:Notified body capacity constraints are delaying quality management recertifications for mid-sized instrument manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capsulorhexis Forceps Market |
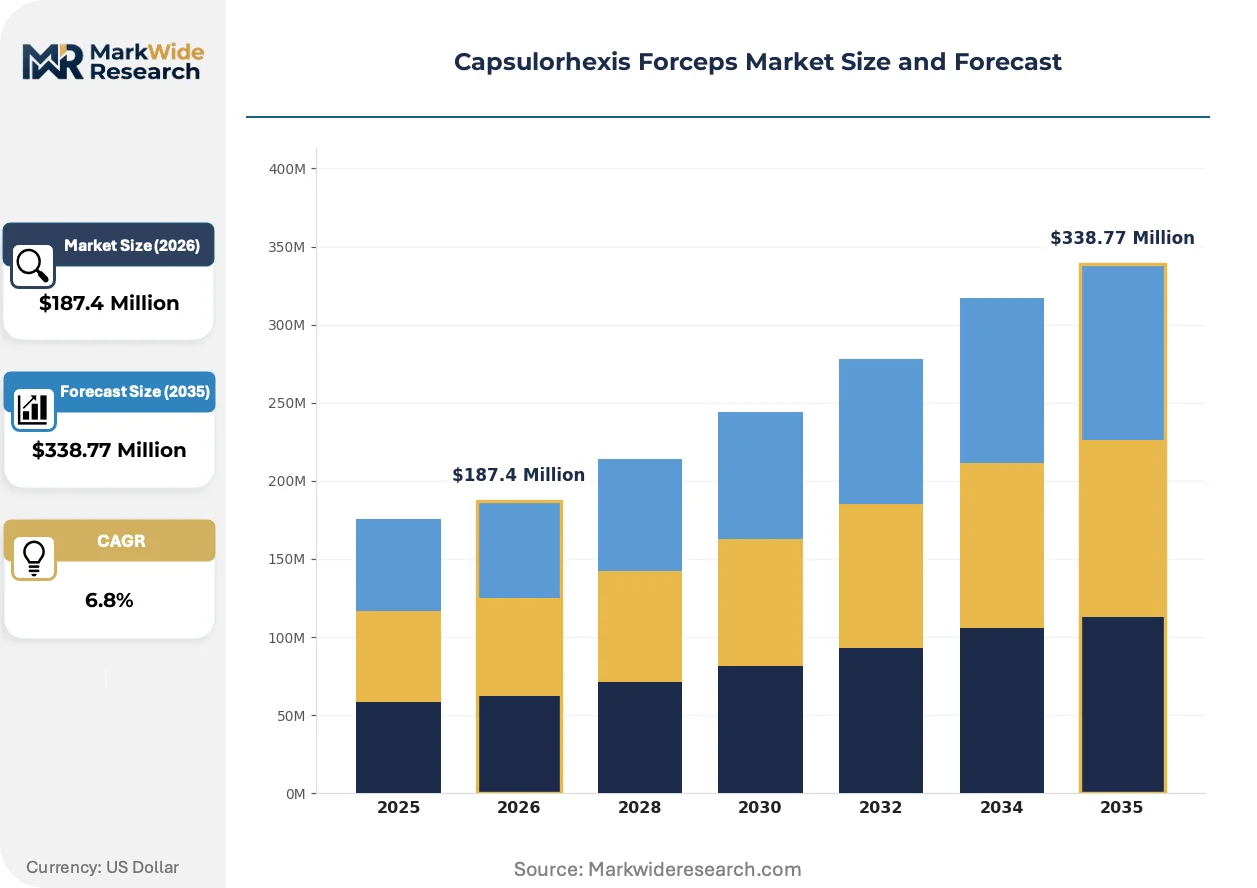
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ophthalmic Forceps, Disposable Forceps, Micro Forceps, Surgical Scissors End User: Ophthalmic Clinics, Hospitals, Surgical Centers, Research Institutions Material: Stainless Steel, Plastic, Titanium Alloy, Carbon Fiber Application: Cataract Surgery, Glaucoma Treatment, Retinal Surgery, Corneal Procedures |
| Companies Covered | ASICO LLC, Storz Ophthalmic Instruments Inc., Bausch + Lomb Incorporated, Carl Zeiss Meditec AG, Moria S.A., Katena Products Inc., Mastel Precision Surgical Instruments LLC, Thompson Surgical Instruments Inc., BVI Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capsulorhexis Forceps Market Evolving Landscape
Digital traceability mandates and laser-assisted surgical workflows are forcing instrument redesigns that prioritize data integration alongside mechanical precision.
Nano-textured titanium surfaces are unifying antimicrobial properties with tactile grip enhancement. Academic medical centers in Boston and Heidelberg are piloting these modified tip geometries for complex pediatric cataract cases. The technology is unifying infection control protocols with microsurgical performance standards, compressing the specification gap between premium and standard instrument tiers.
The EU Medical Device Regulation's Unique Device Identification requirements are mandating laser-etched data matrices on all reusable instruments. German manufacturers are retrofitting production lines with femtosecond marking systems to embed batch codes and sterilization cycle counts. High-volume cataract chains in France and the Netherlands are prioritizing UDI-compliant forceps to streamline their central sterile supply tracking.
Direct procurement from manufacturers is displacing traditional surgical instrument distributors in North American hospital systems. Integrated delivery networks in Texas and Ohio are negotiating multi-year forceps supply agreements that bundle reprocessing validation services. This consolidation is most visible in ophthalmology-focused ambulatory surgery centers seeking to reduce per-procedure instrument costs below distributor markup levels.
Capsulorhexis Forceps Market Segmentation
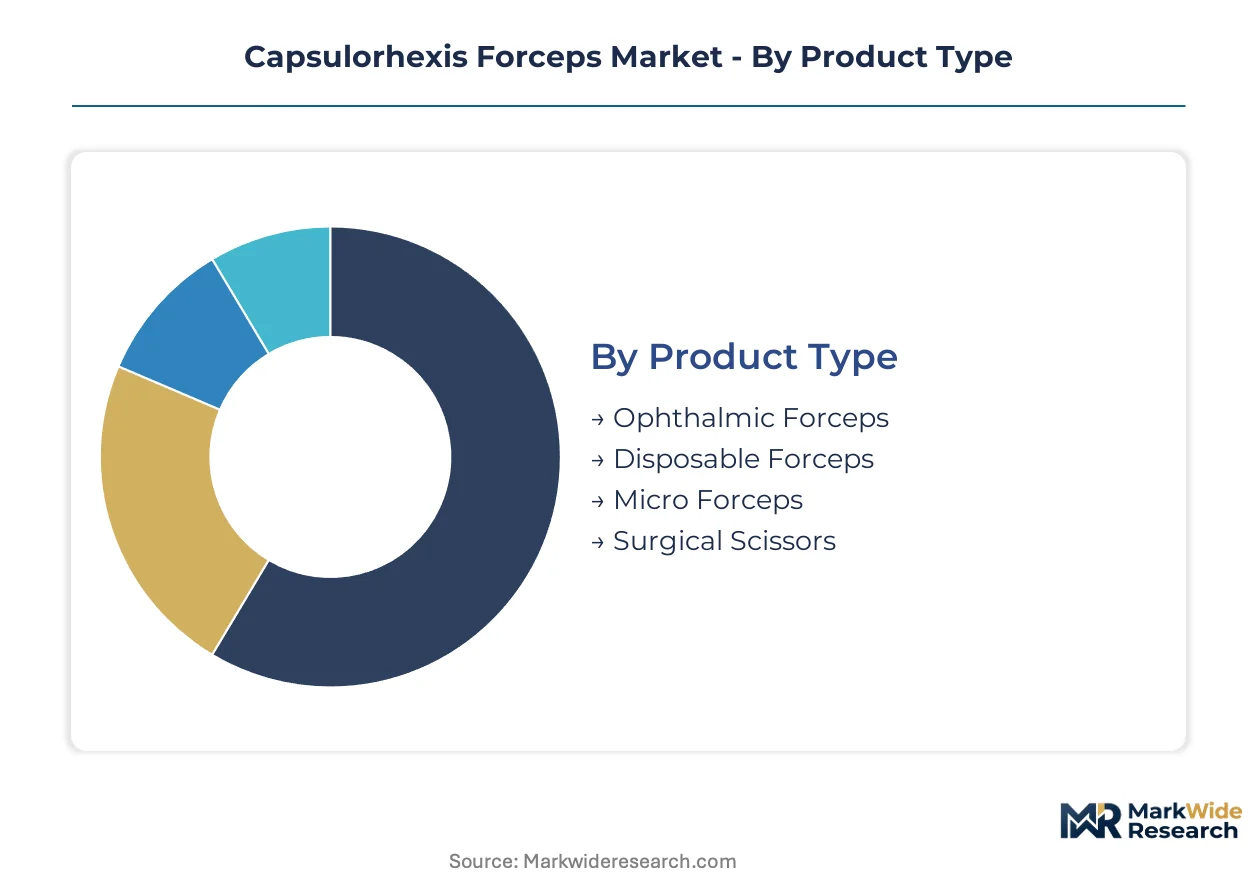
Segmentation in capsulorhexis forceps reveals how instrument specifications align with surgical workflow integration. Surgeons select devices based on reusability economics, tissue interaction requirements, and compatibility with phacoemulsification platforms.
Product Type:
Standalone single-function instruments dominate routine cataract suites, while hybrid-compatible designs serve laser-assisted workflows.
- Ophthalmic Forceps:Titanium alloy construction with sub-0.12mm tip diameters provides torsional rigidity for continuous curvilinear capsulotomy. German and US premium clinics specify these for complex anterior segment procedures requiring tactile feedback precision.
- Disposable Forceps:Polymer-based single-use instruments eliminate reprocessing validation costs. Ambulatory surgical centers in Texas and Ohio prioritize these for infection control compliance and inventory simplification.
- Micro Forceps:Ultra-fine tip geometries target pediatric cataract and traumatic lens extraction cases.
- Surgical Scissors:Ancillary cutting instruments complement forceps in capsular rescue scenarios.
Ophthalmic forceps lead volumes today; disposable forceps are gaining share fastest.
End User:
Procurement authority varies sharply across settings, with integrated delivery networks consolidating purchasing power differently than independent specialty practices.
- Ophthalmic Clinics:Freestanding facilities in São Paulo and Riyadh drive replacement cycles for premium titanium instruments. Vision 2030 healthcare privatization in Saudi Arabia specifies European-manufactured devices for greenfield facilities.
- Hospitals:Central sterile supply departments manage reprocessing workflows for reusable forceps. Academic medical centers in Boston pilot nano-textured titanium surfaces for complex pediatric cases.
- Surgical Centers:High-volume cataract chains in France and the Netherlands prioritize UDI-compliant instruments for supply tracking efficiency.
- Research Institutions:Heidelberg and Boston centers validate modified tip geometries for experimental anterior segment techniques.
Ophthalmic clinics anchor premium tier demand; surgical centers show steepest expansion trajectory.
Material:
Cost-performance tradeoffs separate routine case economics from complex procedure requirements.
- Titanium Alloy:Superior strength-to-weight ratio and biocompatibility profile command premium positioning. Russian and Chinese titanium sponge concentration exposes fabricators to supply volatility.
- Stainless Steel:Cost-effective alternative for standard phacoemulsification suites in cost-sensitive markets.
- Plastic:Single-use polymer substitutes capture routine cases through injection molding economies.
- Carbon Fiber:Experimental lightweight construction for specialized microsurgical applications.
Titanium alloy dominates premium positioning; plastic alternatives expand most quickly in disposable segments.
Application:
Procedure complexity dictates instrument specification tiers, with cataract extraction commanding the largest addressable base.
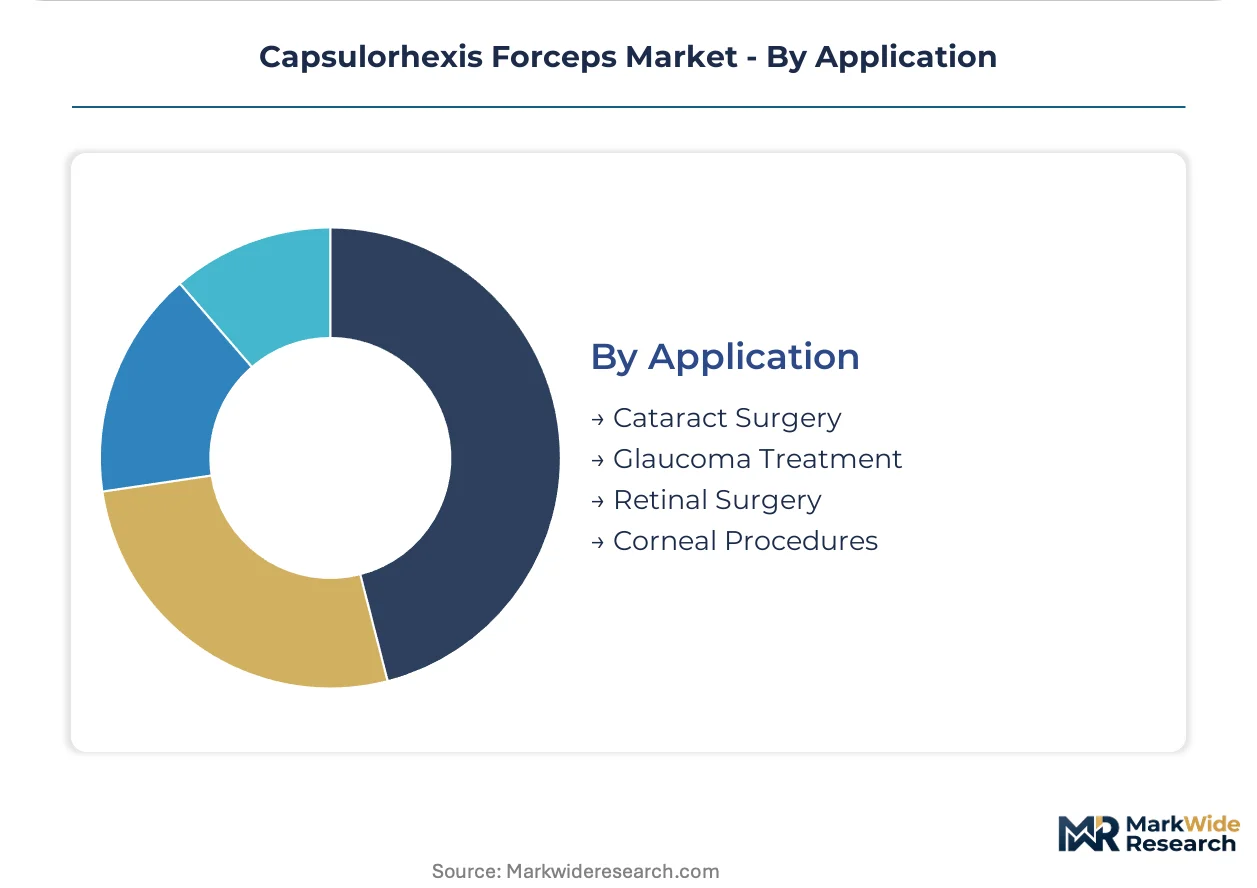
- Cataract Surgery:Phacoemulsification workflows require forceps compatible with both manual and femtosecond laser-assisted capsulotomy. Surgeon demand centers on tactile feedback enhancement for hybrid procedures.
- Glaucoma Treatment:Micro-invasive glaucoma surgery creates secondary demand for specialized anterior segment instruments.
- Retinal Surgery:Vitreoretinal procedures utilize modified forceps designs for lens management during combined operations.
- Corneal Procedures:Descemet's membrane endothelial keratoplasty requires distinct tip geometries from standard capsulorhexis specifications.
Cataract surgery anchors volume concentration; glaucoma treatment applications climb fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as India's PLI scheme for medical devices pulls titanium machining capacity away from EU MDR-constrained European fabricators. Cost-of-compliance gaps between jurisdictions now determine where precision instrument clusters consolidate.
United States
Ambulatory surgical centers in Texas and Ohio drive replacement cycles for premium titanium forceps at 18-24 month intervals. FDA 510(k) clearance pathways govern market entry, with digital health pre-certification pilots reshaping access for smart instrument variants. Boston's academic medical centers pilot nano-textured titanium surfaces for complex pediatric cataract procedures.
Germany
Solingen's precision instrument manufacturers face margin compression from EU MDR clinical evidence requirements that add 14-18 months to certification timelines. The country's national pharmaceutical regulator enforces biocompatibility testing documentation and post-market surveillance systems. Heidelberg medical centers validate modified tip geometries for experimental anterior segment techniques.
India
Gujarat and Tamil Nadu titanium machining clusters are expanding under CDSCO-aligned ISO 13485 quality management standards. The PLI scheme for medical devices incentivizes domestic production to reduce import dependency for South Asian cataract surgical centers. Mumbai and Chennai ophthalmic clinics drive replacement demand for standard-tier instruments.
Saudi Arabia
Vision 2030 healthcare privatization is greenlighting ophthalmology hospitals in Riyadh and Jeddah that specify European-manufactured titanium instruments for premium service tiers. The country's national pharmaceutical regulator harmonizes with Gulf Cooperation Council technical regulations. Private coverage expansion through supplemental insurance is broadening addressable surgical volume.
Japan
Seki City's electron beam micro-welding technicians anchor precision joining capabilities for 0.12mm titanium tips. The Pharmaceuticals and Medical Devices Agency enforces stringent quality management recertifications that constrain mid-sized manufacturer capacity. Tokyo and Osaka academic centers demand hybrid-compatible forceps designs for femtosecond laser-assisted workflows.
Capsulorhexis Forceps Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart instrument integration and disposable polymer substitutes. The vendor base stratifies across three tiers: German and Japanese precision manufacturers with captive titanium sourcing, mid-scale specialists competing on specialized tip geometries, and polymer injection molders capturing routine cases. Strategic archetypes include integrated surgical microscopy ecosystems, standalone instrument pure-plays, and contract manufacturers serving private-label demand. Dominant competitive moves center on direct procurement negotiations with integrated delivery networks and femtosecond marking system investments for UDI compliance.
Within the integrated ecosystem tier, Carl Zeiss Meditec AG anchors European demand through bundled surgical microscopy offerings. ASICO LLC and Katena Products Inc. represent the standalone precision instrument archetype, with the former emphasizing R&D intensity in titanium alloy forceps and the latter competing on specialized tip geometries for complex anterior segment procedures. These three companies exemplify how technical leadership in materials science and geometric precision separates premium positioning from commodity alternatives.
| Leading Market Players |
|---|
| ASICO LLC |
| Storz Ophthalmic Instruments Inc. |
| Bausch + Lomb Incorporated |
| Carl Zeiss Meditec AG |
| Moria S.A. |
| Katena Products Inc. |
| Mastel Precision Surgical Instruments LLC |
| Thompson Surgical Instruments Inc. |
| BVI Medical |
| Others |
Value Network & Pricing Analysis
Titanium sponge price volatility from Russian and Chinese producers cascades through German and Japanese precision manufacturers into three distinct pricing tiers for capsulorhexis forceps. Buyers in premium ophthalmic clinics absorb alloy purity premiums while ambulatory surgical centers in Texas and Ohio negotiate direct procurement contracts that eliminate distributor markups.
Pricing Analysis
Distributor margins of 35-45 percent historically separated manufacturers from hospital purchasing committees, though integrated delivery networks now command direct-to-manufacturer pricing that compresses channel economics. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with EU MDR-compliant titanium instruments commanding substantial premiums over stainless steel alternatives. Cost compression in the standard tier intensifies because polymer injection molders capture routine cataract cases with single-use substitutes. Research institutions and academic medical centers in Boston and Heidelberg show least price sensitivity, prioritizing tactile feedback precision over procurement cost.
Supply Chain Analysis
India's PLI scheme for medical devices reshapes sourcing patterns by incentivizing titanium machining clusters in Gujarat and Tamil Nadu that reduce import dependency for South Asian surgical centers. Russian and Chinese titanium sponge concentration exposes instrument fabricators to export restriction risk, while Japanese electron beam micro-welding capabilities in Seki City anchor precision joining for 0.12mm tip geometries. Distribution runs through specialized surgical instrument distributors in European markets, though North American integrated delivery networks increasingly consolidate procurement through multi-year direct agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The capsulorhexis forceps market functions as a stable compounder anchored by demographic-driven cataract procedure volume expansion across aging populations. Steady replacement cycles at 18-24 month intervals generate predictable revenue streams for precision instrument manufacturers.
For Market Incumbents: Anticipate margin compression from EU MDR clinical evidence burdens by accelerating femtosecond marking system investments for UDI compliance and securing captive titanium sourcing through backward integration into alloy supply. Disposable polymer substitutes threaten routine case volume; defend premium positioning through nano-textured surface R&D partnerships with academic medical centers. For New Entrants and Emerging Players: CDSCO-aligned ISO 13485 pathways in India open a window for contract manufacturers to serve private-label demand from European brands seeking to bypass EU MDR-constrained capacity. Target Saudi Arabia's Vision 2030 greenfield ophthalmology hospitals specifying European-manufactured instruments for premium tiers. Pursue smart instrument integration with embedded pressure sensors as the most penetrable white-space segment. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale specialists competing on specialized tip geometries for complex anterior segment procedures. Long-term viability across the projection horizon rests on regulatory navigation capabilities rather than commodity manufacturing scale. Monitor FDA digital health pre-certification pilot outcomes as the inflection signal for smart instrument variant market access.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates market entry for titanium alloy forceps variants in North American cataract suites. |
| CE Marking Pathway | Unlocks European premium clinic access despite EU MDR clinical evidence timeline extensions. |
| Hospital System Partnership | Secures multi-year direct procurement agreements with Texas and Ohio integrated delivery networks. |
| Software Companion Development | Integrates RFID traceability with hospital inventory management systems for UDI compliance. |
| Reimbursement Strategy | Aligns instrument specifications with Brazil SUS supplemental insurance expansion coverage criteria. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ophthalmic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, CDSCO registration databases, EU MDR notified body documentation, and hospital procurement contract records. Bottom-up surgical procedure volume estimates triangulated against top-down manufacturer shipment data across the analysis window.
Segment-weighting approaches applied product type, material grade, end-user setting, and application complexity dimensions to distribute value and volume outputs throughout the forecast period. CAGRs derived from regression analysis of historical replacement cycles, procedure growth trajectories, and regulatory timeline impacts. Forecast inputs incorporated femtosecond laser adoption curves and ambulatory surgical center expansion patterns specific to anterior segment surgery.
Revisions become necessary when titanium sponge export restrictions materialize, EU MDR notified body capacity constraints extend certification timelines, or polymer injection molding technologies achieve tactile feedback parity with titanium instruments. Forecasts reflect documented assumptions regarding surgeon preference stability and regulatory harmonization progress. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Oxygen Delivery Units Market
Medical Devices
Sweden Respiratory Devices Market
Medical Devices
Endometrial Ablation Devices Market
Medical Devices
Reusable Medical Battery Market
Medical Devices
MRI Guided Drug Delivery Market
Medical Devices
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market
Medical Devices
Injection Practice Pad Market
Medical Devices
Skull Clamp Market
Medical Devices
Hyperpigmentation Treatment Devices Market
Medical Devices
Laparoscopic Electrodes Market
Medical Devices
Brachytherapy Afterloaders Market
Medical Devices
Spain Respiratory Devices Market
Medical Devices
Neurosurgical Products Market
Medical Devices
Hearing Devices 3D Printing Market
Medical Devices
Artificial Vital Organs and Medical Bionics Market
Medical Devices
Medication Dispensing and Packaging Systems Market