
 US Tomato Paste Market | 2026-2036
US Tomato Paste Market Size, Share, and Industry Trends Forecast 2026-2036
US Tomato Paste Market Analytics
Food manufacturing buyers is redrawing procurement patterns across the US tomato paste landscape, shifting volume away from traditional retail channels toward industrial ingredient contracts. Morning Star Company leverages its vertically integrated Central Valley processing network to dominate bulk supply agreements with national sauce and soup manufacturers. Ingomar Packing Co. specializes in aseptic bag-in-box formats for food service distributors, while Conagra Brands sustains private-label and branded retail shelf presence through multi-regional co-packing arrangements.
Tomato paste consists of tomatoes reduced through evaporation to solids content ranging from 24% to 36%, serving as a foundational ingredient in sauces, soups, and prepared meals across commercial and consumer kitchens. Concentrated paste commands the largest production volume share due to its utility as an industrial input, though pouch packaging for retail households is gaining fastest as portion-control convenience reshapes supermarket purchasing. Tin can formats still anchor food service and institutional channels where shelf stability and portion standardization matter most.
The USDA Agricultural Marketing Service enforces grade standards for color, consistency, and defects that determine pricing tiers and buyer acceptance thresholds, while FDA hazard analysis rules under FSMA mandate preventive controls across processing facilities. California's state water regulations and air quality rules from the California Air Resources Board add compliance layers specific to the dominant production region. Stakeholders must monitor how drought-driven water allocation cuts intersect with energy cost volatility to reshape processing economics and geographic sourcing decisions.
Market Dynamics
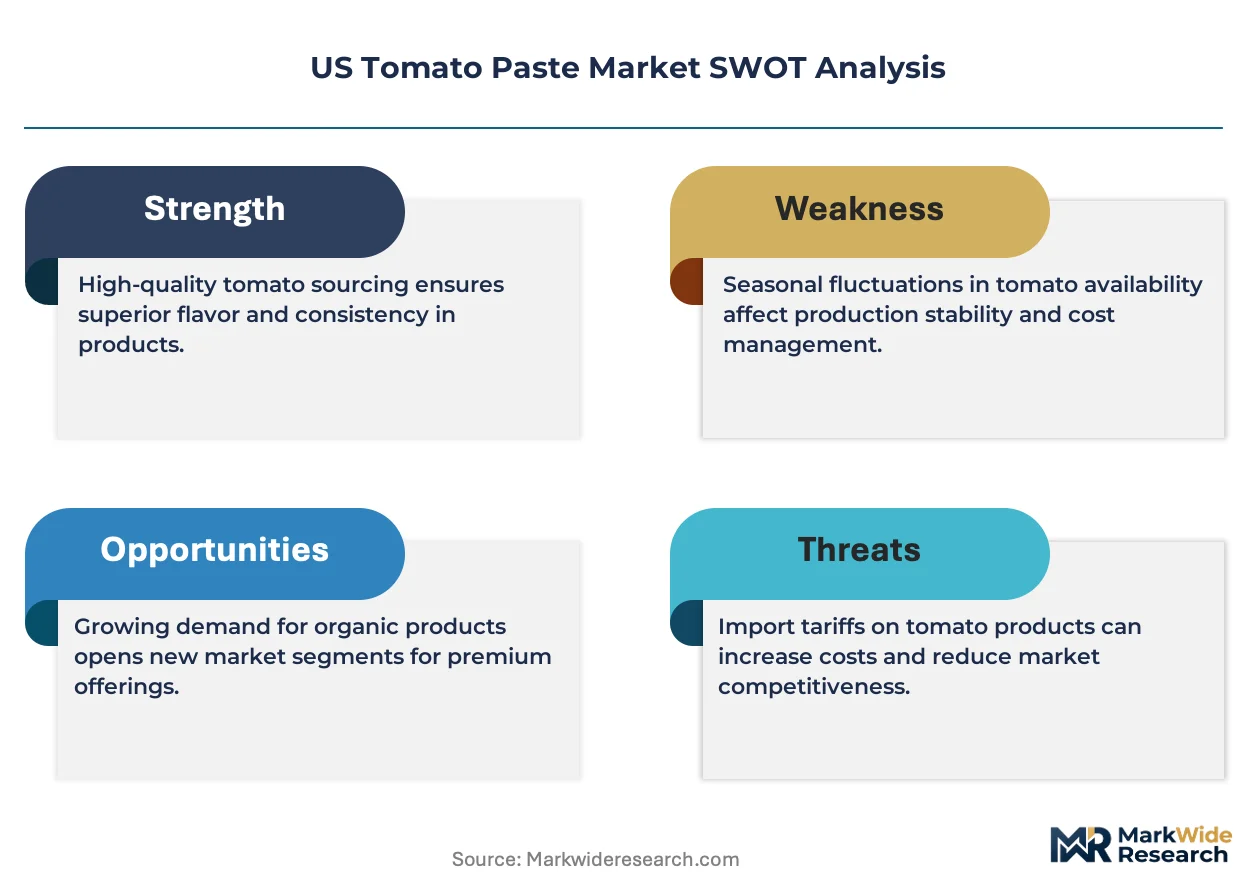
Water scarcity in California's San Joaquin Valley is compressing processing capacity and forcing buyers to renegotiate long-term supply agreements with alternative sourcing clauses. The USDA grade standards and FDA preventive controls create a dual compliance burden that favors scaled operators with dedicated quality infrastructure.
Growth Catalysts
- Industrial sauce manufacturing:National soup and sauce producers are consolidating ingredient procurement under multi-year paste contracts with guaranteed volume tiers and price collars.
- FSMA preventive controls:FDA-mandated hazard analysis plans are accelerating facility upgrades that improve traceability and reduce batch rejection rates at receiving docks.
- Aseptic bag-in-box technology:Food service distributors are adopting bulk aseptic formats to reduce cold-chain costs and extend open-shelf life in institutional kitchens.
Market Restraints
- Tomato solids input volatility:Drought-driven water allocation cuts in California's Central Valley are raising field tomato contract prices and compressing processor margins.
- Single-region supply concentration:Over 90% of domestic processing capacity sits within 200 miles of Fresno, creating systemic weather and logistics risk.
- Regulatory friction from CARB:California Air Resources Board emissions rules are adding capital intensity to evaporator upgrades and limiting facility expansion permits.
Strategic Opportunities
- Retail pouch convenience formats:Supermarket chains are expanding shelf space for single-serve tomato paste pouches targeting smaller households and recipe-specific usage.
- USDA organic certification tailwind:Premium private-label programs are mandating certified organic paste inputs, creating price differentiation for compliant processors.
- Direct-to-food-manufacturer e-procurement:Digital ingredient marketplaces are emerging as channels that bypass traditional broker networks and compress transaction costs.
Industry Challenges
- Evaporator technician shortage:Specialized knowledge of multi-effect vacuum evaporation systems is retiring faster than vocational programs can replace it.
- Legacy ERP integration:FSMA lot-tracking mandates are forcing mid-sized processors to reconfigure accounting and inventory systems for real-time traceability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Tomato Paste Market |
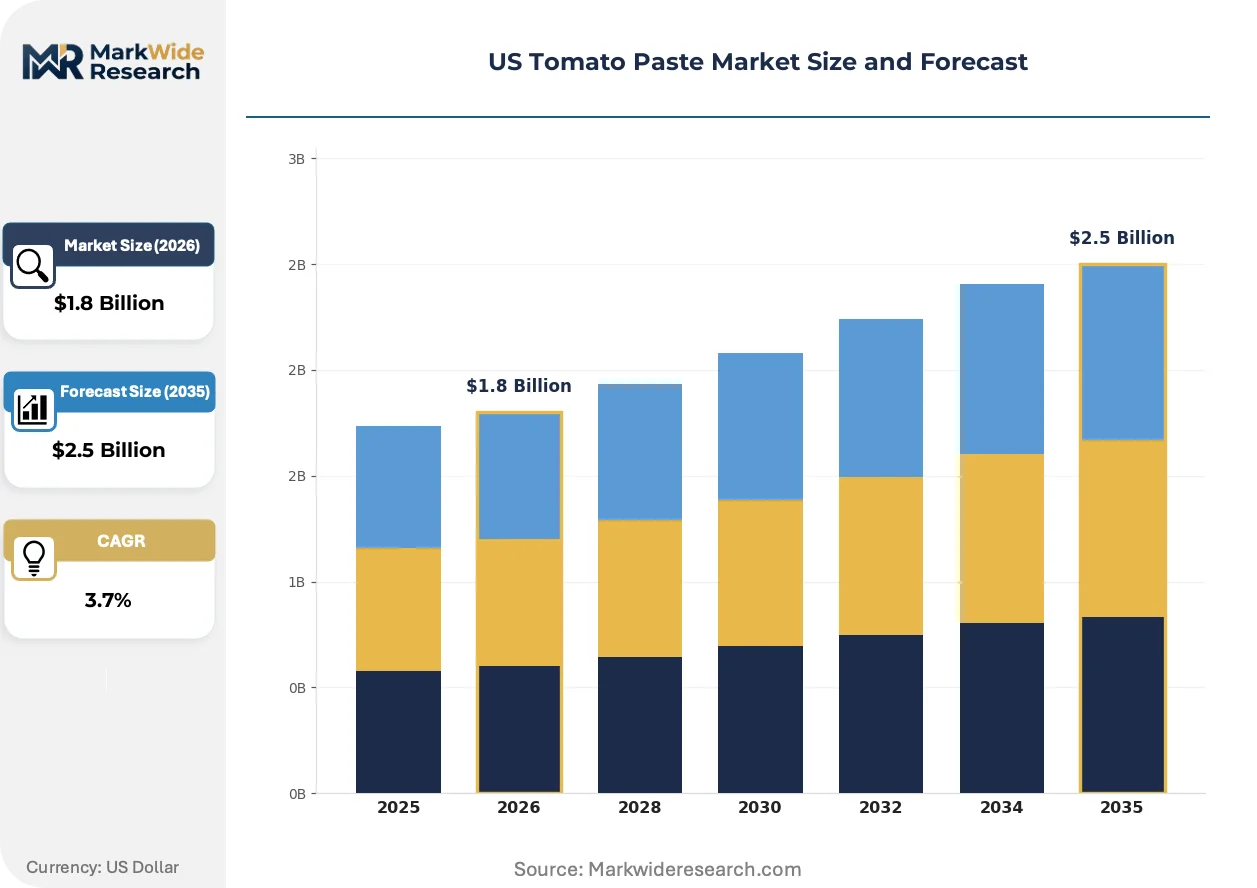
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diced, Pureed, Concentrated, Crushed Packaging Type: Tin Can, Glass Jar, Pouch, Plastic Container End User: Food Service, Retail, Food Manufacturing, Household Distribution Channel: Online, Supermarkets, Wholesalers, Specialty Stores |
| Companies Covered | Morning Star Company, Ingomar Packing Co., Los Gatos Tomato Products, Neil Jones Food Company, Stanislaus Food Products, Pacific Coast Producers, Conagra Brands, Del Monte Foods, Campbell Soup Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Tomato Paste Market Evolving Landscape
Processing technology and packaging formats are converging to reduce energy intensity and extend shelf stability. Regulatory pressure on emissions and water use is accelerating capital deployment toward closed-loop systems.
Concentrated paste production is miniaturizing through adoption of mechanical vapor recompression evaporators that recover latent heat from condensate streams. Morning Star Company and Ingomar Packing Co. are retrofitting Central Valley facilities with MVR units to cut natural gas consumption per ton of finished paste. This thermal efficiency gain is compressing the cost gap between California processors and imported Turkish and Chinese paste alternatives.
The FDA Food Safety Modernization Act preventive controls rule is mandating environmental monitoring for Listeria and Salmonella in processing zones. Facilities must now validate sanitation protocols with documented swab testing and corrective action logs. California processors are investing most heavily in zone 1 and zone 2 environmental controls where product contact surfaces present the highest contamination risk.
Food manufacturers are consolidating ingredient procurement under direct contracts that specify USDA grade, brix level, and aseptic packaging format in single agreements. National soup and sauce producers are displacing spot-market purchasing with annual volume commitments that include price-adjustment clauses tied to field tomato futures. This shift is most visible among Midwest and Southeast manufacturing plants that previously relied on distributor intermediaries for paste supply.
US Tomato Paste Market Segmentation
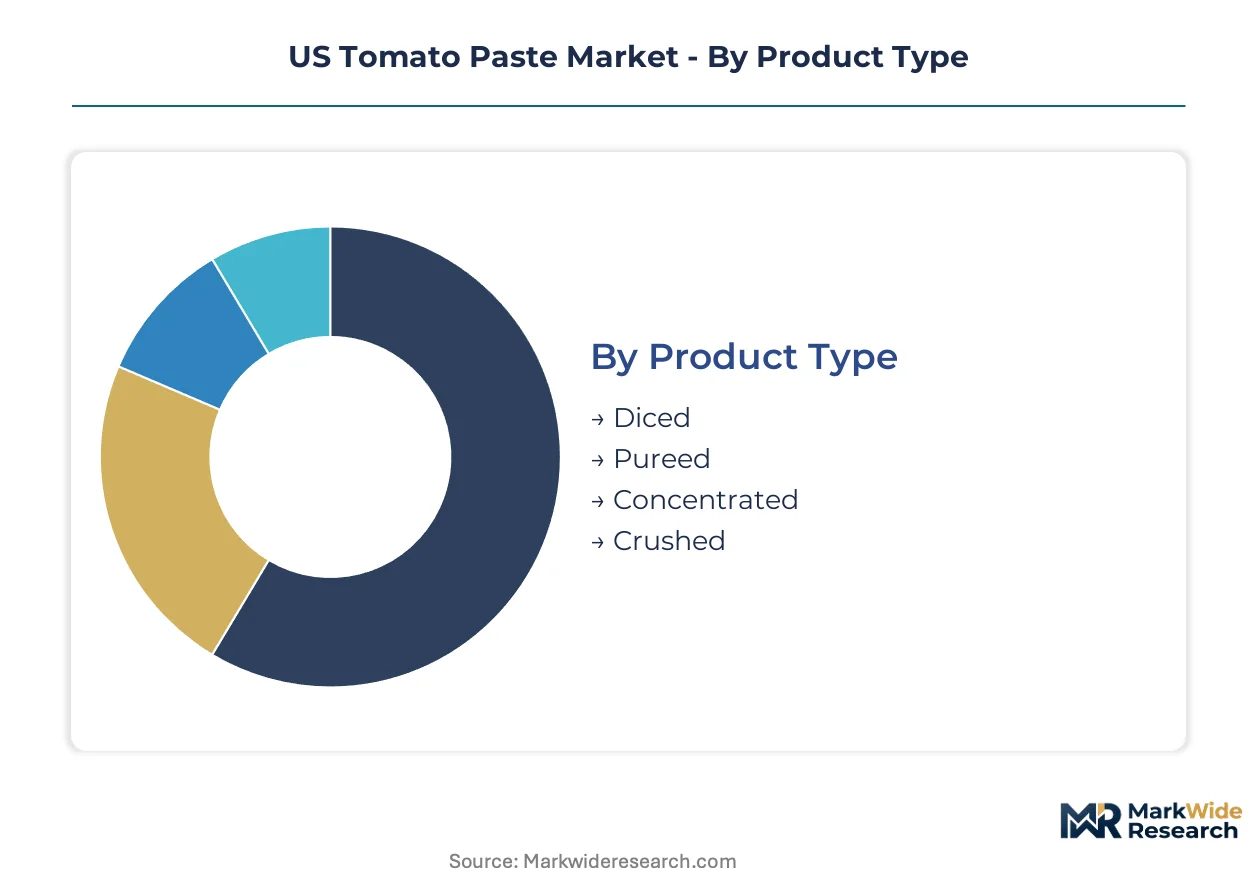
US tomato paste procurement splits sharply between industrial buyers seeking USDA-graded bulk inputs and retail channels demanding convenience formats. FDA preventive controls and California water regulations create divergent compliance burdens across each segment cluster.
Product Type:
USDA grade standards differentiate paste categories through color density and defect thresholds that determine pricing tiers and buyer acceptance criteria.
- Concentrated:Evaporated to 24-36% solids content through multi-effect vacuum processing. Food manufacturing buyers in the Midwest and Southeast are consolidating procurement under direct contracts with guaranteed volume tiers and price collars tied to field tomato futures.
- Diced:Firm tomato cubes preserved in juice or puree for texture-critical applications. Quick-service restaurant chains and frozen pizza manufacturers specify USDA Grade A diced products for consistent cooking performance in high-volume kitchens.
- Pureed:Smooth, seedless tomato liquid strained to uniform consistency. Soup manufacturers and baby food processors drive demand for low-acid purees meeting FDA acidified food regulations.
- Crushed:Coarse tomato blend retaining seeds and skin fragments for rustic sauce applications. Regional Italian-American restaurant groups and private-label sauce brands in the Northeast specify crushed formats for authenticity positioning.
Concentrated paste handles the majority of throughput; pouches are expanding most quickly as portion-control convenience reshapes supermarket purchasing.
Packaging Type:
Packaging economics hinge on thermal processing requirements and cold-chain infrastructure, with aseptic formats commanding premium positioning in food service channels.
- Tin Can:Metal containers with epoxy linings supporting retort sterilization for ambient shelf stability. Institutional food service distributors and military commissaries specify #10 cans for portion standardization and stackability in high-volume storage.
- Pouch:Flexible multi-layer films with spout or tear-notch closures for single-serve dispensing. Supermarket chains in California and Texas are expanding shelf space for recipe-specific pouches targeting smaller households and reducing household food waste.
- Glass Jar:Transparent containers with vacuum-sealed lids for retail premium positioning. Specialty stores and farmers market channels favor glass for organic and heirloom product lines requiring visual differentiation.
- Plastic Container:Polypropylene tubs with resealable lids for refrigerated paste varieties. Deli counter and prepared meal sections in regional supermarket chains specify plastic for grab-and-go convenience.
Tin can formats anchor food service and institutional procurement; pouch packaging gains share fastest as portion-control convenience reshapes retail purchasing.
End User:
Customer type determines volume scale, specification rigor, and contract structure, with industrial buyers displacing spot-market purchasing through multi-year agreements.
- Food Manufacturing:National soup, sauce, and prepared meal producers sourcing USDA-graded paste in bulk aseptic formats. Campbell Soup Company and Kraft Heinz specify brix levels, color scores, and aseptic packaging in single procurement agreements with price-adjustment clauses.
- Food Service:Restaurant chains, institutional cafeterias, and catering operations requiring portion-controlled formats with extended open-shelf life. Sysco and US Foods distribute bag-in-box aseptic paste to reduce cold-chain costs in institutional kitchens.
- Retail:Supermarket chains and mass merchandisers stocking branded and private-label shelf-stable paste. Walmart and Kroger are expanding private-label pouch programs to capture recipe-specific usage occasions.
- Household:Direct-to-consumer sales through farmers markets, community-supported agriculture, and specialty food websites. California Central Valley processors sell small-batch organic paste through direct subscription models.
Food manufacturing commands the dominant volume position; retail pouch formats are climbing the fastest as supermarket chains expand convenience-oriented shelf space.
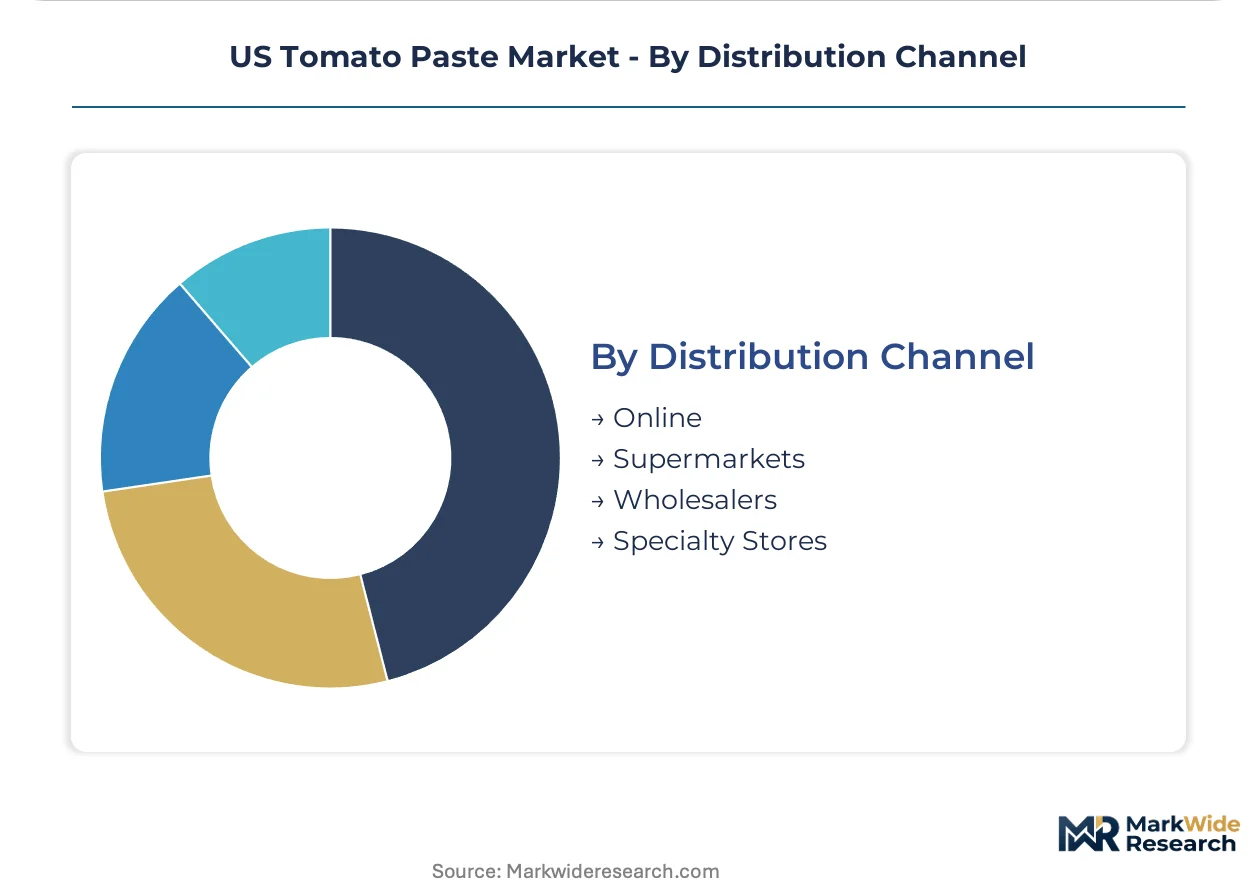
Distribution Channel:
Channel structure reflects buyer scale and specification complexity, with digital platforms emerging as bypass mechanisms for traditional broker networks.
- Wholesalers:Broadline distributors consolidating multi-product shipments to food service and retail accounts. Sysco, US Foods, and Gordon Food Service maintain dedicated tomato paste SKUs for institutional and restaurant contracts.
- Supermarkets:Corporate buying offices negotiating direct with processors for private-label programs. Kroger, Albertsons, and Publix specify USDA grade, organic certification, and packaging format in annual volume commitments.
- Online:Digital marketplaces and direct-to-manufacturer platforms compressing transaction costs for industrial buyers. Emerging ingredient procurement platforms connect Midwest sauce manufacturers with California processors for spot and contract purchasing.
- Specialty Stores:Independent retailers and natural food chains emphasizing organic, heirloom, and regional provenance. Whole Foods Market and regional co-ops mandate certified organic paste with transparent supply chain documentation.
Wholesalers handle the majority of institutional throughput; online channels are gaining share fastest as digital procurement platforms bypass traditional broker intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Oakland's refrigerated container terminals anchor California's tomato paste export capacity, connecting San Joaquin Valley processors to Asian and European food manufacturing buyers through direct transpacific routes.
California
Central Valley processors supply over ninety percent of domestic tomato paste volume, with Fresno County evaporator complexes running near capacity during the August-to-October harvest window. State water allocation cuts under California's Sustainable Groundwater Management Act are forcing growers to retire orchards and fallow fields, compressing field tomato supply. The Modesto and Stockton processing clusters are retrofitting mechanical vapor recompression systems to cut natural gas consumption per ton of finished paste.
Midwest
Ohio and Indiana sauce manufacturers are consolidating procurement under direct contracts with California processors, displacing spot-market purchasing through distributor intermediaries. FDA preventive controls under FSMA are mandating lot-tracking documentation that Midwest plants must validate at receiving docks. Chicago-area food manufacturing plants are negotiating annual volume commitments with price-adjustment clauses tied to field tomato futures.
Southeast
Florida's winter tomato production provides limited paste-grade volume, leaving regional soup and sauce plants dependent on rail shipments from California. The USDA Agricultural Marketing Service grade standards determine pricing tiers for incoming loads at Georgia and North Carolina receiving facilities. Atlanta and Charlotte distribution hubs are expanding cold-storage capacity for aseptic bag-in-box formats serving institutional food service accounts.
Pacific Northwest
Oregon and Washington food processors source limited domestic paste volume, relying on California supply with supplemental imports from Chile and Mexico. The region's specialty organic sauce manufacturers are mandating USDA organic certification in procurement specifications. Portland and Seattle metro-area co-packing facilities are developing private-label pouch programs for regional supermarket chains.
Southwest
Texas food manufacturing growth in Dallas-Fort Worth and Houston is driving demand for bulk aseptic paste in sauce and prepared meal production. The state's independent grid and energy cost volatility are influencing processor decisions on evaporator fuel sources. Border proximity to Mexican tomato production is prompting some buyers to evaluate alternative sourcing clauses in long-term supply agreements.
US Tomato Paste Market Competitive Landscape
Concentration sits with vertically integrated processors controlling field-to-facility supply chains. Morning Star Company and Ingomar Packing Co. anchor bulk supply through Central Valley processing networks, while Conagra Brands and Del Monte Foods sustain multi-regional retail and food service distribution. Three archetypes dominate: field-integrated processors with captive tomato supply, co-packing specialists serving private-label programs, and diversified food conglomerates with paste as a vertical input. Competitive moves center on evaporator technology licensing and backward integration into contracted acreage.
Within the integrated processor tier, Morning Star Company exemplifies field-to-facility control through Central Valley operations. Ingomar Packing Co. occupies a position emphasizing aseptic packaging formats for food service channels. Conagra Brands represents the diversified conglomerate archetype, leveraging multi-regional distribution infrastructure across retail and institutional segments.
| Leading Market Players |
|---|
| Morning Star Company |
| Ingomar Packing Co. |
| Los Gatos Tomato Products |
| Neil Jones Food Company |
| Stanislaus Food Products |
| Pacific Coast Producers |
| Conagra Brands |
| Del Monte Foods |
| Campbell Soup Company |
| Others |
Value Network & Pricing Analysis
Mechanical vapor recompression evaporator adoption is displacing natural gas-fired thermal processing across California's Central Valley, simultaneously compressing energy cost differentials between domestic and imported paste while redrawing procurement geography toward processors with retrofit capital.
Pricing Analysis
Volume-discount tiering structures separate USDA Grade A contracts from Grade B and C alternatives, with food manufacturers locking multi-year agreements at 15,000-ton annual minimums. Price differentiation hinges on organic certification premiums and aseptic packaging format specifications. Cost compression in standard-grade paste is intensifying because drought-driven field tomato contract escalation is squeezing processor margins. Private-label retail buyers exhibit highest price sensitivity, while national soup manufacturers with backward-integrated supply show lowest.
Supply Chain Analysis
Inventory lead times stretch from August harvest through October processing window, forcing buyers to commit tonnage before field yield clarity emerges. Supply concentrates in California's San Joaquin Valley, with supplemental volumes drawing from Italy and Turkey for organic lines. Raw material dependencies center on field tomato contracts, natural gas for evaporation, and epoxy-lined tinplate for can manufacturing. Single-region concentration creates systemic weather risk. Distribution runs through broadline wholesalers Sysco and US Foods for food service, direct processor contracts for manufacturing, and supermarket corporate buying offices for retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents early-cycle expansion as industrial sauce manufacturers consolidate procurement under direct contracts, with aseptic bag-in-box adoption creating new penetration pathways in institutional channels.
For Market Incumbents: Consolidate processing capacity through mechanical vapor recompression retrofits that cut energy intensity and defend margin position against Turkish and Chinese import alternatives. Lock contracted acreage under long-term grower agreements before Sustainable Groundwater Management Act cuts deepen. USDA organic certification investment creates defensible pricing power as premium private-label programs mandate compliant inputs.
For New Entrants and Emerging Players: USDA organic certification fast-tracks access to Whole Foods Market and regional co-op channels where supply documentation requirements filter out conventional processors. White-space sits in direct-to-manufacturer e-procurement platforms that bypass traditional broker networks and compress transaction costs for Midwest sauce plants. Target pouch packaging innovation for single-serve retail expansion in Texas and California supermarket chains.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed co-packing specialists serving private-label retail programs, where margin compression from water scarcity and regulatory compliance creates consolidation pressure. Five-to-ten-year viability favors processors with captive tomato supply and MVR-equipped facilities. Watch California groundwater allocation adjudications as inflection signal for field tomato input cost trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Vapor Recompression Retrofit | Energy cost reduction compresses gap with Turkish and Chinese paste alternatives. |
| USDA Organic Certification Program | Premium private-label mandates at Kroger and Albertsons require compliant processor inputs. |
| Direct E-Procurement Platform Launch | Digital marketplaces bypass traditional broker networks for Midwest sauce manufacturers. |
| Contracted Acreage Expansion | Long-term grower agreements hedge against Sustainable Groundwater Management Act supply cuts. |
| Aseptic Pouch Format Development | Single-serve convenience captures recipe-specific usage in smaller household segments. |
Research Methodology
Initial hypotheses were tested against primary input from tomato paste plant managers, food manufacturing procurement directors, and broadline distributor category buyers and refined through secondary validation. Sources included USDA Agricultural Marketing Service grade standard databases, FDA FSMA compliance filings, California Air Resources Board emissions records, and field tomato futures contract data. Bottom-up volume estimates from processor capacity utilization triangulated against top-down demand aggregation from soup, sauce, and prepared meal production figures.
Variance decomposition across product type, packaging format, end user, and distribution channel segments shaped the analytical framework over the projection horizon. CAGRs derived from regression against historical volume trajectories and forward-looking input cost assumptions. Modeled inputs included California groundwater allocation scenarios, natural gas price volatility bands, and mechanical vapor recompression adoption curves.
Underlying assumptions cover sustained drought conditions in the San Joaquin Valley and stable FDA preventive control enforcement intensity, with deviation risk concentrated in water regulatory adjudications and energy cost spikes. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
India Ready to Mix Food Market
Processed Foods
Processed Potatoes Market
Processed Foods
Low Moisture Food Market
Processed Foods
US Processed Pumpkin Market
Processed Foods
Global Pasta Market
Processed Foods
United States Processed Meat Market
Processed Foods
Processed Beef Market
Processed Foods
Europe Processed Egg Market
Processed Foods
Chocolate Filling Market
Processed Foods
Low Fat Soups Market
Processed Foods
Casual Marinated Products Market
Processed Foods
Fresh Pasta Market
Processed Foods
Ice Cream Parlor Market
Processed Foods
India Spray Dried Food Market
Processed Foods
Spray Cheese Market
Processed Foods
Fat Free Food Market